
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Kanto Denka Kogyo Co., Ltd. reported net sales of ¥65.4 billion (up 4.9%) and operating profit of ¥5.4 billion (up 28.2%) for FY2025, the fiscal year ended March 31, 2026. Specialty gas sales rose on higher sales volumes and price adjustments amid higher operating rates at semiconductor manufacturers, despite the impact of the fire accident at the Shibukawa plant. For FY2026, the company forecasts net sales of ¥95.0 billion (up 45.3%) and operating profit of ¥10.0 billion (up 82.5%). In the company’s materials, FY2025 refers to the fiscal year ended March 31, 2026, and FY2026 to the fiscal year ending March 31, 2027; figures below are in billions of yen unless otherwise noted.
Consolidated Results (Full-Year Actual)
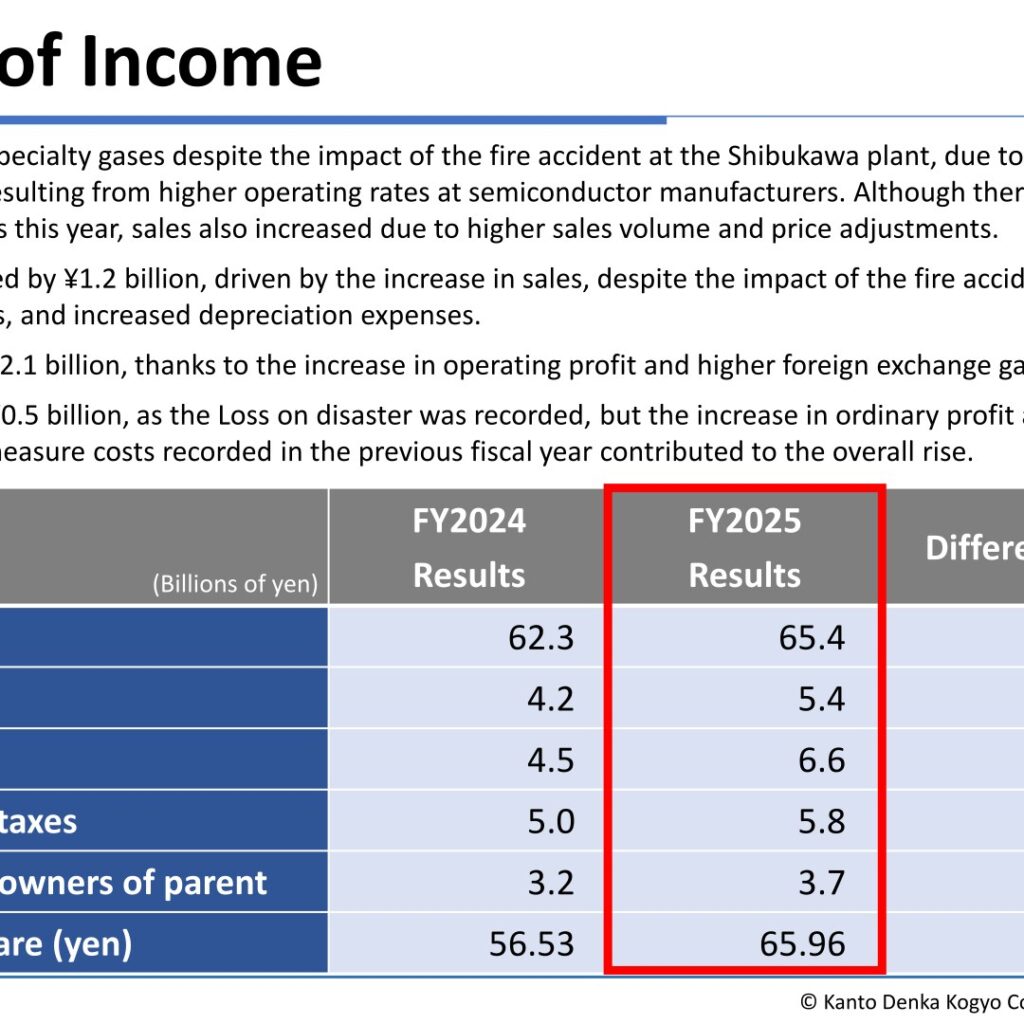
Net sales increased for specialty gases despite the impact of the fire accident at the Shibukawa plant, due to an increase in sales volume and price adjustments resulting from higher operating rates at semiconductor manufacturers. Although there were no technical support fees for battery materials in the year, battery material sales also increased due to higher sales volume and price adjustments.
Operating profit increased by ¥1.2 billion, driven by the increase in sales, despite the impact of the fire accident, rising raw material prices and increased depreciation expenses. Ordinary profit rose by ¥2.1 billion on the higher operating profit and higher foreign exchange gains. Profit attributable to owners of parent increased by ¥0.5 billion: a loss on disaster was recorded, but the increase in ordinary profit and the absence of the environmental countermeasure costs recorded in the previous fiscal year contributed to the overall rise.
| Item (Billions of yen) | FY2025 Results | FY2024 Results | Difference | % change |
|---|---|---|---|---|
| Net sales | 65.4 | 62.3 | 3.0 | 4.9 |
| Operating profit | 5.4 | 4.2 | 1.2 | 28.2 |
| Ordinary profit | 6.6 | 4.5 | 2.1 | 47.1 |
| Profit before income taxes | 5.8 | 5.0 | 0.7 | 15.8 |
| Profit attributable to owners of parent | 3.7 | 3.2 | 0.5 | 16.5 |
| Basic earnings per share (yen) | 65.96 | 56.53 | 9.43 | — |
On the balance sheet, total assets rose to ¥131.3 billion from ¥123.6 billion, with inventories up to ¥21.1 billion and trade receivables up to ¥18.8 billion. Interest-bearing debt was ¥39.8 billion, net assets were ¥74.2 billion, and the equity ratio improved by 1.7 points to 55.1%.
| Balance Sheet (Billions of yen) | FY2025 | FY2024 | Difference | % change |
|---|---|---|---|---|
| Assets | 131.3 | 123.6 | 7.6 | 6.2 |
| Cash and deposits | 20.2 | 20.2 | -0.0 | -0.4 |
| Trade receivables | 18.8 | 15.4 | 3.3 | 21.6 |
| Inventories | 21.1 | 17.2 | 3.8 | 22.5 |
| Interest-bearing debt | 39.8 | 37.8 | 1.9 | 5.2 |
| Net assets | 74.2 | 67.6 | 6.6 | 9.8 |
| Equity ratio (%) | 55.1 | 53.4 | 1.7 | — |
Segment Results
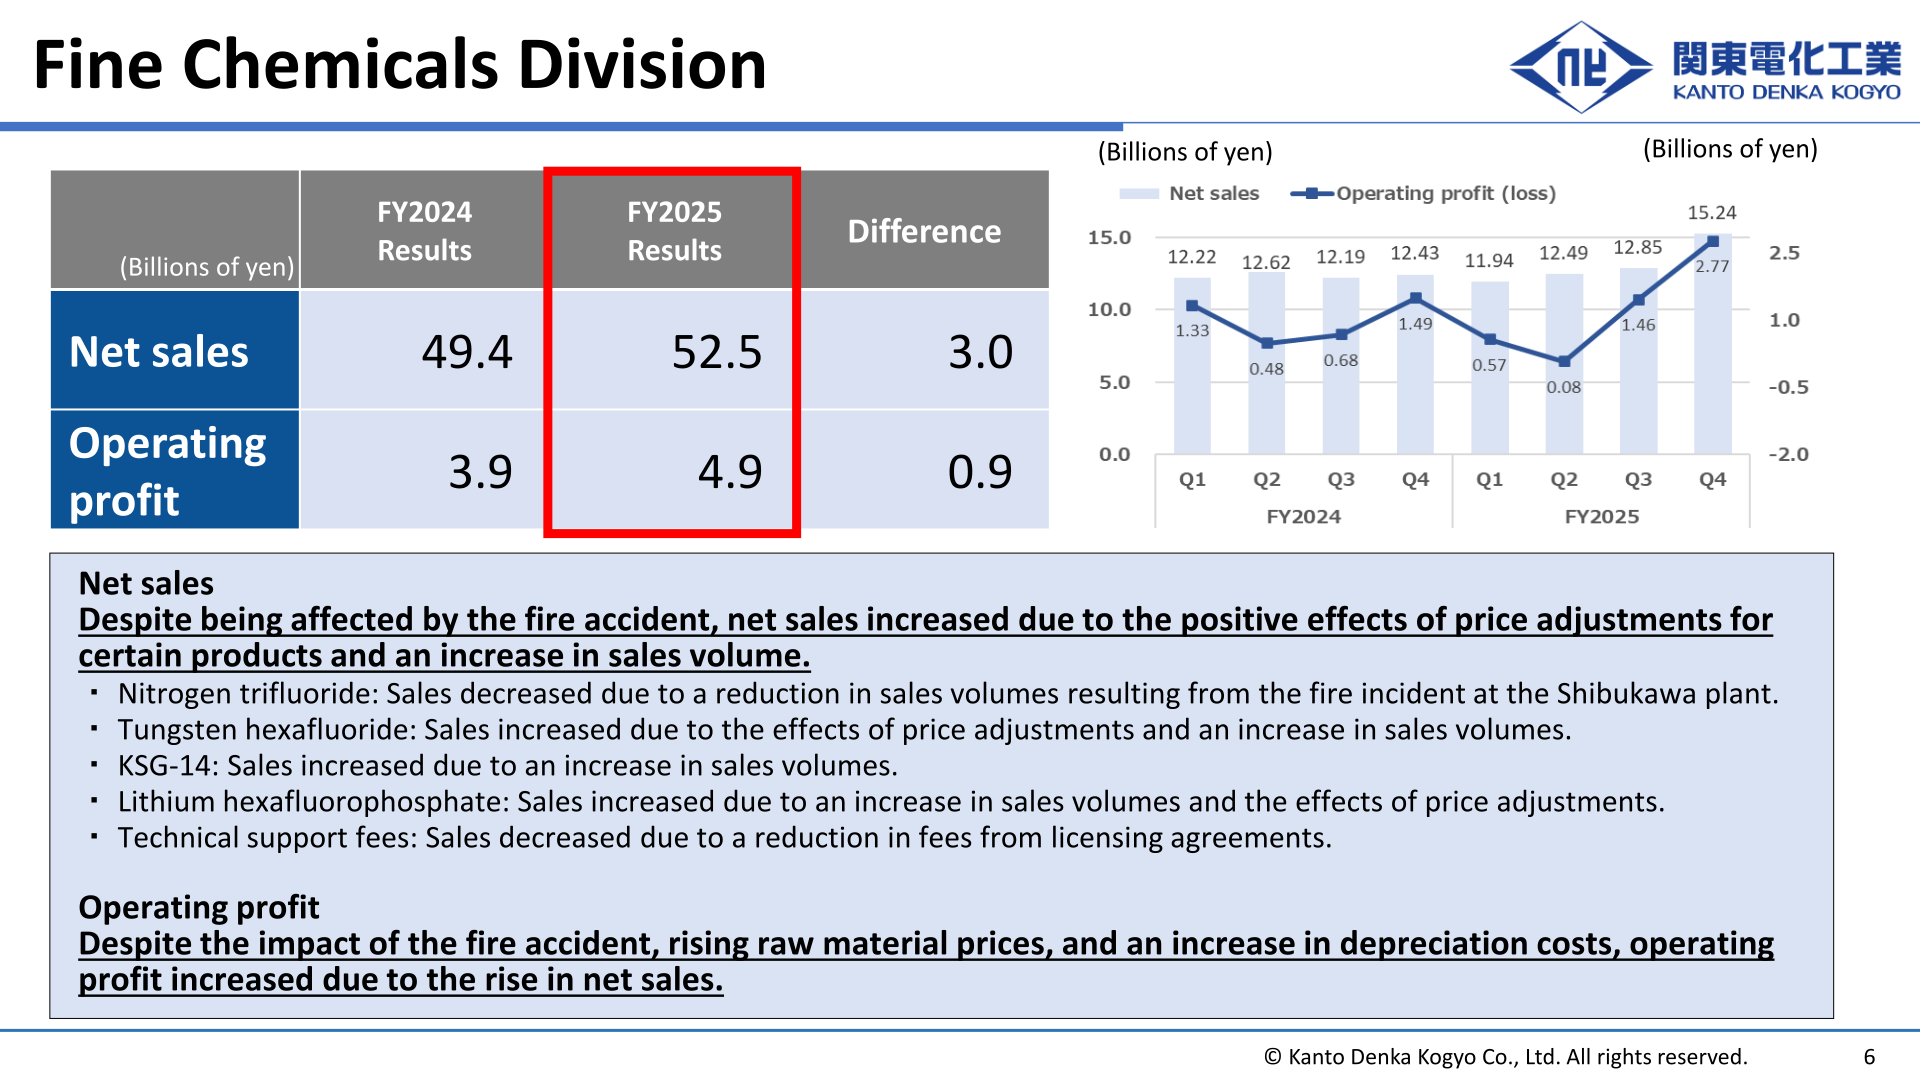
Fine Chemicals: Net sales rose to ¥52.5 billion and operating profit to ¥4.9 billion. Despite the fire accident, sales increased due to price adjustments for certain products and higher sales volumes. Nitrogen trifluoride sales decreased due to lower volumes resulting from the fire at the Shibukawa plant, while tungsten hexafluoride sales increased on price adjustments and higher volumes. KSG-14 sales increased on higher volumes, and lithium hexafluorophosphate sales increased on higher volumes and price adjustments. Technical support fees decreased due to a reduction in fees from licensing agreements.
Fundamental Chemicals: Net sales were ¥8.0 billion and the division returned to an operating profit of ¥0.1 billion from a loss of ¥0.5 billion. Although sales volumes of organic products decreased, net sales increased due to price adjustments for certain products; operating profit improved on those price adjustments, lower raw material prices and a reduction in fixed costs.
Ferrochemicals, Commercial Business and Facilities Divisions (including consolidation adjustments): Net sales were ¥4.8 billion and operating profit declined to ¥0.4 billion. Sales increased in the Commercial Business and Facilities Divisions but decreased in the Ferrochemicals Division due to lower sales volume of carriers; operating profit was also affected by a consolidation adjustment arising from the completion of the KSG-14 mass production equipment in the Facilities Division.
| Segment | Metric | FY2025 Results | FY2024 Results | Difference |
|---|---|---|---|---|
| Fine Chemicals | Net sales | 52.5 | 49.4 | 3.0 |
| Fine Chemicals | Operating profit | 4.9 | 3.9 | 0.9 |
| Fundamental Chemicals | Net sales | 8.0 | 7.9 | 0.0 |
| Fundamental Chemicals | Operating profit (loss) | 0.1 | (0.5) | 0.6 |
| Ferrochemicals, Commercial Business, Facilities (incl. consolidation adjustments) | Net sales | 4.8 | 4.8 | -0.0 |
| Ferrochemicals, Commercial Business, Facilities (incl. consolidation adjustments) | Operating profit | 0.4 | 0.8 | -0.3 |
FY2026 Forecast
For FY2026, net sales are expected to increase by ¥29.6 billion to ¥95.0 billion, driven by higher sales volumes of specialty gases on expanding semiconductor demand and the pass-through of rising raw material prices, as well as higher sales volumes and price adjustment effects in battery materials from new demand primarily in the United States, in line with the trend of reducing reliance on China. Operating profit is expected to increase by ¥4.5 billion to ¥10.0 billion, despite the surge in raw material prices and rising fixed costs. The company states that the effects of rising raw material prices related to the escalating situation in the Middle East have already been factored in within a reasonable range. The assumed exchange rate is ¥155/$ (FY2025: ¥151/$).
| Item (Billions of yen) | FY2026 Forecast | FY2025 Results | Difference | % change |
|---|---|---|---|---|
| Net sales | 95.0 | 65.4 | 29.6 | 45.3 |
| Operating profit | 10.0 | 5.4 | 4.5 | 82.5 |
| Ordinary profit | 10.0 | 6.6 | 3.3 | 50.8 |
| Profit attributable to owners of parent | 6.8 | 3.7 | 3.0 | 79.6 |
| Basic earnings per share (yen) | 118.56 | 65.96 | 52.6 | — |
| FX rate (USD) | ¥155/$ | ¥151/$ | — | — |
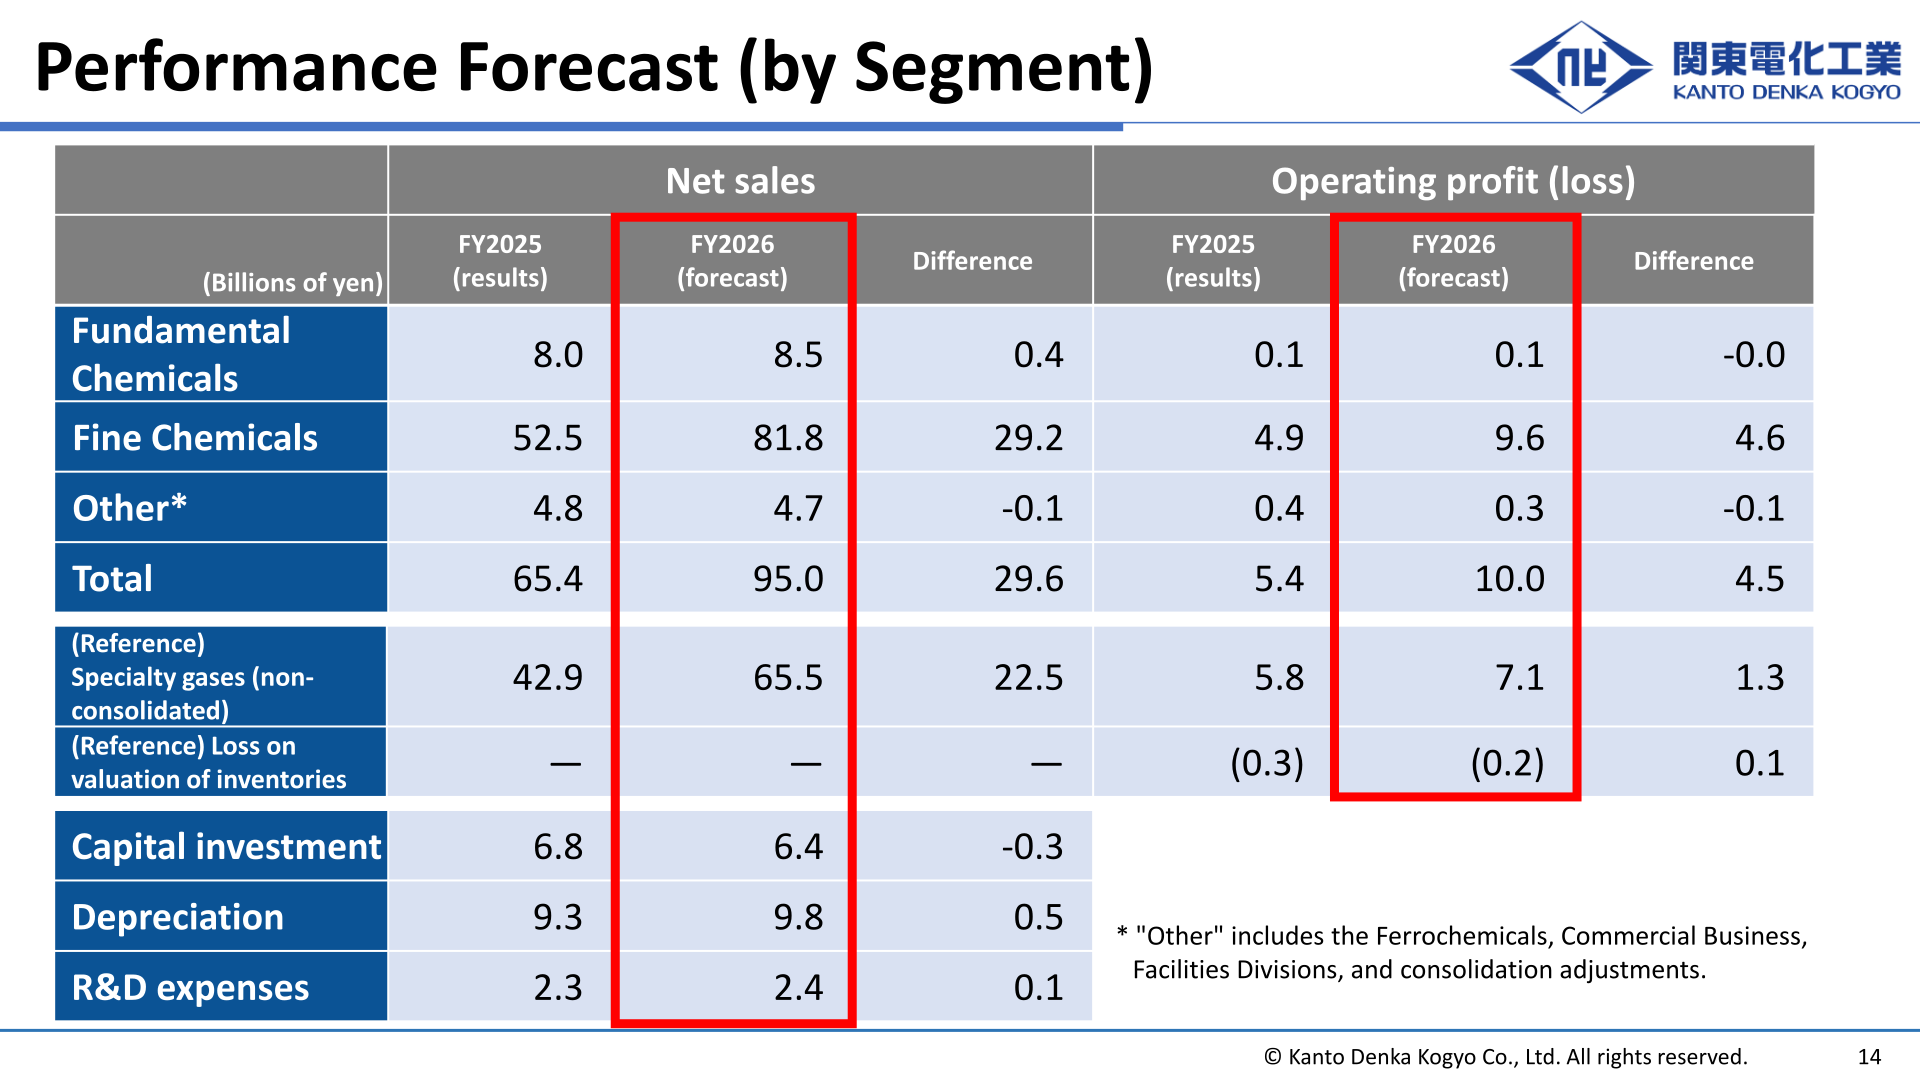
By segment, Fine Chemicals is expected to lead the growth, with net sales of ¥81.8 billion and operating profit of ¥9.6 billion. Specialty gases (non-consolidated, for reference) are forecast at net sales of ¥65.5 billion and operating profit of ¥7.1 billion. Capital investment is planned at ¥6.4 billion, depreciation at ¥9.8 billion and R&D expenses at ¥2.4 billion. On a half-year basis, the company forecasts net sales of ¥42.2 billion and operating profit of ¥5.3 billion in H1, and net sales of ¥52.8 billion and operating profit of ¥4.7 billion in H2.
| Segment (Billions of yen) | Metric | FY2026 Forecast | FY2025 Results | Difference |
|---|---|---|---|---|
| Fundamental Chemicals | Net sales | 8.5 | 8.0 | 0.4 |
| Fundamental Chemicals | Operating profit (loss) | 0.1 | 0.1 | -0.0 |
| Fine Chemicals | Net sales | 81.8 | 52.5 | 29.2 |
| Fine Chemicals | Operating profit (loss) | 9.6 | 4.9 | 4.6 |
| Other* | Net sales | 4.7 | 4.8 | -0.1 |
| Other* | Operating profit (loss) | 0.3 | 0.4 | -0.1 |
| Total | Net sales | 95.0 | 65.4 | 29.6 |
| Total | Operating profit (loss) | 10.0 | 5.4 | 4.5 |
| (Reference) Specialty gases (non-consolidated) | Net sales | 65.5 | 42.9 | 22.5 |
| (Reference) Specialty gases (non-consolidated) | Operating profit (loss) | 7.1 | 5.8 | 1.3 |
| Capital investment | — | 6.4 | 6.8 | -0.3 |
| Depreciation | — | 9.8 | 9.3 | 0.5 |
| R&D expenses | — | 2.4 | 2.3 | 0.1 |
* “Other” includes the Ferrochemicals, Commercial Business and Facilities Divisions and consolidation adjustments.
Shareholder Returns
The results briefing materials do not include information on dividends or share buybacks. This cannot be confirmed from the materials.
Medium-Term Plan and Topics
FY2026 is the final year of the current medium-term management plan. The company expects a sales achievement rate of 95% against the plan’s net sales target of ¥100.0 billion, with specialty gases expected to exceed the plan and battery materials forecast to fall short.
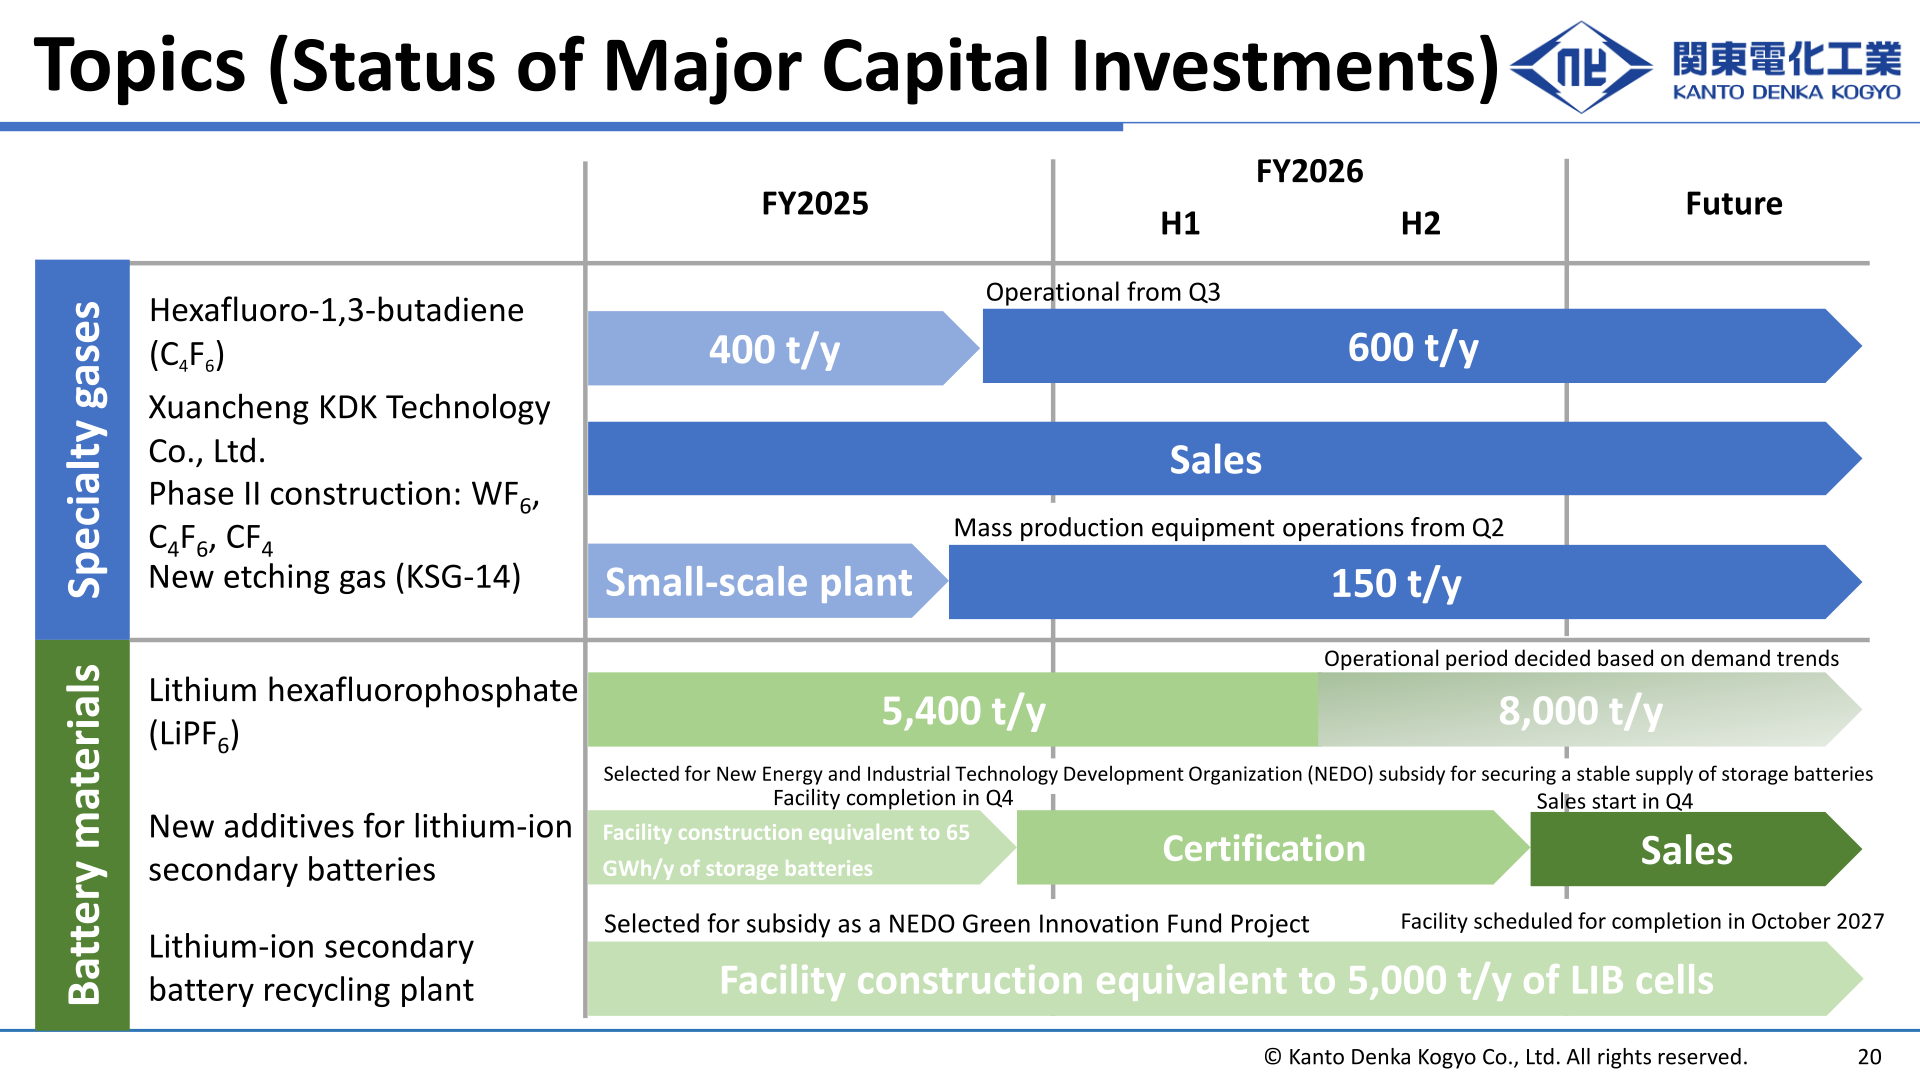
Major capital investments: hexafluoro-1,3-butadiene (C4F6) capacity is being raised from 400 t/y to 600 t/y, and the new etching gas KSG-14 is moving from a small-scale plant to mass production equipment of 150 t/y. For battery materials, lithium hexafluorophosphate (LiPF6) capacity of 5,400 t/y is to be expanded to 8,000 t/y, with the operational period to be decided based on demand trends. A lithium-ion secondary battery recycling plant, selected for subsidy as a NEDO Green Innovation Fund Project, is scheduled for completion in October 2027.
Xuancheng KDK Technology: Because construction of the company’s China plant was significantly delayed by the COVID-19 pandemic, 50% of the investment amount, 161 million yuan (2.3 billion yen), was recorded as a special loss in the non-consolidated financial statements; this is eliminated on consolidation and has no impact on consolidated performance. The subsidiary’s sales, 0.4 billion yen in FY2025, are projected at approximately 4 billion yen for the fiscal year ending March 2027, with profitability expected to begin in the fourth quarter of that year.
Outlook: The company forecasts that the market for semiconductor etching and cleaning gases will grow from ¥230 billion in 2024 to ¥360 billion by 2030, assumes its own CAGR (2024–2030) of 11.0% versus a market average of 7.2%, and targets a share of at least 25% in 2030. In battery materials (LiPF6), it targets the U.S. and Japanese markets, which it expects to grow to 50,000 tons in 2030, with a target share of 50% including technology licensing partners.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















