

This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Tokushu Tokai Paper’s fiscal year ends in March. In this article, FY2025 refers to the fiscal year ended March 31, 2026, which the company labels “FY3/26” in its presentation “Results of Operations for the Fiscal Year Ended March 31, 2026 and the Seventh Medium-term Plan” dated May 20, 2026. Labels in the text and tables below follow the company’s presentation.
The Tokushu Tokai Paper Group (TTP) reported higher sales and earnings for FY3/26. Net sales were 95,413 million yen (+0.6% YoY), operating income was 4,296 million yen (+9.4%), ordinary income was 5,728 million yen (-8.0%), and profit was 4,368 million yen (+21.1%), with ROE improving from 4.6% to 5.4%. However, the company states that progress slowed in the second half because of functional specialty paper weakness beginning in the 2Q, and FY3/26 sales and earnings were below the forecasts. For FY3/27, TTP forecasts net sales of 100,000 million yen and a dividend per share of 94.00 yen under a revised dividend policy.
Consolidated Results (Full-Year Actual)
In the Household Products Business, performance benefited from the full fiscal year contribution of paper towel and toilet paper price revisions, and there was also a contribution from a consolidated subsidiary in the Environment Related Business that joined the TTP Group in April 2024 (Takafuji Co., Ltd., which is included in FY3/25 results for only nine months and, due to a change in its fiscal year, for 14 months in FY3/26). Ordinary income decreased due to lower equity-method income. Profit increased as FY3/25 profit was held down by an impairment loss for production equipment and expenses for shutting down the Gifu Mill.
| Item (Millions of yen) | FY3/25 (results) | FY3/26 (results) | YoY | YoY (%) |
|---|---|---|---|---|
| Net sales | 94,800 | 95,413 | +613 | +0.6% |
| Operating income | 3,928 | 4,296 | +368 | +9.4% |
| Ordinary income | 6,227 | 5,728 | -499 | -8.0% |
| Profit | 3,607 | 4,368 | +761 | +21.1% |
| ROE | 4.6% | 5.4% | +0.8pt | — |
Against the forecasts, the achievement rates were 96.4% for net sales (forecast ¥99.0 billion), 85.9% for operating income (forecast ¥5.0 billion), 81.8% for ordinary income (forecast ¥7.0 billion) and 89.1% for profit (forecast ¥4.9 billion). The company says it acted to offset the slower pace by raising sales of sanitary paper, which benefited from price revisions since early 2026, and by using other measures.
In the breakdown of the YoY change in operating income, volume/prices contributed +551 million yen and the Environment Related Business +226 million yen, while materials (-186 million yen), factory efficiency (-71 million yen) and fixed cost, etc. (-686 million yen) were negative. The company cites rising prices of raw materials in all paper segments and higher personnel expenses, as well as additional fixed expenses included in inventories resulting from higher inventories of some products to prepare for an update of specialty paper production equipment planned for 1H FY3/27.
On the balance sheet, total assets were 141,310 million yen (FY3/25: 139,436 million yen), net assets were 90,102 million yen and the equity ratio rose to 58.9% (+2.6pt). Interest-bearing debt decreased about 2.5 billion yen partly because of the reduction in cash and deposits, and the net debt/equity ratio was unchanged at 0.22.
Segment Results
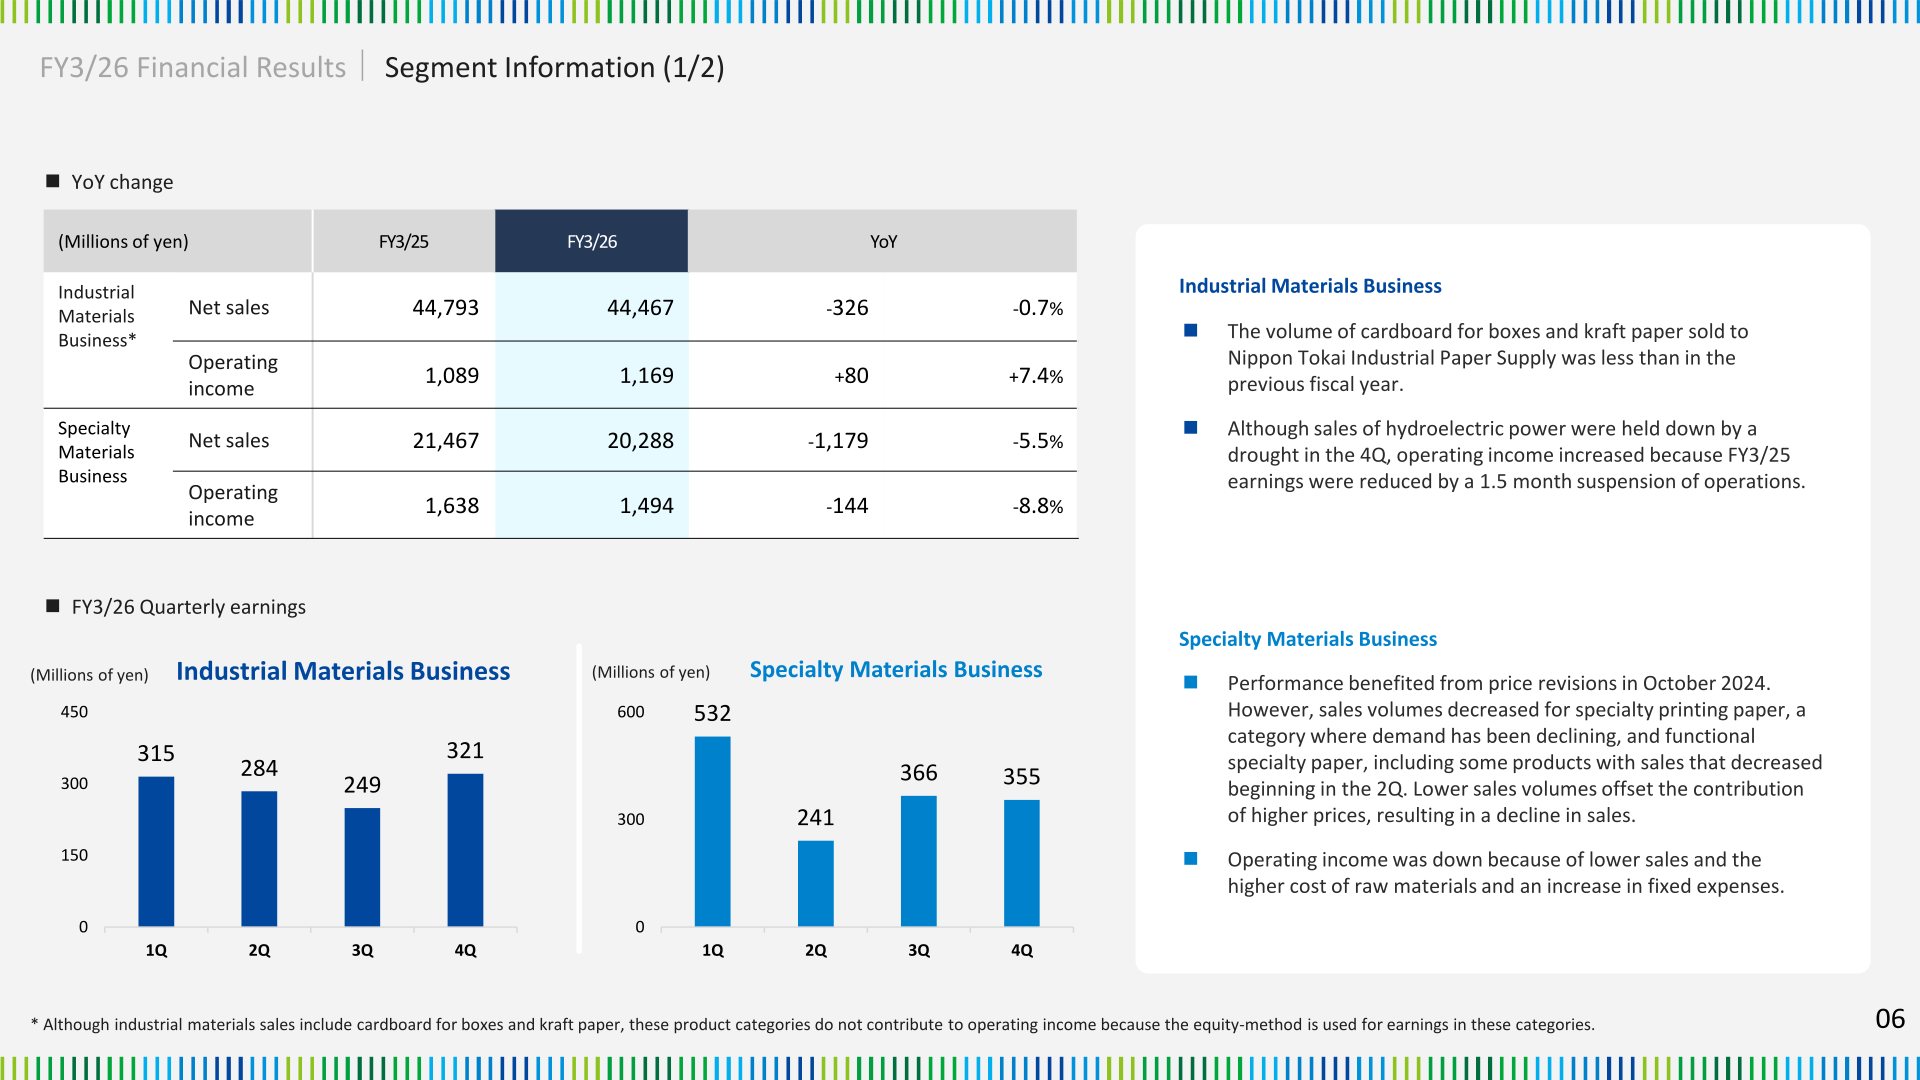
In the Industrial Materials Business, the volume of cardboard for boxes and kraft paper sold to Nippon Tokai Industrial Paper Supply was lower than in the previous fiscal year. Although sales of hydroelectric power were held down by a drought in the 4Q, operating income increased because FY3/25 earnings were reduced by a 1.5 month suspension of operations. The company notes that cardboard for boxes and kraft paper do not contribute to this segment’s operating income because the equity method is used for earnings in these categories.
In the Specialty Materials Business, performance benefited from price revisions in October 2024, but lower sales volumes of specialty printing paper and functional specialty paper offset the contribution of higher prices, resulting in a decline in sales. Operating income was down because of lower sales, the higher cost of raw materials and an increase in fixed expenses.
In the Household Products Business, sales and earnings were higher because of revisions of product prices and steady demand for commercial-use products, despite the rising cost of recycled paper and other raw materials. In the Environment Related Business, the Resource Reuse Business benefited from the full fiscal year consolidation of a recycling company, an upturn following the impact of Takafuji acquisition due diligence expenses in FY3/25, and a larger volume of construction waste materials, while in the Practical-Use of Natural Environment Business an increase in construction completions and firm sales of whisky contributed to results.
| Segment (Millions of yen) | Metric | FY3/25 | FY3/26 | YoY | YoY (%) |
|---|---|---|---|---|---|
| Industrial Materials Business | Net sales | 44,793 | 44,467 | -326 | -0.7% |
| Industrial Materials Business | Operating income | 1,089 | 1,169 | +80 | +7.4% |
| Specialty Materials Business | Net sales | 21,467 | 20,288 | -1,179 | -5.5% |
| Specialty Materials Business | Operating income | 1,638 | 1,494 | -144 | -8.8% |
| Household Products Business | Net sales | 18,646 | 18,993 | +347 | +1.9% |
| Household Products Business | Operating income | 532 | 798 | +266 | +49.8% |
| Environment Related Business | Net sales | 16,783 | 18,089 | +1,306 | +7.8% |
| Environment Related Business | Operating income | 529 | 755 | +226 | +42.7% |
FY3/27 Forecast
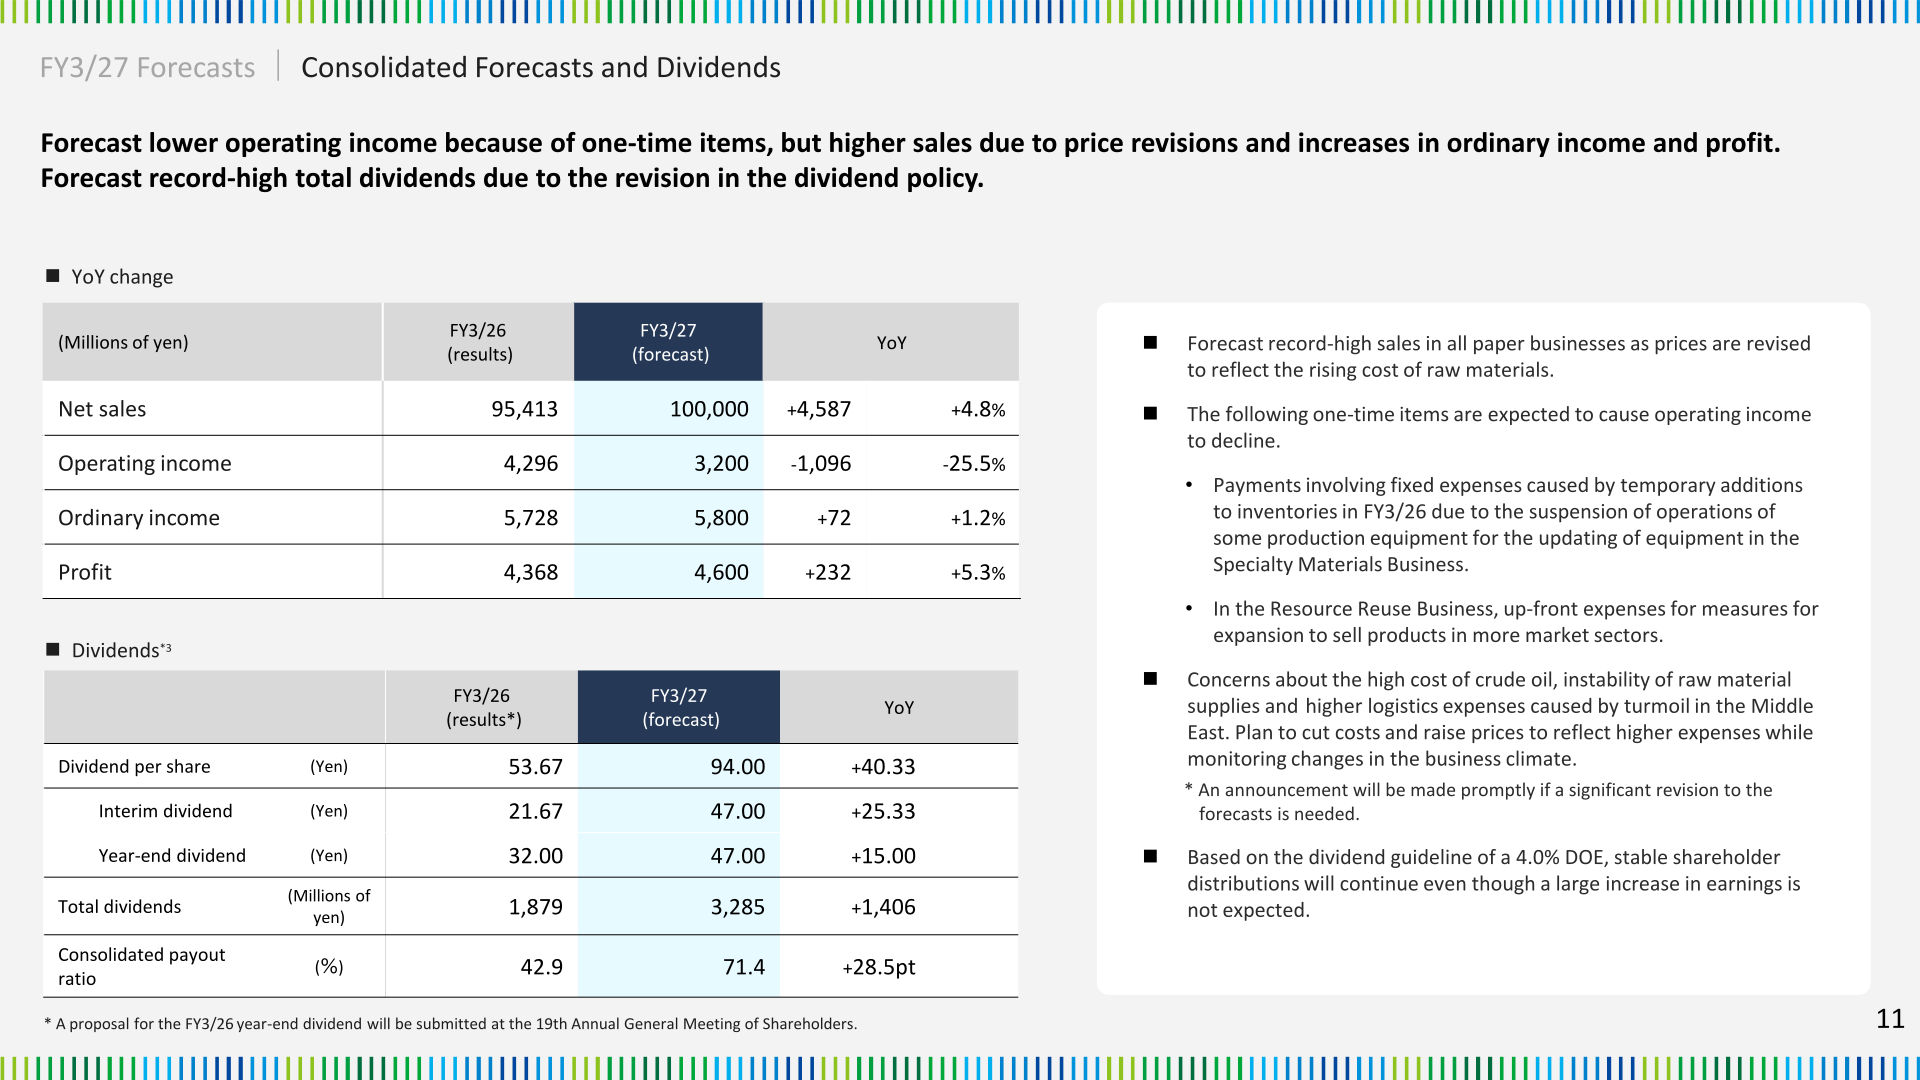
For FY3/27, TTP forecasts record-high sales in all paper businesses as prices are revised to reflect the rising cost of raw materials, and increases in ordinary income and profit. Operating income is expected to decline because of one-time items: payments involving fixed expenses caused by temporary additions to inventories in FY3/26 due to the suspension of some production equipment for equipment updating in the Specialty Materials Business, and up-front expenses in the Resource Reuse Business for expansion into more market sectors. The company expects higher ordinary income because of an increase in equity-method income. It also cites concerns about the high cost of crude oil, instability of raw material supplies and higher logistics expenses caused by turmoil in the Middle East, and plans to cut costs and raise prices while monitoring the business climate.
| Item (Millions of yen) | FY3/26 (results) | FY3/27 (forecast) | YoY | YoY (%) |
|---|---|---|---|---|
| Net sales | 95,413 | 100,000 | +4,587 | +4.8% |
| Operating income | 4,296 | 3,200 | -1,096 | -25.5% |
| Ordinary income | 5,728 | 5,800 | +72 | +1.2% |
| Profit | 4,368 | 4,600 | +232 | +5.3% |
Shareholder Returns
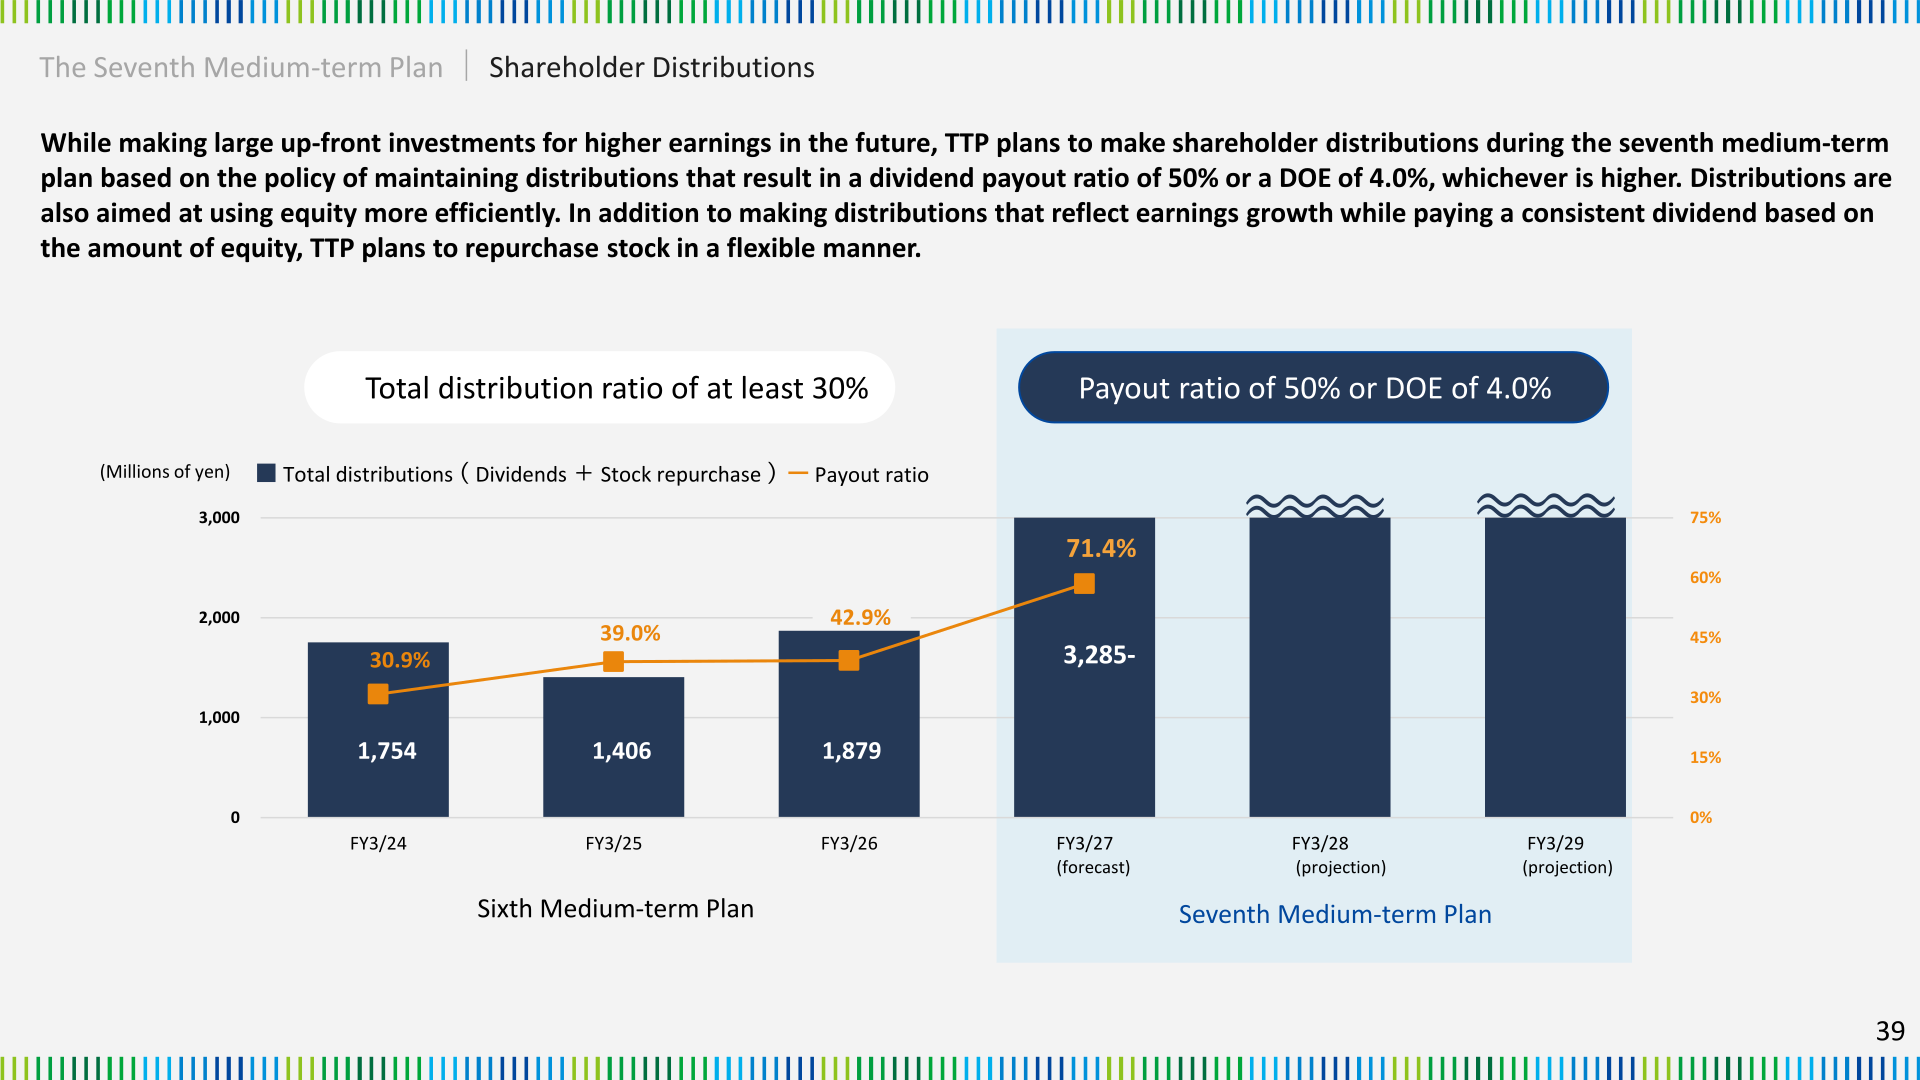
TTP raised the FY3/26 fiscal year-end dividend forecast from 20 yen to 32 yen per share, bringing the annual dividend to 53.67 yen (adjusted for the three-for-one stock split effective October 1, 2025) and the consolidated payout ratio to 42.9%. A proposal for the FY3/26 year-end dividend was to be submitted at the June 2026 shareholders meeting. For FY3/27, the company forecasts a dividend per share of 94.00 yen (interim 47.00 yen, year-end 47.00 yen) and record-high total dividends of 3,285 million yen, with a consolidated payout ratio of 71.4%.
| Dividends | FY3/25 (results) | FY3/26 (results) | FY3/27 (forecast) |
|---|---|---|---|
| Dividend per share (Yen) | 40.00 | 53.67 | 94.00 |
| Interim dividend (Yen) | 20.00 | 21.67 | 47.00 |
| Year-end dividend (Yen) | 20.00 | 32.00 | 47.00 |
| Total dividends (Millions of yen) | 1,405 | 1,879 | 3,285 |
| Consolidated payout ratio (%) | 39.0 | 42.9 | 71.4 |
Under the Sixth Medium-term Plan, the policy was a total distribution ratio of at least 30%. During the Seventh Medium-term Plan, TTP plans to make shareholder distributions based on a dividend payout ratio of 50% or a DOE of 4.0%, whichever is higher, and to repurchase stock in a flexible manner. The company states that, based on the 4.0% DOE guideline, stable shareholder distributions will continue even though a large increase in earnings is not expected in FY3/27.
Seventh Medium-term Plan and VISION 2035
Under the Sixth Medium-term Plan, the company reports three consecutive years of operating income growth and two consecutive years of ordinary income growth to all-time highs, but the final-year targets (operating income 5,000 million yen, ordinary income 8,000 million yen, ROE 7.0%) were not accomplished due to slower than planned actions for growth and higher sales. The company notes that the ROE was below the estimated cost of capital of 9.0% and the PBR is still below one.
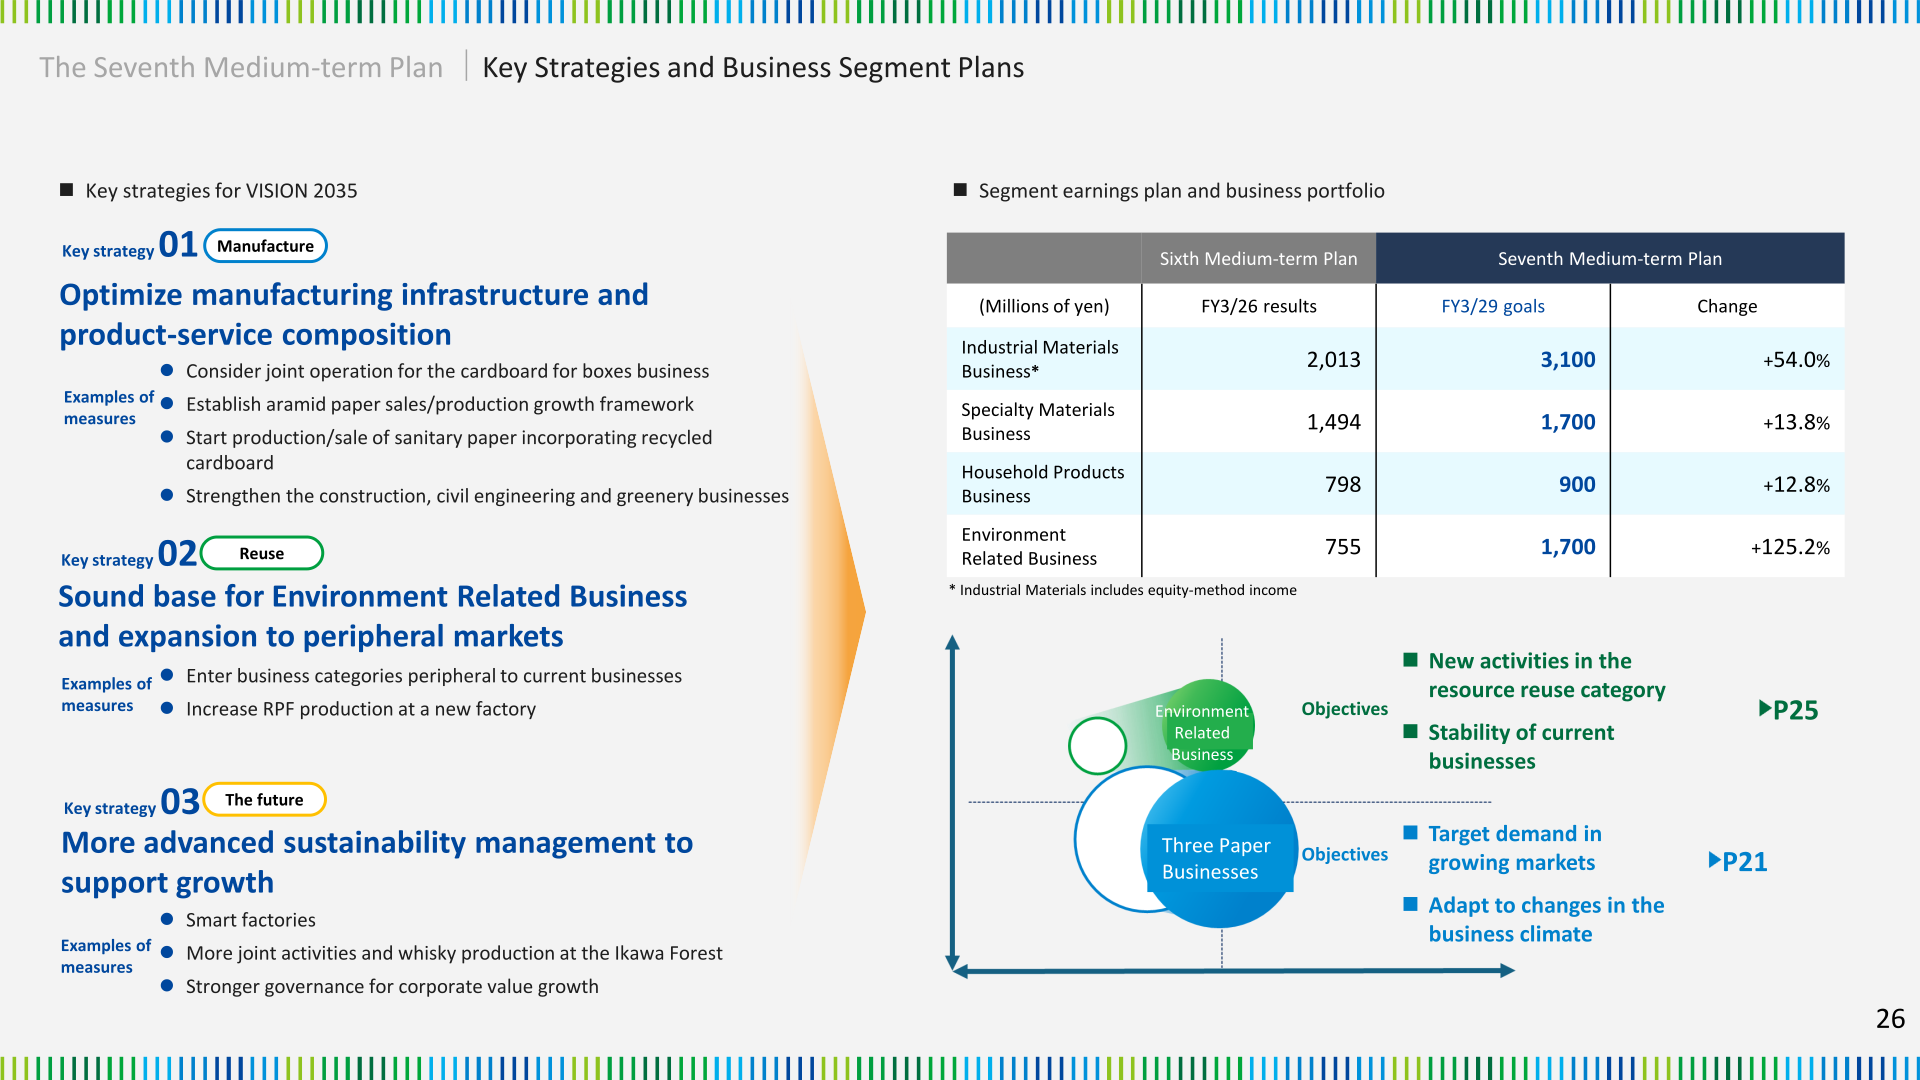
The Seventh Medium-term Plan (FY3/27-FY3/29) is positioned as the first step toward VISION 2035, with goals of ordinary income of ¥8.0 billion and an ROE of at least 7.0% in FY3/29. Under VISION 2035, the milestones are ordinary income of ¥10.0 billion and ROE of at least 8.0% under the Eighth Medium-term Plan, and ordinary income of ¥13.0 billion and ROE of at least 9.0% under the Ninth Medium-term Plan. Key measures include considering joint operation for the cardboard for boxes business, establishing an aramid paper sales/production growth framework, starting production and sale of sanitary paper incorporating recycled cardboard, and increasing RPF (plastics densified fuel) production at a new factory.
| Segment profit (Millions of yen) | FY3/26 results | FY3/29 goals | Change |
|---|---|---|---|
| Industrial Materials Business (includes equity-method income) | 2,013 | 3,100 | +54.0% |
| Specialty Materials Business | 1,494 | 1,700 | +13.8% |
| Household Products Business | 798 | 900 | +12.8% |
| Environment Related Business | 755 | 1,700 | +125.2% |
In its three-year cash allocation plan (FY3/27-FY3/29), TTP expects cash flows from operating activities of ¥40 billion to be the primary source of funds, with interest-bearing debt used for M&A and other investments for growth. The company aims to lower the equity ratio to about 50% by the end of the Seventh Medium-term Plan. To raise the PBR (0.67 times in FY3/26) to 1.0, TTP lists three actions: higher return, control of the level of equity through increased shareholder distributions, and more IR and disclosure activities to raise investors’ expectations.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.















