

This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: CERES Inc. has a December fiscal year-end; FY2025 in this article refers to the fiscal year ended December 31, 2025, as labeled in the company’s materials.
CERES Inc. reported FY2025 net sales of 29,660 million yen (+7.1% YoY), a record high, as the Point business grew revenue by 39.4% YoY despite revenue declines in D2C and Mercury and the deconsolidation of YUMEMI. EBITDA rose 71.4% YoY to 5,392 million yen, supported by strong performance at Moppy and an extraordinary gain of approximately ¥2.7 bn from the sale of shares in subsidiary YUMEMI. The company also withdrew its previous medium-term plan and announced the new Medium-Term Management Plan 2030, targeting ¥60.0 bn in net sales, ¥12.0 bn in EBITDA and ROE of 15%.
Consolidated Results (Full-Year Actual)
Operating profit was 2,334 million yen (+4.8% YoY), roughly flat, as point business growth offset declines in D2C and Mercury. Ordinary profit declined 21.4% to 2,105 million yen, reflecting a reversal at bitbank from a ¥472 million profit to an approximately 200 million loss. Profit attributable to owners of parent rose 68.6% to 2,497 million yen. According to the company, FY2024 results include three months of YUMEMI’s performance, while FY2025 results exclude it due to deconsolidation.
| Item (Millions of yen) | FY2025 | FY2024 | YoY |
|---|---|---|---|
| Net sales | 29,660 | 27,706 | +7.1% |
| Gross profit | 13,017 | 13,335 | -2.4% |
| SG&A expenses | 10,682 | 11,107 | -3.8% |
| Operating profit | 2,334 | 2,228 | +4.8% |
| Ordinary profit | 2,105 | 2,677 | -21.4% |
| Profit attributable to owners of parent | 2,497 | 1,480 | +68.6% |
| EBITDA | 5,392 | 3,146 | +71.4% |
Against the revised forecast announced on May 30, 2025, net sales reached 104.4% as strong performance in the point business more than offset weaker-than-expected results in D2C and Mercury, while operating profit reached 81.9% of the revised forecast. On the balance sheet, total assets were 37,504 million yen (FY2024: 32,976 million yen) and total net assets were 13,964 million yen (FY2024: 12,721 million yen).
Segment Results
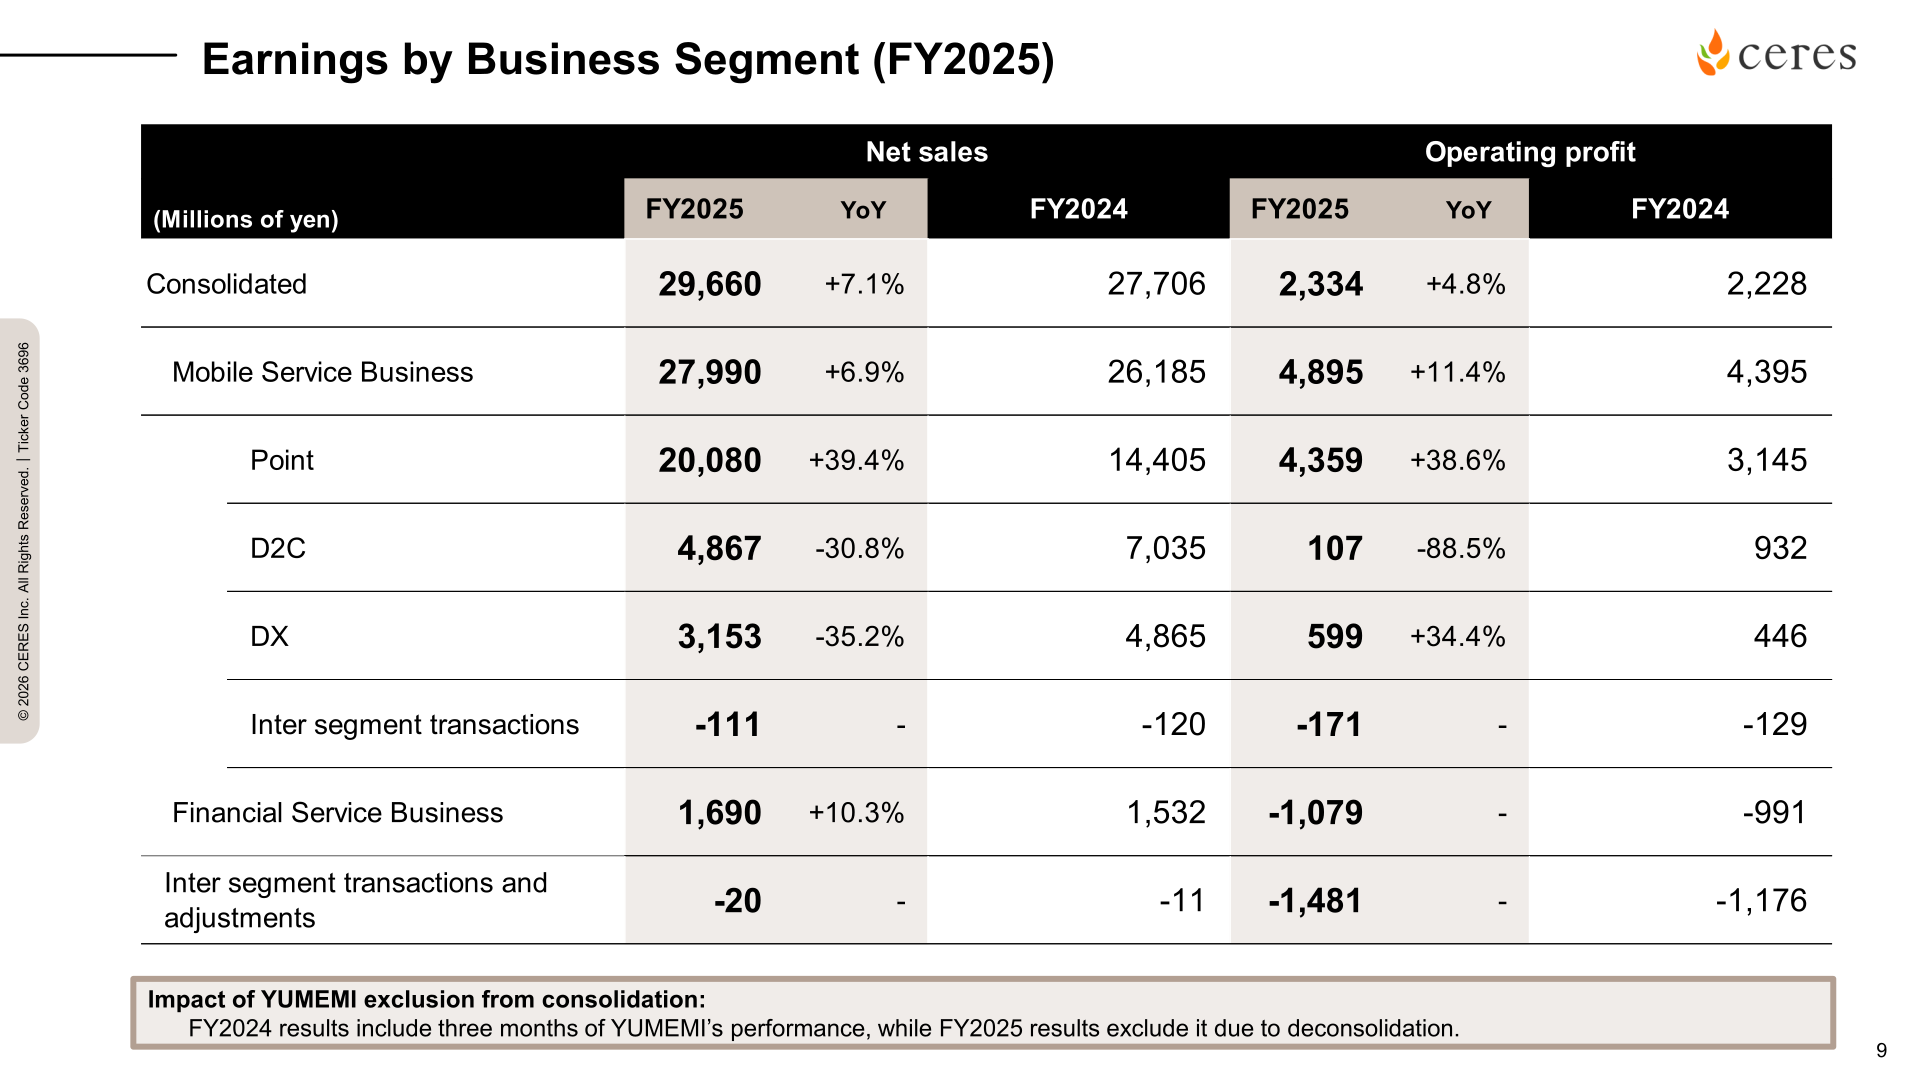
The Mobile Service Business posted record-high net sales of 27,990 million yen (+6.9%) and operating profit of 4,895 million yen (+11.4%), driven by strong growth in the Point business despite YUMEMI’s deconsolidation. Point net sales rose 39.4% to 20,080 million yen and operating profit rose 38.6% to 4,359 million yen. Moppy’s active members reached 6.48 million (YoY +13.4%), and e-commerce GMV via Moppy reached ¥140 billion. D2C net sales fell 30.8% to 4,867 million yen and operating profit fell 88.5% to 107 million yen due to slower sales of the core product Pitsole; inventory valuation losses of approximately ¥170 million were recorded in FY2025.
The Financial Service Business grew net sales 10.3% to 1,690 million yen, supported by strong revenue growth at labol, but recorded a wider operating loss of 1,079 million yen due to the prolonged downturn in the crypto asset market. As of the end of FY2025, altcoin prices were down 18% from the beginning of the year.
| Segment (Millions of yen) | Net sales FY2025 | YoY | Net sales FY2024 | Operating profit FY2025 | YoY | Operating profit FY2024 |
|---|---|---|---|---|---|---|
| Consolidated | 29,660 | +7.1% | 27,706 | 2,334 | +4.8% | 2,228 |
| Mobile Service Business | 27,990 | +6.9% | 26,185 | 4,895 | +11.4% | 4,395 |
| Point | 20,080 | +39.4% | 14,405 | 4,359 | +38.6% | 3,145 |
| D2C | 4,867 | -30.8% | 7,035 | 107 | -88.5% | 932 |
| DX | 3,153 | -35.2% | 4,865 | 599 | +34.4% | 446 |
| Inter segment transactions | -111 | – | -120 | -171 | – | -129 |
| Financial Service Business | 1,690 | +10.3% | 1,532 | -1,079 | – | -991 |
| Inter segment transactions and adjustments | -20 | – | -11 | -1,481 | – | -1,176 |
FY2026 Forecast
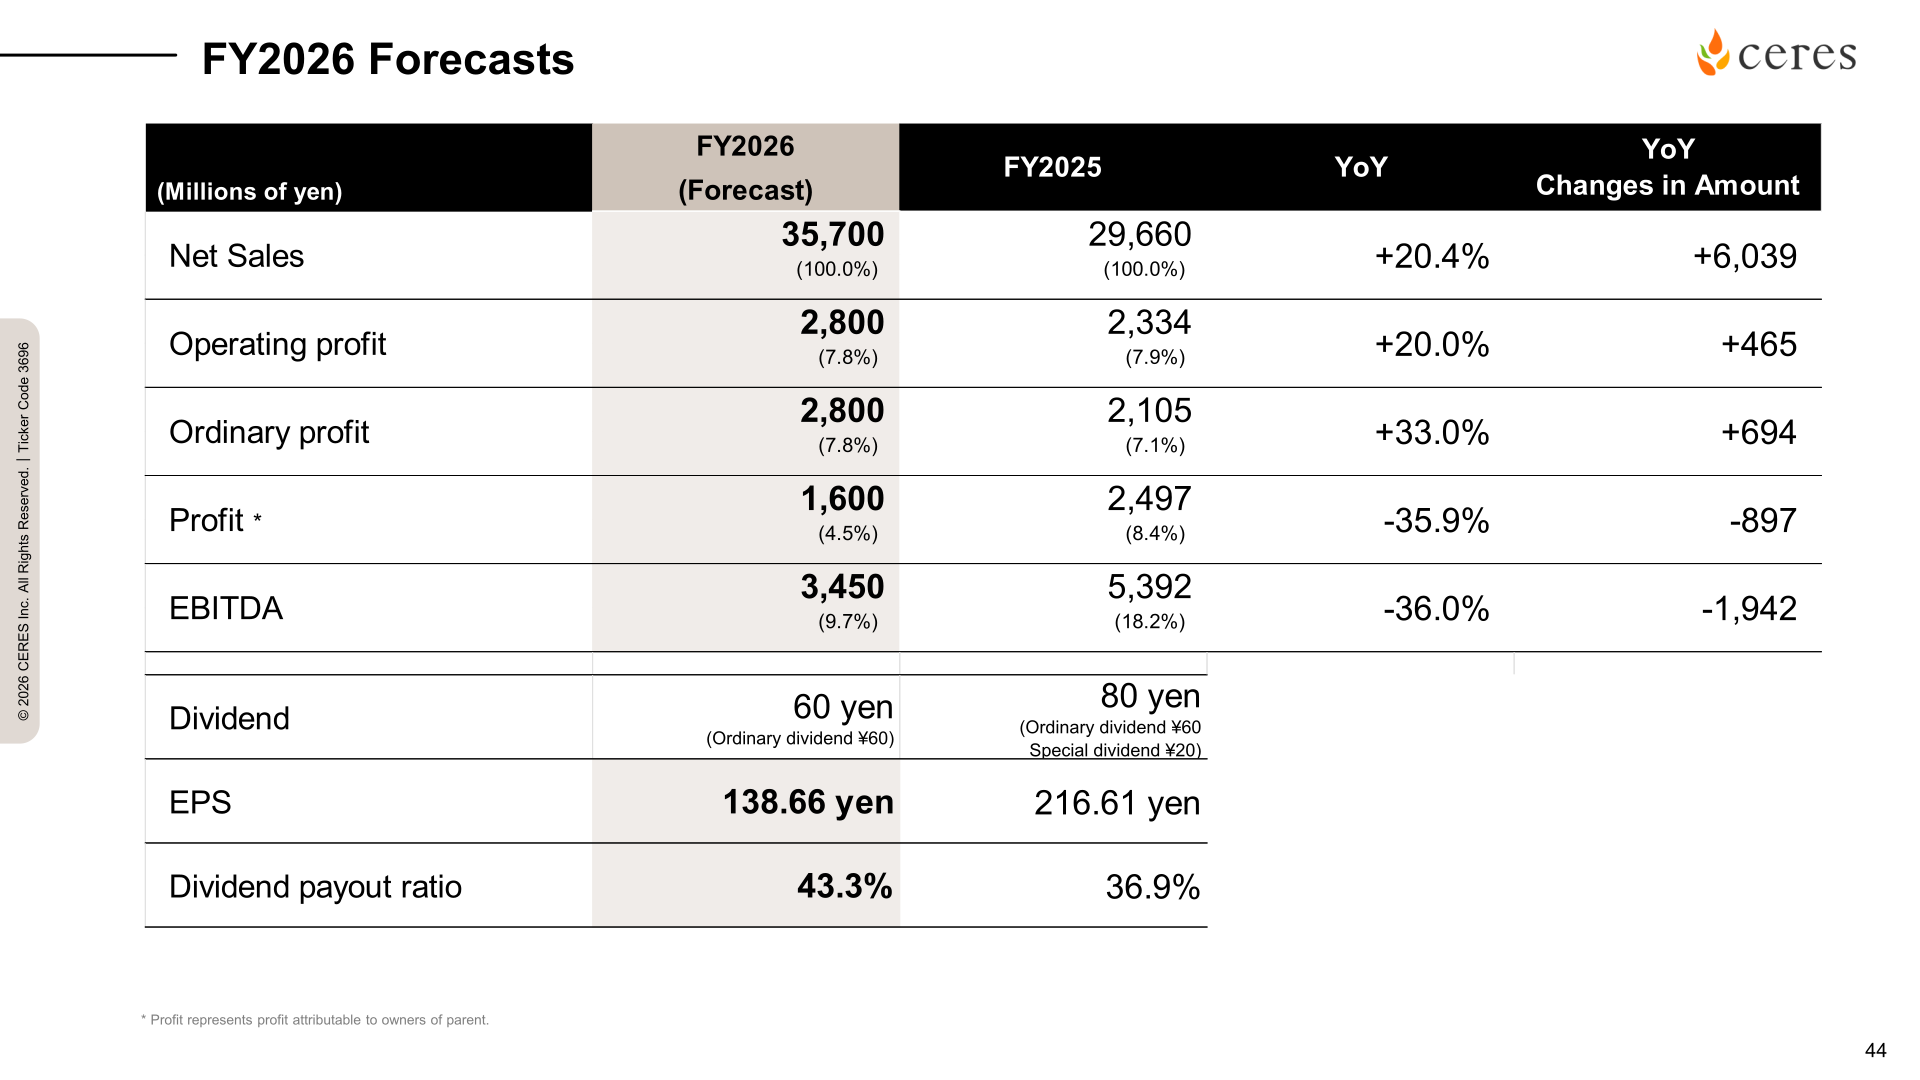
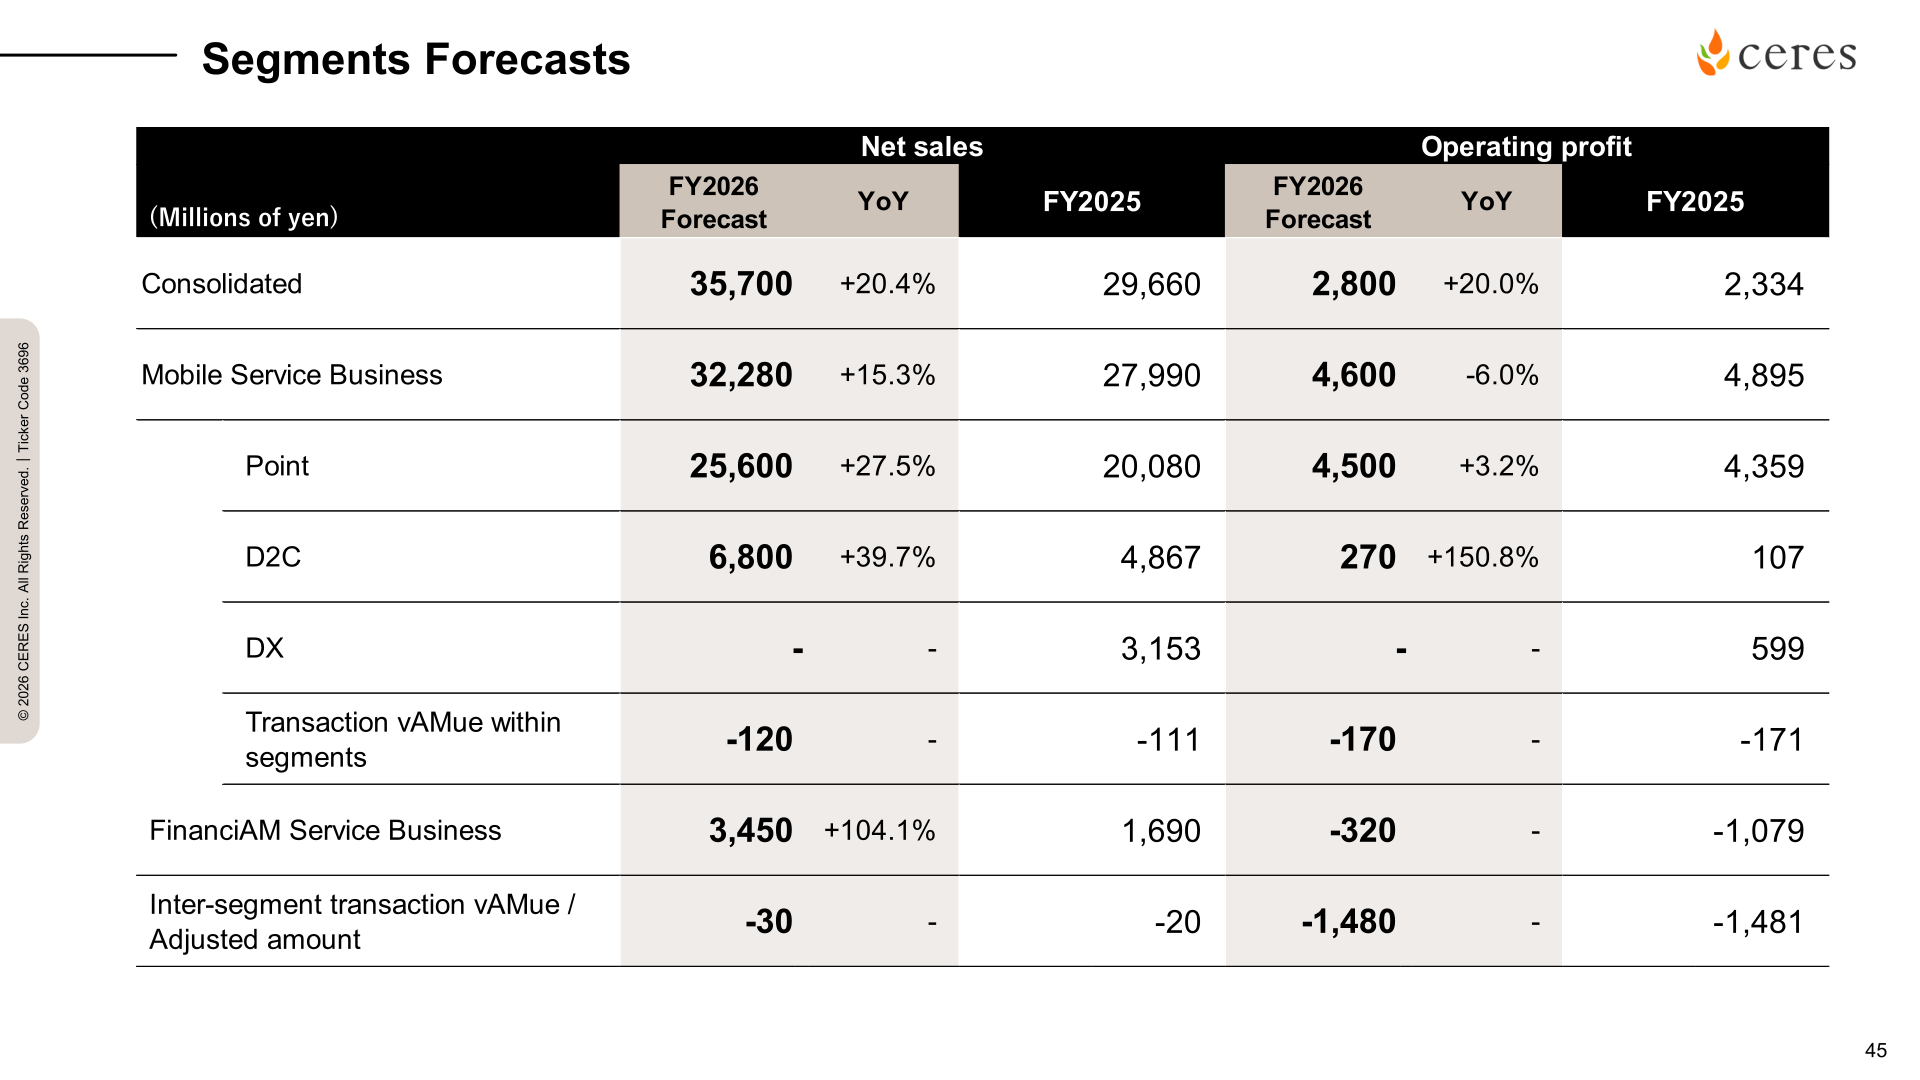
For FY2026, the company forecasts net sales of 35,700 million yen (+20.4%) and operating profit of 2,800 million yen (+20.0%). Ordinary profit is expected to rise 33.0% to 2,800 million yen, while profit attributable to owners of parent is forecast to decline 35.9% to 1,600 million yen and EBITDA to decline 36.0% to 3,450 million yen. By segment, Point net sales are forecast at 25,600 million yen (+27.5%), D2C at 6,800 million yen (+39.7%) and Financial Service at 3,450 million yen (+104.1%), with the Financial Service operating loss forecast to narrow to -320 million yen.
| Item (Millions of yen) | FY2026 Forecast | FY2025 | YoY | Change in amount |
|---|---|---|---|---|
| Net sales | 35,700 | 29,660 | +20.4% | +6,039 |
| Operating profit | 2,800 | 2,334 | +20.0% | +465 |
| Ordinary profit | 2,800 | 2,105 | +33.0% | +694 |
| Profit attributable to owners of parent | 1,600 | 2,497 | -35.9% | -897 |
| EBITDA | 3,450 | 5,392 | -36.0% | -1,942 |
| EPS | 138.66 yen | 216.61 yen | – | – |
Shareholder Returns
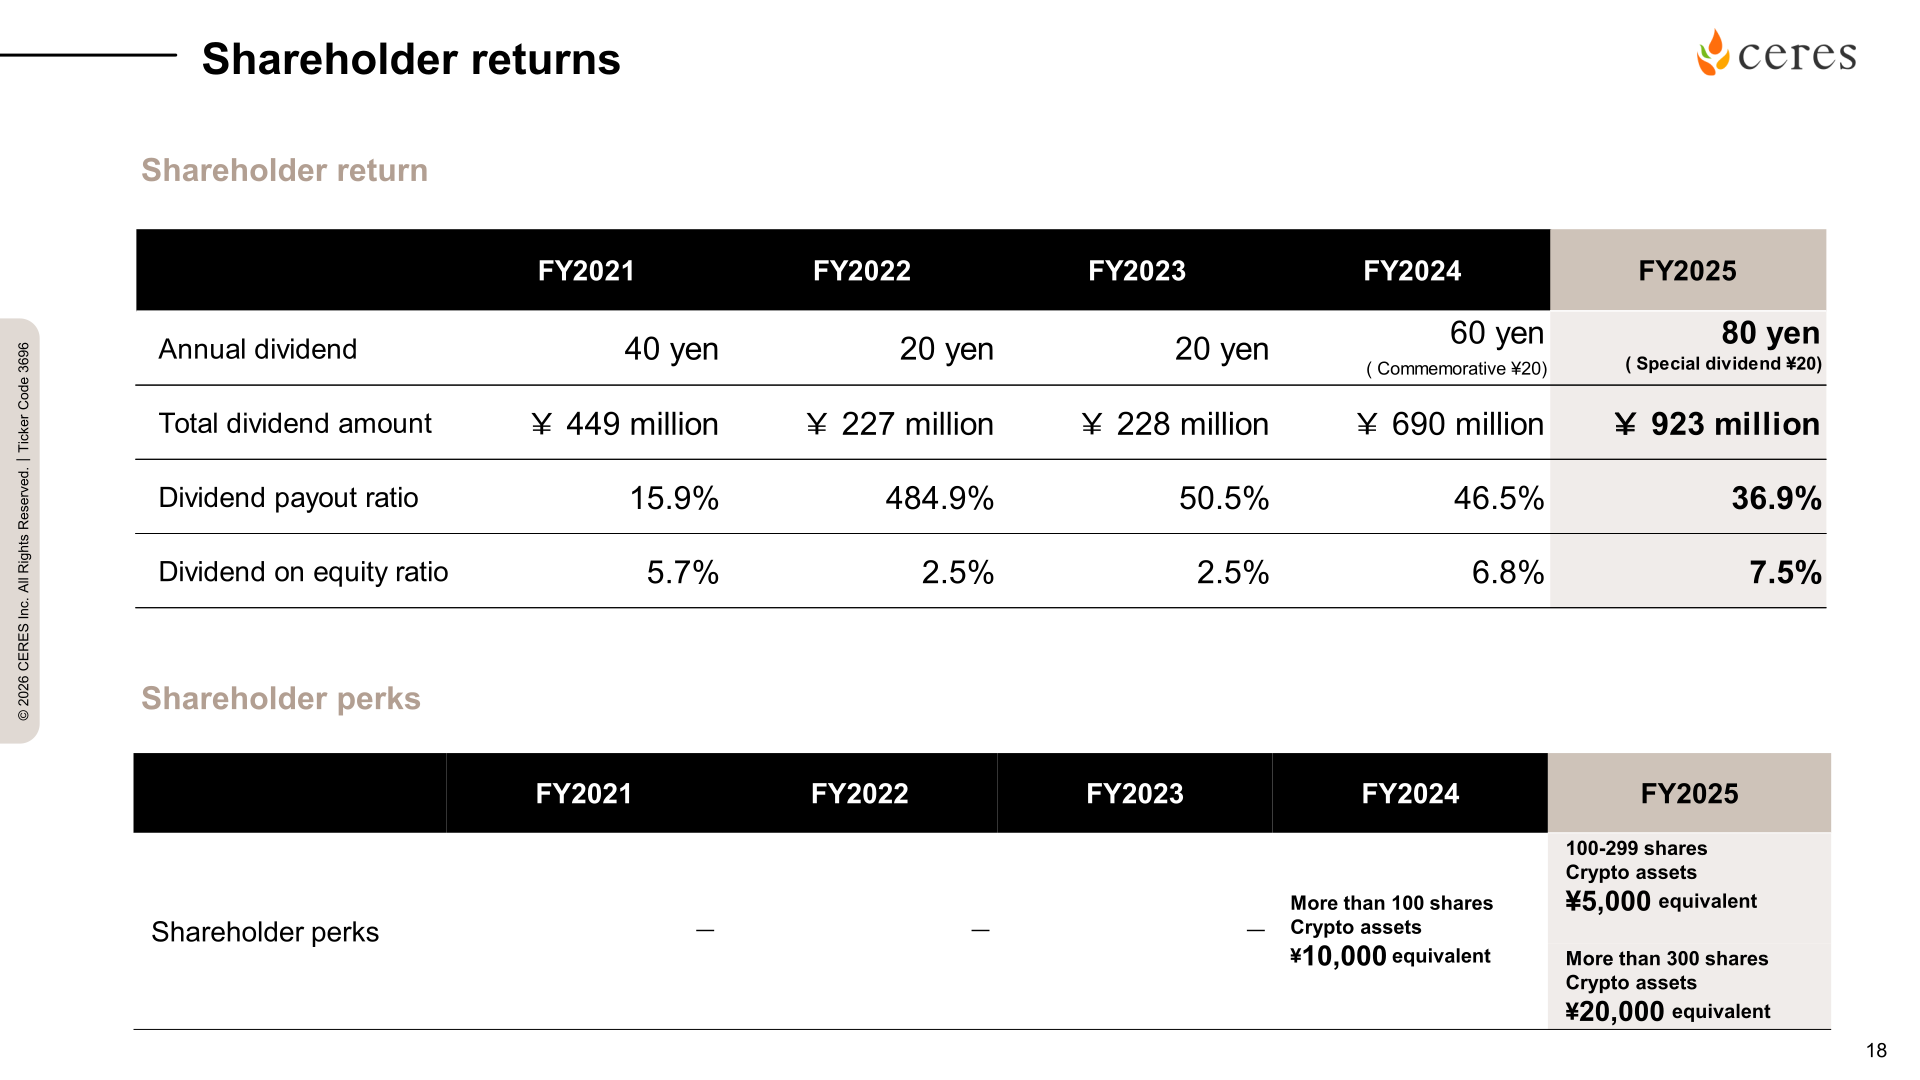
The annual dividend for FY2025 was 80 yen, including a special dividend of ¥20, for a total dividend amount of ¥923 million, a dividend payout ratio of 36.9% and a dividend on equity ratio of 7.5%. For FY2026, the company plans an annual dividend of 60 yen (ordinary dividend ¥60), with a forecast dividend payout ratio of 43.3%. As a shareholder perk for FY2025, shareholders holding 100-299 shares receive crypto assets equivalent to ¥5,000, and those holding more than 300 shares receive crypto assets equivalent to ¥20,000.
| Item | FY2026 Forecast | FY2025 | FY2024 |
|---|---|---|---|
| Annual dividend | 60 yen (Ordinary dividend ¥60) | 80 yen (Special dividend ¥20) | 60 yen (Commemorative ¥20) |
| Total dividend amount | – | ¥ 923 million | ¥ 690 million |
| Dividend payout ratio | 43.3% | 36.9% | 46.5% |
| Dividend on equity ratio | – | 7.5% | 6.8% |
Medium-Term Management Plan 2030
In light of strategic portfolio optimization and prolonged crypto market weakness, CERES withdrew the Medium-Term Management Plan announced in December 2021 and announced the Medium-Term Management Plan 2030 (2026-2030). Targets for FY2030 are net sales of ¥60bn (CAGR FY2025-2030: 15.1%), EBITDA of ¥12bn (CAGR FY2025-2030: 17.4%) and ROE of 15%, compared with an average ROE of 15.2% for FY2021-2025. By business, the FY2030 targets are net sales of ¥35.0bn and EBITDA of ¥6.0bn for Point (with 10 million Moppy active members), net sales of ¥15.0bn and EBITDA of ¥2.0bn for D2C, and net sales of ¥10.0bn and EBITDA of ¥4.0bn for Financial Services.
During FY2025, the company divested YUMEMI to reallocate capital to higher-synergy businesses, acquired the Point Income business through a business transfer, made CyberBuzz an equity-method affiliate and consolidated two D2C companies into the Group.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.















