
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Kanamic Network’s fiscal year ends in September; “FY2025” in this article refers to the fiscal year ended September 30, 2025, as labeled in the company’s “FY2025 Financial Results and Company Information” presentation dated November 13, 2025. The company reported record-high sales and profits since listing, with consolidated net sales of 5,500 million JPY (YoY 109.9%) and EBITDA of 2,024 million JPY (YoY 112.8%). All three segments achieved increased sales and profits, and profit margins improved across all segments. For FY2026 the company forecasts sales of 6,350, EBITDA of 2,500 and operating profit of 2,050, and plans to raise the dividend to 9.00 JPY.
Consolidated Results (Full-Year Actual)
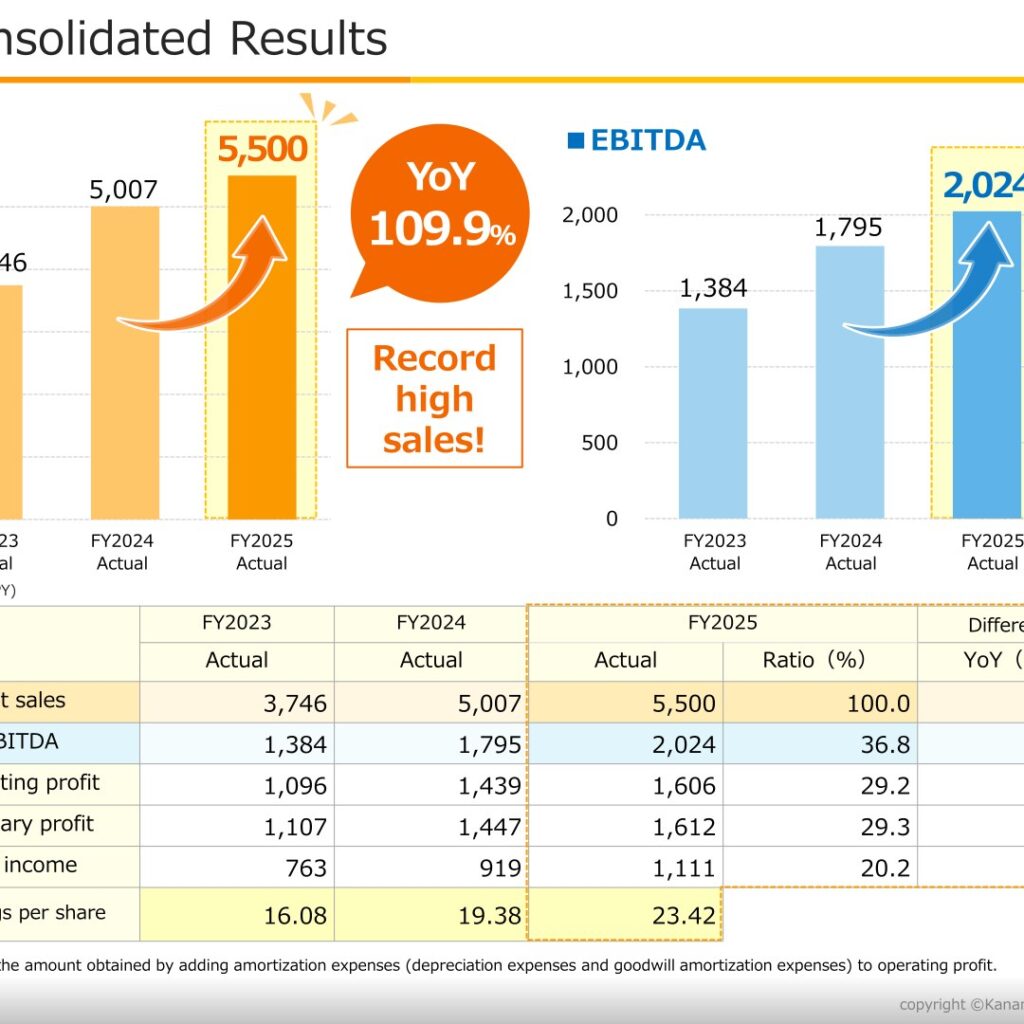
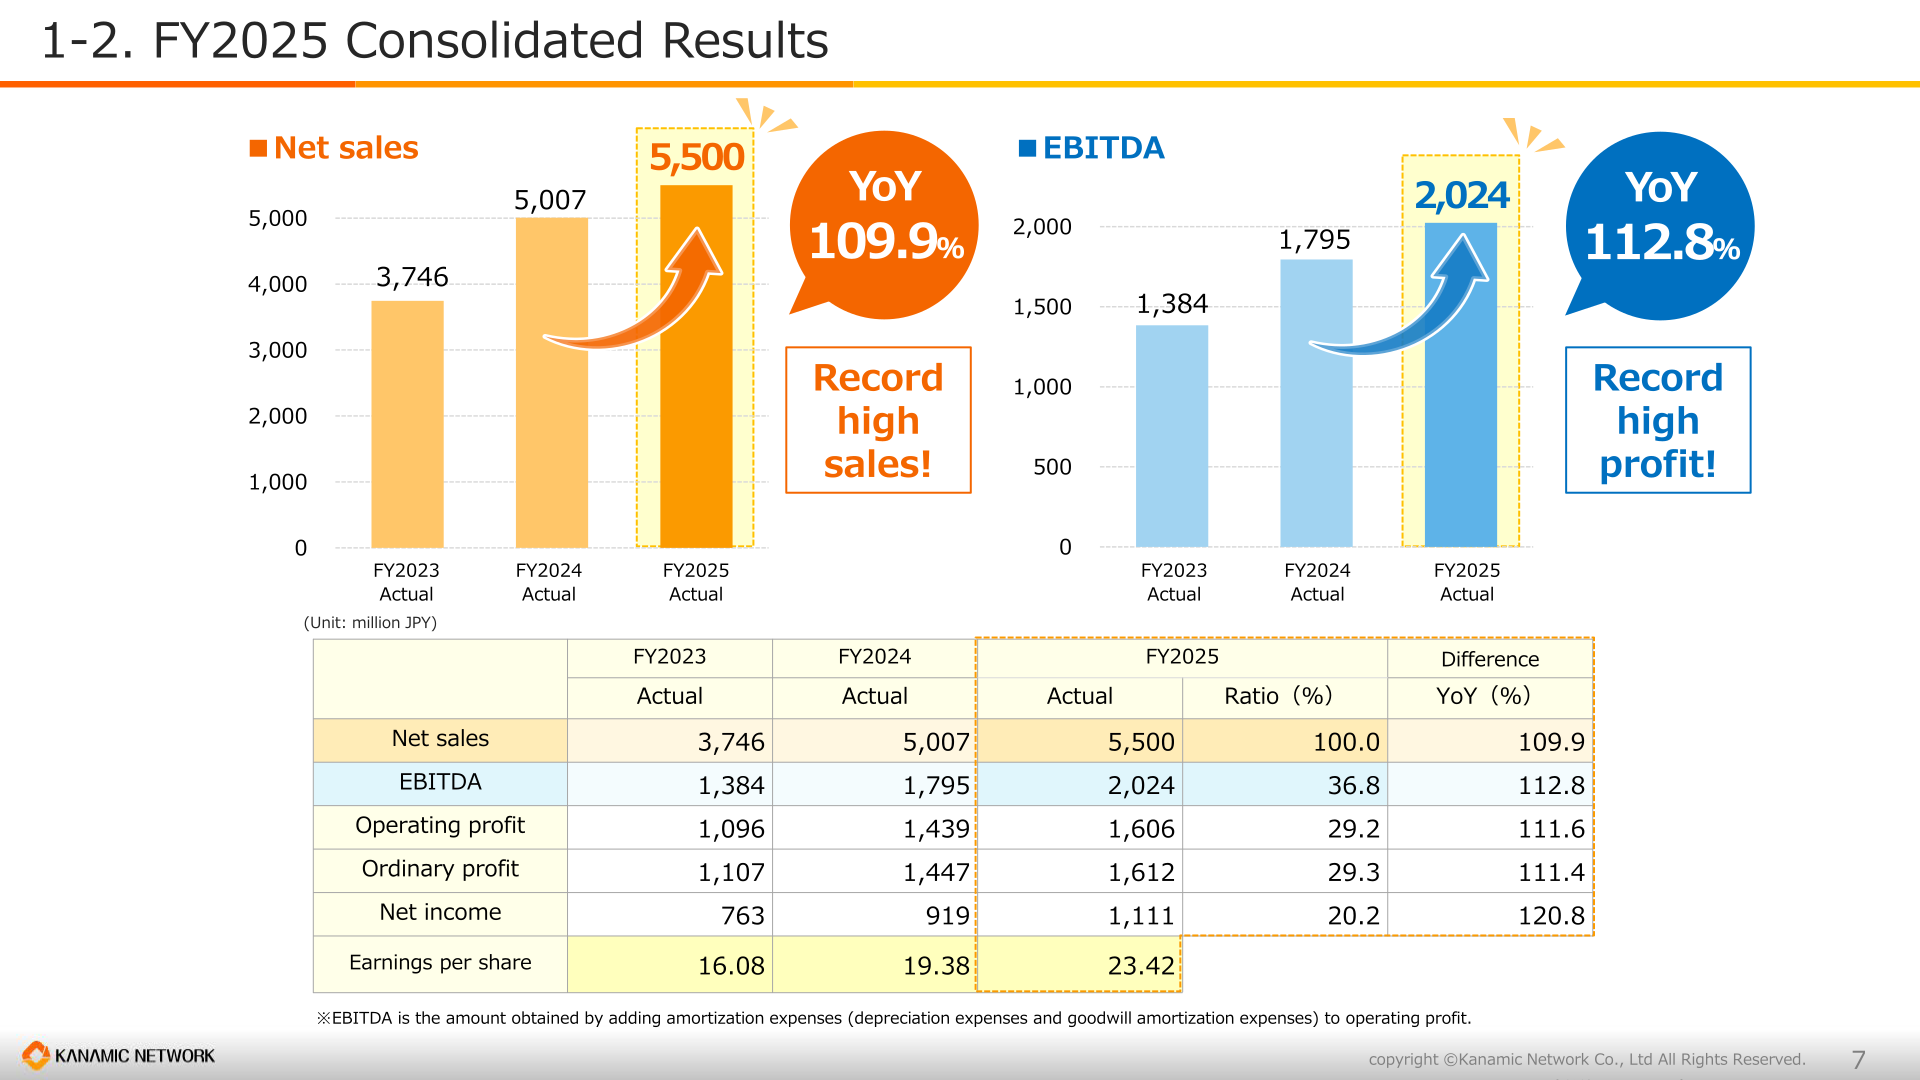
Net sales rose to 5,500 million JPY from 5,007 million JPY (YoY 109.9%). Operating profit was 1,606 million JPY (YoY 111.6%), ordinary profit 1,612 million JPY (YoY 111.4%) and net income 1,111 million JPY (YoY 120.8%). EBITDA, defined by the company as operating profit plus amortization (depreciation and amortization of goodwill), reached 2,024 million JPY (YoY 112.8%). Earnings per share were 23.42 JPY, compared with 19.38 JPY in FY2024. The presentation describes the year as “Record high sales!” and “Record high profit!”.
| Item (million JPY) | FY2023 Actual | FY2024 Actual | FY2025 Actual | Ratio (%) | YoY (%) |
|---|---|---|---|---|---|
| Net sales | 3,746 | 5,007 | 5,500 | 100.0 | 109.9 |
| EBITDA | 1,384 | 1,795 | 2,024 | 36.8 | 112.8 |
| Operating profit | 1,096 | 1,439 | 1,606 | 29.2 | 111.6 |
| Ordinary profit | 1,107 | 1,447 | 1,612 | 29.3 | 111.4 |
| Net income | 763 | 919 | 1,111 | 20.2 | 120.8 |
| Earnings per share (JPY) | 16.08 | 19.38 | 23.42 | – | – |
Key KPIs also grew. At the end of FY2025 the number of paid user IDs was 221,822 (YoY 116%) and free user IDs 117,497 (YoY 116%). The number of regions was 1,397 (YoY 100.9%), and URBANFIT stores totaled 24 as of the end of September 2025 (YoY 109.1%). The company describes the number of paid users, free users and offices as its most important KPIs, all of which maintained significant increases compared to the previous period.
Segment Results
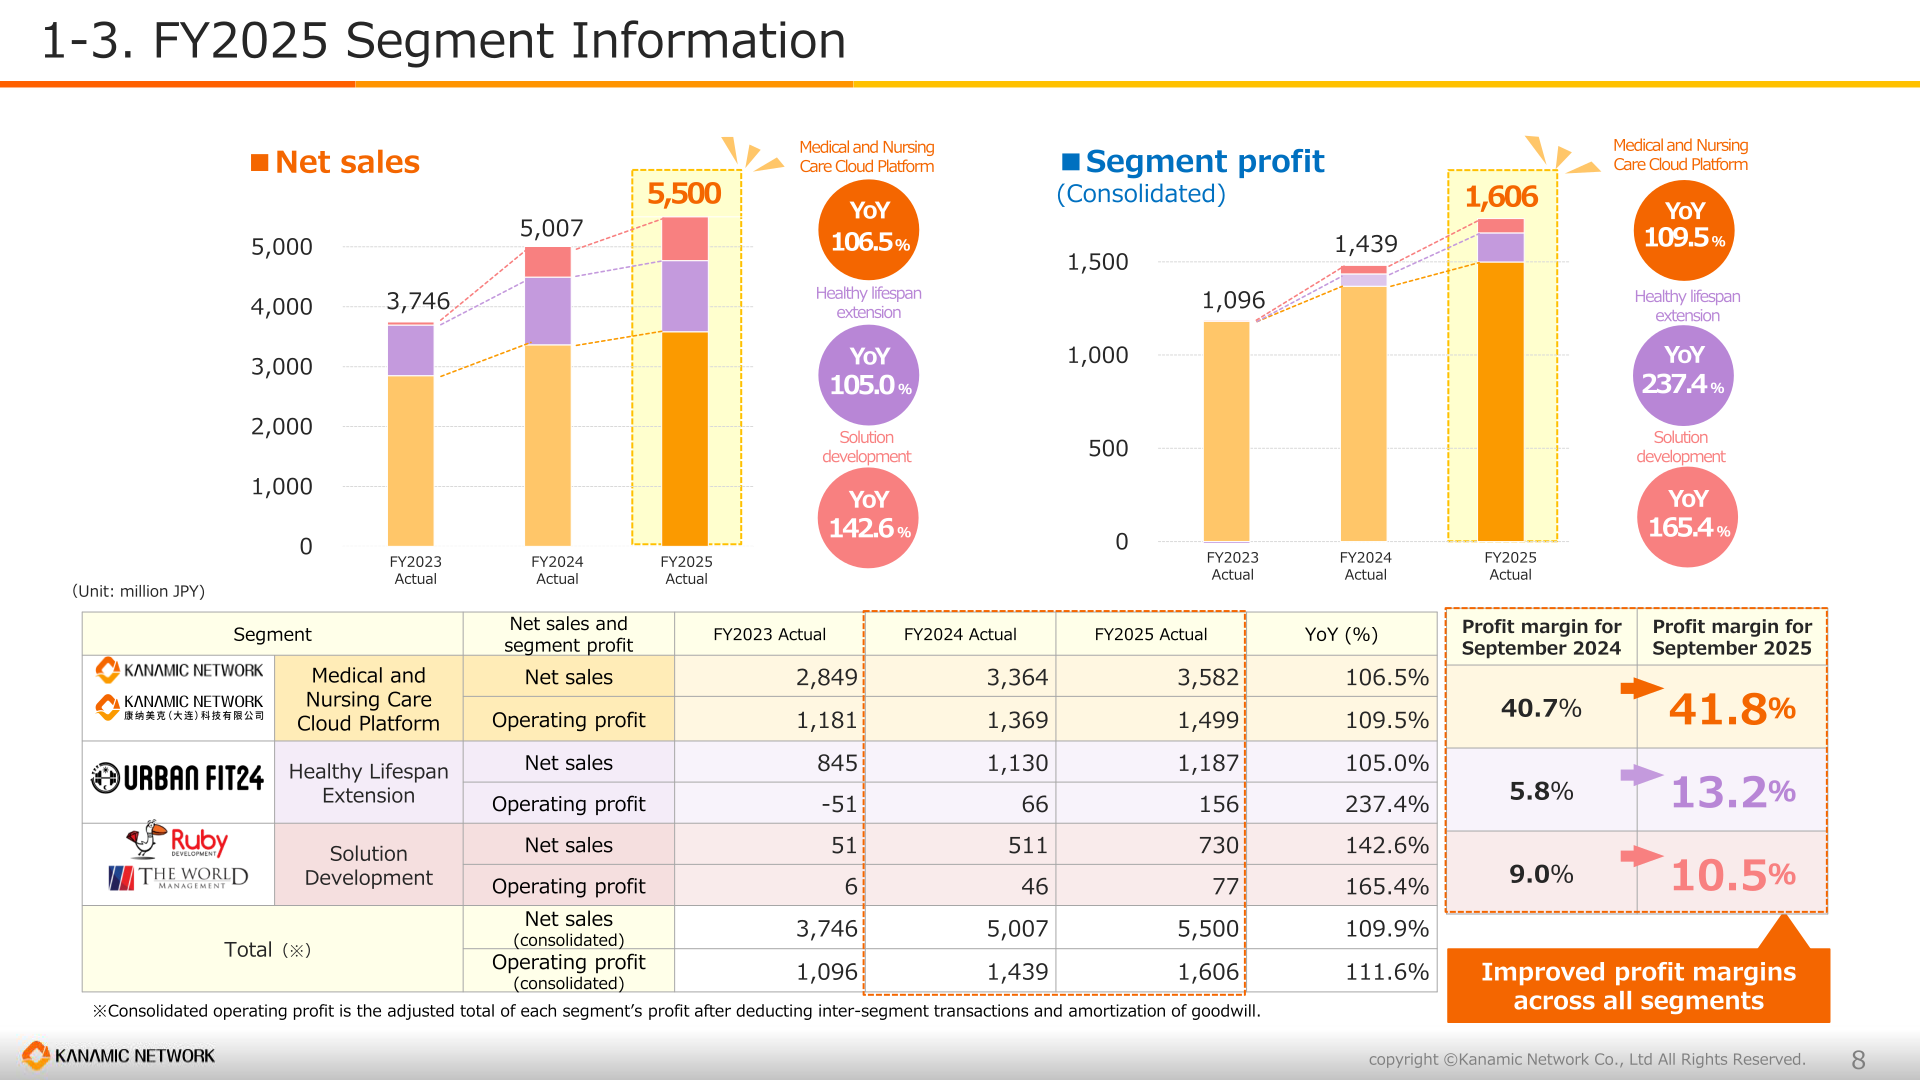
The Medical and Nursing Care Cloud Platform segment, the core business, grew net sales to 3,582 million JPY (106.5%) and operating profit to 1,499 million JPY (109.5%), lifting its profit margin from 40.7% to 41.8%. The Healthy Lifespan Extension segment, which operates the URBAN FIT24 fitness gyms, increased net sales to 1,187 million JPY (105.0%) and operating profit to 156 million JPY (237.4%), with the profit margin improving from 5.8% to 13.2%. The Solution Development segment, which includes Ruby Development and The World Management, grew net sales to 730 million JPY (142.6%) and operating profit to 77 million JPY (165.4%), with a margin of 10.5% versus 9.0%. Consolidated operating profit is the adjusted total of each segment’s profit after deducting inter-segment transactions and amortization of goodwill.
| Segment | Metric | FY2024 Actual | FY2025 Actual | YoY (%) |
|---|---|---|---|---|
| Medical and Nursing Care Cloud Platform | Net sales | 3,364 | 3,582 | 106.5% |
| Medical and Nursing Care Cloud Platform | Operating profit | 1,369 | 1,499 | 109.5% |
| Healthy Lifespan Extension | Net sales | 1,130 | 1,187 | 105.0% |
| Healthy Lifespan Extension | Operating profit | 66 | 156 | 237.4% |
| Solution Development | Net sales | 511 | 730 | 142.6% |
| Solution Development | Operating profit | 46 | 77 | 165.4% |
| Total | Net sales (consolidated) | 5,007 | 5,500 | 109.9% |
| Total | Operating profit (consolidated) | 1,439 | 1,606 | 111.6% |
FY2026 Forecast
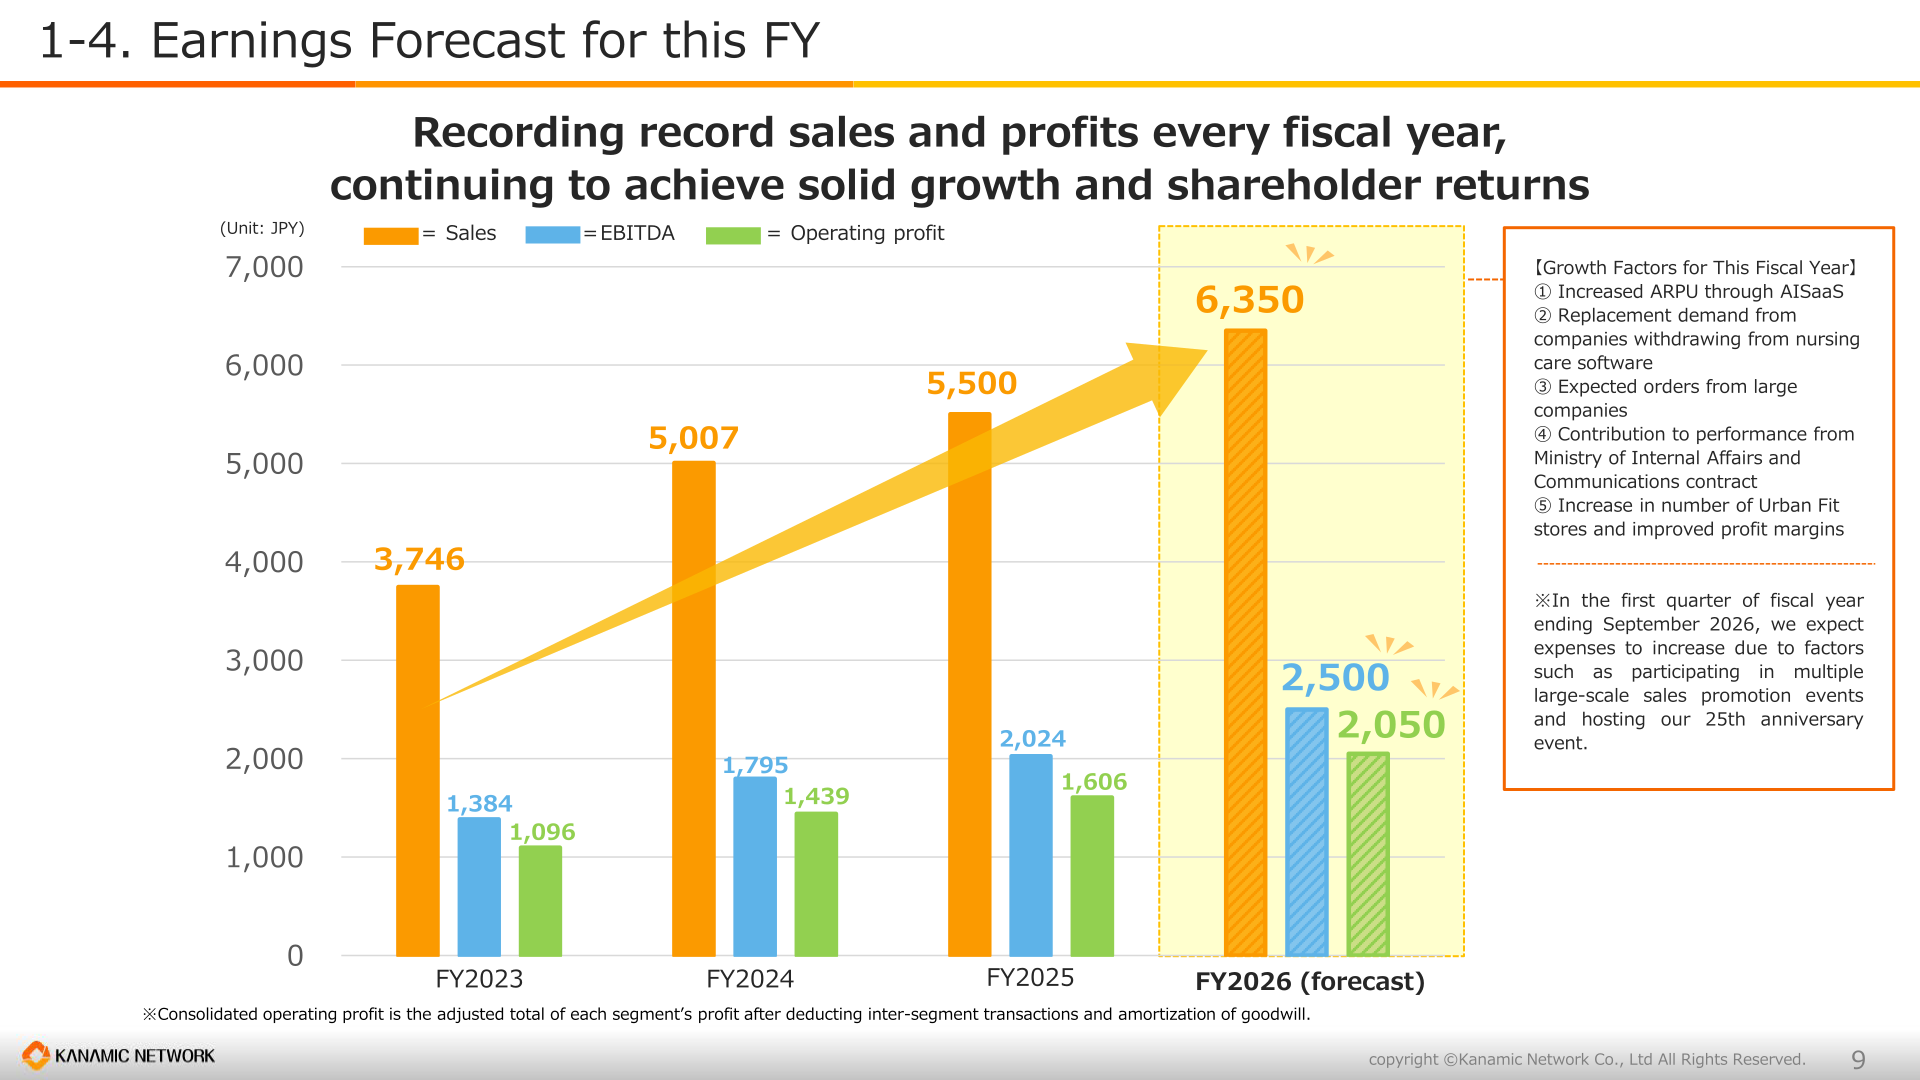
For the fiscal year ending September 2026, the company forecasts sales of 6,350, EBITDA of 2,500 and operating profit of 2,050, under the headline “Recording record sales and profits every fiscal year, continuing to achieve solid growth and shareholder returns.” Its long-term trend slide lists FY2026 net sales of 6.35B JPY and operating profit of 2.05B JPY, with a profit margin of 32.3%. Growth factors cited are (1) increased ARPU through AISaaS, (2) replacement demand from companies withdrawing from nursing care software, (3) expected orders from large companies, (4) contribution to performance from a Ministry of Internal Affairs and Communications contract, and (5) an increase in the number of Urban Fit stores and improved profit margins. The company notes that in the first quarter it expects expenses to increase due to factors such as participating in multiple large-scale sales promotion events and hosting its 25th anniversary event.
| Item | FY2026 Forecast | FY2025 Actual |
|---|---|---|
| Sales | 6,350 | 5,500 |
| EBITDA | 2,500 | 2,024 |
| Operating profit | 2,050 | 1,606 |
| Dividend per share (JPY) | 9.00 | 7.50 |
Shareholder Returns
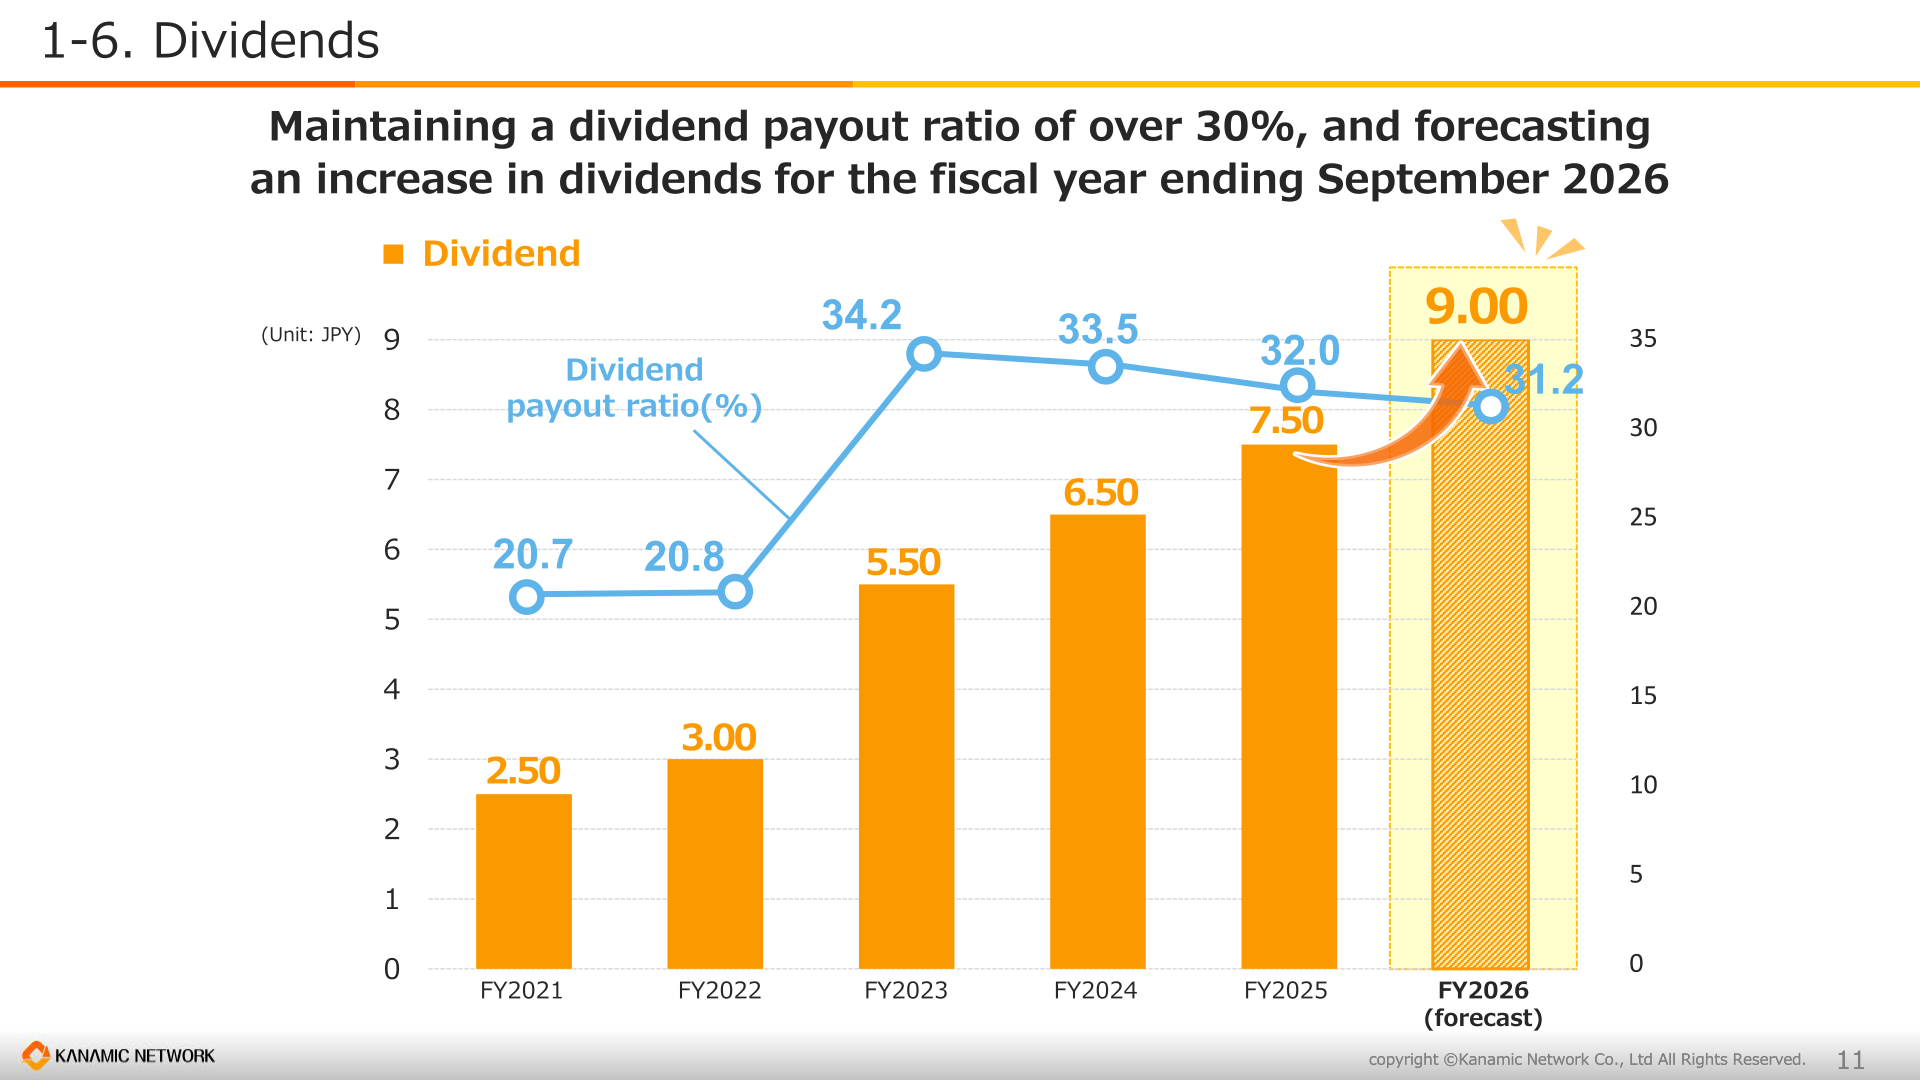
The company pays a dividend of 7.50 JPY per share for FY2025, up from 6.50 JPY in FY2024, for a dividend payout ratio of 32.0%. It is maintaining a dividend payout ratio of over 30% and forecasts an increase in the dividend to 9.00 JPY for the fiscal year ending September 2026 (payout ratio 31.2%). Under its capital allocation policy, above 30% of net profit is to go to shareholder returns and approximately 70% to growth investment and M&A. Shareholder benefits include an Urban Fit 24 voucher for shareholders with 100 shares or more (equivalent to 5,940JPY, tax included) and lottery-based JCB gift cards worth 200,000JPY for 10 winners, plus 3 additional winners among shareholders meeting continuous-holding conditions.
| Fiscal year | Dividend per share (JPY) | Dividend payout ratio (%) |
|---|---|---|
| FY2021 | 2.50 | 20.7 |
| FY2022 | 3.00 | 20.8 |
| FY2023 | 5.50 | 34.2 |
| FY2024 | 6.50 | 33.5 |
| FY2025 | 7.50 | 32.0 |
| FY2026 (forecast) | 9.00 | 31.2 |
Medium- to Long-Term Plan: Kanamic Vision 2035
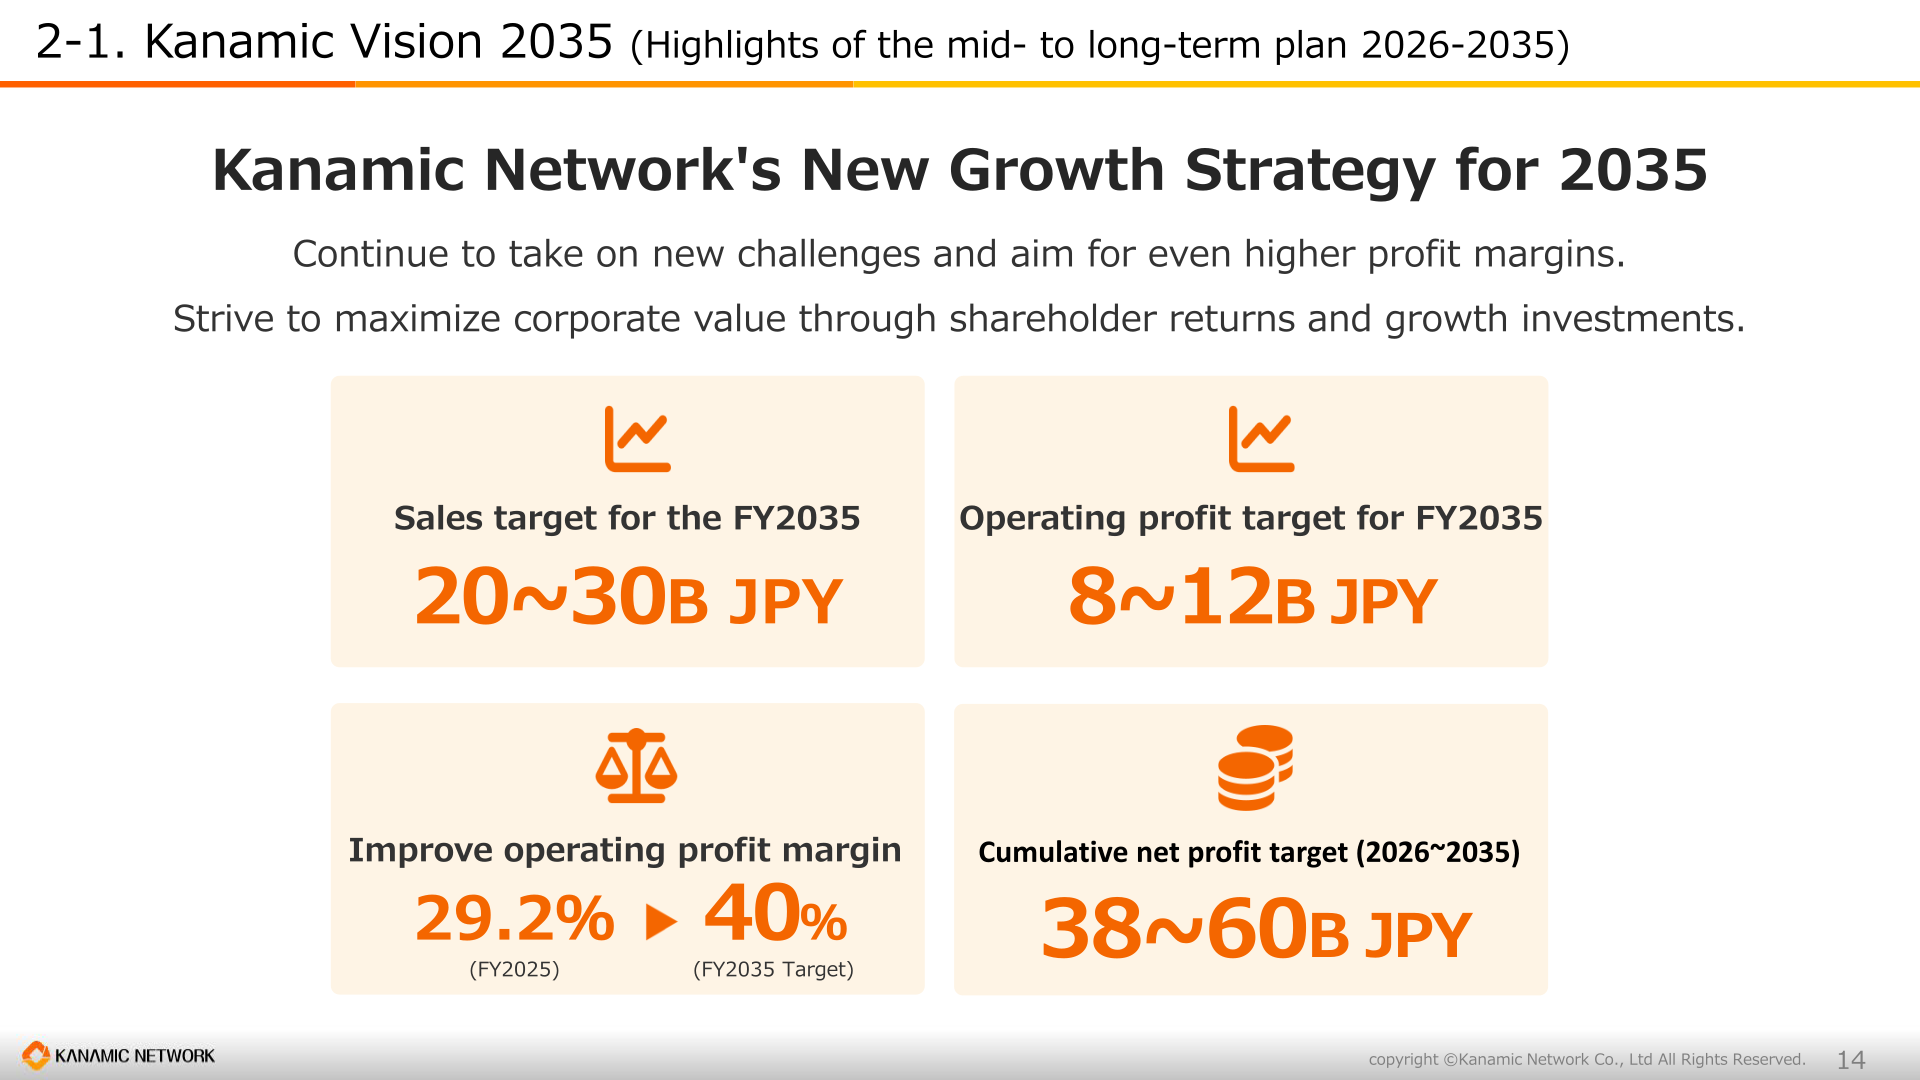
The company formulated Kanamic Vision 2035, a mid- to long-term plan for 2026 to 2035, with the aim of becoming a truly global company that leads the digital transformation of healthcare and nursing care around the world. Targets for FY2035 are sales of 20~30B JPY and operating profit of 8~12B JPY, with the operating profit margin improving from 29.2% (FY2025) to 40%. The cumulative net profit target for 2026~2035 is 38~60B JPY. Interim targets for 2030 are net sales of 10~12B and operating profit of 3.5~4B. The company cites a sales CAGR of 19.2% since listing (FY2016~FY2025) and 13.6~18.8% for the next 10 years (FY2026~FY2035).
By segment, the company targets profit margins in FY2035 of 50% for the cloud service business (41.8% in FY2025), 25% for the healthy lifespan extension business (13.2% in FY2025) and 15% for the solution development business. Levers include improving ARPU through AISaaS following the 2025 release of “AI-100Vision”, accelerating Urban Fit store expansion mainly through franchise stores, and expanding SAP/Sage sales to the ASEAN market from its Singapore base. Its 10-year cumulative targets are 26.5~42B JPY for growth investment and M&A and 11.5~18B JPY for shareholder returns.
Business Topics
Topics during the period include the June 11, 2025 announcement of what the company calls Japan’s first full-scale AI-equipped cloud-based nursing care software (nursing care AI SaaS), selection for the Ministry of Internal Affairs and Communications’ demonstration contract for a medical, nursing care and health information sharing system in Singapore, a contract to design and develop the Tokyo Metropolitan Government ACP portal site, and the release of an AI function that automatically creates home nursing plans. Subsidiary The World Management Pte. Ltd. obtained GROW with SAP certification in Singapore.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















