
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: NEOJAPAN has a January fiscal year-end. On this site, “FY2025” refers to the fiscal year ended January 31, 2026, which the company’s materials label “FY01/26”; labels in the body and tables follow the materials.
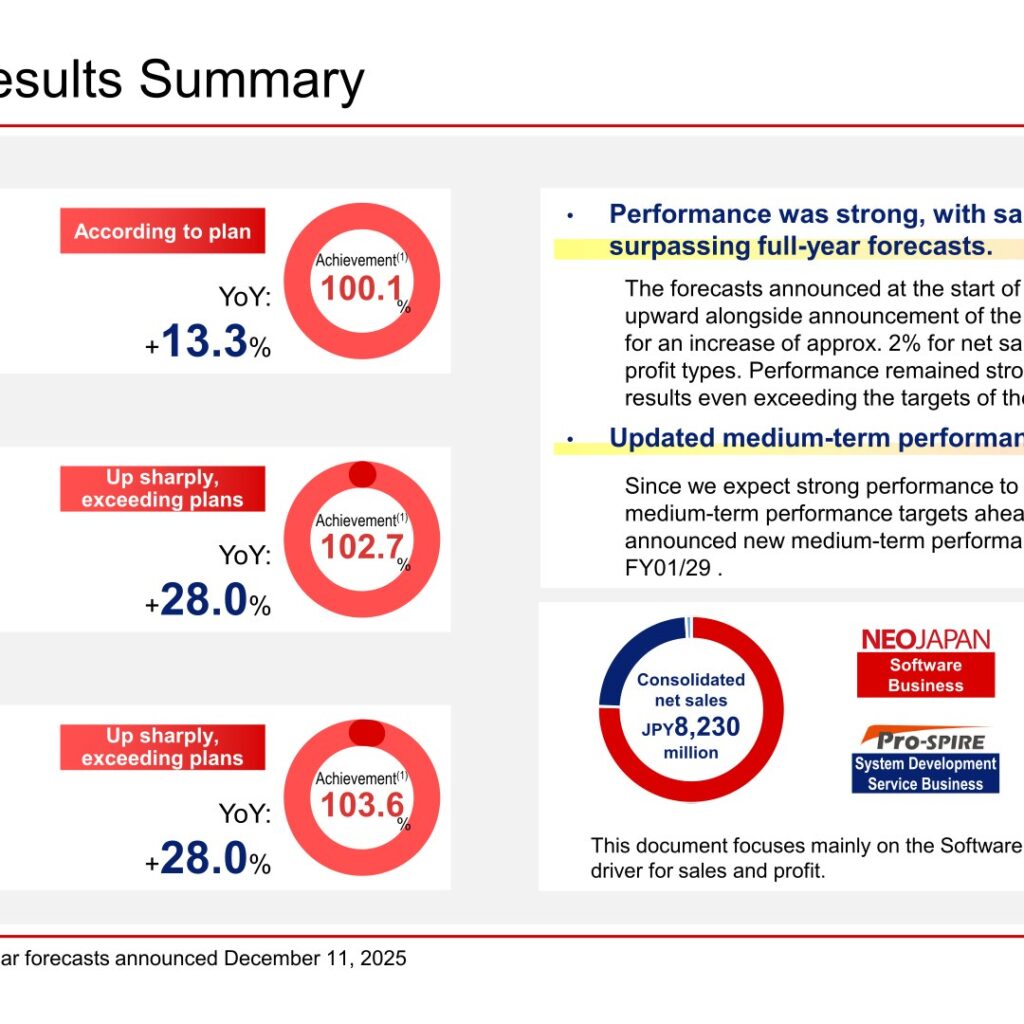
NEOJAPAN Inc. (TSE Prime: 3921), developer of the groupware desknet’s NEO, the no-code business app platform AppSuite and the business chat ChatLuck, reported FY01/26 consolidated net sales of JPY8,230 million (+13.3% YoY), operating profit of JPY2,497 million (+28.0% YoY) and profit attributable to owners of parent of JPY1,809 million (+28.0% YoY). Sales and all profit lines exceeded the full-year forecasts revised upward on December 11, 2025, and the company achieved its 14th consecutive year of revenue growth, driven by the Software Business. For FY01/27, it forecasts net sales of JPY8,619 million (+4.7%) and operating profit of JPY2,680 million (+7.3%), and it has announced new medium-term performance targets through FY01/29.
Consolidated Results (Full-Year Actual)
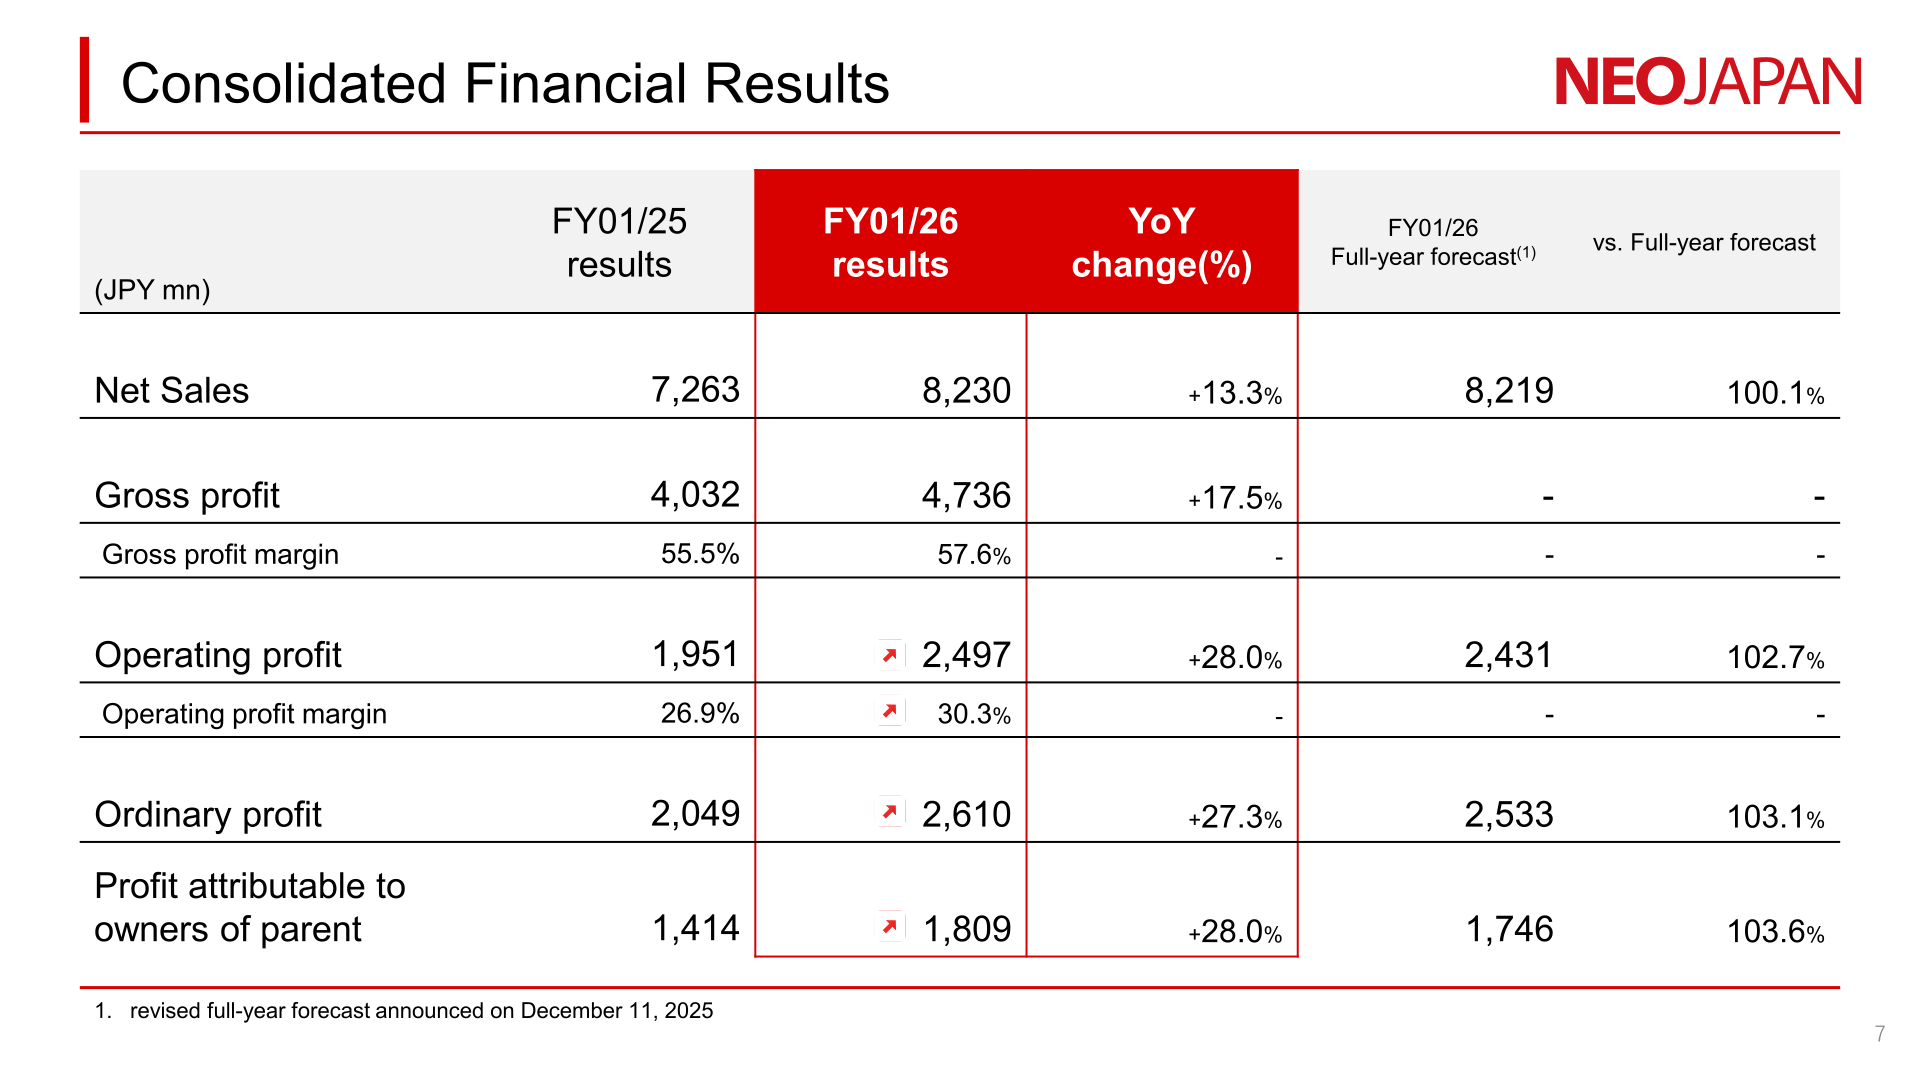
Net sales were JPY8,230 million, achieving 100.1% of the revised full-year forecast announced on December 11, 2025. Operating profit was JPY2,497 million (102.7% of forecast), with the operating profit margin rising to 30.3% from 26.9%. Ordinary profit was JPY2,610 million (+27.3%, 103.1% of forecast) and profit attributable to owners of parent was JPY1,809 million (103.6% of forecast). The company explains that the forecasts announced at the start of the year were revised upward alongside the Q3 results, and that performance remained strong thereafter, with full-year results exceeding the revised plans. Gross profit rose 17.5% to JPY4,736 million, and the gross profit margin improved to 57.6% from 55.5%.
| Item (JPY mn) | FY01/25 Results | FY01/26 Results | YoY Change (%) | FY01/26 Full-Year Forecast (Revised) | vs. Full-Year Forecast |
|---|---|---|---|---|---|
| Net sales | 7,263 | 8,230 | +13.3% | 8,219 | 100.1% |
| Gross profit | 4,032 | 4,736 | +17.5% | – | – |
| Gross profit margin | 55.5% | 57.6% | – | – | – |
| Operating profit | 1,951 | 2,497 | +28.0% | 2,431 | 102.7% |
| Operating profit margin | 26.9% | 30.3% | – | – | – |
| Ordinary profit | 2,049 | 2,610 | +27.3% | 2,533 | 103.1% |
| Profit attributable to owners of parent | 1,414 | 1,809 | +28.0% | 1,746 | 103.6% |
On the balance sheet, total assets rose to JPY10,693 million from JPY9,240 million, with cash and deposits of JPY6,426 million (up JPY1,029 million) and interest-bearing debt of JPY3 million. Net assets were JPY7,482 million. The equity ratio was 69.9% (+1.6 points) and ROE was 26.3% (+3.9 points), which the company describes as sustaining both at high levels.
Segment Results
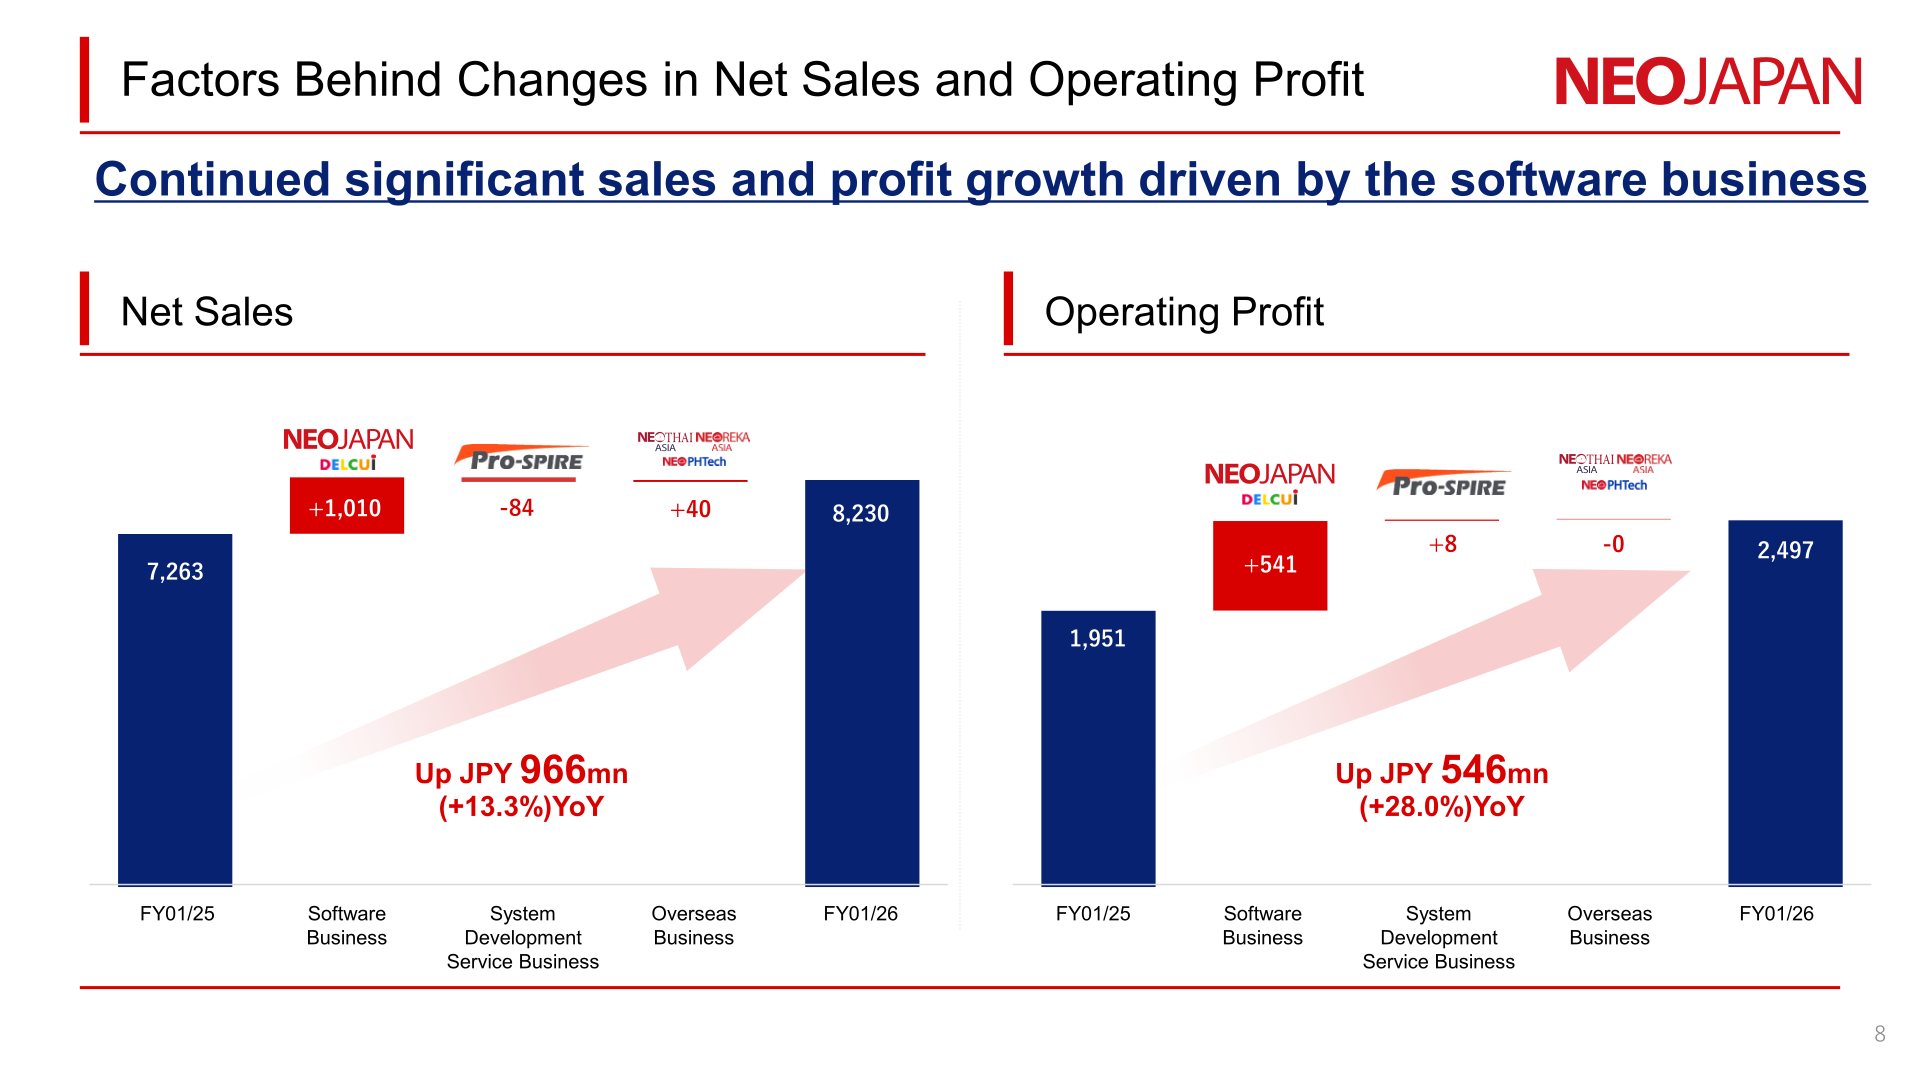
Of the JPY966 million increase in consolidated net sales, the Software Business (NEOJAPAN and DELCUI) contributed +1,010 million yen, the System Development Service Business (Pro-SPIRE) -84 million yen and the Overseas Business (NEO THAI ASIA, NEOREKA ASIA and NEOPhilippine Tech) +40 million yen. Of the JPY546 million increase in operating profit, the Software Business contributed +541 million yen, the System Development Service Business +8 million yen and the Overseas Business -0 million yen. Software Business net sales rose 19.4% to JPY6,217 million and its operating profit rose 27.4% to JPY2,516 million. The System Development Service Business saw net sales decline 4.2% to JPY1,935 million, but the company notes it secured increased profits (operating profit JPY73 million, +12.2%) through measures such as reducing outsourcing costs.
| Segment | Metric | FY01/26 | FY01/25 | YoY |
|---|---|---|---|---|
| Software Business | Net sales (JPY mn) | 6,217 | 5,206 | +19.4% |
| System Development Service Business | Net sales (JPY mn) | 1,935 | 2,020 | -4.2% |
| Software Business | Operating profit (JPY mn) | 2,516 | 1,974 | +27.4% |
| System Development Service Business | Operating profit (JPY mn) | 73 | 65 | +12.2% |
Segment net sales are figures after eliminating intersegment transactions. In the Software Business, Q4 FY01/26 revenue was JPY1,629 million (+11.8% YoY versus JPY1,458 million), a record for the quarter. Cloud services sales were JPY1,140 million (+15.2%), including desknet’s NEO at JPY920 million (+11.5%) and AppSuite at JPY110 million (+43.2%), while packaged products were JPY452 million (+1.4%), supported by support services of JPY278 million (+8.7%). Stock revenue was JPY1,335 million (+13.1%) and the stock revenue ratio remained high at 81.9%. ARR reached JPY5,348 million, up 12.5% YoY. The quarterly cloud cancellation rate was 0.27%, which the company says is its lowest level since the price revisions in Sep. 2024. The cumulative number of packaged product users of desknet’s NEO increased 2.6% YoY and the number of cloud users increased 3.9% YoY.
FY01/27 Forecast
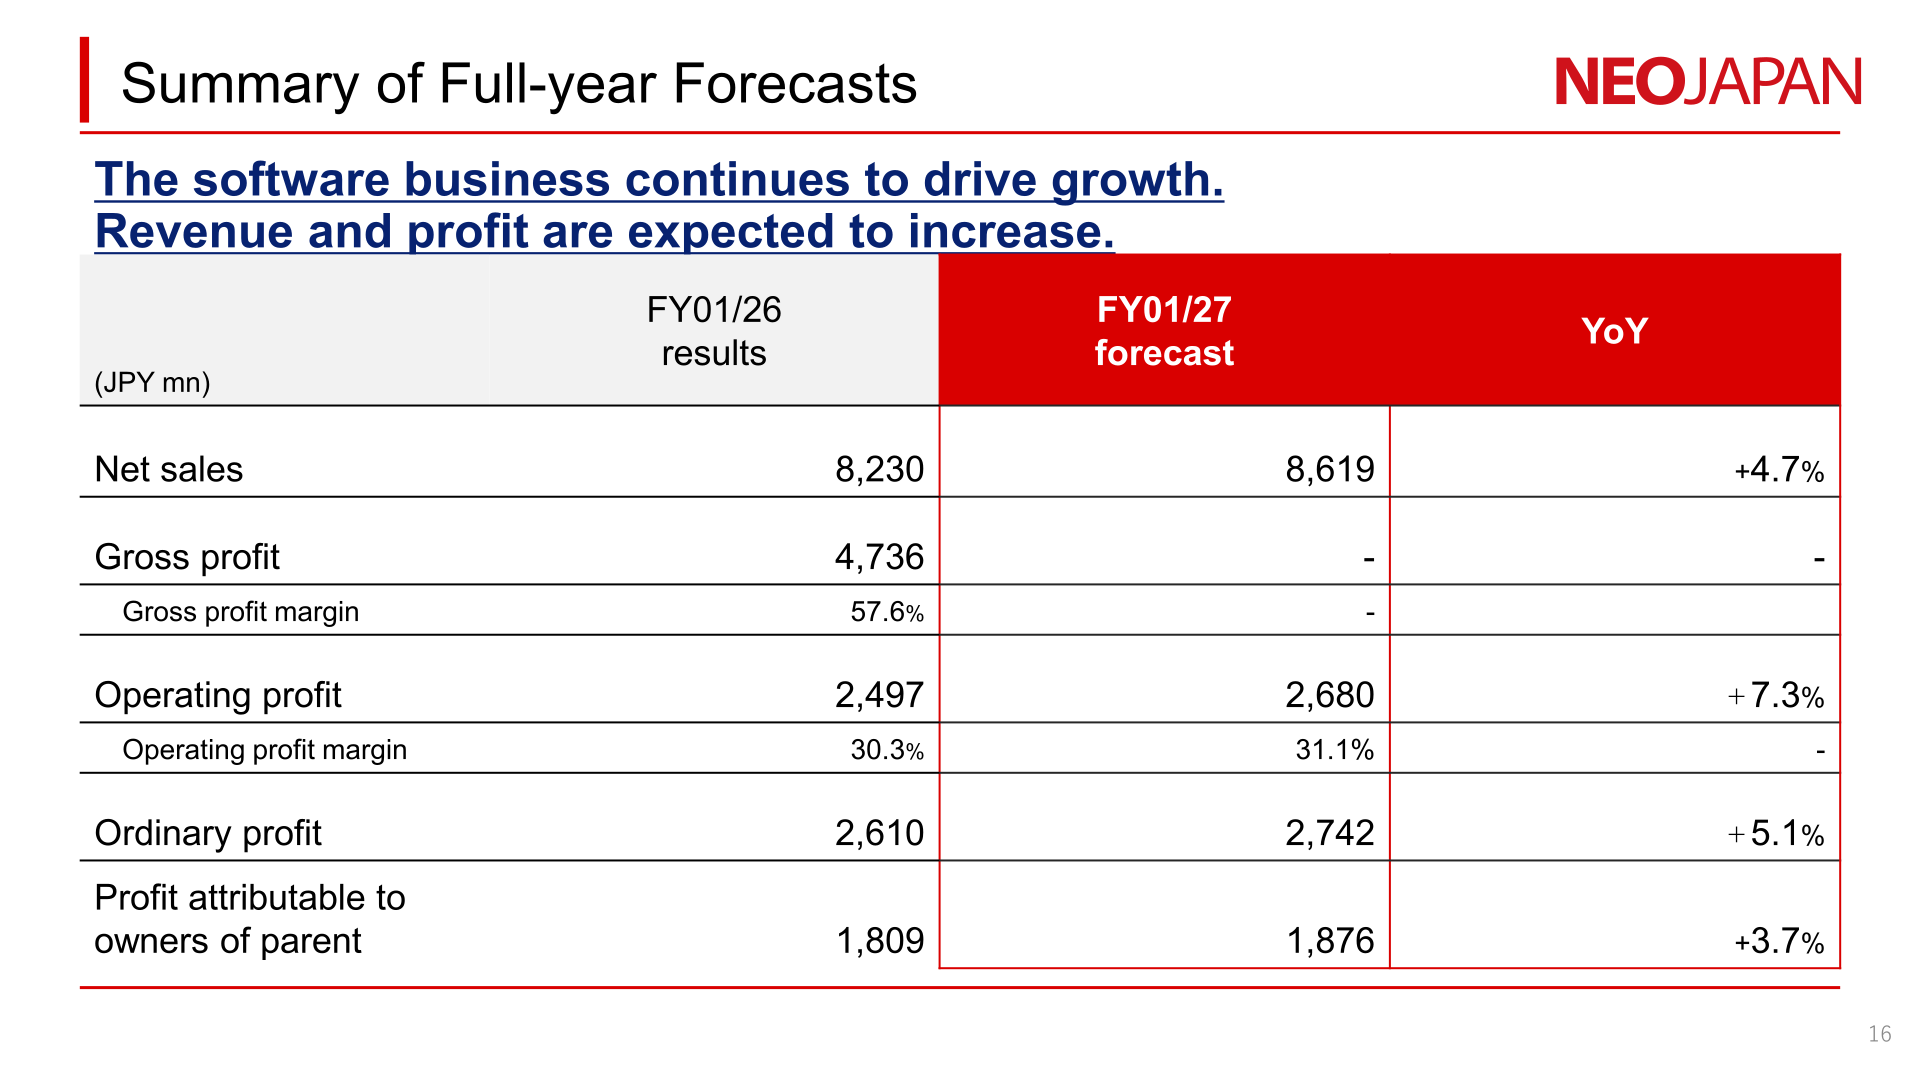
For FY01/27, the company states that the software business continues to drive growth and expects revenue and profit to increase. It forecasts net sales of JPY8,619 million (+4.7%), operating profit of JPY2,680 million (+7.3%) with an operating profit margin of 31.1%, ordinary profit of JPY2,742 million (+5.1%) and profit attributable to owners of parent of JPY1,876 million (+3.7%). In the Software Business, the company plans approximately JPY444 million in advertising costs for the year ending January 2027 as it enhances measures to strengthen brand recognition through elevator advertising and other means.
| Item (JPY mn) | FY01/27 Forecast | FY01/26 Results | YoY |
|---|---|---|---|
| Net sales | 8,619 | 8,230 | +4.7% |
| Operating profit | 2,680 | 2,497 | +7.3% |
| Operating profit margin | 31.1% | 30.3% | – |
| Ordinary profit | 2,742 | 2,610 | +5.1% |
| Profit attributable to owners of parent | 1,876 | 1,809 | +3.7% |
Shareholder Returns
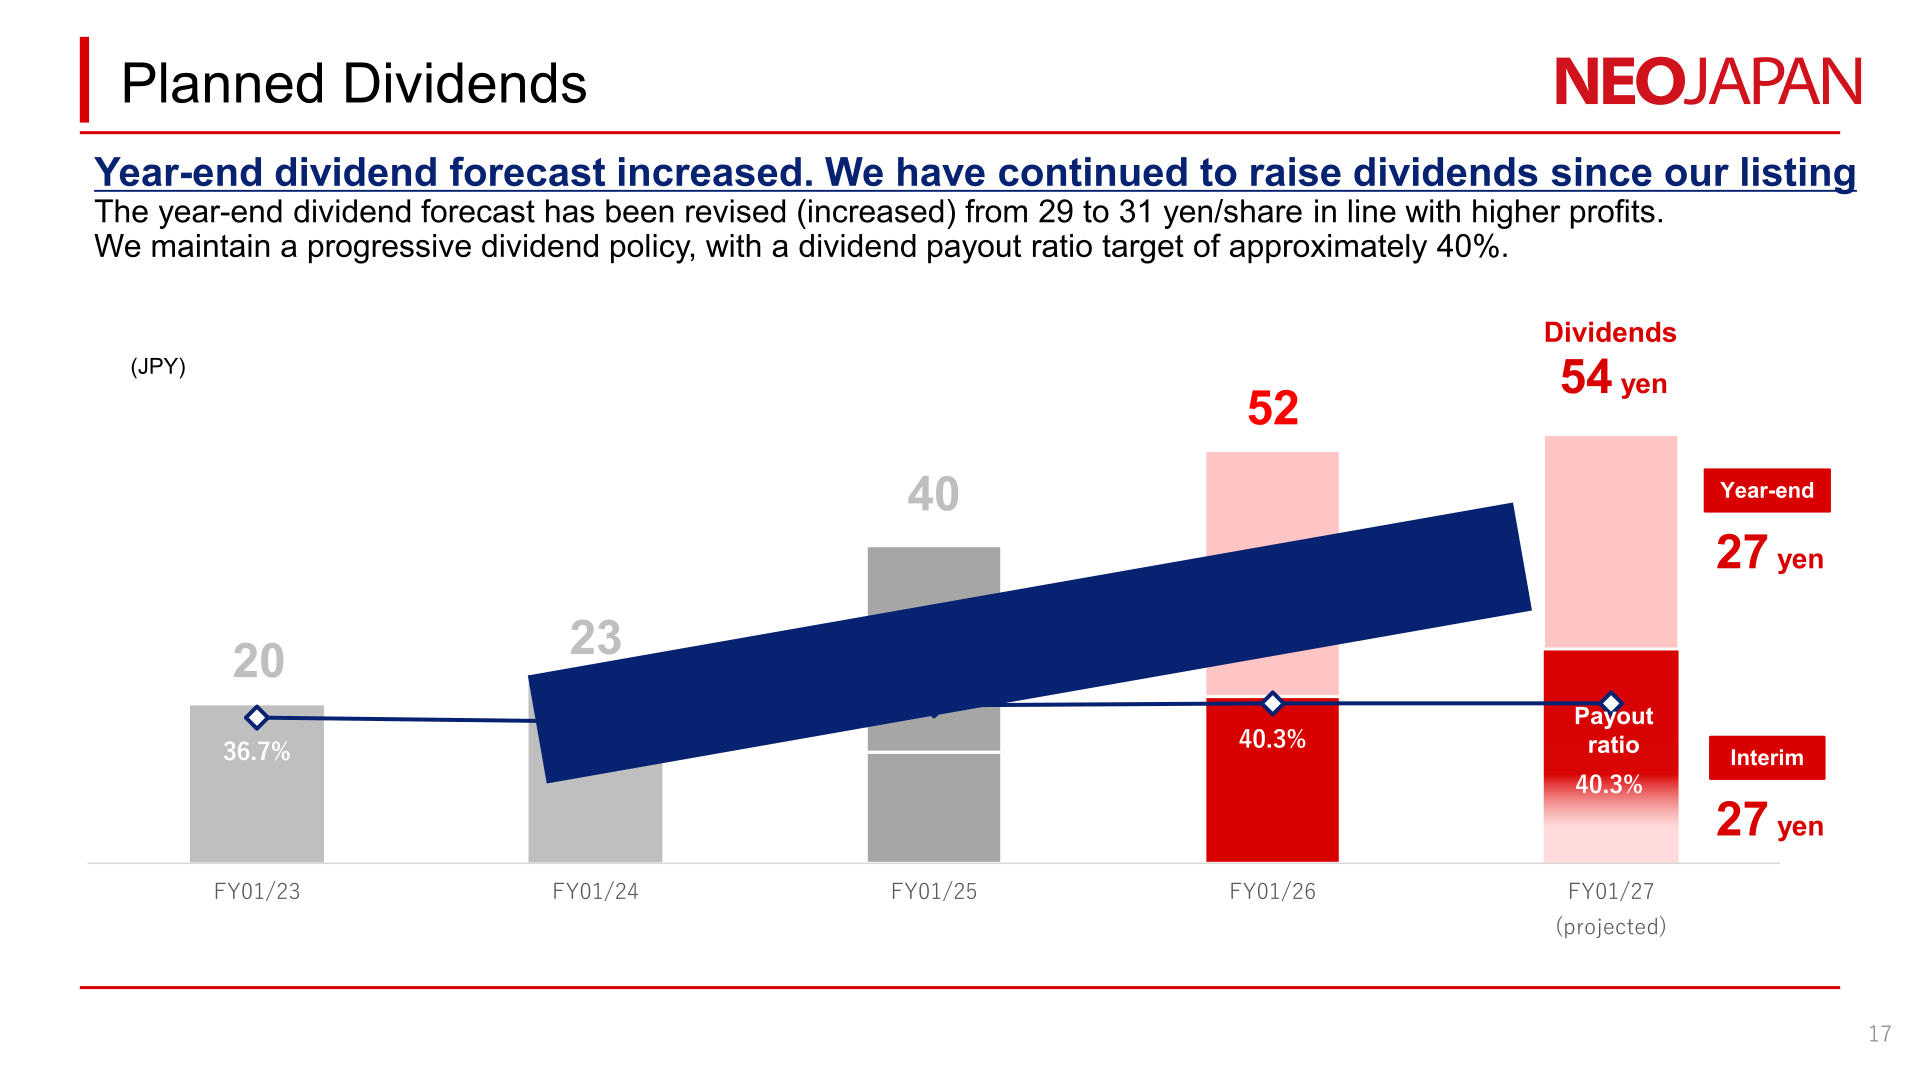
The annual dividend for FY01/26 was 52 yen per share, with a payout ratio of 40.3%, up from 40 yen in FY01/25. The company states that the year-end dividend forecast was revised (increased) from 29 to 31 yen per share in line with higher profits, and that it has continued to raise dividends since its listing. For FY01/27, it projects an annual dividend of 54 yen (interim 27 yen, year-end 27 yen) with a payout ratio of 40.3%. The company maintains a progressive dividend policy with a dividend payout ratio target of approximately 40%.
| Fiscal year | Annual dividend per share (JPY) | Payout ratio |
|---|---|---|
| FY01/23 | 20 | 36.7% |
| FY01/24 | 23 | Not shown |
| FY01/25 | 40 | Not shown |
| FY01/26 | 52 | 40.3% |
| FY01/27 (projected) | 54 (interim 27 / year-end 27) | 40.3% |
Medium-Term Performance Targets and Growth Strategy
The company expects to achieve the initial operating profit target of JPY2,620 million for the fiscal year ending January 2028 one year ahead of schedule, and has therefore announced new medium-term performance targets for the three years ending January 2029. The new targets call for a net sales CAGR of 7.0%, with the company striving to reach net sales of JPY10.0 billion in FY01/29 (JPY10,072 million shown on the target chart), and an operating profit CAGR of 8.0%, reaching JPY3,144 million in FY01/29.
The growth strategies consist of three pillars: (1) expanding desknet’s NEO sales through AI-powered functionality enhancements and capturing replacement demand for on-premises products, while accelerating cross-selling of AppSuite, ChatLuck, neoAI Chat, NEOPORT and other products, with the aim of increasing AppSuite users to 30% of desknet’s NEO users within the next few years; (2) expanding the Overseas Business, where FY01/26 sales grew to 2.1 times the previous period’s level and a “One Team” structure has been built across the three ASEAN companies; and (3) new business sales expansion through LiveX AI, sales of which began in October 2025, initially targeting the digital signage market.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















