
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: MarkLines has a December fiscal year-end. On this site, “FY2025” refers to the fiscal year ended December 31, 2025, which the company’s materials label “FY ended Dec. 2025”; labels in the body and tables follow the materials.
MarkLines Co., Ltd. (TSE: 3901), which operates an automotive industry information platform, reported consolidated net sales of JPY 5,570 million (+0.1% y/y) and consolidated operating income of JPY 2,095 million (△5.4% y/y) for the fiscal year ended December 31, 2025. The Information Platform business grew 5.6% y/y, but other businesses were sluggish amid a tough environment for Japanese and European automakers, and fixed costs rose with the operation of the Benchmark Center. For the fiscal year ending December 2026, the company forecasts net sales of JPY 6,150 million (+10.4%) and operating income of JPY 2,350 million (+12.1%), and states that it expects to achieve record profits again.
Consolidated Results (Full-Year Actual)
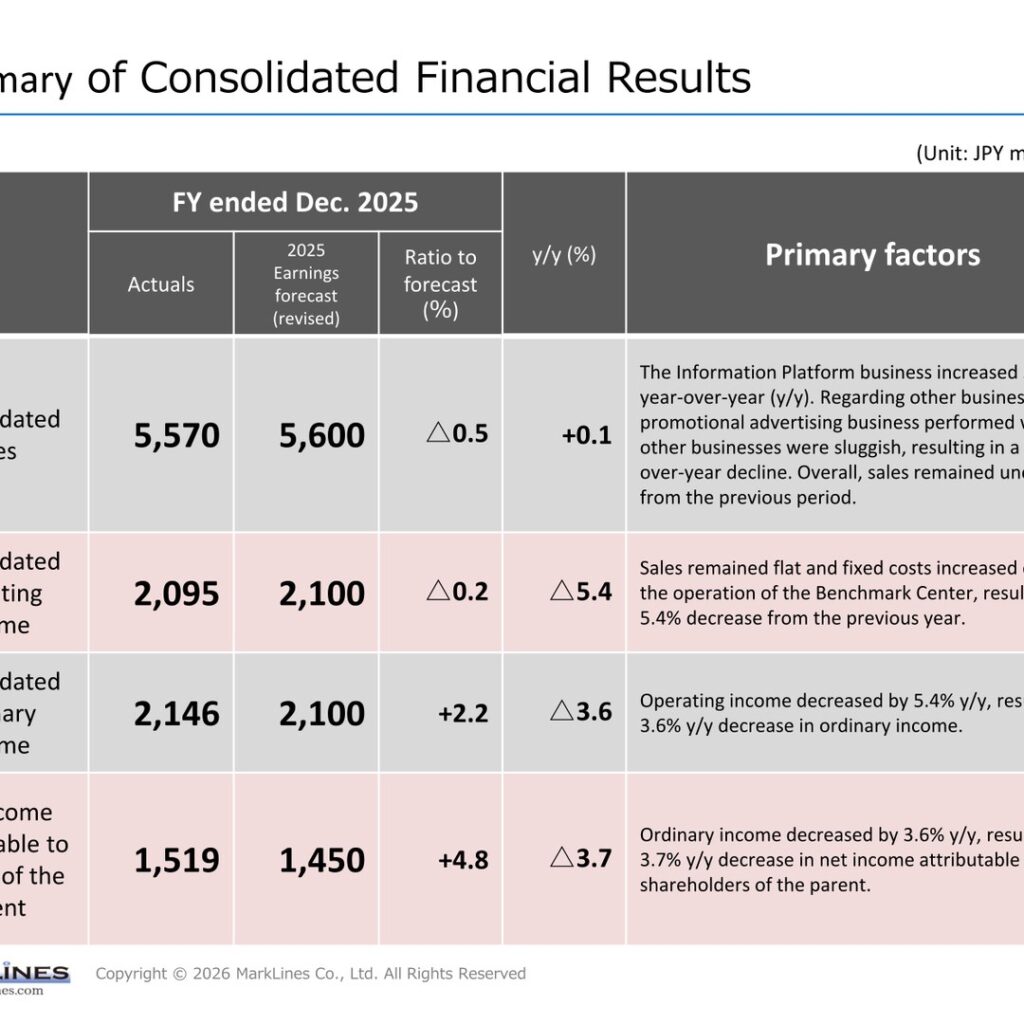
Consolidated net sales were JPY 5,570 million, against the revised earnings forecast of JPY 5,600 million (△0.5% vs. forecast) and up 0.1% y/y. The company explains that the Information Platform business increased 5.6% y/y and the promotional advertising business performed well, but other businesses were sluggish, so overall sales remained unchanged from the previous period. Consolidated operating income was JPY 2,095 million (forecast: JPY 2,100 million), down 5.4% y/y, as sales remained flat and fixed costs increased due to the operation of the Benchmark Center. Consolidated ordinary income was JPY 2,146 million (+2.2% vs. forecast, △3.6% y/y), and net income attributable to owners of the parent was JPY 1,519 million (+4.8% vs. forecast, △3.7% y/y). In the previous fiscal year, consolidated net sales were JPY 5,562 million and consolidated operating income was JPY 2,216 million.
| Item (JPY millions) | FY ended Dec. 2025 Actual | 2025 Earnings Forecast (Revised) | Ratio to Forecast (%) | y/y (%) |
|---|---|---|---|---|
| Consolidated sales | 5,570 | 5,600 | △0.5 | +0.1 |
| Consolidated operating income | 2,095 | 2,100 | △0.2 | △5.4 |
| Consolidated ordinary income | 2,146 | 2,100 | +2.2 | △3.6 |
| Net income attributable to owners of the parent | 1,519 | 1,450 | +4.8 | △3.7 |
By quarter, the company notes that Q1 fell short of the previous year due to a rebound from particularly strong Q1 performance a year earlier, including one-off sales in the vehicle teardown and measurement business. In Q2, many OEMs and parts suppliers held off on budget execution due to the unpredictable impact of U.S. tariff policy, but sales and operating income both increased. In Q3, consolidated net sales exceeded the prior-year level on higher Information Platform sales helped by the weaker yen, while operating income decreased. In Q4, orders for the Consulting and Teardown Survey Data sales businesses decreased, resulting in lower sales and operating income. Quarterly net sales in 2025 were JPY 1,587 million, 1,342 million, 1,232 million and 1,408 million, and quarterly operating income was JPY 590 million, 481 million, 464 million and 559 million.
In the sales bridge, Information Platform sales contributed +140, sales other than the Information Platform business △196, and exchange rate fluctuations +64 (JPY millions). Among other businesses, Promotional Advertising sales increased by JPY 22 million and Recruiting Solutions sales by JPY 12 million, while Consulting sales fell by JPY 139 million and Teardown Survey Data sales decreased by JPY 70 million. On the cost side, fixed costs including personnel expenses increased approximately JPY 97 million with the startup of the Benchmark Center, and labor costs increased both in Japan and at overseas subsidiaries due to factors such as base pay increases.
Segment Results
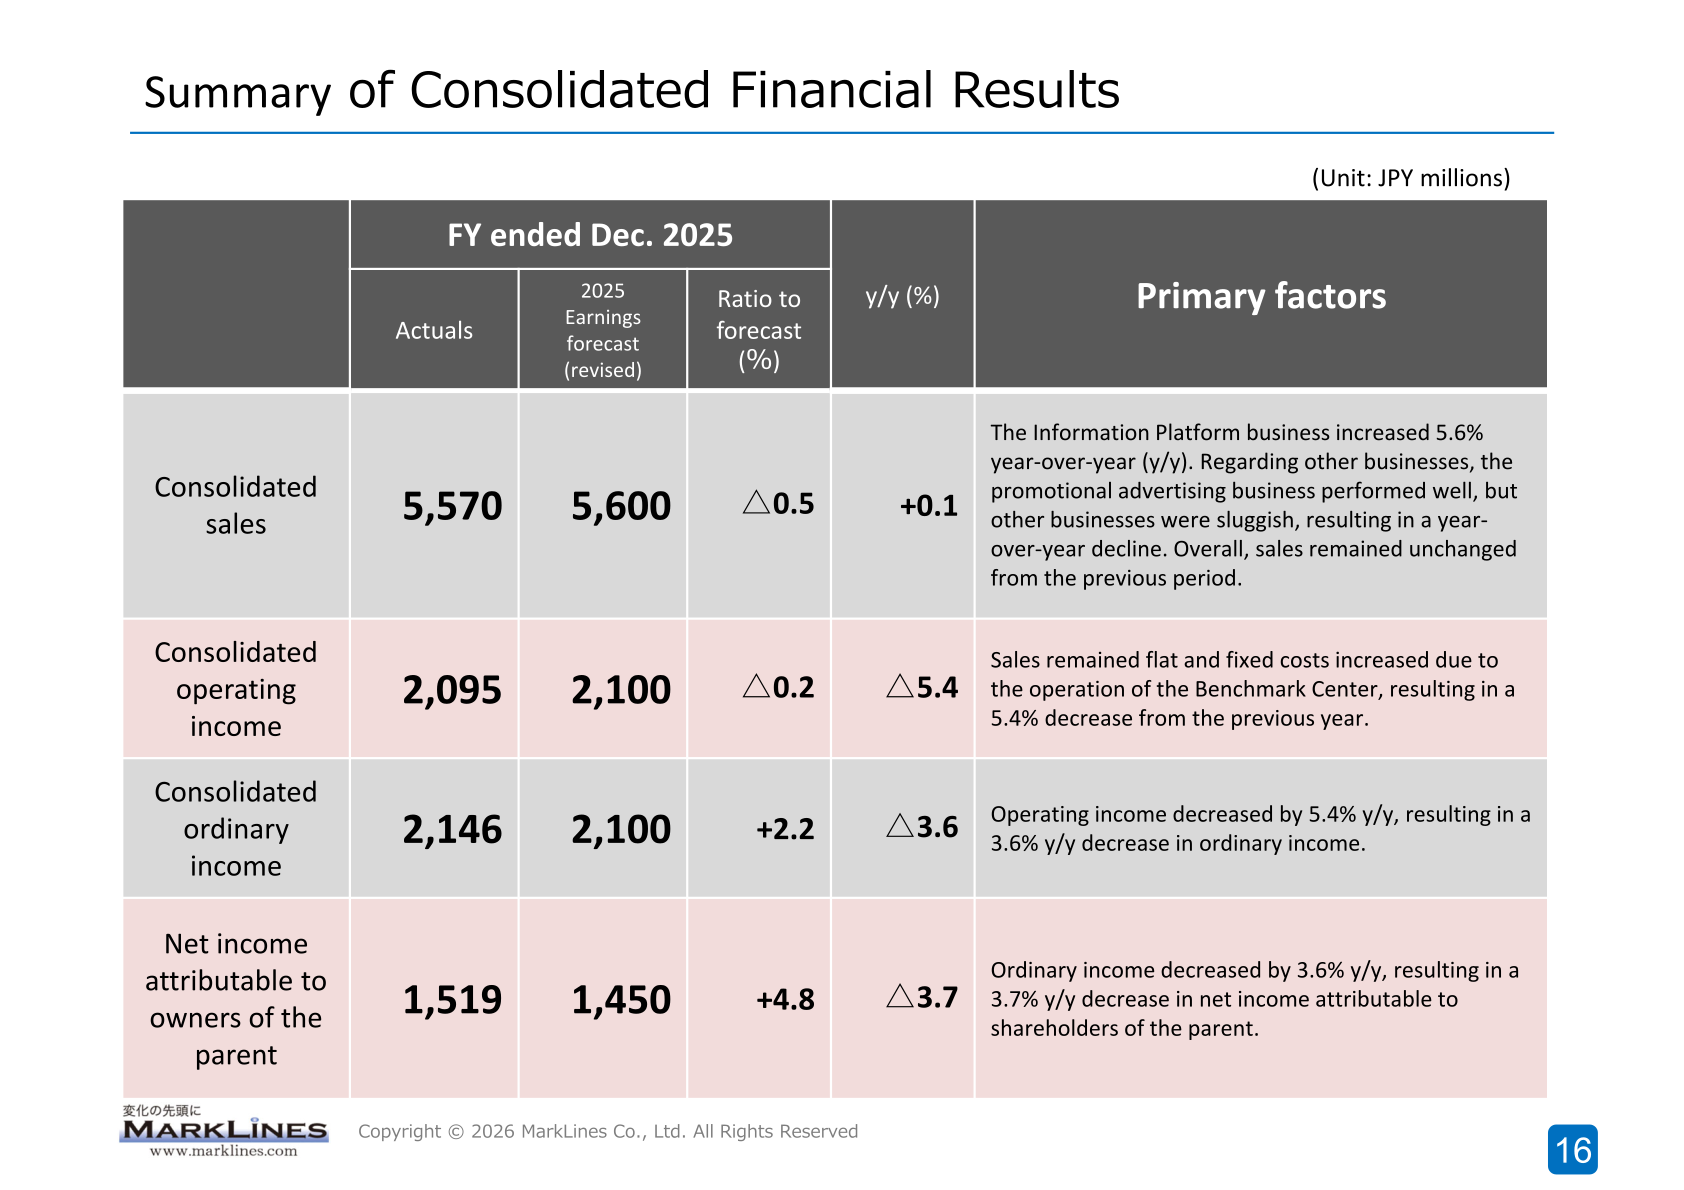
The Information Platform business, the core segment, posted net sales of JPY 3,834 million (+5.6%) and segment profit of JPY 1,897 million (+1.5%). The company explains that the poor performance of Japanese and European OEMs caused new contracts to stagnate and cancellations to increase, but sales rose thanks to the accumulation of contracts already acquired and the continued appreciation of the Chinese yuan. Promotional Advertising sales rose 20.2% on stable repeat orders and a higher order amount per project, and Market Forecast Information Sales also increased in both sales and profit. By contrast, Consulting sales fell 22.4% and segment profit fell 86.6% as budget execution by Japanese OEMs and major parts suppliers was delayed from April onward following the announcement of U.S. tariff policies. Teardown Survey Data Sales declined 37.8%, as EV-related analysis report sales were lower than expected and partner Munro & Associates effectively withdrew from the analysis report writing business. The Vehicle Teardown and Measurement business increased sales by 2.0% but posted a segment loss of △36 due to increased fixed costs at the Benchmark Center.
| Business Unit (JPY millions) | Metric | 2025 Results | 2024 Results | y/y change |
|---|---|---|---|---|
| Information Platform business | Net sales | 3,834 | 3,629 | +205 (+5.6%) |
| Information Platform business | Segment profit | 1,897 | 1,869 | +28 (+1.5%) |
| Promotional Advertising business | Net sales | 136 | 113 | +22 (+20.2%) |
| Promotional Advertising business | Segment profit | 103 | 96 | +7 (+7.5%) |
| Market Forecast Information Sales business | Net sales | 304 | 295 | +8 (+3.0%) |
| Market Forecast Information Sales business | Segment profit | 91 | 87 | +3 (+4.2%) |
| Vehicle and Parts Procurement business | Net sales | 462 | 494 | △32 (△6.6%) |
| Vehicle and Parts Procurement business | Segment profit | 28 | 50 | △22 (△44.0%) |
| Teardown Survey Data Sales business | Net sales | 116 | 186 | △70 (△37.8%) |
| Teardown Survey Data Sales business | Segment profit | 28 | 64 | △36 (△56.4%) |
| Automotive Fund business | Net sales | 39 | 39 | +0 (+0.0%) |
| Automotive Fund business | Segment profit | 17 | 5 | +12 (+241.2%) |
| Consulting business | Net sales | 486 | 625 | △139 (△22.4%) |
| Consulting business | Segment profit | 8 | 65 | △56 (△86.6%) |
| Recruiting Solutions Department | Net sales | 91 | 78 | +12 (+15.9%) |
| Recruiting Solutions Department | Segment profit | △33 | △33 | △0 (-) |
| Vehicle Teardown and Measurement business | Net sales | 100 | 98 | +2 (+2.0%) |
| Vehicle Teardown and Measurement business | Segment profit | △36 | 10 | △47 (-) |
| Other | Segment profit | △8 | - | △8 (-) |
| Consolidated | Net sales | 5,570 | 5,562 | +8 (+0.1%) |
| Consolidated | Operating income | 2,095 | 2,216 | △120 (△5.4%) |
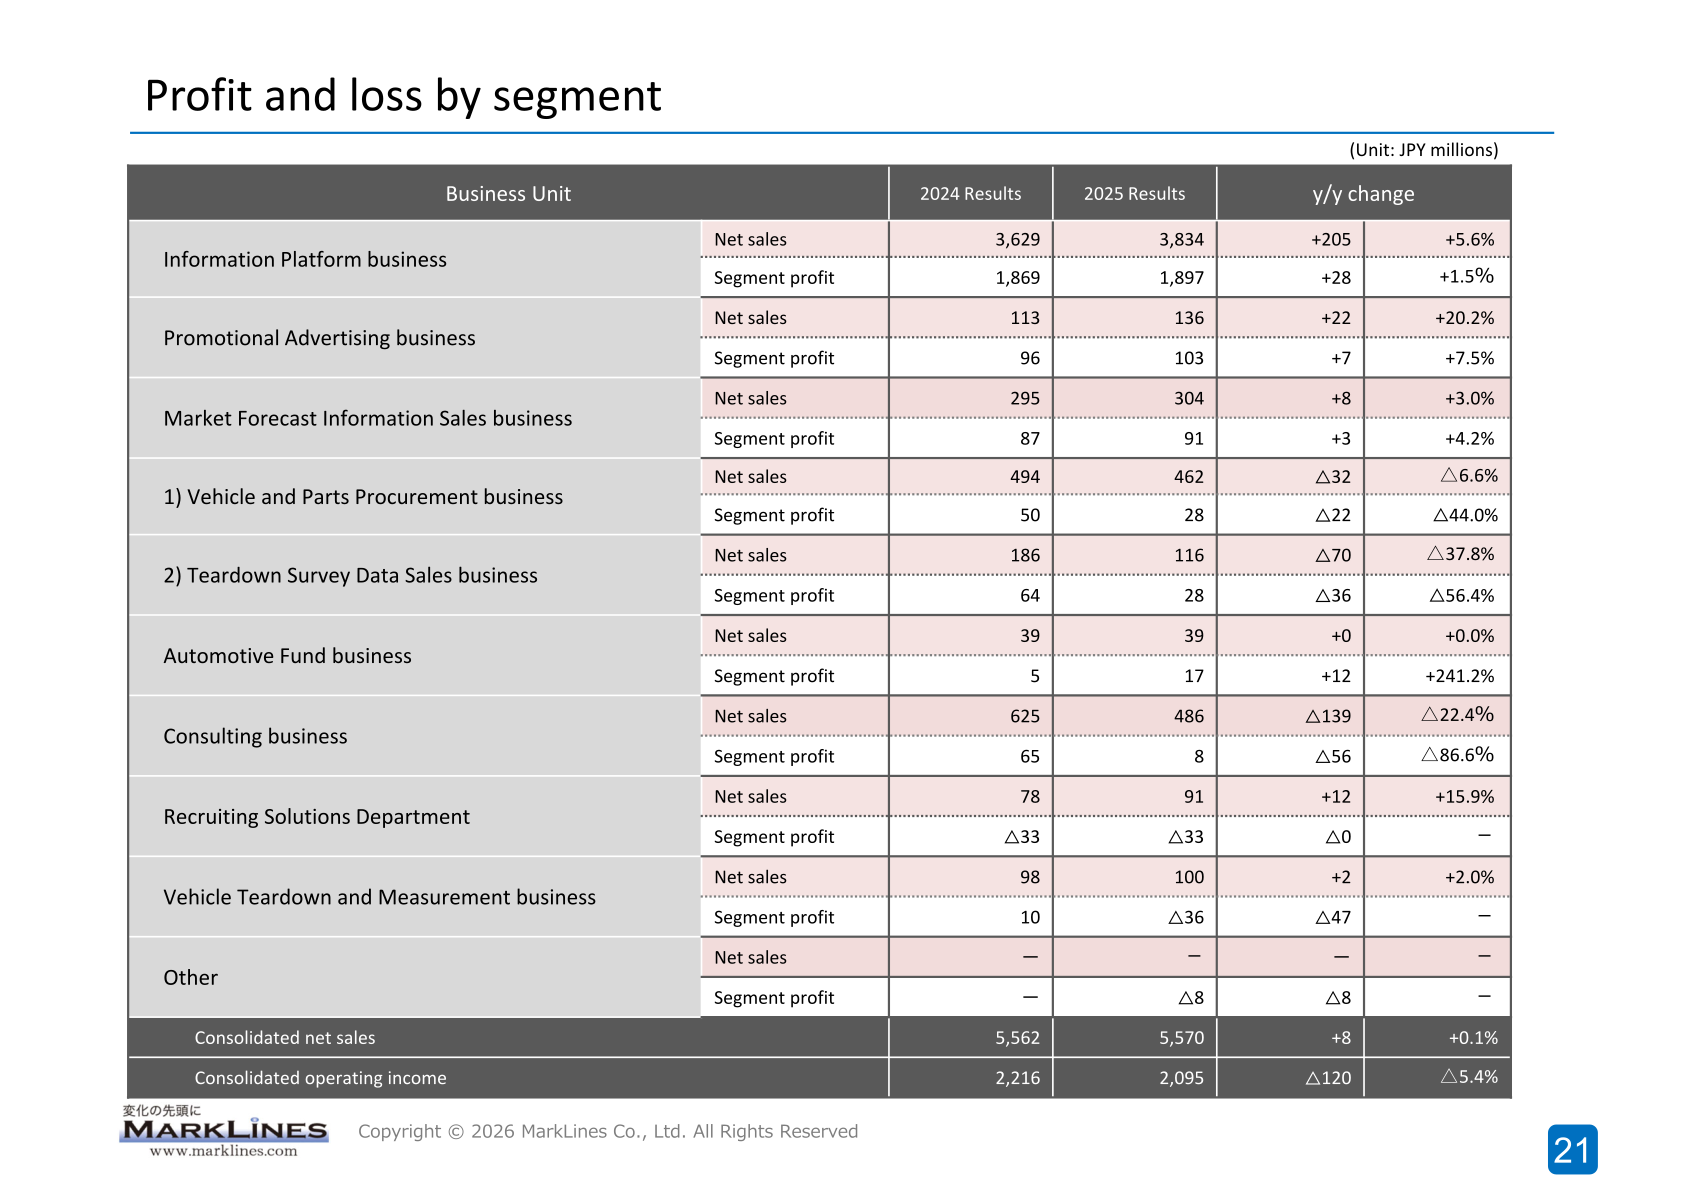
Information Platform sales increased in every region. Sales outside Japan accounted for 64.1% of the segment. By currency, the average contract unit price for existing customers in JPY was 676,636 for full year 2025, up 17.5% from 575,627 in full year 2024; the company attributes the rise to an increase in applications for relatively high-priced plans and to cancellations being concentrated among SMEs with low unit price contracts. The number of contracts declined from 5,616 at the end of 2024 to 5,476 in Q4 2025, and the number of clients from 7,610 in Q1 2025 to 7,430 in Q4 2025, as cancellations by small and midsize companies increased.
| Information Platform sales by region (JPY millions) | FY2025 | 2024 | y/y (%) |
|---|---|---|---|
| Japan | 1,377 | 1,361 | +1.2 |
| China | 670 | 644 | +4.1 |
| Asia | 714 | 663 | +7.8 |
| North America | 585 | 512 | +14.3 |
| Europe | 450 | 420 | +7.1 |
| Other | 35 | 28 | +27.1 |
| Total | 3,834 | 3,629 | +5.6 |
Full-Year Forecast (FY ending Dec. 2026)
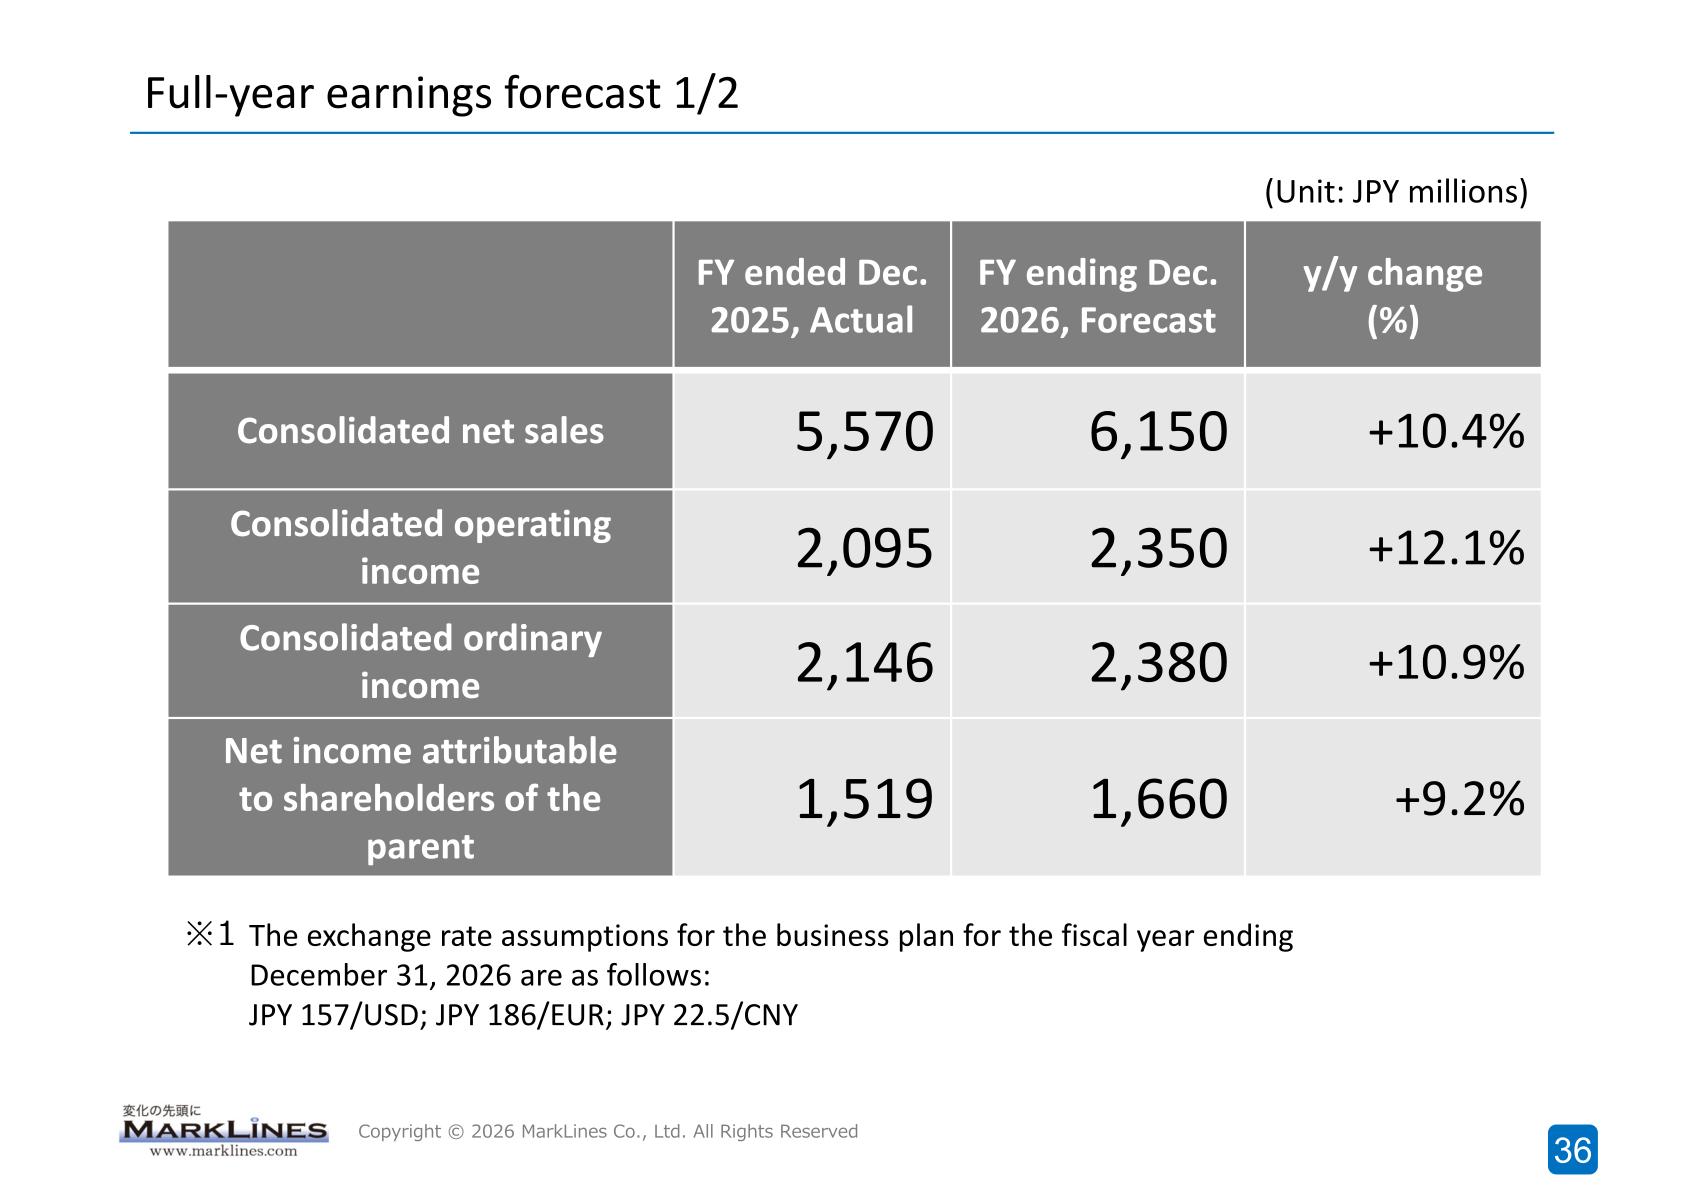
For the fiscal year ending December 2026, MarkLines forecasts consolidated net sales of JPY 6,150 million (+10.4%), consolidated operating income of JPY 2,350 million (+12.1%), consolidated ordinary income of JPY 2,380 million (+10.9%) and net income attributable to shareholders of the parent of JPY 1,660 million (+9.2%). The exchange rate assumptions are JPY 157/USD, JPY 186/EUR and JPY 22.5/CNY. The company states that although it was unable to achieve record profits for the 15th consecutive fiscal year in the fiscal year ended December 2025, it expects to achieve record profits again in the fiscal year ending December 2026.
| Item (JPY millions) | FY ending Dec. 2026 Forecast | FY ended Dec. 2025 Actual | y/y change (%) |
|---|---|---|---|
| Consolidated net sales | 6,150 | 5,570 | +10.4% |
| Consolidated operating income | 2,350 | 2,095 | +12.1% |
| Consolidated ordinary income | 2,380 | 2,146 | +10.9% |
| Net income attributable to shareholders of the parent | 1,660 | 1,519 | +9.2% |
Shareholder Returns
The results briefing materials do not include information on dividends or share buybacks. This cannot be confirmed from the materials.
Growth Strategy and Topics
Generative AI: Full-scale development of search functions utilizing generative AI began in the second half of 2025, and in January 2026 the company launched the “MarkLines Gen-AI Beta Version” as an additional Information Platform service for corporate clients. It presents data from MarkLines’ automotive-related databases in response to natural-language questions, provides analysis in text form, and supports questions and answers in over 60 languages. The company is making functional improvements based on user feedback and plans to release the official version after these are completed.
Price revisions: Having kept service fees unchanged for more than 20 years since launch, the company decided to revise prices for existing Information Platform contracts. For JPY contracts, for example, the annual fee for up to 2 people changes to 600,000 (previously 480,000) and for 21 or more people to 2,400,000 (previously 1,200,000). Revisions are being applied sequentially starting with contracts renewing at the end of 2025 and are to be completed by the end of 2026; the company expects them to raise the average unit price of existing contracts in stages each month over the next two years.
Other initiatives: In April 2025 the company established MarkLines Software Development Co., Ltd. (capital JPY 90 million; MarkLines 51%, Huaqin Technology Co., Ltd. 49%) to provide contract development services for automotive software in the Japanese market, aiming to receive orders in 2026. Through its Automotive Industry Support Fund 2021, it invested in MICWARE Co., Ltd. in February 2025 and KopherBit Co., Ltd. (Taiwan) in December 2025. In December 2025 the head office and Akasaka satellite office were consolidated into the new head office at Roppongi Central Tower. Going forward, the company aims to promote new contract acquisition and upselling in the U.S., China, Europe and India, and to strengthen its Reverse Engineering field by expanding orders at the Benchmark Center, particularly from the Toyota Group, and by extending services to commercial vehicles and motorcycles.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















