
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
TechMatrix Corporation’s materials label the fiscal year from April 2025 to March 2026 (fiscal year ended March 31, 2026, the company’s 42nd business period) as “FY2025”, and the year ending March 31, 2027 as “FY2026”; this article follows those labels.
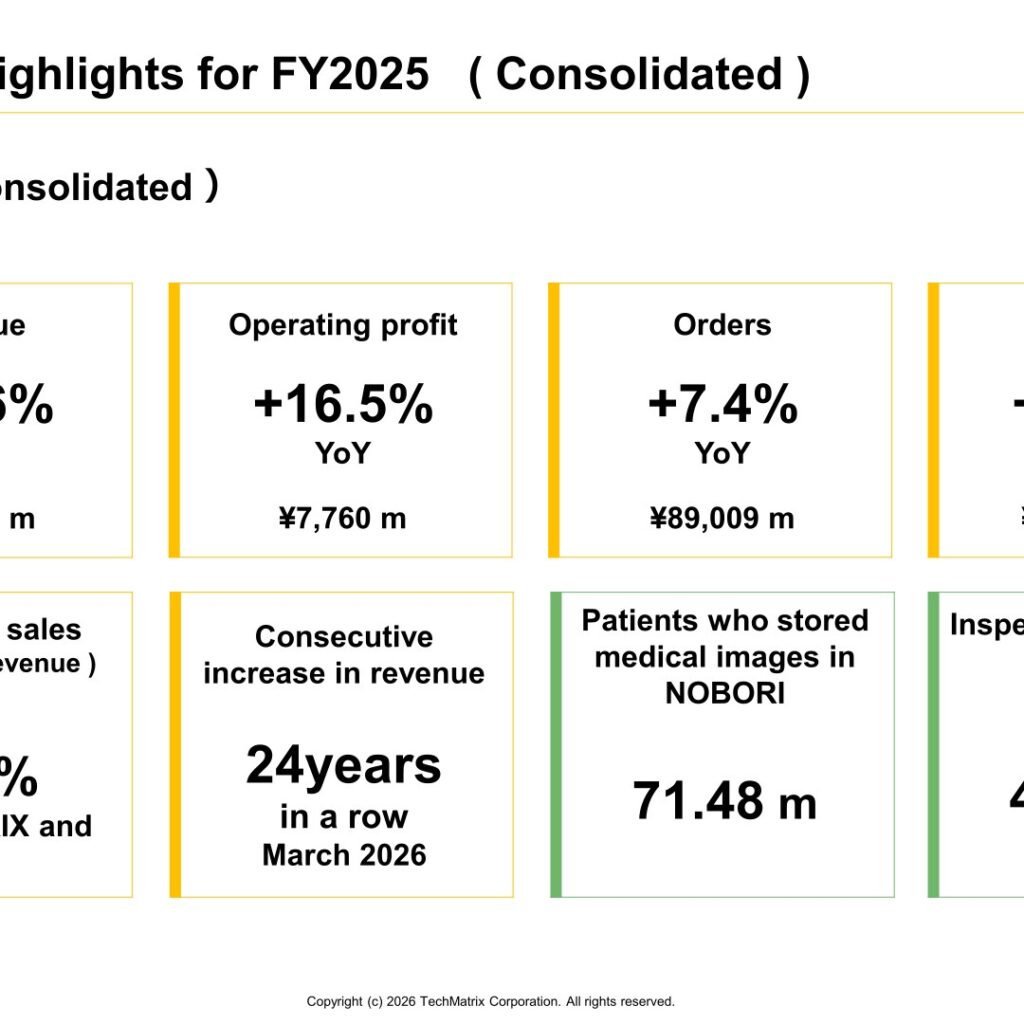
TechMatrix posted its highest-ever consolidated revenue, operating profit, profit before tax and profit attributable to owners of parent in FY2025. Revenue rose 10.6% year on year to ¥71,733 million and operating profit rose 16.5% to ¥7,760 million, driven by the Information Infrastructure business. Orders grew 7.4% to ¥89,009 million and the order backlog grew 19.6% to ¥105,431 million. The annual dividend was raised to ¥52.0 per share, and the company plans ¥54.0 for FY2026.
Consolidated Results (Full-Year Actual)
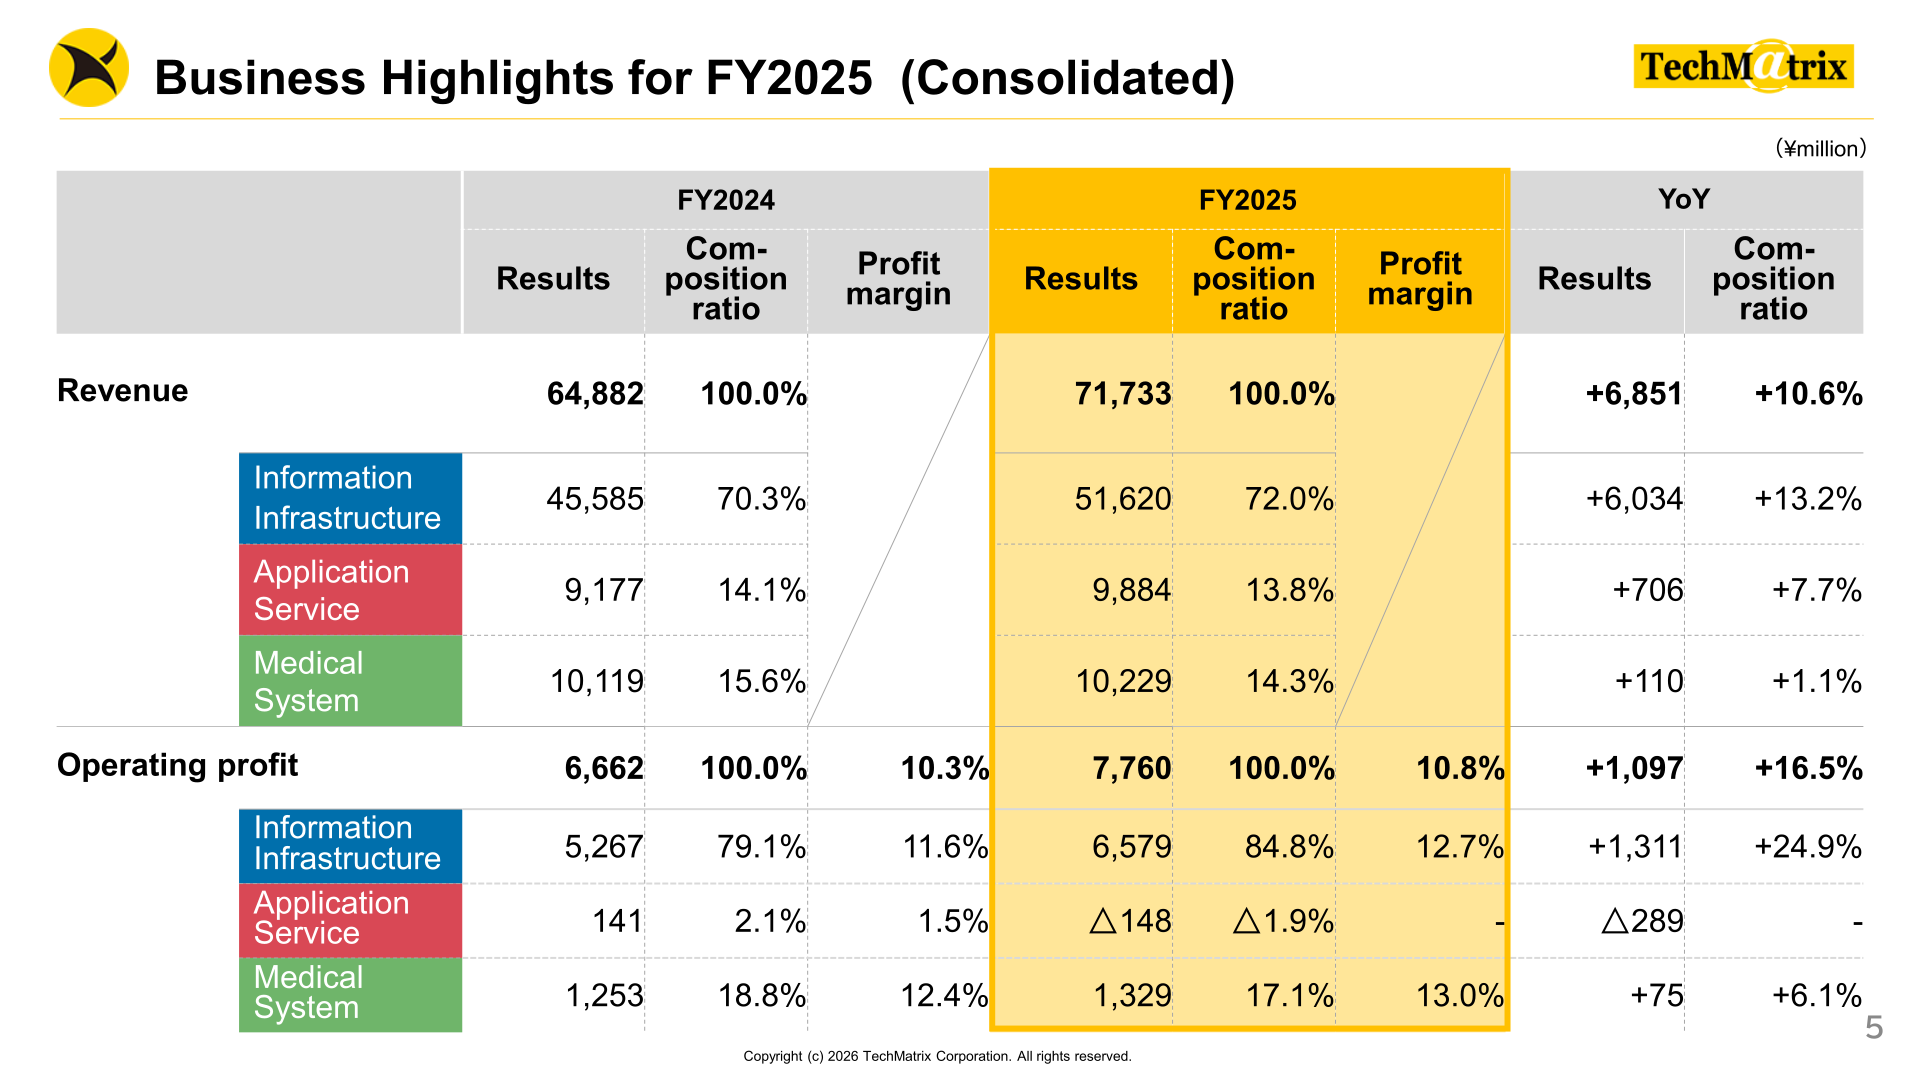
Operating profit margin improved from 10.3% to 10.8%. Profit before tax rose 22.5% to ¥7,861 million and profit attributable to owners of parent rose 27.7% to ¥5,178 million. Provisions for a salary system revision and a review of refresh leave reduced operating profit by ¥80 million. Because the provisional accounting treatment for the November 12, 2024 business combination with Firmus Sdn. Bhd. was finalized during the year, prior-year figures reflect the revised amounts.
| Item (¥ million) | FY2025 | FY2024 | Change | Change % |
|---|---|---|---|---|
| Revenue | 71,733 | 64,882 | +6,851 | +10.6% |
| Operating profit | 7,760 | 6,662 | +1,097 | +16.5% |
| Operating profit margin | (10.8%) | (10.3%) | (+0.5P) | — |
| Profit before tax | 7,861 | 6,418 | +1,442 | +22.5% |
| Profit attributable to owners of parent | 5,178 | 4,056 | +1,121 | +27.7% |
Consolidated orders increased as the Information Infrastructure business absorbed the decline from large-scale renewals in the previous fiscal year through steady accumulation of new and renewal orders, and the backlog increased on a higher proportion of stock-type (subscription) projects. The stock-type (recurring) sales ratio of TechMatrix and PSP was 81.1%. On the balance sheet, total assets were ¥121,531 million (FY2024: ¥105,497 million), cash and cash equivalents were ¥35,801 million (¥27,325 million) and total equity attributable to owners of parent was ¥26,327 million (¥24,202 million); advance payments and advances received increased as orders for subscription-based cloud security services grew.
Segment Results
Information Infrastructure: Revenue rose 13.2% to ¥51,620 million and operating profit rose 24.9% to ¥6,579 million, both record highs. In addition to conventional cloud-based security solutions, cross-selling of AI-powered SOC automation solutions progressed, multi-year subscriptions accumulated, and Firmus (consolidated from the third quarter of FY2024) contributed. These gains offset temporary demand from one-time factors in the previous fiscal year (revenue of approximately 1.7 billion yen in 2Q and operating profit of 200 million yen in 3Q). The increase in SG&A expenses remained slight despite revenue growth.
Application Services: Revenue rose 7.7% to ¥9,884 million on strong demand for the cloud-based contact center CRM system FastHelp and the accumulation of stock-type business as subscriptions progressed (CRM, software quality assurance and EdTech). The segment posted an operating loss of ¥148 million (FY2024: operating profit of ¥141 million) because all EdTech software development costs were recorded as research and development expenses (cumulative impact of ▲184 million yen) and personnel and selling and administrative expenses rose with the expansion of the CRM business, partly offset by the rebound from the previous year’s impairment loss on EdTech software assets (▲330 million yen).
Medical Systems: Revenue was ¥10,229 million (+1.1%) and operating profit was ¥1,329 million (+6.1%). NOBORI, the medical information cloud service and PHR application, performed well, as did Ichigo and A-Line, while on-premise sales declined with the gradual shift to cloud computing. Operating profit held at the previous year’s level despite higher investment costs, owing to the expanded sales composition of cloud services. As of March 2026, NOBORI stored medical images for 71.48 m patients and 484.2 m inspections.
| Segment | Metric (¥ million) | FY2025 | FY2024 | Change |
|---|---|---|---|---|
| Information Infrastructure | Revenue | 51,620 | 45,585 | +6,034 (+13.2%) |
| Information Infrastructure | Operating profit | 6,579 | 5,267 | +1,311 (+24.9%) |
| Information Infrastructure | Orders | 64,134 | 60,482 | +6.0% |
| Information Infrastructure | Backlog | 78,880 | 66,366 | +12,514 (18.9%) |
| Application Service | Revenue | 9,884 | 9,177 | +706 (+7.7%) |
| Application Service | Operating profit | △148 | 141 | △289 |
| Application Service | Orders | 10,938 | 9,924 | +10.2% |
| Application Service | Backlog | 7,125 | 6,071 | +1,054 (17.4%) |
| Medical System | Revenue | 10,229 | 10,119 | +110 (+1.1%) |
| Medical System | Operating profit | 1,329 | 1,253 | +75 (+6.1%) |
| Medical System | Orders | 13,936 | 12,459 | +11.9% |
| Medical System | Backlog | 19,425 | 15,717 | +3,707 (23.6%) |
FY2026 Forecast (Year Ending March 31, 2027)
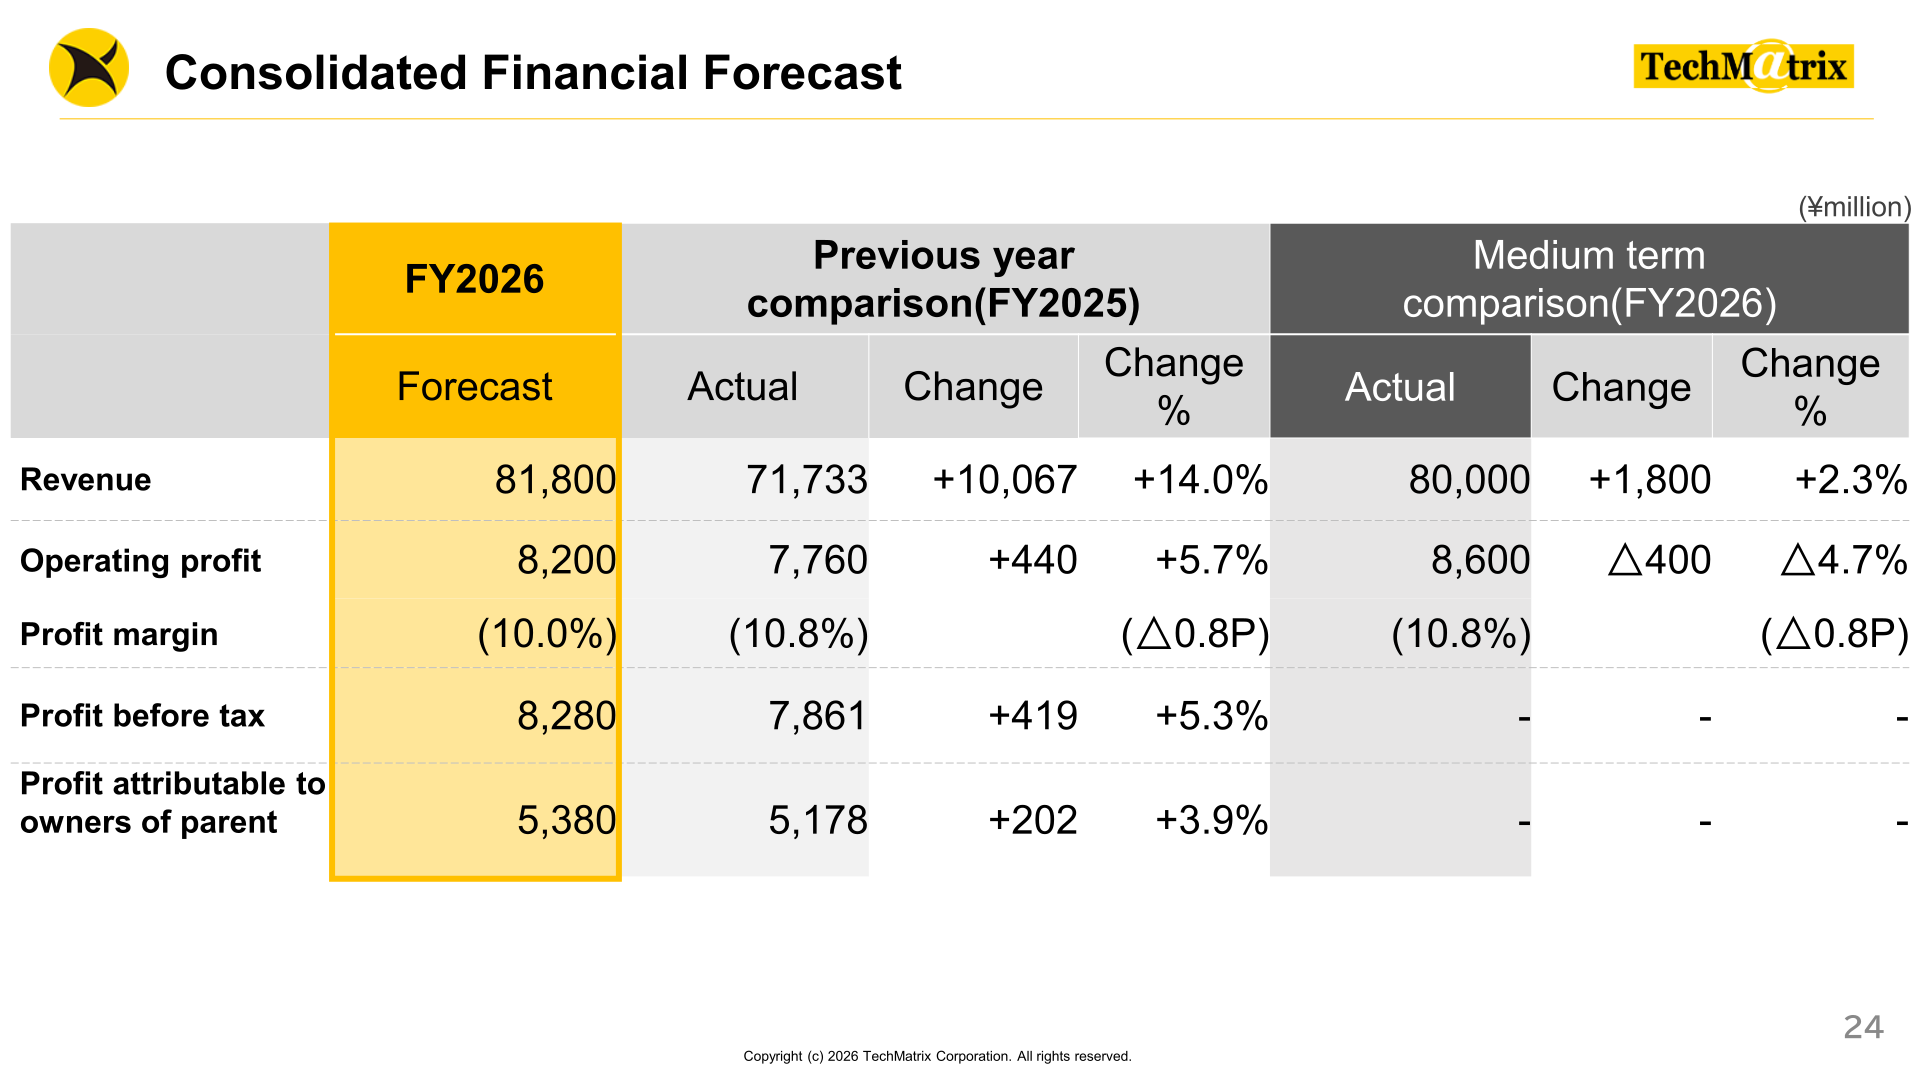
For FY2026, TechMatrix forecasts revenue of ¥81,800 million (+14.0%) and operating profit of ¥8,200 million (+5.7%), with sales growth driven by the Information Infrastructure business. Against the third-year targets of the medium-term management plan (revenue ¥80,000 million, operating profit ¥8,600 million), revenue is forecast to exceed the plan by ¥1,800 million while operating profit is ¥400 million below it. The company states that operating profit is expected to reach the third-year target excluding the impact of making Medmain a consolidated subsidiary in the Medical Systems business; the change in the method of recording EdTech software development costs is the other difference in assumptions versus the plan.
| Item (¥ million) | FY2026 Forecast | FY2025 Actual | Change | Change % |
|---|---|---|---|---|
| Revenue | 81,800 | 71,733 | +10,067 | +14.0% |
| Operating profit | 8,200 | 7,760 | +440 | +5.7% |
| Operating profit margin | (10.0%) | (10.8%) | (△0.8P) | — |
| Profit before tax | 8,280 | 7,861 | +419 | +5.3% |
| Profit attributable to owners of parent | 5,380 | 5,178 | +202 | +3.9% |
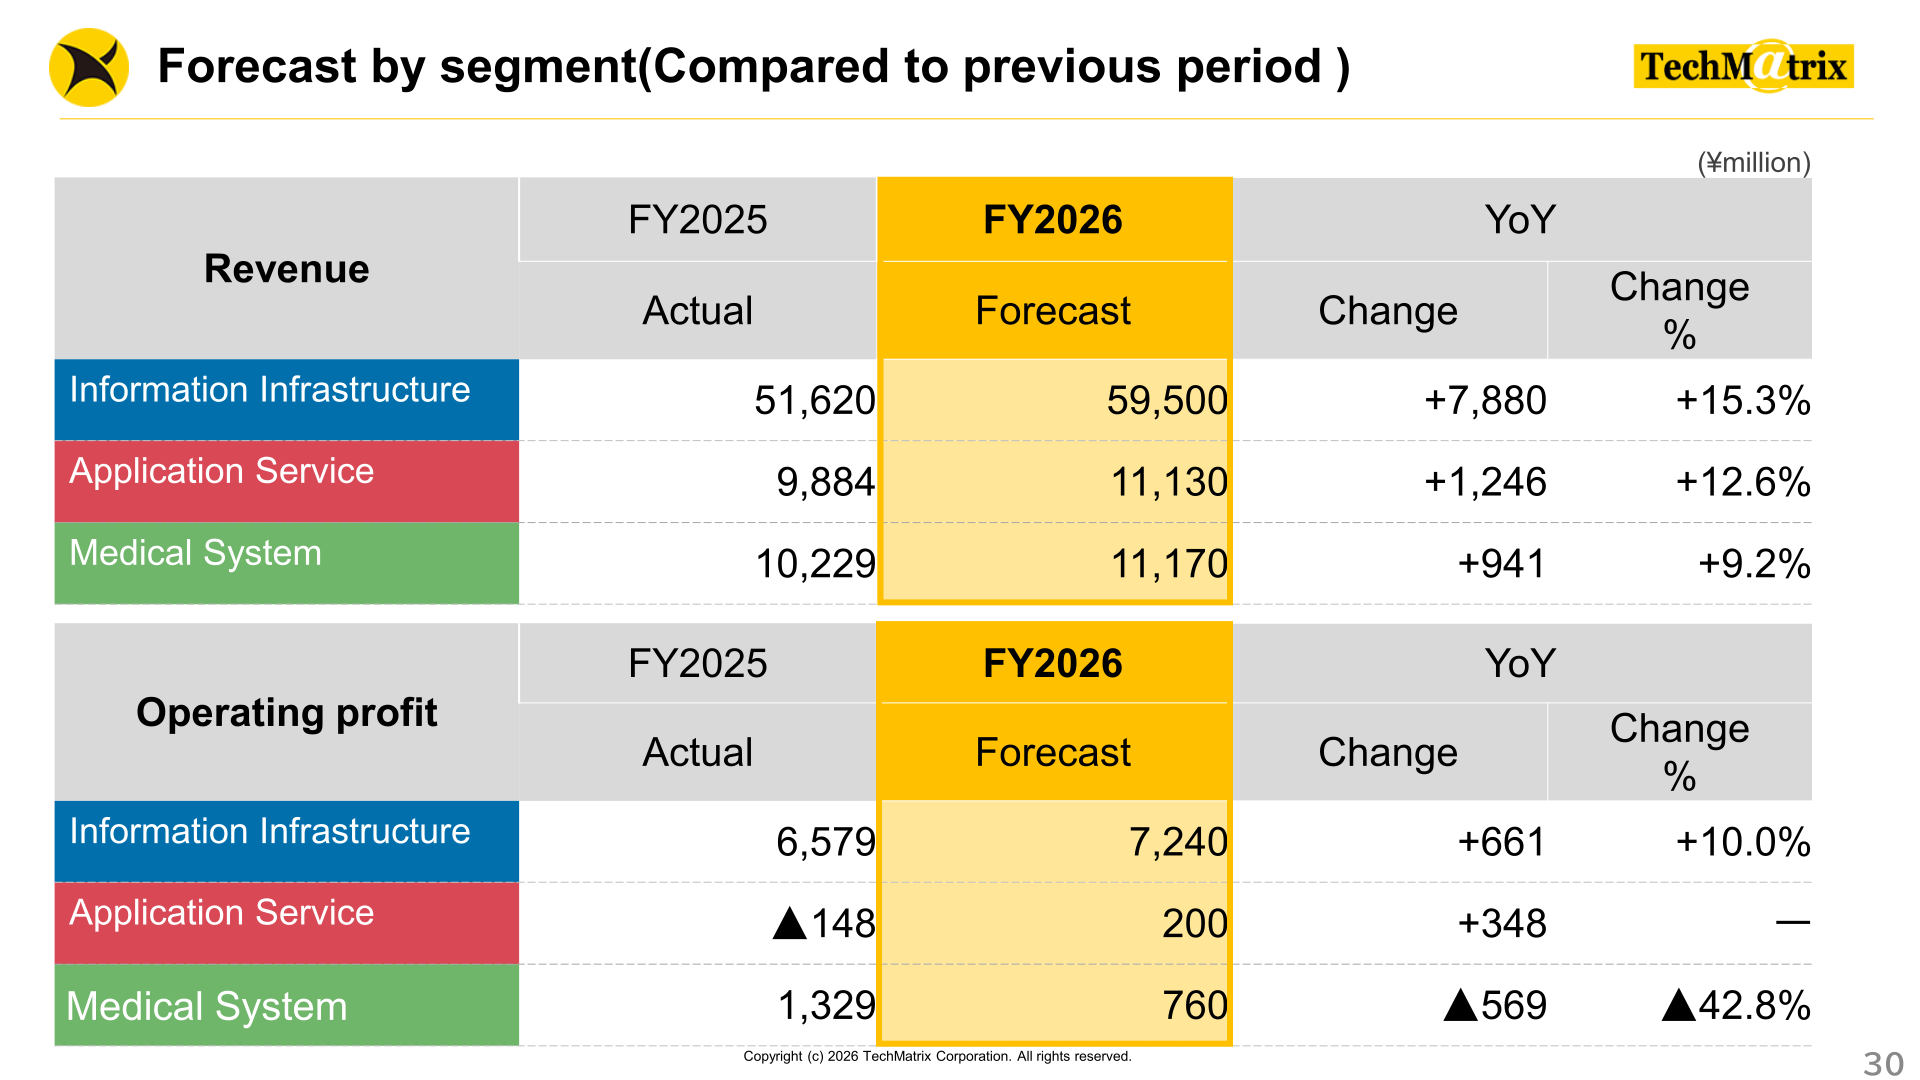
By segment, Information Infrastructure is expected to exceed the medium-term plan on backlog accumulation from stock-type projects and cross-selling of AI-powered SOC task automation solutions. Application Services sales are expected to land at roughly the plan level, with the operating profit plan reviewed in light of the previous term’s trends. In Medical Systems, the operating profit plan was revised for personnel strengthening, development investment and the consolidation of Medmain.
| Segment | Metric (¥ million) | FY2026 Forecast | FY2025 Actual | Change |
|---|---|---|---|---|
| Information Infrastructure | Revenue | 59,500 | 51,620 | +7,880 (+15.3%) |
| Information Infrastructure | Operating profit | 7,240 | 6,579 | +661 (+10.0%) |
| Application Service | Revenue | 11,130 | 9,884 | +1,246 (+12.6%) |
| Application Service | Operating profit | 200 | ▲148 | +348 |
| Medical System | Revenue | 11,170 | 10,229 | +941 (+9.2%) |
| Medical System | Operating profit | 760 | 1,329 | ▲569 (▲42.8%) |
Shareholder Returns
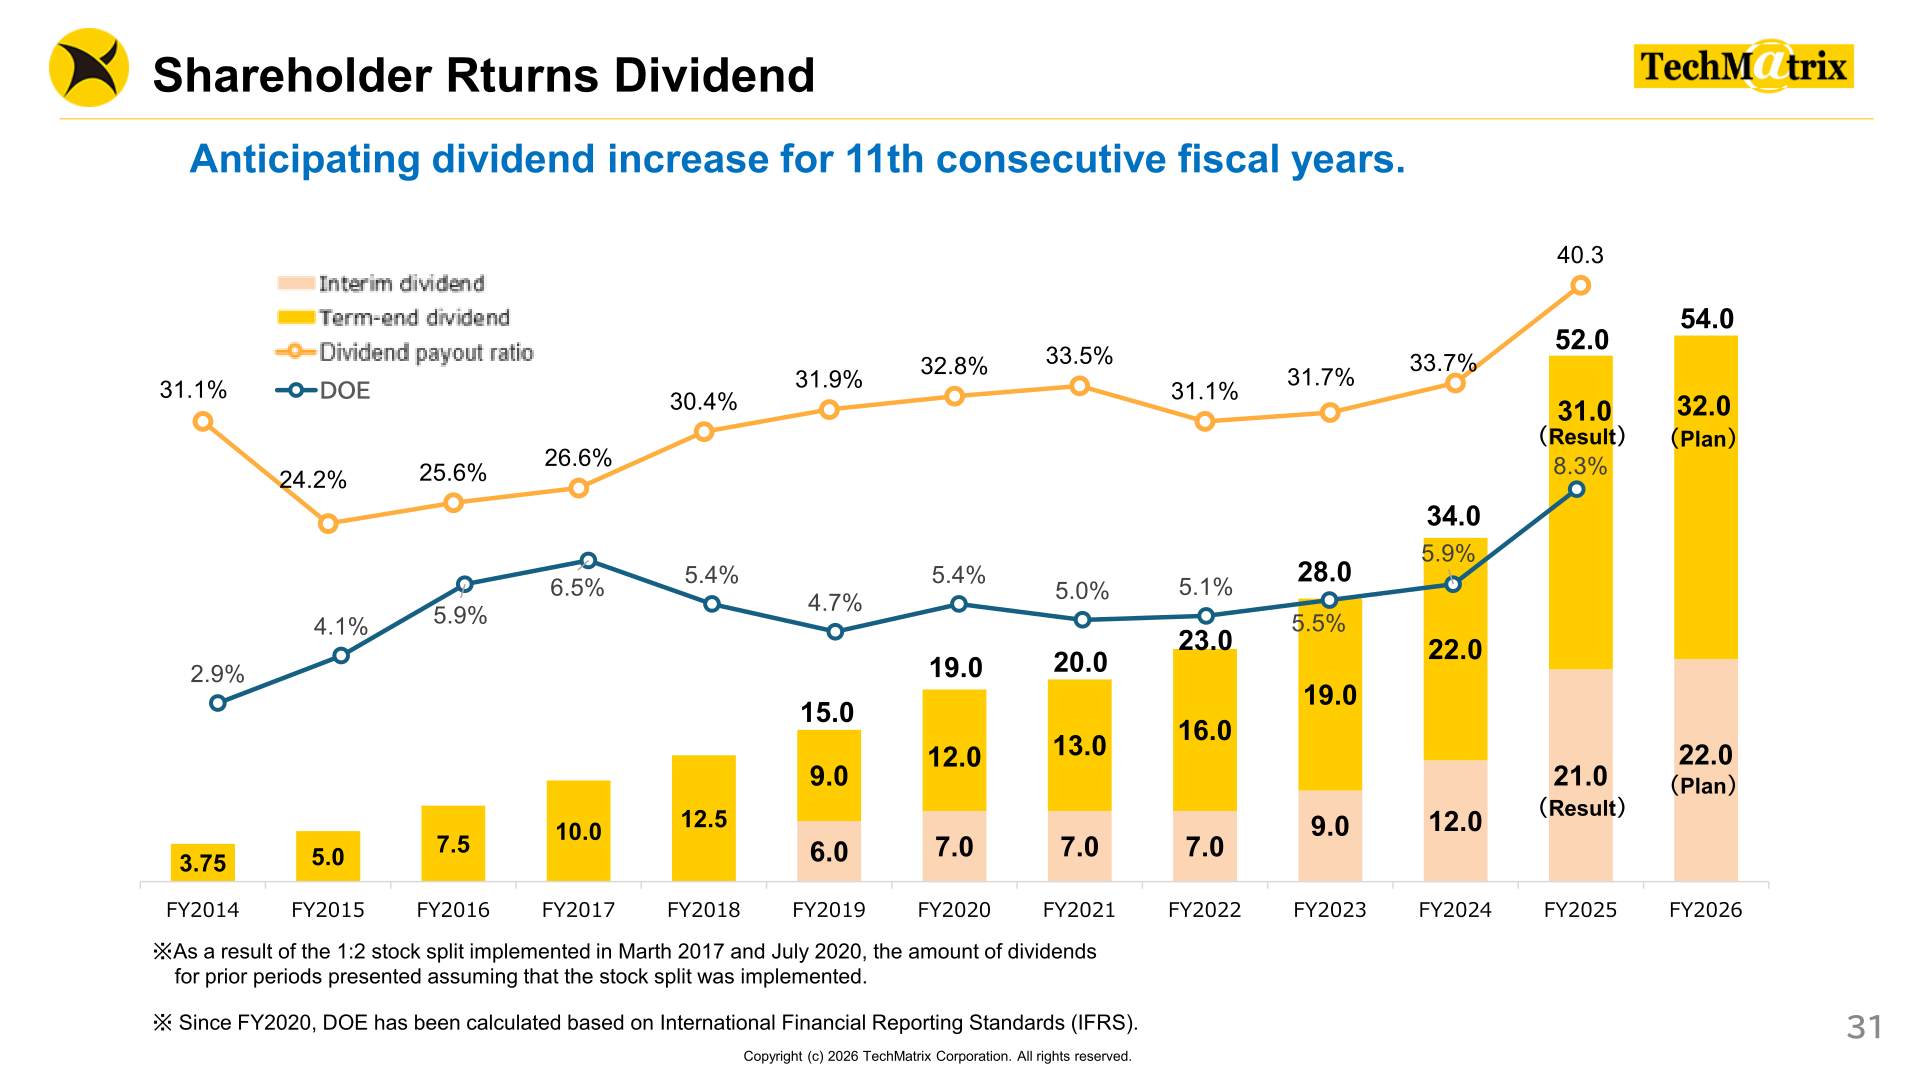
The FY2025 annual dividend was ¥52.0 per share (interim ¥21.0, term-end ¥31.0), up from ¥34.0 in FY2024, with a dividend payout ratio of 40.3% and DOE of 8.3%. For FY2026 the company plans ¥54.0 (interim ¥22.0, term-end ¥32.0), anticipating a dividend increase for the 11th consecutive fiscal year. Under its revised dividend policy, TechMatrix aims to pay whichever is the higher of a dividend making the consolidated payout ratio 40% or a dividend making the consolidated dividend on equity ratio (DOE) 7%, and will consider share buybacks based on its financial position, investment plans, capital efficiency and other factors.
| Dividend per share (¥) | FY2024 (Result) | FY2025 (Result) | FY2026 (Plan) |
|---|---|---|---|
| Interim dividend | 12.0 | 21.0 | 22.0 |
| Term-end dividend | 22.0 | 31.0 | 32.0 |
| Annual dividend | 34.0 | 52.0 | 54.0 |
| Dividend payout ratio | 33.7% | 40.3% | — |
| DOE | 5.9% | 8.3% | — |
Medium-Term Management Plan and Topics
FY2025 was the second year of the medium-term management plan “Creating Customer Value in the New Era” (April 2024–March 2027), whose purposes are expanding business domains, expanding business in the overseas market and creating businesses by utilizing data. Progress cited includes a partnership with U.S. OT security company Dispel, the launch of the automated penetration testing tool Pentera, accelerated introduction of Palo Alto Cortex XSIAM and a supporting installation, operations and monitoring service; deployment of EdTech in public schools and a business alliance with Benesse; the in-house software development dashboard Quomiru; and the acquisition of Regulus inc., a specialist in clinical research using medical imaging.
In the Medical Systems business, TechMatrix made Medmain Inc., which possesses pathological diagnosis technologies including AI development technologies, a consolidated subsidiary, aiming to expand into the pathology area by leveraging PSP’s cloud storage of medical image data. For the fiscal year ended December 31, 2025, Medmain reported revenue of ¥158 million and operating profit of △¥396 million.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















