
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: DIGITAL HEARTS HOLDINGS Co., Ltd. has a March fiscal year-end. In the company’s materials, “FY2025” refers to the fiscal year ended March 31, 2026, and “FY2026” to the current fiscal year ending March 31, 2027; the labels below follow the company’s materials. Figures are in JPY mn unless otherwise stated.
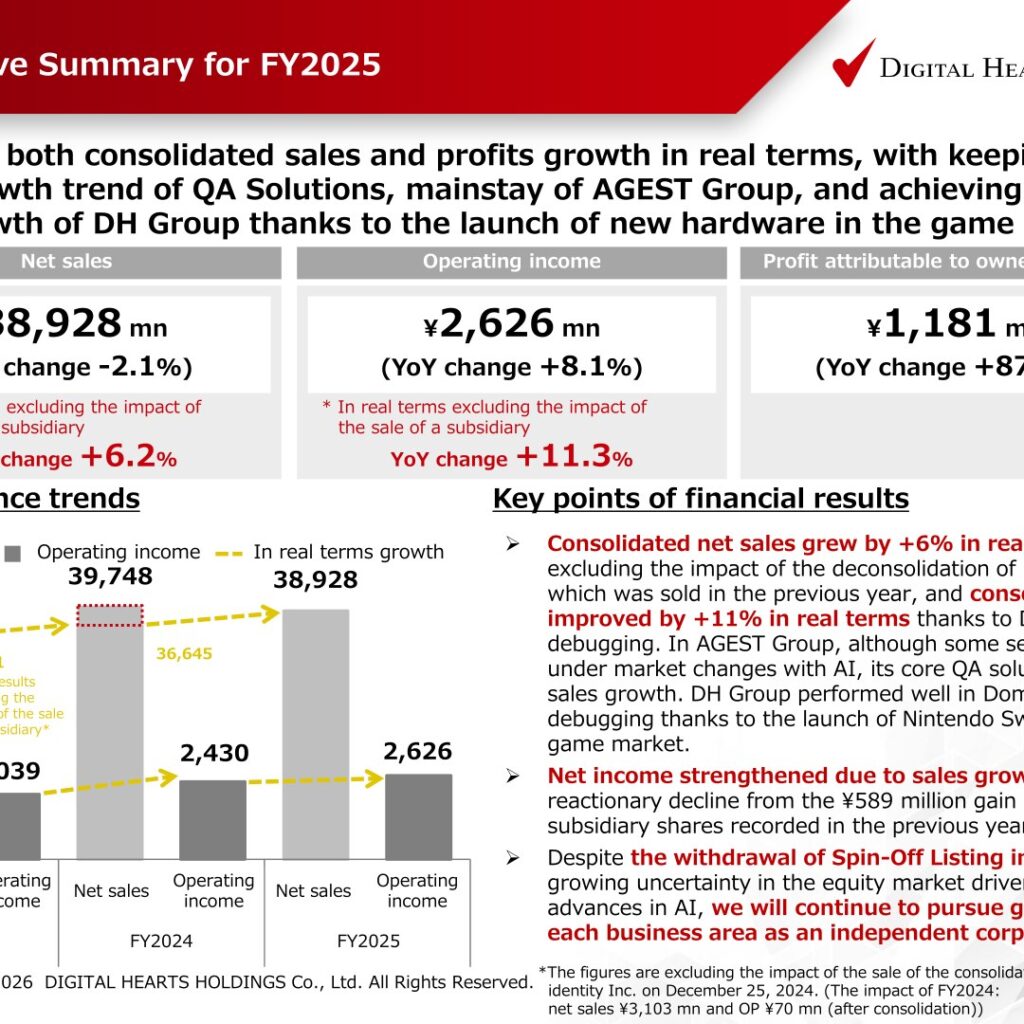
Digital Hearts Holdings, which operates game debugging and localization (DH Group Business) and software QA and security services (AGEST Group Business), reported FY2025 net sales of ¥38,928 mn (YoY change -2.1%), operating income of ¥2,626 mn (+8.1%) and profit attributable to owners of parent of ¥1,181 mn (+87.7%). Excluding the impact of the sale of the consolidated subsidiary identity Inc. on December 25, 2024, net sales grew +6.2% and operating income +11.3% in real terms, driven by Domestic debugging on the launch of Nintendo Switch 2. For FY2026 the company forecasts net sales of ¥41,080 mn (+5.5%), operating profit of ¥2,730 mn (+4.0%) and profit attributable to owners of parent of ¥1,850 mn (+56.6%), with an annual dividend of ¥25.0.
Consolidated Results (Full-Year Actual)
According to the company, sales decreased due to the exclusion of the subsidiary sold in FY2024, but existing businesses achieved sales growth excluding this impact (the impact of FY2024: net sales ¥3,103 mn and OP ¥70 mn after consolidation). Driven by the tailwind of a new hardware launch, high-profit Domestic debugging expanded, resulting in an increase in operating income. Despite the absence of the ¥589 million gain on the sale of subsidiary shares recorded in the previous year, net income increased significantly due to higher operating profit and lower extraordinary losses.
| Item (JPY mn) | FY2025 | FY2024 | YoY change | YoY change excl. sale of a subsidiary |
|---|---|---|---|---|
| Net sales | 38,928 | 39,748 | -2.1% | +6.2% |
| Gross profit | 10,000 | 10,137 | -1.4% | +4.3% |
| SG&A | 7,374 | 7,707 | -4.3% | +2.0% |
| Operating income | 2,626 | 2,430 | +8.1% | +11.3% |
| Operating income margin | 6.7% | 6.1% | +0.6 points | +0.3 points |
| Ordinary income | 2,582 | 2,278 | +13.4% | — |
| Profit attributable to owners of parent | 1,181 | 629 | +87.7% | — |
| EBITDA | 3,562 | 3,456 | +3.1% | +9.3% |
FY2025 non-operating expenses were ¥165 mn, including a ¥83 mn loss on investments accounted for using the equity method (losses on JetSynthesys Digital Services Private Limited and Fennel Co., Ltd.). Extraordinary losses were ¥726 mn, including impairment losses of ¥238 mn (mainly goodwill related to DIGITAL HEARTS CROSS Marketing and Solutions Limited), a ¥344 mn loss on valuation of investment securities (TOKYO GameFi, Inc. and other investments) and ¥140 mn of extra retirement allowances related to an early retirement program at AGEST, Inc. implemented to optimize back-office functions following the withdrawal of the Spin-Off Listing initiatives.
At the end of FY2025 (March 31, 2026), total assets were ¥21,531 mn (+¥1,582 mn), with goodwill rising to ¥1,790 mn from ¥1,035 mn, and total net assets were ¥9,961 mn. Net cash provided by operating activities was ¥3,224 mn and net cash used in investing activities was -¥3,724 mn. The shareholders’ equity ratio was 44.7% and ROE was 12.7%.
Segment Results
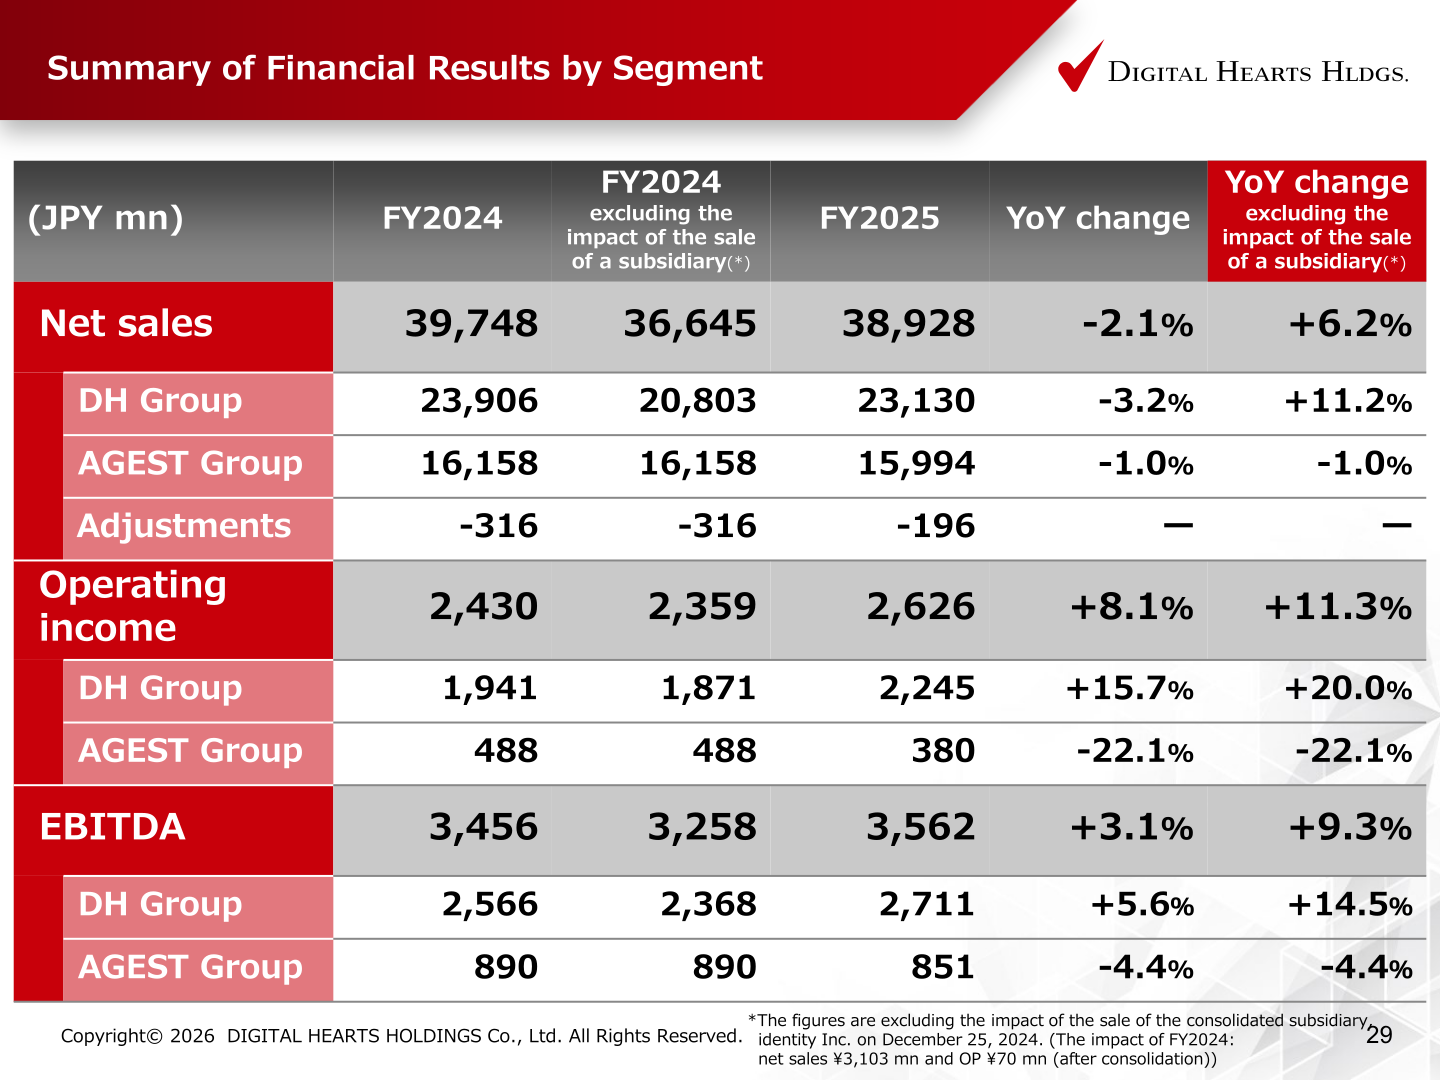
DH Group Business: net sales were ¥23,130 mn (-3.2%), but +11.2% in real terms excluding the subsidiary sale, and segment income rose +15.7% to ¥2,245 mn, exceeding the company plan. Domestic debugging sales grew +10.5% to ¥15,116 mn, capturing increasing demand against the backdrop of the Nintendo Switch 2 launch, with console-game debugging growing more than +20% YoY; its gross profit margin remained at 27.4%, in line with the previous year. Global and others sales were ¥8,014 mn (-21.6%), but grew +13% in real terms on translation and LQA growth from the full-scale launch of “ella,” a game-specialized AI translation engine, and game-development support for new Nintendo Switch 2 titles. HUWIZ SOLUTIONS INC., a Canadian gaming QA company that became a consolidated subsidiary on November 20, 2025, contributed from Q4. A change in depreciation methods at a subsidiary increased full-year segment income by ¥93 mn.
AGEST Group Business: net sales were ¥15,994 mn (-1.0%) and segment income was ¥380 mn (-22.1%). QA solution sales rose +1.1% to ¥14,083 mn, as domestic testing projects increased despite a decline in development support services amid wider AI penetration, and overseas QA returned to growth excluding MK Partners, Inc., sold in FY2024. IT services and others sales fell -14.3% to ¥1,910 mn due to the strategic downsizing of low-profit businesses and vendor price hikes on security monitoring tools. Segment income declined due to lower high-margin security monitoring revenue and increased Q4 promotional spending for the proprietary AI test tool “TFACT” and the vulnerability risk visualization tool “SBOM Archi.”
| Segment | Metric (JPY mn) | FY2025 | FY2024 | YoY change |
|---|---|---|---|---|
| DH Group Business | Net sales | 23,130 | 23,906 | -3.2% |
| DH Group Business | Domestic debugging net sales | 15,116 | 13,679 | +10.5% |
| DH Group Business | Global and others net sales | 8,014 | 10,226 | -21.6% |
| DH Group Business | Segment income | 2,245 | 1,941 | +15.7% |
| DH Group Business | EBITDA | 2,711 | 2,566 | +5.6% |
| AGEST Group Business | Net sales | 15,994 | 16,158 | -1.0% |
| AGEST Group Business | QA solution net sales | 14,083 | 13,928 | +1.1% |
| AGEST Group Business | IT services and others net sales | 1,910 | 2,230 | -14.3% |
| AGEST Group Business | Segment income | 380 | 488 | -22.1% |
| AGEST Group Business | EBITDA | 851 | 890 | -4.4% |
FY2026 Forecast
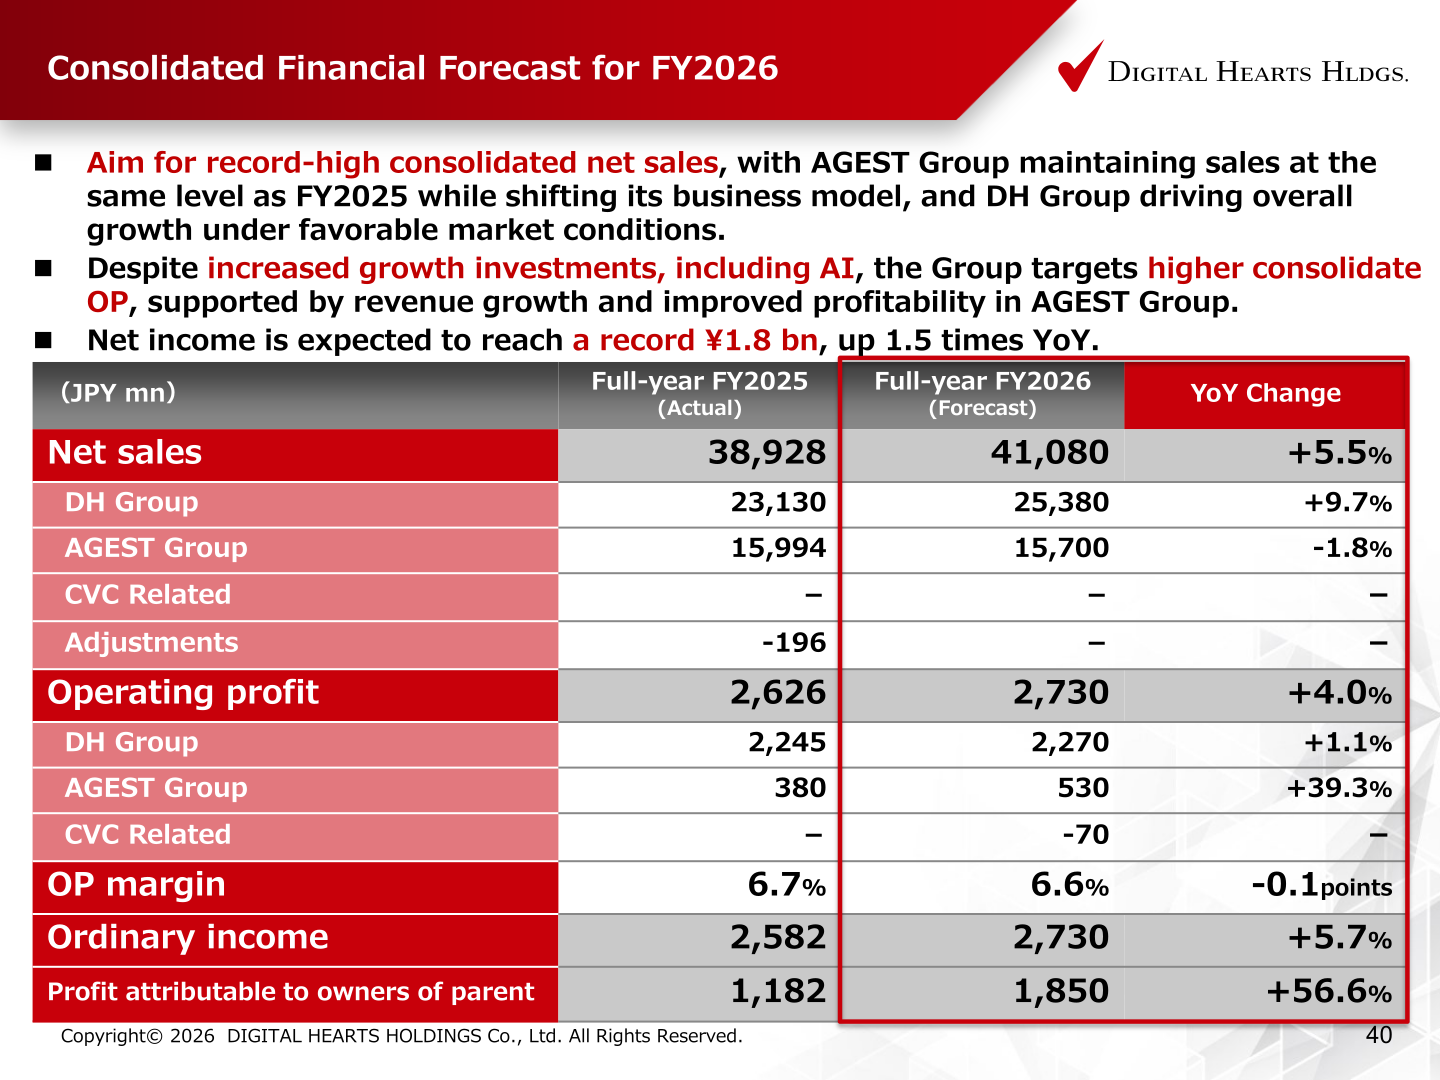
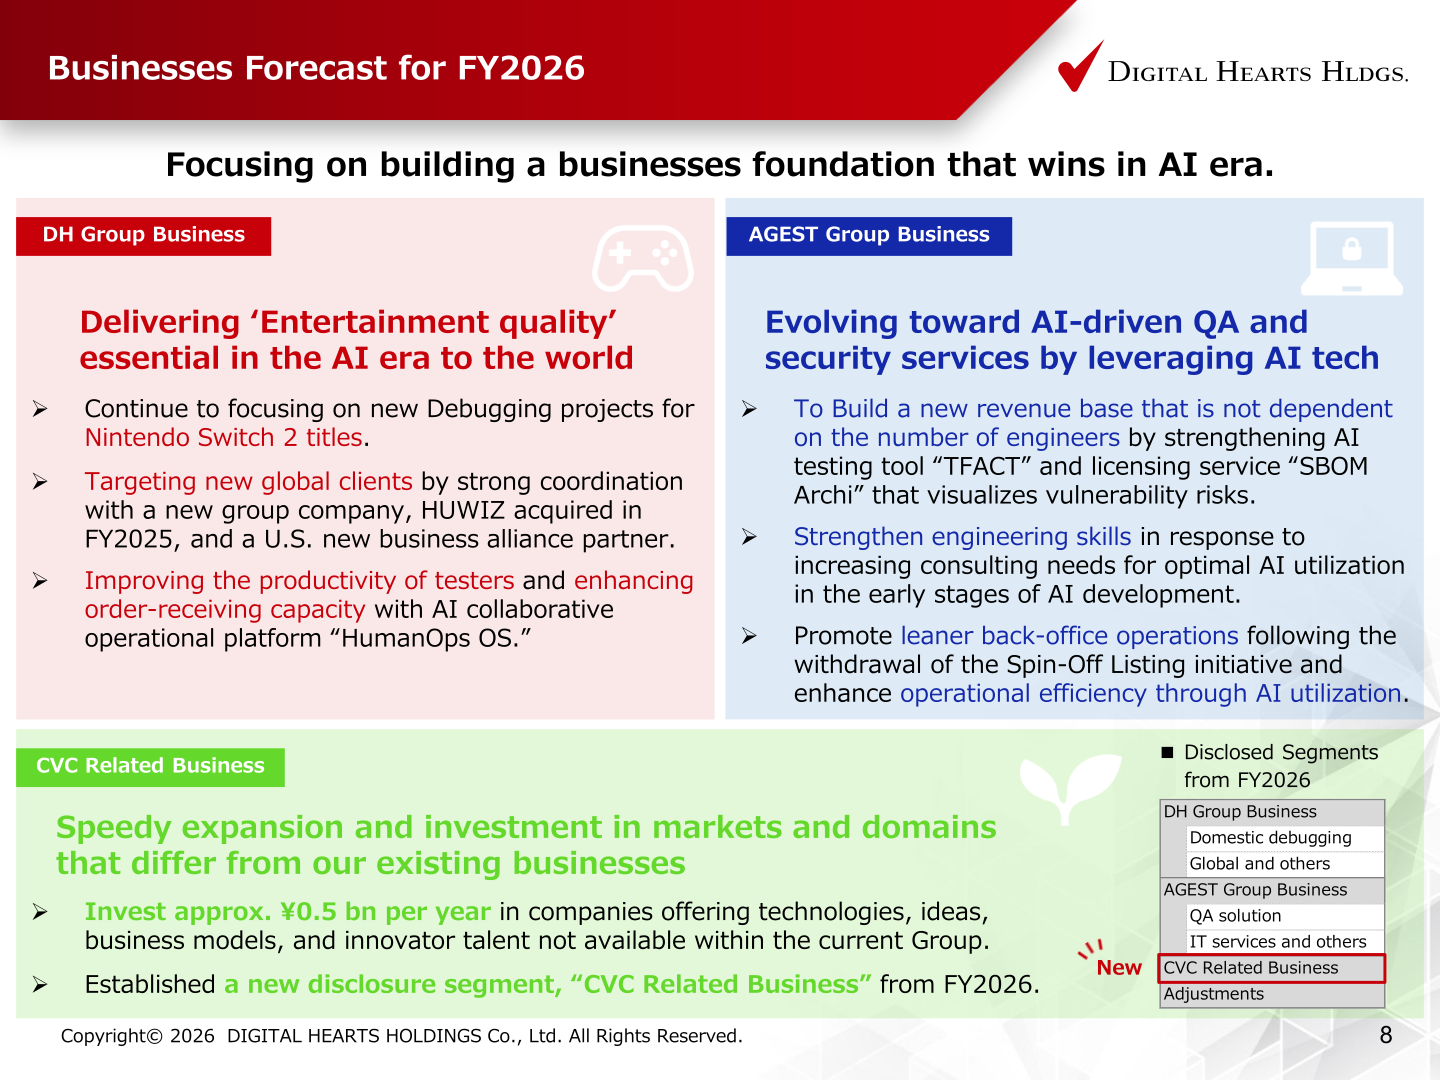
For FY2026 the company aims for record-high consolidated net sales, with the AGEST Group maintaining sales at the same level as FY2025 while shifting its business model, and the DH Group driving overall growth under favorable market conditions. Despite increased growth investments, including AI, it targets higher consolidated operating profit, supported by revenue growth and improved profitability in the AGEST Group, and expects net income to reach a record ¥1.8 bn. A new disclosure segment, “CVC Related Business,” is established from FY2026.
| Item (JPY mn) | FY2026 (Forecast) | FY2025 (Actual) | YoY change |
|---|---|---|---|
| Net sales | 41,080 | 38,928 | +5.5% |
| DH Group | 25,380 | 23,130 | +9.7% |
| AGEST Group | 15,700 | 15,994 | -1.8% |
| Operating profit | 2,730 | 2,626 | +4.0% |
| DH Group | 2,270 | 2,245 | +1.1% |
| AGEST Group | 530 | 380 | +39.3% |
| CVC Related | -70 | - | - |
| OP margin | 6.6% | 6.7% | -0.1points |
| Ordinary income | 2,730 | 2,582 | +5.7% |
| Profit attributable to owners of parent | 1,850 | 1,182 | +56.6% |
The forecast slide shows the FY2025 actual profit attributable to owners of parent as ¥1,182 mn, while the results summary slides show ¥1,181 mn; both figures are reproduced as stated in the materials.
Shareholder Returns
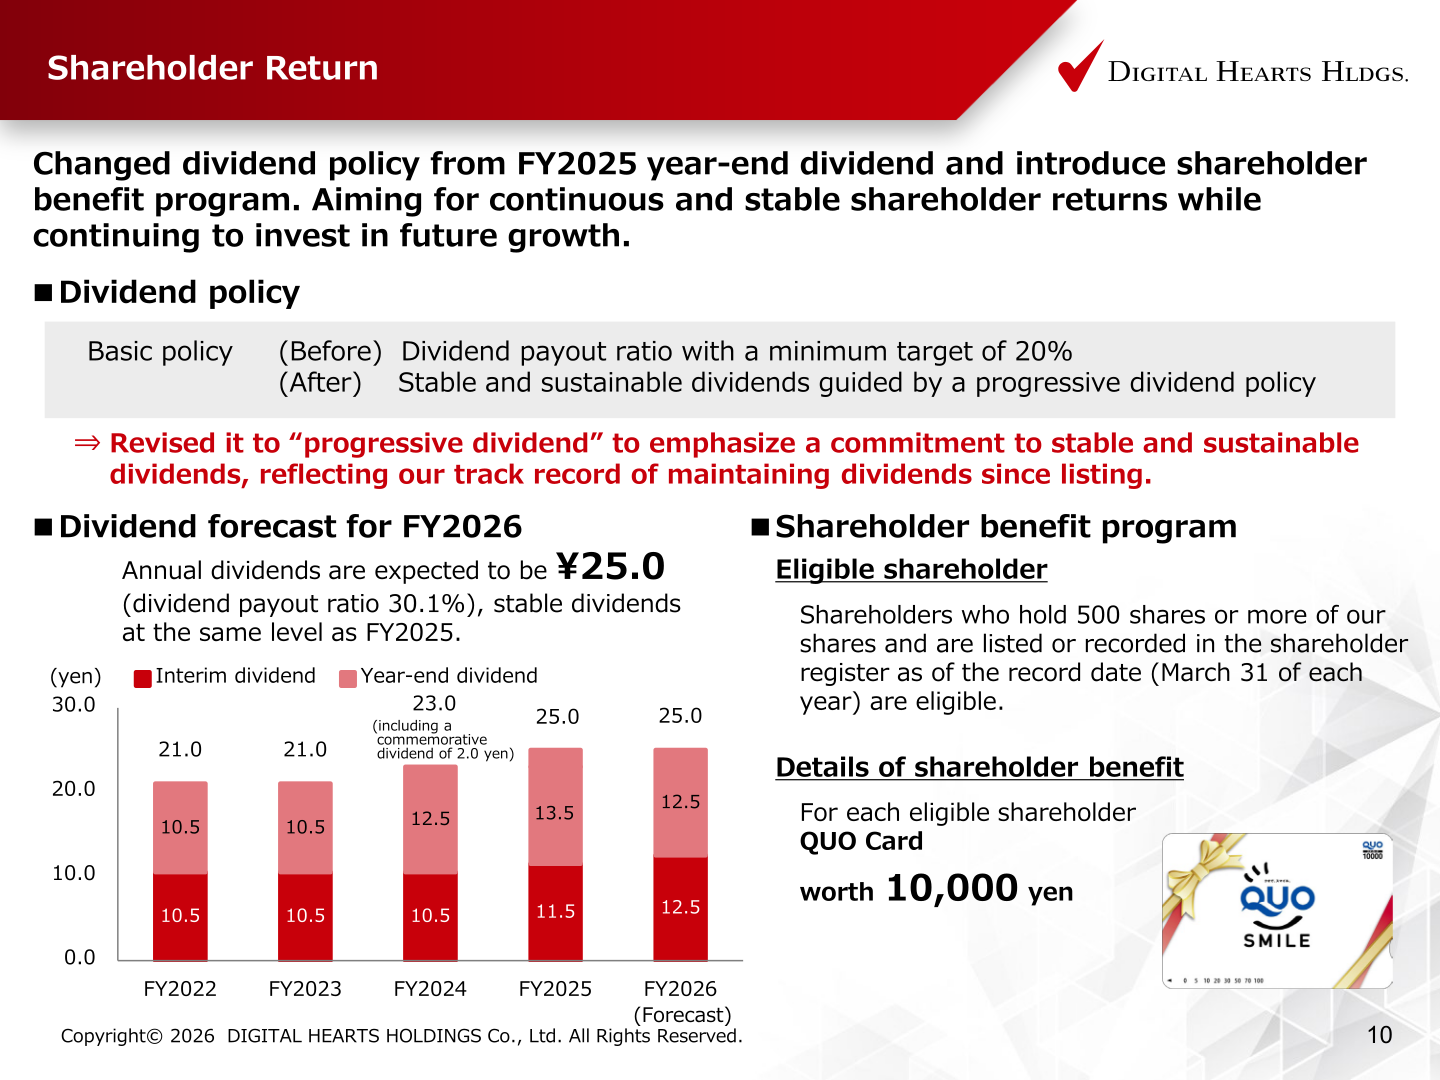
The company changed its dividend policy from the FY2025 year-end dividend, from a dividend payout ratio with a minimum target of 20% to stable and sustainable dividends guided by a progressive dividend policy, and introduced a shareholder benefit program. The FY2025 annual dividend was ¥25.0 (interim ¥11.5, year-end ¥13.5), and the FY2026 annual dividend is expected to be ¥25.0 (dividend payout ratio 30.1%), at the same level as FY2025. Under the new benefit program, shareholders holding 500 shares or more as of the March 31 record date each year receive a QUO Card worth 10,000 yen.
| Dividend per share (yen) | FY2026 (Forecast) | FY2025 | FY2024 |
|---|---|---|---|
| Interim | 12.5 | 11.5 | 10.5 |
| Year-end | 12.5 | 13.5 | 12.5 |
| Annual | 25.0 | 25.0 | 23.0 (including a commemorative dividend of 2.0 yen) |
Growth Strategy and Topics
The Spin-Off Listing initiatives were withdrawn in response to changes in the equity market amid rapid advances in AI, and the company will continue to pursue growth across each business area as an independent corporate group. The DH Group Business aims to deliver “Entertainment quality” assurance driven by human sensibility, intuition and insight, focusing on new debugging projects for Nintendo Switch 2 titles, targeting new global clients with HUWIZ and a U.S. localization business alliance partner, and improving tester productivity with the AI collaborative operational platform “HumanOps OS.”
The AGEST Group Business aims to transition from a man-month model to a SaaS and recurring model. It started external sales of the AI-enabled test management tool TFACT in January 2026, and its SBOM management tool, also launched in January 2026, received over 400 inquiries within 4 months of launch. Multiple recurring services are planned for launch in FY2026, alongside leaner back-office operations following the withdrawal of the Spin-Off Listing initiative. The Group has also established a Corporate Venture Capital (CVC) division with an annual investment level of approx. ¥500 mn, and adheres to a financial discipline of a consolidated ROIC (EBITDA basis) of at least 15%.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















