
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
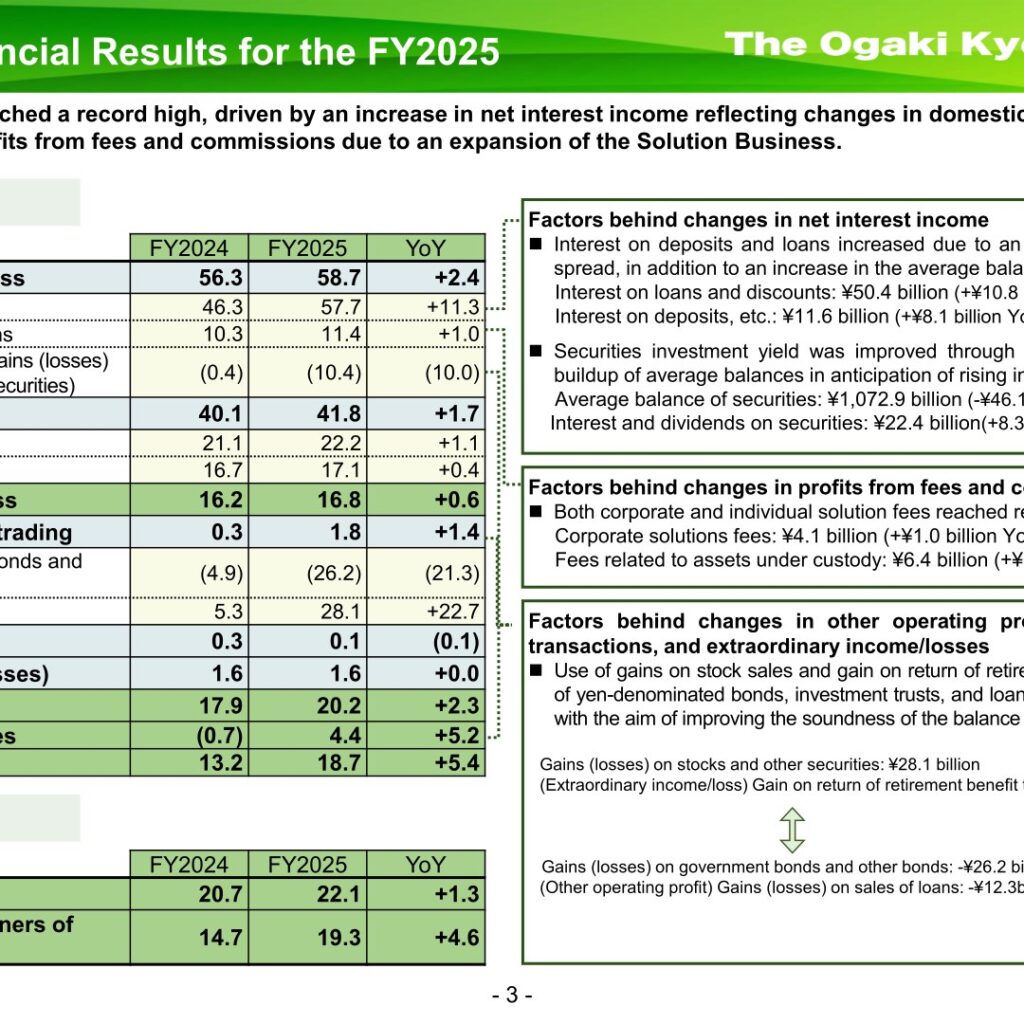
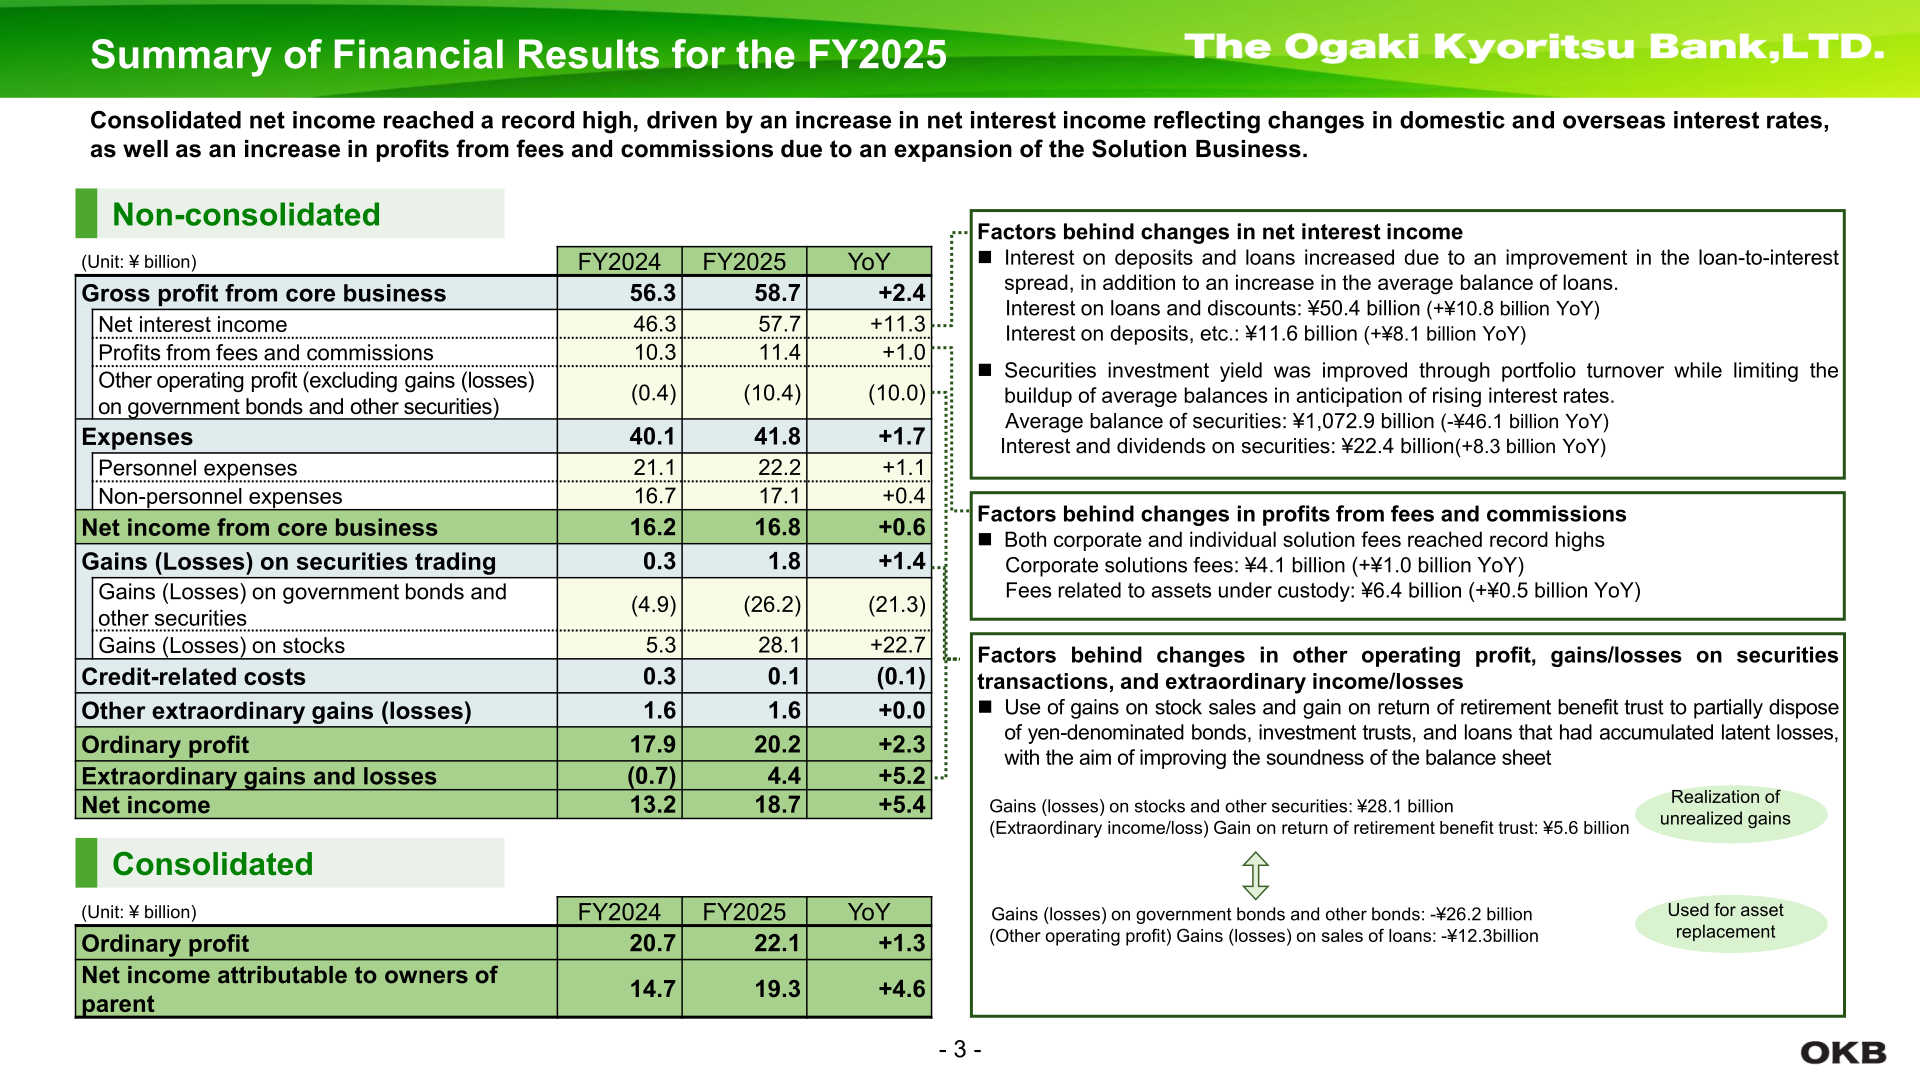
The Ogaki Kyoritsu Bank, Ltd. (8361) reported consolidated net income attributable to owners of parent of ¥19.3 billion for the fiscal year ended March 31, 2026 (FY2025), a record high, up ¥4.6 billion year on year. The increase was driven by higher net interest income amid rising domestic and overseas interest rates and higher profits from fees and commissions on growth in the Solution Business. Consolidated ordinary profit rose ¥1.3 billion to ¥22.1 billion, and consolidated ROE increased 1.19 percentage points to 5.67%, exceeding the bank’s medium-term target of 5.0% or higher. The annual dividend for FY2025 was increased by ¥40 to ¥150 per share (including a ¥10 commemorative dividend), and the bank plans a further record-high consolidated net income of ¥20.6 billion for FY2026.
Consolidated Results (Full-Year Actual)
Consolidated net income reached a record high on higher net interest income and fee income, together with gains on sales of stocks recorded in connection with a reduction of strategic shareholdings, the proceeds of which were used to dispose of assets carrying unrealized losses in order to strengthen balance sheet soundness.
| Item | FY2025 | FY2024 | Change |
|---|---|---|---|
| Ordinary profit (¥ billion) | 22.1 | 20.7 | +1.3 |
| Net income attributable to owners of parent (¥ billion) | 19.3 | 14.7 | +4.6 |
| Consolidated ROE | 5.67% | 4.48% | +1.19ppt |
Non-Consolidated Results (Core Business)
On a non-consolidated basis (figures in ¥ billion), gross profit from core business increased on higher net interest income, driven by an improvement in the loan-to-deposit interest spread and an increase in the average balance of loans, as well as higher securities yields. Other operating profit declined due to losses on sales of loans recorded as part of balance-sheet asset replacement.
| Item | FY2025 | FY2024 | Change |
|---|---|---|---|
| Gross profit from core business | 58.7 | 56.3 | +2.4 |
| Net interest income | 57.7 | 46.3 | +11.3 |
| Profits from fees and commissions | 11.4 | 10.3 | +1.0 |
| Other operating profit (ex. gains/losses on government bonds and other securities) | (10.4) | (0.4) | (10.0) |
| Expenses | 41.8 | 40.1 | +1.7 |
| Net income from core business | 16.8 | 16.2 | +0.6 |
| Ordinary profit | 20.2 | 17.9 | +2.3 |
| Net income | 18.7 | 13.2 | +5.4 |
Asset Quality and Capital
Credit-related costs (non-consolidated) decreased to ¥0.1 billion from ¥0.3 billion, mainly due to a decrease in the provision of specific allowance for loan losses. The balance of claims disclosed under the Banking Act and the Financial Revitalization Act decreased to ¥56.1 billion from ¥58.3 billion, and the non-performing loan ratio improved to 1.20% from 1.28%. The consolidated capital adequacy ratio was 9.82% on a transitional basis (down from 9.99% at FY2024) and 9.38% on a fully loaded basis, both above the bank’s 9.0%-or-higher target; risk assets increased on loan growth and the phased application of risk weights for equities.
| Item | FY2025 | FY2024 | Change |
|---|---|---|---|
| Credit-related costs, non-consolidated (¥ billion) | 0.1 | 0.3 | (0.1) |
| Non-performing loan ratio | 1.20% | 1.28% | (0.08)ppt |
| Balance of non-performing loans (¥ billion) | 56.1 | 58.3 | (2.2) |
| Consolidated capital adequacy ratio, transitional basis | 9.82% | 9.99% | – |
FY2026 Forecast
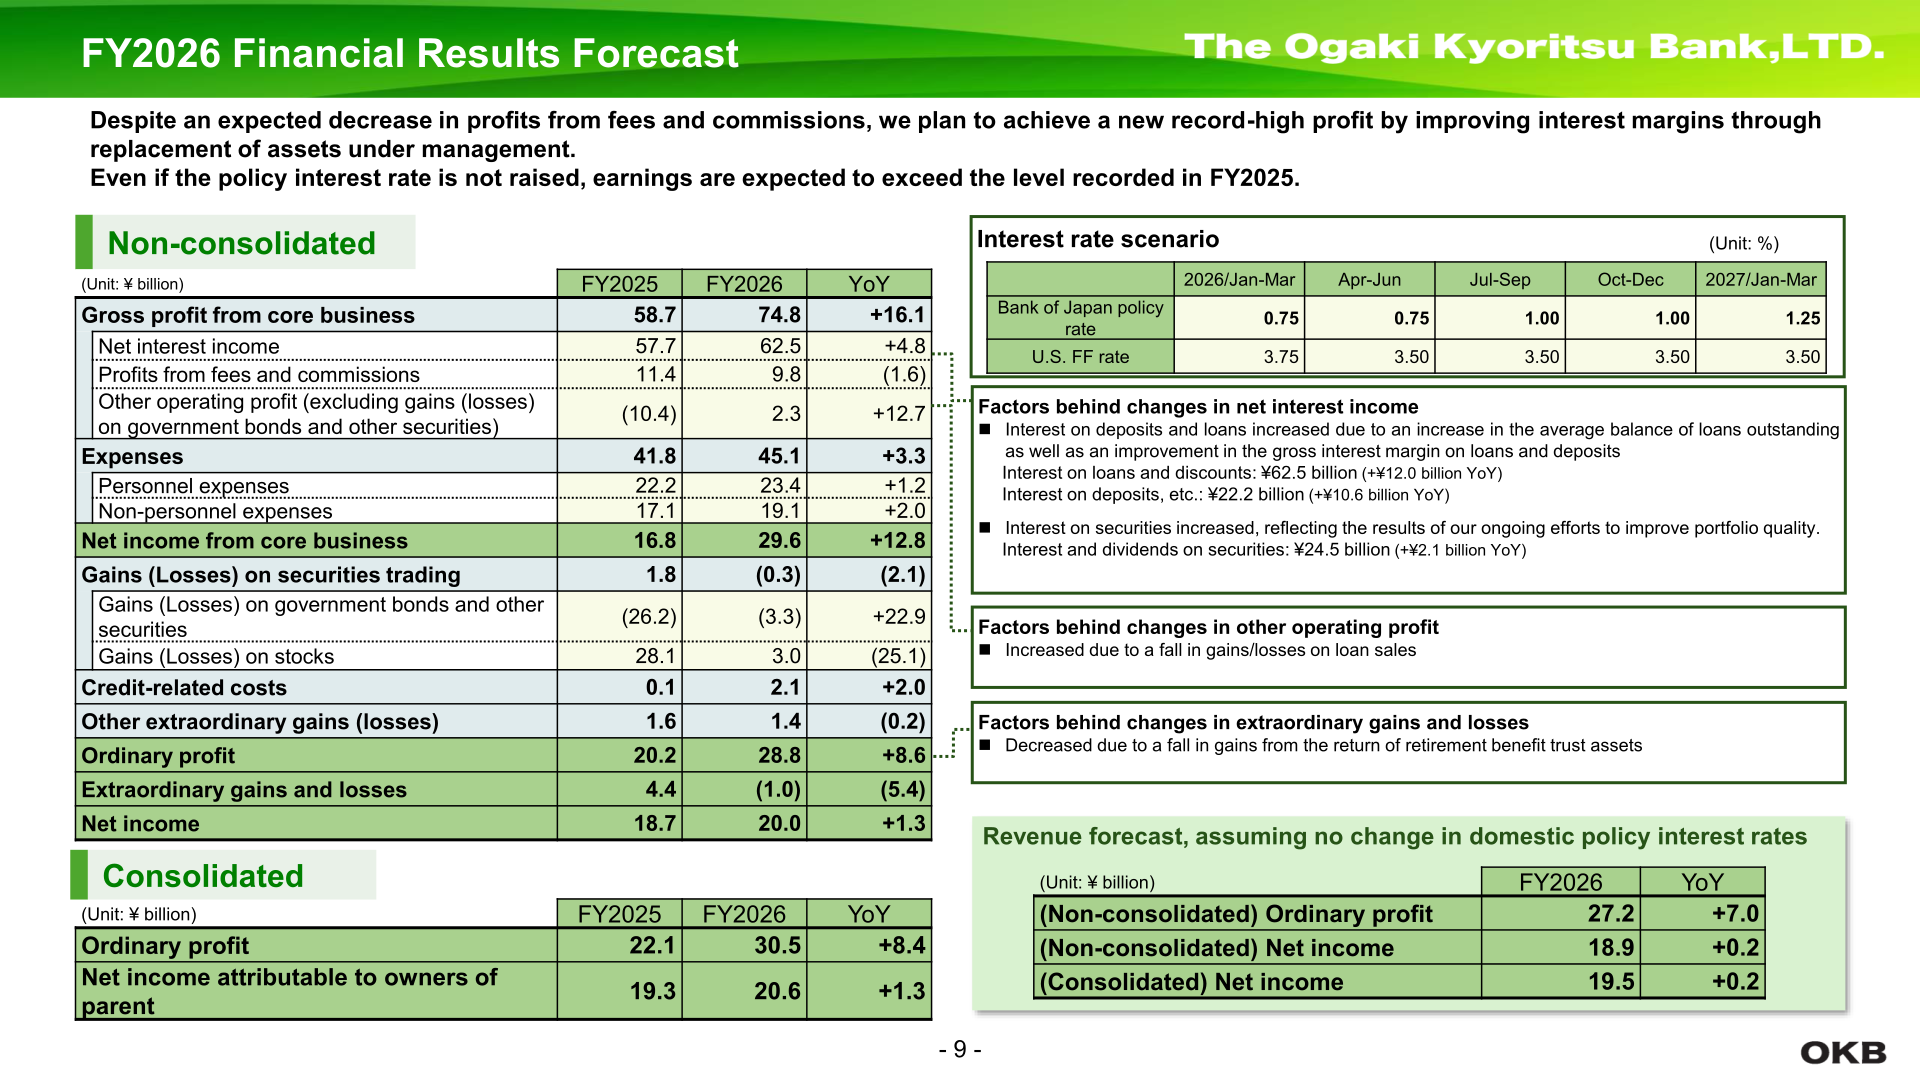
For FY2026 (the fiscal year ending March 31, 2027), OKB forecasts consolidated net income attributable to owners of parent of ¥20.6 billion, a further record high, and consolidated ordinary profit of ¥30.5 billion. The bank expects a decrease in profits from fees and commissions but plans to offset this through improved interest margins from replacement of assets under management. Under its assumed interest rate scenario (Bank of Japan policy rate rising from 0.75% in Jan-Mar 2026 to 1.25% by Jan-Mar 2027), even if the policy rate is not raised further, the bank still expects earnings to exceed the FY2025 level, projecting non-consolidated ordinary profit of ¥27.2 billion and consolidated net income of ¥19.5 billion in that scenario.
| Item | FY2026 (Forecast) | FY2025 (Actual) | Change |
|---|---|---|---|
| Ordinary profit, consolidated (¥ billion) | 30.5 | 22.1 | +8.4 |
| Net income attributable to owners of parent, consolidated (¥ billion) | 20.6 | 19.3 | +1.3 |
| Gross profit from core business, non-consolidated (¥ billion) | 74.8 | 58.7 | +16.1 |
| Net income, non-consolidated (¥ billion) | 20.0 | 18.7 | +1.3 |
Financial Targets (Medium-Term Management Plan “Always”)
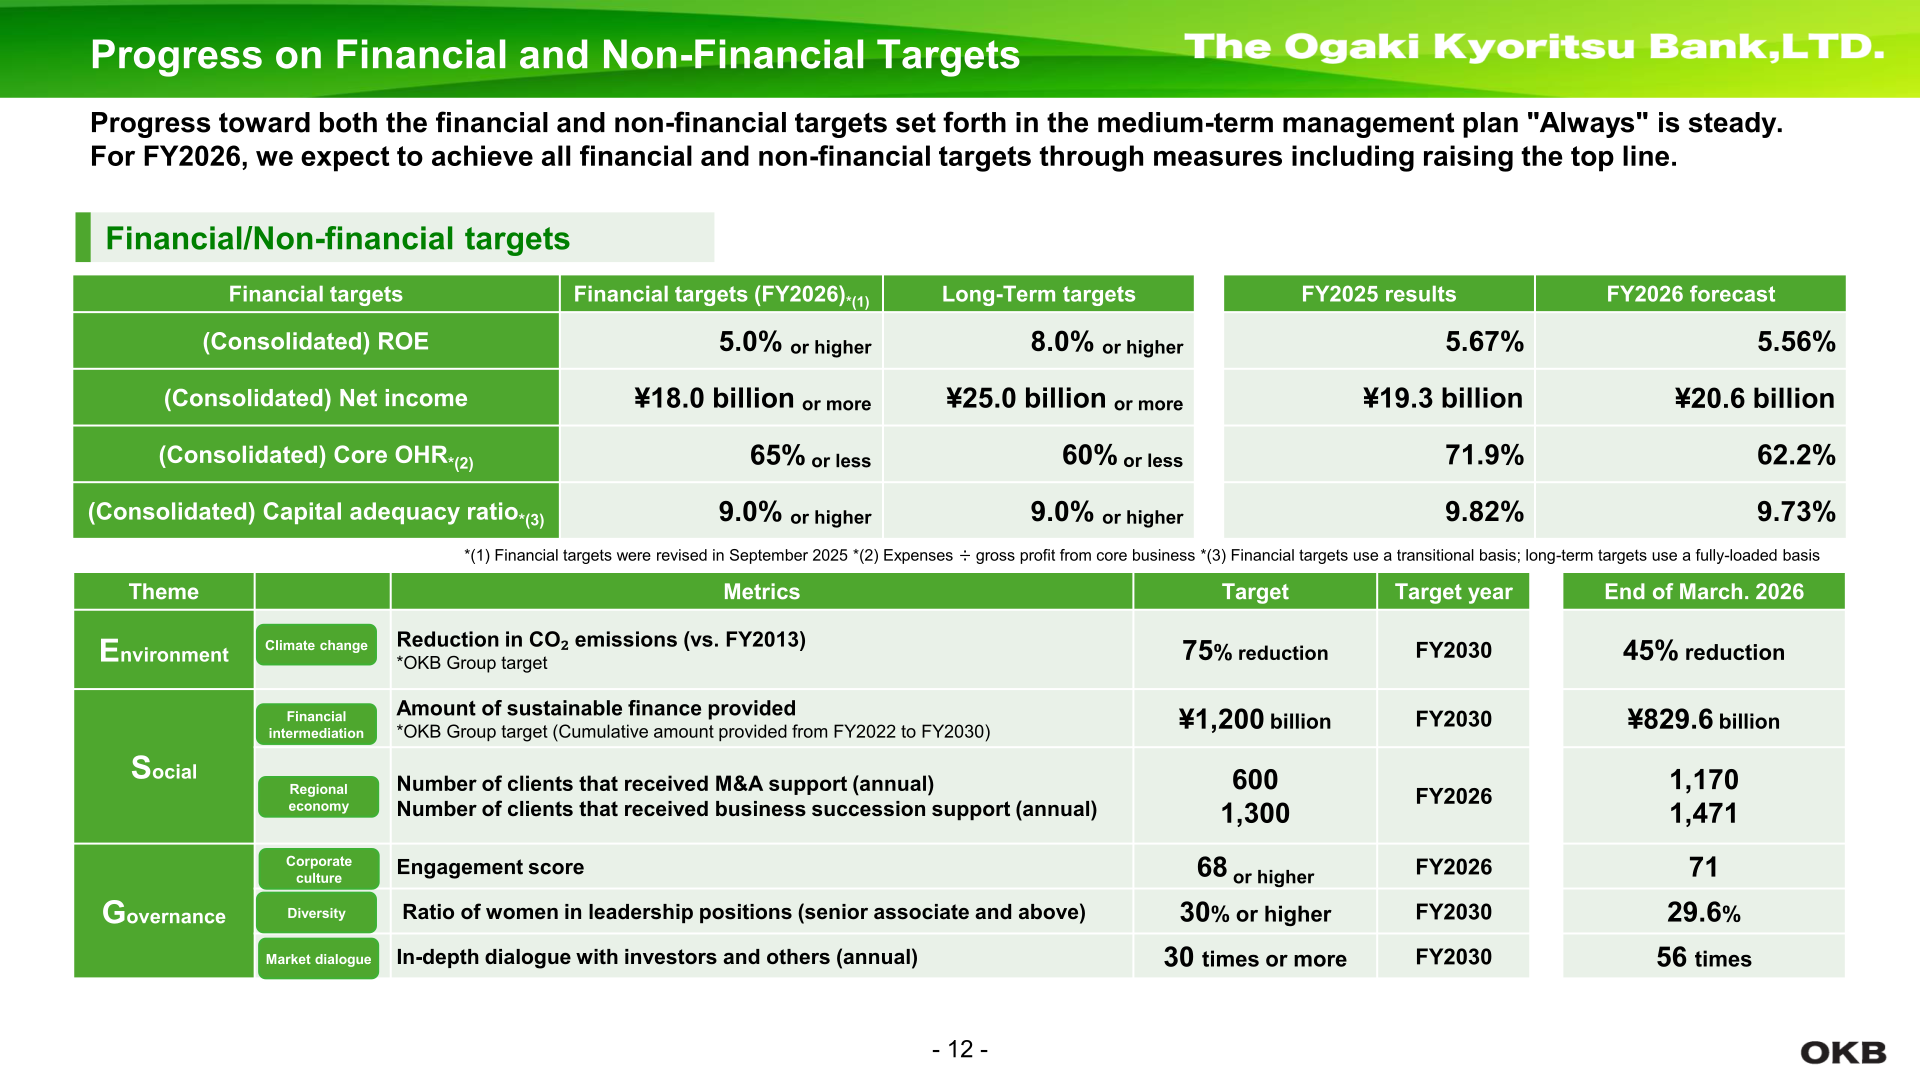
Financial targets under the medium-term management plan “Always” were revised upward in September 2025. The bank aims for consolidated ROE of 5.0% or higher (long-term target: 8.0% or higher), consolidated net income of ¥18.0 billion or more (long-term: ¥25.0 billion or more), consolidated Core OHR (expenses divided by gross profit from core business) of 65% or less (long-term: 60% or less), and a consolidated capital adequacy ratio (transitional basis) of 9.0% or higher. FY2025 results already exceeded the FY2026 targets for ROE, net income and capital adequacy ratio.
| Metric | FY2026 Target | Long-Term Target | FY2025 Results | FY2026 Forecast |
|---|---|---|---|---|
| Consolidated ROE | 5.0% or higher | 8.0% or higher | 5.67% | 5.56% |
| Consolidated net income | ¥18.0 billion or more | ¥25.0 billion or more | ¥19.3 billion | ¥20.6 billion |
| Consolidated Core OHR | 65% or less | 60% or less | 71.9% | 62.2% |
| Consolidated capital adequacy ratio | 9.0% or higher | 9.0% or higher | 9.82% | 9.73% |
Shareholder Returns
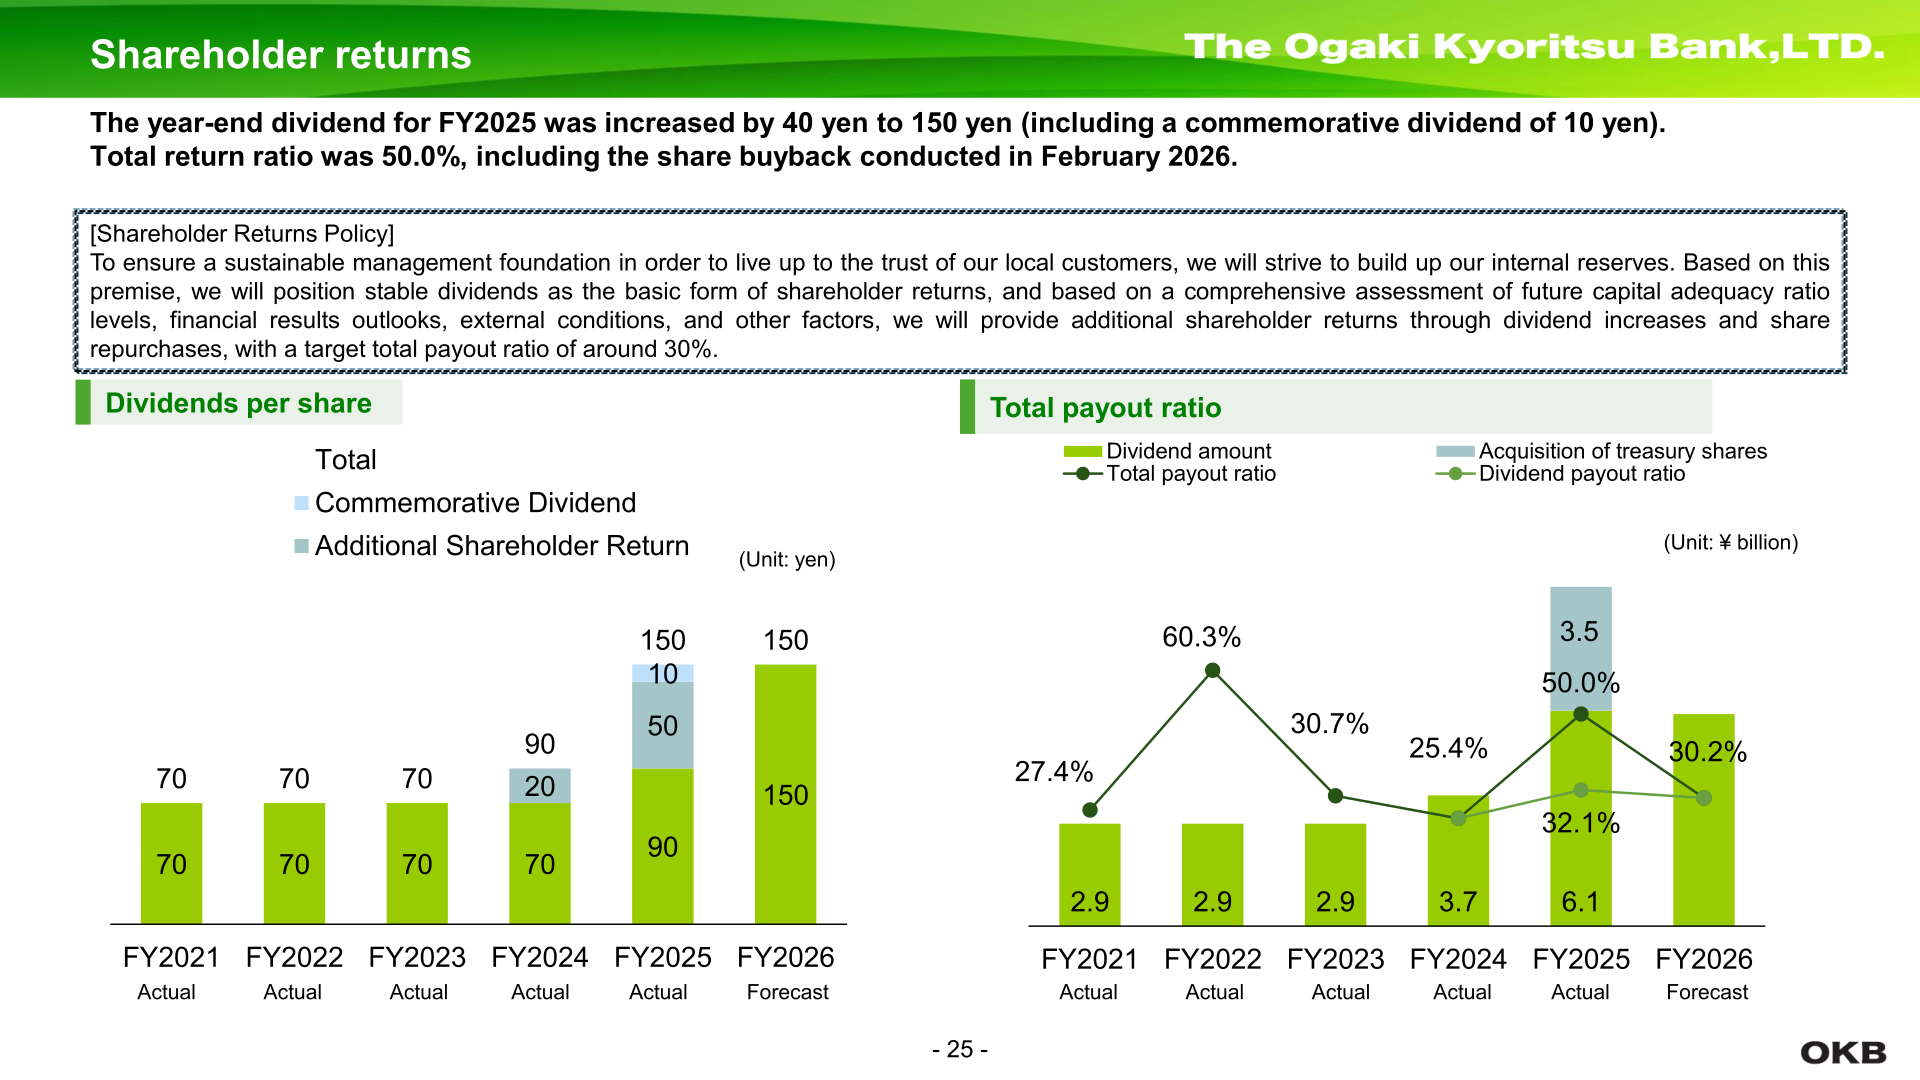
The year-end dividend for FY2025 was increased by ¥40 to ¥150 per share (including a commemorative dividend of ¥10). The total return ratio was 50.0%, including the share buyback conducted in February 2026. Under its shareholder returns policy, the bank positions stable dividends as the basic form of shareholder returns and, based on a comprehensive assessment of future capital adequacy ratio levels, financial results outlooks, external conditions and other factors, provides additional shareholder returns through dividend increases and share repurchases, targeting a total payout ratio of around 30%. The annual dividend per share for FY2026 is forecast to remain at ¥150.
| Item | FY2025 (Actual) | FY2026 (Forecast) |
|---|---|---|
| Dividend per share, annual (incl. commemorative dividend) | ¥150 | ¥150 |
| Total payout ratio | 50.0% | 30.2% |
Medium-Term Plan / Topics
Under the medium-term management plan “Always,” OKB aims to enhance corporate value by improving ROE through growth strategy, talent strategy and initiatives to strengthen the management foundation, while also seeking to improve PER through enhanced dialogue with shareholders. Consolidated PBR rose to 0.70 for FY2025 from 0.31 for FY2024, and consolidated PER rose to 13.2 for FY2025 from 6.7 for FY2024. The bank’s strategic shareholdings policy was revised in February 2026: it now targets reducing the ratio of cross-shareholdings (including deemed cross-shareholdings) to consolidated net assets (market value basis) to less than 20% by the end of March 2028, changed from the previous target of reducing strategic shareholdings (excluding deemed shareholdings) to roughly 20% of consolidated net assets by the end of March 2027. In FY2025, the number of strategic shareholding issues held decreased by 18 year on year to 205, though the consolidated net assets ratio (including deemed holdings) declined only slightly, to 27.5%, as market value rose with higher stock prices.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















