
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Komatsu Matere has a March fiscal year-end. This article classifies the fiscal year ended March 31, 2026 (April 2025 – March 2026), labeled “FY3/2026” in the company’s materials, as FY2025 under this site’s convention; the body text and tables below keep the company’s own labels. The forecast year is labeled “FY3/2027”.
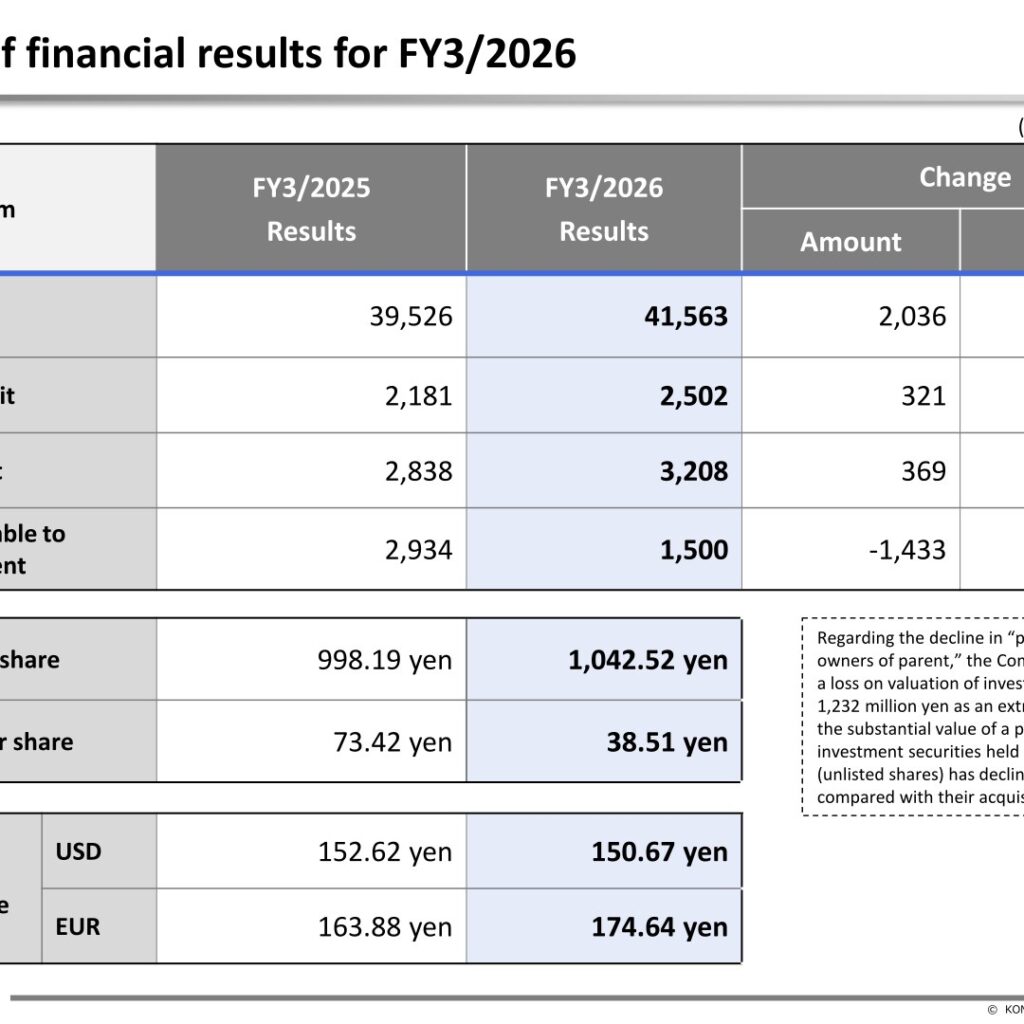
KOMATSU MATERE Co.,Ltd. released its “Financial Results for FY3/2026” on May 13, 2026. Net sales rose 5.2% year on year to 41,563 million yen, operating profit rose 14.7% to 2,502 million yen and ordinary profit rose 13.0% to 3,208 million yen. Profit attributable to owners of parent fell 48.9% to 1,500 million yen, as the company recorded a loss on valuation of investment securities of 1,232 million yen as an extraordinary loss. The annual dividend was 27 yen per share, an increase of 2 yen from the previous fiscal year. For FY3/2027, the company forecasts net sales of 42,000 million yen and operating profit of 1,500 million yen.
Consolidated Results (Full-Year Actual)
Net sales increased by 2,036 million yen to 41,563 million yen and operating profit increased by 321 million yen to 2,502 million yen. Regarding the decline in profit attributable to owners of parent, the company explains that it recorded a loss on valuation of investment securities of 1,232 million yen as an extraordinary loss, as the substantial value of a portion of the investment securities it holds (unlisted shares) declined significantly compared with their acquisition cost. Net income per share was 38.51 yen (73.42 yen in the previous year), and net assets per share were 1,042.52 yen (998.19 yen).
| Item (Millions of yen) | FY3/2026 Results | FY3/2025 Results | Change | Change (%) |
|---|---|---|---|---|
| Net sales | 41,563 | 39,526 | 2,036 | 5.2 |
| Operating profit | 2,502 | 2,181 | 321 | 14.7 |
| Ordinary profit | 3,208 | 2,838 | 369 | 13.0 |
| Profit attributable to owners of parent | 1,500 | 2,934 | -1,433 | -48.9 |
| Net income per share | 38.51 yen | 73.42 yen | ||
| Net assets per share | 1,042.52 yen | 998.19 yen | ||
| Average exchange rate (USD) | 150.67 yen | 152.62 yen | ||
| Average exchange rate (EUR) | 174.64 yen | 163.88 yen |
In the analysis of changes in operating profit, total profit increase factors were +1,588 million yen, including a sales price difference of +1,163 million yen, total cost reduction of +276 million yen, a raw materials and fuel price difference of +125 million yen, exchange rate of +18 million yen and other of +6 million yen (the portion of the profit increase attributable to the newly consolidated subsidiary). Total profit decrease factors were -1,266 million yen, consisting of production quantity of -438 million yen and restructuring and other charges of -828 million yen, which include system-related investments and expenses for improving the working environment, maintaining manufacturing facilities and enhancing welfare benefits.
Segment Results
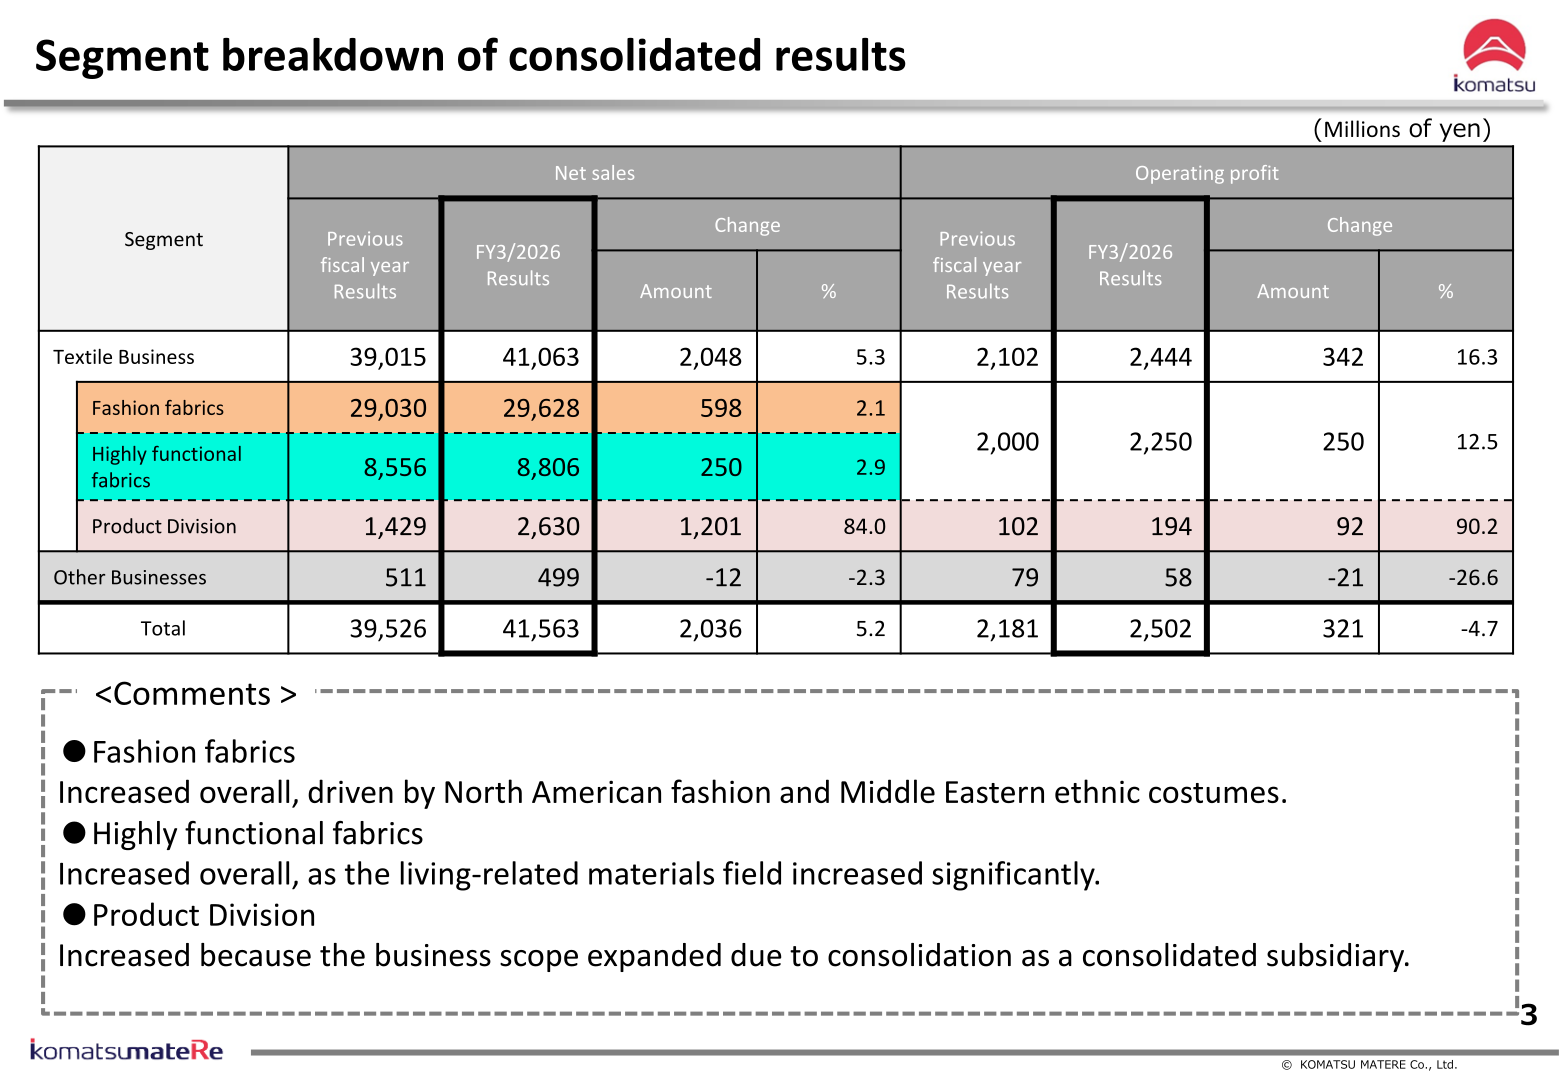
Textile Business net sales rose 5.3% to 41,063 million yen and operating profit rose 16.3% to 2,444 million yen. Fashion fabrics increased overall, driven by North American fashion and Middle Eastern ethnic costumes; within the division, national costume sales increased by 859 million yen (+15.4%) on the continued introduction of high-value-added products, while sports & functions decreased by 123 million yen (-2.3%) due to production adjustments in the domestic functional (uniform) field and fashion decreased by 137 million yen (-0.8%) due to a decline in sales to Asia, including China. Highly functional fabrics increased overall as the living-related materials field increased significantly; the living field rose by 374 million yen (+14.4%) as differentiated products for household goods, such as bags and parasols, continued to perform strongly. The Product Division increased because the business scope expanded due to consolidation as a consolidated subsidiary.
| Segment (Millions of yen) | Metric | FY3/2026 Results | Previous fiscal year Results | Change (%) |
|---|---|---|---|---|
| Textile Business | Net sales | 41,063 | 39,015 | 5.3 |
| Fashion fabrics | Net sales | 29,628 | 29,030 | 2.1 |
| Highly functional fabrics | Net sales | 8,806 | 8,556 | 2.9 |
| Product Division | Net sales | 2,630 | 1,429 | 84.0 |
| Other Businesses | Net sales | 499 | 511 | -2.3 |
| Total | Net sales | 41,563 | 39,526 | 5.2 |
| Textile Business | Operating profit | 2,444 | 2,102 | 16.3 |
| Fashion fabrics and Highly functional fabrics (combined) | Operating profit | 2,250 | 2,000 | 12.5 |
| Product Division | Operating profit | 194 | 102 | 90.2 |
| Other Businesses | Operating profit | 58 | 79 | -26.6 |
| Total | Operating profit | 2,502 | 2,181 |
By market, domestic sales rose by 1,311 million yen (+5.8%) and overseas sales rose by 725 million yen (+4.3%), with living-related materials and the Product Division increasing in the domestic market. Overseas, sales to North America rose 11.6% to 5,677 million yen as fashion sales to the United States and Canada continued to increase, and sales to the Middle East rose 12.1% to 5,991 million yen due to the continued introduction of high-value-added products. Sales to Europe fell 3.5% to 3,701 million yen (sales to luxury brands remained strong while the sports field decreased), and sales to Asia and others fell 14.5% to 2,232 million yen as casual fashion sales to China decreased.
FY3/2027 Forecast
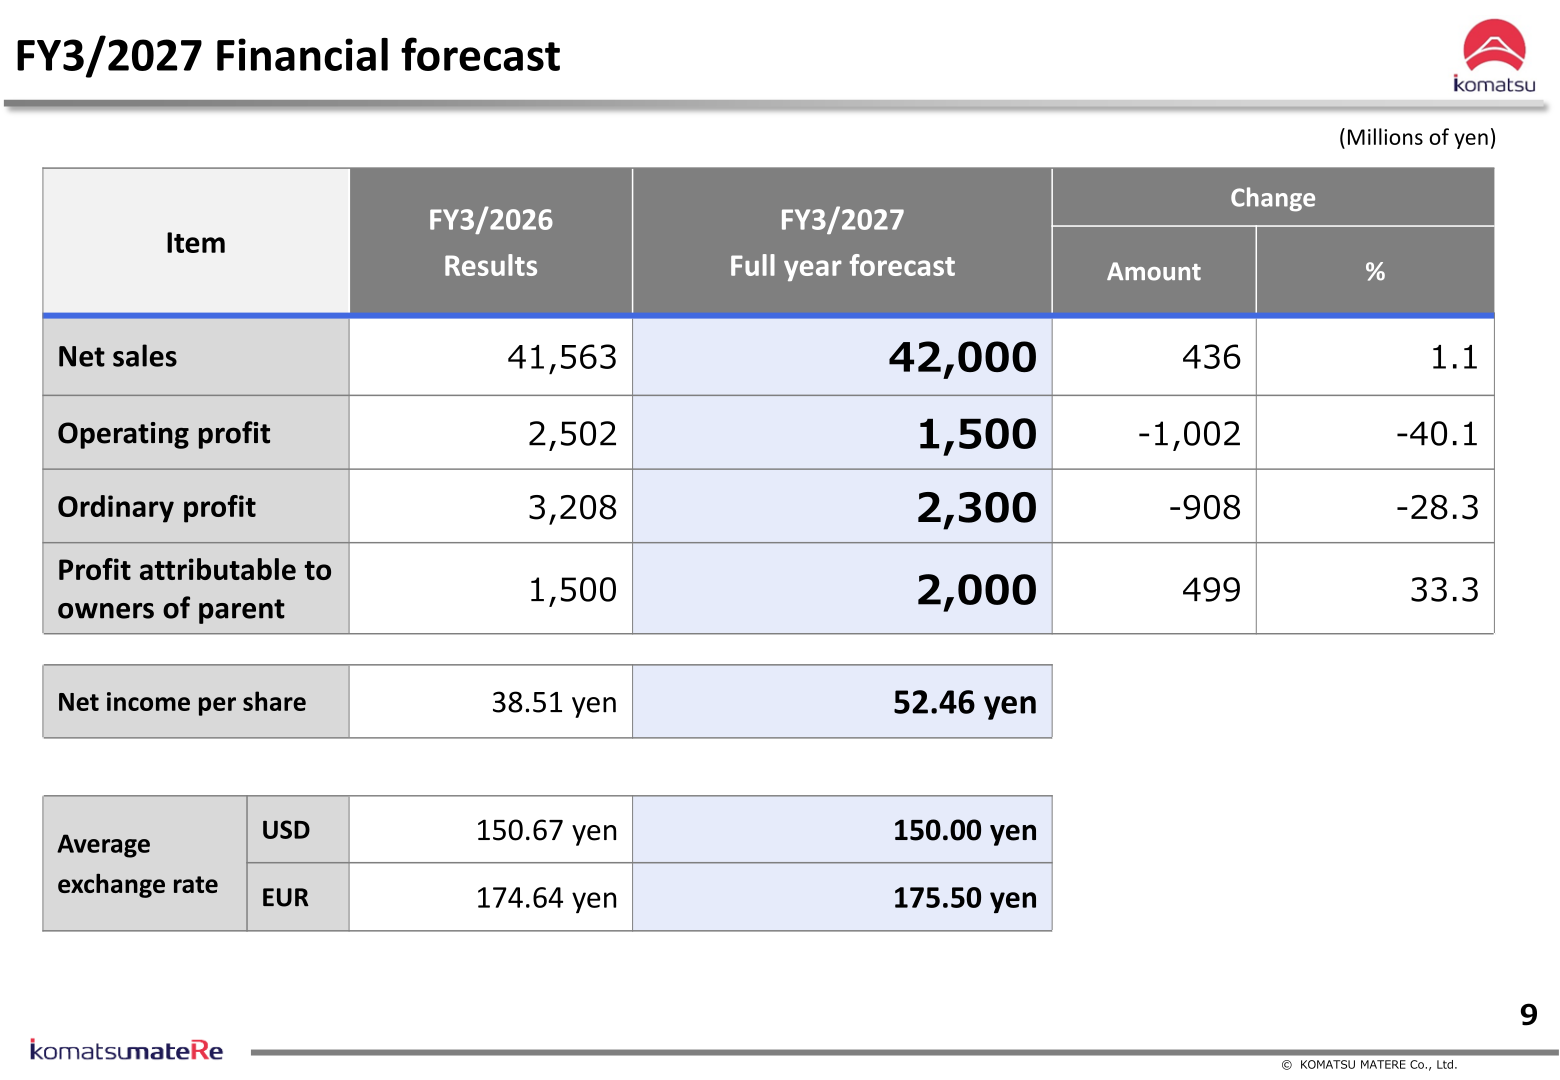
For FY3/2027, the company forecasts net sales of 42,000 million yen (+1.1%), operating profit of 1,500 million yen (-40.1%), ordinary profit of 2,300 million yen (-28.3%) and profit attributable to owners of parent of 2,000 million yen (+33.3%), based on assumed exchange rates of 150.00 yen to the US dollar and 175.50 yen to the euro. In the operating profit bridge, total profit decrease factors of -4,159 million yen include factors related to the situation in the Middle East of -2,050 million yen and restructuring expenses, etc. of -2,052 million yen (including expenses for strengthening the foundation such as introducing high-efficiency equipment, promoting DX, improving manufacturing environments and enhancing welfare benefits), as well as a raw material and fuel price difference of -57 million yen. Total profit increase factors of +3,156 million yen include a sales price difference of +1,623 million yen, total cost reduction of +793 million yen and productivity improvement of +740 million yen, parts of which represent profit improvement measures associated with the heightened tensions in the Middle East.
| Item (Millions of yen) | FY3/2027 Full year forecast | FY3/2026 Results | Change | Change (%) |
|---|---|---|---|---|
| Net sales | 42,000 | 41,563 | 436 | 1.1 |
| Operating profit | 1,500 | 2,502 | -1,002 | -40.1 |
| Ordinary profit | 2,300 | 3,208 | -908 | -28.3 |
| Profit attributable to owners of parent | 2,000 | 1,500 | 499 | 33.3 |
| Net income per share | 52.46 yen | 38.51 yen | ||
| Average exchange rate (USD) | 150.00 yen | 150.67 yen | ||
| Average exchange rate (EUR) | 175.50 yen | 174.64 yen |
Capital expenditures are planned at 4,870 million yen for FY3/2027 (3,200 million yen in FY3/2026), including system-related investment of 2,580 million yen and manufacturing-related investment of 1,570 million yen. Depreciation expenses are forecast at 2,200 million yen (1,580 million yen in FY3/2026).
Shareholder Returns
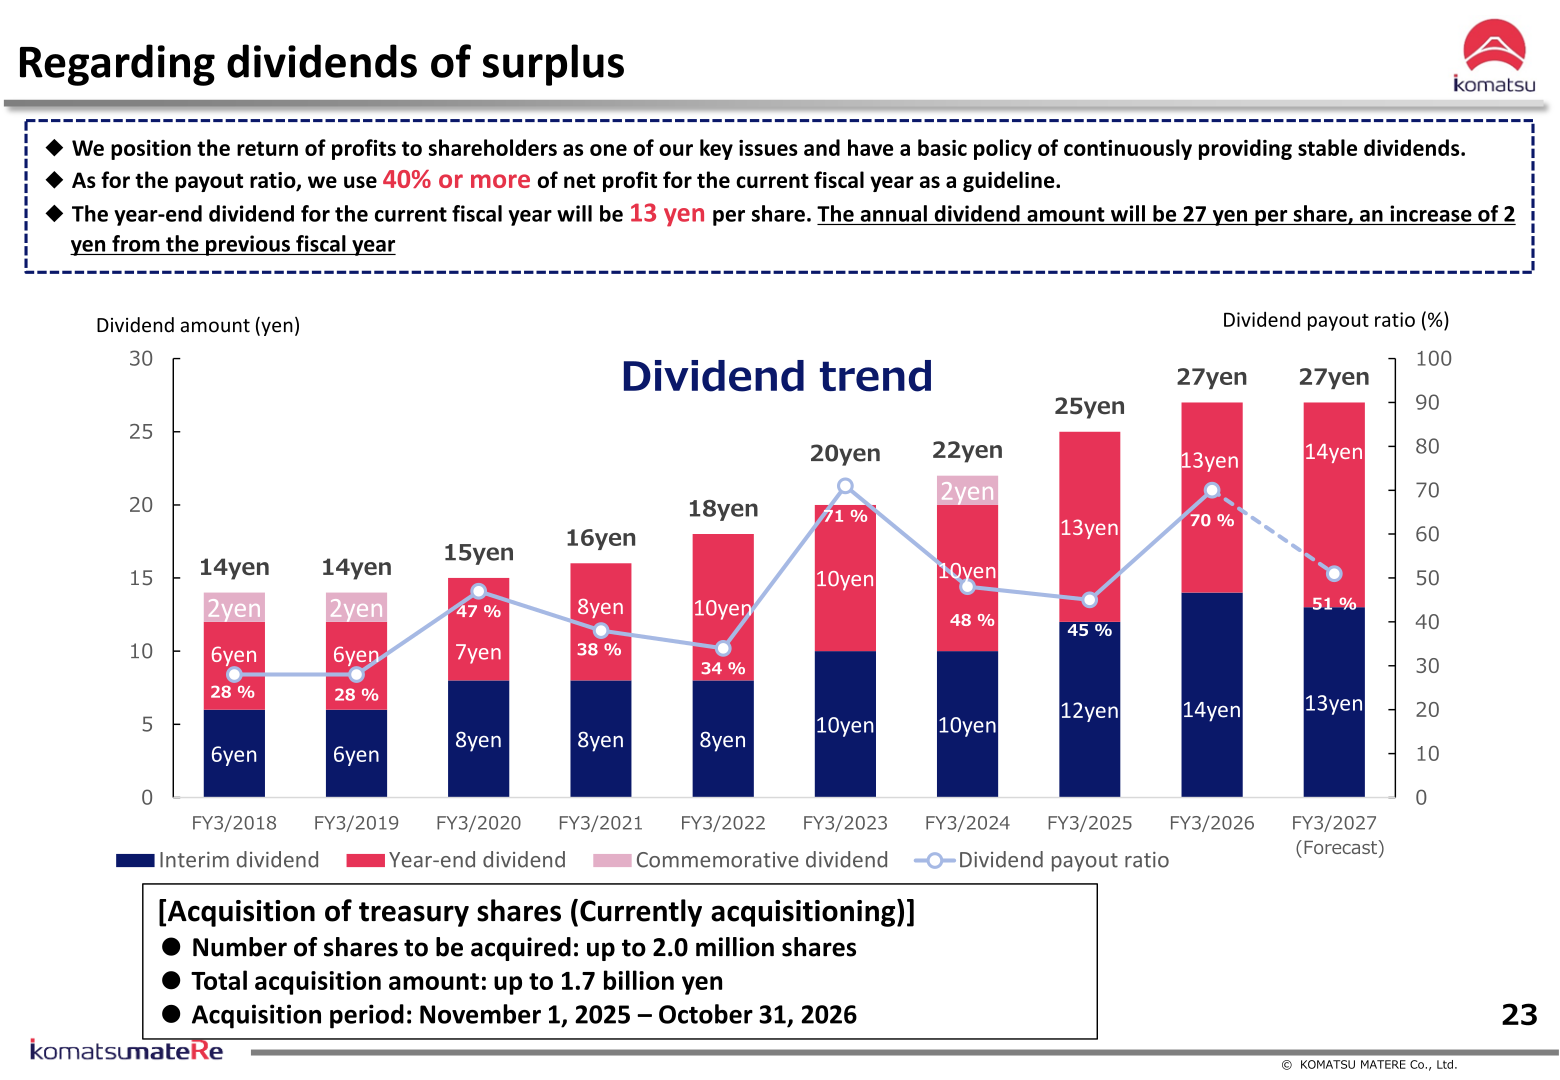
The company positions the return of profits to shareholders as one of its key issues, has a basic policy of continuously providing stable dividends, and uses a payout ratio of 40% or more of net profit for the current fiscal year as a guideline. The FY3/2026 annual dividend was 27 yen per share (interim 14 yen, year-end 13 yen), an increase of 2 yen from the previous fiscal year, for a dividend payout ratio of 70%. For FY3/2027, the company forecasts an annual dividend of 27 yen (interim 13 yen, year-end 14 yen) with a payout ratio of 51%. The company is also acquiring treasury shares of up to 2.0 million shares and up to 1.7 billion yen during the period from November 1, 2025 to October 31, 2026. The total return ratio for FY3/2026 was 155%.
| Dividend per share | FY3/2027 (Forecast) | FY3/2026 | FY3/2025 |
|---|---|---|---|
| Interim dividend | 13 yen | 14 yen | 12 yen |
| Year-end dividend | 14 yen | 13 yen | 13 yen |
| Annual dividend | 27 yen | 27 yen | 25 yen |
| Dividend payout ratio | 51% | 70% | 45% |
Under its reduction of policy shareholdings, the company aims to reduce policy shareholdings by 50% (approximately 4.0 billion yen) over the three years of the medium-term management plan “KFW-2026”. Sales (book value) were 1,462 million yen in the year to March 2026, with 1,300 million yen targeted for the year to March 2027. As of March 2026, the company held shares in 11 listed and 12 unlisted companies.
Medium-Term Management Plan “KFW-2026”
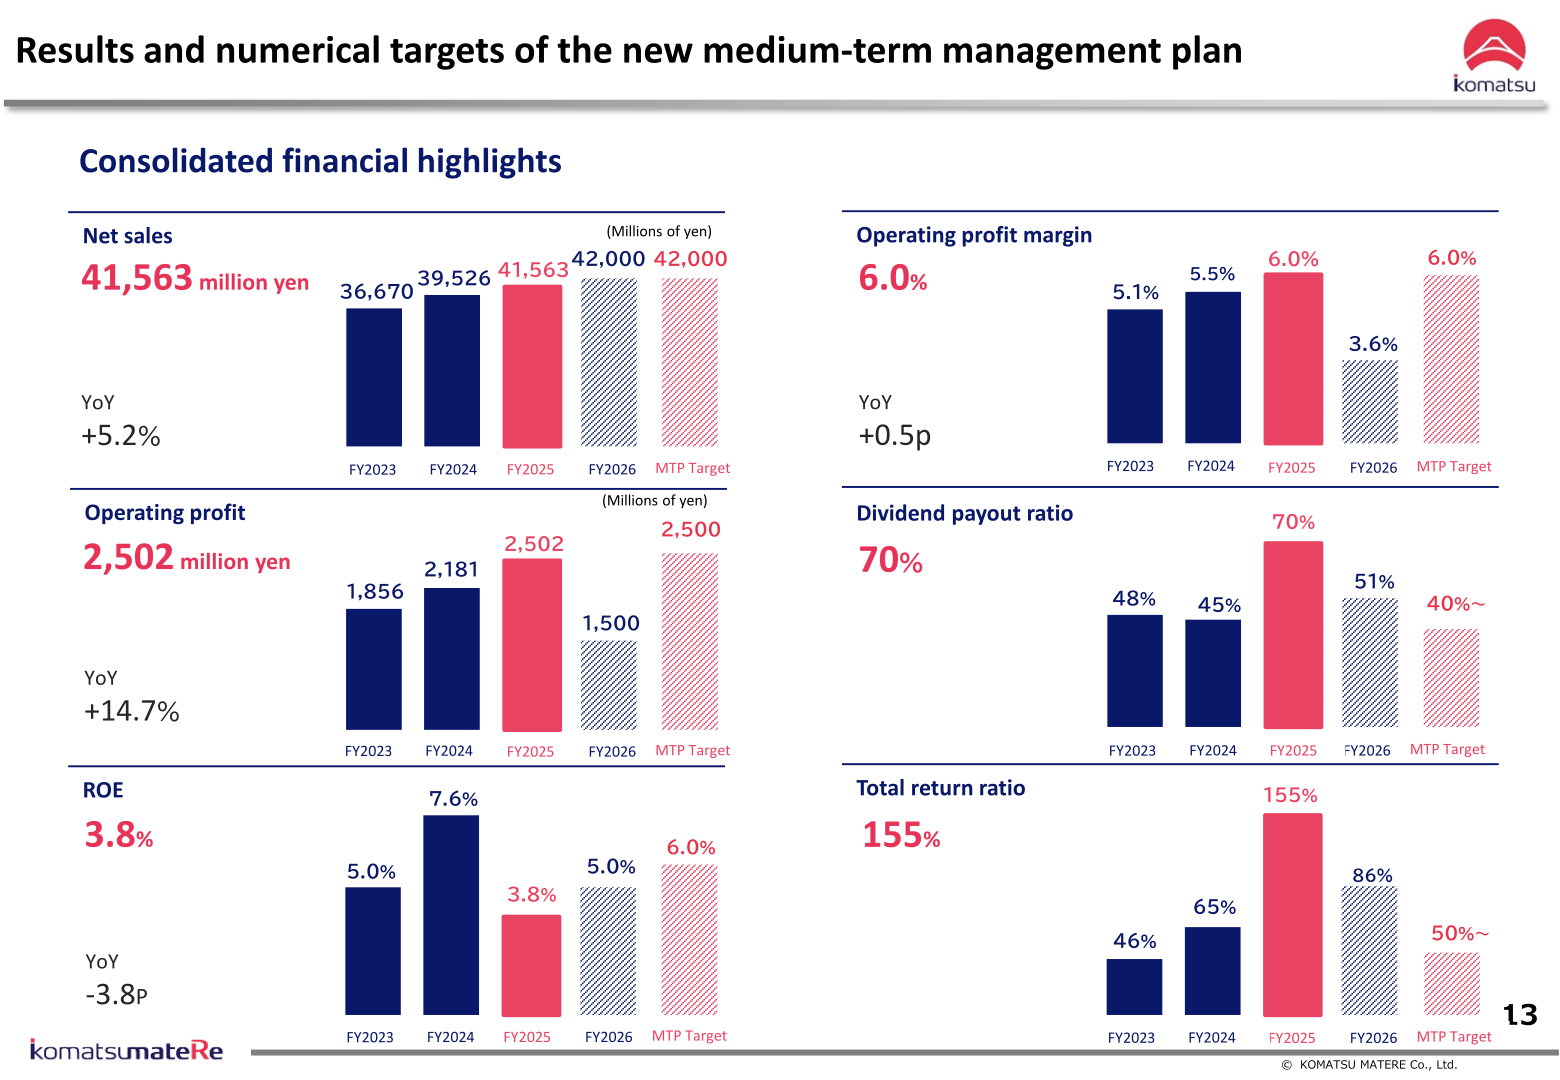
Under the medium-term management plan “KFW-2026” (slogan: “Art in Technology”), the MTP targets are net sales of 42,000 million yen, operating profit of 2,500 million yen, an operating profit margin of 6.0%, ROE of 6.0%, a dividend payout ratio of 40% or more and a total return ratio of 50% or more. In FY2025 (FY3/2026), results were net sales of 41,563 million yen, operating profit of 2,502 million yen, an operating profit margin of 6.0% (+0.5p), ROE of 3.8% (-3.8P), a dividend payout ratio of 70% and a total return ratio of 155%. The plan for FY2026 shows operating profit of 1,500 million yen, an operating profit margin of 3.6% and ROE of 5.0%. Sales of the Product Division reached 2.6 bn yen in FY2025.
Among its initiatives, the company is developing sustainable materials with Spiber Inc. (Brewed Protein™) and Bioworks Corporation (PlaX™), expanding its carbon fiber composite “CABKOMA Strand Rod” as a seismic reinforcement method, and growing adoption of its sludge volume reduction bio-agent “Bellefomer” to 55 cases (YoY +31 cases). It has also launched “factoRe100”, a project to reorganize its domestic manufacturing sites into next-generation factory groups, with scheduled completion in 2043 and a total construction cost of 30 billion yen or more (current outlook).
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















