
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Chikaranomoto Holdings’ fiscal year ends in March. Following this site’s convention, the fiscal year ended March 31, 2026 is classified as FY2025; the company labels it FY2025-26 (FY25 in some charts), and the body text and tables below keep the company’s own labels (FY2024-25 = prior year; FY2026-27 = fiscal year ending March 2027). The International Store Operations segment reports on a January–December basis (Jan–Dec 2025), while Domestic Store Operations and Merchandise cover April 2025–March 2026. Figures are in millions of yen unless otherwise stated.
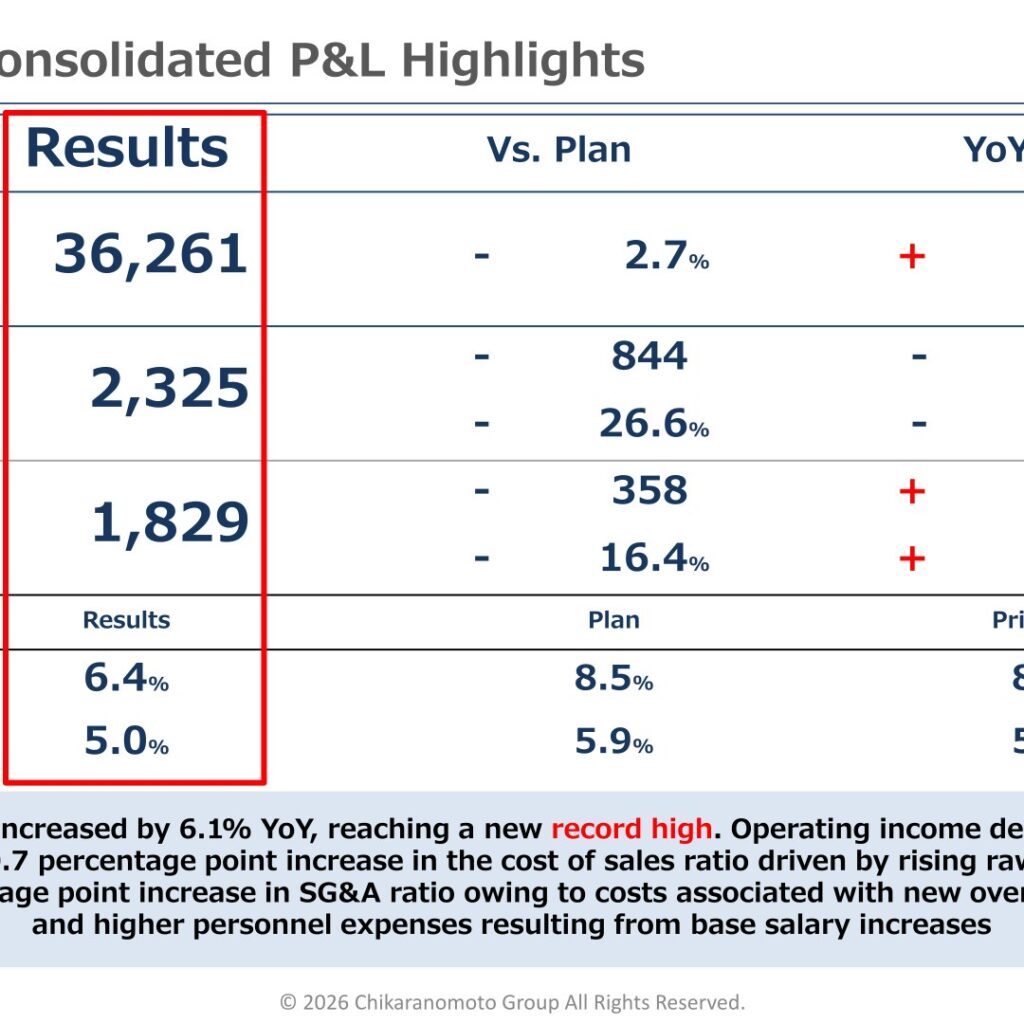
Chikaranomoto Holdings, operator of the IPPUDO ramen chain, reported FY2025-26 consolidated revenue of 36,261 million yen, up 6.1% year on year and a new record high. Operating income fell 17.3% (down 484 million yen) to 2,325 million yen, which the company attributes mainly to a 0.7 percentage point rise in the cost of sales ratio driven by rising raw material prices and a 1.1 percentage point rise in the SG&A ratio owing to new overseas area development costs and higher personnel expenses from base salary increases. Net income rose 4.0% to 1,829 million yen. For FY2026-27 the company plans revenue of 40,125 million yen (+10.7%) and operating income of 2,595 million yen (+11.6%), and it forecasts an annual dividend of 24 yen per share, including a 2-yen special dividend for its 40th anniversary.
Consolidated Results (FY2025-26 Actual)
Revenue of 36,261 million yen was 2.7% below plan but 6.1% above the prior year. Operating income of 2,325 million yen was 844 million yen (26.6%) below plan and 484 million yen (17.3%) below the prior year, and the operating margin was 6.4%, compared with 8.5% in the plan and 8.2% in the prior year. Net income of 1,829 million yen was 358 million yen (16.4%) below plan but 71 million yen (4.0%) above the prior year, for a net income ratio of 5.0%.
In its KPI review, the company says steady performance at domestic same-store locations and contributions from 17 new domestic stores drove record-high sales, while inflation in overseas operations, higher raw material costs, base salary increases and new area development expenses pushed the operating margin down by 1.8 points; it expects improvement in the next fiscal year through pricing initiatives and cost optimization. ROE was 16.1%. At the end of March 2026, total assets were 20,071 million yen (18,541 million yen a year earlier), total net assets 12,112 million yen (10,661 million yen) and cash and deposits 7,588 million yen (7,150 million yen), and the equity ratio rose to 60.3% from 57.5%.
| Item (Million Yen) | FY2025-26 Results | Vs. Plan | YoY | FY2024-25 |
|---|---|---|---|---|
| Revenue | 36,261 | -2.7% | +6.1% | 34,166 |
| Operating income | 2,325 | -844 (-26.6%) | -484 (-17.3%) | 2,809 |
| Net income | 1,829 | -358 (-16.4%) | +71 (+4.0%) | — |
| Operating margin | 6.4% | Plan: 8.5% | — | 8.2% |
| Net income ratio | 5.0% | Plan: 5.9% | — | 5.1% |
Segment Results
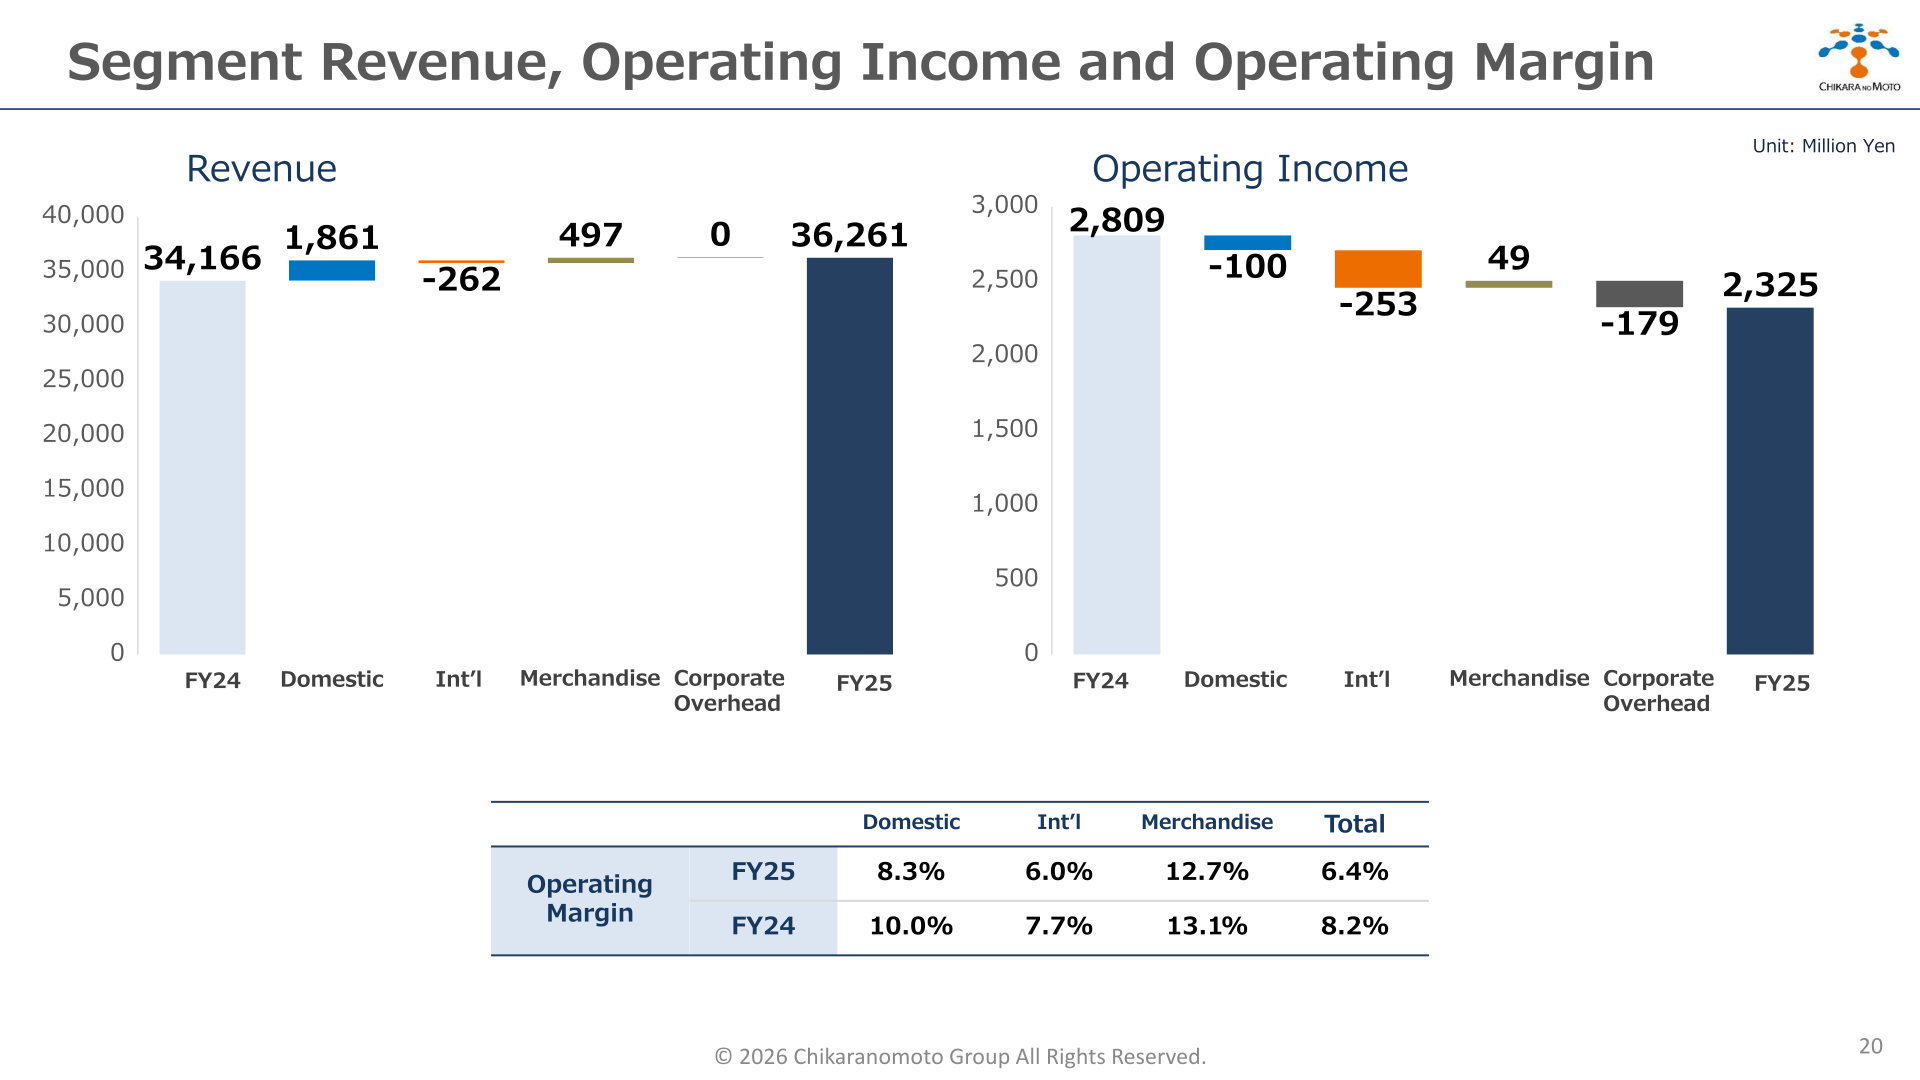
Domestic Store Operations (Apr 2025–Mar 2026): Revenue rose 12.0% to a record 17,417 million yen (1.3% above plan). The company notes it has not raised prices since October 2023, so performance was supported by the increase in store count: 21 stores were opened, including 8 acquired through M&A, and 4 were closed, a net increase of 17 stores. Existing-store sales were 100.6% of the prior year for FY2025 (customer count 99.6%, average check 101.0%), and the inbound customer ratio averaged 19.3%, although inbound demand from China has slowed since February 2026. Operating income fell 6.5% (100 million yen) to 1,447 million yen, with the cost of sales ratio up 0.6 points on rising raw material costs alongside continued investment in human capital such as base salary increases; the operating margin was 8.3% (10.0% in the prior year).
International Store Operations (Jan–Dec 2025): Revenue declined 1.8% to 14,427 million yen (6.8% below plan), mainly due to a slowdown in global economic growth, an uncertain operating environment and delays in new store openings; the foreign exchange impact was negative 0.2% YoY. The segment opened 18 stores and closed 14, a net increase of 4, as it restructured unprofitable stores and opened new halal-format locations. Existing-store sales were 93.8% of the prior year (customer count 92.2%, average check 101.8%). Operating income fell 22.6% (254 million yen) to 870 million yen, which the company attributes mainly to upfront costs of new area development and delays in opening large-scale stores in Spain and New York, together with higher fixed cost ratios; the operating margin was 6.0% (7.7% in the prior year).
Merchandise (Apr 2025–Mar 2026): Revenue rose 12.7% to a record 4,416 million yen, driven by strong e-commerce sales and IPPUDO-related products, and operating income rose 9.6% to a record 562 million yen. The operating margin declined slightly to 12.7% (13.1% in the prior year) due to lower gross margins on certain collaboration products. Corporate overhead was 555 million yen, and the corporate overhead SG&A ratio was maintained at a low 1.5% of consolidated revenue.
The group had 317 stores in 16 countries and regions (21 more than at the end of the previous fiscal year), following its expansion into Spain: 173 domestic stores (146 owned, 27 licensed; as of March 31, 2026) and 144 international stores (75 owned, 69 licensed; as of December 31, 2025).
| Segment (Million Yen) | Metric | FY2025-26 | FY2024-25 | YoY |
|---|---|---|---|---|
| Domestic Store Operations | Revenue | 17,417 | 15,556 | +12.0% |
| Domestic Store Operations | Operating income | 1,447 | 1,547 | -6.5% |
| Domestic Store Operations | Operating margin | 8.3% | 10.0% | — |
| International Store Operations | Revenue | 14,427 | 14,690 | -1.8% |
| International Store Operations | Operating income | 870 | 1,124 | -22.6% |
| International Store Operations | Operating margin | 6.0% | 7.7% | — |
| Merchandise | Revenue | 4,416 | 3,919 | +12.7% |
| Merchandise | Operating income | 562 | 513 | +9.6% |
| Merchandise | Operating margin | 12.7% | 13.1% | — |
| Corporate overhead | Operating income | -555 | -375 | — |
| Consolidated | Operating income | 2,325 | 2,809 | -17.3% |
FY2026-27 Financial Plan
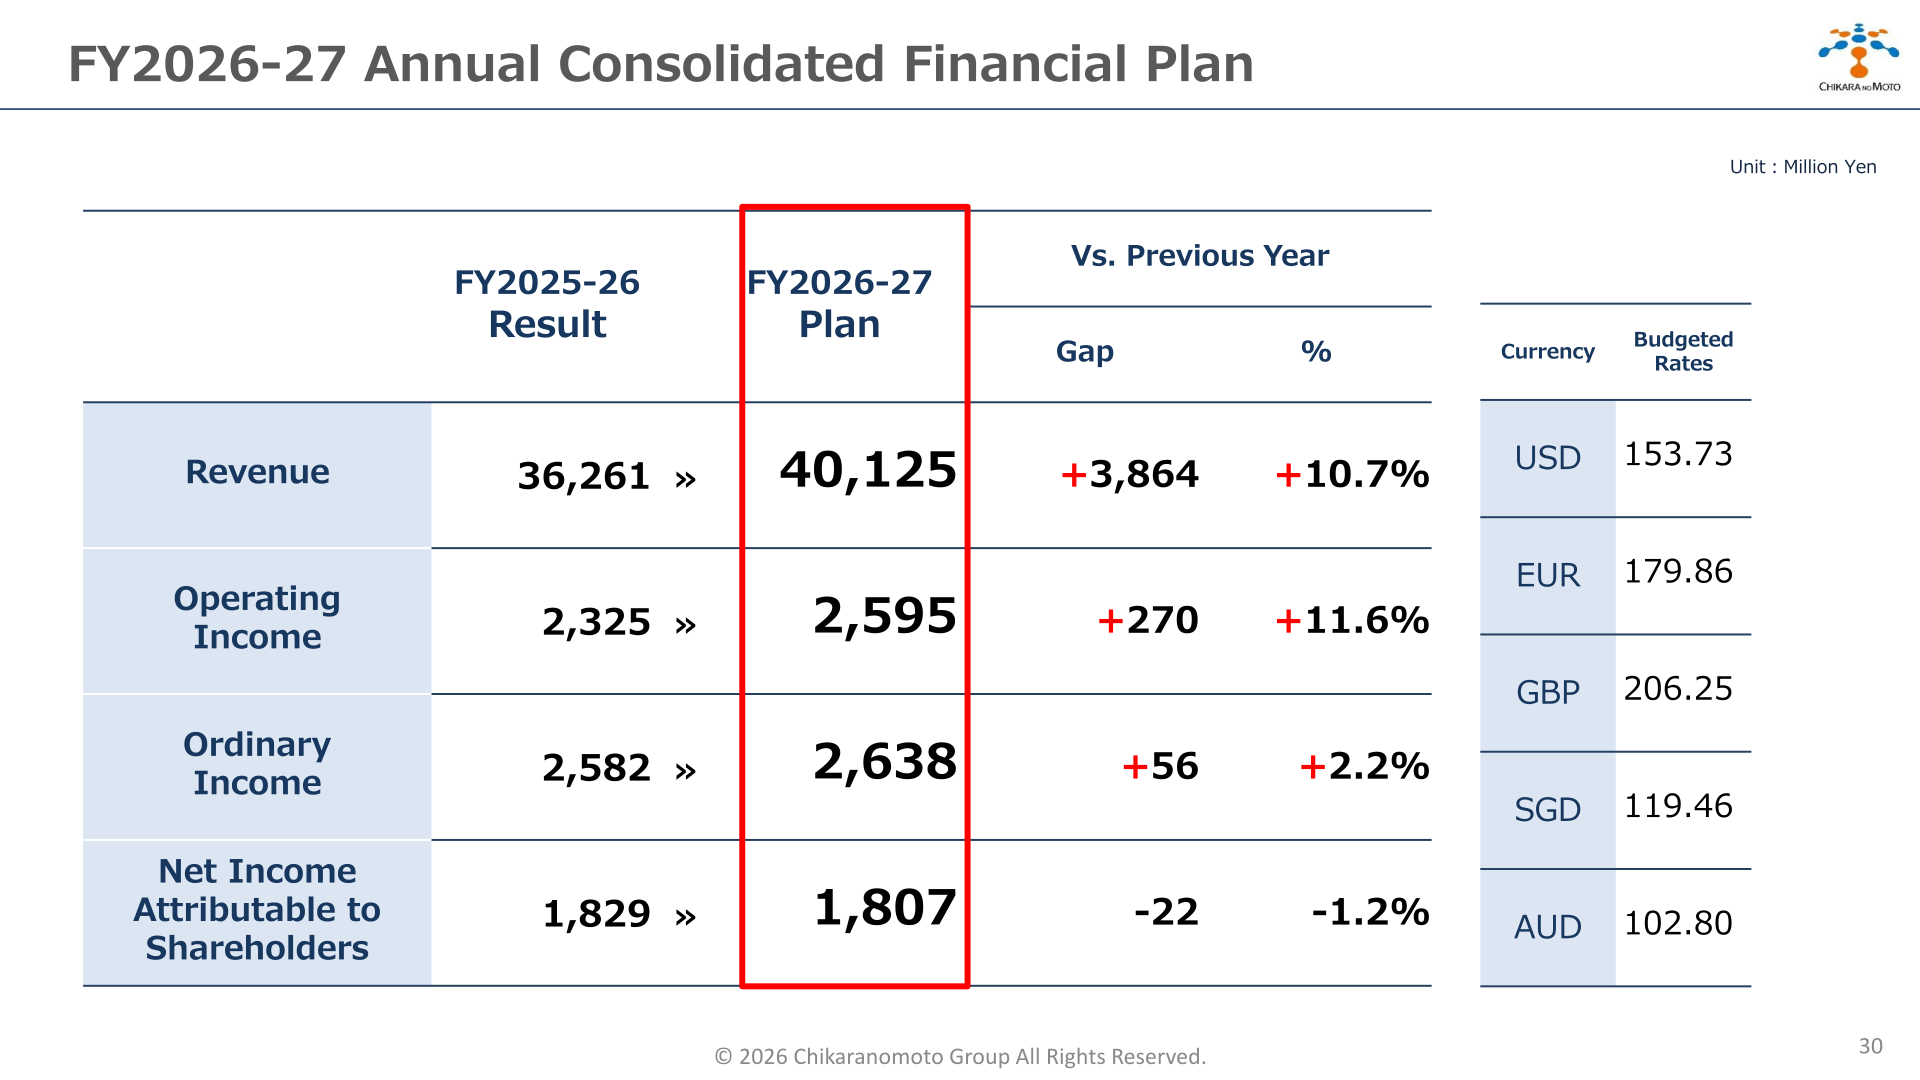
For FY2026-27, the company plans revenue of 40,125 million yen (+3,864 million yen, +10.7%), operating income of 2,595 million yen (+270 million yen, +11.6%), ordinary income of 2,638 million yen (+2.2%) and net income attributable to shareholders of 1,807 million yen (-1.2%). Budgeted exchange rates are USD 153.73, EUR 179.86, GBP 206.25, SGD 119.46 and AUD 102.80 yen.
By segment, Domestic expects existing stores to grow 100.7% YoY, plans to open 15 to 20 stores per year and to invest actively in production efficiency and store profitability, and expects continued cost control and higher average spending from inbound tourism to lift profits. International expects existing-store sales in key regions, which account for approximately 80% of total sales, to reach 100.4% YoY on a local currency basis, and plans to open 16 stores while closing unprofitable ones for a net increase of 3; despite anticipated cost increases, it expects profit growth from the opening of previously delayed stores, market expansion through new strategic approaches and DX initiatives. Merchandise plans collaborations with major convenience stores, expanded sales at large retailers, stronger exports and products for health-conscious consumers.
| Item (Million Yen) | FY2026-27 Plan | FY2025-26 Result | YoY |
|---|---|---|---|
| Revenue | 40,125 | 36,261 | +10.7% |
| Operating income | 2,595 | 2,325 | +11.6% |
| Ordinary income | 2,638 | 2,582 | +2.2% |
| Net income attributable to shareholders | 1,807 | 1,829 | -1.2% |
| Domestic revenue | 19,333 | 17,417 | +11.0% |
| International revenue | 15,517 | 14,427 | +7.5% |
| Merchandise revenue | 5,276 | 4,416 | +19.5% |
| Domestic operating income | 1,613 | 1,447 | +11.4% |
| International operating income | 878 | 870 | +0.9% |
| Merchandise operating income | 725 | 562 | +29.0% |
| Corporate overhead | -621 | -555 | — |
Shareholder Returns
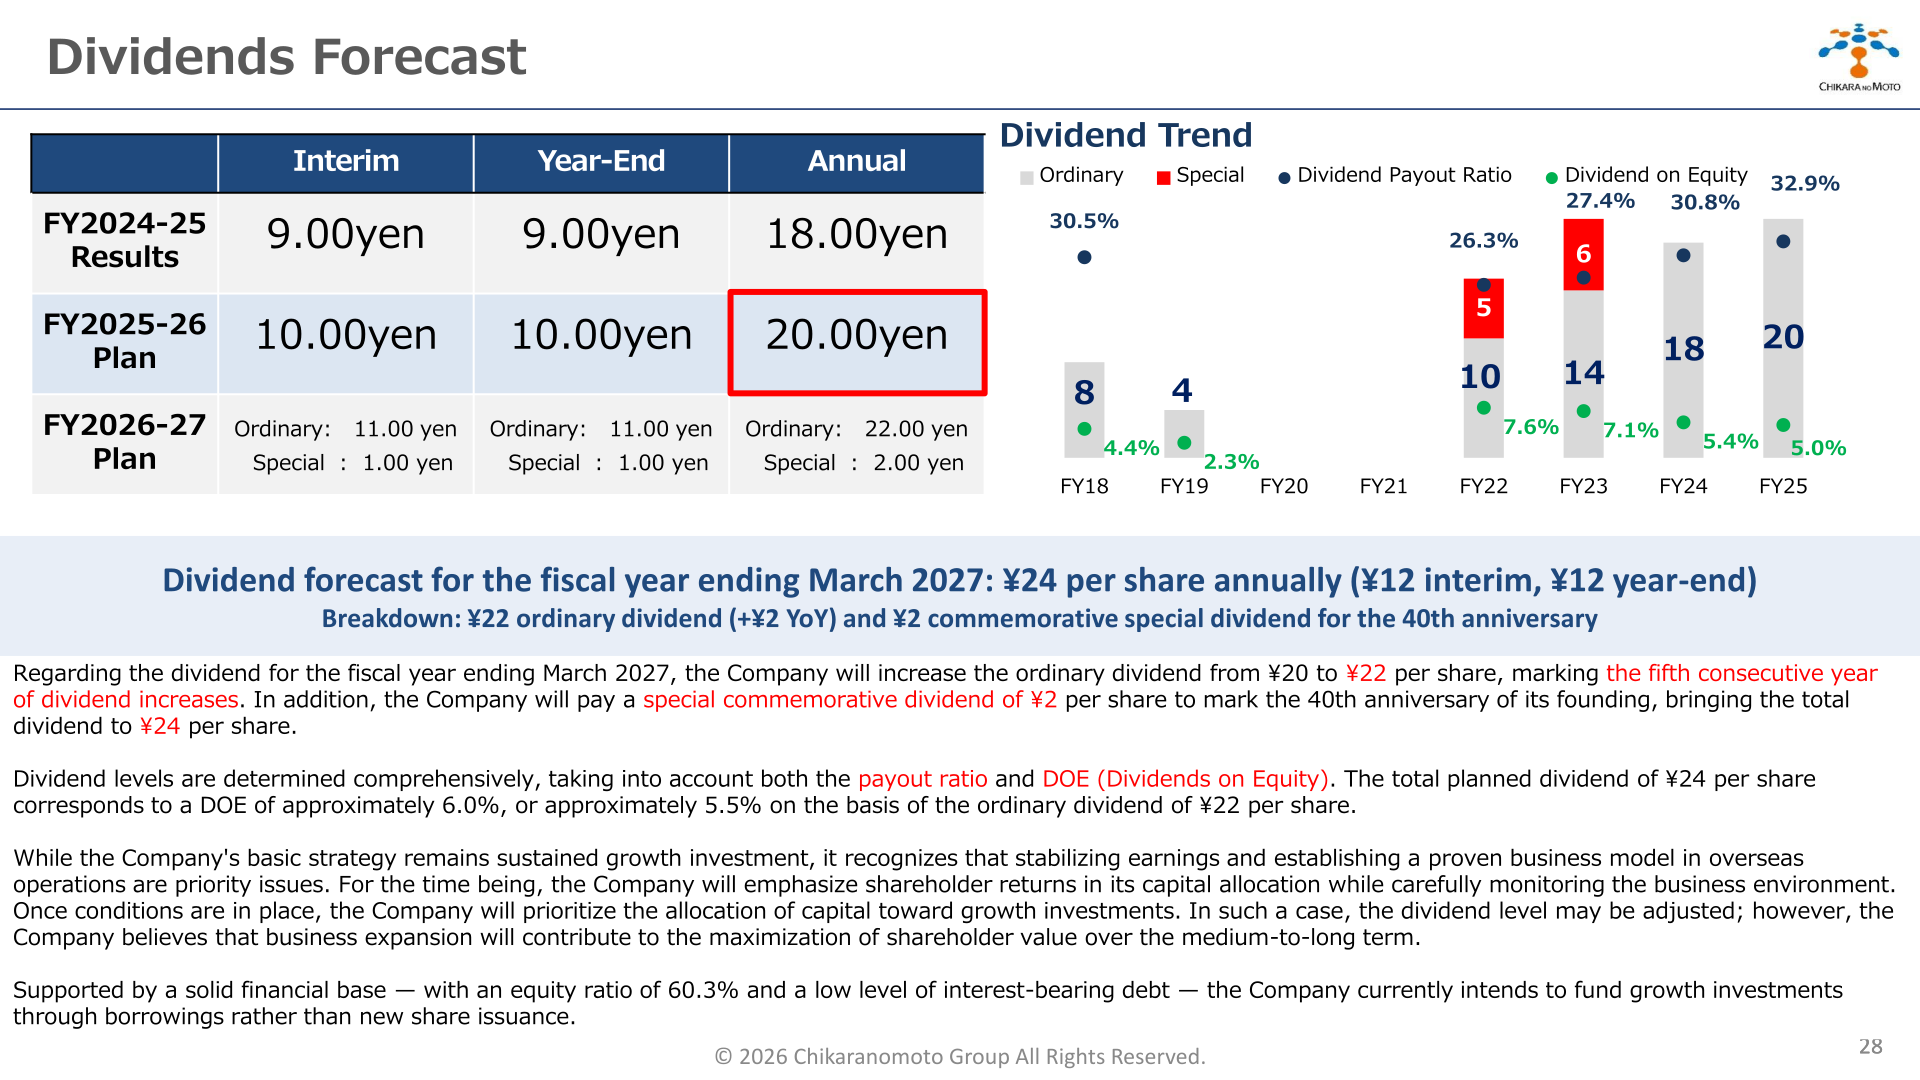
The FY2025-26 dividend was 20.00 yen per share (10.00 yen interim and 10.00 yen year-end), up 2 yen from 18.00 yen in FY2024-25 and paid as planned, for a payout ratio of 32.9%. Over the medium term the company intends to continue stable shareholder returns with a target payout ratio of 20% or higher.
For the fiscal year ending March 2027, the company will raise the ordinary dividend from 20 yen to 22 yen per share, marking the fifth consecutive year of dividend increases, and will pay a special commemorative dividend of 2 yen per share for the 40th anniversary of its founding, bringing the total to 24 yen per share (12 yen interim, 12 yen year-end). The company says the planned 24 yen corresponds to a DOE of approximately 6.0% (approximately 5.5% on the basis of the 22-yen ordinary dividend). While its basic strategy remains sustained growth investment, it will for the time being emphasize shareholder returns in its capital allocation, and with an equity ratio of 60.3% and low interest-bearing debt it currently intends to fund growth investments through borrowings rather than new share issuance.
| Dividend per share | Interim | Year-End | Annual |
|---|---|---|---|
| FY2024-25 Results | 9.00 yen | 9.00 yen | 18.00 yen |
| FY2025-26 Plan | 10.00 yen | 10.00 yen | 20.00 yen |
| FY2026-27 Plan | Ordinary 11.00 yen / Special 1.00 yen | Ordinary 11.00 yen / Special 1.00 yen | Ordinary 22.00 yen / Special 2.00 yen |
FY2027-28 Vision
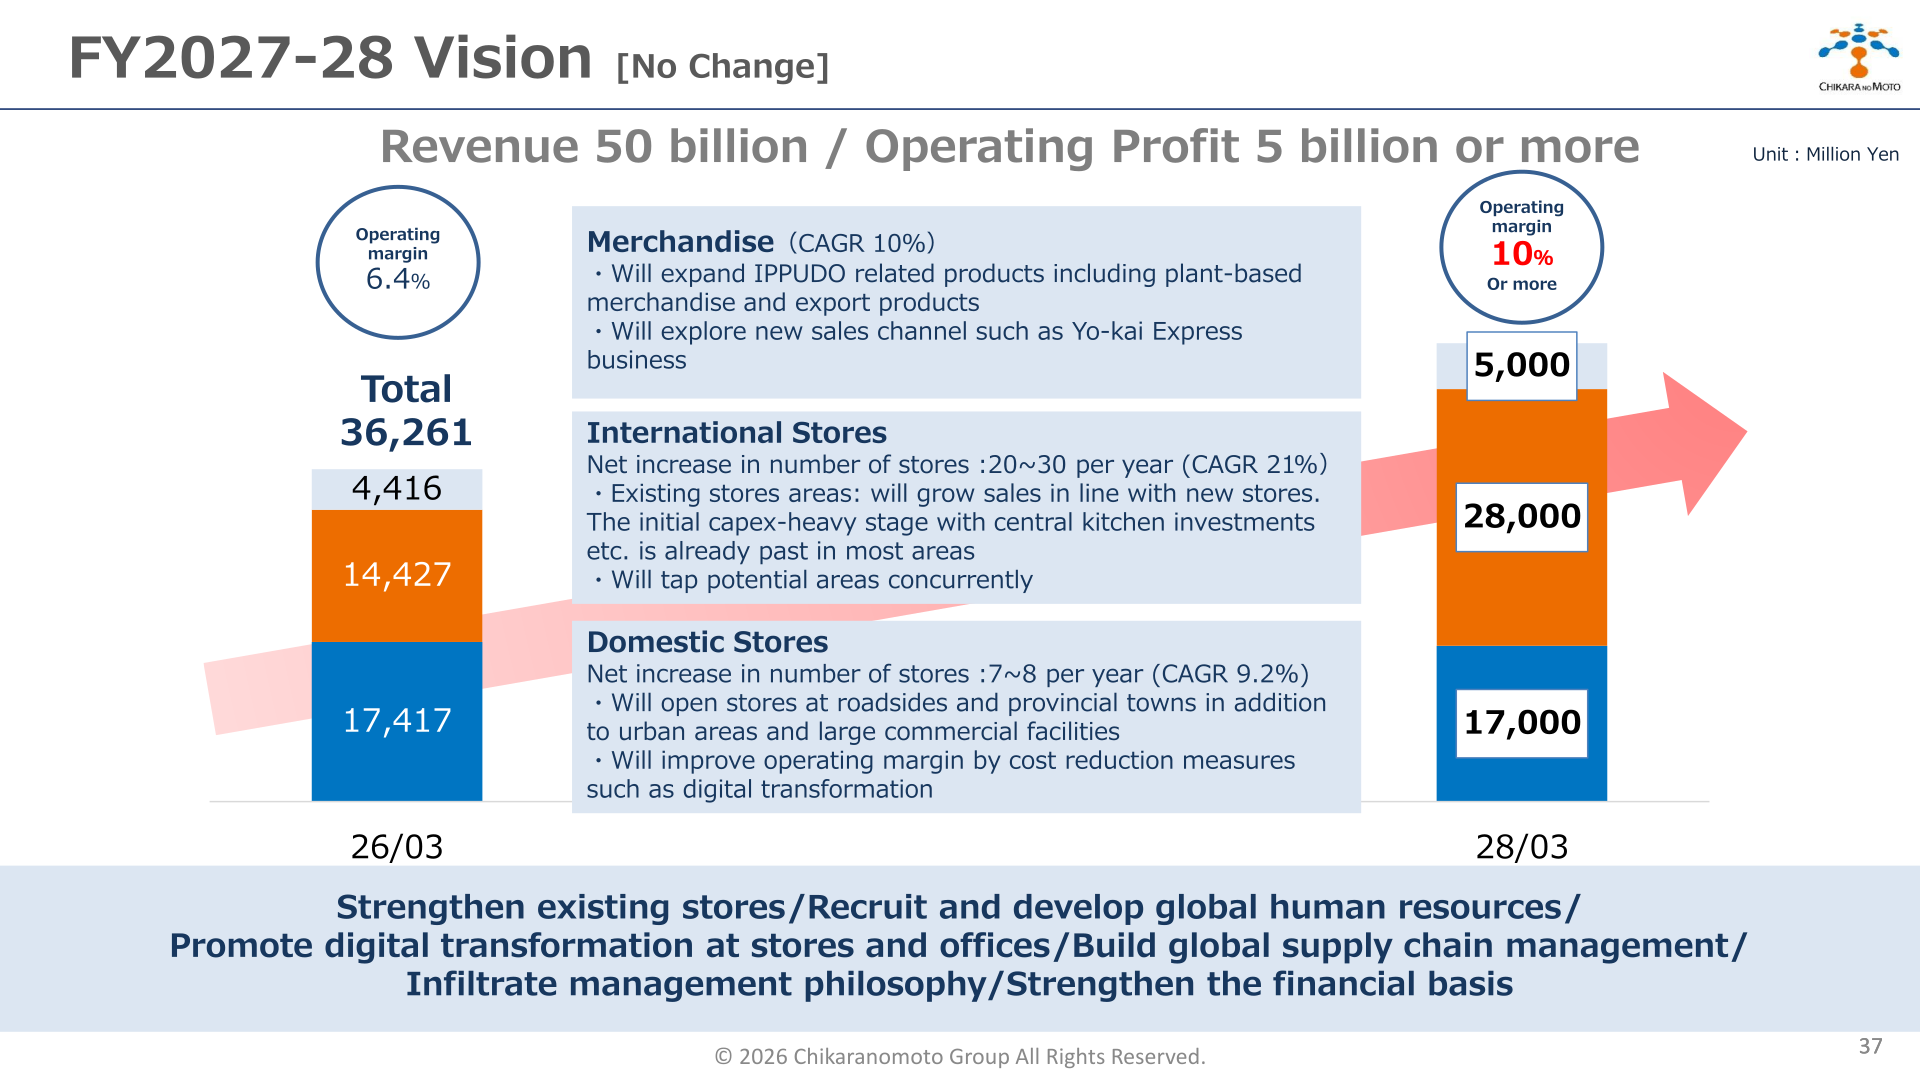
The company left its FY2027-28 Vision unchanged: revenue of 50 billion yen and operating profit of 5 billion yen or more, with an operating margin of 10% or more (6.4% in FY2025-26). The slide shows revenue targets for 28/03 (versus 26/03 actuals of 17,417, 14,427 and 4,416 million yen, respectively) of 17,000 million yen for Domestic Stores, 28,000 million yen for International Stores and 5,000 million yen for Merchandise. Domestic aims for a net increase of 7 to 8 stores per year (CAGR 9.2%), including roadside and provincial locations, and margin improvement through digital transformation; International aims for a net increase of 20 to 30 stores per year (CAGR 21%); and Merchandise targets a 10% CAGR through IPPUDO-related products, including plant-based and export items, and new channels such as the Yo-kai Express business. Group-wide priorities include strengthening existing stores, recruiting and developing global talent, digital transformation, global supply chain management and strengthening the financial base.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















