
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: KAGA ELECTRONICS CO., LTD.’s presentation labels the fiscal year ended March 31, 2026, as “FY2026/3” and the prior fiscal year as “FY2025/3.” This article follows japan-equity.com’s convention of referring to the most recently completed fiscal year as FY2025; tables and figures below retain the source presentation’s original “FY2025/3″/”FY2026/3” labels.
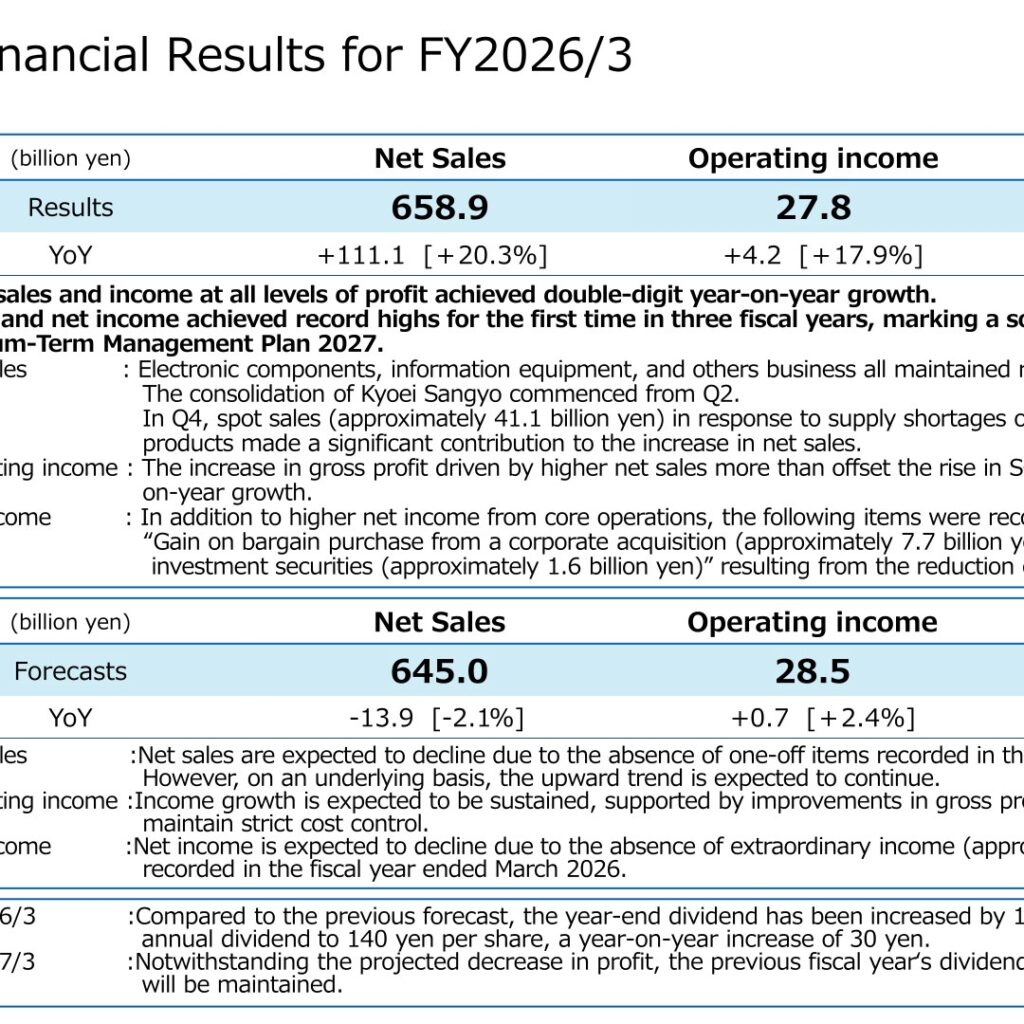
KAGA ELECTRONICS CO., LTD. reported consolidated net sales of ¥658,941 million for the fiscal year ended March 2026 (FY2026/3), up 20.3% year on year, with operating income rising 17.9% to ¥27,824 million and profit attributable to owners of parent up 82.0% to ¥31,099 million. Both net sales and net income reached record highs for the first time in three fiscal years, marking a solid start to the company’s Medium-Term Management Plan 2027. The company said net sales growth reflected robust performance across the electronic components, information equipment, and other businesses, the consolidation of Kyoei Sangyo from the second quarter, and approximately ¥41.1 billion of Q4 spot sales in response to supply shortages of certain semiconductor products. Operating income increased as higher gross profit from the sales growth more than offset a rise in SG&A expenses, while net income also benefited from extraordinary income of approximately ¥7.7 billion in gain on bargain purchase from a corporate acquisition and approximately ¥1.6 billion in gain on sale of investment securities from the reduction of cross-shareholdings.
Consolidated Results (Full-Year Actual)
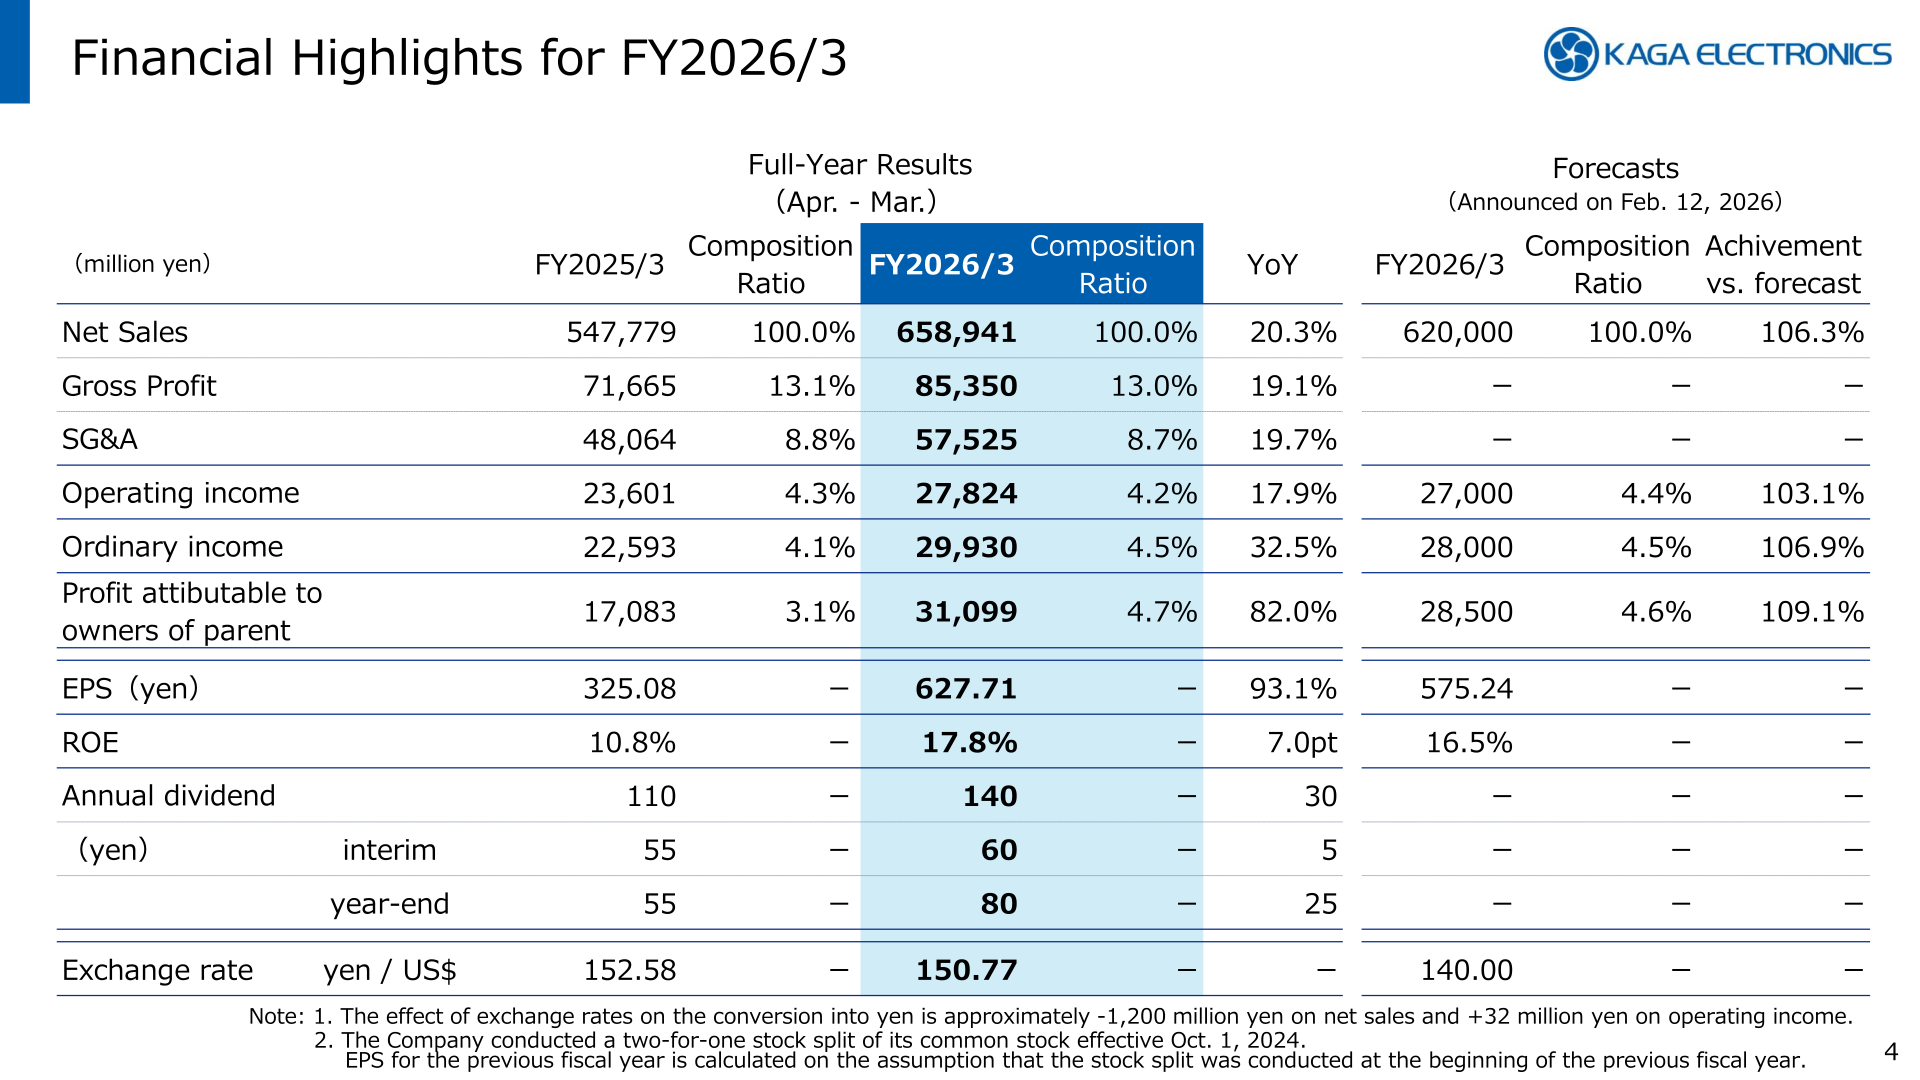
Gross profit margin was roughly flat at 13.0% (13.1% in FY2025/3), while ordinary income rose 32.5% to ¥29,930 million. EPS rose 93.1% to ¥627.71, and ROE improved 7.0 percentage points to 17.8%. Full-year results exceeded the company’s previous forecast (announced February 12, 2026) on every line: net sales reached 106.3% of the ¥620,000 million forecast, operating income 103.1% of ¥27,000 million, ordinary income 106.9% of ¥28,000 million, and net income 109.1% of ¥28,500 million.
| Item | FY2025/3 (Actual) | FY2026/3 (Actual) | YoY |
|---|---|---|---|
| Net sales (million yen) | 547,779 | 658,941 | +20.3% |
| Gross profit (million yen) | 71,665 | 85,350 | +19.1% |
| SG&A expenses (million yen) | 48,064 | 57,525 | +19.7% |
| Operating income (million yen) | 23,601 | 27,824 | +17.9% |
| Ordinary income (million yen) | 22,593 | 29,930 | +32.5% |
| Profit attributable to owners of parent (million yen) | 17,083 | 31,099 | +82.0% |
| EPS (yen) | 325.08 | 627.71 | +93.1% |
| ROE | 10.8% | 17.8% | +7.0pt |
| Annual dividend per share (yen) | 110 | 140 | +30 |
Segment Results
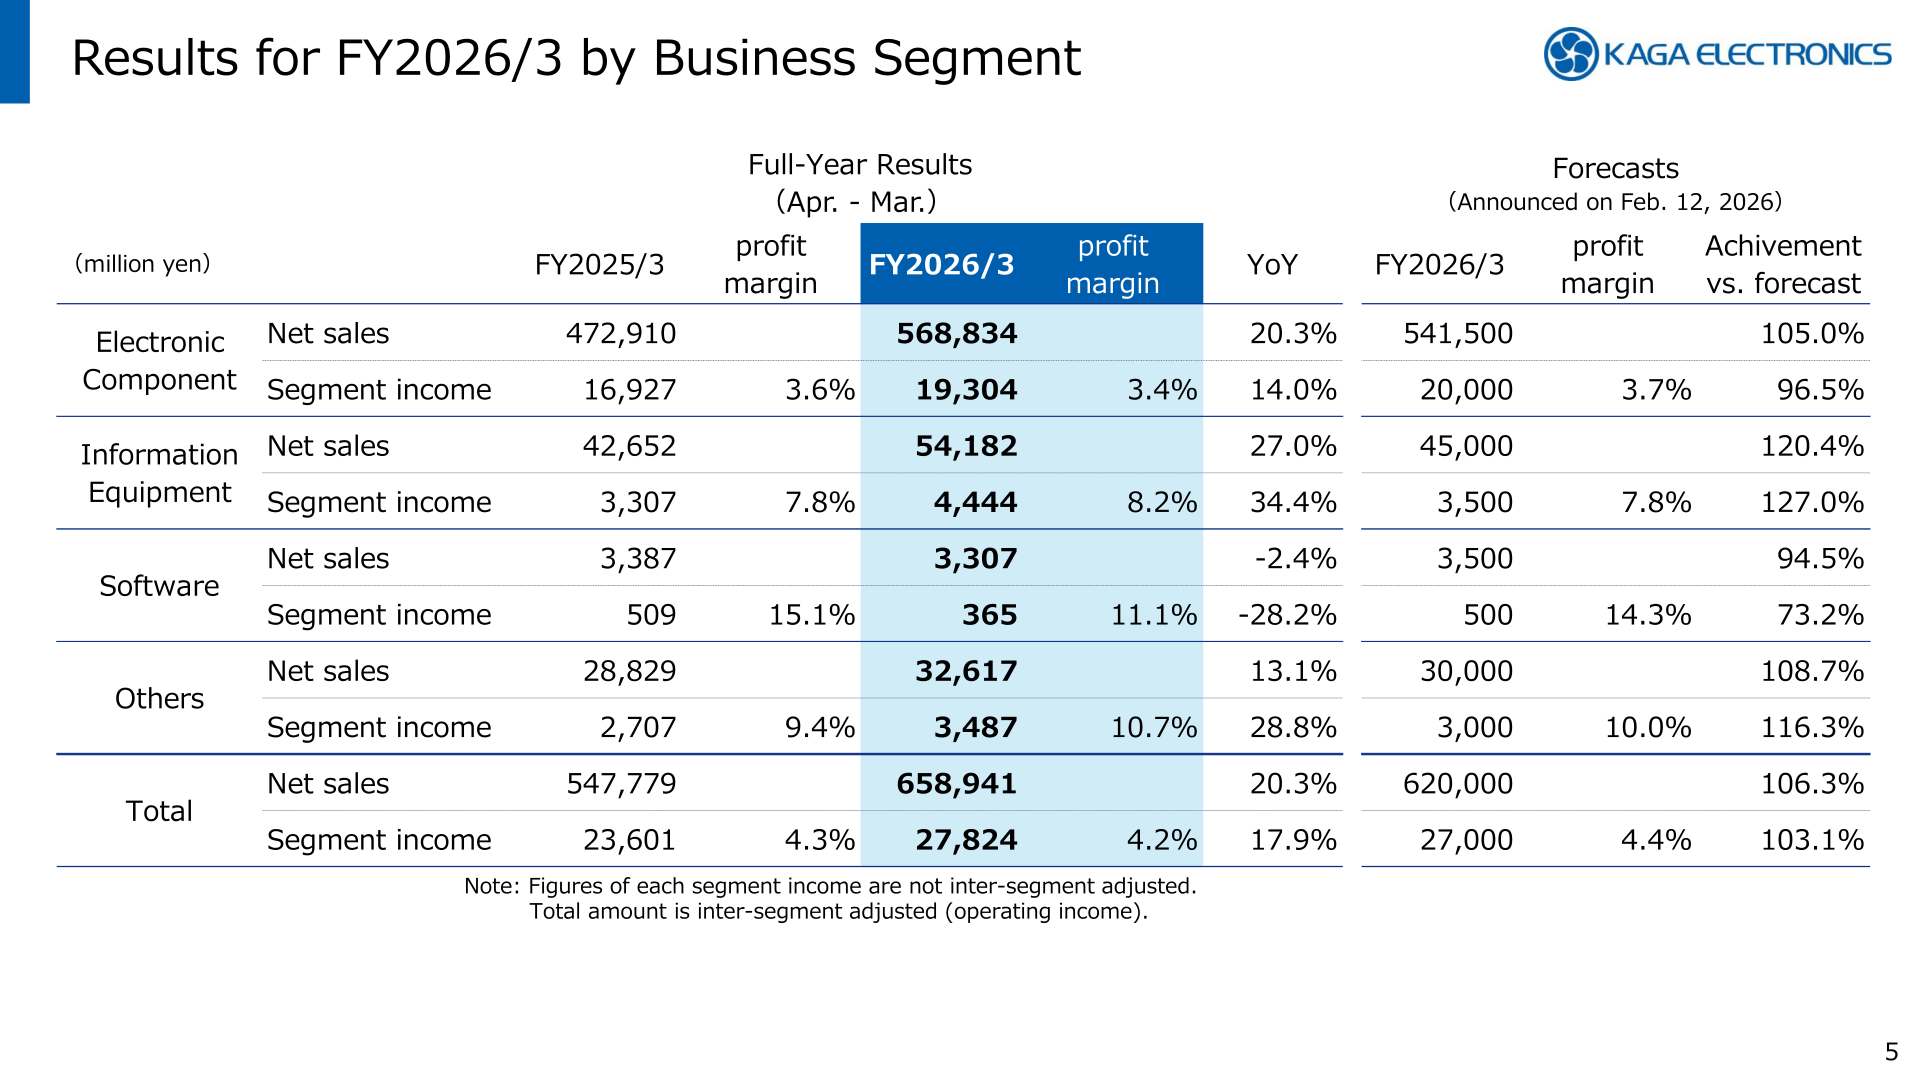
All four business segments increased net sales year on year. The Electronic Component segment, the company’s core business, grew net sales 20.3% to ¥568,834 million, with segment income up 14.0% to ¥19,304 million; the company attributed the increase to easing inventory adjustments in the supply chain, the consolidation of Kyoei Sangyo from the second quarter, and spot sales of commodity memory products amid tight supply-demand conditions. The Information Equipment segment posted the fastest growth, with net sales up 27.0% to ¥54,182 million and segment income up 34.4% to ¥4,444 million, supported by robust PC sales to educational institutions and mass retailers (including AI PCs) and strong LED installation work for convenience stores and financial institutions. The Software segment was the only segment to decline, with net sales down 2.4% to ¥3,307 million and segment income down 28.2% to ¥365 million. The Others segment grew net sales 13.1% to ¥32,617 million and segment income 28.8% to ¥3,487 million.
| Segment | Metric | FY2025/3 (Actual) | FY2026/3 (Actual) | YoY |
|---|---|---|---|---|
| Electronic Component | Net sales (million yen) | 472,910 | 568,834 | +20.3% |
| Electronic Component | Segment income (million yen) | 16,927 | 19,304 | +14.0% |
| Information Equipment | Net sales (million yen) | 42,652 | 54,182 | +27.0% |
| Information Equipment | Segment income (million yen) | 3,307 | 4,444 | +34.4% |
| Software | Net sales (million yen) | 3,387 | 3,307 | -2.4% |
| Software | Segment income (million yen) | 509 | 365 | -28.2% |
| Others | Net sales (million yen) | 28,829 | 32,617 | +13.1% |
| Others | Segment income (million yen) | 2,707 | 3,487 | +28.8% |
| Total | Net sales (million yen) | 547,779 | 658,941 | +20.3% |
| Total | Segment income (million yen) | 23,601 | 27,824 | +17.9% |
FY2027/3 Forecast
For the fiscal year ending March 2027, KAGA ELECTRONICS forecasts consolidated net sales of ¥645,000 million, down 2.1% year on year, as the absence of the spot sales and other one-off items recorded in FY2026/3 is expected to reduce net sales, although the company said the underlying upward trend is expected to continue. Operating income is forecast to rise 2.4% to ¥28,500 million, supported by an improved gross profit margin and continued cost control, while ordinary income is forecast to decline 6.5% to ¥28,000 million. Profit attributable to owners of parent is forecast to fall 35.7% to ¥20,000 million, reflecting the absence of approximately ¥10 billion in extraordinary income recorded in FY2026/3. By segment, the Electronic Component segment is forecast to see net sales decline 3.3% to ¥550,000 million while segment income rises 3.6% to ¥20,000 million; Information Equipment is forecast to grow net sales 6.1% to ¥57,500 million and segment income 12.5% to ¥5,000 million; Software is forecast to grow net sales 5.8% to ¥3,500 million and segment income 36.7% to ¥500 million; and Others is forecast to grow net sales 4.2% to ¥34,000 million while segment income falls 14.0% to ¥3,000 million.
| Item | FY2026/3 (Actual) | FY2027/3 (Forecast) | YoY |
|---|---|---|---|
| Net sales (million yen) | 658,941 | 645,000 | -2.1% |
| Operating income (million yen) | 27,824 | 28,500 | +2.4% |
| Ordinary income (million yen) | 29,930 | 28,000 | -6.5% |
| Profit attributable to owners of parent (million yen) | 31,099 | 20,000 | -35.7% |
| EPS (yen) | 627.71 | 419.65 | -208.06 |
| ROE | 17.8% | 10.5% | -7.3pt |
| Annual dividend per share (yen) | 140 | 140 | — |
Shareholder Returns
KAGA ELECTRONICS increased its year-end dividend by ¥10 from the previous forecast to ¥80 per share, bringing the FY2026/3 annual dividend to ¥140 per share (¥60 interim, ¥80 year-end), up ¥30 year on year. The consolidated dividend payout ratio for FY2026/3 was 22.3% (30.3% excluding the gain on bargain purchase), and DOE (consolidated dividend on equity ratio) was 4.5% (4.6% excluding the gain on bargain purchase). For FY2027/3, the company plans to maintain the ¥140 per share annual dividend despite the forecast decline in profit. Under its shareholder return policy announced November 6, 2024, the company raised its consolidated dividend payout ratio guideline to 30%-40% (from 25%-35% previously) and introduced a new DOE guideline of 4%, while flexibly implementing extraordinary dividends and share buybacks in line with profit levels and capital efficiency. On August 8, 2025, the company repurchased all of its shares held by its four primary banks — which had indicated an intention to sell the shares to reduce strategic shareholdings under the corporate governance code — through ToSTNET-3 for a total of ¥14.4 billion, and cancelled all 4,920,000 repurchased shares (9.4% of total issued shares) on August 18, 2025.
| Item | FY2025/3 (Results) | FY2026/3 (Results) | FY2027/3 (Forecast) |
|---|---|---|---|
| Profit attributable to owners of parent (million yen) | 17,083 | 31,099 | 20,000 |
| Dividend per share, full year (yen) | 110.00 | 140.00 | 140.00 |
| of which, extraordinary dividend (yen) | — | 30.00 | — |
| Consolidated dividend payout ratio | 33.8% | 22.3% | 33.4% |
| DOE | 4.2% | 4.5% | 4.2% |
Medium-Term Management Plan / Topics
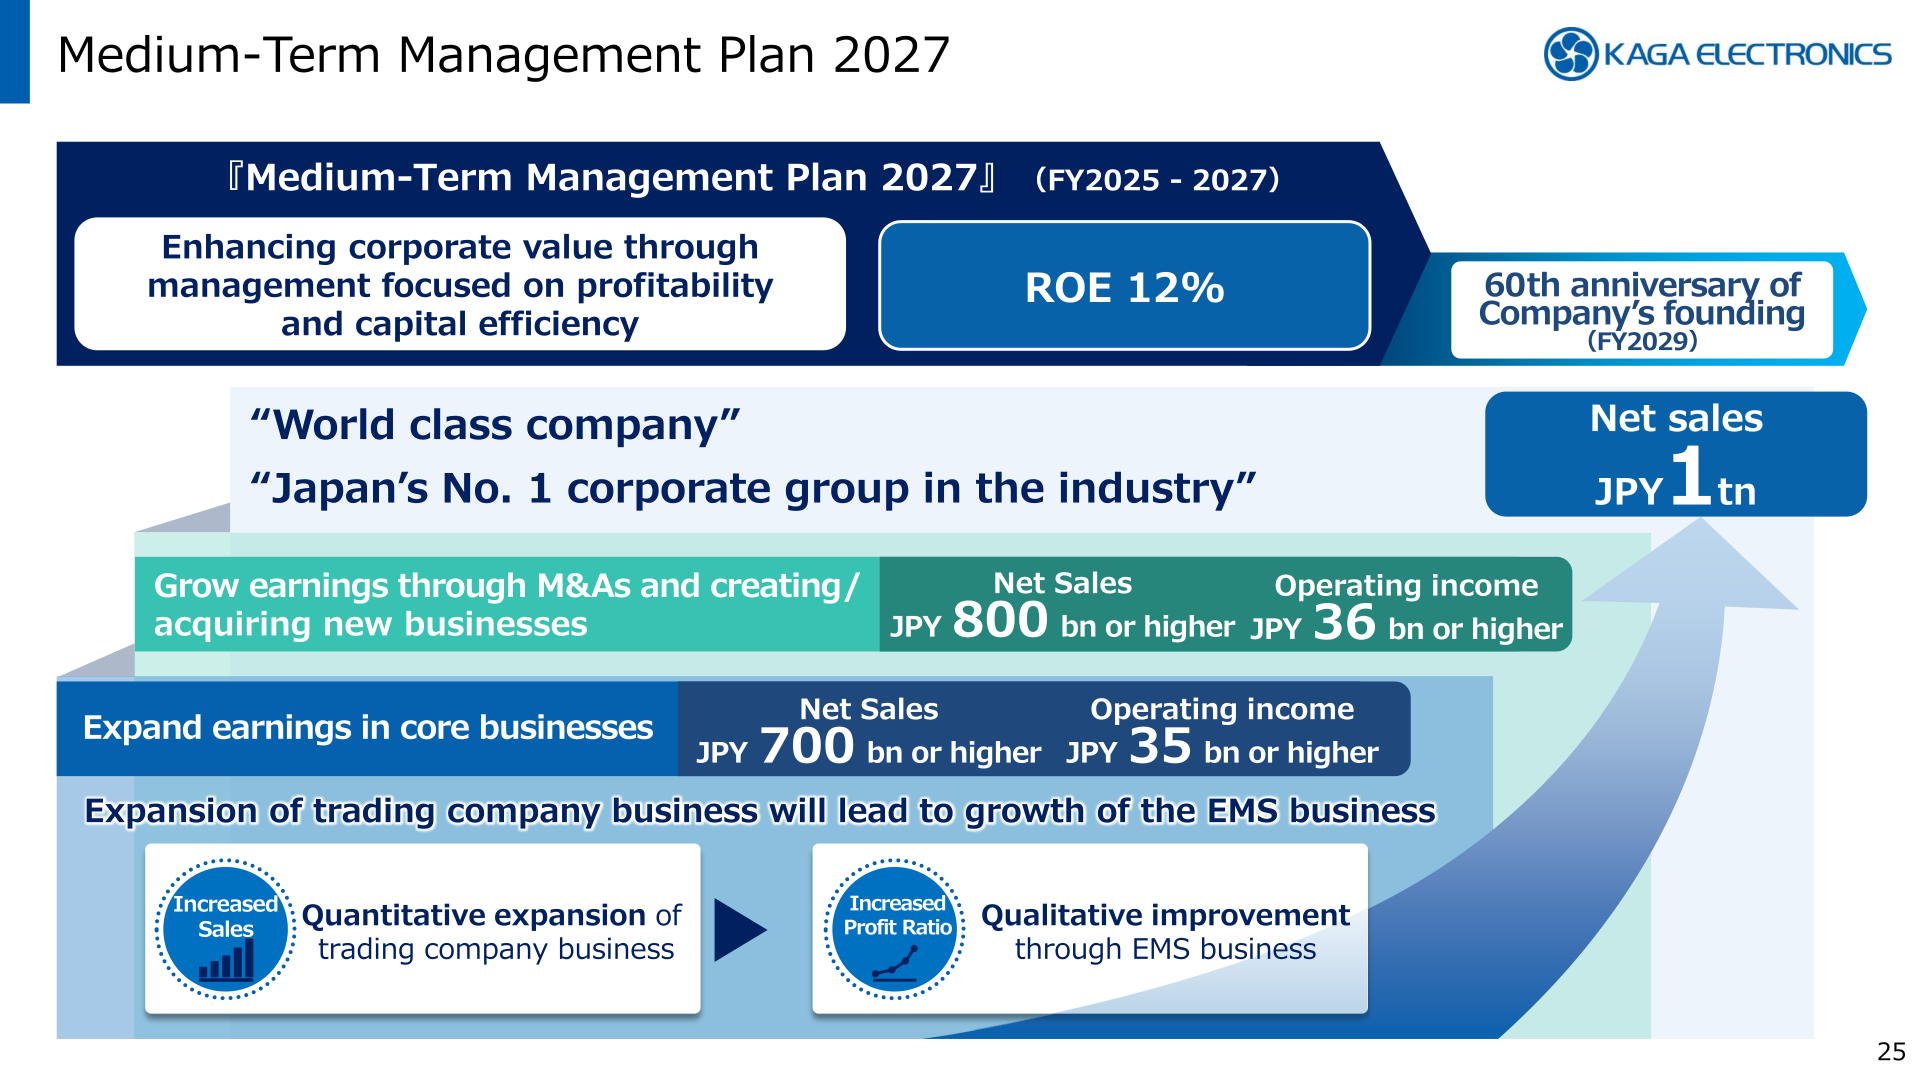
FY2026/3 was the first year of KAGA ELECTRONICS’ Medium-Term Management Plan 2027 (covering FY2025-FY2027), which targets consolidated net sales of JPY 1 trillion and ROE of 12% by the company’s 60th anniversary in FY2029. Under the plan, the company aims for net sales of JPY 700 billion or higher and operating income of JPY 35 billion or higher from expanding earnings in its core businesses, and net sales of JPY 800 billion or higher and operating income of JPY 36 billion or higher including growth from M&As and new businesses. In its first year, the company acquired Kyoei Sangyo Co., Ltd. through a tender offer completed July 18, 2025, raising its ownership to 54.48% and making Kyoei Sangyo a consolidated subsidiary; Kyoei Sangyo was delisted from the Tokyo Stock Exchange on October 16, 2025, and became a wholly-owned subsidiary on November 7, 2025, after KAGA acquired all shares held by Mitsubishi Electric, for a total acquisition price of ¥10.7 billion across the three steps. The company also started new EMS production lines, with a Thailand (Amatanakorn) factory beginning operation in December 2025 and a Singapore factory beginning operation in April 2026.
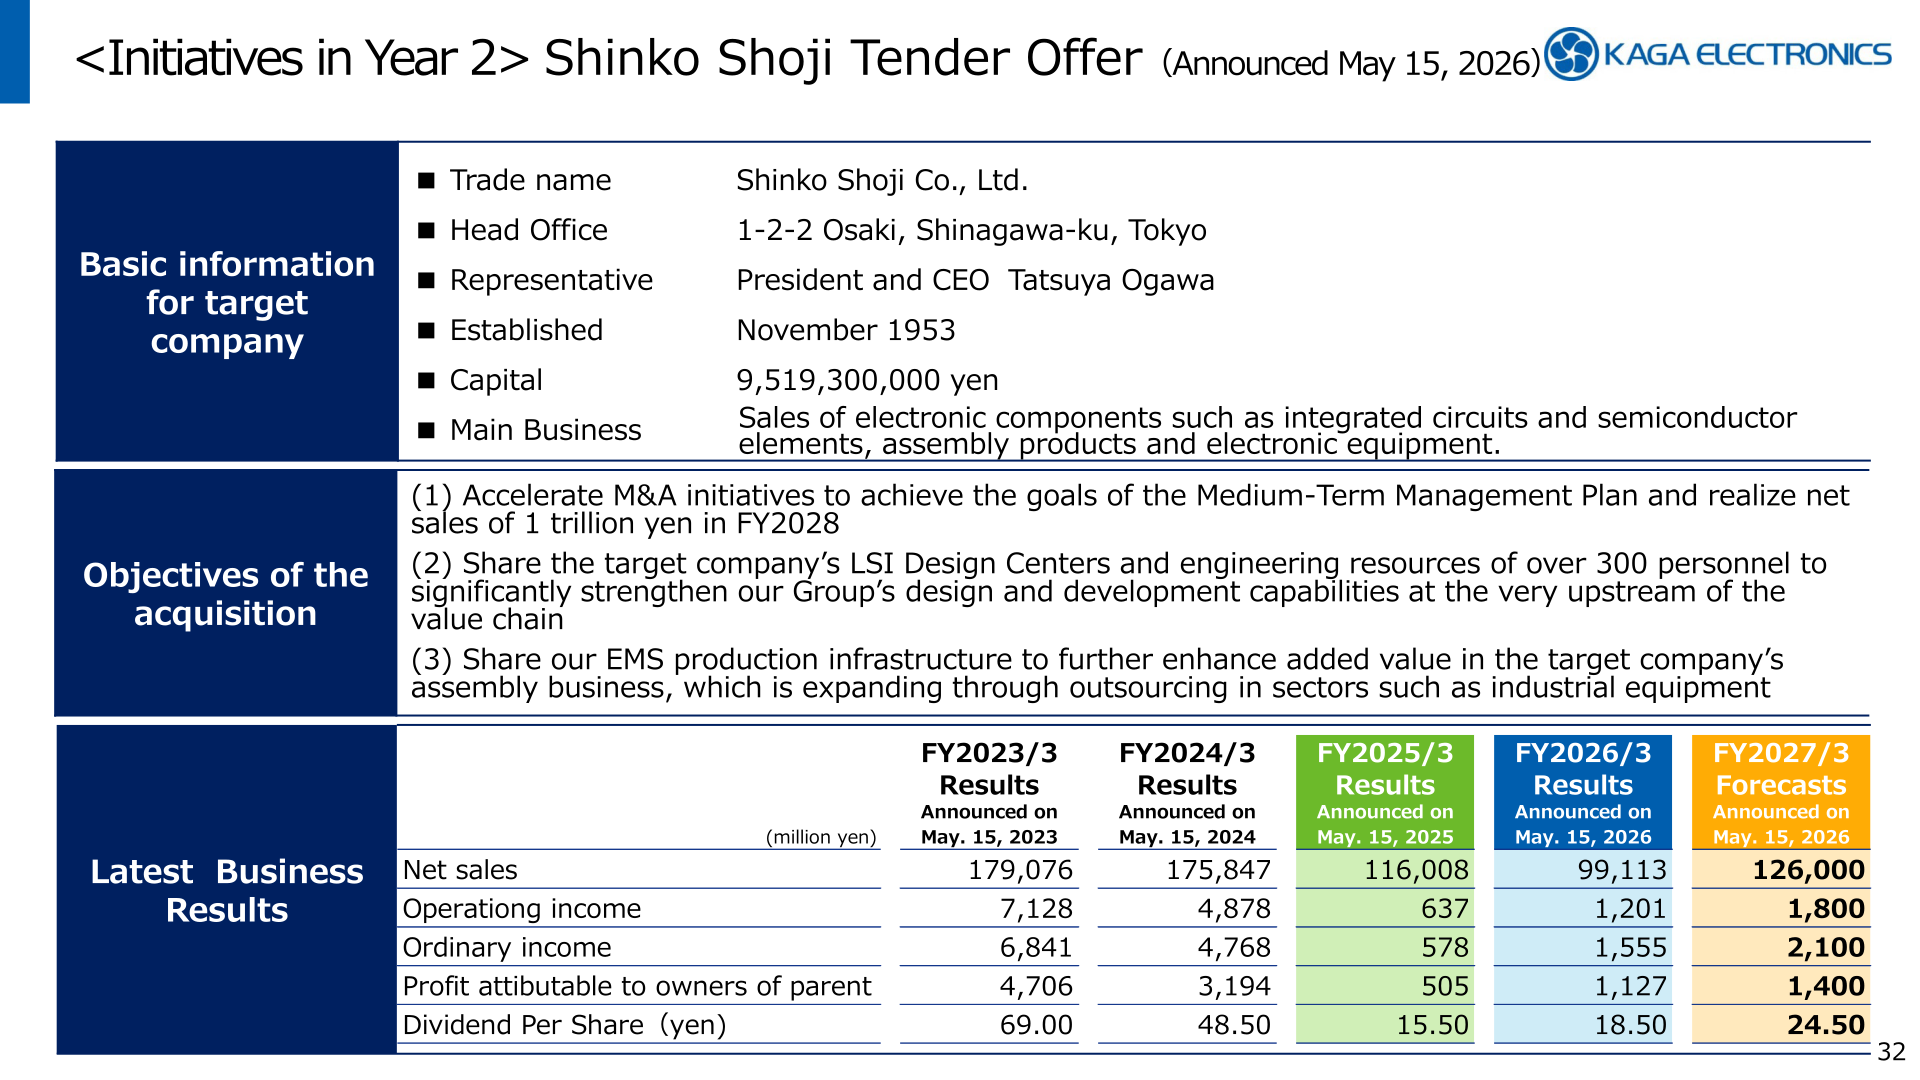
On May 15, 2026, KAGA ELECTRONICS announced a tender offer for Shinko Shoji Co., Ltd. (TSE Prime: 8141) at ¥1,580 per share, a total purchase price of approximately ¥46 billion, running from May 18, 2026, to June 26, 2026. The company said the acquisition is intended to accelerate M&A initiatives toward its FY2028 target of JPY 1 trillion in net sales, to add Shinko Shoji’s LSI design centers and more than 300 design and development engineers to strengthen upstream design capabilities, and to enhance value in Shinko Shoji’s EMS assembly business through KAGA’s production infrastructure. Shinko Shoji reported net sales of ¥99,113 million and operating income of ¥1,201 million for FY2026/3 (its fiscal year ended March 2026), and forecasts net sales of ¥126,000 million and operating income of ¥1,800 million for FY2027/3.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















