
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: This site classifies each company’s most recently completed fiscal year as “FY2025”. Baroque Japan Limited’s fiscal year ends in February, and the company labels the year covered here (the fiscal year ended February 2026) as “FY2026/02”; that labeling is retained in the body and tables below.
Baroque Japan Limited (TSE Prime: 3548), the apparel company behind MOUSSY, SLY, AZUL BY MOUSSY and RODEO CROWNS WIDE BOWL, reported FY2026/02 net sales of 51,499 million yen (88.5% of the prior year) and operating profit of 321 million yen (39.5% of the prior year). Consolidated sales fell mainly because of the dissolution of the China JV with Belle, while sluggish sales at AZUL BY MOUSSY weighed on profit. Profit attributable to owners of parent turned positive at 366 million yen, compared with a loss of (2,575) million yen in FY2025/02. For FY2027/02 the company forecasts net sales of 52,970 million yen and operating profit of 1,352 million yen, and alongside the results it announced a New Medium-Term Management Plan 2027-2028.
Consolidated Results (Full-Year Actual)
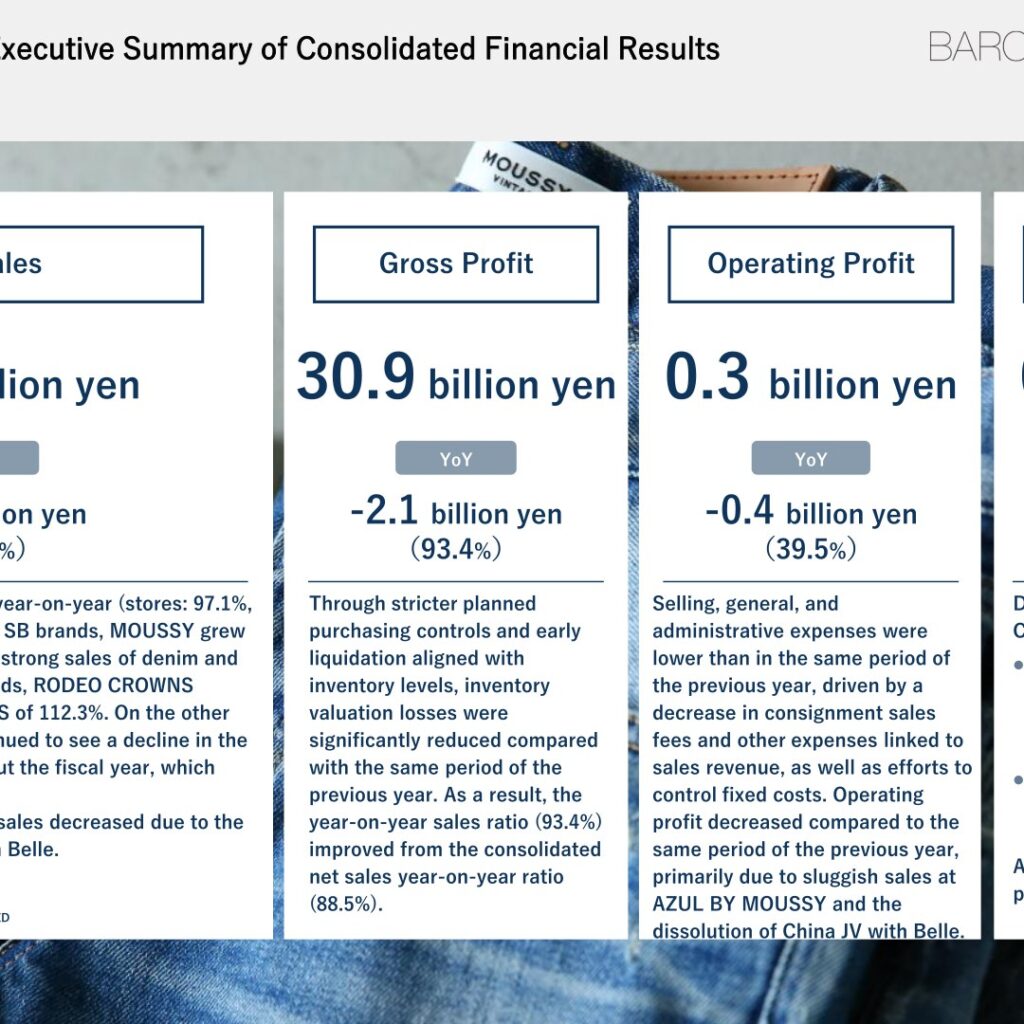
Net sales decreased by 6,680 million yen to 51,499 million yen. The domestic business was 96.3% year on year (stores: 97.1%, e-commerce: 93.4%). Among FB and SB brands, MOUSSY grew 103.8% year on year on strong sales of denim and collaboration items, and among SC brands RODEO CROWNS WIDE BOWL recovered with same-store sales (SSS) of 112.3%. On the other hand, AZUL BY MOUSSY continued to see a decline in the number of customers throughout the fiscal year, which impacted overall sales, and consolidated net sales also decreased due to the dissolution of the China JV with Belle (BELLE INTERNATIONAL HOLDINGS LIMITED).
Gross profit was 30,927 million yen (93.4% of the prior year), and the gross profit ratio improved to 60.1% from 56.9%. Through stricter planned purchasing controls and early liquidation aligned with inventory levels, inventory valuation losses were significantly reduced compared with the previous year. SG&A expenses fell to 30,606 million yen (94.8%), driven by a decrease in consignment sales fees and other expenses linked to sales revenue, as well as efforts to control fixed costs. Operating profit decreased by 491 million yen to 321 million yen, primarily due to sluggish sales at AZUL BY MOUSSY and the dissolution of the China JV. Because of the JV dissolution, no share of loss of entities accounted for using the equity method was recorded in the current fiscal year and a gain on the sale of shares of subsidiaries and associates was recorded; as a result, ordinary profit was 383 million yen (versus a loss of (1,683) million yen) and net profit turned positive.
| Item (Millions of yen) | FY2026/02 | Ratio to Sales | YoY | Increase/Decrease | FY2025/02 |
|---|---|---|---|---|---|
| Net sales | 51,499 | – | 88.5% | -6,680 | 58,180 |
| Gross profit | 30,927 | 60.1% | 93.4% | -2,172 | 33,100 |
| SG&A expenses | 30,606 | 59.4% | 94.8% | -1,681 | 32,287 |
| Operating profit | 321 | 0.6% | 39.5% | -491 | 812 |
| Ordinary profit (loss) | 383 | 0.7% | – | +2,067 | (1,683) |
| Profit (loss) attributable to owners of parent | 366 | 0.7% | – | +2,941 | (2,575) |
In an appendix, the company also compares FY2026/02 with FY2025/02 figures excluding the China JV. On that basis, FY2025/02 net sales were 53,740 million yen and operating profit 339 million yen, so FY2026/02 net sales were 95.8% and operating profit 94.6% of the prior-year level; FY2025/02 profit attributable to owners of parent excluding the China JV was (99) million yen.
Within consolidated SG&A expenses, store rent and fee for franchisee was 12,482 million yen (96.2%), salaries and wages 5,442 million yen (93.7%), advertising and promotional expenses 1,843 million yen (95.0%) and depreciation 905 million yen (96.6%). On the balance sheet at the end of FY2026/02, total assets were 32,593 million yen (34,051 million yen a year earlier), liabilities 17,887 million yen and net assets 14,705 million yen (45.1% of total assets). Cash and deposits were 11,319 million yen, accounts receivable-trade declined to 2,442 million yen from 7,760 million yen, merchandise was 5,003 million yen, and non-current assets increased to 13,441 million yen from 9,262 million yen.
Segment Results
The domestic business recorded net sales of 50,771 million yen (96.3%), of which store sales were 37,900 million yen (97.1%) and EC sales 10,147 million yen (93.4%). Domestic operating profit rose to 207 million yen from 109 million yen, ordinary profit was 399 million yen, and profit was 170 million yen compared with a loss of (525) million yen in the previous year.
| Domestic Business (Millions of yen) | FY2026/02 | Ratio to Sales | YoY | Increase/Decrease | FY2025/02 |
|---|---|---|---|---|---|
| Net sales | 50,771 | – | 96.3% | -1,962 | 52,734 |
| Store sales | 37,900 | 74.6% | 97.1% | -1,131 | 39,031 |
| EC sales | 10,147 | 20.0% | 93.4% | -719 | 10,867 |
| Gross profit | 29,935 | 59.0% | 97.3% | -843 | 30,778 |
| SG&A expenses | 29,728 | 58.6% | 96.9% | -941 | 30,669 |
| Operating profit | 207 | 0.4% | 189.8% | +98 | 109 |
| Ordinary profit | 399 | 0.8% | 12669.9% | +396 | 3 |
| Profit (loss) | 170 | 0.3% | – | +696 | (525) |
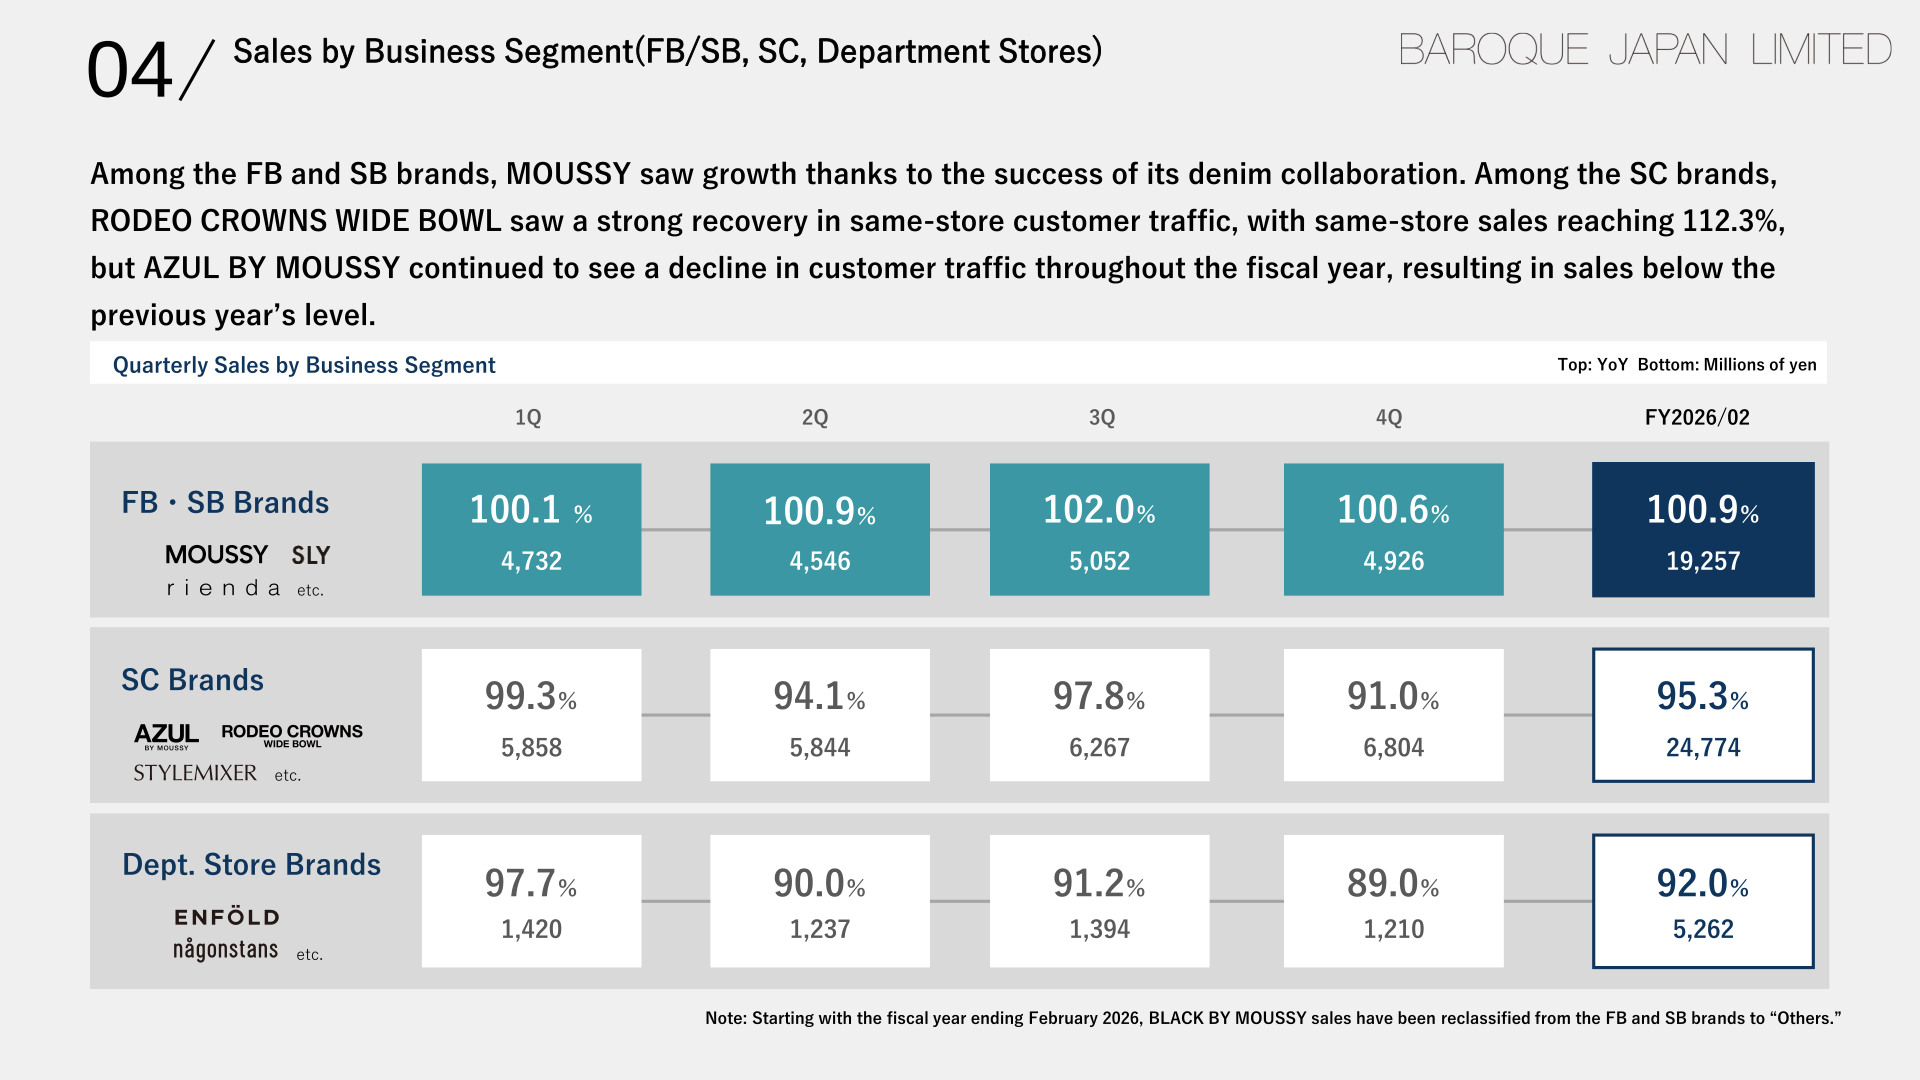
By business segment, FB and SB brands (MOUSSY, SLY, rienda, etc.) posted full-year sales of 19,257 million yen (100.9%), with every quarter above the prior-year level; MOUSSY saw growth thanks to the success of its denim collaboration. SC brands (AZUL BY MOUSSY, RODEO CROWNS WIDE BOWL, STYLEMIXER, etc.) recorded 24,774 million yen (95.3%): RODEO CROWNS WIDE BOWL saw a strong recovery in same-store customer traffic, but AZUL BY MOUSSY’s customer traffic declined throughout the year. Department store brands (ENFÖLD, någonstans, etc.) recorded 5,262 million yen (92.0%). Starting with the fiscal year ending February 2026, BLACK BY MOUSSY sales have been reclassified from the FB and SB brands to “Others”.
| Business Segment (Millions of yen) | 1Q | 2Q | 3Q | 4Q | FY2026/02 | FY2026/02 YoY |
|---|---|---|---|---|---|---|
| FB/SB brands | 4,732 | 4,546 | 5,052 | 4,926 | 19,257 | 100.9% |
| SC brands | 5,858 | 5,844 | 6,267 | 6,804 | 24,774 | 95.3% |
| Department store brands | 1,420 | 1,237 | 1,394 | 1,210 | 5,262 | 92.0% |
FY2027/02 Forecast
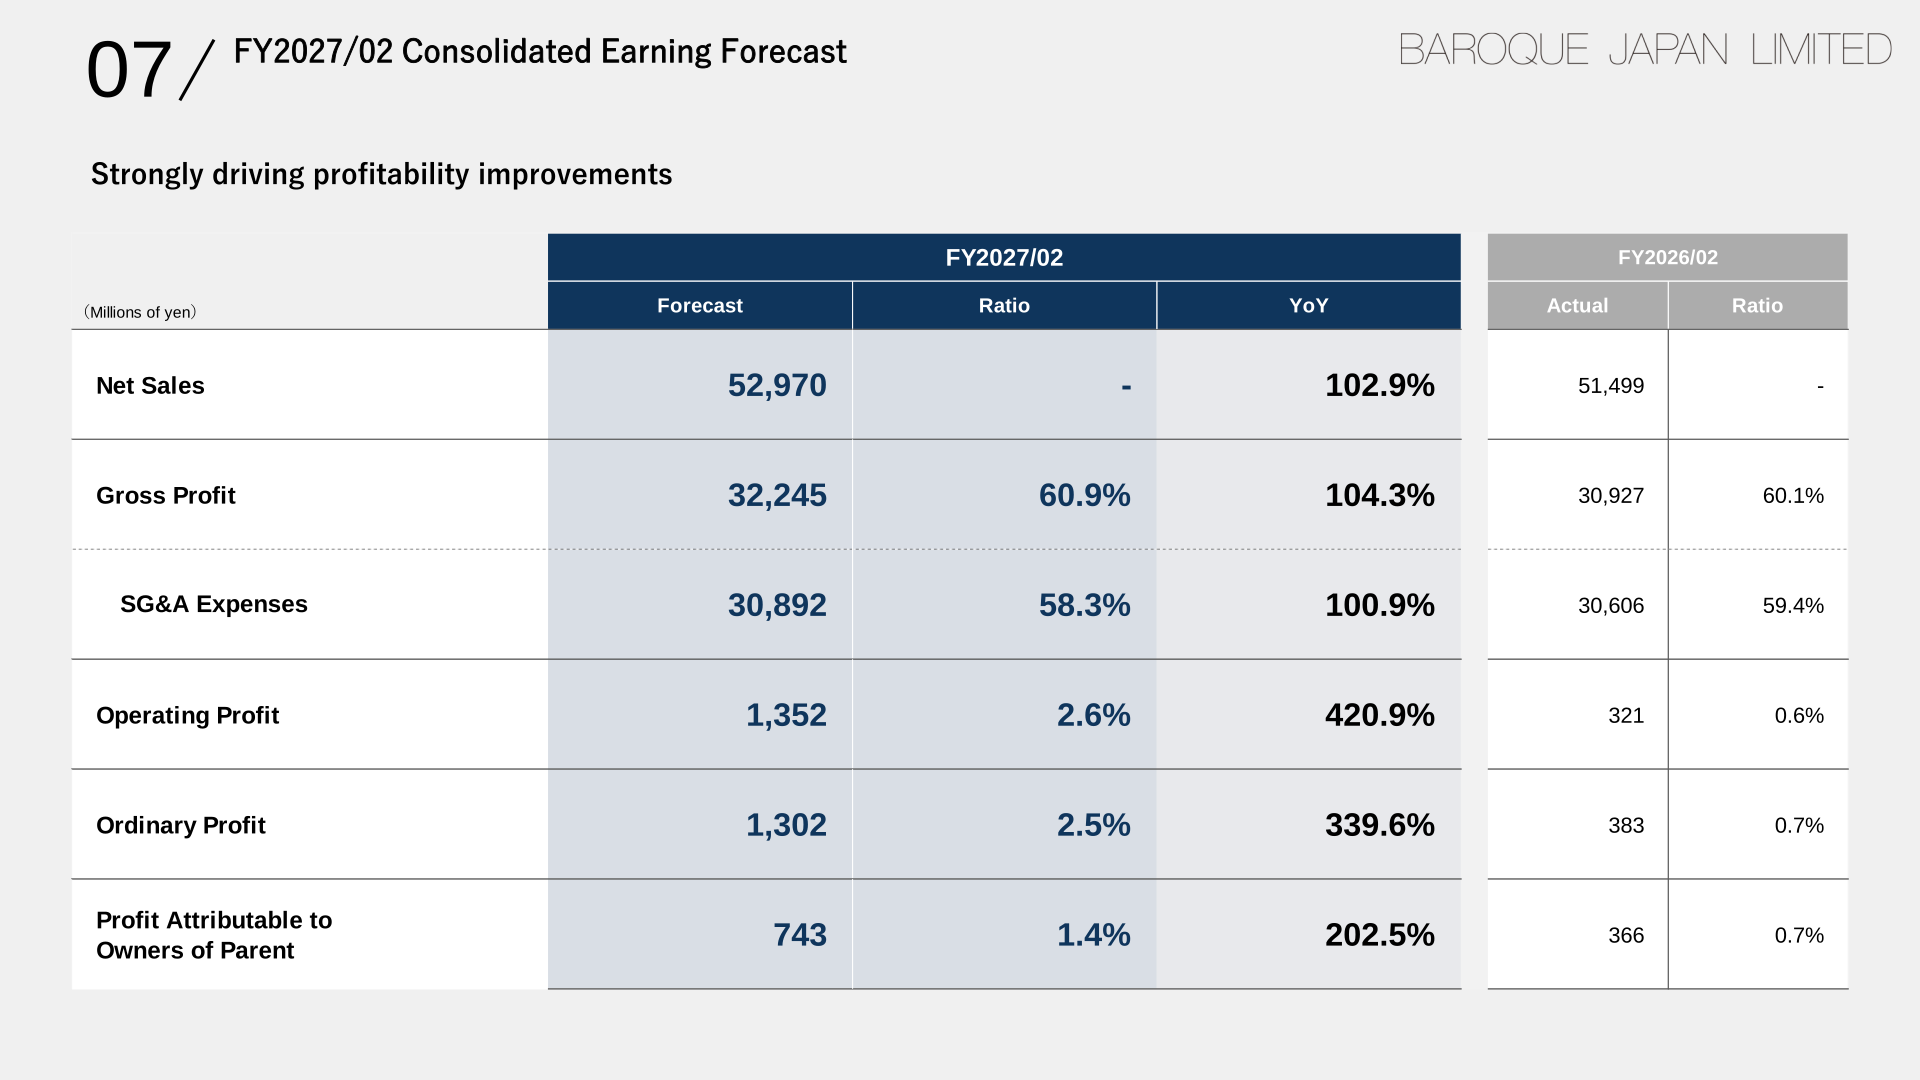
Under the heading “Strongly driving profitability improvements”, the company forecasts FY2027/02 net sales of 52,970 million yen (102.9% of FY2026/02) and gross profit of 32,245 million yen, with the gross profit ratio rising to 60.9%. SG&A expenses are expected to be 30,892 million yen (100.9%), and operating profit is forecast at 1,352 million yen (420.9%), for an operating profit ratio of 2.6%. Ordinary profit is forecast at 1,302 million yen and profit attributable to owners of parent at 743 million yen (202.5%).
| Item (Millions of yen) | FY2027/02 Forecast | Ratio to Sales | YoY | FY2026/02 (Actual) |
|---|---|---|---|---|
| Net sales | 52,970 | – | 102.9% | 51,499 |
| Gross profit | 32,245 | 60.9% | 104.3% | 30,927 |
| SG&A expenses | 30,892 | 58.3% | 100.9% | 30,606 |
| Operating profit | 1,352 | 2.6% | 420.9% | 321 |
| Ordinary profit | 1,302 | 2.5% | 339.6% | 383 |
| Profit attributable to owners of parent | 743 | 1.4% | 202.5% | 366 |
Shareholder Returns
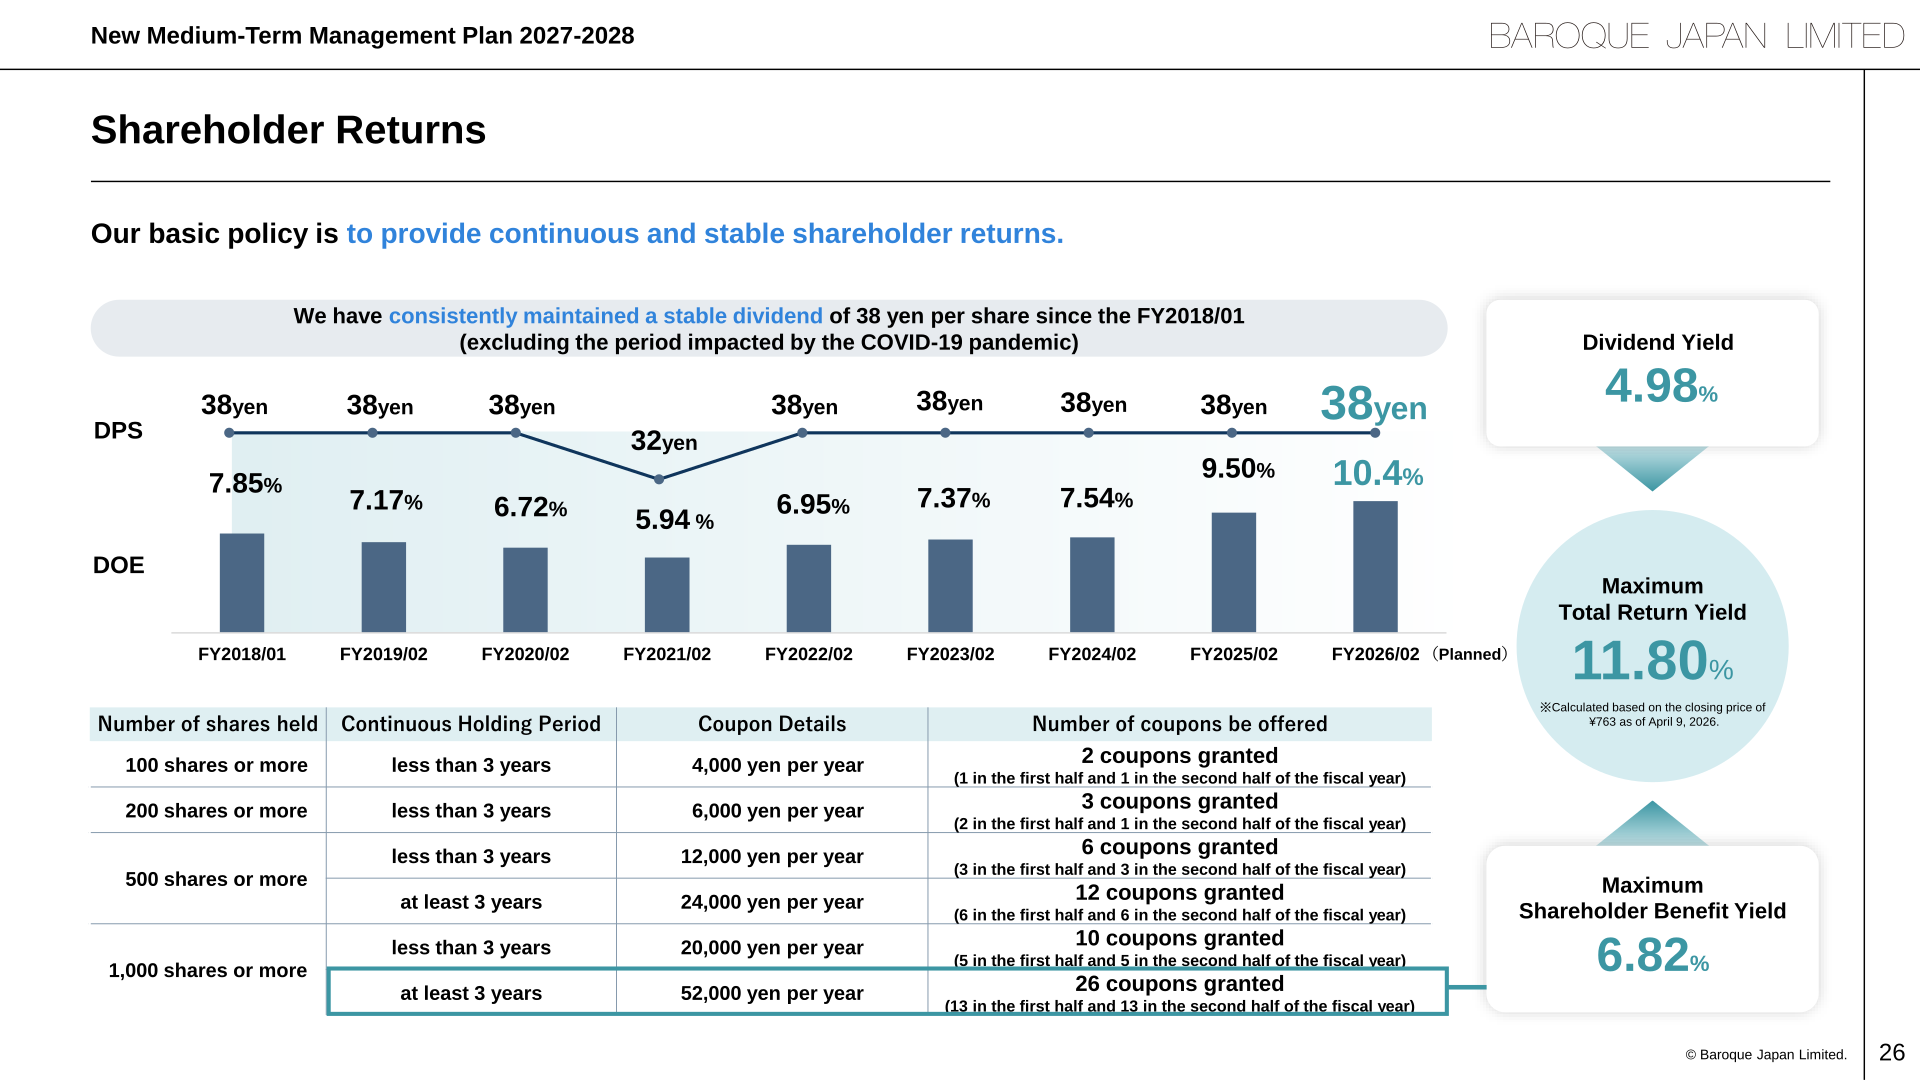
The company’s basic policy is to provide continuous and stable shareholder returns. It has consistently maintained a stable dividend of 38 yen per share since FY2018/01, excluding the period impacted by the COVID-19 pandemic (32 yen in FY2021/02). The dividend for FY2026/02 is planned at 38 yen, with DOE (dividend on equity) of 10.4%, up from 9.50% in FY2025/02. The FY2027/02 dividend per share cannot be confirmed from the materials.
The company also offers a shareholder benefit program of coupons: holders of 100 shares or more receive 4,000 yen per year, rising to 52,000 yen per year (26 coupons) for holders of 1,000 shares or more with a continuous holding period of at least 3 years. Based on the closing price of ¥763 as of April 9, 2026, the company calculates a dividend yield of 4.98%, a maximum shareholder benefit yield of 6.82% and a maximum total return yield of 11.80%. Under the new medium-term plan’s capital allocation, operating cash flow is to be directed to investment in existing and new businesses while ensuring continuous and stable shareholder returns.
New Medium-Term Management Plan 2027-2028
The company did not achieve the targets of its previous medium-term management plan (2022-2026). Against targets of a consolidated operating profit ratio of 3.0~4.0%, ROE of 4.0~5.0% and inventory turnover of 5.5~6.5 times, FY2026/02 results were 0.6%, 2.4% and 4.0 times, respectively. The company cites a decline in customers at AZUL, its flagship domestic shopping center brand, a decline in organizational productivity because necessary functions are scattered across individual brands, and a revenue structure heavily reliant on the apparel business. The new plan designates the two years from FY2027/02 as a period for financial recovery and the creation of new businesses, under the theme “Transforming into a Lean Management Structure and Creating New High-Growth, Profitable Businesses”.
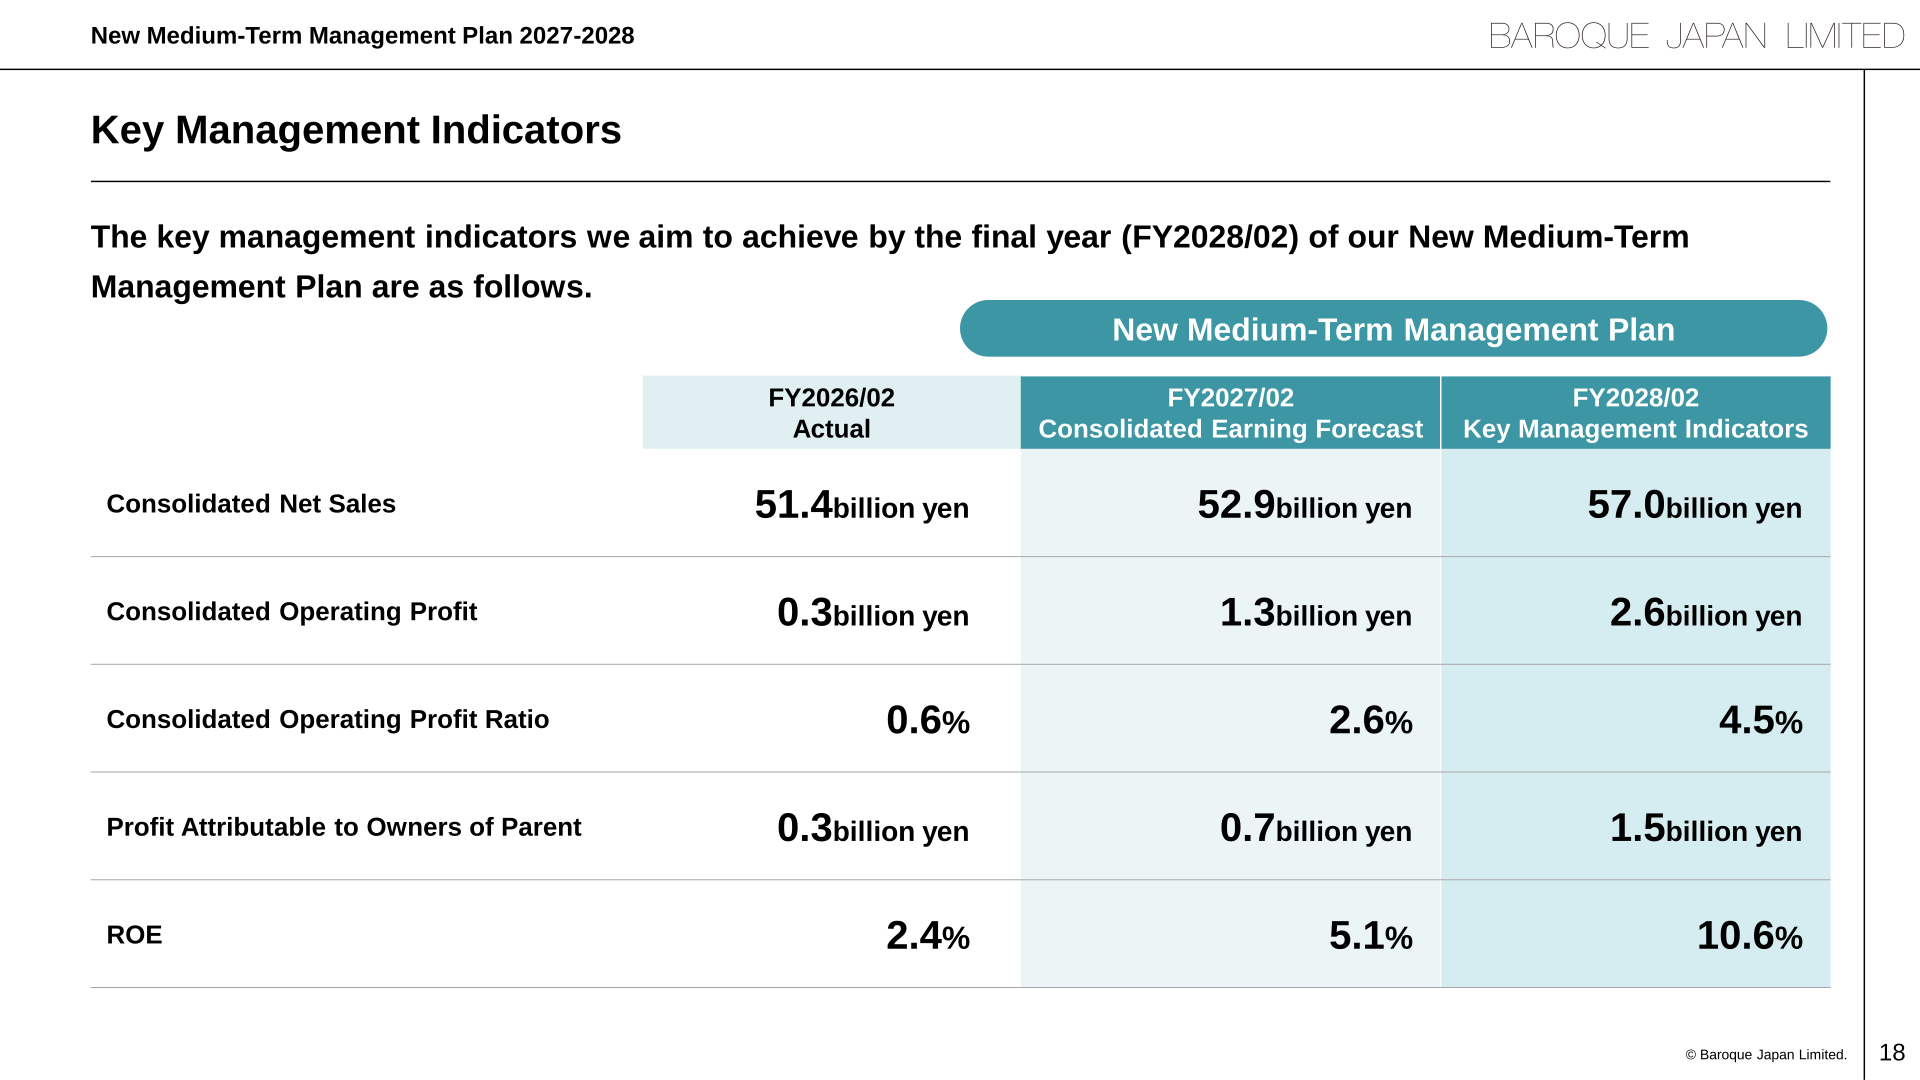
Key management indicators for the plan’s final year, FY2028/02, are consolidated net sales of 57.0 billion yen, consolidated operating profit of 2.6 billion yen (operating profit ratio of 4.5%), profit attributable to owners of parent of 1.5 billion yen and ROE of 10.6%, compared with FY2026/02 actual results of 51.4 billion yen, 0.3 billion yen (0.6%), 0.3 billion yen and 2.4%. The FY2027/02 forecast implies ROE of 5.1%.
For the turnaround of AZUL BY MOUSSY, whose FY2026/02 same-store sales were 94.6% with the number of customers at 92.6% and average sales per customer at 102.1% year on year, the company plans to strengthen product differentiation, use higher-quality materials, reinforce PR, renovate stores and revise pricing to more accessible levels, while applying the expertise of MOUSSY (SSS of 106.6% in FY2026/02) and RODEO CROWNS WIDE BOWL (SSS of 112.3%). Other initiatives include performance-based incentives for each store, a shift from brand-specific operations to a centralized operating structure with consolidated suppliers, expanded store openings for high-growth brands and the development of new brands exceeding 10 billion yen in net sales.
Beyond apparel, the company will pursue new industries through DB Capital Limited, a joint venture with JD.com, aimed at promoting Japanese companies’ technologies and products to the world and supporting their overseas expansion into regions such as China and Europe. The materials describe a joint investment of 15 billion yen in DB Capital Limited, with a BJL equity stake of 25%.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















