
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Kawada Technologies, Inc. has a March fiscal year-end and labels the fiscal year covered here as “FY3/2026” (April 1, 2025 through March 31, 2026); on this site the most recently completed fiscal year is classified as FY2025, and the labels used in the text, tables and segment data below follow the company’s own materials.
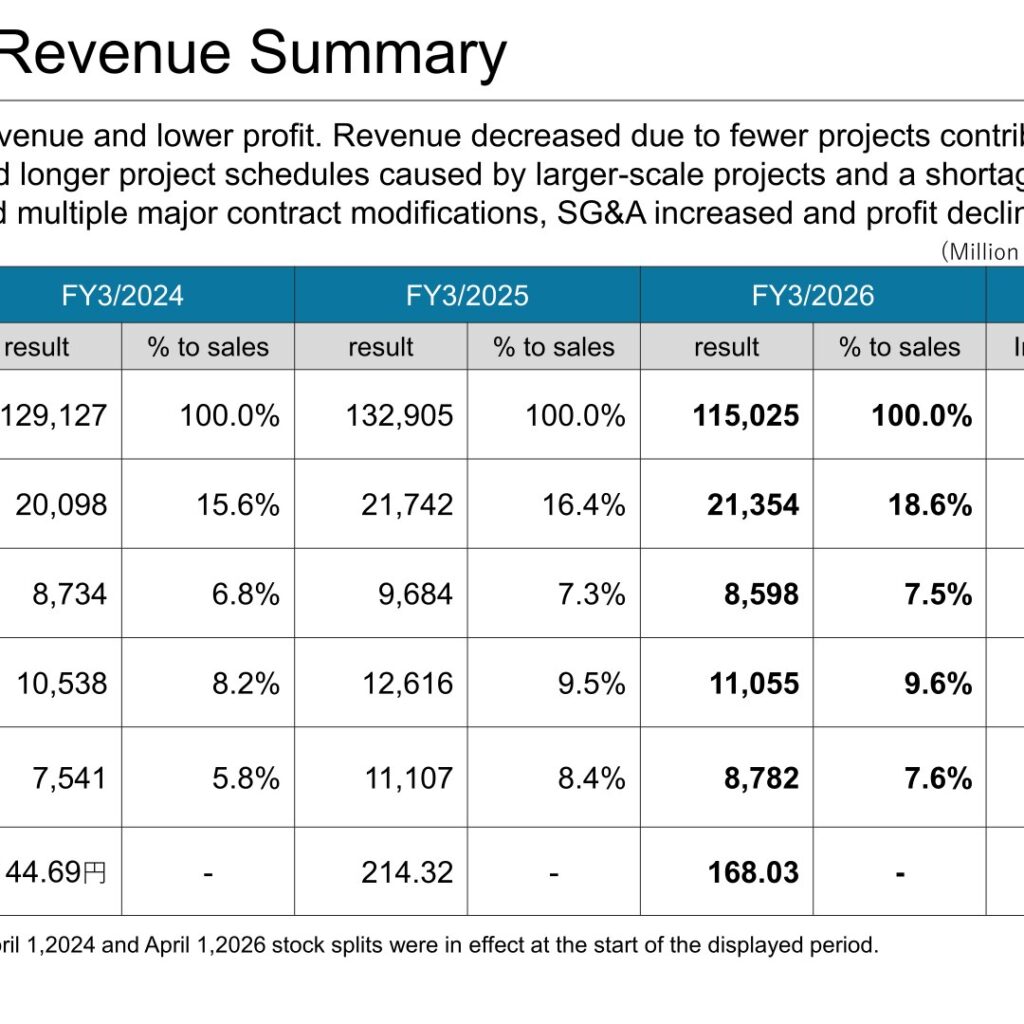
Kawada Technologies, the holding company of a group engaged in steel bridges, prestressed-concrete bridges, architectural steel frames, construction and software/robotics, reported FY3/2026 sales of 115,025 million yen (-13.5% YoY), operating profit of 8,598 million yen (-11.2%), ordinary profit of 11,055 million yen (-12.4%) and net income attributable to owners of Kawada of 8,782 million yen (-20.9%). The company says it closed with lower revenue and lower profit, as fewer projects contributed to completed work amid longer project schedules caused by larger-scale projects and a shortage of personnel. Ending order backlog reached a record high of 178,306 million yen. For FY3/2027, the company forecasts sales of 125,000 million yen and operating profit of 7,200 million yen, and it has adopted a new shareholder returns policy targeting a total shareholder return ratio of around 50% during the 4th Medium-Term Management Plan.
Consolidated Results (Full-Year Actual)
According to the company, revenue decreased due to fewer projects contributing to this term’s completed work amid longer project schedules, and although it secured multiple major contract modifications, SG&A increased and profit declined. Gross profit was 21,354 million yen, with the gross margin rising to 18.6% from 16.4%, and the operating margin improved to 7.5% from 7.3%. EPS was 168.03 yen, calculated assuming the April 1, 2024 and April 1, 2026 stock splits were in effect at the start of the displayed period.
| Item (million yen) | FY3/2026 | % to sales | FY3/2025 | YoY (amount) | YoY (%) |
|---|---|---|---|---|---|
| Sales | 115,025 | 100.0% | 132,905 | -17,880 | -13.5% |
| Gross Profit | 21,354 | 18.6% | 21,742 | -387 | -1.8% |
| Operating Profit | 8,598 | 7.5% | 9,684 | -1,086 | -11.2% |
| Ordinary Profit | 11,055 | 9.6% | 12,616 | -1,561 | -12.4% |
| Net Income Attributable to Owners of Kawada | 8,782 | 7.6% | 11,107 | -2,325 | -20.9% |
| Earnings Per Share (yen) | 168.03 | – | 214.32 | -46.29 | -21.6% |
Orders for steel and PC bridges remained weak throughout the year, and the company describes competition for orders as intense and the environment as very challenging. Newly received orders fell 13.9% to 127,638 million yen, with orders in the Steel Construction and Civil Engineering segments falling sharply while other segments were roughly flat. Due to sluggish progress on backlog projects, ending order backlog rose 6.2% to 178,306 million yen, a record high. On the balance sheet, collection of receivables progressed and short-term borrowings for working capital were repaid: total assets decreased to 162,986 million yen, net assets increased to 99,510 million yen and the equity ratio rose to 60.7% (+5.7pp). ROE was 9.2% (-3.6pp) and ROA 6.7% (-1.0pp). Operating cash flow was 15,160 million yen. Provisions for construction losses increased to 3,805 million yen due to cost-preceding for projects ordered in the Steel Construction segment during the term.
Segment Results
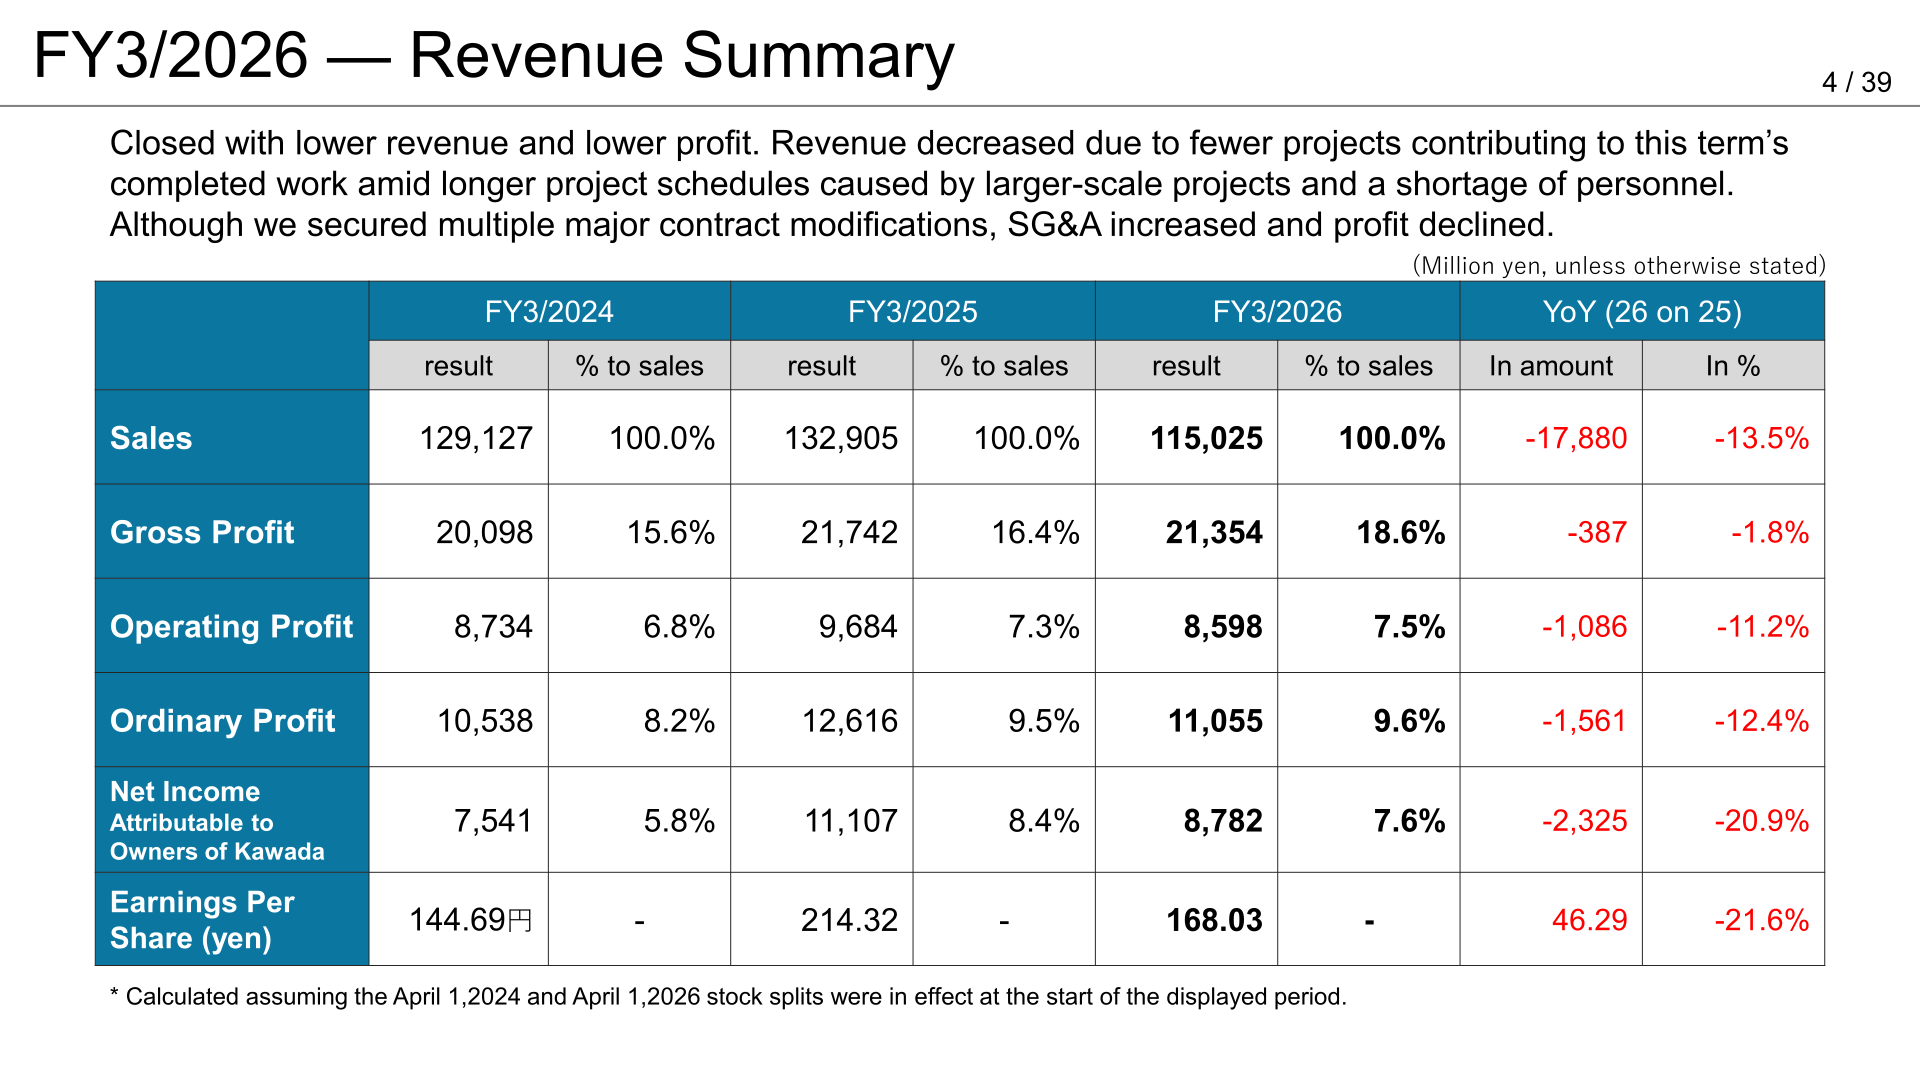
Steel Construction: In steel bridges, the market size is holding, with repair/maintenance and modification increasing while new construction is declining; projects are getting larger and schedules longer, so although backlog is ample, progress this term was limited and net sales decreased. Profit and profit margin improved on captured contract modifications. In architectural steel frames, orders were covered by Kansai-area projects during a lull in Tokyo-area projects; net sales fell on reduced carryover, and profit slightly decreased despite a higher margin. Segment sales fell 21.0% to 49,879 million yen while operating profit rose 0.7% to 6,320 million yen, for an operating margin of 12.7% (+2.8pp).
Civil Engineering: In the prestressed-concrete bridge market, new bid opportunities have declined; intensified competition and a large order won in the prior term mainly caused the order decline, although order targets were met. Net sales fell on longer schedules in new construction and maintenance, and contract modifications won in new construction improved profit, but renewal and maintenance declined due to the absence of prior-term large design-change gains. Segment sales were 32,918 million yen (-14.8%) and operating profit 1,654 million yen (-21.4%). Architecture: Orders increased YoY despite some projects missing contracting within the term; sales rose 8.0% to 16,703 million yen, but profit slightly decreased to 1,308 million yen on steady progress on a challenging multi-story warehouse project. Solution: Software information-sharing services remained solid and robot direct sales were strong, with sales of 8,197 million yen (+3.1%) and operating profit of 3,098 million yen (+3.9%).
| Segment (million yen) | Newly-Received Orders FY3/2026 | Sales FY3/2026 | Sales FY3/2025 | Operating Profit FY3/2026 | Operating Profit FY3/2025 | Operating Margin FY3/2026 |
|---|---|---|---|---|---|---|
| Steel Construction | 59,301 | 49,879 | 63,172 | 6,320 | 6,274 | 12.7% |
| Civil Engineering | 34,283 | 32,918 | 38,622 | 1,654 | 2,106 | 5.0% |
| Architecture | 16,042 | 16,703 | 15,473 | 1,308 | 1,444 | 7.8% |
| Solution | 8,520 | 8,197 | 7,949 | 3,098 | 2,982 | 37.8% |
Segment figures are not adjusted for internal sales between business segments. Ending order backlog by segment was 104,794 million yen in Steel Construction (+9.9%), 52,064 million yen in Civil Engineering (+2.7%), 17,127 million yen in Architecture (-3.7%) and 3,926 million yen in Solution.
Full-Year Forecast (FY3/2027)
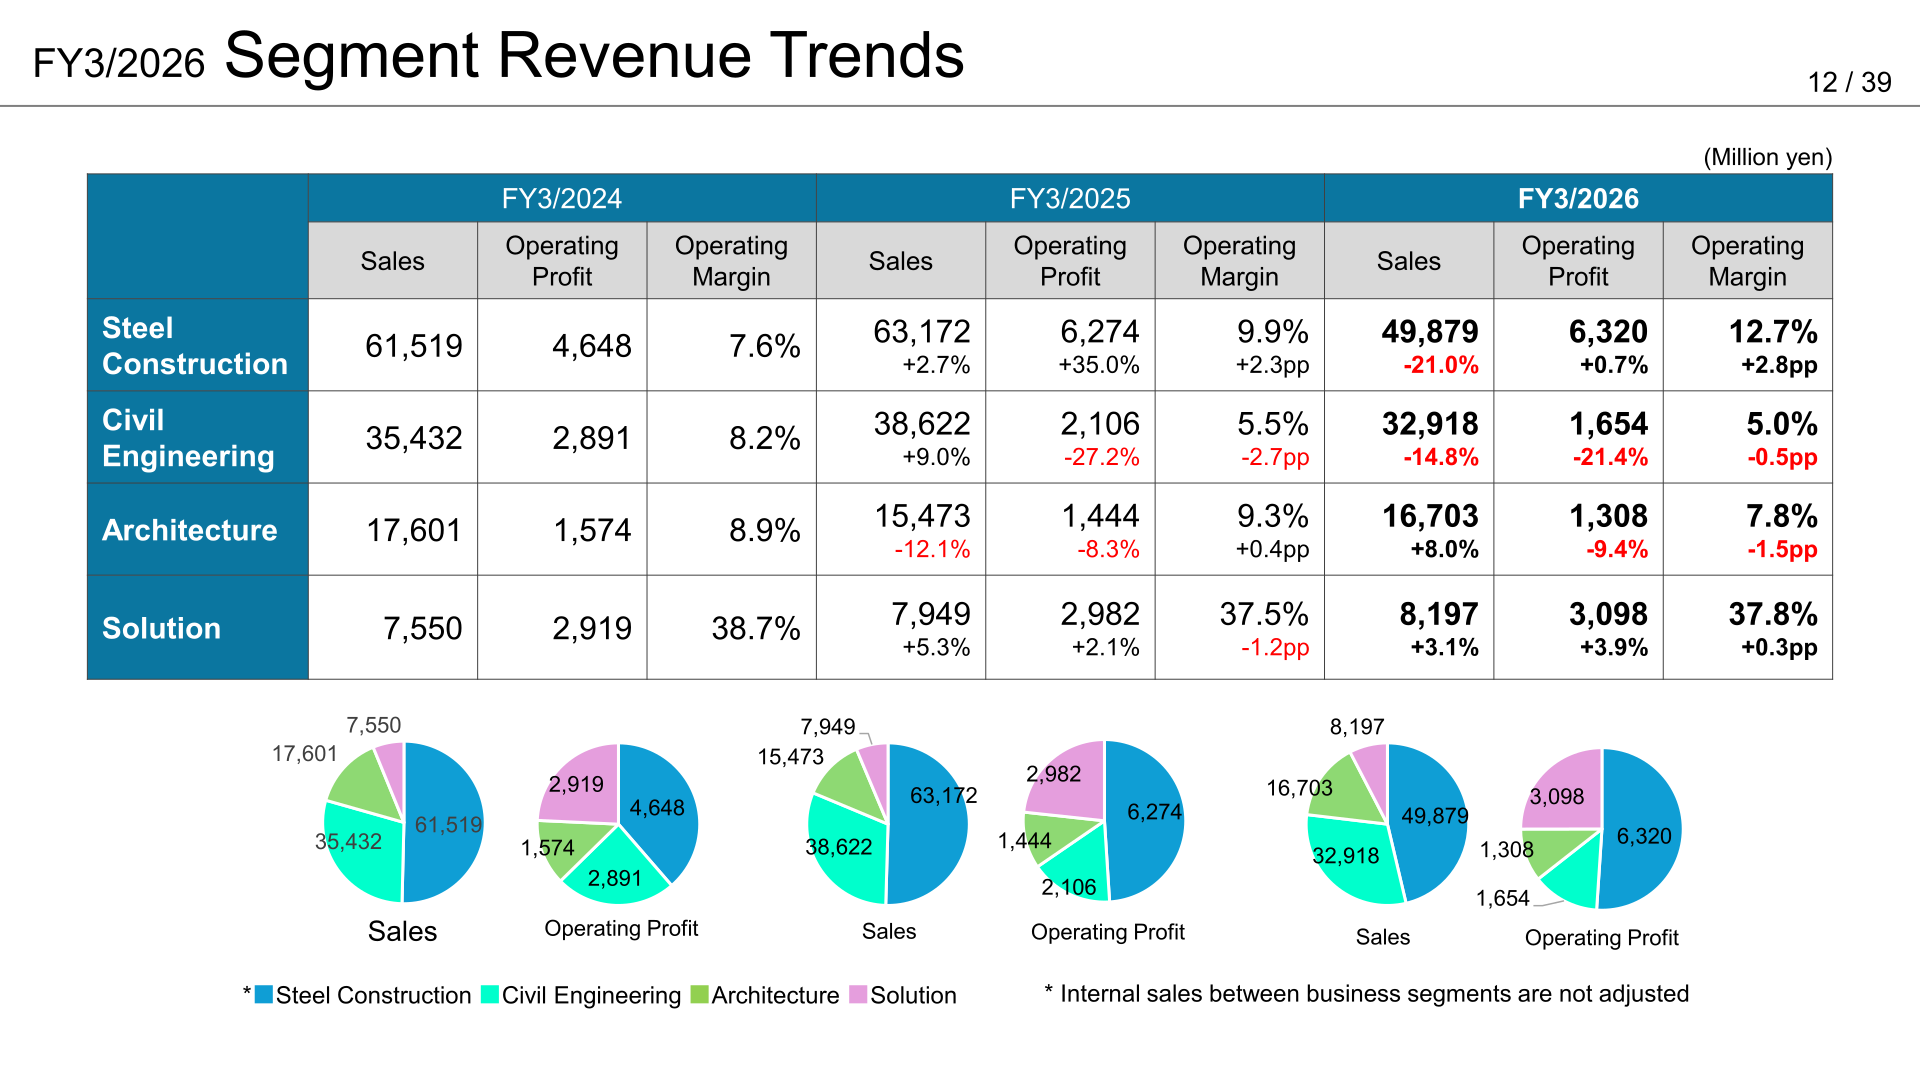
With continued yen depreciation, labor shortages, rising prices of various goods and uncertain global conditions that could strain construction materials, the company assumes a challenging business environment. It expects net sales to exceed the prior term at 125,000 million yen (+8.7%), while operating profit and below are forecast to decline, with operating profit of 7,200 million yen (-16.3%) and net income attributable to owners of Kawada of 7,100 million yen (-19.2%). By segment, Steel Construction expects a sales increase to 55,500 million yen but lower profit of 4,400 million yen on fewer contract modifications; Civil Engineering targets sales at the prior-term level and profit growth through actively capturing contract modifications; Architecture expects orders of 20,500 million yen and sales of 19,500 million yen; and Solution expects sales of 8,700 million yen. From FY2027 onward, issuance of orders for the Osaka Bay Road westward extension construction portion is expected.
| Item (million yen) | FY3/2027 (forecast) | FY3/2026 (actual) | YoY (amount) | YoY (%) |
|---|---|---|---|---|
| Sales | 125,000 | 115,025 | +9,974 | +8.7% |
| Operating Profit | 7,200 | 8,598 | -1,398 | -16.3% |
| Ordinary Profit | 9,500 | 11,055 | -1,555 | -14.1% |
| Net Income Attributable to Owners of Kawada | 7,100 | 8,782 | -1,682 | -19.2% |
| Earnings Per Share (yen) | 135.71 | 168.03 | -32.32 | -19.2% |
| Segment (million yen) | Orders forecast | Sales forecast | Operating Profit forecast | Operating Margin forecast |
|---|---|---|---|---|
| Steel Construction | 52,000 | 55,500 | 4,400 | 7.9% |
| Civil Engineering | 34,000 | 33,000 | 1,800 | 5.5% |
| Architecture | 20,500 | 19,500 | 1,200 | 6.2% |
| Solution | 8,500 | 8,700 | 3,000 | 34.5% |
Shareholder Returns
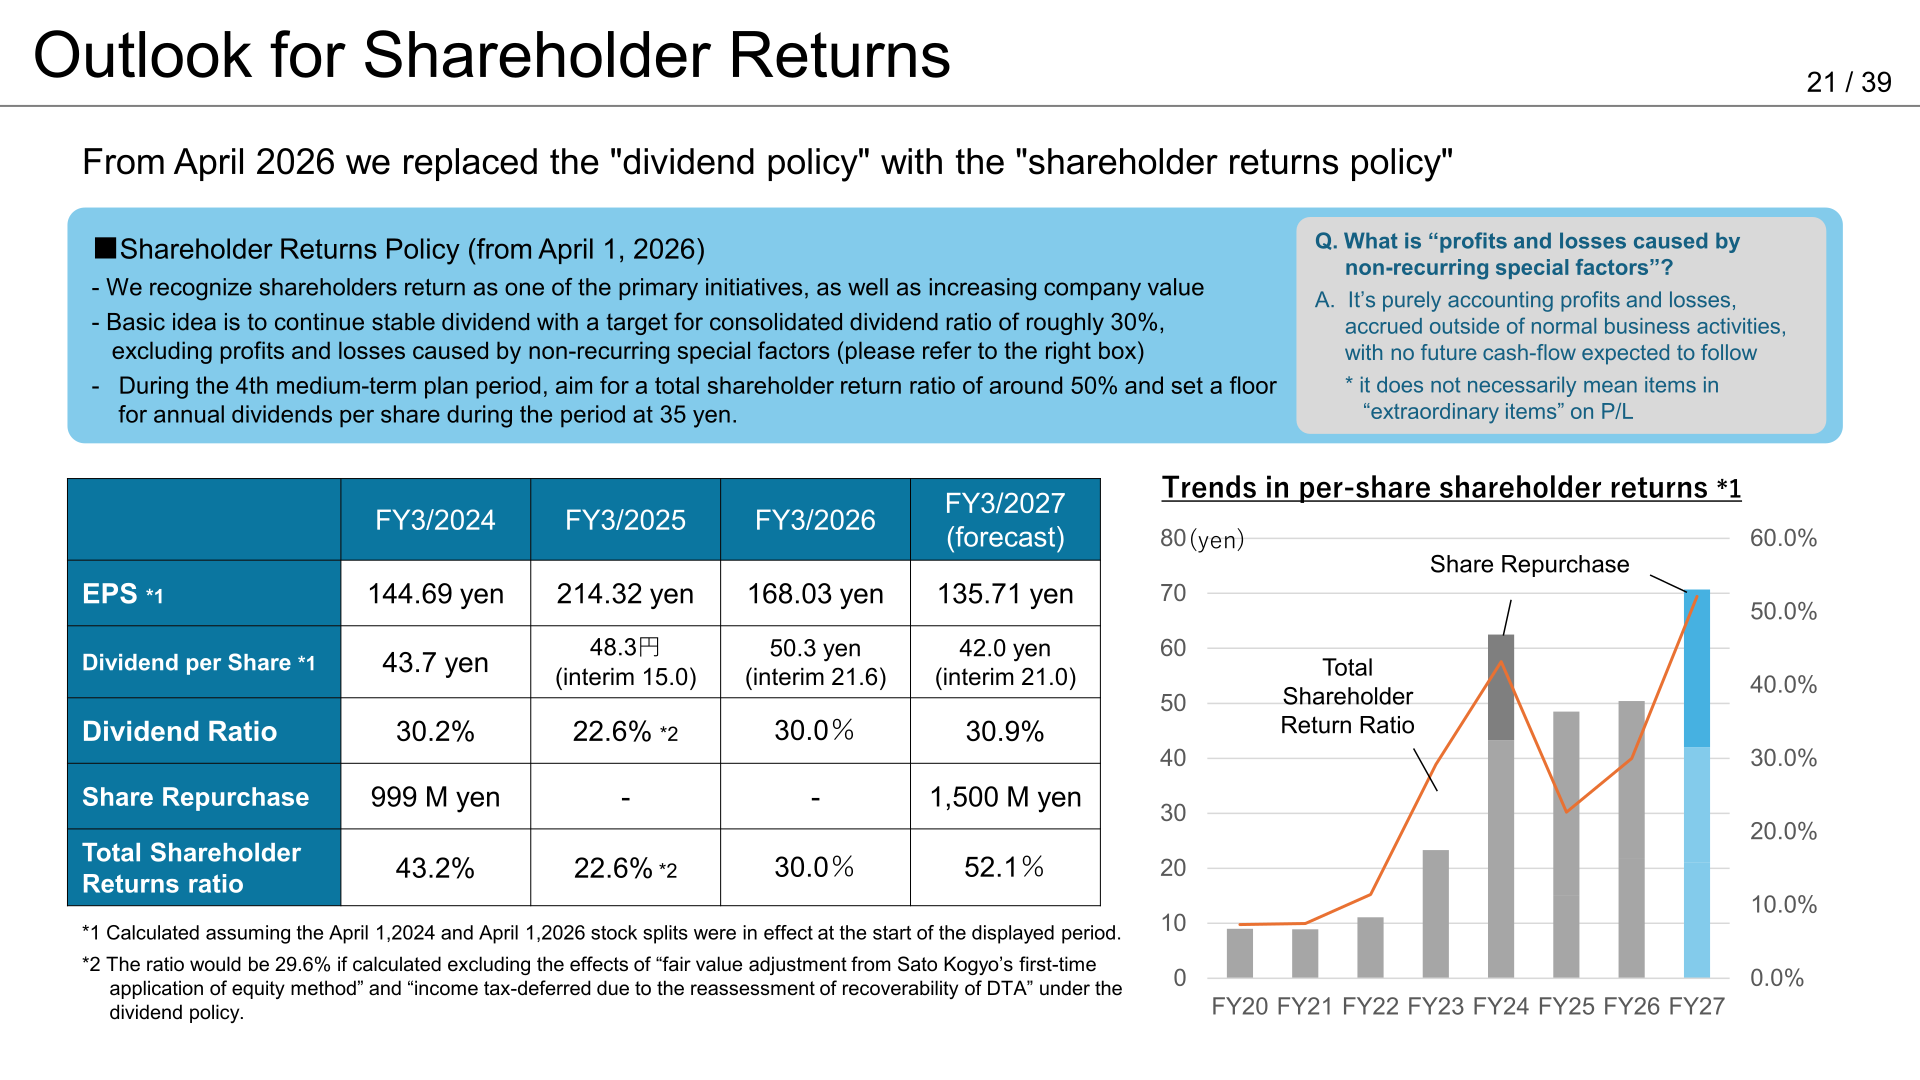
From April 2026, Kawada Technologies replaced its dividend policy with a shareholder returns policy. The basic idea is to continue a stable dividend with a target consolidated dividend ratio of roughly 30%, excluding profits and losses caused by non-recurring special factors, and during the 4th Medium-Term Plan period to aim for a total shareholder return ratio of around 50%, with a floor for annual dividends per share of 35 yen. The company implemented a 1-for-3 ordinary share split effective April 1, 2026, and is conducting a share repurchase of up to 1.5 billion yen with an acquisition period from April 1, 2026 to June 24, 2026. Per-share figures below are calculated assuming the April 1, 2024 and April 1, 2026 stock splits were in effect at the start of the displayed period.
| Indicator | FY3/2027 (forecast) | FY3/2026 | FY3/2025 |
|---|---|---|---|
| EPS | 135.71 yen | 168.03 yen | 214.32 yen |
| Dividend per Share | 42.0 yen (interim 21.0) | 50.3 yen (interim 21.6) | 48.3 yen (interim 15.0) |
| Dividend Ratio | 30.9% | 30.0% | 22.6% |
| Share Repurchase | 1,500 M yen | – | – |
| Total Shareholder Returns ratio | 52.1% | 30.0% | 22.6% |
The company notes that the FY3/2025 ratio would be 29.6% if calculated excluding the effects of the fair value adjustment from Sato Kogyo’s first-time application of the equity method and income tax-deferred due to the reassessment of recoverability of deferred tax assets under the dividend policy.
The 4th Medium-Term Management Plan
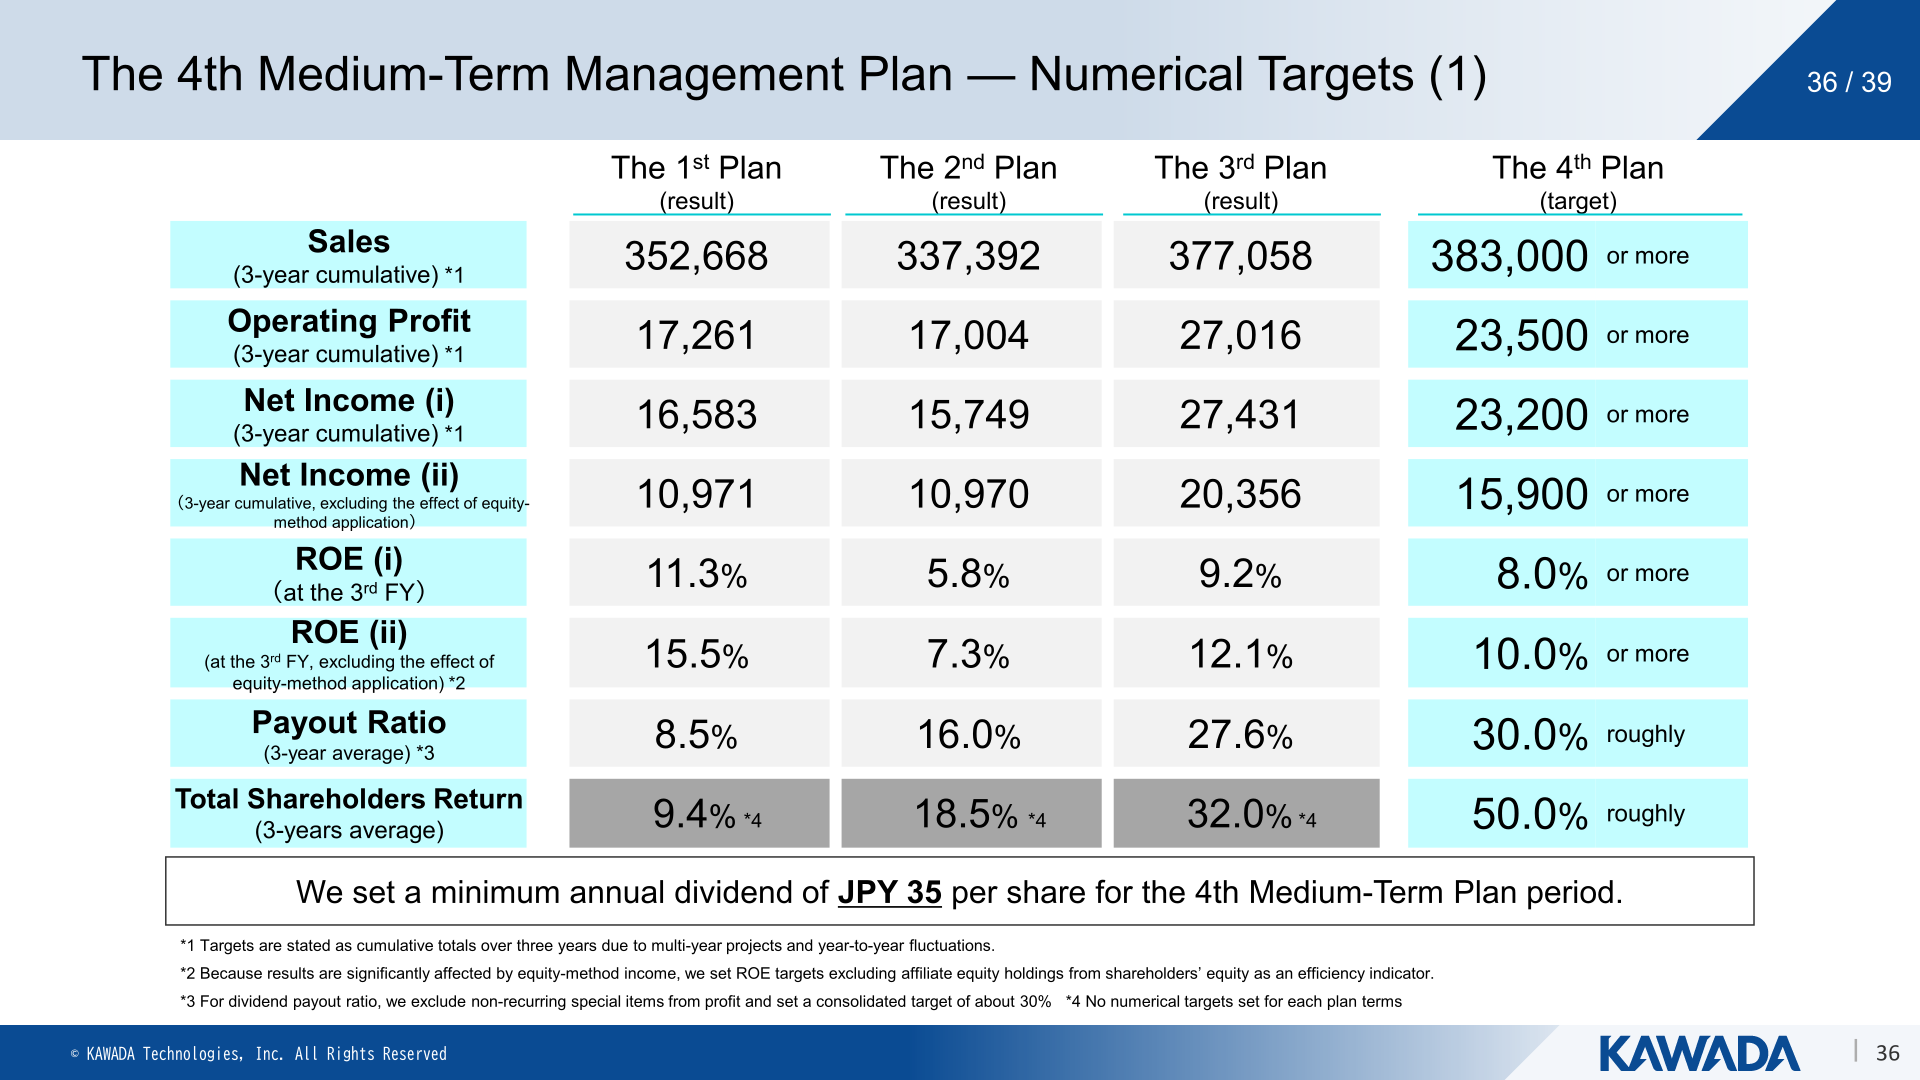
Under the 3rd Medium-Term Management Plan, three-year cumulative sales of 377,058 million yen reached 96.4% of the initial target, while cumulative operating profit of 27,016 million yen (145.3%) and net income of 27,431 million yen (175.8%) exceeded targets, and ROE in the third year was 9.2%. The 4th Medium-Term Management Plan, announced on May 12, 2026, focuses on business portfolio reform, with basic policies of strengthening ambidextrous management across core and growth businesses, “Kawada’s Unique” technology development combining “Construction” x “Robotics”, evolution of sustainability management, and deepening capital efficiency and enhancing shareholder returns. The company aims for JPY 150 billion in revenue by FY2030 and JPY 200 billion in the medium to long term.
| Target (3-year cumulative unless stated, million yen) | The 4th Plan (target) | The 3rd Plan (result) |
|---|---|---|
| Sales | 383,000 or more | 377,058 |
| Operating Profit | 23,500 or more | 27,016 |
| Net Income (i) | 23,200 or more | 27,431 |
| Net Income (ii) (excluding the effect of equity-method application) | 15,900 or more | 20,356 |
| ROE (i) (at the 3rd FY) | 8.0 % or more | 9.2 % |
| ROE (ii) (at the 3rd FY, excluding the effect of equity-method application) | 10.0 % or more | 12.1 % |
| Payout Ratio (3-year average) | 30.0 % roughly | 27.6 % |
| Total Shareholders Return (3-year average) | 50.0 % roughly | 32.0 % |
The cash allocation plan for the period envisages operating cash flow of 25B yen, with business investment of 12.5B yen (capital investment of 9.5B yen and growth investment of 3.0B yen), shareholder returns of 12B yen and repayment of debt, etc. of 0.5B yen. The company expects the steel bridge and civil engineering businesses to see decreased revenue and profit due to reduced market orders and fewer contract modifications from expressway company projects, while noting that the Osaka Bay Coastal Road West Extension, if awarded, would contribute to sales from the final year of the plan; Solution is expected to grow sales and profit through business area expansion. Regarding its equity-method affiliate Sato Kogyo, which represents a large portion of shareholders’ equity, the company says it will further enhance business synergies and continue to request improvements in profitability and capital efficiency.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















