
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Saint Marc Holdings does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials (its most recent full-year results presentation), with figures transcribed as reported. On this site the most recently completed fiscal year is labeled FY2025; for Saint Marc Holdings this is the fiscal year ended March 2026.
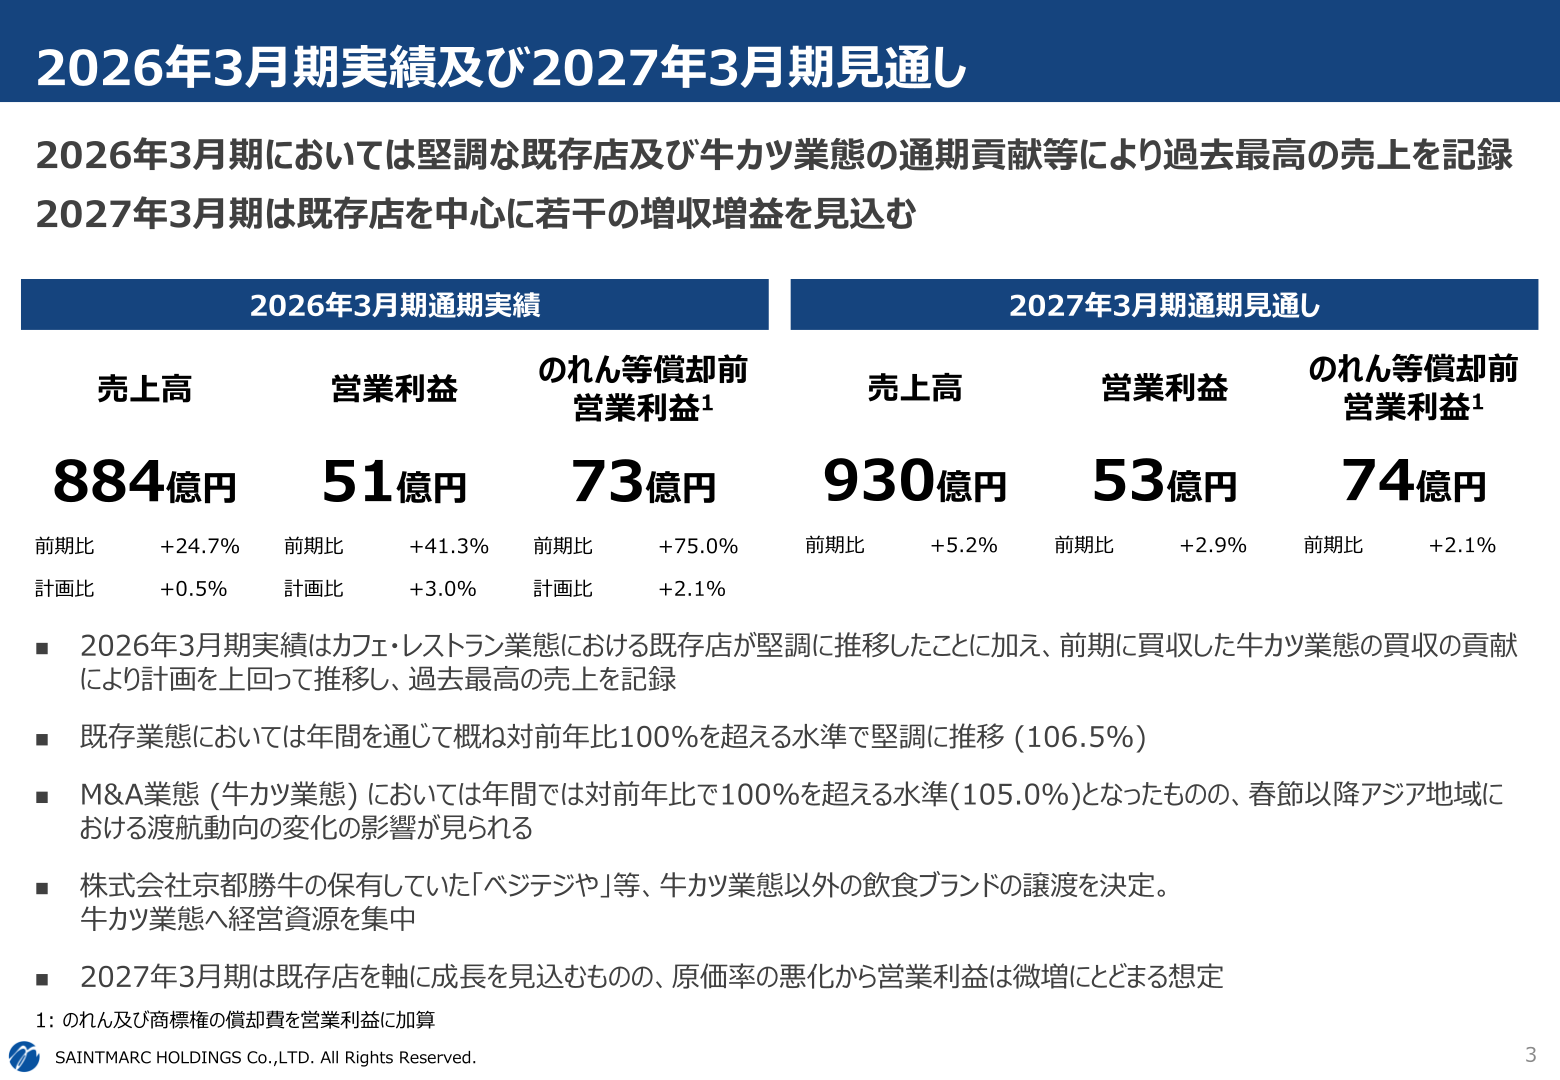
On May 26, 2026, Saint Marc Holdings Co., Ltd. released its results presentation for the fiscal year ended March 2026 (full year). In addition to solid performance at existing stores of its existing formats, the full-year contribution of the gyukatsu (beef cutlet) formats acquired in the previous fiscal year lifted net sales to a record 88.4 billion yen (+24.7% year on year). Operating profit was 5.1 billion yen (+41.3%), operating profit before amortization of goodwill, etc. was 7.3 billion yen (+75.0%), and profit attributable to owners of parent was 2.7 billion yen (+6.5%), for higher sales and higher profit across the board. For the fiscal year ending March 2027, the company expects net sales of 93.0 billion yen (+5.2%), centered on existing stores, while planning only a slight increase in operating profit due to a deterioration in the cost-of-sales ratio.
Consolidated Results (Full-Year Actual)
In the fiscal year ended March 2026, the M&A of the two gyukatsu formats contributed for the full year, resulting in net sales of 88,432 million yen (+24.7% year on year; +0.5% versus plan), operating profit of 5,149 million yen (+41.3%; +3.0% versus plan), and ordinary profit of 5,058 million yen (+31.8%; +5.4% versus plan). With the full contribution of the gyukatsu formats, the cost-of-sales ratio rose +1.9pt from 24.9% to 26.8%, while the SG&A ratio improved △2.5pt from 69.9% to 67.4%. Profit attributable to owners of parent was 2,705 million yen (+6.5%; +17.6% versus plan). The previous fiscal year included a temporary profit boost from the recognition of deferred tax assets (0.82 billion yen), making for a high bar for comparison, but the company ultimately landed above the previous year’s level.
| Item (million yen) | FY ended Mar 2026 | FY ended Mar 2025 | Change |
|---|---|---|---|
| Net sales | 88,432 | 70,895 | +24.7% |
| Cost of sales | 23,699 | 17,686 | +34.0% |
| Operating profit before amortization of goodwill, etc. | 7,334 | 4,189 | +75.0% |
| Operating profit | 5,149 | 3,644 | +41.3% |
| Ordinary profit | 5,058 | 3,839 | +31.8% |
| Profit attributable to owners of parent | 2,705 | 2,540 | +6.5% |
Results by Business (Restaurant / Café)
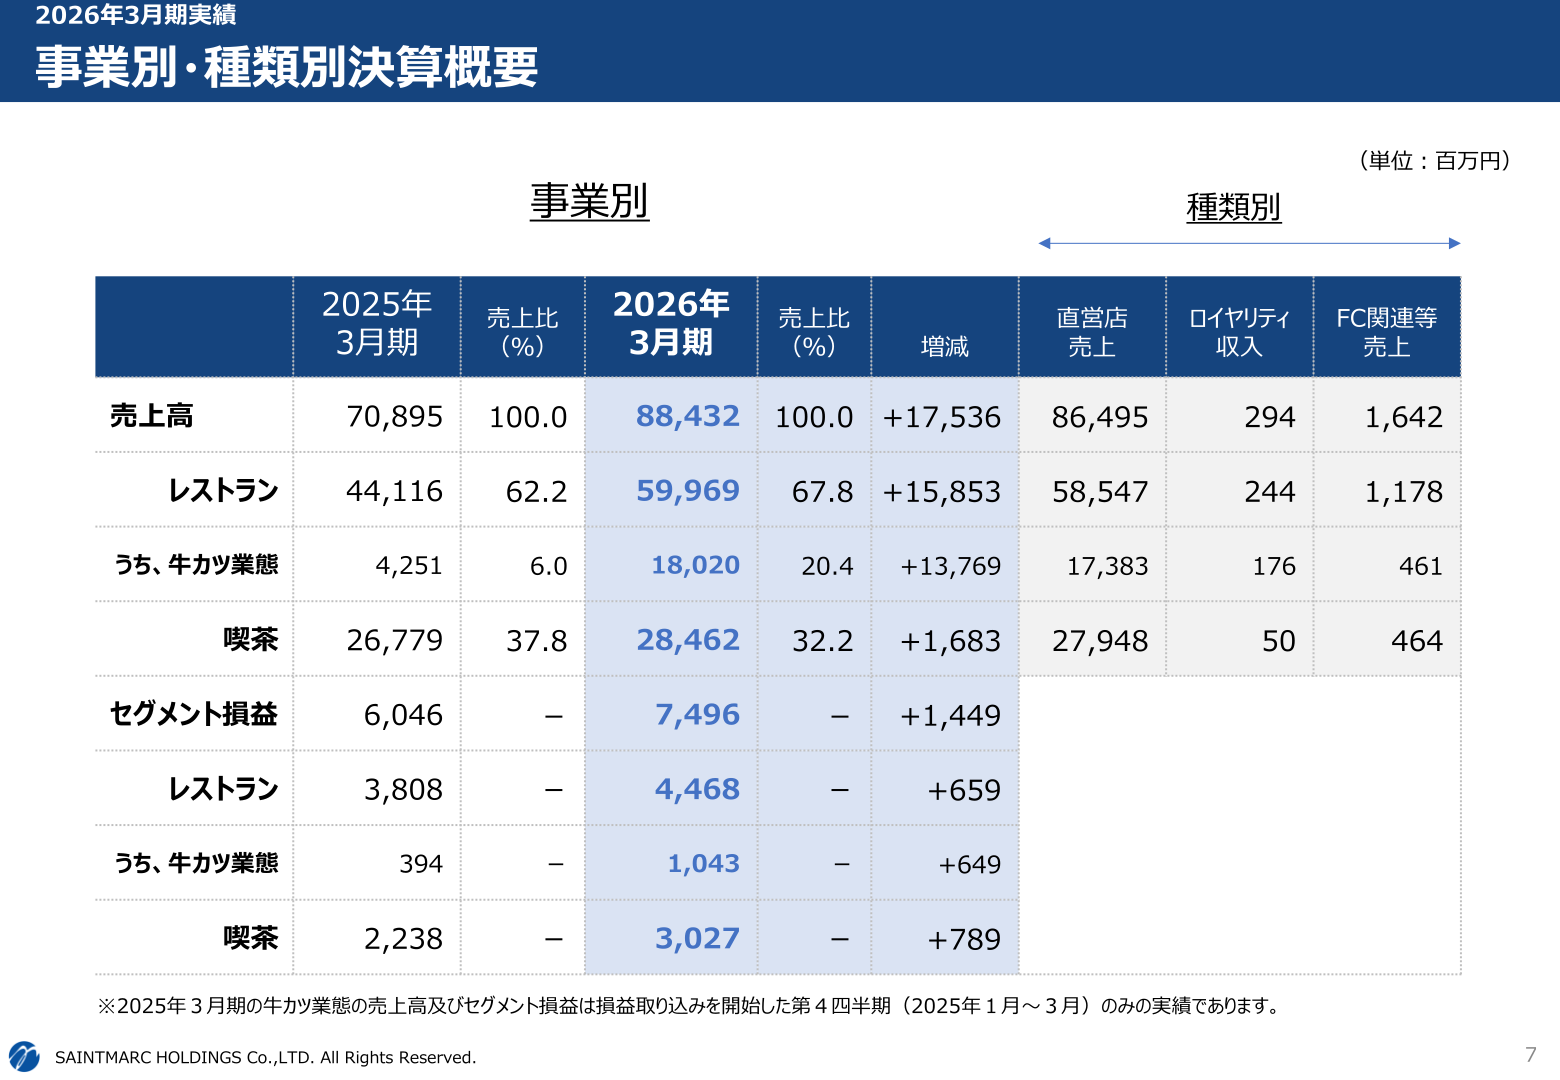
By business and type, net sales of the Restaurant business were 59,969 million yen (67.8% of sales; +15,853 million yen year on year), of which the gyukatsu formats accounted for 18,020 million yen (20.4% of sales; +13,769 million yen year on year). The Café business posted 28,462 million yen (32.2% of sales; +1,683 million yen year on year). Segment profit was 7,496 million yen company-wide (+1,449 million yen year on year), with Restaurant at 4,468 million yen (+659 million yen, of which the gyukatsu formats contributed 1,043 million yen, +649 million yen) and Café at 3,027 million yen (+789 million yen). Note that the previous fiscal year’s figures for the gyukatsu formats cover only the fourth quarter (January–March 2025), when the company began consolidating their results.
| Category | Metric | FY ended Mar 2026 | FY ended Mar 2025 |
|---|---|---|---|
| Company-wide | Net sales | 88,432 | 70,895 |
| Restaurant | Net sales | 59,969 | 44,116 |
| of which, gyukatsu formats | Net sales | 18,020 | 4,251 |
| Café | Net sales | 28,462 | 26,779 |
| Company-wide | Segment profit | 7,496 | 6,046 |
| Restaurant | Segment profit | 4,468 | 3,808 |
| of which, gyukatsu formats | Segment profit | 1,043 | 394 |
| Café | Segment profit | 3,027 | 2,238 |
Full-Year Forecast
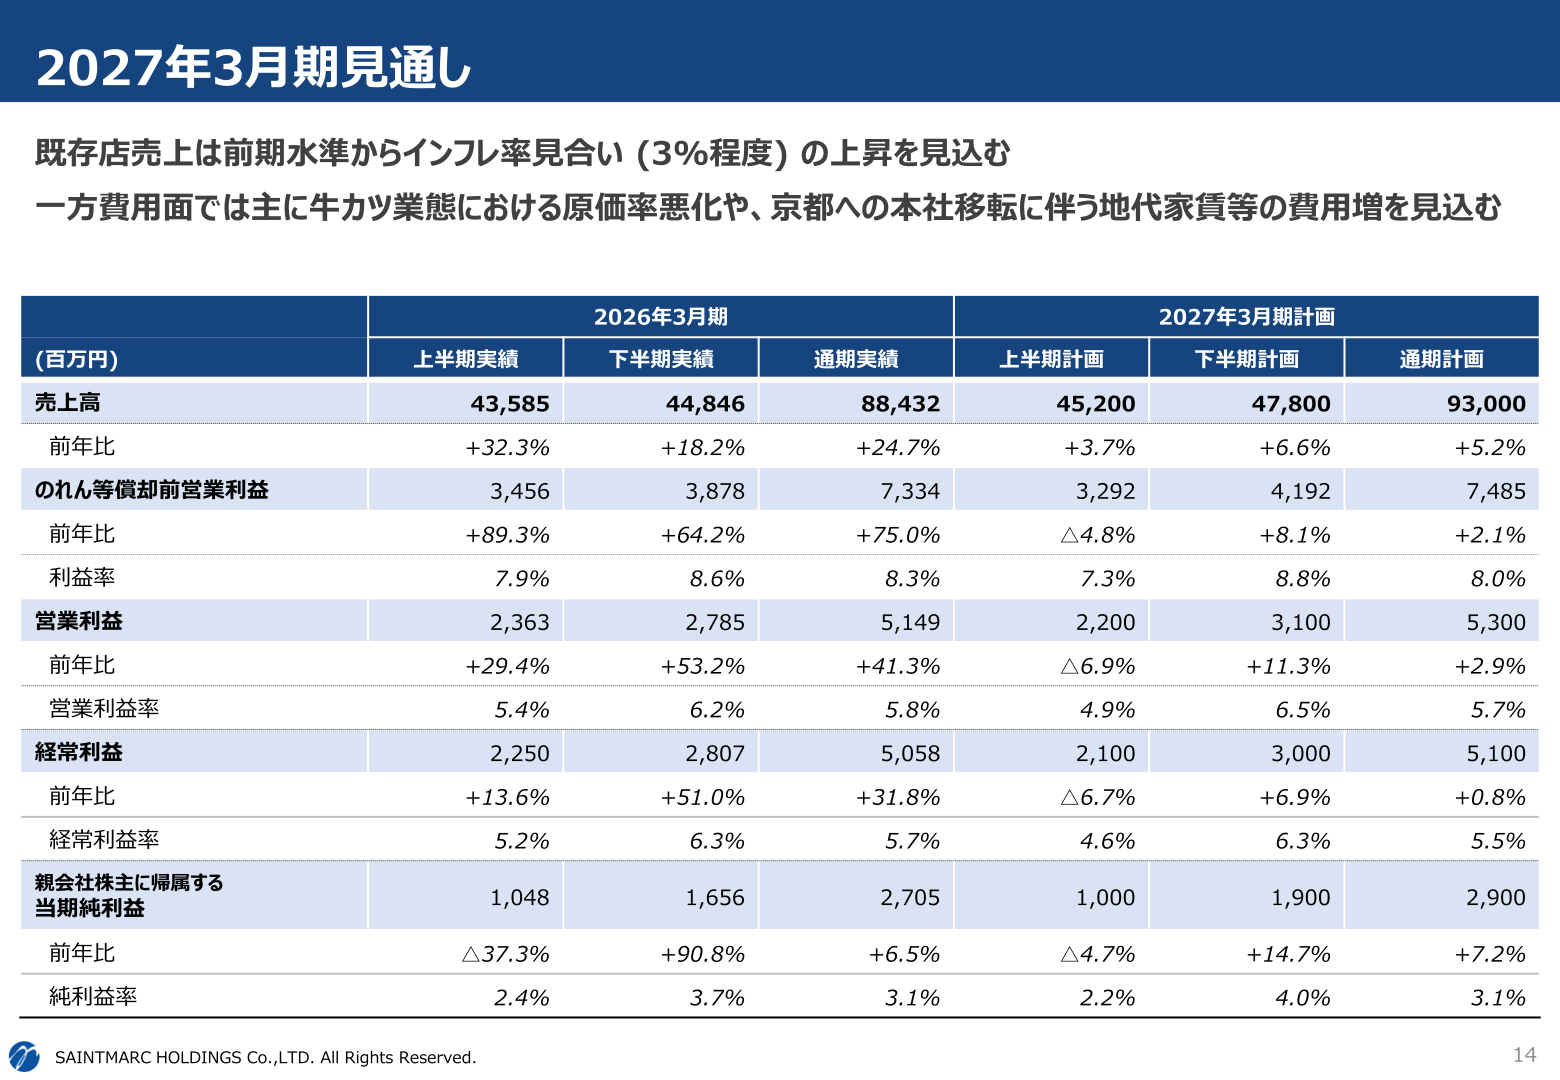
For the fiscal year ending March 2027, the company expects existing-store sales to rise in line with inflation (around 3%), while anticipating a deterioration in the cost-of-sales ratio, mainly in the gyukatsu formats, and higher costs such as rent associated with relocating its head office to Kyoto. The full-year plan calls for net sales of 93,000 million yen (+5.2% year on year), operating profit before amortization of goodwill, etc. of 7,485 million yen (+2.1%), operating profit of 5,300 million yen (+2.9%), ordinary profit of 5,100 million yen (+0.8%), and profit attributable to owners of parent of 2,900 million yen (+7.2%).
| Item (million yen) | FY ending Mar 2027 Plan | FY ended Mar 2026 Actual | YoY |
|---|---|---|---|
| Net sales | 93,000 | 88,432 | +5.2% |
| Operating profit before amortization of goodwill, etc. | 7,485 | 7,334 | +2.1% |
| Operating profit | 5,300 | 5,149 | +2.9% |
| Ordinary profit | 5,100 | 5,058 | +0.8% |
| Profit attributable to owners of parent | 2,900 | 2,705 | +7.2% |
Shareholder Returns
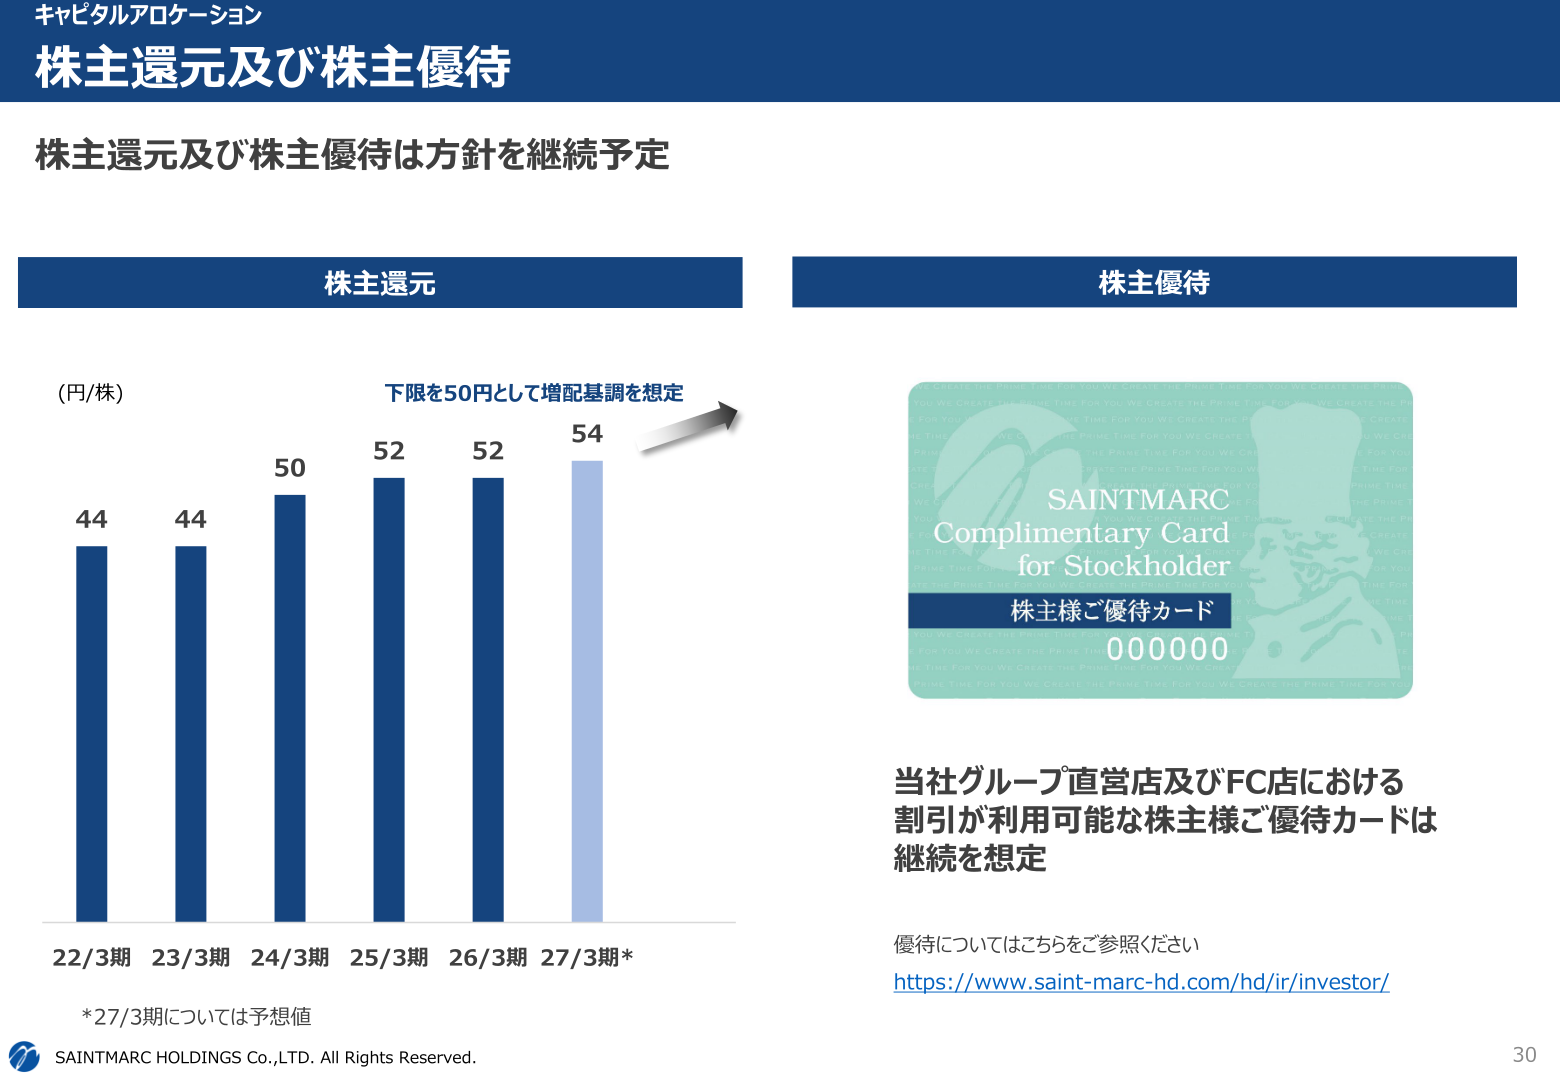
The company assumes a trend of dividend increases with a floor of 50 yen, and forecasts an annual dividend per share of 54 yen for FY3/27. As for shareholder benefits, it assumes continuation of the shareholder benefit card, which offers discounts at directly operated and franchise stores.
| Fiscal year | Dividend per share (yen) |
|---|---|
| FY3/22 | 44 |
| FY3/23 | 44 |
| FY3/24 | 50 |
| FY3/25 | 52 |
| FY3/26 | 52 |
| FY3/27 (forecast) | 54 |
Medium-Term Plan / Topics
The company revised the targets of its medium-term management plan in November 2025 to reflect the M&A of the gyukatsu formats and the progress of its existing businesses, and now targets net sales of 100.0 billion yen and operating profit before amortization of goodwill, etc. of 9.0 billion yen for FY3/29. For the gyukatsu formats (Kyoto Katsugyu and Gyukatsu Motomura), it assumes a potential domestic market of around 150 to 200 stores and plans to continue franchise expansion overseas as well. Meanwhile, brands held by Kyoto Katsugyu other than the gyukatsu formats (such as “Vegetejiya”) will be transferred to ATC Dining, concentrating management resources on the gyukatsu formats. The company is also relocating its head office from Okayama Prefecture to Kyoto Prefecture, and expects approximately 0.17 billion yen in costs that will continue from the next fiscal year onward and approximately 0.07 billion yen in one-time costs, while expecting to recover approximately 0.15 billion yen through the disposal of certain assets.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















