
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Sanyo Trading does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials, with figures transcribed as reported. Sanyo Trading has a September fiscal year-end, so figures labeled FY2025 refer to the fiscal year ended September 30, 2025, the most recent completed full year.
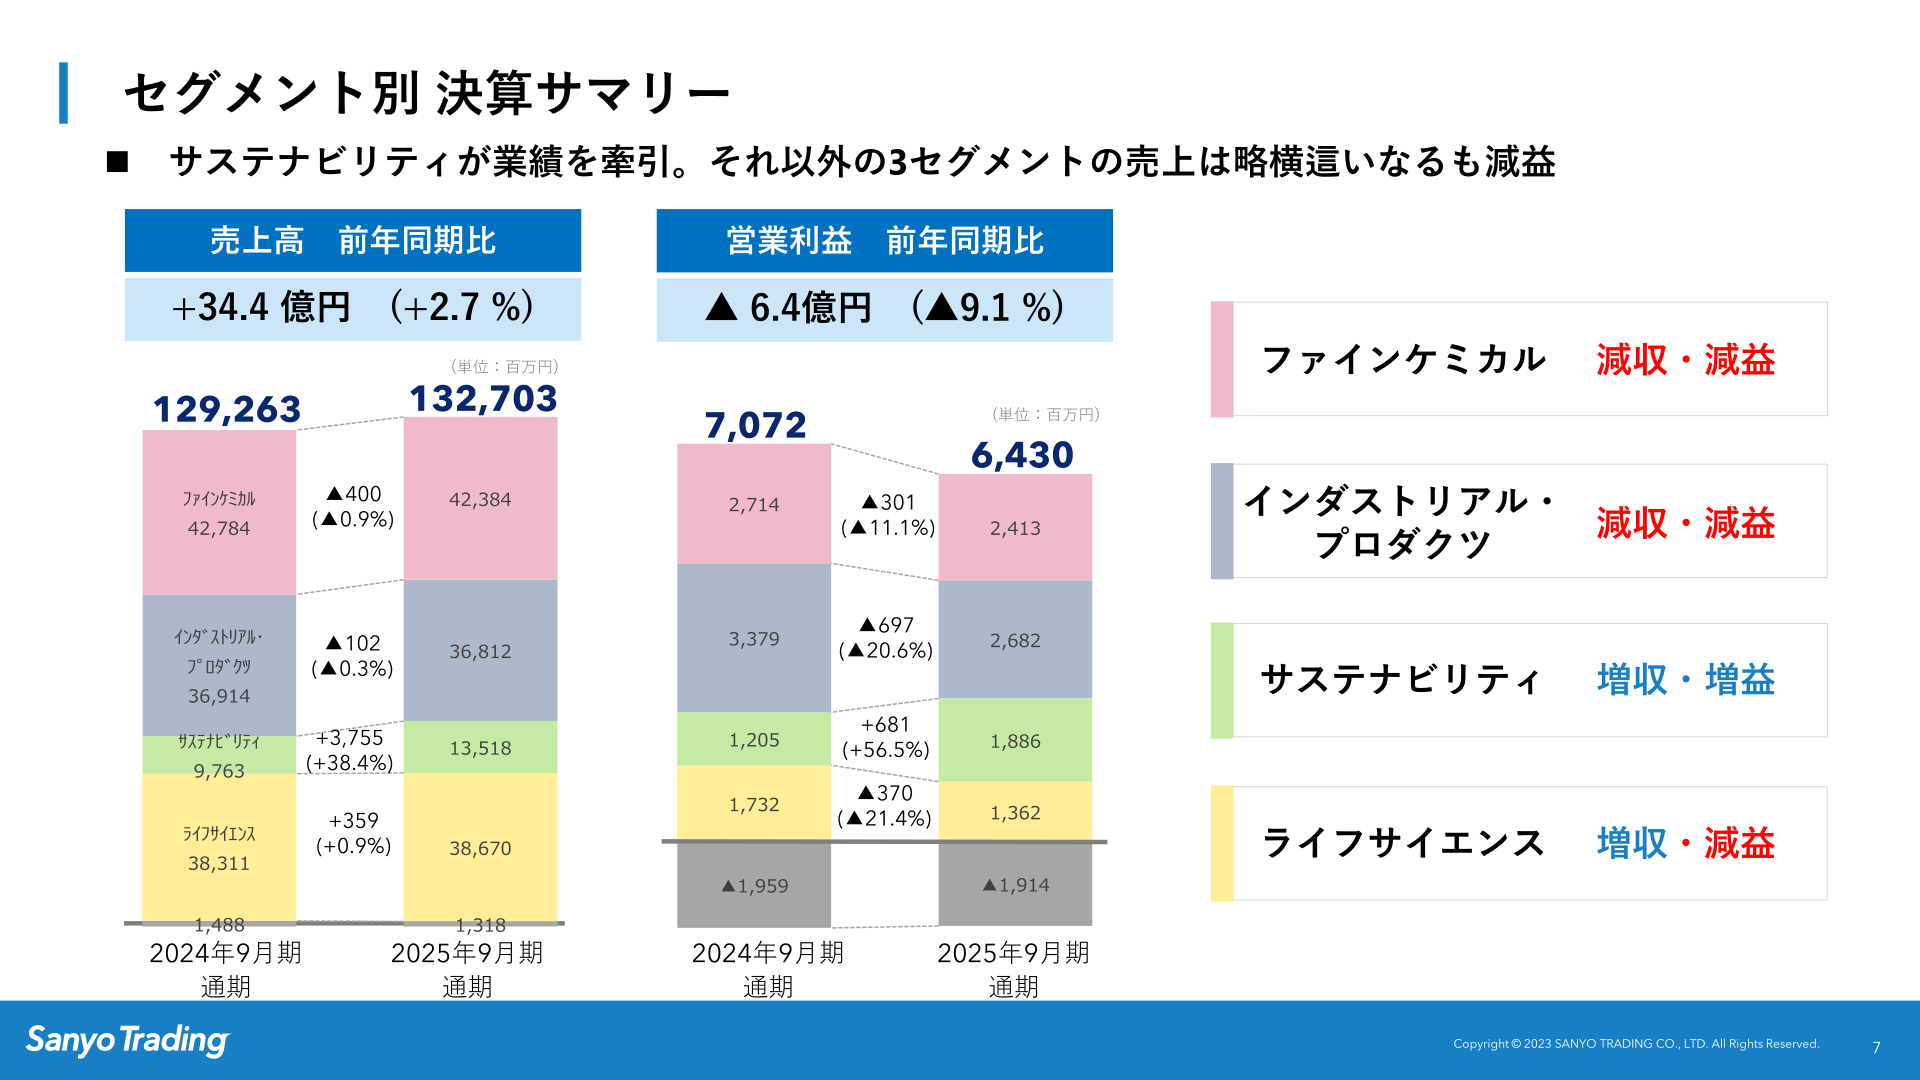
On November 17, 2025, Sanyo Trading announced its consolidated results for the fiscal year ended September 30, 2025. Net sales came to 132,703 million yen (+2.7% year on year) and gross profit to 22,564 million yen (+1.5% YoY), both setting record highs. Operating profit, however, declined to 6,430 million yen (▲9.1% YoY) on higher headcount and IT-related investment, recurring profit fell to 6,879 million yen (▲13.0% YoY) owing partly to lump-sum amortization of goodwill, and net income attributable to owners of the parent decreased to 4,615 million yen (▲11.4% YoY), all down year on year.
Consolidated Results (FY2025 Actual)
Net sales and gross profit were maintained at high levels, but selling, general and administrative expenses expanded to 16,133 million yen (+6.4% YoY) on higher personnel costs, increased depreciation from the new core IT system, and greater sales-promotion spending associated with business development, which weighed on operating profit. Against the initial forecast (net sales of 132,000 million yen and operating profit of 7,100 million yen), net sales exceeded the forecast, while operating profit, recurring profit, and net income all fell short of the initial forecast.
| Item | FY2025 (ended Sep 2025) | FY2024 (ended Sep 2024) | YoY |
|---|---|---|---|
| Net sales | 132,703 million yen | 129,263 million yen | +2.7% |
| Gross profit (gross margin) | 22,564 million yen (17.0%) | 22,229 million yen (17.2%) | +1.5% |
| SG&A expenses | 16,133 million yen | 15,156 million yen | +6.4% |
| Operating profit (operating margin) | 6,430 million yen (4.8%) | 7,072 million yen (5.5%) | ▲9.1% |
| Recurring profit (recurring margin) | 6,879 million yen (5.2%) | 7,905 million yen (6.1%) | ▲13.0% |
| Net income attributable to owners of the parent | 4,615 million yen | 5,207 million yen | ▲11.4% |
| EPS | 160.23 yen | 180.88 yen | – |
Segment Results
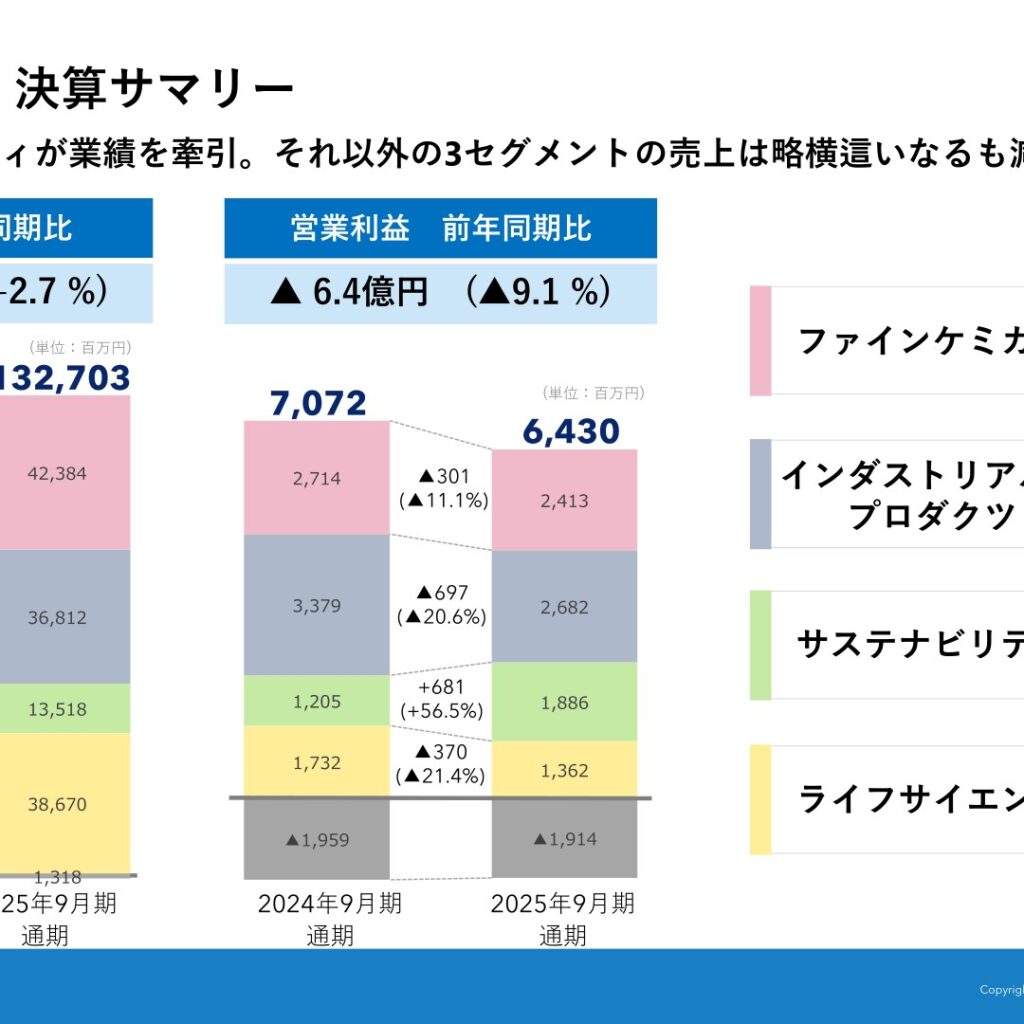
By segment, Sustainability drove earnings, with net sales of 13,518 million yen (+38.4% YoY) and operating profit of 1,886 million yen (+56.5% YoY). This was supported by the booking of a large project in the woody biomass-related business, strong momentum in ocean development centered on marine survey equipment and materials, and firm demand for geothermal-related equipment. On the other hand, Life Science saw operating profit decline to 1,362 million yen (▲21.4% YoY) due to the termination of a distributorship agreement for bio-related instruments, while Fine Chemicals and Industrial Products also posted lower profits despite broadly flat sales.
| Segment | Net sales (FY2025) | YoY | Operating profit (FY2025) | YoY |
|---|---|---|---|---|
| Fine Chemicals | 42,384 million yen | ▲0.9% | 2,413 million yen | ▲11.1% |
| Industrial Products | 36,812 million yen | ▲0.3% | 2,682 million yen | ▲20.6% |
| Sustainability | 13,518 million yen | +38.4% | 1,886 million yen | +56.5% |
| Life Science | 38,670 million yen | +0.9% | 1,362 million yen | ▲21.4% |
Results by Region
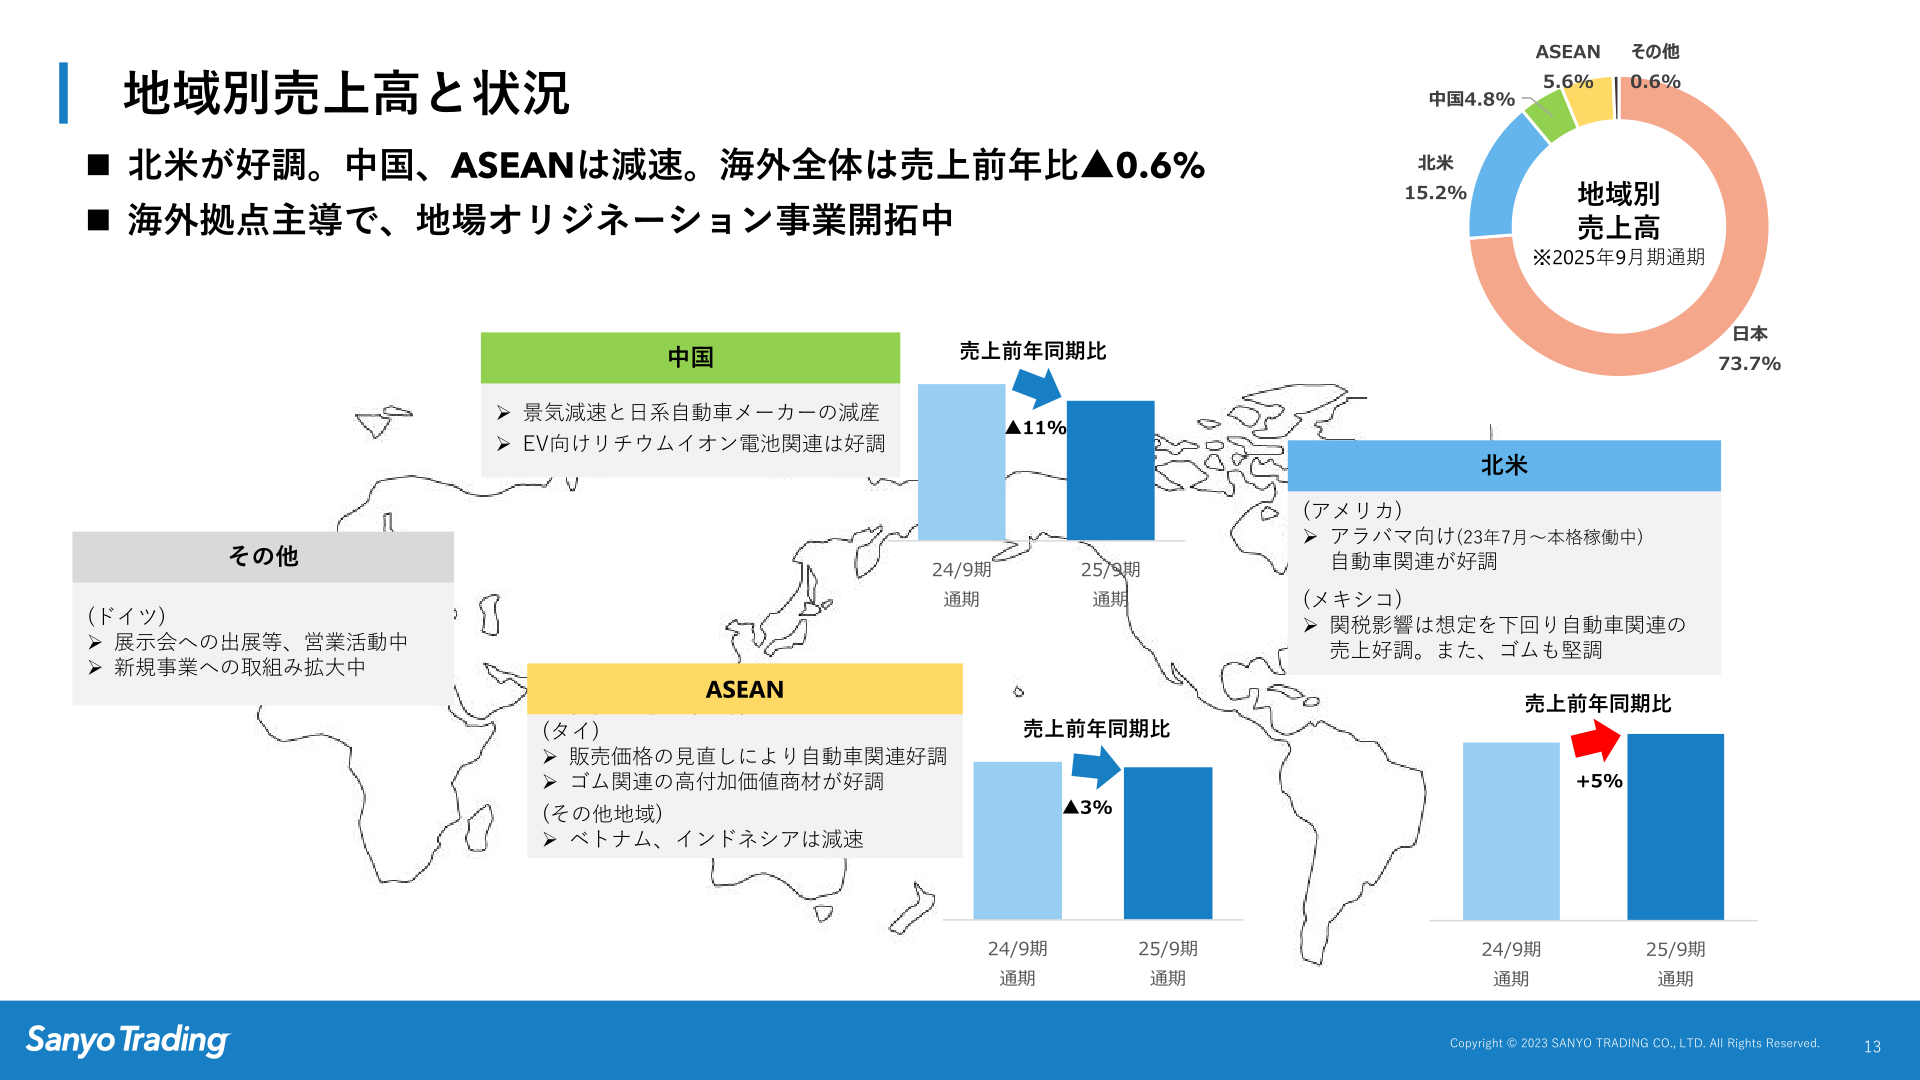
By region, the composition of net sales for FY2025 was Japan 73.7%, North America 15.2%, China 4.8%, ASEAN 5.6%, and Other 0.6%. North America grew +5% year on year on strong automotive-related demand, while China fell ▲11% amid an economic slowdown and production cuts by Japanese automakers, and ASEAN declined ▲3% on slowdowns in Vietnam and Indonesia. Overall overseas sales were ▲0.6% year on year.
Full-Year Forecast (FY ending September 2026)
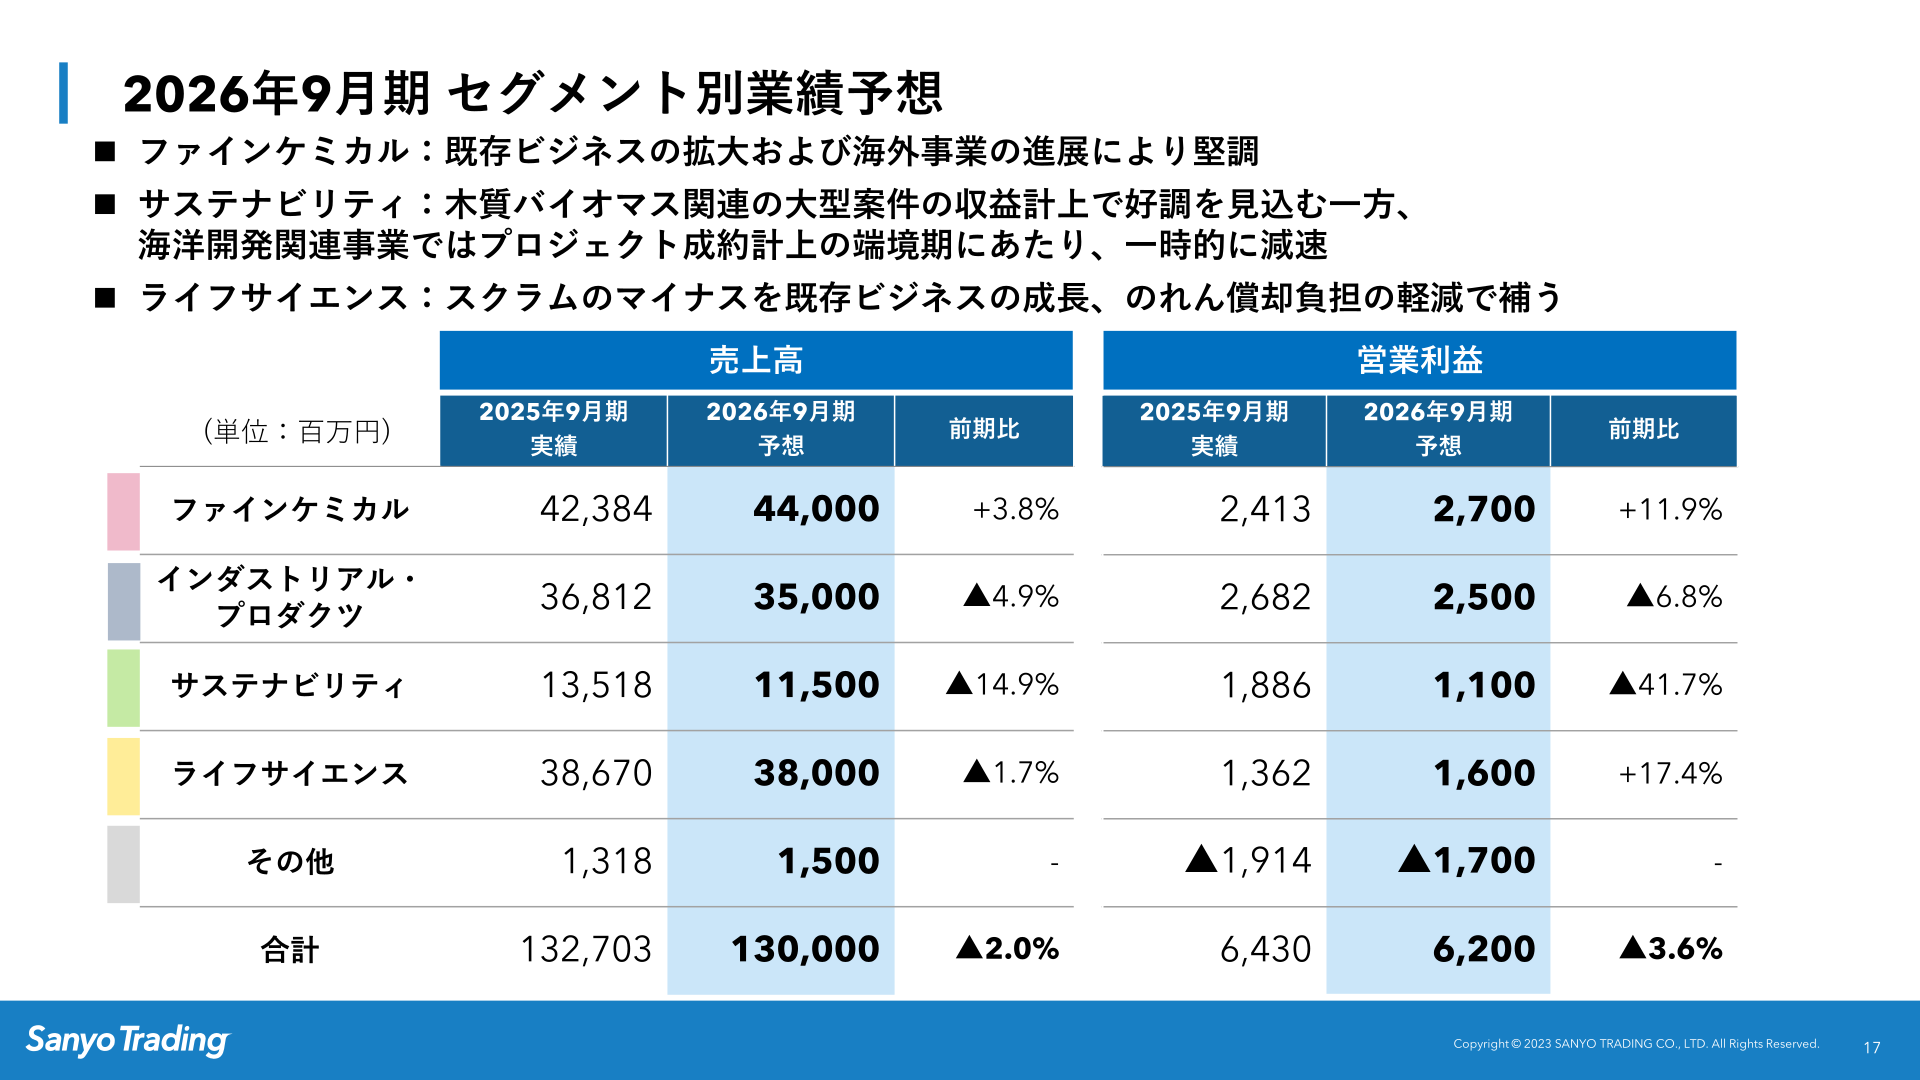
The company expects the fiscal year ending September 2026 to be a pause, reflecting upfront growth investment and the timing of business monetization. It forecasts net sales of 130,000 million yen (▲2.0% YoY), operating profit of 6,200 million yen (▲3.6% YoY), recurring profit of 6,500 million yen (▲5.5% YoY), and net income attributable to owners of the parent of 4,100 million yen (▲11.2% YoY). By segment, Fine Chemicals is expected to post operating profit of 2,700 million yen (+11.9%) on expansion of existing businesses and progress in overseas operations, while Sustainability is forecast at operating profit of 1,100 million yen (▲41.7%), temporarily slowing as ocean-development-related projects fall between contract-booking cycles. Life Science is expected to post operating profit of 1,600 million yen (+17.4%), with the decline at Scrum offset by growth in existing businesses and a lighter goodwill-amortization burden. The company expects new projects to contribute to earnings progressively from the fiscal year ending September 2027 onward.
| Item | FY2026 Forecast (ending Sep 2026) | FY2025 (Actual) | YoY |
|---|---|---|---|
| Net sales | 130,000 million yen | 132,703 million yen | ▲2.0% |
| Operating profit (operating margin) | 6,200 million yen (4.8%) | 6,430 million yen (4.8%) | ▲3.6% |
| Recurring profit (margin) | 6,500 million yen (5.0%) | 6,879 million yen (5.2%) | ▲5.5% |
| Net income attributable to owners of the parent | 4,100 million yen | 4,615 million yen | ▲11.2% |
| EPS | 142.31 yen | 160.23 yen | – |
SANYO VISION 2028 Progress
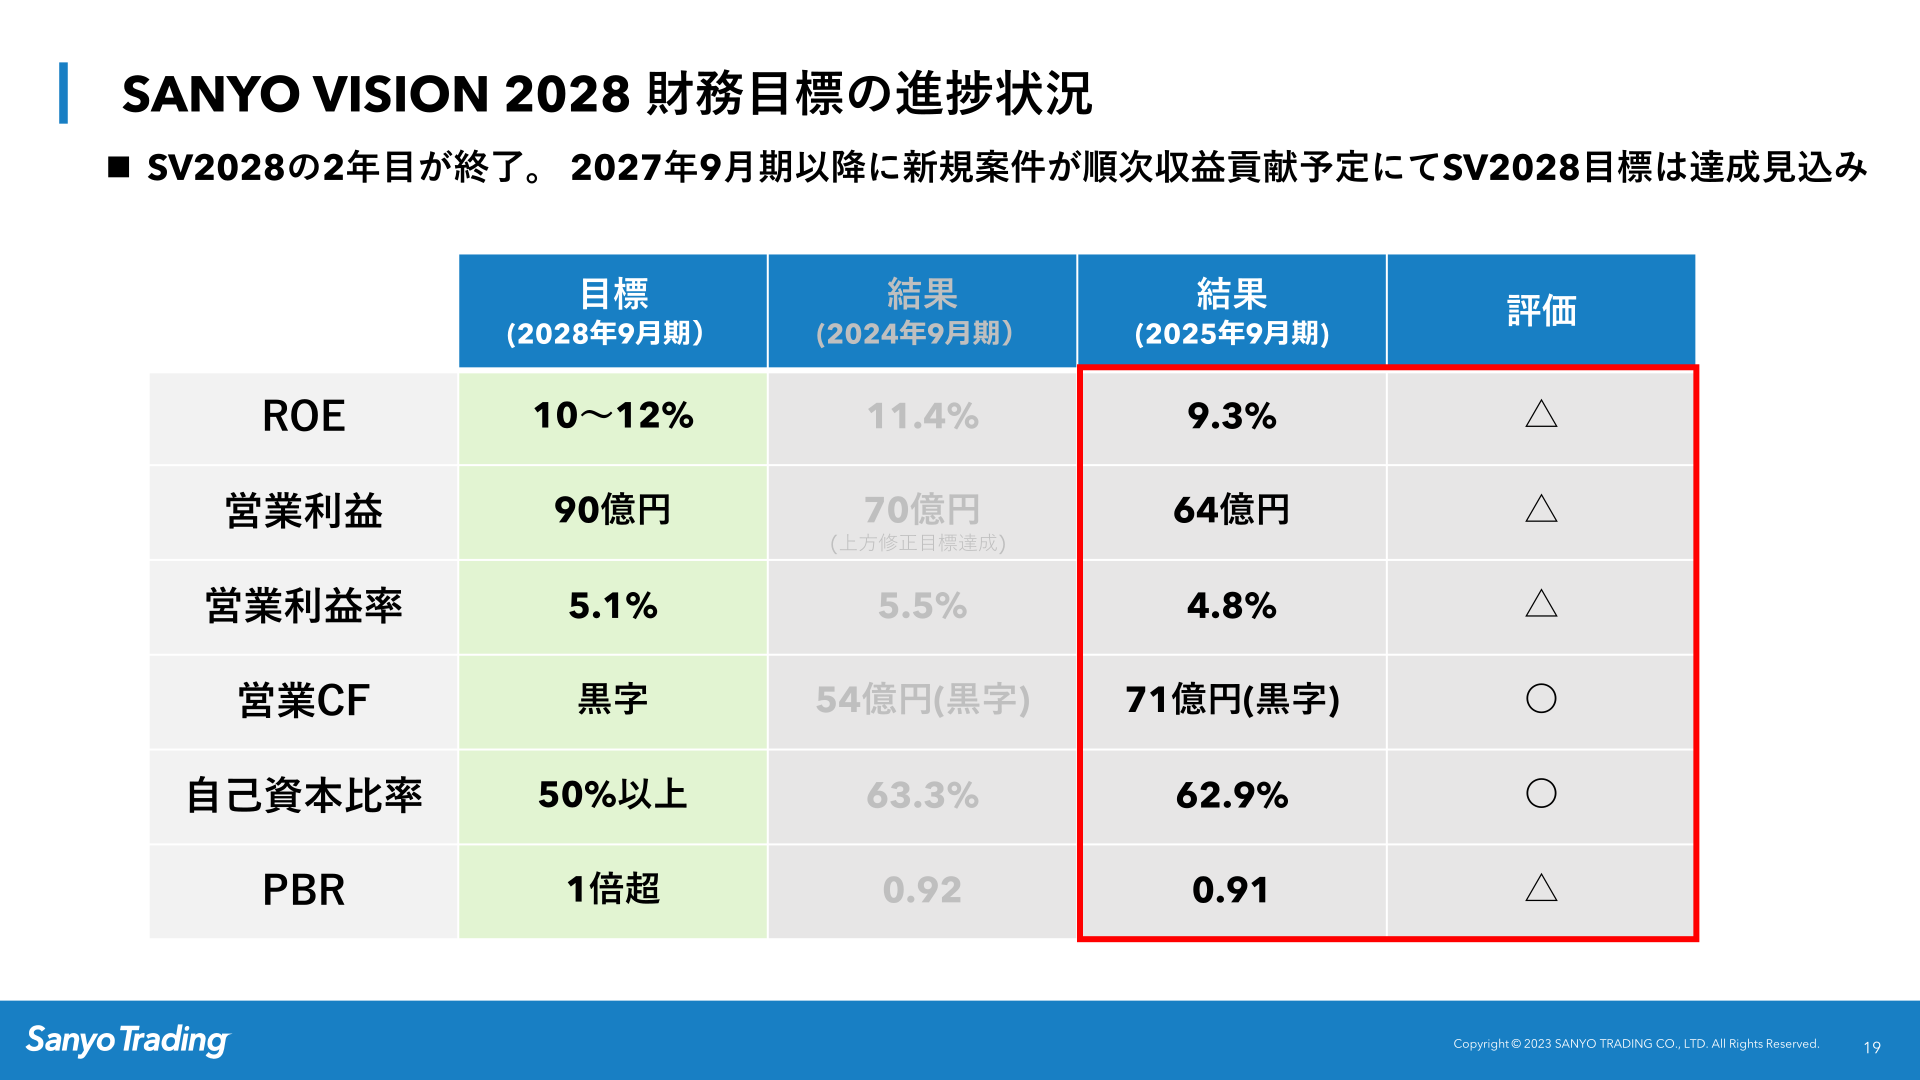
The five-year long-term management plan ‘SANYO VISION 2028,’ announced in November 2023, has completed its second year. Against the FY2028 (ending September 2028) targets, FY2025 results were ROE of 9.3% (target 10-12%), operating profit of 6.4 billion yen (target 9.0 billion yen), and an operating margin of 4.8% (target 5.1%), each rated ‘△.’ Meanwhile, operating cash flow was a positive 7.1 billion yen (target: positive) and the equity ratio was 62.9% (target 50% or more), both maintaining a ‘○’ rating, while PBR was 0.91x (target above 1x), rated ‘△.’ The company plans for new projects to contribute to earnings progressively from the fiscal year ending September 2027 onward and expects to achieve its operating profit target of 9.0 billion yen.
| Metric | Target (FY2028) | FY2024 result | FY2025 result | Rating |
|---|---|---|---|---|
| ROE | 10-12% | 11.4% | 9.3% | △ |
| Operating profit | 9.0 billion yen | 7.0 billion yen | 6.4 billion yen | △ |
| Operating margin | 5.1% | 5.5% | 4.8% | △ |
| Operating CF | Positive | 5.4 billion yen (positive) | 7.1 billion yen (positive) | ○ |
| Equity ratio | 50% or more | 63.3% | 62.9% | ○ |
| PBR | Above 1x | 0.92 | 0.91 | △ |
Shareholder Returns
The company’s basic policy is a payout ratio of 30% or more together with a progressive dividend, and it has maintained stable dividends for 13 consecutive years since its listing. It also states that it will flexibly consider share buybacks, taking into account share-price levels and funding needs for growth investment. Annual dividends were 55 yen in FY2024 (payout ratio 30.4%) and 57 yen in FY2025 (payout ratio 36.6%), and the company forecasts 58 yen for FY2026.
Topics
On the investment front, aiming to expand into the automotive aftermarket, the company acquired all shares of EMAS SUPPLIES & SERVICES PTE LTD, a Singapore-based trading company specializing in automotive air-conditioning parts (share transfer executed on October 1, 2025). It also opened a branch in the Republic of Korea, a promising market for its Life Science business, and began operations there in October 2025. In addition, through a business alliance with Korea’s KORBON CO., LTD., it acquired convertible bonds issued by that company (acquired on October 30, 2025) and obtained exclusive distribution rights in Japan for single-walled carbon nanotubes (SWCNT).
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















