
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note on fiscal-year labels: this article covers HARD OFF CORPORATION’s most recent completed fiscal year, the year ended March 31, 2026, which this site classifies as FY2025; the company labels it “FY 2026” and its own labels are kept unchanged in the text, tables and segment data below.
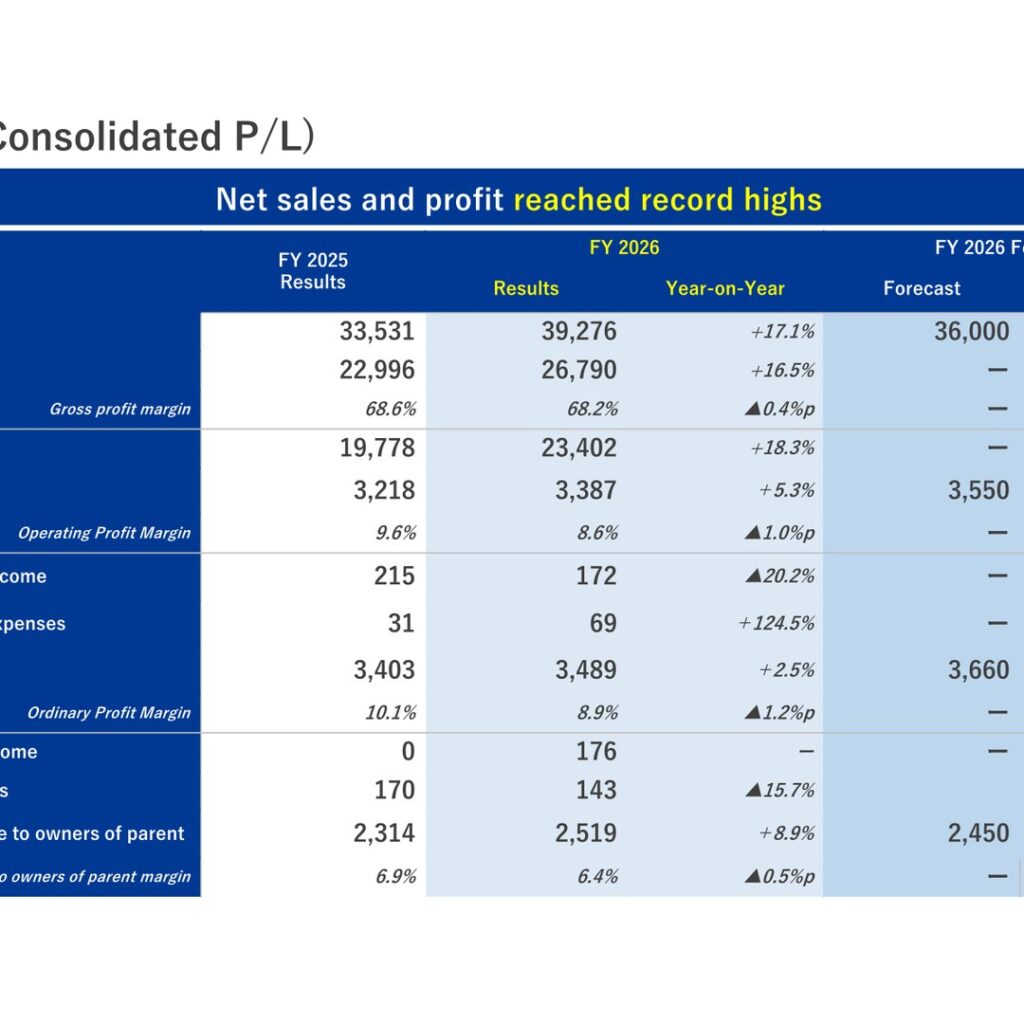
HARD OFF CORPORATION Co., Ltd. (TSE Prime: 2674) reported net sales of 39,276 million yen for the fiscal year ended March 2026 (FY 2026), up 17.1% year on year, with the company noting this marked the 30th consecutive year of sales growth and a record high. Operating profit rose 5.3% to 3,387 million yen, ordinary profit rose 2.5% to 3,489 million yen and profit attributable to owners of parent rose 8.9% to 2,519 million yen — each a record high for the fourth consecutive period, according to the presentation. Growth was driven by the contribution of 24 stores opened in the previous year, 30 new stores in the year under review, and the consolidation of ECONOS Co., Ltd. (69 stores) from the third quarter. For the fiscal year ending March 2027 (FY 2027), the company forecasts net sales of 45,700 million yen and ordinary profit of 4,100 million yen.
Consolidated Results (Full-Year Actual)
Net sales of 39,276 million yen came in at 109.1% of the company’s own 36,000 million yen forecast, and profit attributable to owners of parent at 102.8% of its 2,450 million yen forecast, while operating profit and ordinary profit finished at 95.4% of their respective forecasts. Gross profit margin was 68.2%, down 0.4 percentage points, and operating profit margin was 8.6%, down 1.0 percentage point.
| Item (millions of yen) | FY 2025 Results | FY 2026 Results | Year-on-Year | FY 2026 Forecast | Achievement rate |
|---|---|---|---|---|---|
| Net sales | 33,531 | 39,276 | +17.1% | 36,000 | 109.1% |
| Gross profit | 22,996 | 26,790 | +16.5% | ー | ー |
| Gross profit margin | 68.6% | 68.2% | ▲0.4%p | ー | ー |
| SG & A expenses | 19,778 | 23,402 | +18.3% | ー | ー |
| Operating profit | 3,218 | 3,387 | +5.3% | 3,550 | 95.4% |
| Operating Profit Margin | 9.6% | 8.6% | ▲1.0%p | ー | ー |
| Non-operating income | 215 | 172 | ▲20.2% | ー | ー |
| Non-operating expenses | 31 | 69 | +124.5% | ー | ー |
| Ordinary profit | 3,403 | 3,489 | +2.5% | 3,660 | 95.4% |
| Ordinary Profit Margin | 10.1% | 8.9% | ▲1.2%p | ー | ー |
| Extraordinary income | 0 | 176 | ー | ー | ー |
| Extraordinary loss | 170 | 143 | ▲15.7% | ー | ー |
| Profit attributable to owners of parent | 2,314 | 2,519 | +8.9% | 2,450 | 102.8% |
| Profit attributable to owners of parent margin | 6.9% | 6.4% | ▲0.5%p | ー | ー |
SG&A expenses increased 18.3% to 23,402 million yen, which the company attributes to increased personnel and depreciation costs, opening expenses for 30 new stores, and a one-time charge of 83 million yen related to the tender offer for ECONOS Co., Ltd. Within SG&A, personnel expenses rose 19.1% to 12,939 million yen, depreciation rose 28.8% to 1,115 million yen and rent rose 10.3% to 4,271 million yen. Profit lines were also boosted by a 176 million yen gain on step acquisition related to the consolidation of ECONOS Co., Ltd. Domestic existing-store sales were 104.3% of the prior year for the full year, with quarterly readings of 100.7% in Q1, 102.7% in Q2, 107.3% in Q3 and 106.0% in Q4.
Segment Results
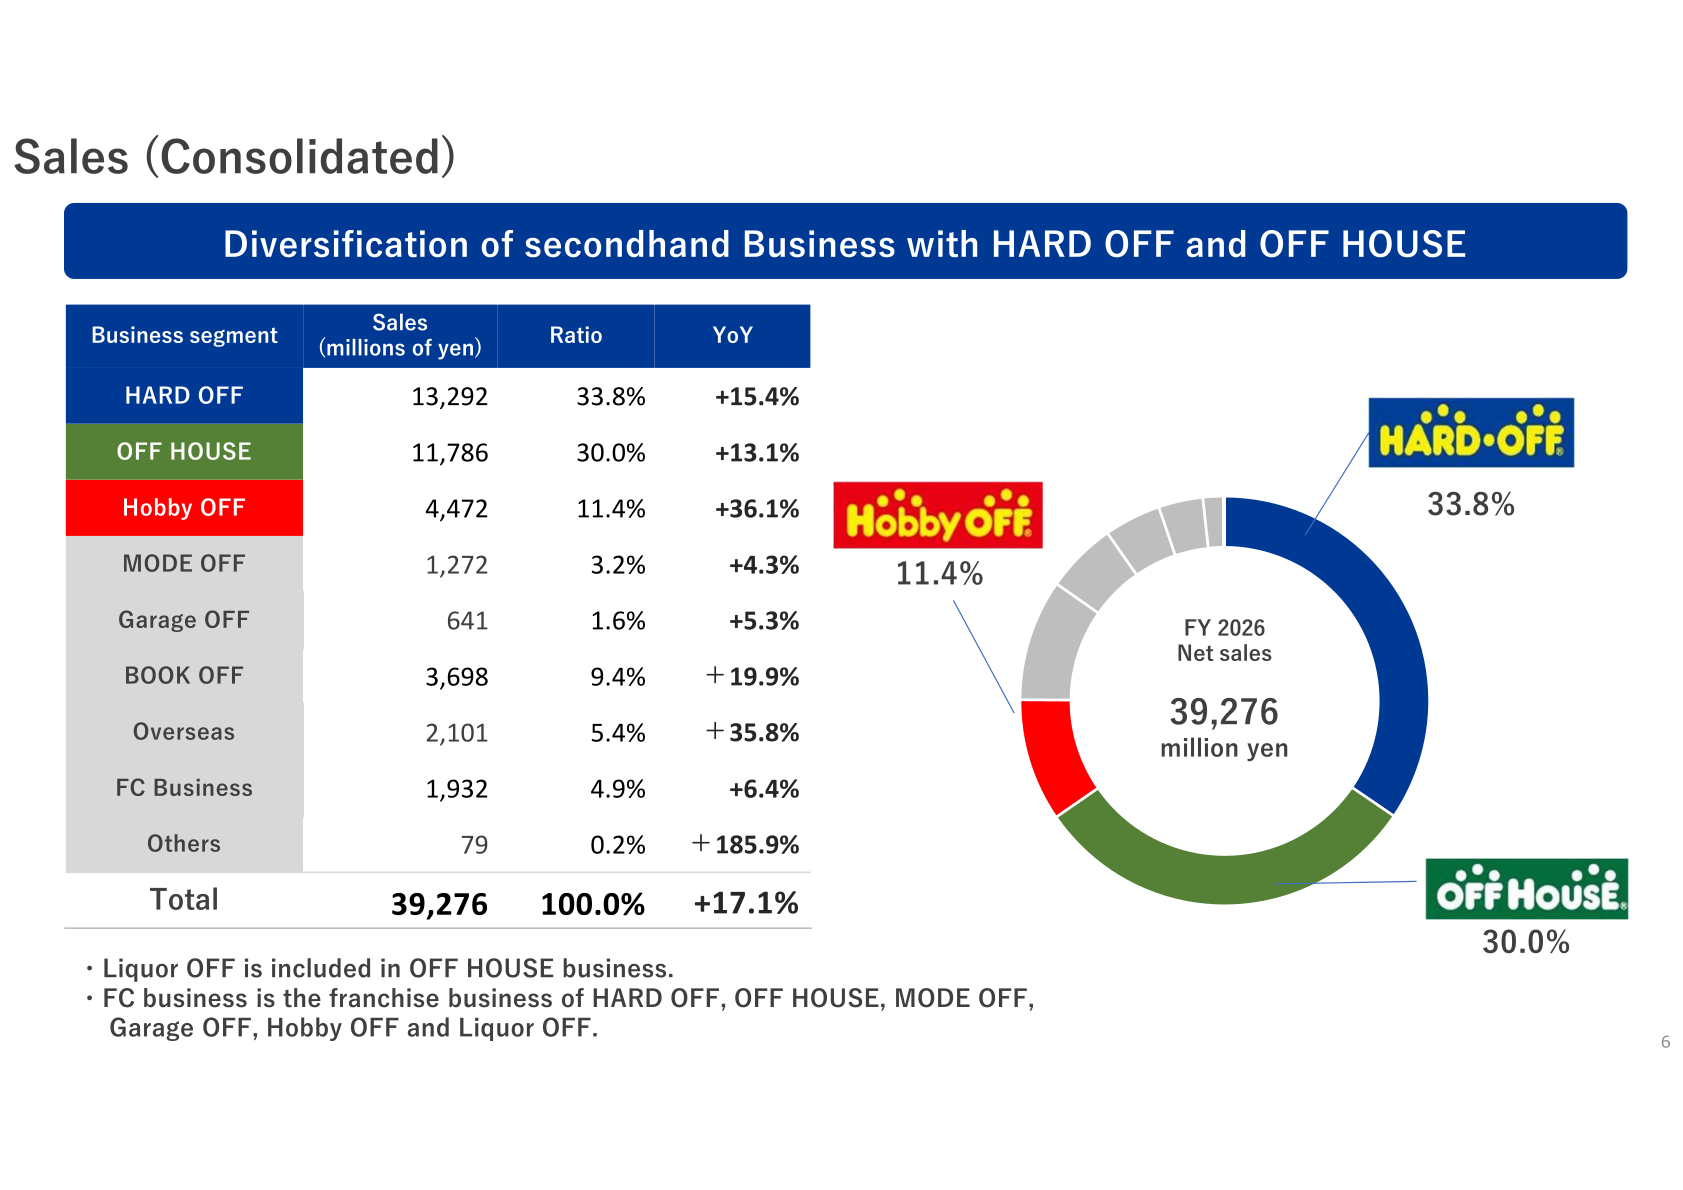
By business segment, HARD OFF remained the largest contributor at 13,292 million yen of sales (33.8% of the total), followed by OFF HOUSE at 11,786 million yen (30.0%). Hobby OFF grew fastest among the major formats at +36.1%, and Overseas sales rose 35.8% to 2,101 million yen.
| Business segment | Sales (millions of yen) | Ratio | YoY |
|---|---|---|---|
| HARD OFF | 13,292 | 33.8% | +15.4% |
| OFF HOUSE | 11,786 | 30.0% | +13.1% |
| Hobby OFF | 4,472 | 11.4% | +36.1% |
| MODE OFF | 1,272 | 3.2% | +4.3% |
| Garage OFF | 641 | 1.6% | +5.3% |
| BOOK OFF | 3,698 | 9.4% | +19.9% |
| Overseas | 2,101 | 5.4% | +35.8% |
| FC Business | 1,932 | 4.9% | +6.4% |
| Others | 79 | 0.2% | +185.9% |
| Total | 39,276 | 100.0% | +17.1% |
The group ended March 2026 with 1,078 stores, comprising 545 directly operated stores and 533 franchised stores, a net increase of 66. During the year 30 directly operated stores and 27 franchised stores were opened while 4 directly operated and 4 franchised stores were closed; through the subsidiarization of ECONOS Co., Ltd., 53 stores were transferred from franchise to directly operated status and 16 stores were newly added. ECONOS Co., Ltd., a Sapporo-based franchisee established in March 1964 with capital of 335,903 thousand yen, was made a subsidiary through a tender offer on October 2, 2025.
Full-Year Forecast
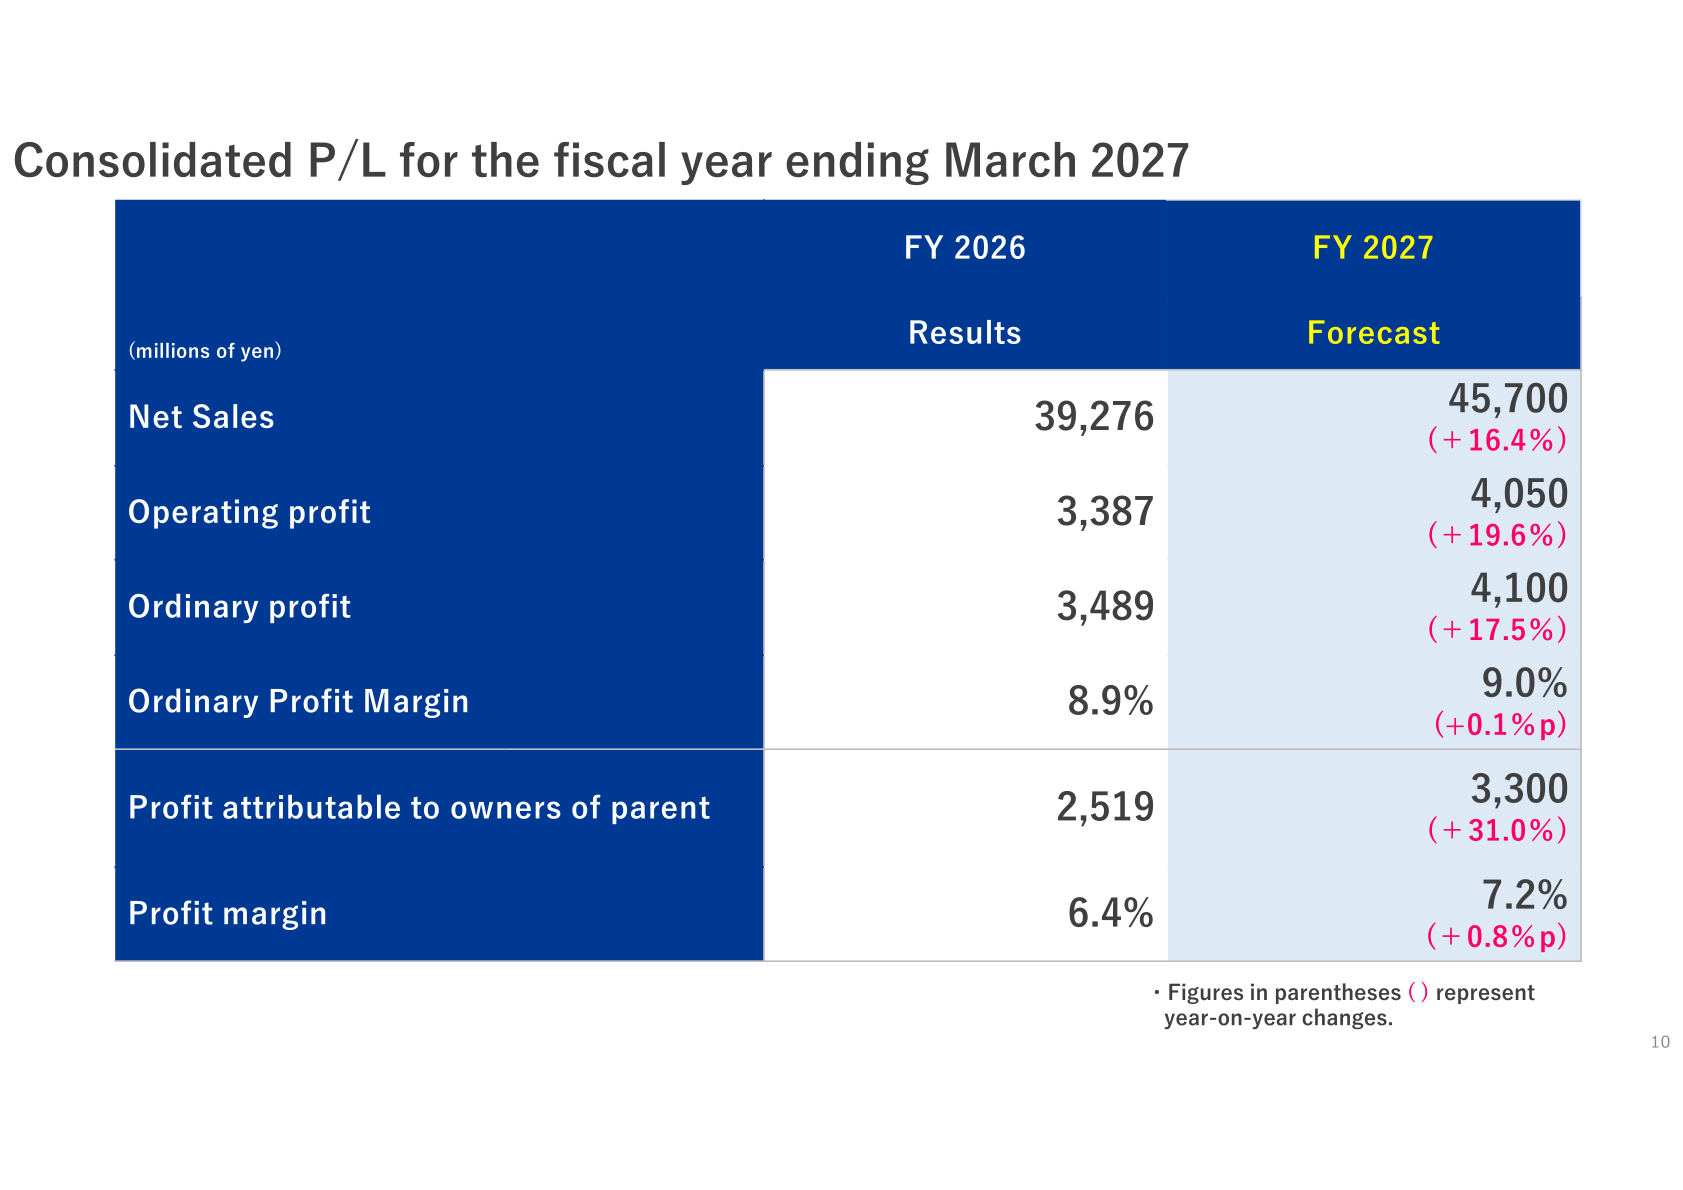
For the fiscal year ending March 2027, the company forecasts net sales of 45,700 million yen (+16.4%), which it describes as a record high for a 31st consecutive fiscal term, on an assumed increase in existing-store sales of approximately 4.0%. Profit attributable to owners of parent is forecast to rise 31.0% to 3,300 million yen, driven by an extraordinary gain of 1,160 million yen on sales of investment securities, with all profit lines expected to reach record highs for a fifth consecutive fiscal term.
| Item (millions of yen) | FY 2027 Forecast | FY 2026 Results |
|---|---|---|
| Net Sales | 45,700 (+16.4%) | 39,276 |
| Operating profit | 4,050 (+19.6%) | 3,387 |
| Ordinary profit | 4,100 (+17.5%) | 3,489 |
| Ordinary Profit Margin | 9.0% (+0.1%p) | 8.9% |
| Profit attributable to owners of parent | 3,300 (+31.0%) | 2,519 |
| Profit margin | 7.2% (+0.8%p) | 6.4% |
On a chain basis (directly operated plus franchised stores), domestic chain sales are forecast to rise 9.1% from 77,473 million yen to 84,500 million yen, and combined domestic and overseas chain sales to rise 9.7% from 80,503 million yen to 88,300 million yen. The store network is planned to expand by 36 directly operated and 21 franchised stores for a net increase of 57, to 1,135 stores. On management efficiency, the company shows ROE rising from 13.1% to 15.5%, ROA from 12.2% to 12.6%, EPS from ¥181.19 to ¥237.19 and BPS from ¥1,453.07 to ¥1,605.25, with ROIC declining from 11.4% to 10.8%.
Shareholder Returns
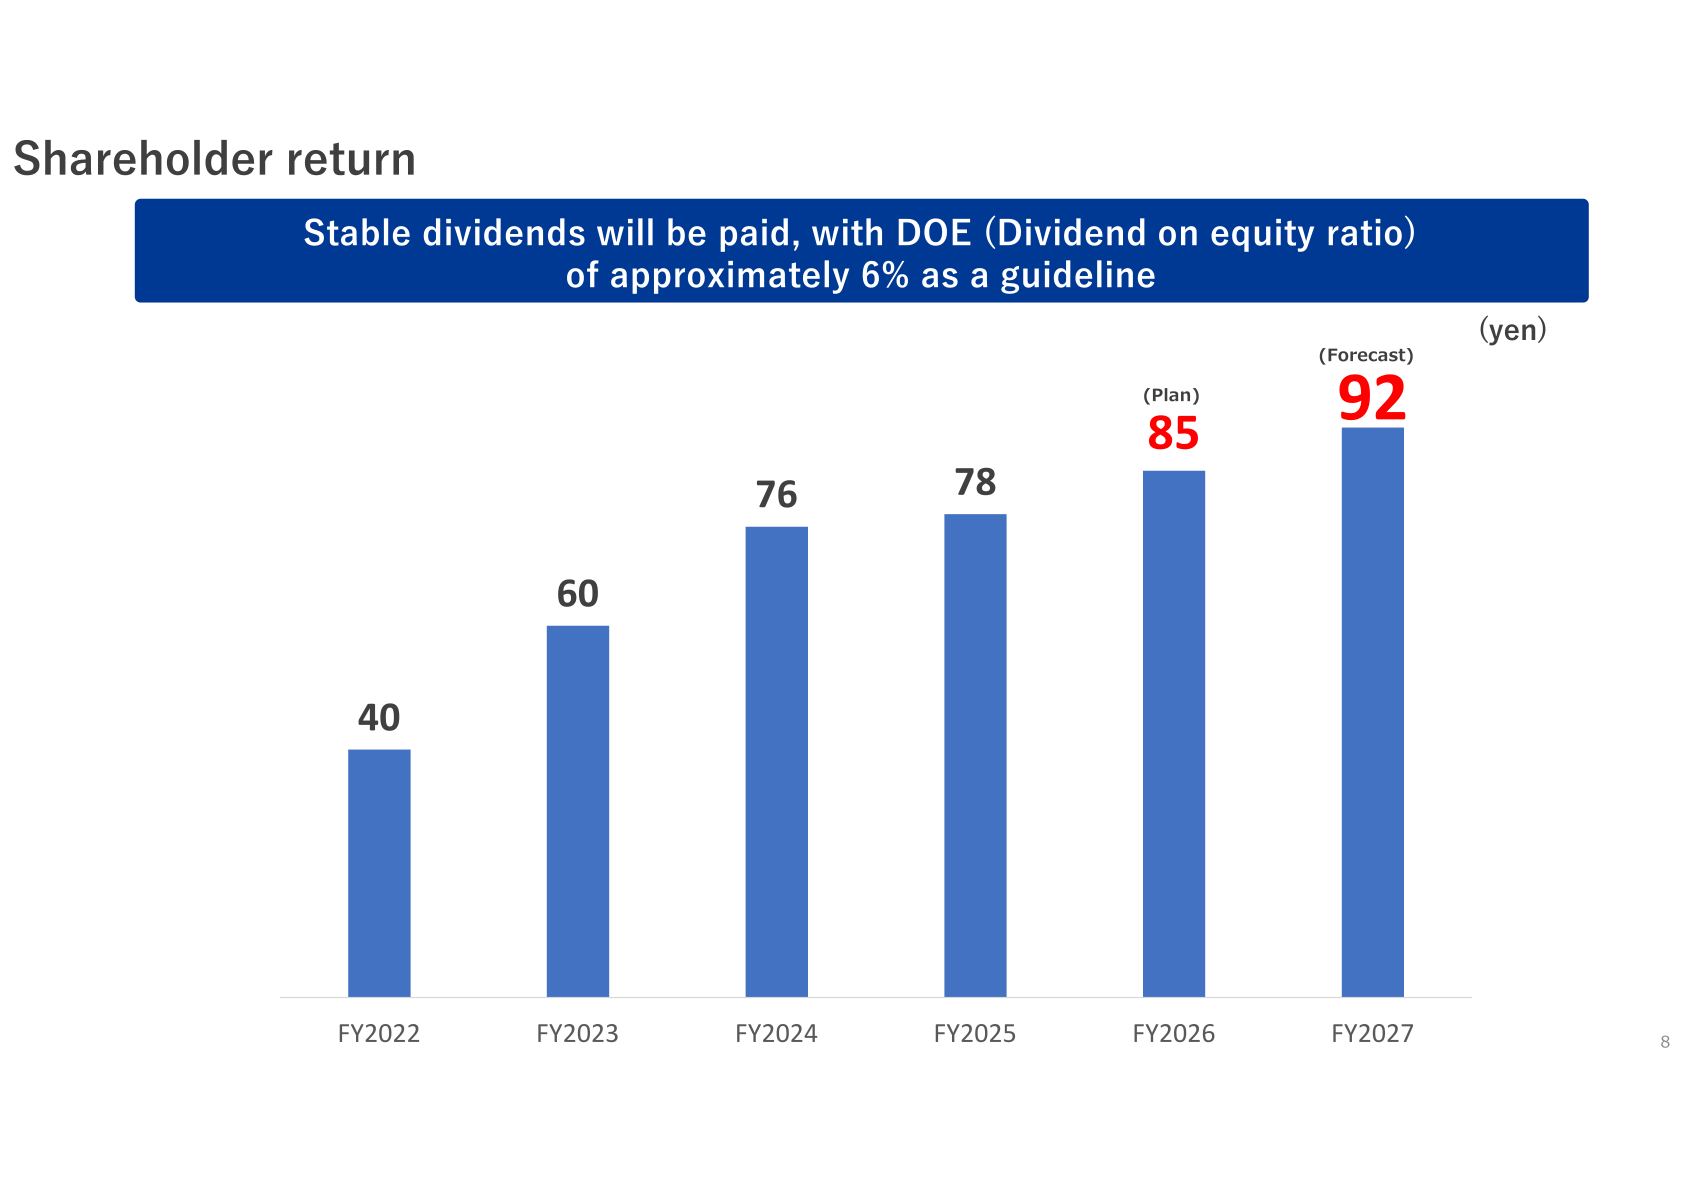
The company’s policy is to pay stable dividends using a consolidated DOE (dividend on equity ratio) of approximately 6% as a guideline. The presentation shows a dividend per share of 85 yen for FY 2026 (Plan) and a forecast of 92 yen for FY 2027, continuing the increases from 40 yen in FY2022.
| Fiscal year | Dividend per share (yen) |
|---|---|
| FY2022 | 40 |
| FY2023 | 60 |
| FY2024 | 76 |
| FY2025 | 78 |
| FY2026 | 85 (Plan) |
| FY2027 | 92 (Forecast) |
Medium-Term Management Plan
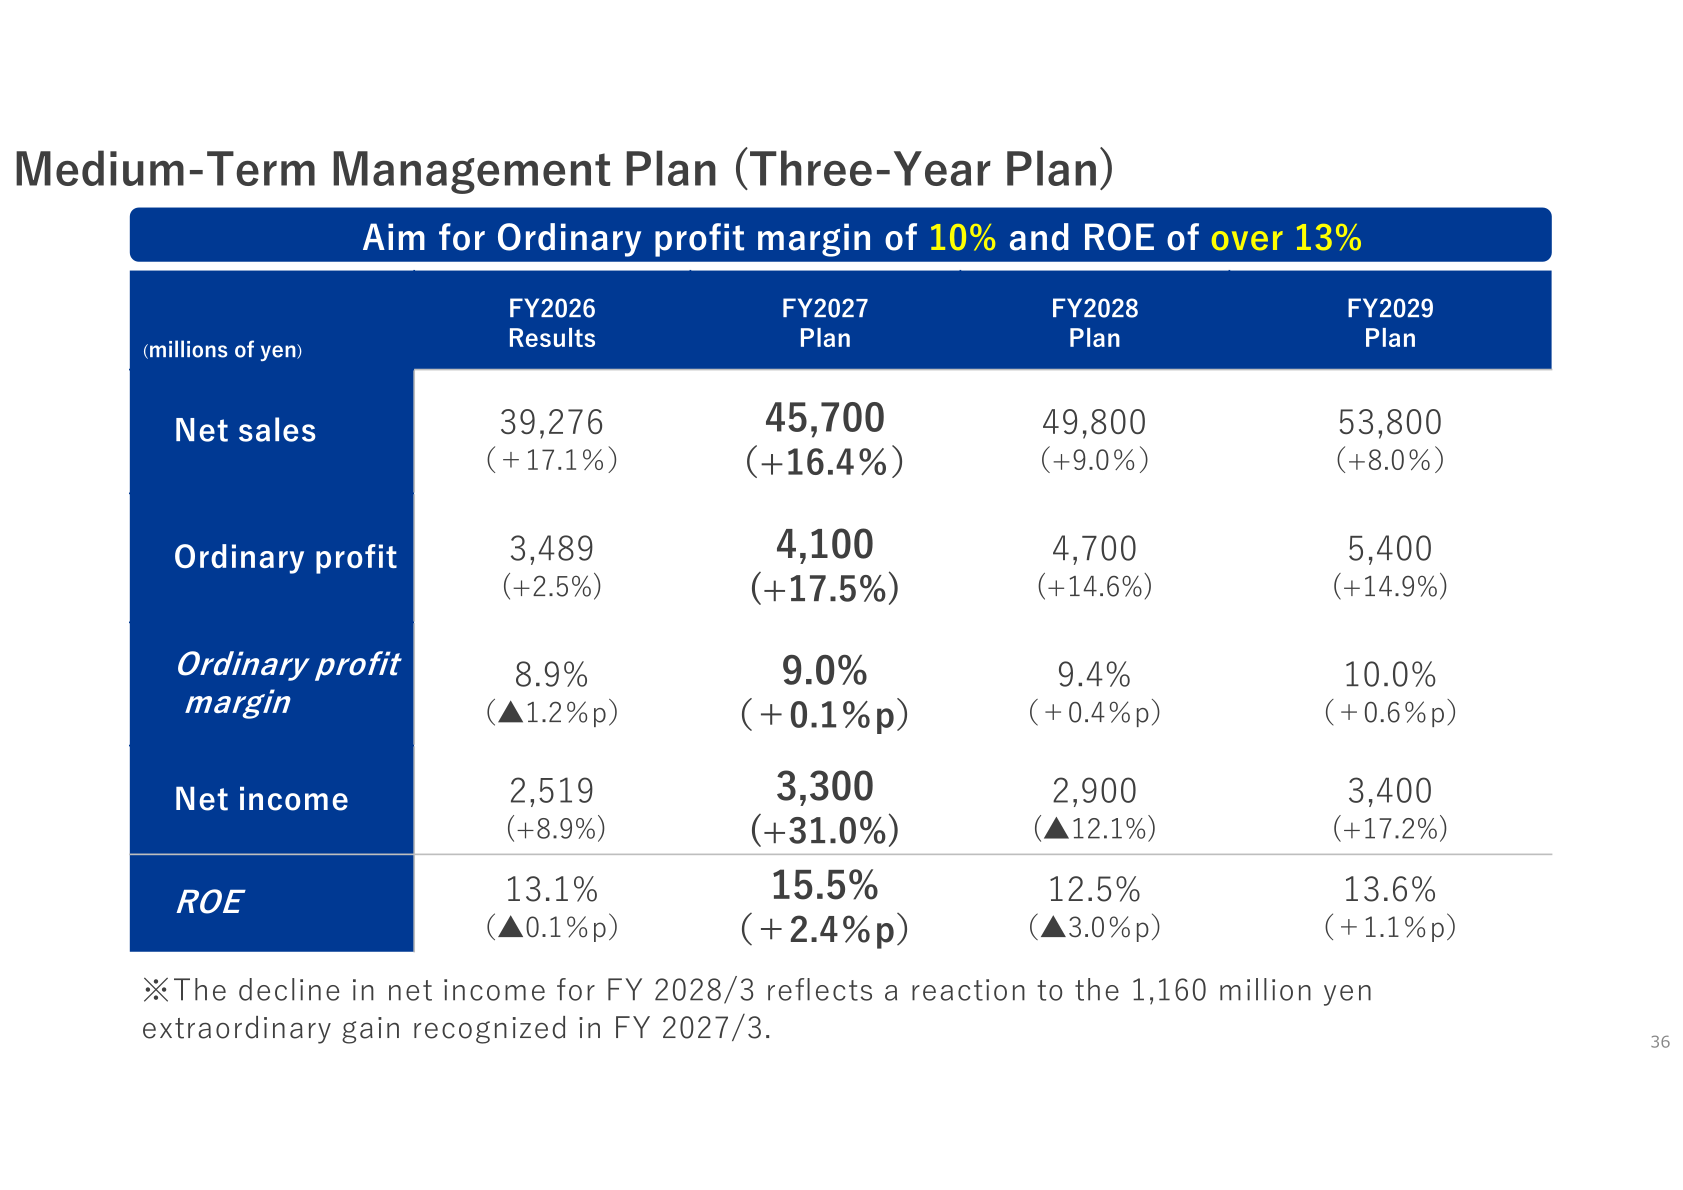
The three-year medium-term management plan targets an ordinary profit margin of 10% and ROE of over 13%. It assumes existing-store sales growth of +4% in FY2027 and +3% in FY2028 and FY2029, with a net increase of about 50 stores per year on average, taking the store count to 1,135 at the end of FY2027, 1,185 at the end of FY2028 and 1,235 at the end of FY2029. The plan notes that the decline in net income for FY 2028/3 reflects a reaction to the 1,160 million yen extraordinary gain recognized in FY 2027/3.
| Item (millions of yen) | FY2026 Results | FY2027 Plan | FY2028 Plan | FY2029 Plan |
|---|---|---|---|---|
| Net sales | 39,276 (+17.1%) | 45,700 (+16.4%) | 49,800 (+9.0%) | 53,800 (+8.0%) |
| Ordinary profit | 3,489 (+2.5%) | 4,100 (+17.5%) | 4,700 (+14.6%) | 5,400 (+14.9%) |
| Ordinary profit margin | 8.9% (▲1.2%p) | 9.0% (+0.1%p) | 9.4% (+0.4%p) | 10.0% (+0.6%p) |
| Net income | 2,519 (+8.9%) | 3,300 (+31.0%) | 2,900 (▲12.1%) | 3,400 (+17.2%) |
| ROE | 13.1% (▲0.1%p) | 15.5% (+2.4%p) | 12.5% (▲3.0%p) | 13.6% (+1.1%p) |
The plan is built on four strategies: a physical store strategy, a store opening strategy targeting 1,300 stores by 2030 at a density of one store per 100,000 people in each trade area, a digital strategy centred on the “Re”NK CHANNEL concept, and an overseas strategy. Digital targets for FY 2027 include annual chain sales of ¥8.0 billion at the OFF MALL e-commerce site, a total purchase amount of ¥1.1 billion through the Buyback Offer App, and 440,000 monthly users of the HARD OFF official app. On capital efficiency, the company states its cost of equity is around 6 to 7% on a CAPM basis, that ROE was 13.0% in FY2024, 13.2% in FY2025 and 13.1% in FY2026, and that PBR was 1.3 times at the end of FY2026, with a FY2029/3 target of ROE over 13.0%.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















