
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Temairazu’s fiscal year ends in June, and the company labels the year ended June 30, 2026 as “FY2026”; this article classifies that year as FY2025 under our site convention, while all figures, tables and labels below follow the company’s own presentation.
Temairazu, Inc. reported higher sales and profit for the fiscal year ended June 30, 2026, with net sales of 2,414,083 thousand yen (up 10.5% year on year) and operating profit of 1,747,457 thousand yen (up 8.6%). Results exceeded the initial forecast announced on July 31, 2025 on every line shown in the materials. The channel manager “TEMAIRAZU” application service business drove the growth, while the Hikaku.com internet media business remained in the red. Including dividends and treasury stock purchases, the total shareholder return for the year reached 109.5%.
Full-Year Results (FY2026 Actual)
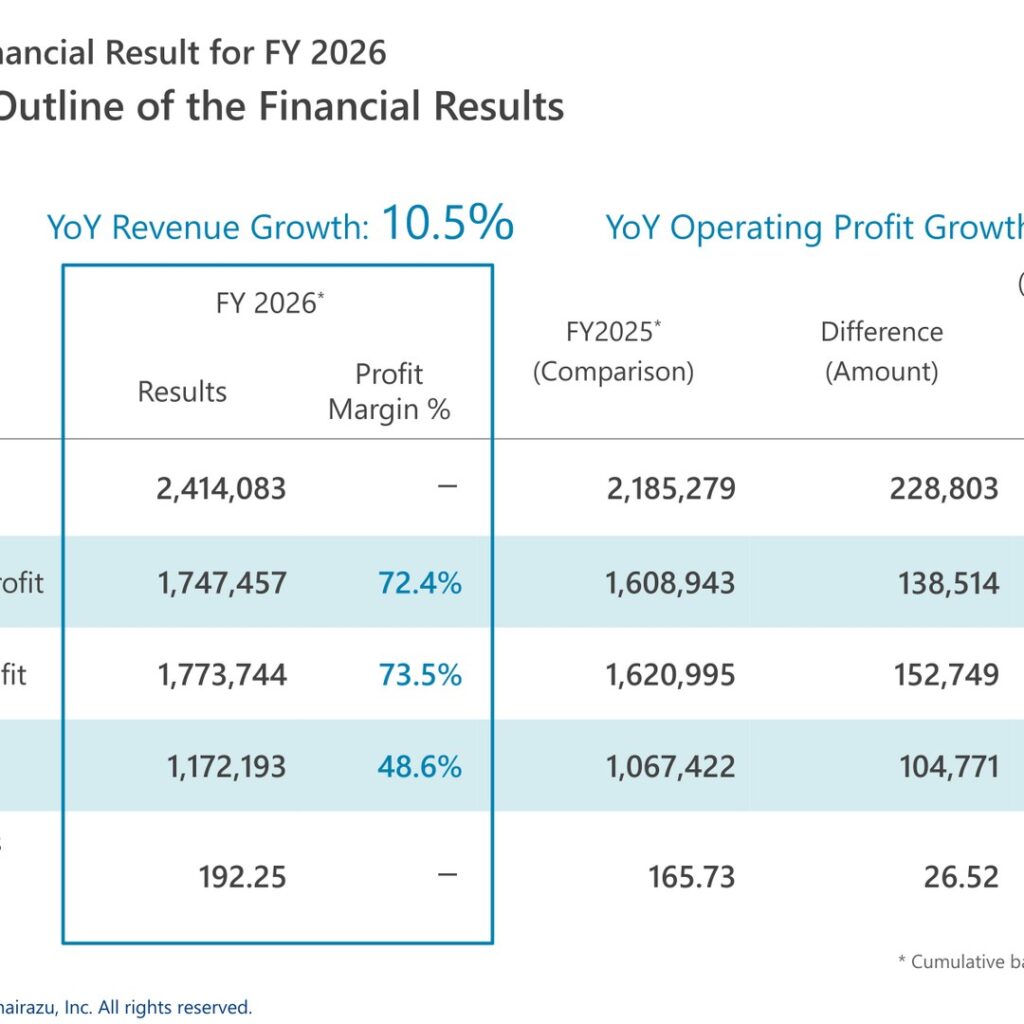
Net sales rose 10.5% to 2,414,083 thousand yen and operating profit rose 8.6% to 1,747,457 thousand yen, for an operating profit margin of 72.4%. Ordinary profit was 1,773,744 thousand yen (margin 73.5%) and net income was 1,172,193 thousand yen (margin 48.6%). Net earnings per share came to 192.25 yen, up 26.52 yen (+16.0%) from the prior year. Figures are presented on a cumulative basis for the fiscal year.
| Item (Unit: JPY’000) | FY2026 | FY2025 | Difference (Amount) | Difference (percentage) |
|---|---|---|---|---|
| Net Sales | 2,414,083 | 2,185,279 | 228,803 | +10.5% |
| Operating Profit | 1,747,457 | 1,608,943 | 138,514 | +8.6% |
| Ordinary Profit | 1,773,744 | 1,620,995 | 152,749 | +9.4% |
| Net Income | 1,172,193 | 1,067,422 | 104,771 | +9.8% |
| Net earnings per share (Unit: 1 JPY) | 192.25 | 165.73 | 26.52 | +16.0% |
Against the FY2026 forecast announced on July 31, 2025, net sales reached 102.1% of plan, operating income 106.5% and ordinary income 107.2%.
| Item (Unit: JPY’000) | FY2026 Forecast announced on July 31, 2025 | FY2026 Results | Achievement |
|---|---|---|---|
| Net Sales | 2,365,312 | 2,414,083 | 102.1% |
| Operating Income | 1,640,170 | 1,747,457 | 106.5% |
| Ordinary Income | 1,654,250 | 1,773,744 | 107.2% |
Segment Results
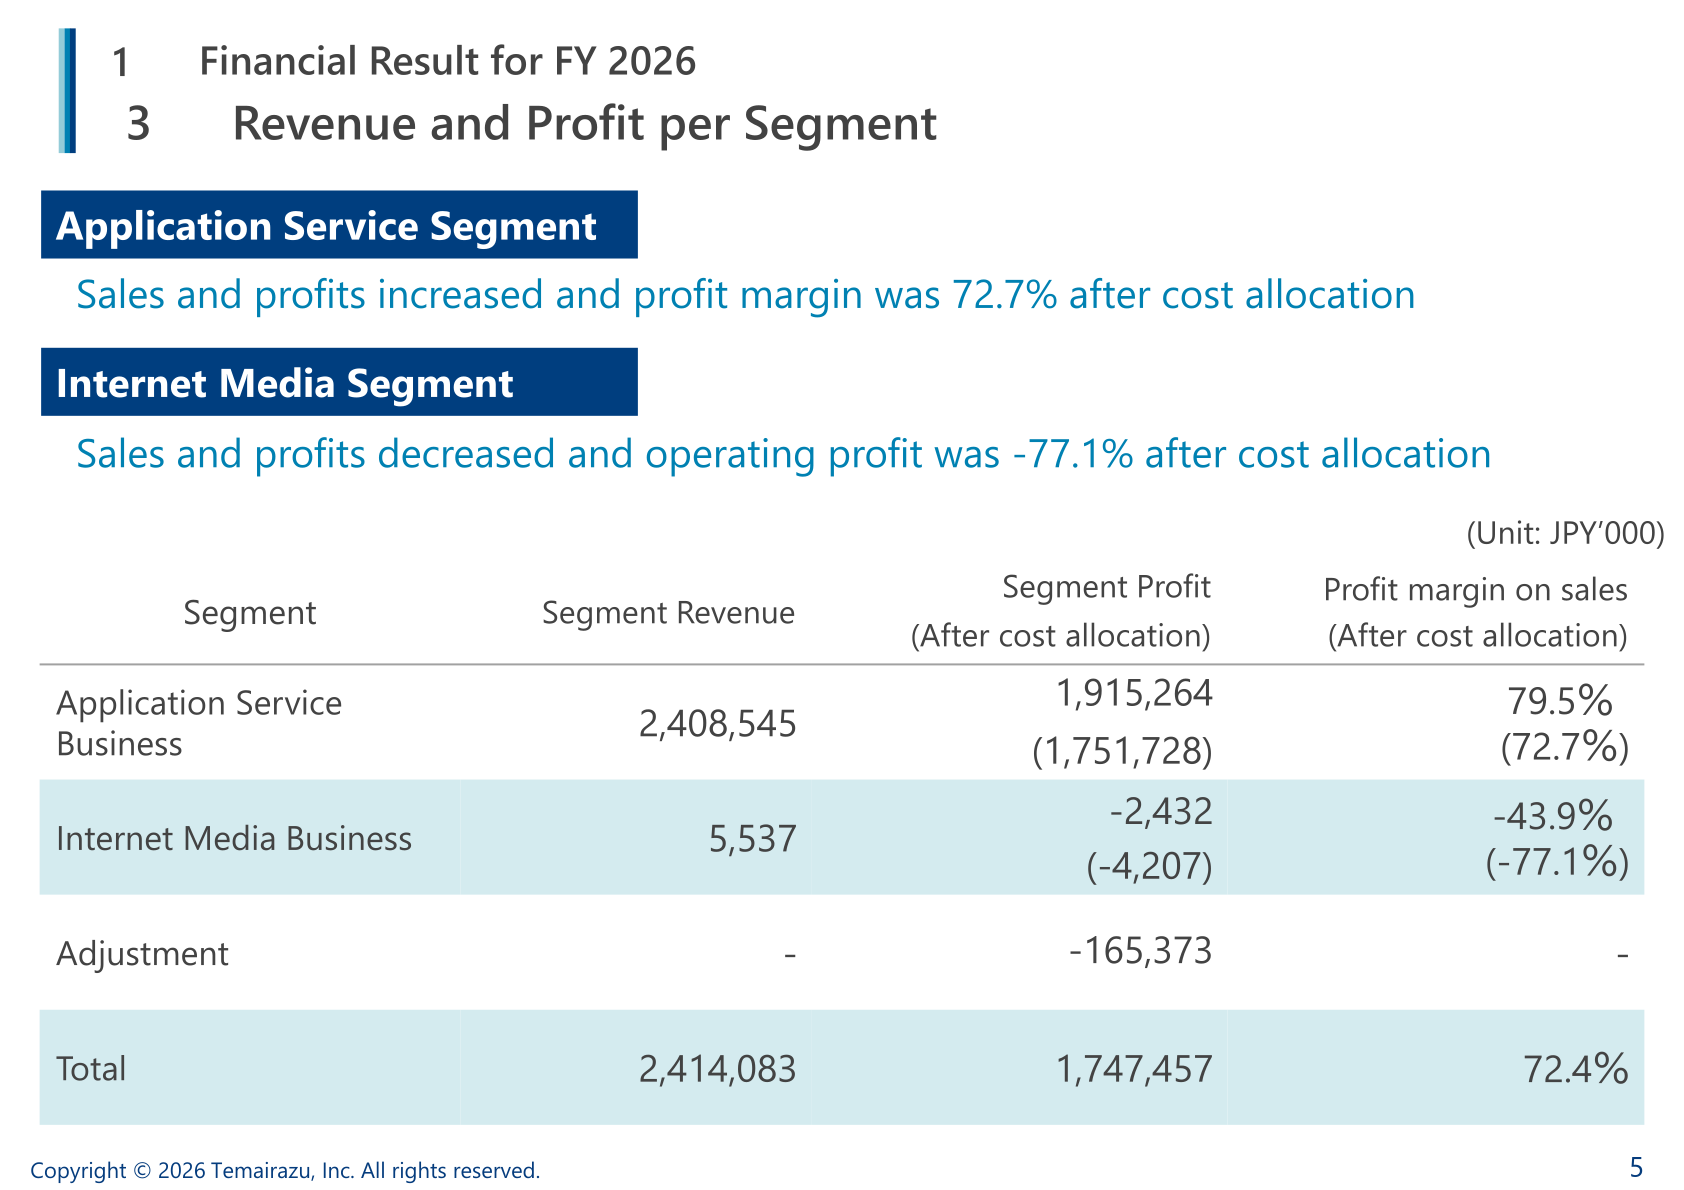
In the Application Service Business, sales and profits increased and the profit margin was 72.7% after cost allocation. In the Internet Media Business, sales and profits decreased and operating profit was -77.1% after cost allocation. Figures in parentheses are after allocation of company-wide costs. The segment table on P.5 of the materials shows the Internet Media Business segment profit after cost allocation as (-4,207), while P.26 of the same materials shows -4,270; the latter is the figure consistent with the stated -77.1% margin and with the total, and is the one used here.
| Segment (Unit: JPY’000) | Segment Revenue | Segment Profit (After cost allocation) | Profit margin on sales (After cost allocation) |
|---|---|---|---|
| Application Service Business | 2,408,545 | 1,915,264 (1,751,728) | 79.5% (72.7%) |
| Internet Media Business | 5,537 | -2,432 (-4,270) | -43.9% (-77.1%) |
| Adjustment | – | -165,373 | – |
| Total | 2,414,083 | 1,747,457 | 72.4% |
Segment profit after cost allocation in the Application Service Business grew 8.8% year on year, from 1,609,448 thousand yen in FY2025 to 1,751,728 thousand yen in FY2026. The materials cite an increase in the number of accommodation bookings — the total number of guest nights in Japan remained resilient despite certain geopolitical impacts — and a churn rate that is kept steadily low. Within the segment, cumulative FY2026 fixed monthly income was JPY 1,794 million (YoY +9.8%), monthly variable income was JPY 558 million (YoY +17.7%) and other income was JPY 55 million.
In the Internet Media Business (Hikaku.com), segment profit after cost allocation moved from -505 thousand yen in FY2025 to -4,270 thousand yen in FY2026, a year-on-year change of -744.9%. The materials attribute the revenue decrease to website traffic that dropped because of search engine algorithms, and list continuous updates to increase traffic: search engine optimization, user interface improvements and mobile usability improvements.
During the year the company also expanded connectivity, commencing system integration with online travel agents and platforms including Traveloka, Be., Tabiiro, DerbySoft, Resort Worx, Tiket.com, KKday, NEWT, HKTV Booking and Jcation, with hotel systems such as Oracle OPERA Cloud, Smart Order PMS and D-EDGE CRS, and with revenue management systems including IDeaS G3 RMS, DYNAMIC PLUS “D+” and Tabist “Dynamic Pricing”.
Balance Sheet
Total assets stood at 7,145,287 thousand yen at the end of FY2026 against 7,218,071 thousand yen at the end of FY2025. Cash was 6,410,138 thousand yen, a decrease of 177,895 thousand yen. Liabilities were 486,568 thousand yen and net assets were 6,658,718 thousand yen, with the equity ratio at 93.2% versus 93.8% a year earlier.
Shareholder Returns
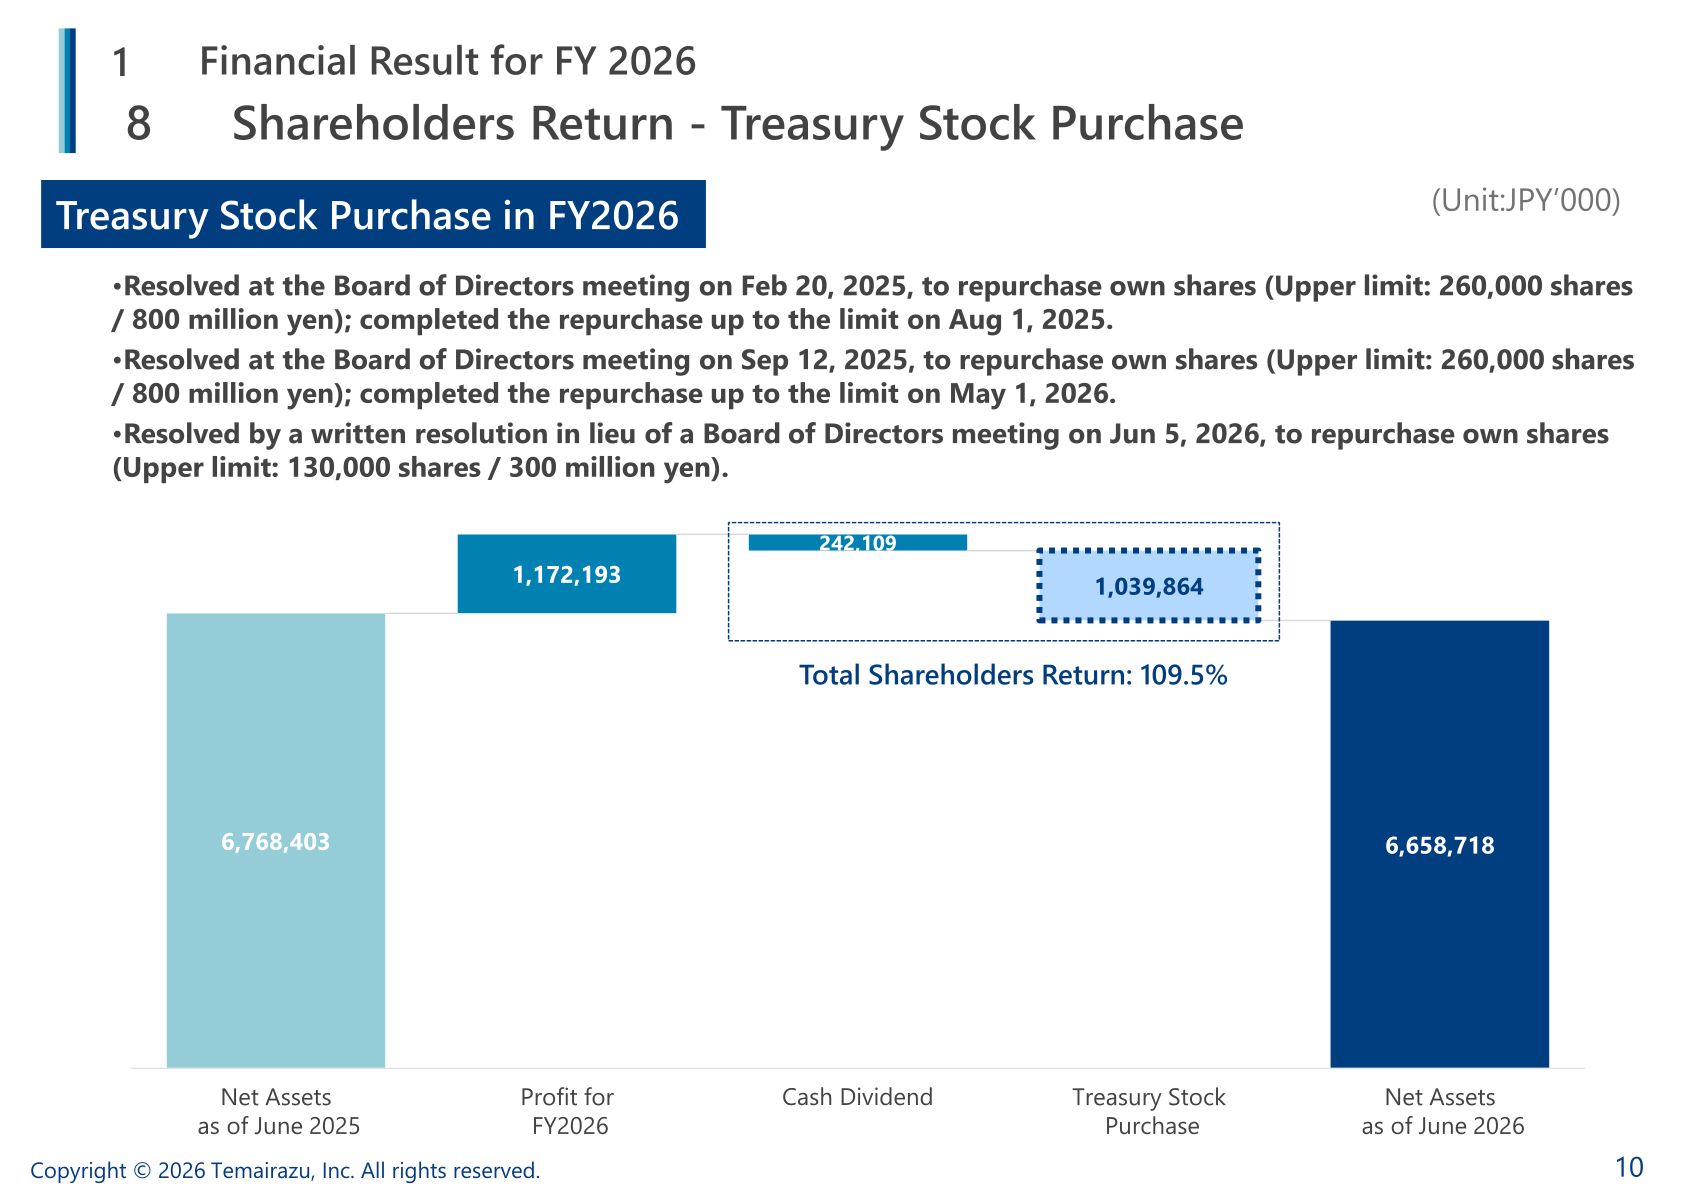
Net assets moved from 6,768,403 thousand yen as of June 2025 to 6,658,718 thousand yen as of June 2026, after profit for FY2026 of 1,172,193 thousand yen, a cash dividend of 242,109 thousand yen and treasury stock purchases of 1,039,864 thousand yen. The materials state a total shareholders return of 109.5%. On treasury stock, the company resolved at the Board of Directors meeting on Feb 20, 2025 to repurchase own shares (upper limit: 260,000 shares / 800 million yen) and completed the repurchase up to the limit on Aug 1, 2025; resolved at the Board of Directors meeting on Sep 12, 2025 to repurchase own shares (upper limit: 260,000 shares / 800 million yen) and completed the repurchase up to the limit on May 1, 2026; and resolved by a written resolution in lieu of a Board of Directors meeting on Jun 5, 2026 to repurchase own shares (upper limit: 130,000 shares / 300 million yen).
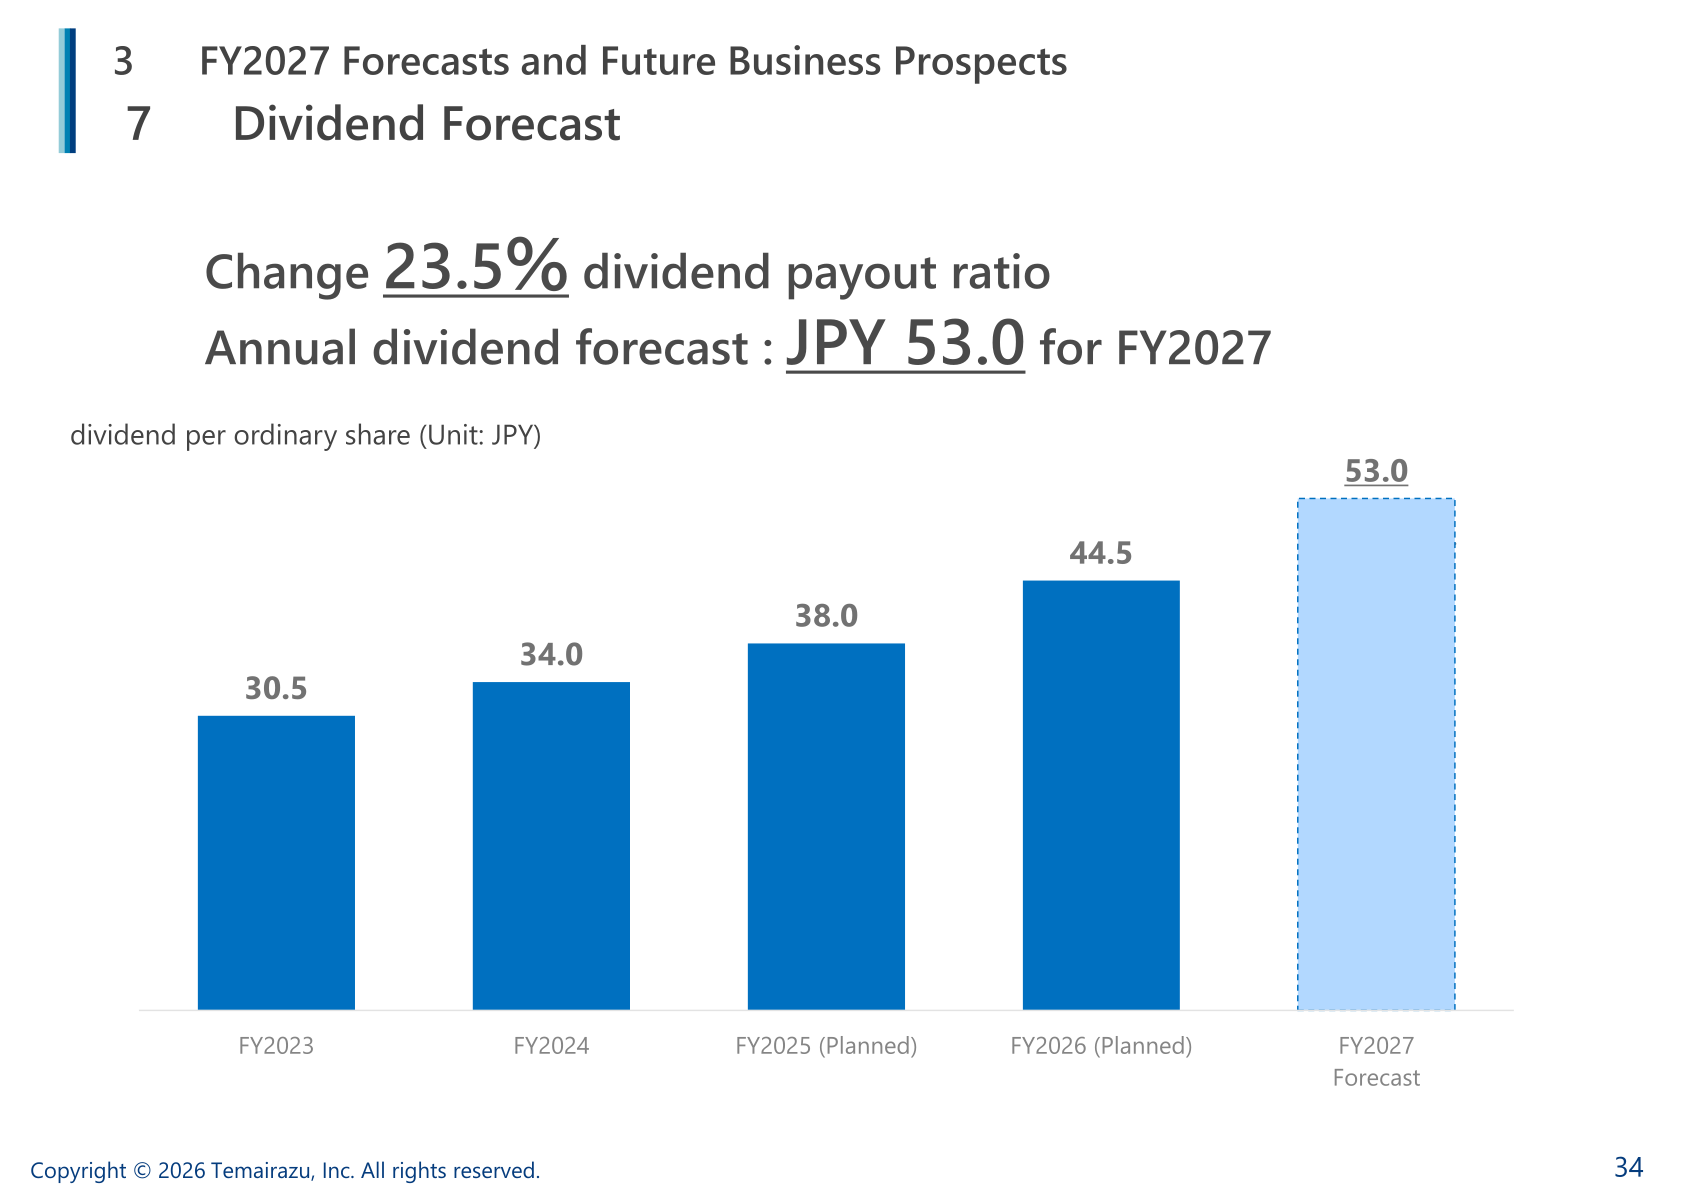
The dividend forecast slide shows an annual dividend per ordinary share of 30.5 yen for FY2023, 34.0 yen for FY2024, 38.0 yen for FY2025 (Planned) and 44.5 yen for FY2026 (Planned), with an annual dividend forecast of 53.0 yen for FY2027 at a dividend payout ratio of 23.5%.
| Dividend per ordinary share (Unit: JPY) | FY2023 | FY2024 | FY2025 (Planned) | FY2026 (Planned) | FY2027 Forecast |
|---|---|---|---|---|---|
| Annual dividend | 30.5 | 34.0 | 38.0 | 44.5 | 53.0 |
Next-Year Forecast and Business Prospects
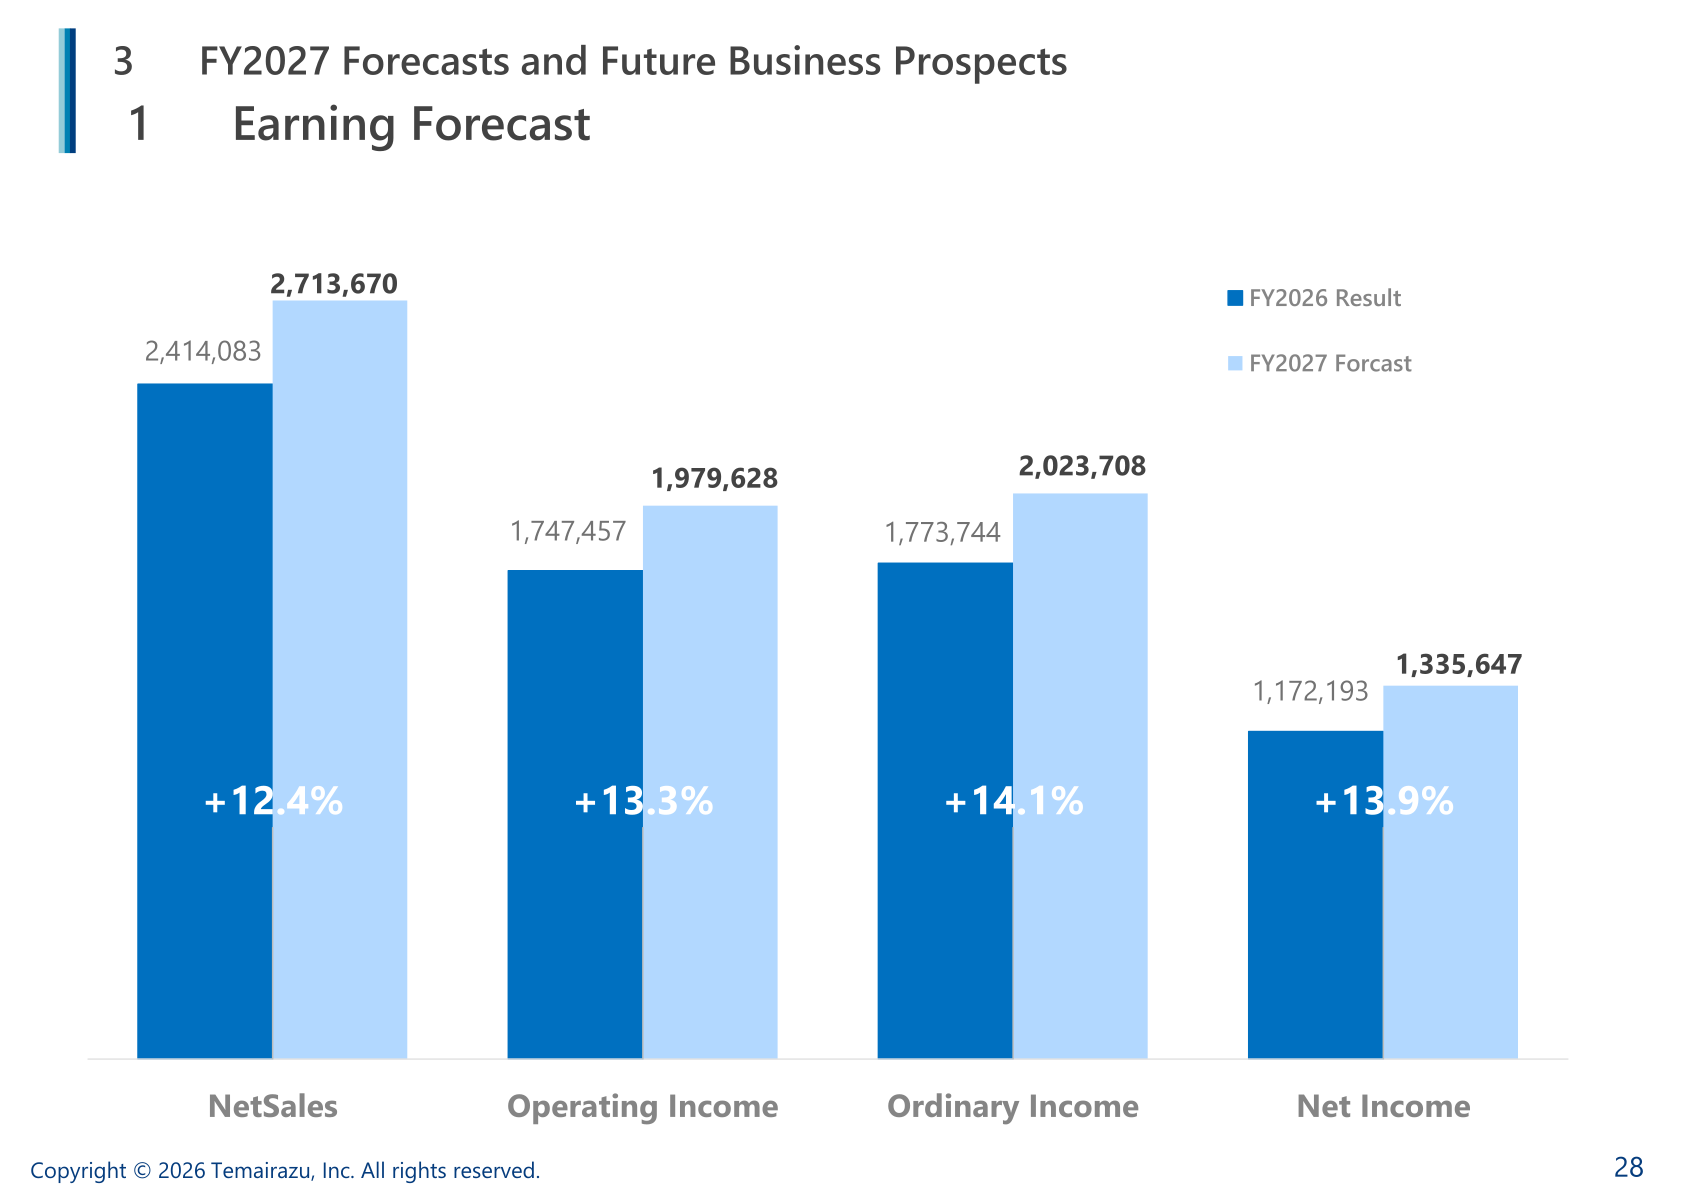
For the next fiscal year the company forecasts net sales of 2,713,670 thousand yen (+12.4%), operating income of 1,979,628 thousand yen (+13.3%), ordinary income of 2,023,708 thousand yen (+14.1%) and net income of 1,335,647 thousand yen (+13.9%).
| Item (Unit: JPY’000) | FY2027 Forecast | FY2026 Result | Change |
|---|---|---|---|
| Net Sales | 2,713,670 | 2,414,083 | +12.4% |
| Operating Income | 1,979,628 | 1,747,457 | +13.3% |
| Ordinary Income | 2,023,708 | 1,773,744 | +14.1% |
| Net Income | 1,335,647 | 1,172,193 | +13.9% |
Segment profit after cost allocation in the Application Service Business is forecast at 1,984,544 thousand yen, a year-on-year increase of 13.2%. The forecast assumes continuing steady demand for accommodation following FY2026, various risk factors in the economy such as rising prices, interest rates and foreign exchange rates, and new construction plans for accommodation facilities remaining at a certain level, alongside continued investment in human capital, systems including security measures, and development. For the Internet Media Business the company forecasts a decrease in segment profit year on year, while continuing updates to increase website traffic.
On future business development for the Application Service Business, the company lists responding to steady accommodation demand, enhancing “Temairazu Jido” and the “Temairazu” family of products, expanding OTA connectivity for customers’ sales channel expansion, and strengthening integrations with various hospitality solutions. As key investment areas, it plans to invest JPY 100-200 million over the next few years in new initiatives for mid- to long-term growth, in addition to continued investment in sales and development headcount and in development for acquiring new customers.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















