
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
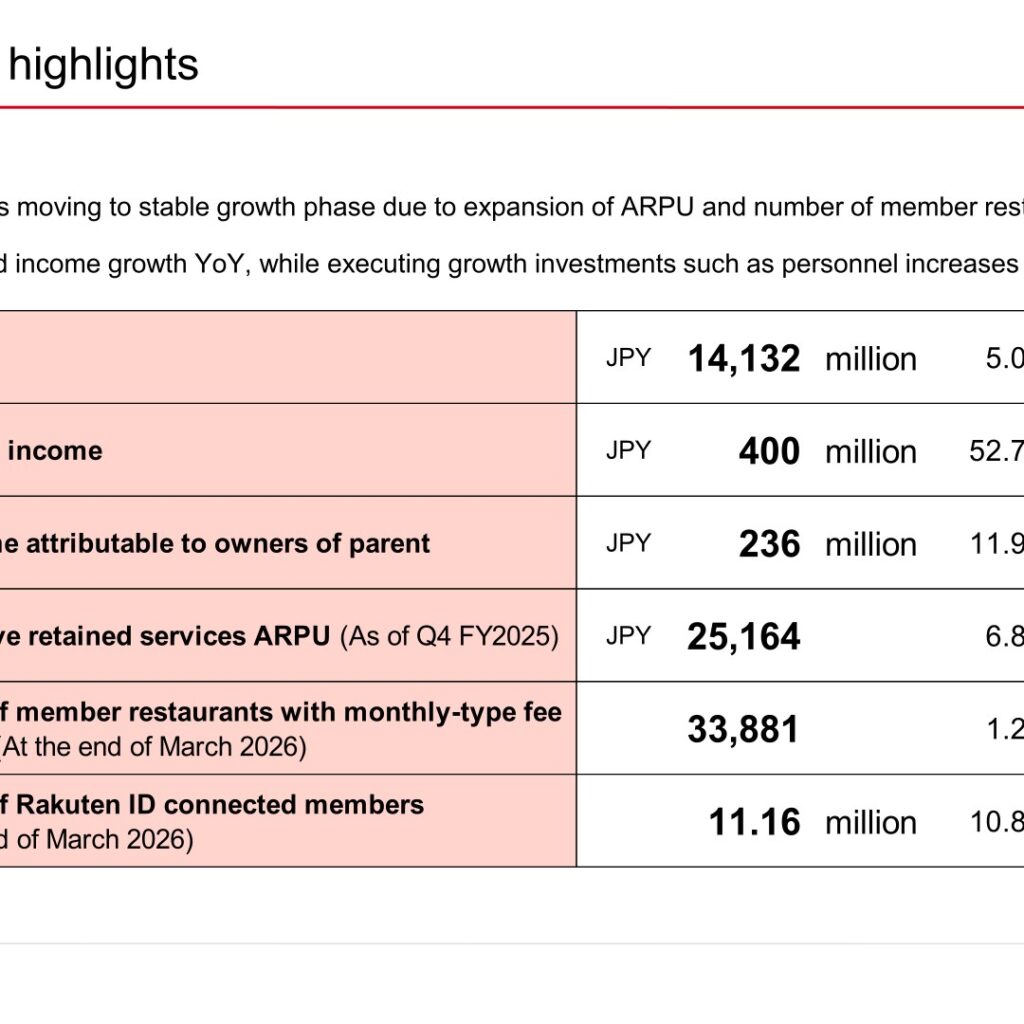
Gurunavi, Inc. reported net sales of JPY 14,132 million for the fiscal year 2025 (the fiscal year ended March 31, 2026), up 5.0% year on year, and operating income of JPY 400 million, up 52.7%. Net income attributable to owners of parent was JPY 236 million, up 11.9%. The company states that net sales are moving to a stable growth phase due to expansion of ARPU and the number of member restaurants, and that it achieved income growth year on year while executing growth investments such as personnel increases. For the fiscal year 2026 the company forecasts net sales of JPY 15,100 million, up 6.8%, with an operating loss of JPY 830 million as it makes strategic investments.
Consolidated Results (Full-Year Actual)
Net sales rose 5.0% to JPY 14,132 million. Cost of sales increased 12.3% to JPY 5,770 million while SG&A expenses decreased 1.2% to JPY 7,961 million, lifting operating income 52.7% to JPY 400 million. Ordinary income was JPY 368 million, up 41.2%, and net income attributable to owners of parent was JPY 236 million, up 11.9%. The operating margin was 2.8% of sales, against 2.0% in the previous fiscal year.
| Item (JPY million) | FY2024 | FY2025 | YoY |
|---|---|---|---|
| Net sales | 13,458 | 14,132 | 5.0% |
| Cost of sales | 5,140 | 5,770 | 12.3% |
| Gross profit | 8,317 | 8,362 | 0.5% |
| SG&A expenses | 8,055 | 7,961 | (1.2)% |
| Operating income | 262 | 400 | 52.7% |
| Ordinary income | 261 | 368 | 41.2% |
| Net income before income taxes | 226 | 239 | 5.4% |
| Net income attributable to owners of parent | 211 | 236 | 11.9% |
The materials note that the company recorded a gain on sale of investment securities of JPY 103 million as extraordinary income, and an impairment loss of JPY 234 million on fixed assets of some facilities in the restaurant development business etc. as extraordinary loss.
On the balance sheet, total assets stood at JPY 10,911 million as of March 31, 2026, a decrease of JPY 217 million from a year earlier, with cash and deposits of JPY 3,300 million, down JPY 1,741 million. Total liabilities were JPY 5,667 million, down JPY 483 million, and total net assets were JPY 5,243 million, up JPY 265 million. The shareholders’ equity ratio was 47.7%. The company refinanced short-term borrowings raised in February 2025 (JPY 1.2 billion) into long-term borrowings in September 2025, and changed the committed line established in September 2024 (JPY 3 billion) to an uncommitted line in September 2025.
Sales Breakdown by Service
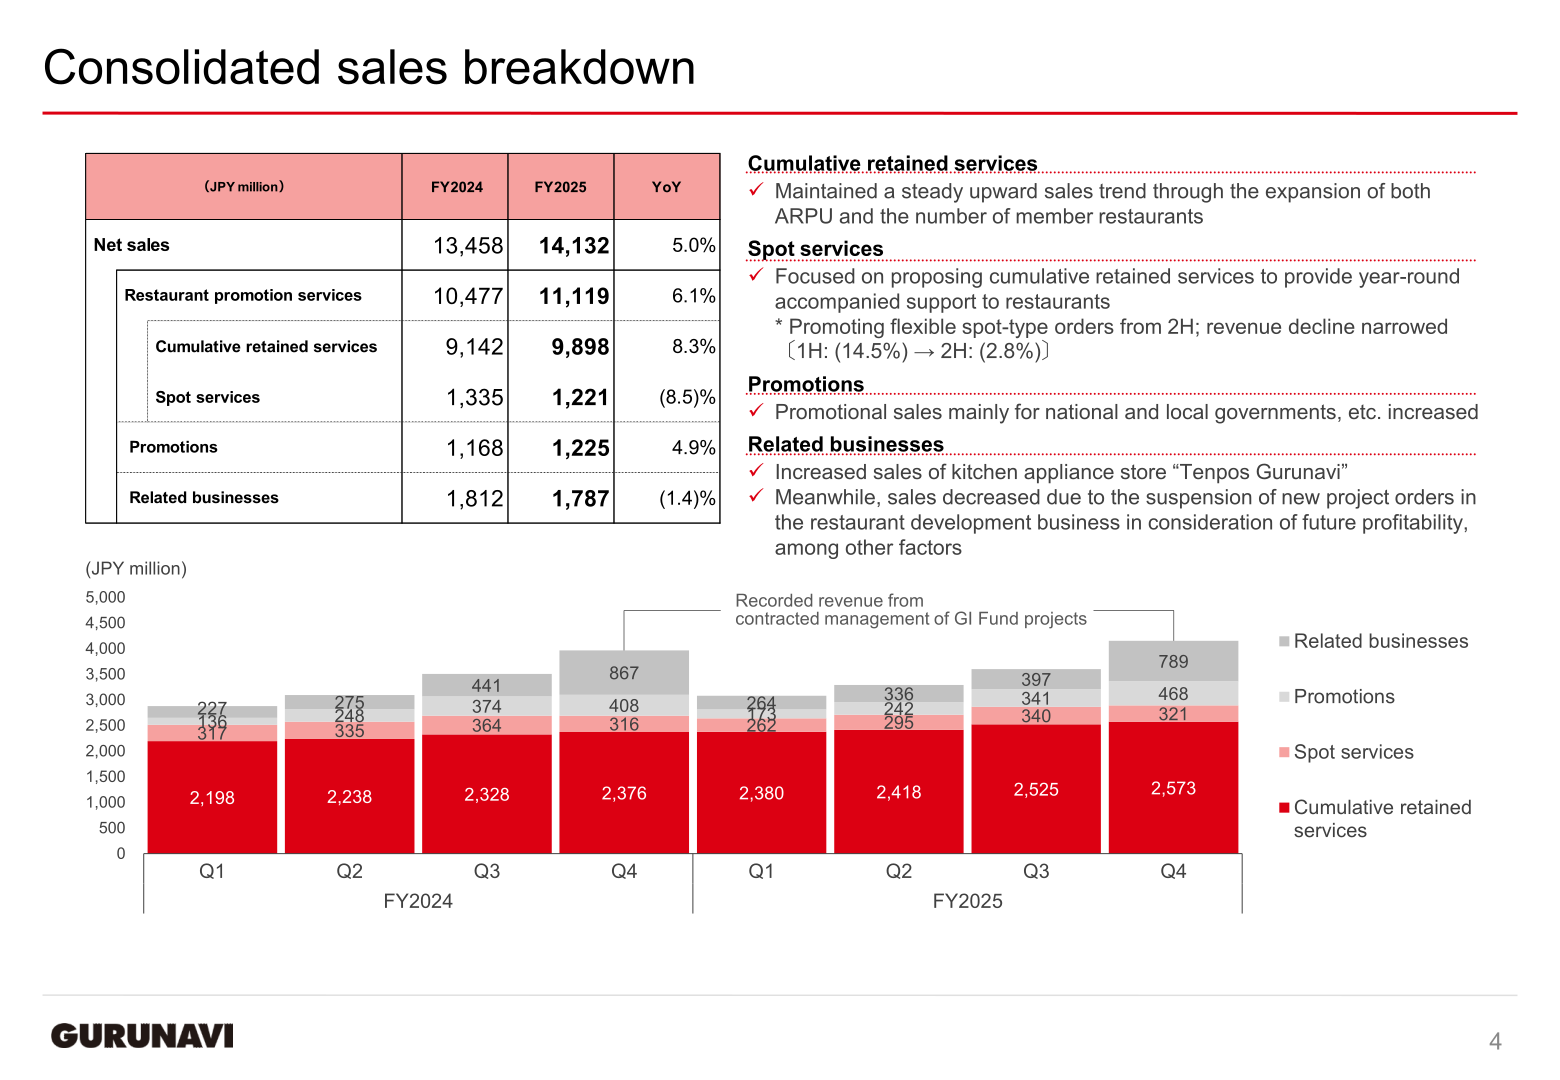
Restaurant promotion services generated net sales of JPY 11,119 million, up 6.1%. Within this, cumulative retained services grew 8.3% to JPY 9,898 million, which the company attributes to a steady upward sales trend through the expansion of both ARPU and the number of member restaurants. Spot services declined 8.5% to JPY 1,221 million as the company focused on proposing cumulative retained services; the materials note that flexible spot-type orders were promoted from the second half and that the revenue decline narrowed from (14.5)% in 1H to (2.8)% in 2H. Promotions rose 4.9% to JPY 1,225 million on higher promotional sales mainly for national and local governments. Related businesses fell 1.4% to JPY 1,787 million: sales of kitchen appliance store “Tenpos Gurunavi” increased, while sales decreased due to the suspension of new project orders in the restaurant development business in consideration of future profitability, among other factors.
| Item (JPY million) | FY2024 | FY2025 | YoY |
|---|---|---|---|
| Net sales | 13,458 | 14,132 | 5.0% |
| Restaurant promotion services | 10,477 | 11,119 | 6.1% |
| Restaurant promotion services — Cumulative retained services | 9,142 | 9,898 | 8.3% |
| Restaurant promotion services — Spot services | 1,335 | 1,221 | (8.5)% |
| Promotions | 1,168 | 1,225 | 4.9% |
| Related businesses | 1,812 | 1,787 | (1.4)% |
Cost Breakdown
Total cost rose 4.1% to JPY 13,731 million. Cost of sales increased 12.3%, which the company attributes to an increase in labor costs on enhanced recruitment to strengthen the restaurant support business, an increase in depreciation costs due to the accumulation of fixed assets, and an increase in outsourcing expenses mainly due to sales expansion. Within SG&A, business consignment expenses decreased on the advancement of insourcing, rent expenses increased mainly due to higher usage and price revisions of rental systems, and personnel expenses decreased due to the rebound from a bonus increase in the previous period, while salaries and compensation increased due to personnel increases. The total number of non-consolidated personnel (excluding employees seconded to other companies) rose from 800 at the end of FY2024 to 841 at the end of FY2025.
| Item (JPY million) | FY2024 | FY2025 | YoY |
|---|---|---|---|
| Total cost | 13,195 | 13,731 | 4.1% |
| Cost of sales | 5,140 | 5,770 | 12.3% |
| SG&A | 8,055 | 7,961 | (1.2)% |
| SG&A — Personnel expenses | 4,863 | 4,855 | (0.2)% |
| SG&A — Rent expenses | 936 | 985 | 5.2% |
| SG&A — Business consignment expenses | 745 | 643 | (13.8)% |
| SG&A — Advertising and promotion expenses | 503 | 521 | 3.6% |
| SG&A — Other | 1,005 | 955 | (4.9)% |
Key Operating Indicators
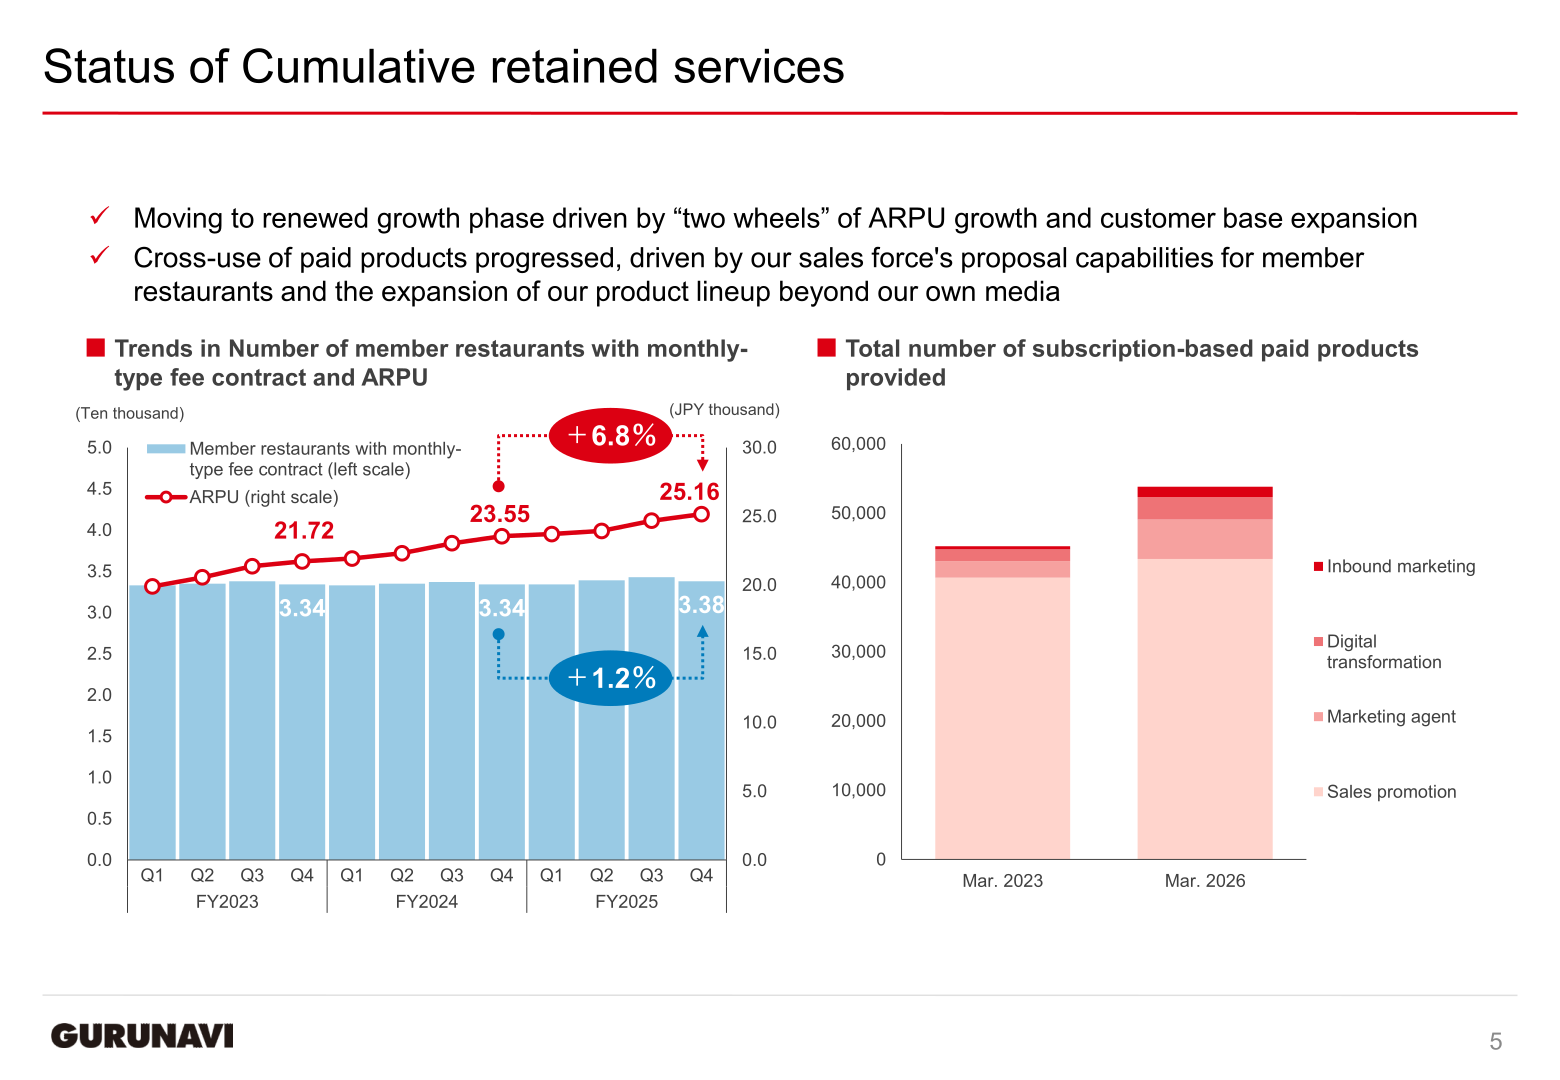
Cumulative retained services ARPU as of Q4 FY2025 was JPY 25,164, up 6.8% year on year. The number of member restaurants with a monthly-type fee contract was 33,881 at the end of March 2026, up 1.2% year on year and up by 400 from the end of March 2025, while the number of total paying member restaurants was 42,920, up by 1,019 from the end of March 2025. The number of Rakuten ID connected members reached 11.16 million at the end of March 2026, up 10.8%. The number of Gurunavi members was 29.20 million as of April 1, 2026. For the mobile ordering service “Gurunavi FineOrder,” the number of contracted companies was 179, mainly large chain companies, with an active rate of 89% in March 2026.
FY2026 Forecast
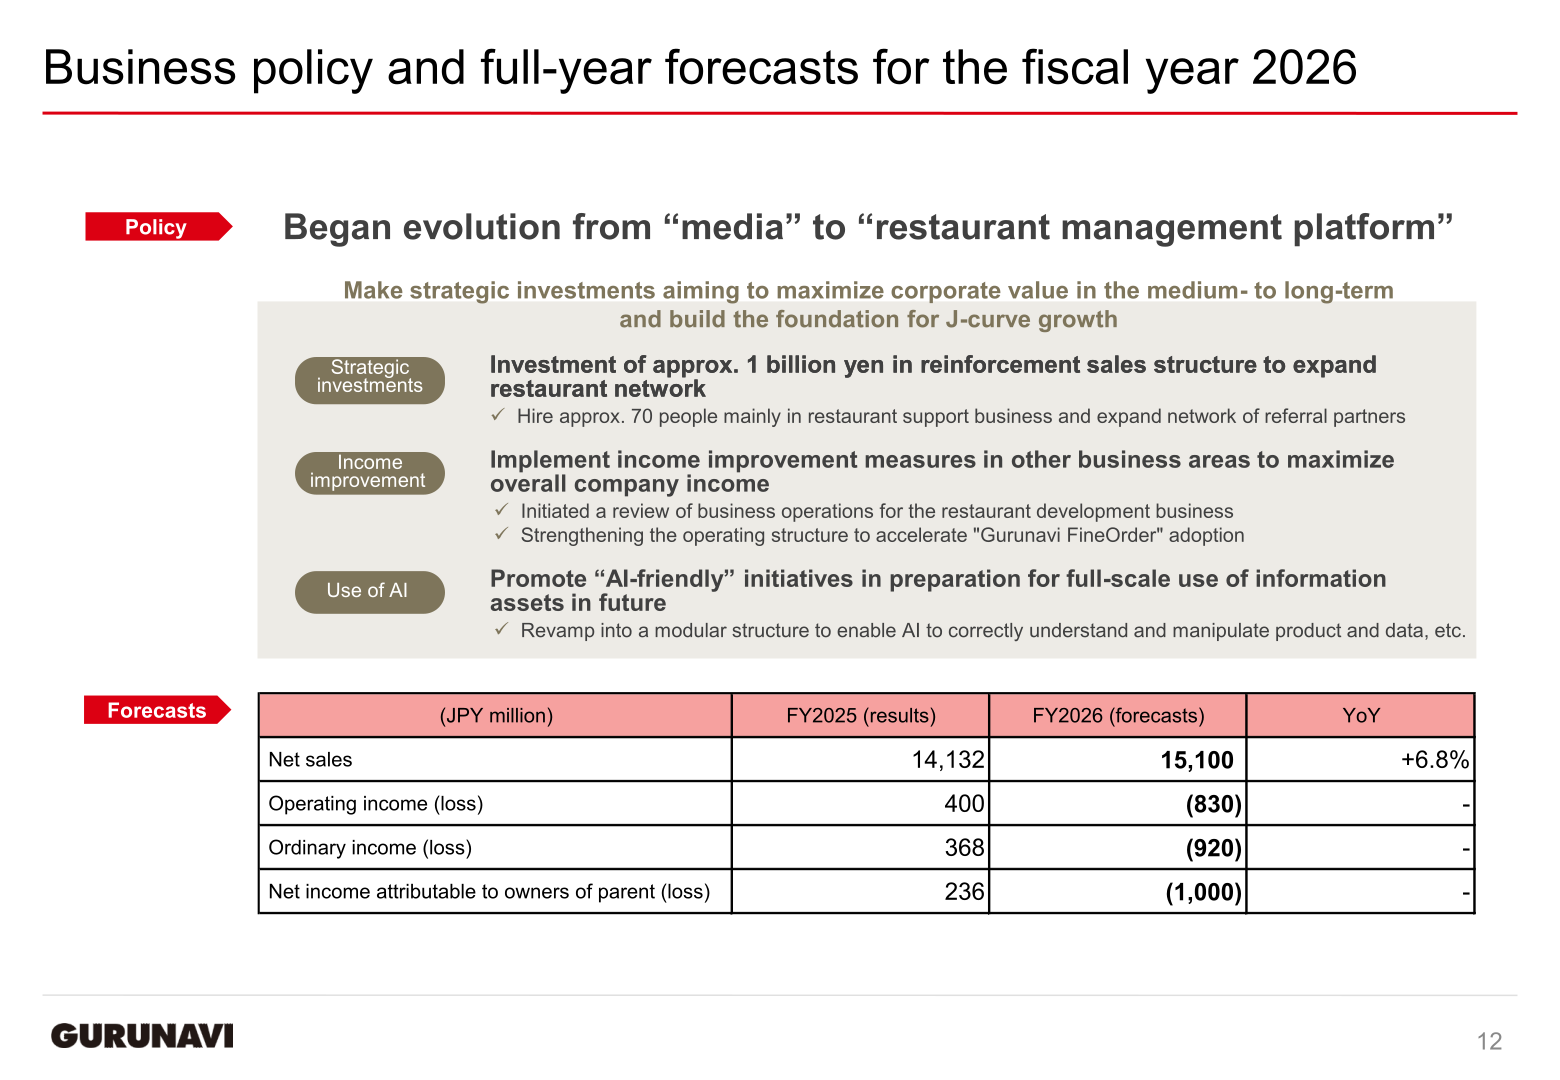
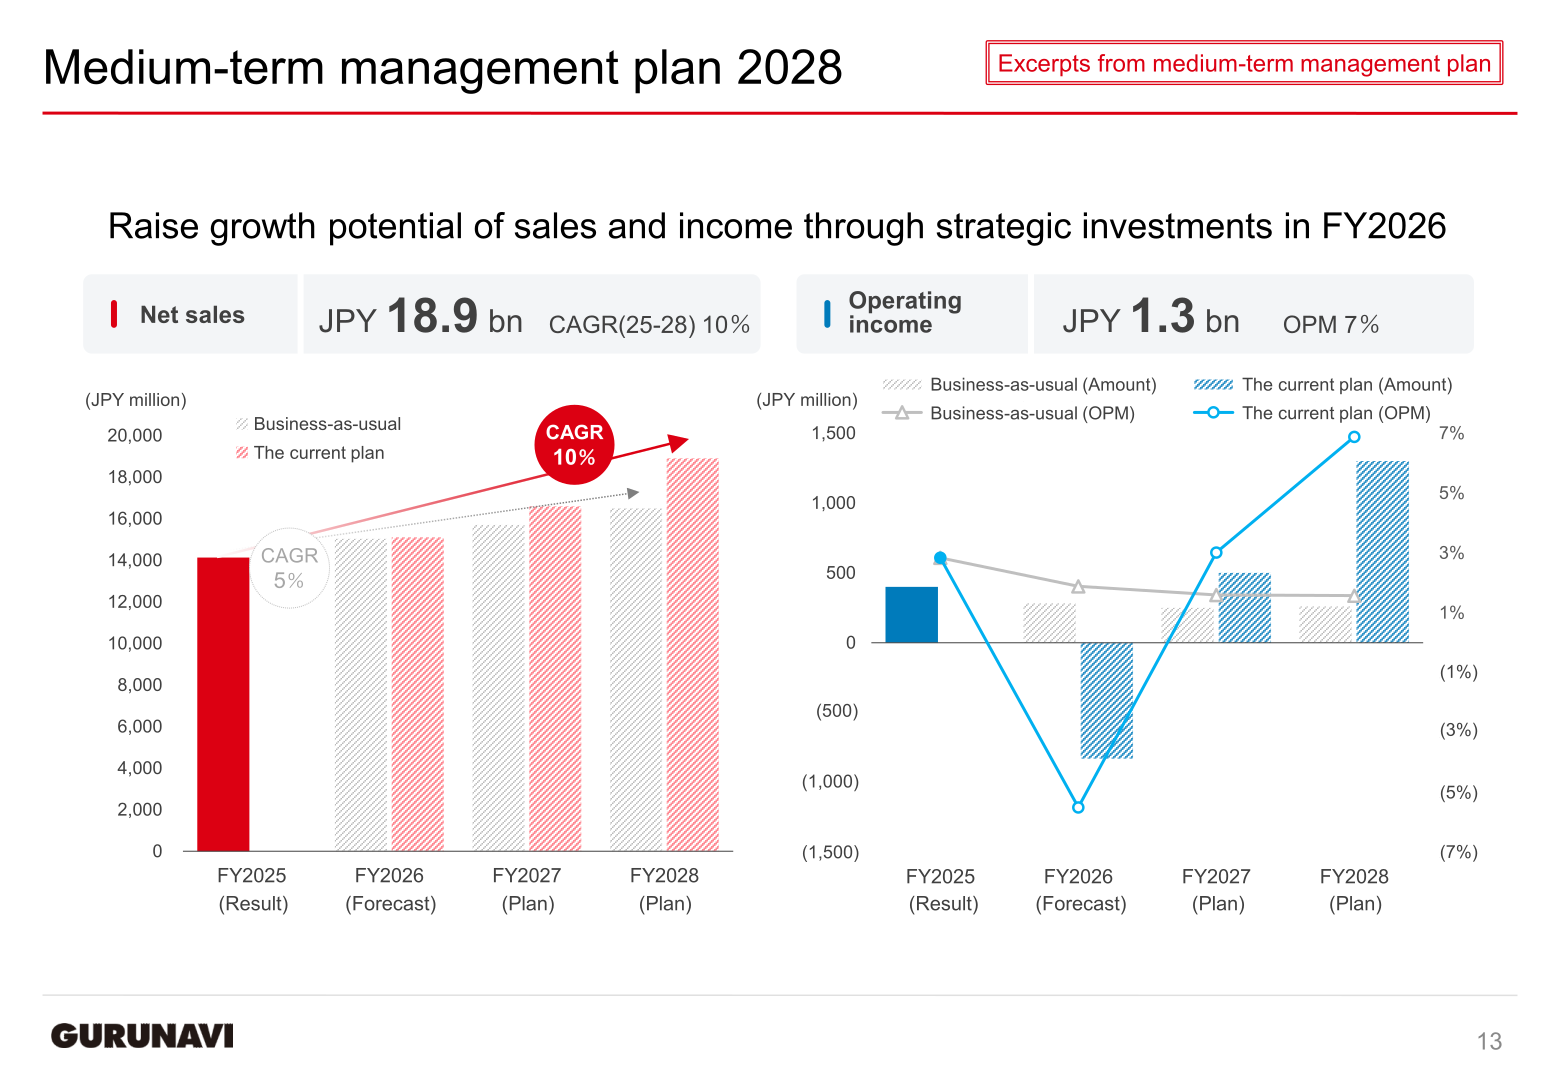
For the fiscal year 2026 the company forecasts net sales of JPY 15,100 million, up 6.8%, with an operating loss of JPY 830 million, an ordinary loss of JPY 920 million and a net loss attributable to owners of parent of JPY 1,000 million. The stated policy is to make strategic investments aiming to maximize corporate value in the medium to long term and to build the foundation for J-curve growth, having begun the evolution from “media” to a “restaurant management platform.” Planned actions include an investment of approximately 1 billion yen in reinforcing the sales structure to expand the restaurant network, with the hiring of approximately 70 people mainly in the restaurant support business and the expansion of the network of referral partners. The company also cites income improvement measures — a review of business operations for the restaurant development business and a strengthened operating structure to accelerate “Gurunavi FineOrder” adoption — and “AI-friendly” initiatives that revamp its products and data into a modular structure.
| Item (JPY million) | FY2025 (results) | FY2026 (forecasts) | YoY |
|---|---|---|---|
| Net sales | 14,132 | 15,100 | +6.8% |
| Operating income (loss) | 400 | (830) | – |
| Ordinary income (loss) | 368 | (920) | – |
| Net income attributable to owners of parent (loss) | 236 | (1,000) | – |
Shareholder Returns
In the historical data table of the presentation, dividends per share on common shares are shown as “-” for FY2025, the same as for FY2020 through FY2024, and the payout ratio is likewise shown as “-“. Dividends per share on Class A preferred shares are also shown as “-” for FY2024 and FY2025. Earnings per share were JPY 4.18 in FY2025 against JPY 2.00 in FY2024, return on equity was 4.7% and return on assets was 2.1%. The number of shares of treasury stock was 526,662 at the end of FY2025. A dividend forecast or shareholder return policy for the fiscal year 2026 cannot be confirmed from the materials.
Medium-Term Management Plan 2028
Excerpts from the medium-term management plan included in the presentation target net sales of JPY 18.9 bn with a CAGR(25-28) of 10%, and operating income of JPY 1.3 bn with an OPM of 7%. The company frames FY2026 strategic investments as raising the growth potential of sales and income relative to a business-as-usual path. Over the longer term, the 2026-2028 phase is positioned as “Expansion” — establishing foundations for new growth to become the No. 1 company with a restaurant information network, with the functional expansion of the “restaurant management platform” and a customer base reconstruction phase — targeting 60,000 paying member restaurants (+17,000) and 100,000 total member restaurants (+23,000), ahead of a next medium-term management plan from 2029 aiming for record-high income.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















