
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: this article covers MEITO CO., LTD.’s most recent completed full year, which the company labels “FYE3/2026” (the fiscal year ended March 31, 2026); our site classifies it as FY2025. Labels in the text, tables and segment data below are kept exactly as they appear in the company’s materials. Net sales rose 3.7% year on year to ¥29,106 million and ordinary profit rose 9.0% to ¥2,913 million, while operating profit fell 12.5% to ¥1,230 million on promotion expenses for the Company’s 80th anniversary projects and write-downs on inventories. Profit attributable to owners of parent fell 35.0% to ¥3,067 million against a prior year that had included a larger gain on sale of investment securities. The company was renamed MEITO CO., LTD. in 2025 (former name: Meito Sangyo Co., Ltd.).
Consolidated Results (Full-Year Actual)
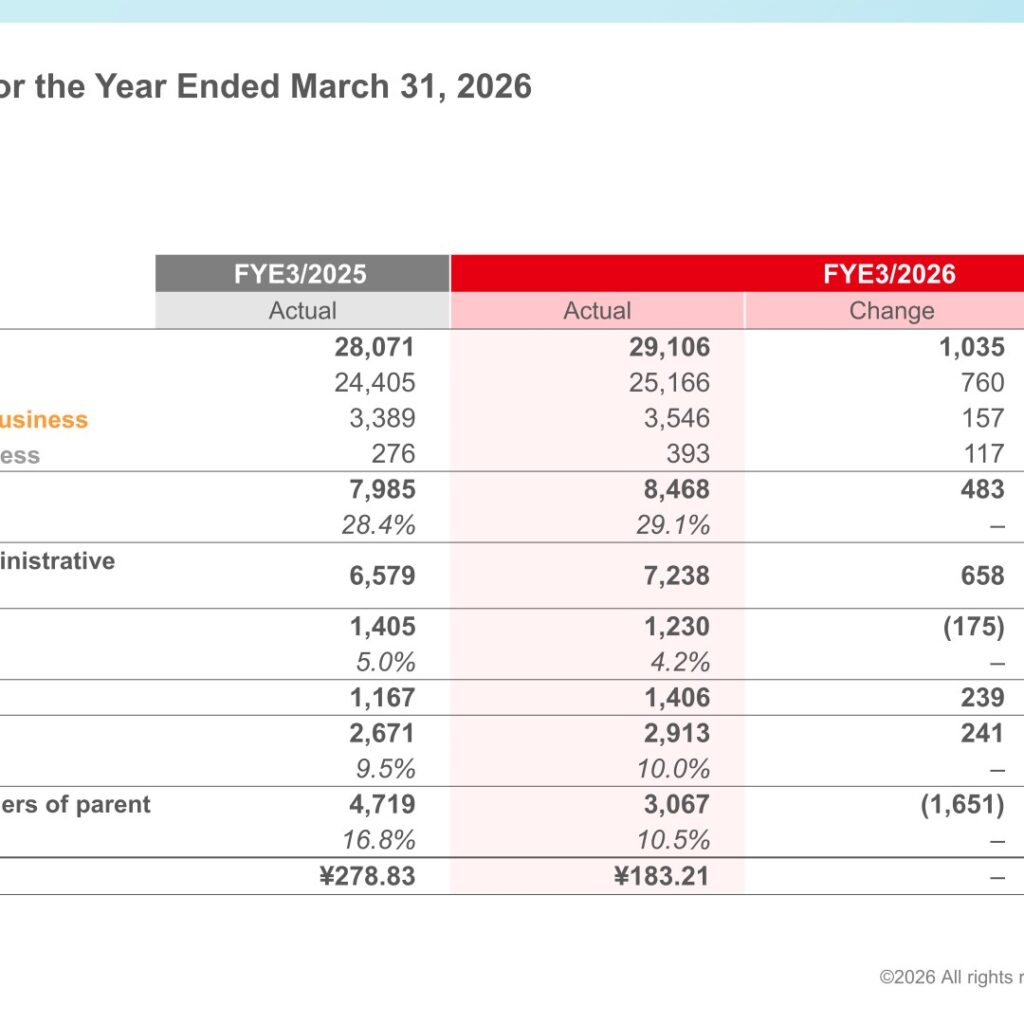
Net sales increased by ¥1,035 million, or 3.7%, to ¥29,106 million. Gross profit rose 6.1% to ¥8,468 million and the gross profit margin improved to 29.1% from 28.4%, but selling, general and administrative expenses increased 10.0% to ¥7,238 million, and operating profit decreased 12.5% to ¥1,230 million. The company attributes the operating profit decline to expenses for various promotions carried out as part of its 80th anniversary projects and to write-downs on inventories, despite improvement of the cost-to-sales ratio attributable to an increase in net sales, changes in product volumes, and price revisions. Ordinary profit increased 9.0% to ¥2,913 million, due to an increase in dividend income (¥1,406 million, up 20.5%) and a gain on sale of investment securities. Profit attributable to owners of parent decreased 35.0% to ¥3,067 million: a gain on sale of investment securities of ¥1,449 million was recorded as extraordinary income this year, against ¥3,363 million in the previous consolidated fiscal year.
| Item (Millions of yen) | FYE3/2026 (Actual) | FYE3/2025 (Actual) | Change | Change (%) |
|---|---|---|---|---|
| Net sales | 29,106 | 28,071 | 1,035 | 3.7% |
| Gross profit | 8,468 | 7,985 | 483 | 6.1% |
| Gross profit margin | 29.1% | 28.4% | – | – |
| Selling, general and administrative expenses | 7,238 | 6,579 | 658 | 10.0% |
| Operating profit | 1,230 | 1,405 | (175) | (12.5%) |
| Operating profit margin | 4.2% | 5.0% | – | – |
| Dividend income | 1,406 | 1,167 | 239 | 20.5% |
| Ordinary profit | 2,913 | 2,671 | 241 | 9.0% |
| Ordinary profit margin | 10.0% | 9.5% | – | – |
| Profit attributable to owners of parent | 3,067 | 4,719 | (1,651) | (35.0%) |
| Net income margin | 10.5% | 16.8% | – | – |
| EPS | ¥183.21 | ¥278.83 | – | – |
In the bridge analysis of operating profit, the impact of higher revenue (including price revisions) contributed ¥328 million and raw materials (including changes to product volume) ¥215 million, with other costs adding ¥92 million, while write-downs on inventories were a negative ¥293 million and SG&A expenses (expenses for the 80th anniversary projects, etc.) a negative ¥517 million, taking operating profit from ¥1,405 million to ¥1,230 million.
Segment Results
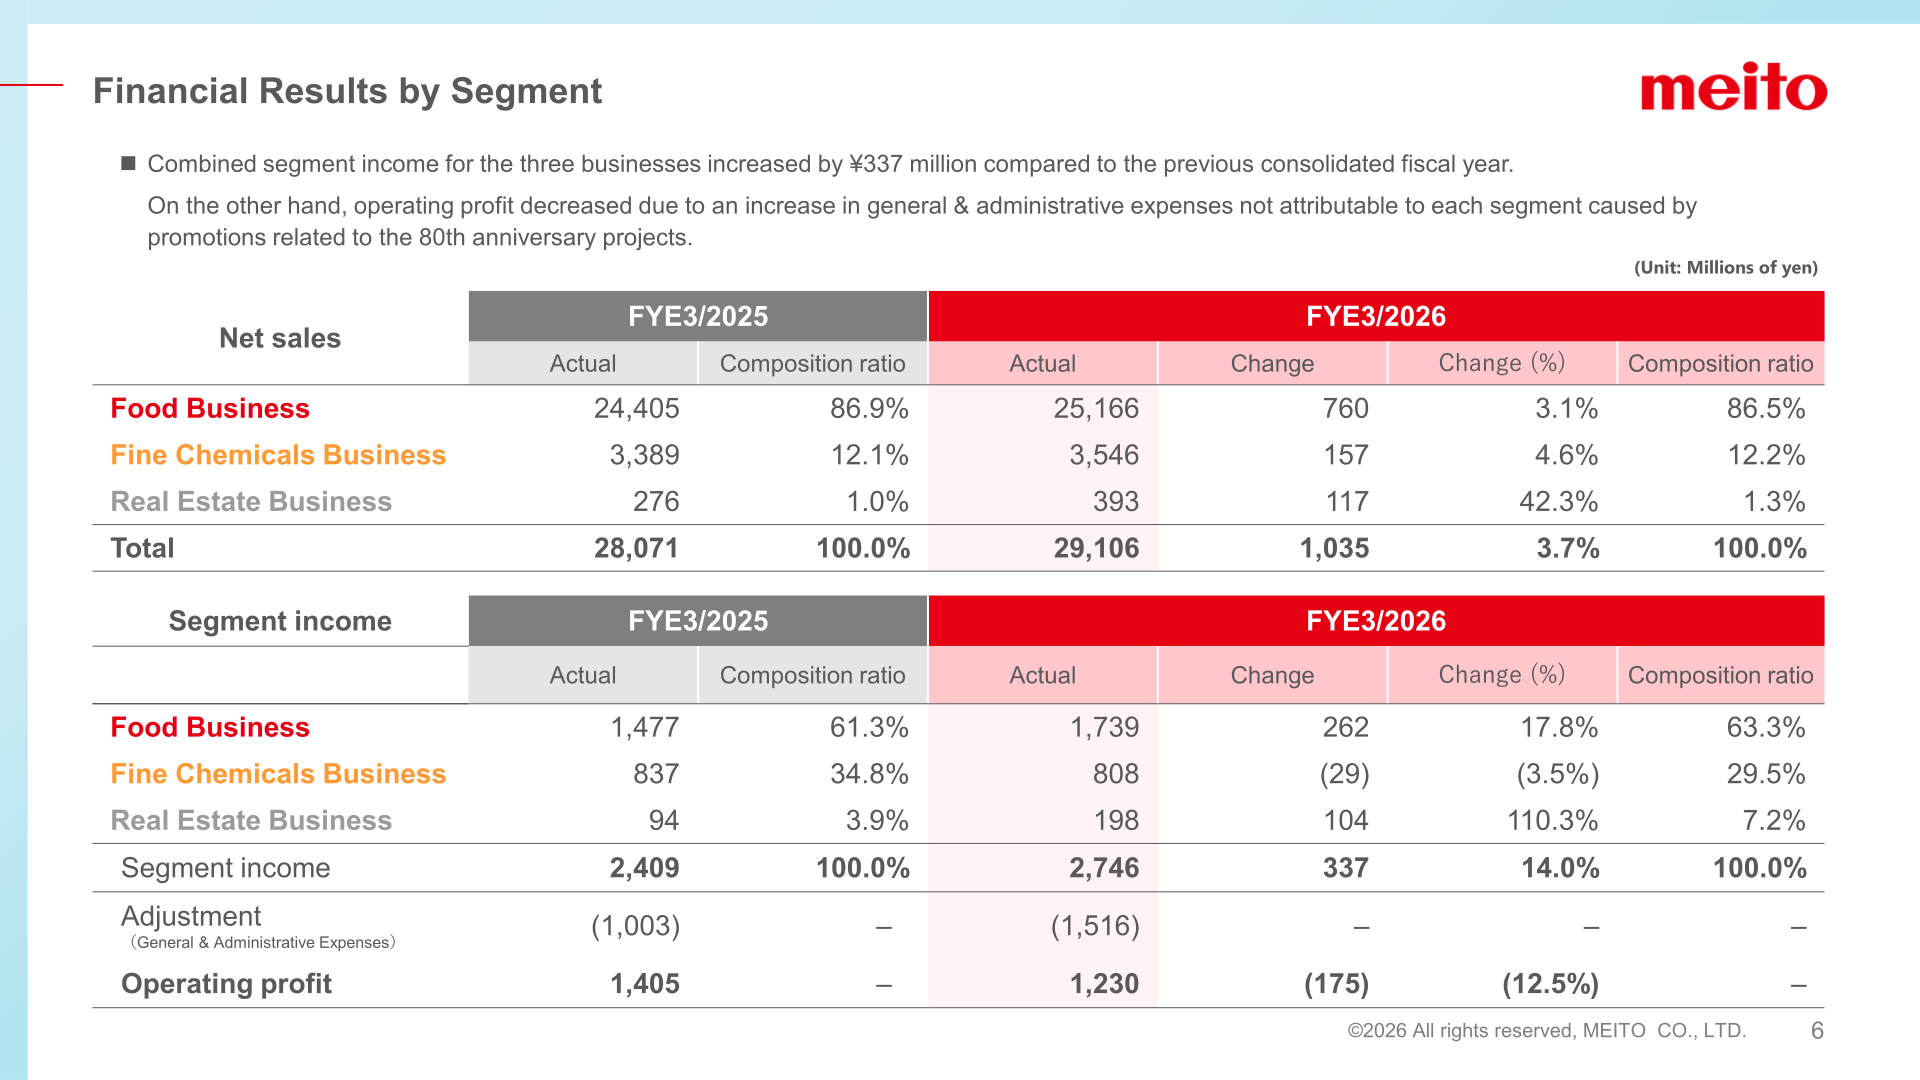
Combined segment income for the three businesses increased by ¥337 million, or 14.0%, to ¥2,746 million. Operating profit nevertheless decreased because general and administrative expenses not attributable to each segment (the adjustment line) widened to ¥1,516 million from ¥1,003 million, reflecting promotions related to the 80th anniversary projects.
| Segment (Millions of yen) | Net sales FYE3/2026 | Net sales FYE3/2025 | Segment income FYE3/2026 | Segment income FYE3/2025 |
|---|---|---|---|---|
| Food Business | 25,166 | 24,405 | 1,739 | 1,477 |
| Fine Chemicals Business | 3,546 | 3,389 | 808 | 837 |
| Real Estate Business | 393 | 276 | 198 | 94 |
| Total / Segment income | 29,106 | 28,071 | 2,746 | 2,409 |
| Adjustment (General & Administrative Expenses) | – | – | (1,516) | (1,003) |
| Operating profit | – | – | 1,230 | 1,405 |
Food Business: 3.1% increase in revenue and 17.8% increase in segment income. Revenue was driven by growth in the powdered drink mix division, where sales of cocoa products expanded to ¥3,245 million. The confectionery division secured revenue exceeding the previous fiscal year’s level at ¥18,949 million, with chocolate products flat year on year and revenue at subsidiary ACE BAKERY Co., Ltd. up on steady sales of jelly products including the “Freeze and Eat Sherbet” series. The ice cream division increased slightly to ¥2,319 million. Segment income benefited from changes in product volumes and price revisions made several times over prior fiscal years, despite write-downs on inventories at fiscal year end.
Fine Chemicals Business: 4.6% increase in revenue and 3.5% decrease in segment income. Revenue rose on aggressive sales activities mainly in overseas markets, with overseas sales of ¥2,364 million, while segment income fell due to a higher cost-of-sales ratio. In the enzyme division (¥2,057 million), sales of “Rennet,” a milk-clotting enzyme for cheese, increased significantly overseas, while “Lipase” was flat. The pharmaceuticals division decreased to ¥1,278 million on lower sales of “Dextran sulfate.” Real Estate Business: revenue rose 42.3% and segment income 110.3%, due to the acquisition of real estate in Tokyo in September 2025 and the commencement of leasing.
Balance Sheet and Cash Flow
Total liabilities and net assets grew to ¥100,319 million from ¥83,325 million. Non-current assets increased ¥18,318 million to ¥84,247 million, with property, plant and equipment up ¥9,838 million to ¥30,088 million and investment securities up ¥8,669 million to ¥51,733 million on a rise in market prices of shares held. Cash and deposits declined to ¥3,575 million from ¥7,194 million. Net cash used in operating activities was ¥708 million and net cash used in investing activities was ¥9,296 million, while financing activities provided ¥6,387 million; the company notes that land was acquired in the Real Estate Business and construction in progress increased due to the construction of a new plant, with borrowings implemented to pay for the capital investment.
Full-Year Forecast
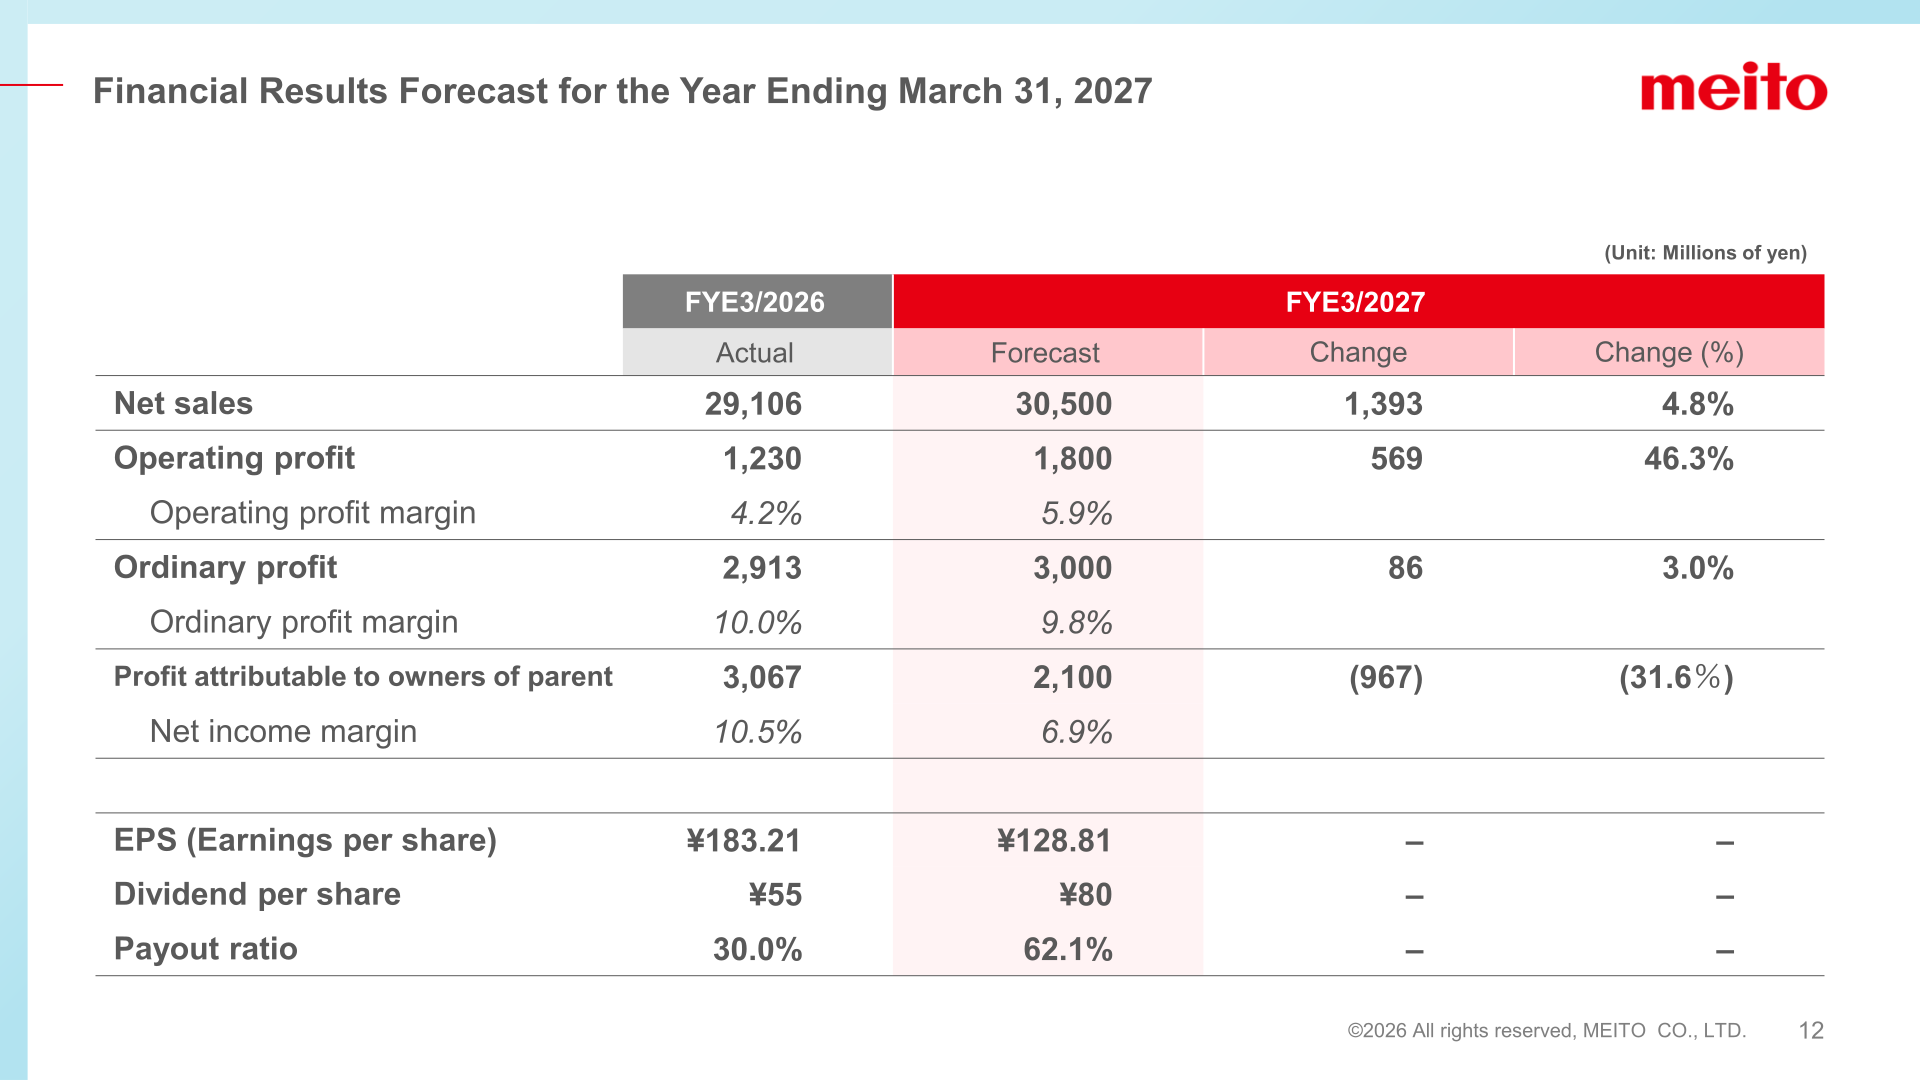
For the year ending March 31, 2027, the company forecasts net sales of ¥30,500 million (up 4.8%), operating profit of ¥1,800 million (up 46.3%) and ordinary profit of ¥3,000 million (up 3.0%), with profit attributable to owners of parent of ¥2,100 million (down 31.6%). Forecast EPS is ¥128.81.
| Item (Millions of yen) | FYE3/2027 (Forecast) | FYE3/2026 (Actual) | Change | Change (%) |
|---|---|---|---|---|
| Net sales | 30,500 | 29,106 | 1,393 | 4.8% |
| Operating profit | 1,800 | 1,230 | 569 | 46.3% |
| Operating profit margin | 5.9% | 4.2% | – | – |
| Ordinary profit | 3,000 | 2,913 | 86 | 3.0% |
| Ordinary profit margin | 9.8% | 10.0% | – | – |
| Profit attributable to owners of parent | 2,100 | 3,067 | (967) | (31.6%) |
| Net income margin | 6.9% | 10.5% | – | – |
| EPS (Earnings per share) | ¥128.81 | ¥183.21 | – | – |
| Dividend per share | ¥80 | ¥55 | – | – |
| Payout ratio | 62.1% | 30.0% | – | – |
| Segment net sales (Millions of yen) | FYE3/2027 (Forecast) | FYE3/2026 (Actual) | Change | Change (%) |
|---|---|---|---|---|
| Food Business | 26,400 | 25,166 | 1,233 | 4.9% |
| Fine Chemicals Business | 3,600 | 3,546 | 53 | 1.5% |
| Real Estate Business | 500 | 393 | 106 | 27.0% |
| Total | 30,500 | 29,106 | 1,393 | 4.8% |
Shareholder Returns
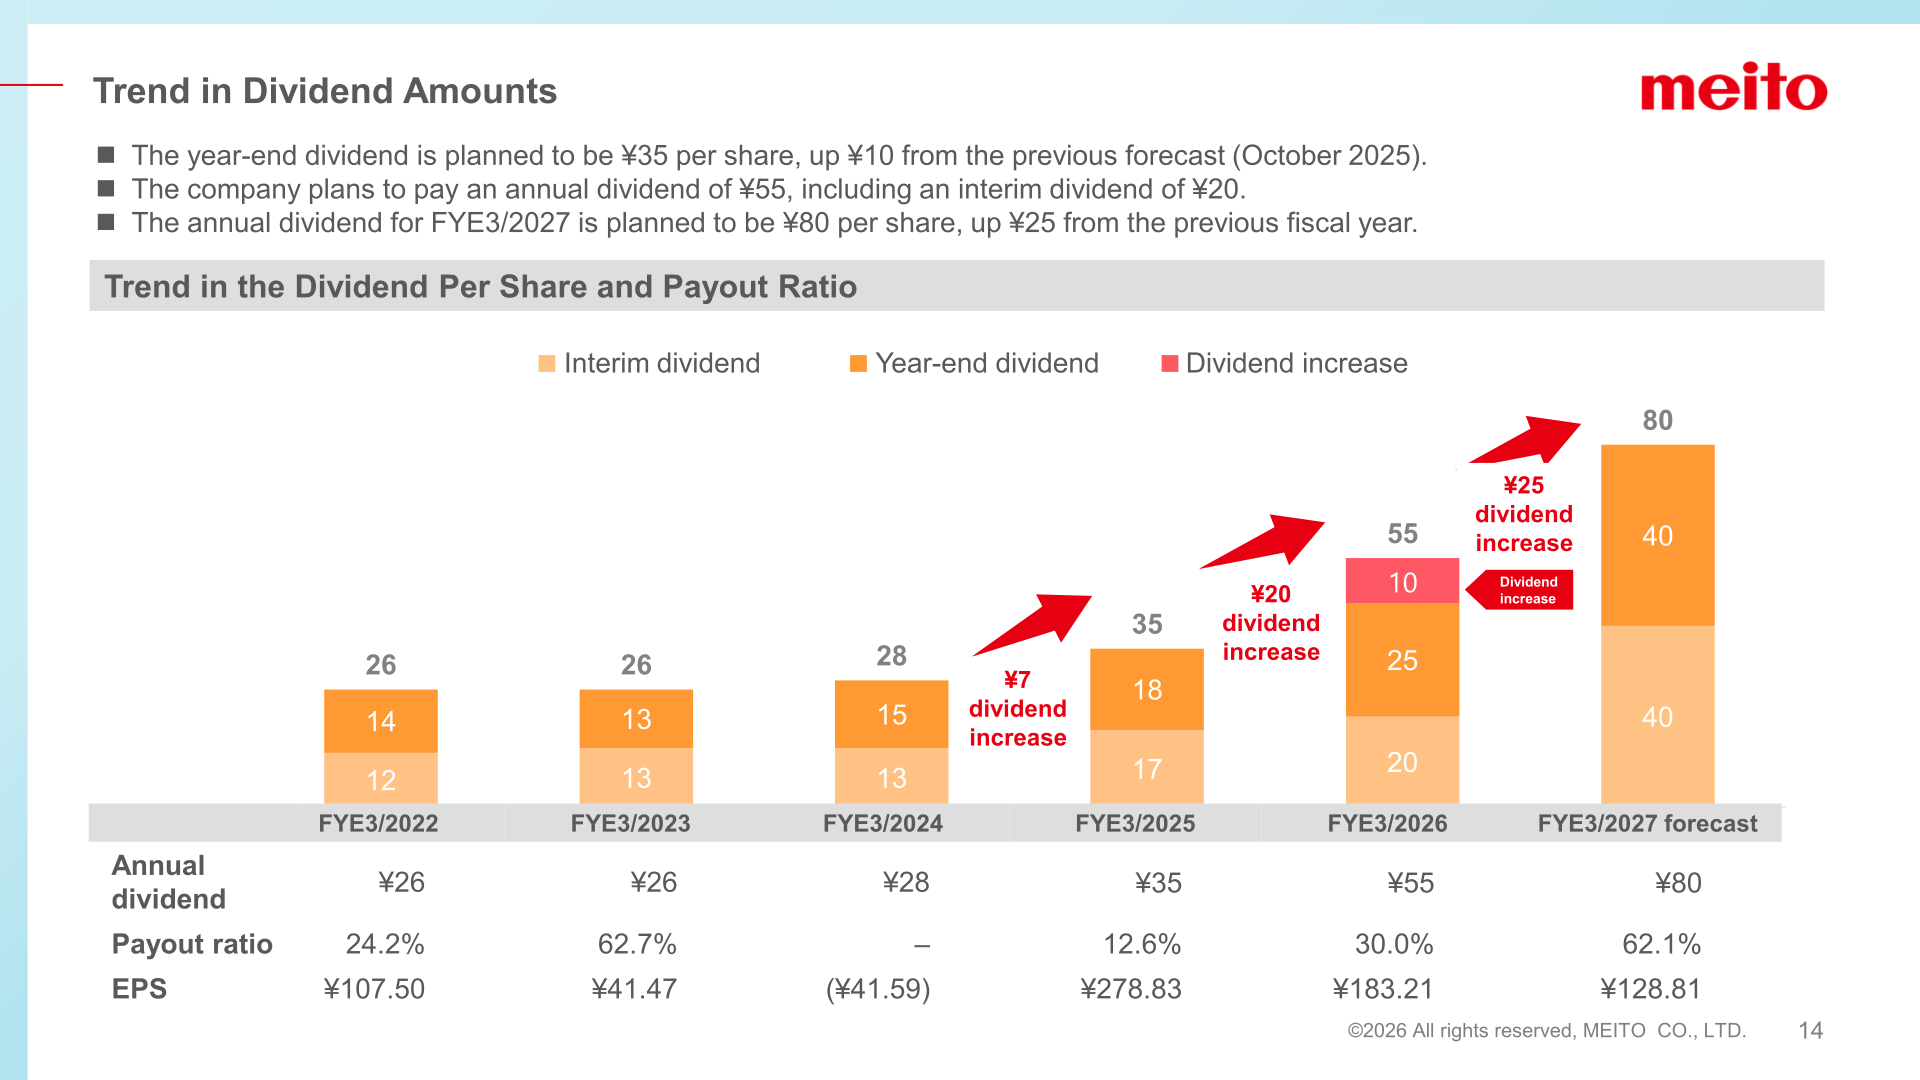
The year-end dividend is planned to be ¥35 per share, up ¥10 from the previous forecast (October 2025). Including an interim dividend of ¥20, the company plans to pay an annual dividend of ¥55 for FYE3/2026, for a payout ratio of 30.0%, versus ¥35 in FYE3/2025. The annual dividend for FYE3/2027 is planned to be ¥80 per share, up ¥25 from the previous fiscal year, with a payout ratio of 62.1%.
| Item | FYE3/2024 | FYE3/2025 | FYE3/2026 | FYE3/2027 (Forecast) |
|---|---|---|---|---|
| Annual dividend | ¥28 | ¥35 | ¥55 | ¥80 |
| Payout ratio | – | 12.6% | 30.0% | 62.1% |
| EPS | (¥41.59) | ¥278.83 | ¥183.21 | ¥128.81 |
Under the review of the financial strategy of the Medium-Term Management Plan, the annual dividend per share for FYE3/2027 is raised by ¥20, from ¥60 planned prior to the review to ¥80. For the acquisition and cancellation of own shares, the total amount is increased to ¥3.5 billion from the previous plan of ¥2.0 billion under the medium-term management plan; as approximately ¥1.5 billion had been spent by FYE3/2026, the remaining approximately ¥2.0 billion will be used for the acquisition and cancellation of own shares in FYE3/2027. The company also plans to accelerate the sale of shareholdings in FYE3/2027, with planned shareholder returns totaling approximately ¥3.3 billion.
Medium-Term Plan and Topics
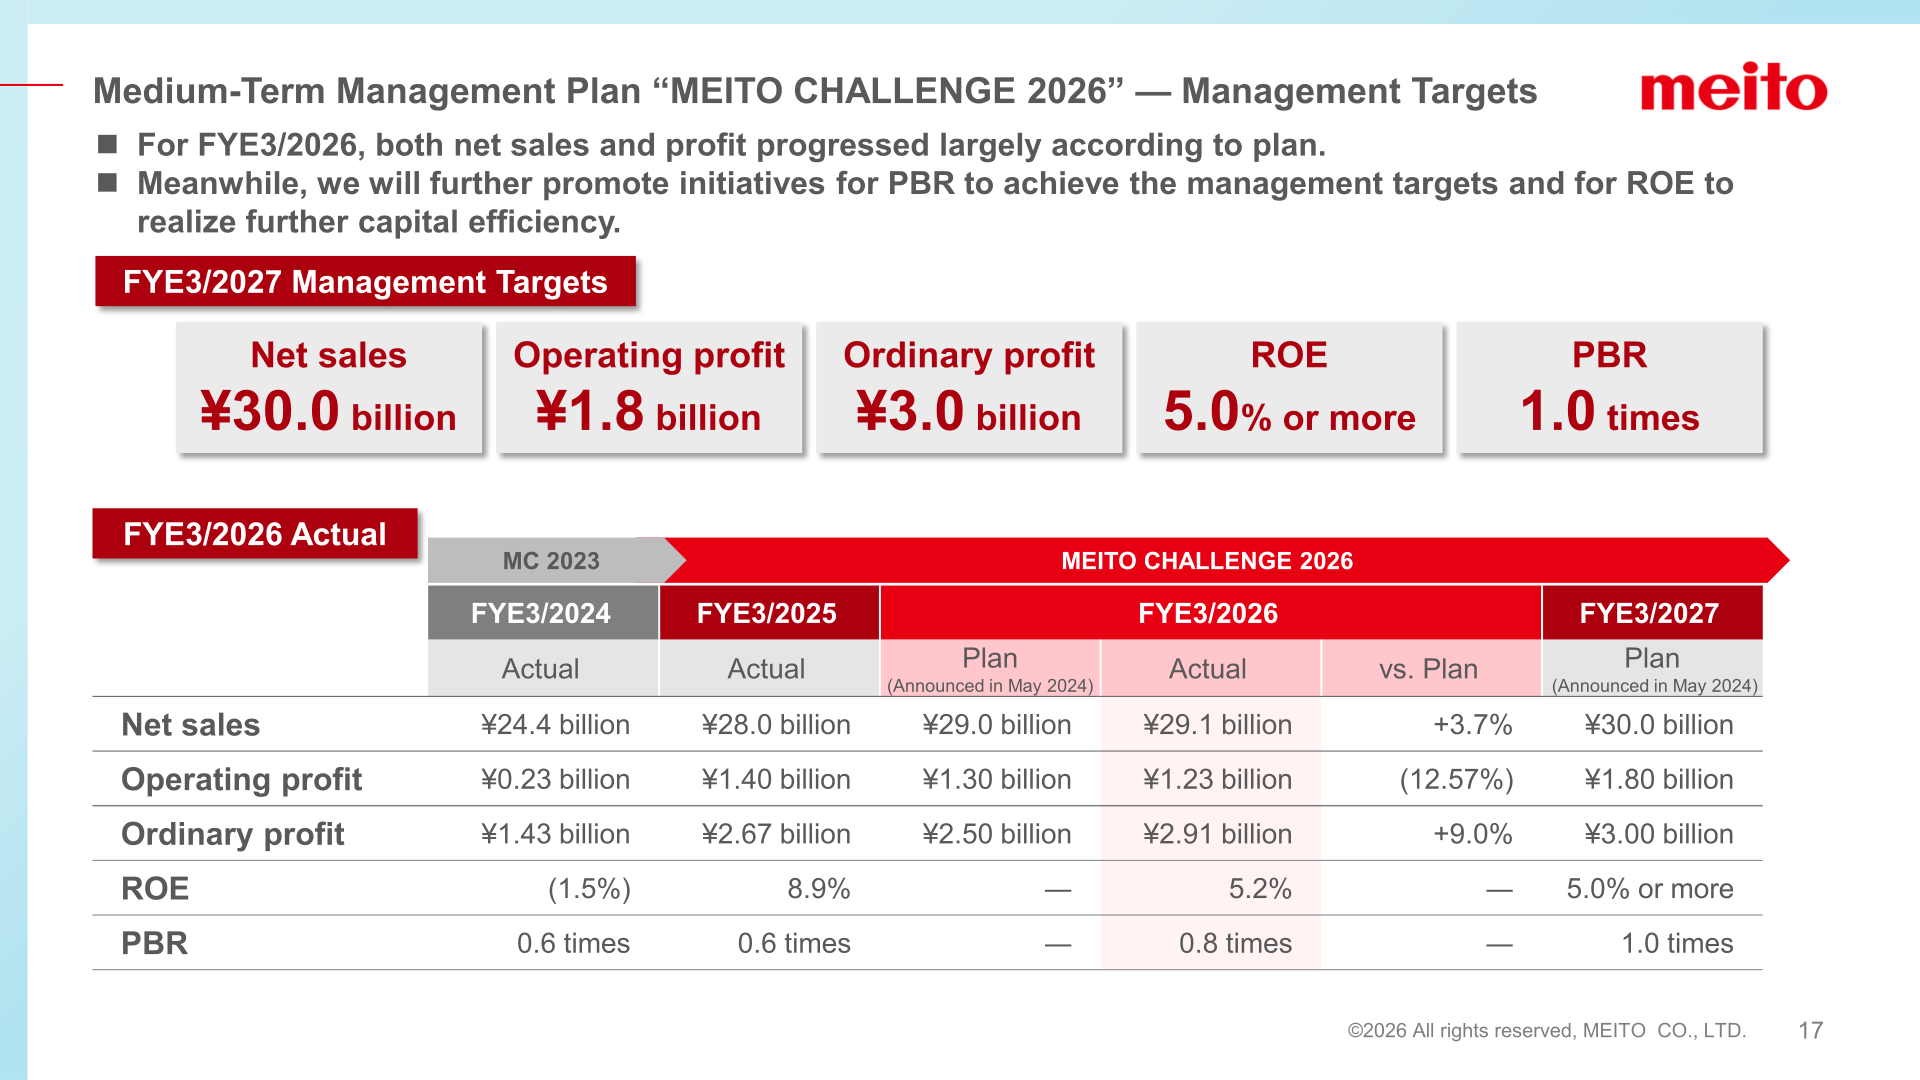
Under the Medium-Term Management Plan “MEITO CHALLENGE 2026,” the company states that for FYE3/2026 both net sales and profit progressed largely according to plan. Against the plan announced in May 2024 of ¥29.0 billion in net sales, ¥1.30 billion in operating profit and ¥2.50 billion in ordinary profit, actual results were ¥29.1 billion (+3.7%), ¥1.23 billion (12.57% below plan) and ¥2.91 billion (+9.0%). ROE was 5.2% and PBR 0.8 times in FYE3/2026. The FYE3/2027 management targets are net sales of ¥30.0 billion, operating profit of ¥1.8 billion, ordinary profit of ¥3.0 billion, ROE of 5.0% or more, and PBR of 1.0 times.
| Management targets | FYE3/2025 (Actual) | FYE3/2026 (Actual) | FYE3/2027 Plan (Announced in May 2024) |
|---|---|---|---|
| Net sales | ¥28.0 billion | ¥29.1 billion | ¥30.0 billion |
| Operating profit | ¥1.40 billion | ¥1.23 billion | ¥1.80 billion |
| Ordinary profit | ¥2.67 billion | ¥2.91 billion | ¥3.00 billion |
| ROE | 8.9% | 5.2% | 5.0% or more |
| PBR | 0.6 times | 0.8 times | 1.0 times |
On raw materials, the company notes that chocolate prices have risen worldwide due to the cacao bean price surge of recent years, causing demand to recede, and that with cacao bean growing conditions relatively favorable the market has reversed and now favors supply over demand. Because it holds inventories of certain raw materials purchased prior to the decline in market price, it expects it to take some time before the market price decline is reflected in product costs, and it intends to work through inventories quickly through strengthened sales initiatives and product formulation adjustments. It also flags growing uncertainty about future market prices of naphtha-derived raw materials used for packaging materials due to the Middle East situation.
The company also disclosed the financial policy of its next Medium-Term Management Plan, “MEITO CHALLENGE 2029,” built on three key initiatives: generating cash by the sale of shareholdings; planning large-scale strategic growth investments totaling more than ¥20.0 billion; and expanding shareholder returns totaling more than ¥10.0 billion, by flexibly implementing the acquisition and cancellation of own shares while maintaining progressive dividends.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















