
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: the company labels this period FY10/2025, the fiscal year ended October 2025; it is classified as FY2025 on this site, while the labels in the text and tables below follow the source materials. Note: FIT EASY does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials, with figures transcribed as reported. In FY10/2025 (full year), FIT EASY Inc. posted net sales of 9.73 billion yen (145.8% of the previous year) on 60 new store openings. Operating profit was 2.31 billion yen (141.7%), ordinary profit was 2.31 billion yen (144.8%) and net income was 1.52 billion yen (141.3%), for higher sales and higher profits across the board. On solid member acquisition, net income came to 1.52 billion yen, above the earnings forecast of 1.48 billion yen. Chain-wide sales including membership-fee receipts at franchised stores were 20.27 billion yen (156.5% of the previous year).
Results (FY10/2025 Actual)
Against the full-year earnings forecast, net sales came to 9.73 billion yen, or 105.8% of plan; operating profit 2.31 billion yen, or 104.6% of plan; ordinary profit 2.31 billion yen, or 104.0% of plan; and net income 1.52 billion yen, or 103.3% of plan, all above plan. Although SG&A expenses increased on items such as costs for the move to the Prime Market and shareholder benefit costs, the operating margin was maintained at 23.8%, almost the same as the previous year, and the net margin was 15.7%, at the same level as the previous year.
| Item | FY10/2024 (million yen) | FY10/2025 (million yen) | YoY |
|---|---|---|---|
| Net sales | 6,673 | 9,731 | 145.8% |
| Operating profit (operating margin) | 1,631 (24.5%) | 2,311 (23.8%) | 141.7% |
| Ordinary profit (ordinary margin) | 1,600 (24.0%) | 2,318 (23.8%) | 144.8% |
| Net income (net margin) | 1,082 (16.2%) | 1,528 (15.7%) | 141.3% |
Net Sales Composition (by Revenue Category)
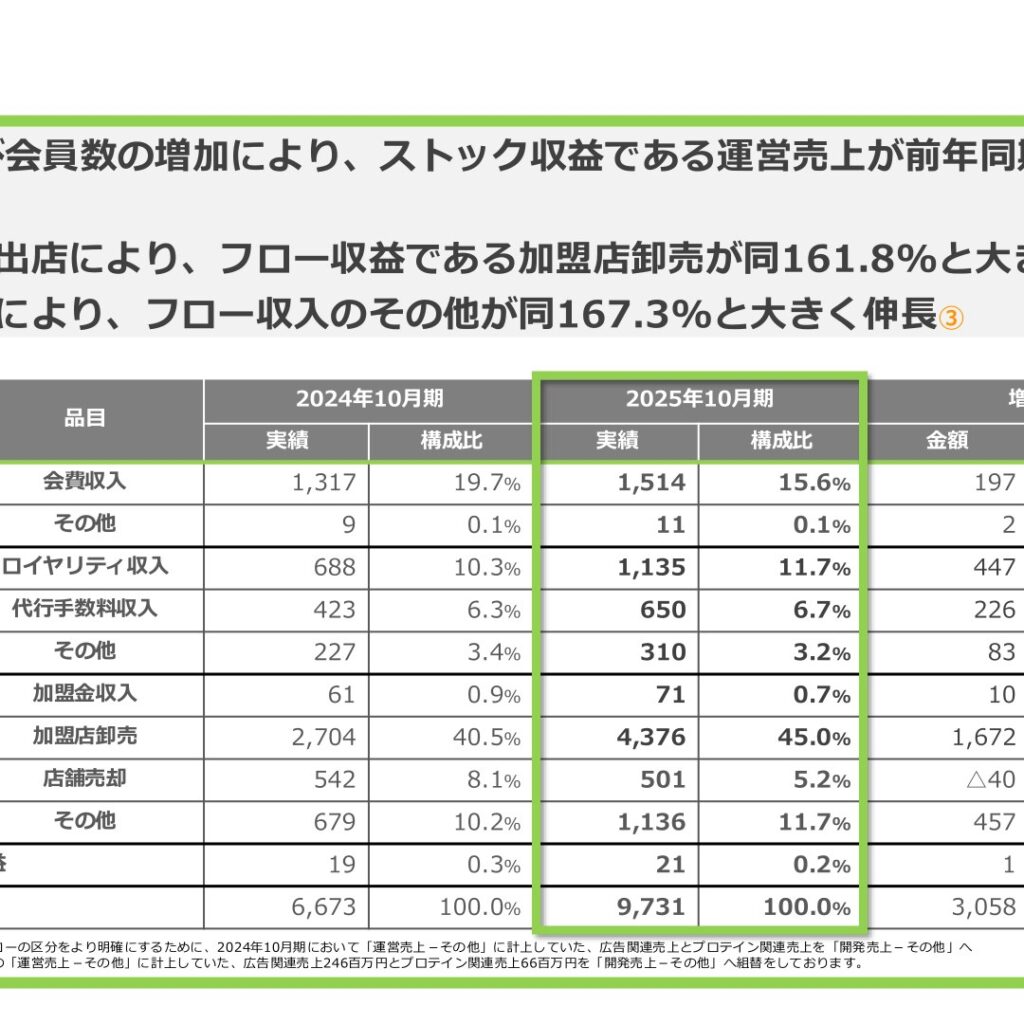
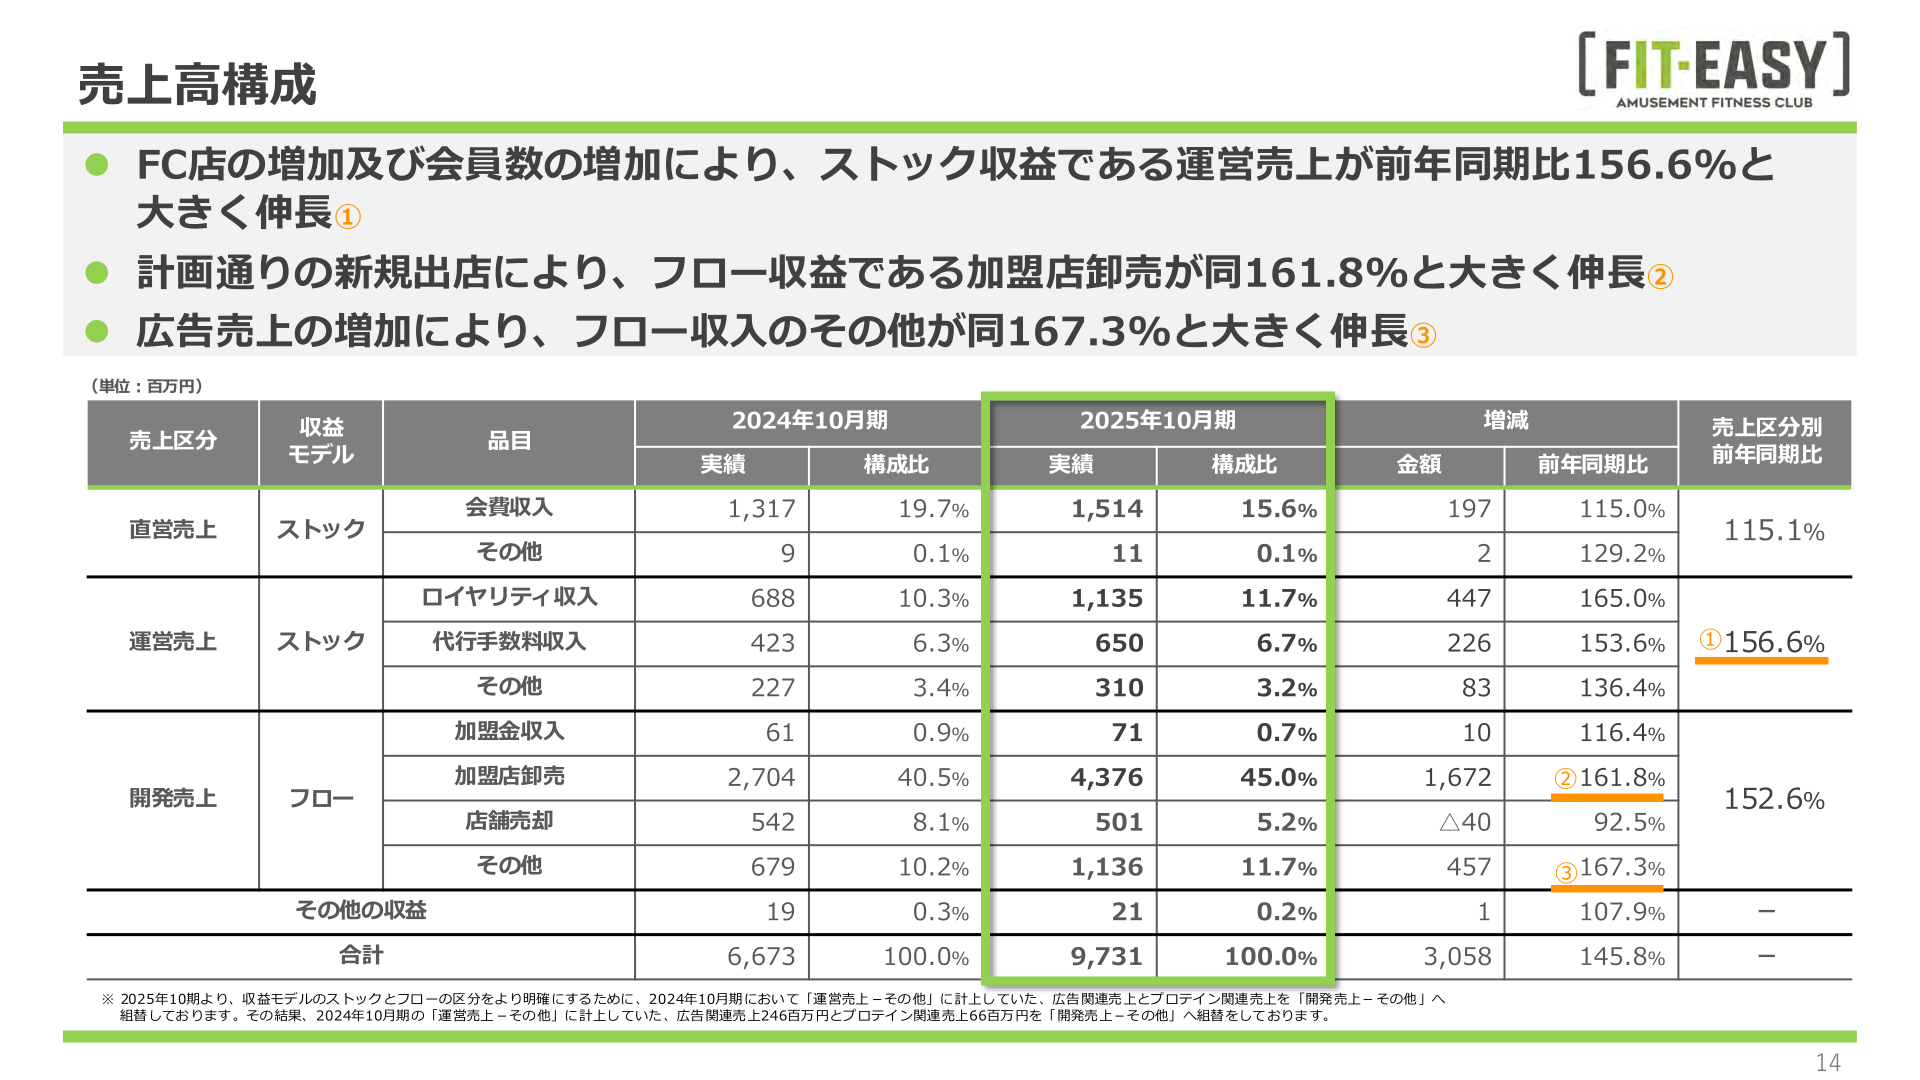
By revenue model, both stock revenue, consisting of directly operated store sales and operating sales, and flow revenue, consisting of development sales, grew. With the increase in franchised stores and in the number of members, royalty income within operating sales grew to 165.0% of the previous year and agency commission income to 153.6%. Franchisee wholesale, a flow revenue item, grew to 161.8% on new store openings in line with plan, and other sales reached 167.3% on an increase in advertising sales.
| Item | FY10/2024 (million yen) | FY10/2025 (million yen) | Change | YoY |
|---|---|---|---|---|
| Membership fee income | 1,317 | 1,514 | 197 | 115.0% |
| Other (directly operated store sales) | 9 | 11 | 2 | 129.2% |
| Royalty income | 688 | 1,135 | 447 | 165.0% |
| Agency commission income | 423 | 650 | 226 | 153.6% |
| Other (operating sales) | 227 | 310 | 83 | 136.4% |
| Franchise entry fee income | 61 | 71 | 10 | 116.4% |
| Franchisee wholesale | 2,704 | 4,376 | 1,672 | 161.8% |
| Sale of stores | 542 | 501 | △40 | 92.5% |
| Other (development sales) | 679 | 1,136 | 457 | 167.3% |
| Other revenue | 19 | 21 | 1 | 107.9% |
| Total | 6,673 | 9,731 | 3,058 | 145.8% |
Full-Year Forecast (FY10/2026)
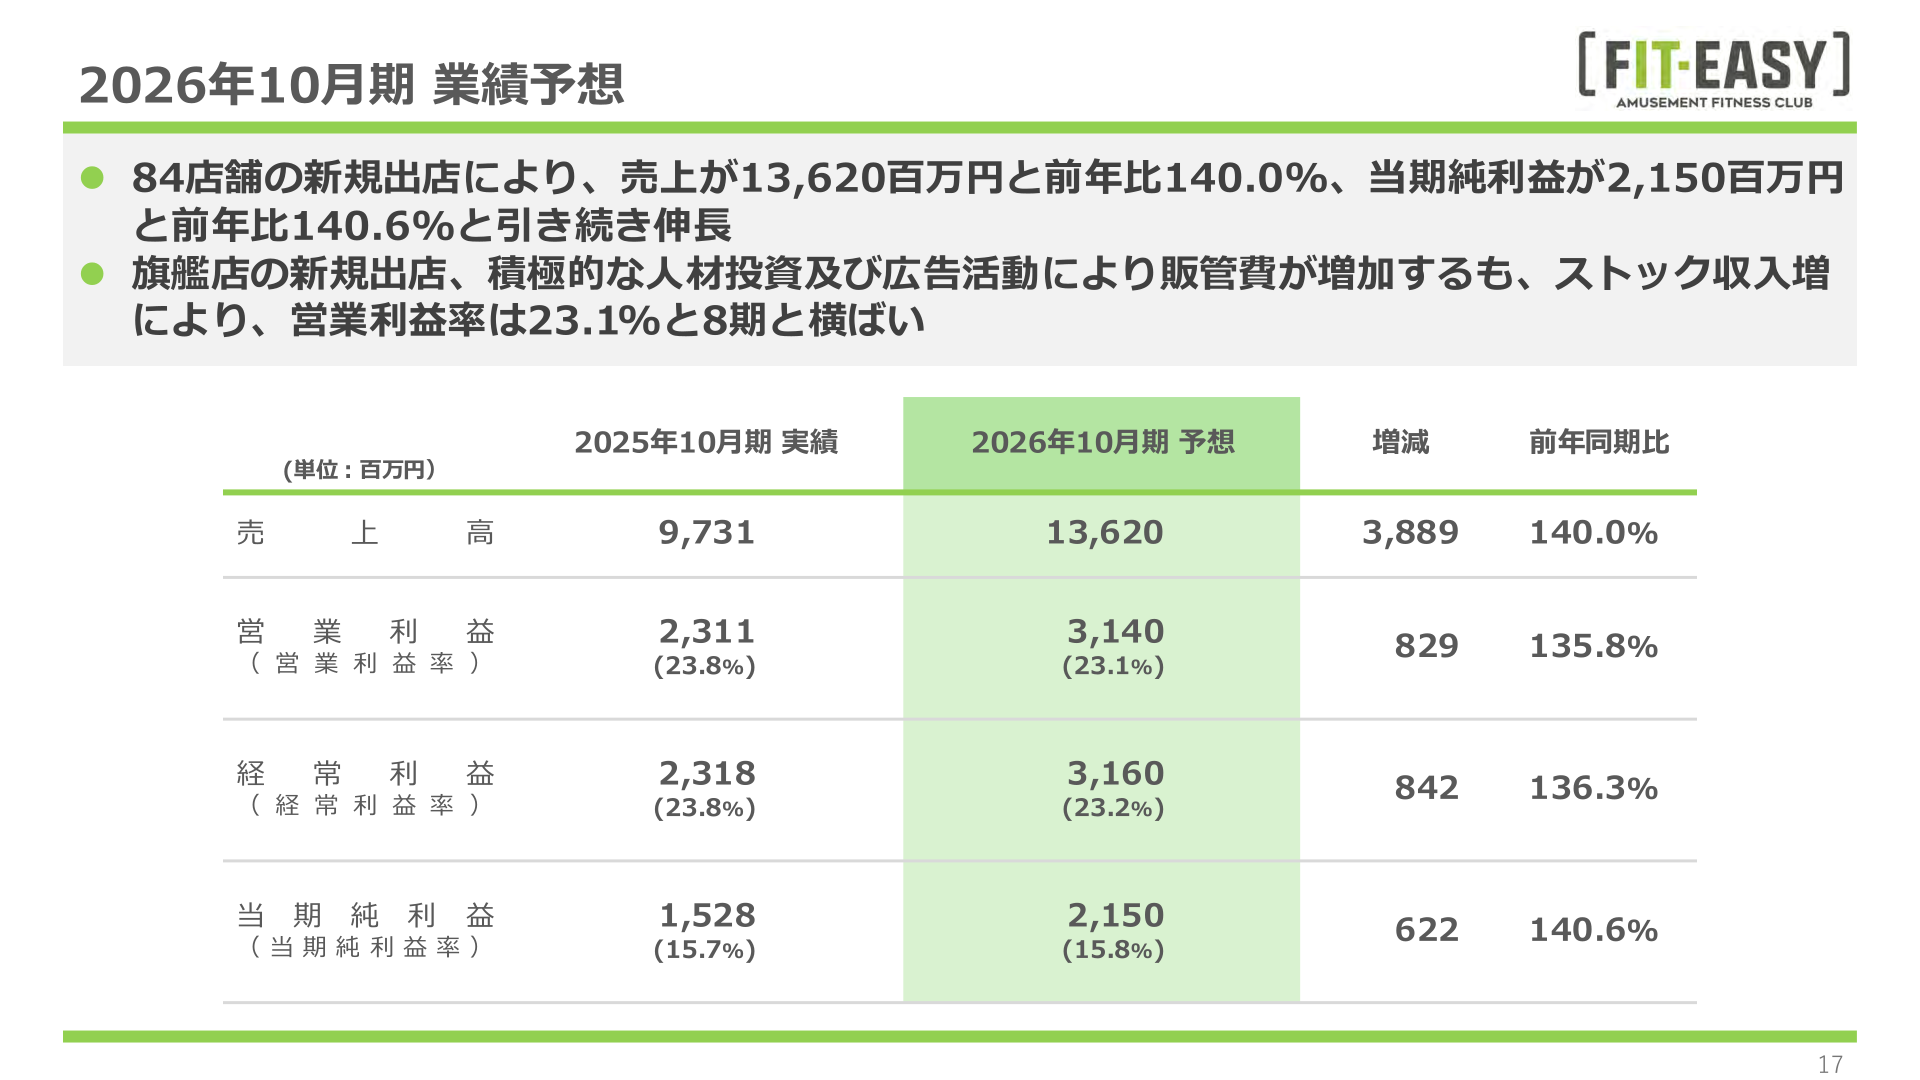
For FY10/2026 the company expects continued growth, with net sales of 13,620 million yen (140.0% of the previous year) and net income of 2,150 million yen (140.6%) on 84 new store openings. Although SG&A expenses will increase on new flagship store openings, aggressive investment in human resources and advertising activities, the operating margin is expected to be 23.1%, roughly flat versus FY10/2025, thanks to higher stock revenue.
| Item | FY10/2025 Actual (million yen) | FY10/2026 Forecast (million yen) | Change | YoY |
|---|---|---|---|---|
| Net sales | 9,731 | 13,620 | 3,889 | 140.0% |
| Operating profit (operating margin) | 2,311 (23.8%) | 3,140 (23.1%) | 829 | 135.8% |
| Ordinary profit (ordinary margin) | 2,318 (23.8%) | 3,160 (23.2%) | 842 | 136.3% |
| Net income (net margin) | 1,528 (15.7%) | 2,150 (15.8%) | 622 | 140.6% |
Shareholder Returns
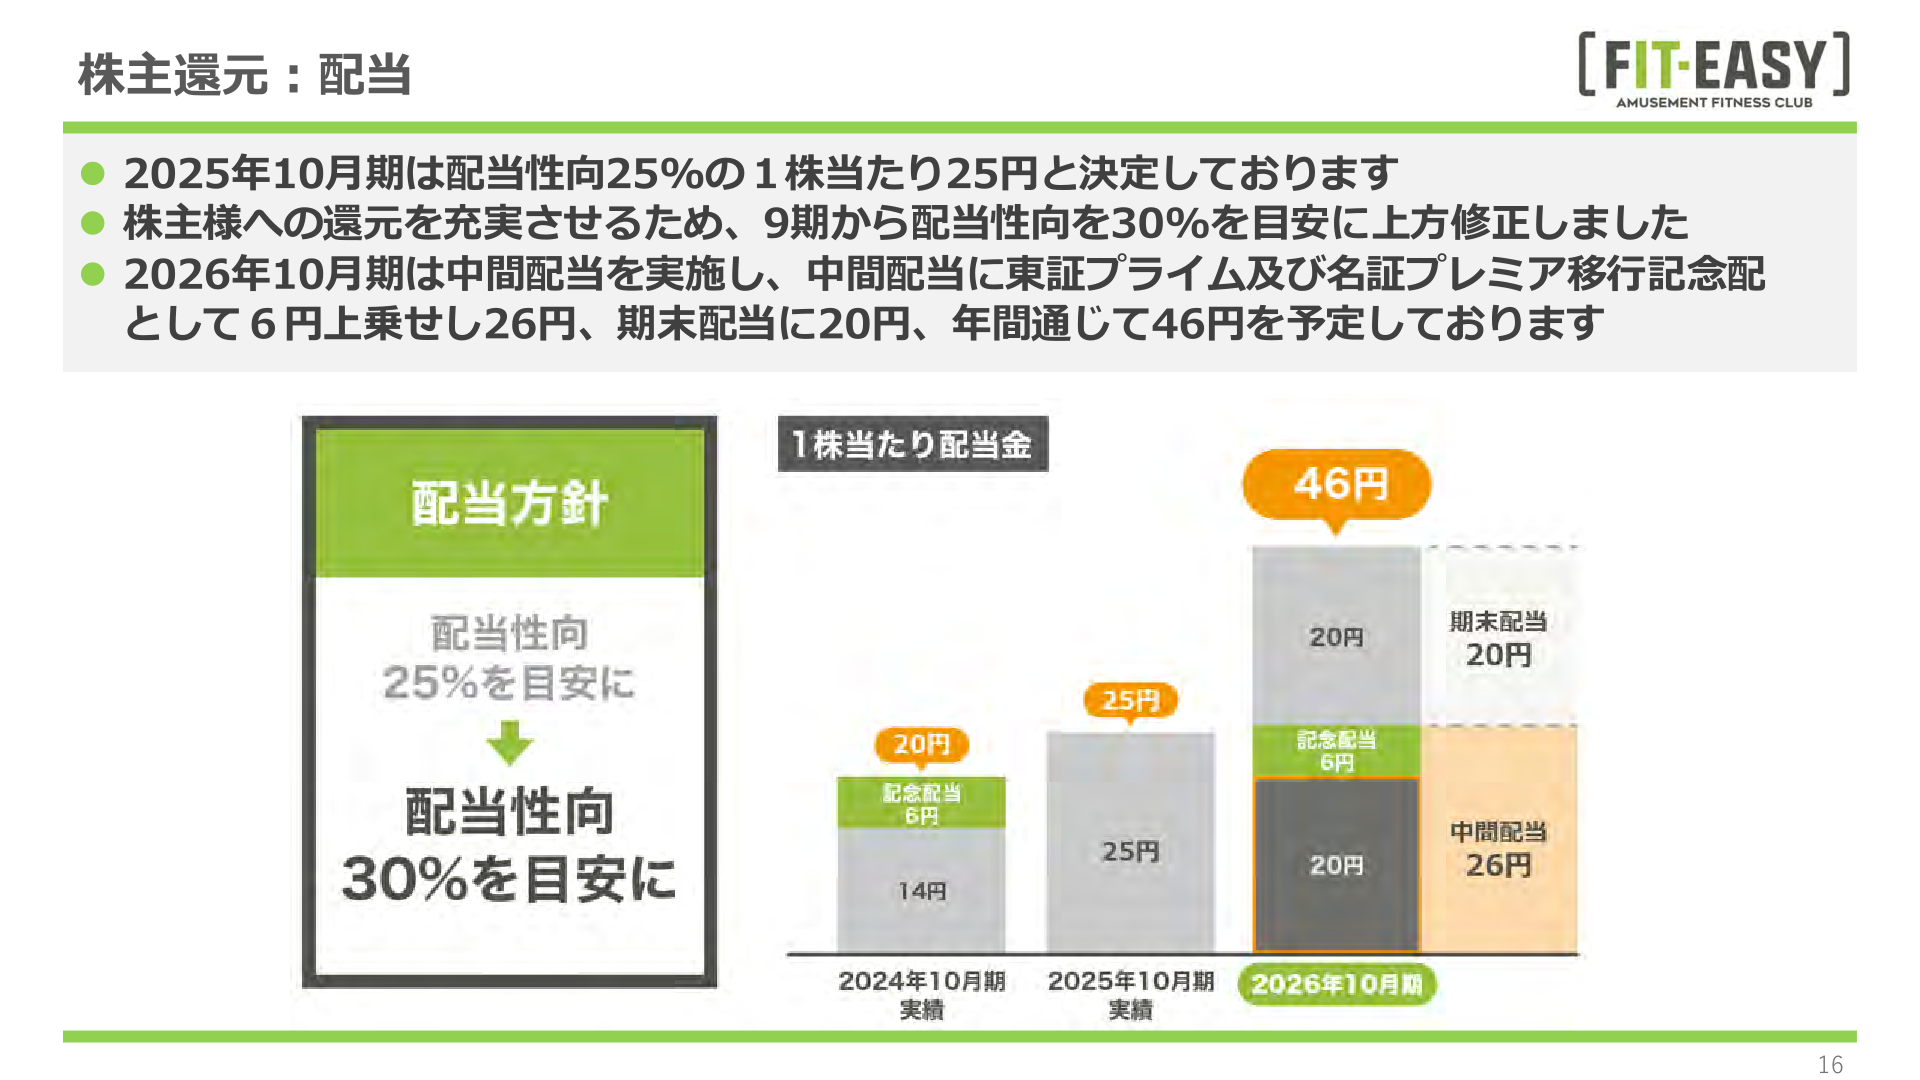
For FY10/2025 the company decided on a dividend of 25 yen per share, corresponding to a payout ratio of 25%. In order to enhance returns to shareholders, it revised the payout ratio upward to a guide of 30% from the 9th fiscal year (FY10/2026). In FY10/2026 the company will pay an interim dividend, and the interim dividend is set at 26 yen, which includes an additional 6 yen to commemorate the move to the TSE Prime Market and the Nagoya Stock Exchange Premier Market; together with a planned year-end dividend of 20 yen, the annual dividend is planned at 46 yen.
| Fiscal year | Payout ratio | Dividend per share |
|---|---|---|
| FY10/2025 (Actual) | 25% | 25 yen |
| FY10/2026 (Planned) | 30% guide | Interim 26 yen (including 6 yen commemorative) + year-end 20 yen = 46 yen for the year |
Rolling Revision of the Medium-Term Management Plan
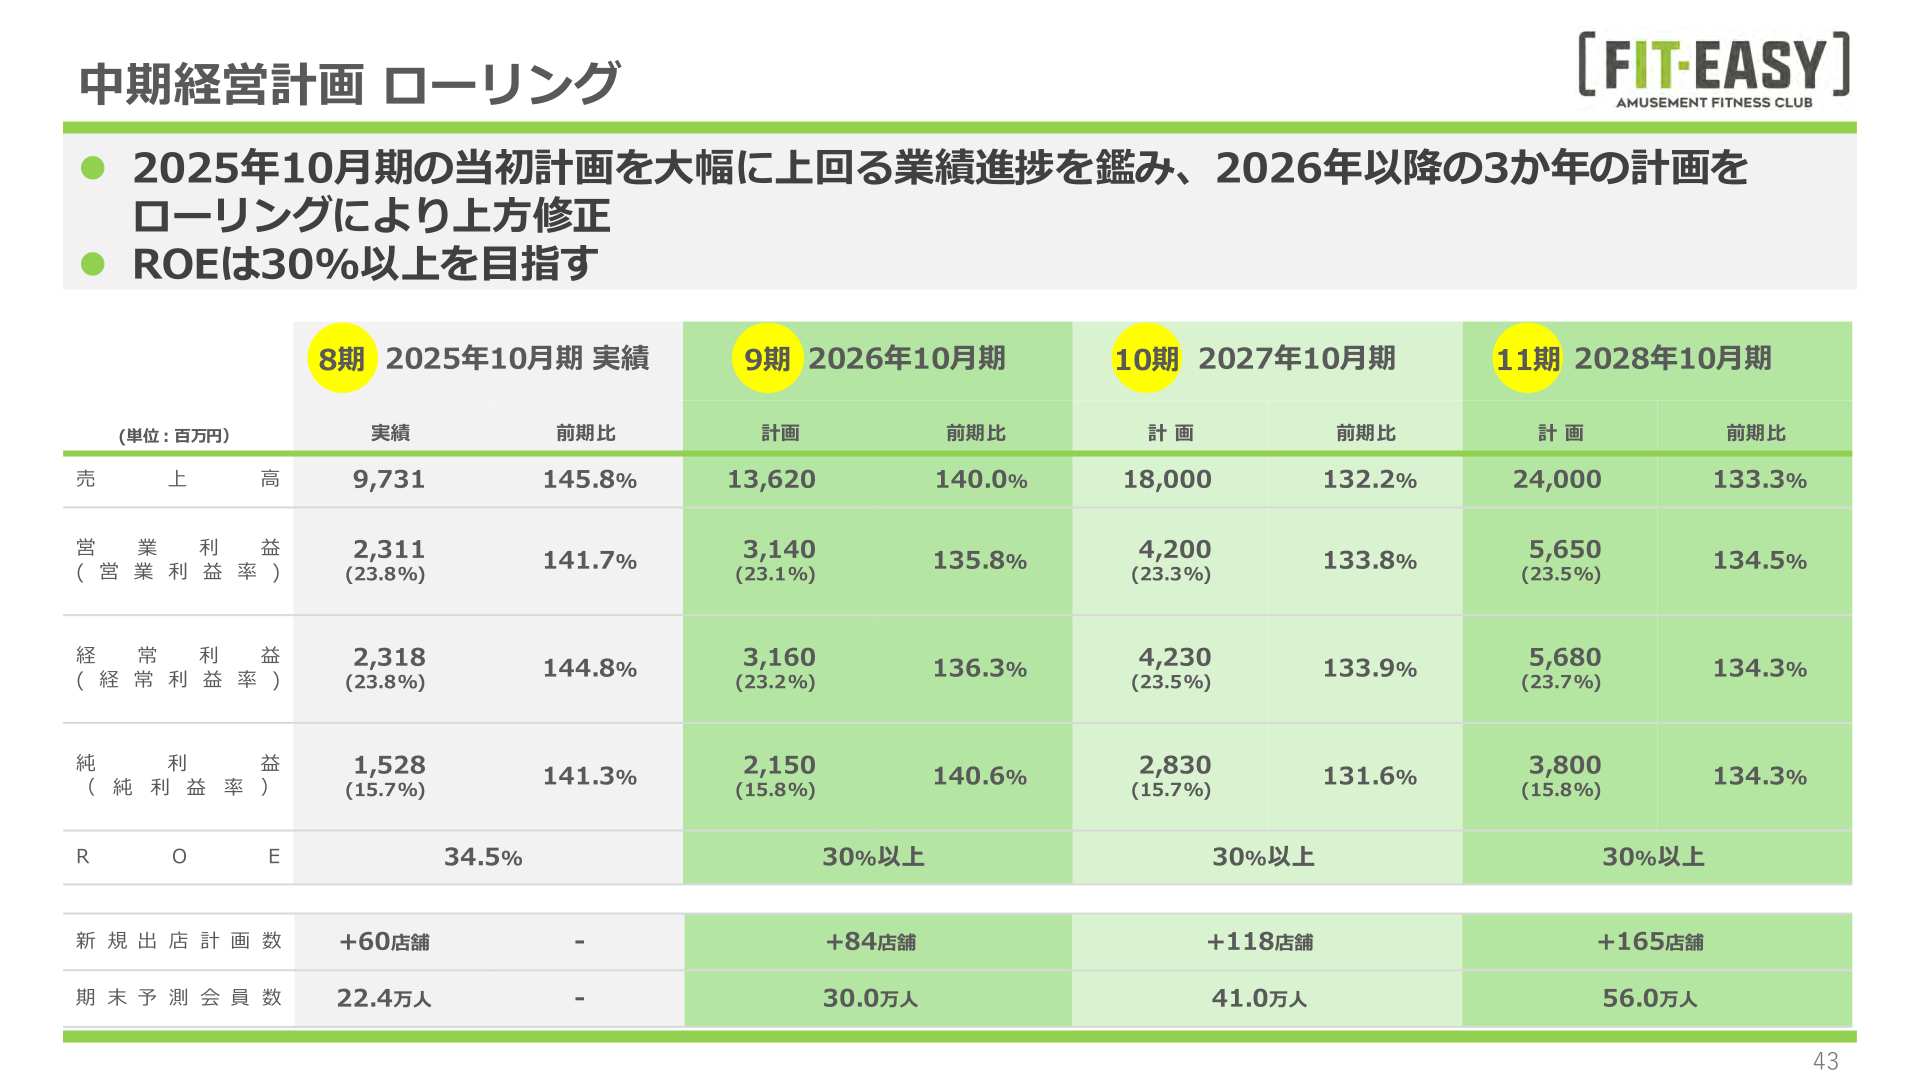
Against the medium-term management plan disclosed in December 2024, both new store openings and the number of members progressed at a pace above plan. In light of this, the plan for the three years from 2026 was revised upward on a rolling basis. For FY10/2026 the company plans net sales of 13,620 million yen (140.0% of the previous year), operating profit of 3,140 million yen (135.8%) and net income of 2,150 million yen (140.6%). For FY10/2027 it plans net sales of 18,000 million yen and net income of 2,830 million yen, and for FY10/2028 net sales of 24,000 million yen and net income of 3,800 million yen, while targeting ROE of 30% or more.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















