
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
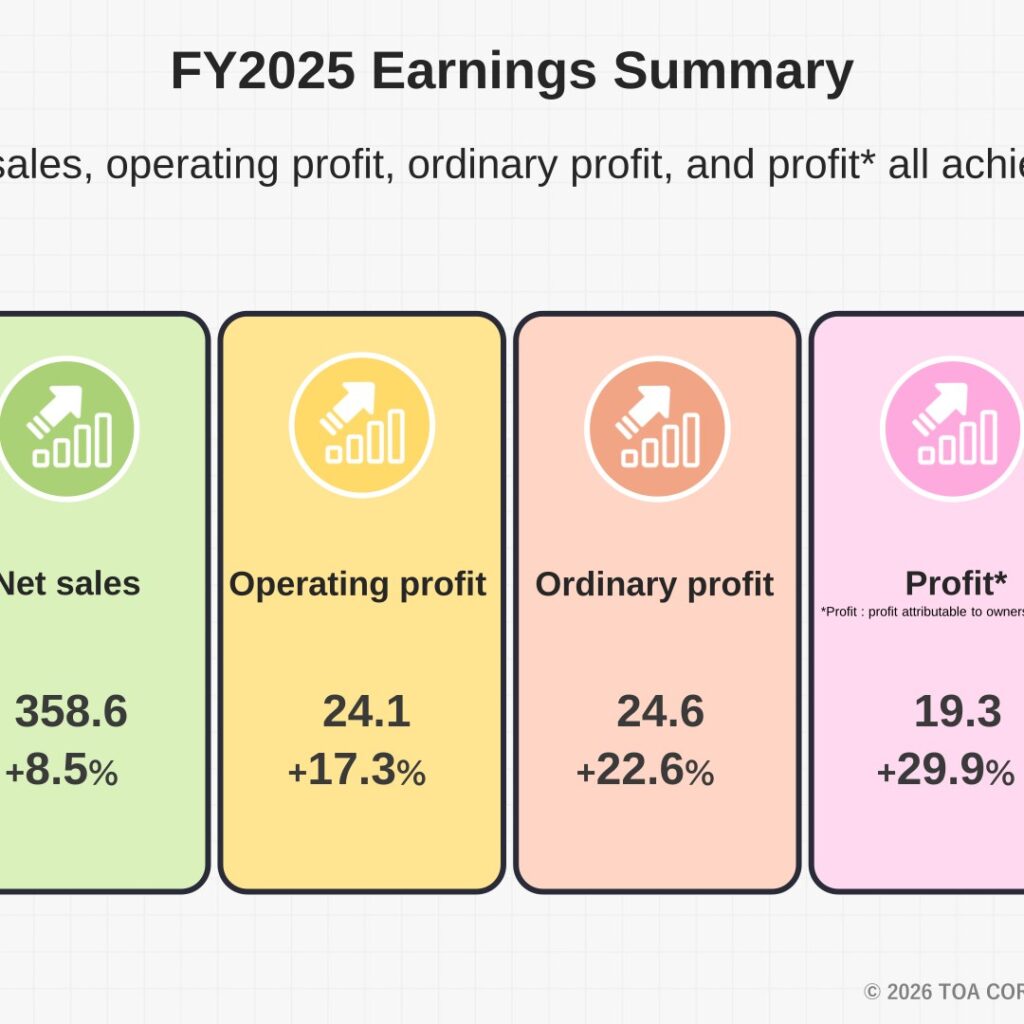
TOA CORPORATION, a marine civil engineering and building construction contractor, reported consolidated net sales of 358.6 billion yen for FY2025 (the fiscal year ended March 31, 2026), up 8.5% year on year, with operating profit of 24.1 billion yen (+17.3%), ordinary profit of 24.6 billion yen (+22.6%) and profit attributable to owners of parent of 19.3 billion yen (+29.9%). The company states that consolidated net sales, operating profit, ordinary profit and profit all achieved record highs. ROE rose 2.7 points to 17.4%. Non-consolidated orders received were 338.7 billion yen, down 4.3% year on year, exceeding the February 2026 forecast of 325.0 billion yen by 13.7 billion yen.
Consolidated Results (Full-Year Actual)
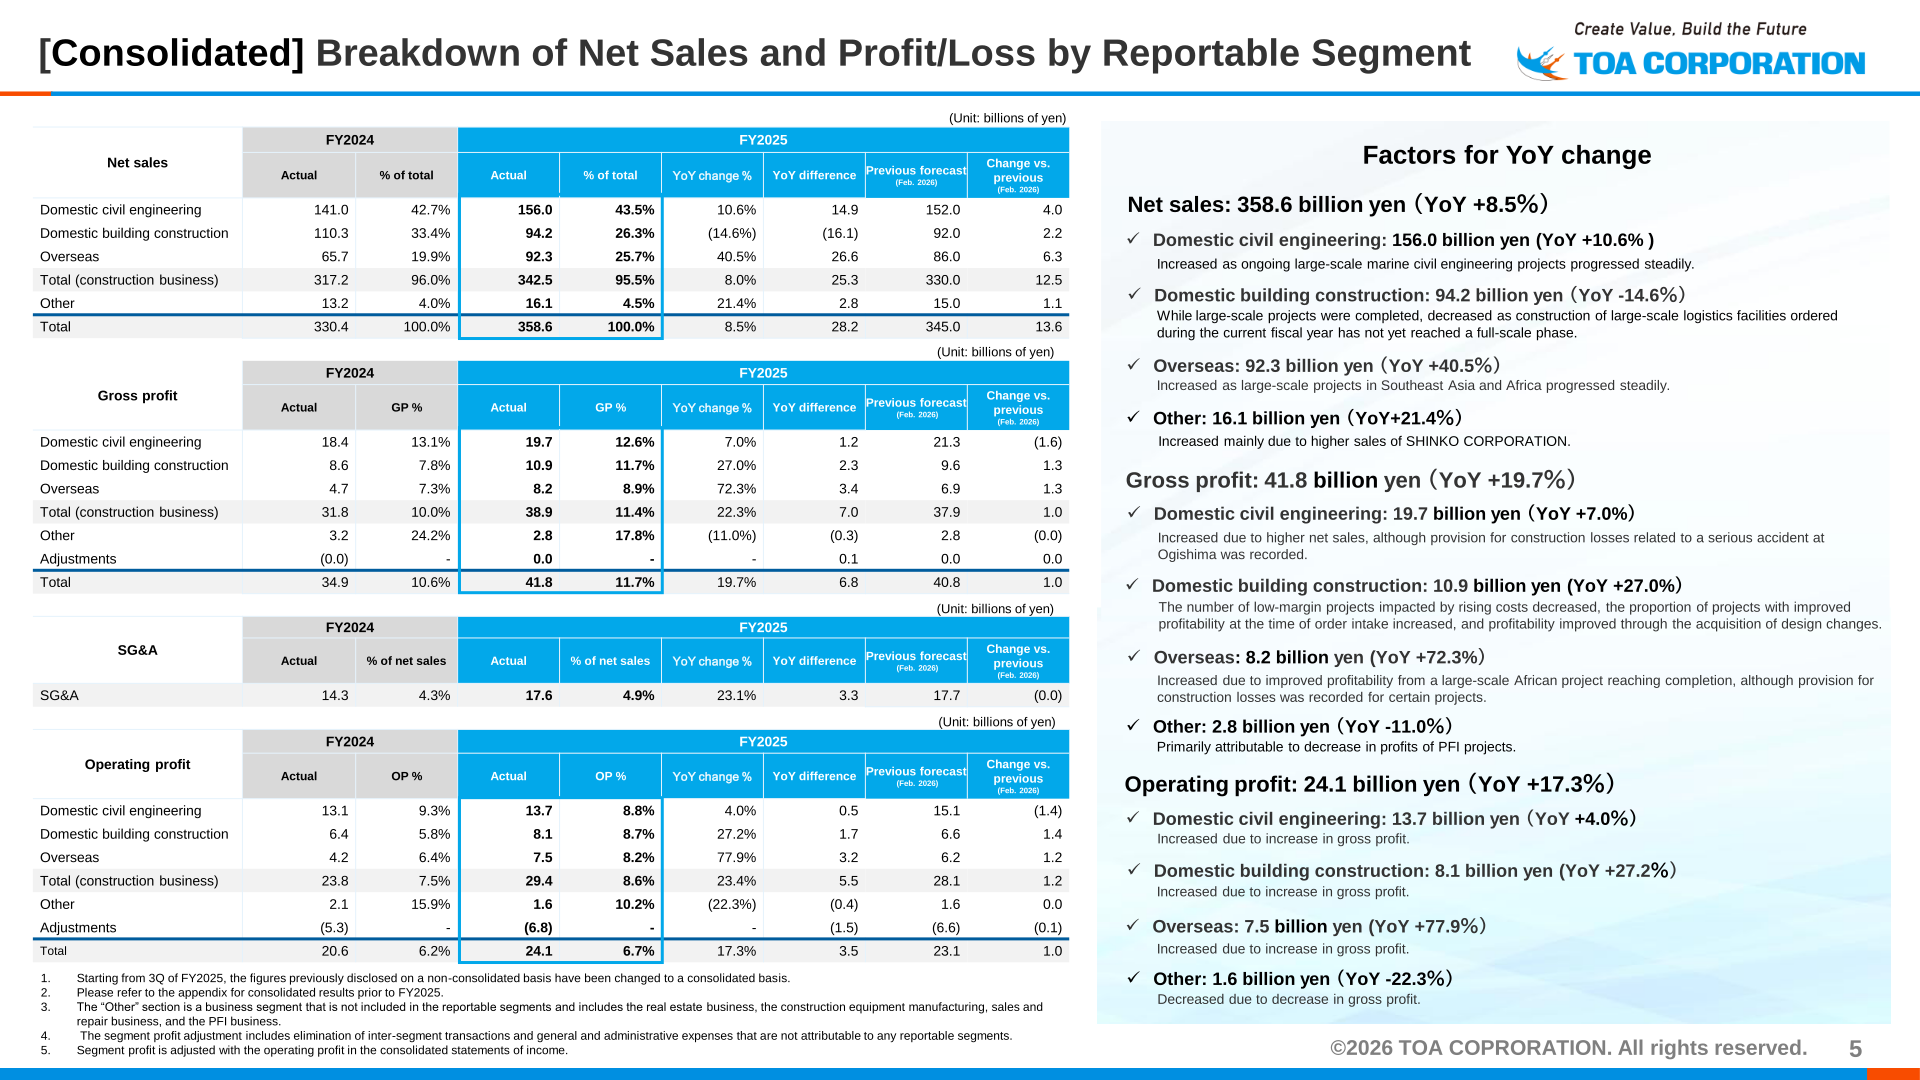
Net sales increased 8.5% year on year, driven by the steady progress of large-scale projects in domestic civil engineering and overseas. Operating profit rose 17.3%, mainly due to improved profitability in domestic building construction and overseas. Orders received on a non-consolidated basis decreased by 4.3% year on year due to weaker overseas performance, despite strong domestic civil engineering and building construction orders. Gross profit was 41.8 billion yen (+19.7%), with the gross profit margin improving to 11.7% from 10.6%, while SG&A rose 23.1% to 17.6 billion yen.
| Item (Consolidated) | FY2024 Actual | FY2025 Actual | % of net sales | YoY change % |
|---|---|---|---|---|
| Orders received (non-consolidated) | 353.7 | 338.7 | – | (4.3%) |
| Net sales | 330.4 | 358.6 | 100.0% | 8.5% |
| Gross profit | 34.9 | 41.8 | 11.7% | 19.7% |
| SG&A | 14.3 | 17.6 | 4.9% | 23.1% |
| Operating profit | 20.6 | 24.1 | 6.7% | 17.3% |
| Ordinary profit | 20.0 | 24.6 | 6.9% | 22.6% |
| Profit before income taxes | 20.9 | 25.6 | 7.2% | 22.3% |
| Profit attributable to owners of parent | 14.9 | 19.3 | 5.4% | 29.9% |
| Net assets | 107.8 | 117.9 | – | 9.3% |
| ROE | 14.7% | 17.4% | – | 2.7-point |
Unit: billions of yen, as presented in the source material. On a non-consolidated basis, net sales were 343.1 billion yen (+8.0%), operating profit 22.4 billion yen (+21.0%), ordinary profit 22.7 billion yen (+27.1%) and profit 18.1 billion yen (+34.0%), with ROE of 19.4%.
Segment Results
Domestic civil engineering net sales rose 10.6% to 156.0 billion yen as ongoing large-scale marine civil engineering projects progressed steadily; segment operating profit increased 4.0% to 13.7 billion yen. Domestic building construction net sales fell 14.6% to 94.2 billion yen because construction of large-scale logistics facilities ordered during the fiscal year had not yet reached a full-scale phase, but operating profit rose 27.2% to 8.1 billion yen as the number of low-margin projects affected by rising costs decreased and profitability improved through the acquisition of design changes. Overseas net sales grew 40.5% to 92.3 billion yen on steady progress of large-scale projects in Southeast Asia and Africa, and operating profit rose 77.9% to 7.5 billion yen. The Other segment, which includes the real estate business, the construction equipment manufacturing, sales and repair business and the PFI business, posted net sales of 16.1 billion yen (+21.4%) and operating profit of 1.6 billion yen (-22.3%). From 3Q of FY2025, figures previously disclosed on a non-consolidated basis have been changed to a consolidated basis.
| Segment | Net sales FY2024 | Net sales FY2025 | Operating profit FY2024 | Operating profit FY2025 |
|---|---|---|---|---|
| Domestic civil engineering | 141.0 | 156.0 | 13.1 | 13.7 |
| Domestic building construction | 110.3 | 94.2 | 6.4 | 8.1 |
| Overseas | 65.7 | 92.3 | 4.2 | 7.5 |
| Total (construction business) | 317.2 | 342.5 | 23.8 | 29.4 |
| Other | 13.2 | 16.1 | 2.1 | 1.6 |
| Adjustments | – | – | (5.3) | (6.8) |
| Total | 330.4 | 358.6 | 20.6 | 24.1 |
By order intake, domestic civil engineering orders (non-consolidated) rose 14.8% to 157.5 billion yen, with public-sector orders of 108.7 billion yen and private-sector orders of 48.7 billion yen. Domestic building construction orders rose 11.7% to 101.4 billion yen, supported by orders for multiple logistics facilities in the private sector. Overseas orders fell 38.5% to 73.5 billion yen, although the company describes this as a robust level of around 70.0 billion yen and notes it exceeded the February forecast by 8.5 billion yen following new construction contracts and an additional design change in Southeast Asia.
Financial Position and Cash Flows
Total assets stood at 298.9 billion yen as of March 2026, against 305.4 billion yen a year earlier. Current assets decreased mainly due to a decline in notes receivable and accounts receivable from completed construction contracts, while investments and other assets increased mainly due to an increase in retirement benefit assets. Liabilities decreased on a reduction in short-term borrowings and commercial paper, although the provision for construction losses increased, and net assets rose to 117.9 billion yen from 107.8 billion yen as retained earnings increased. Operating cash flow was 48.0 billion yen, investing cash flow was (1.5) billion yen and financing cash flow was (39.1) billion yen, lifting the cash balance from 41.5 billion yen at the beginning of FY2025 to 49.2 billion yen at the end of FY2025.
FY2026 Forecast
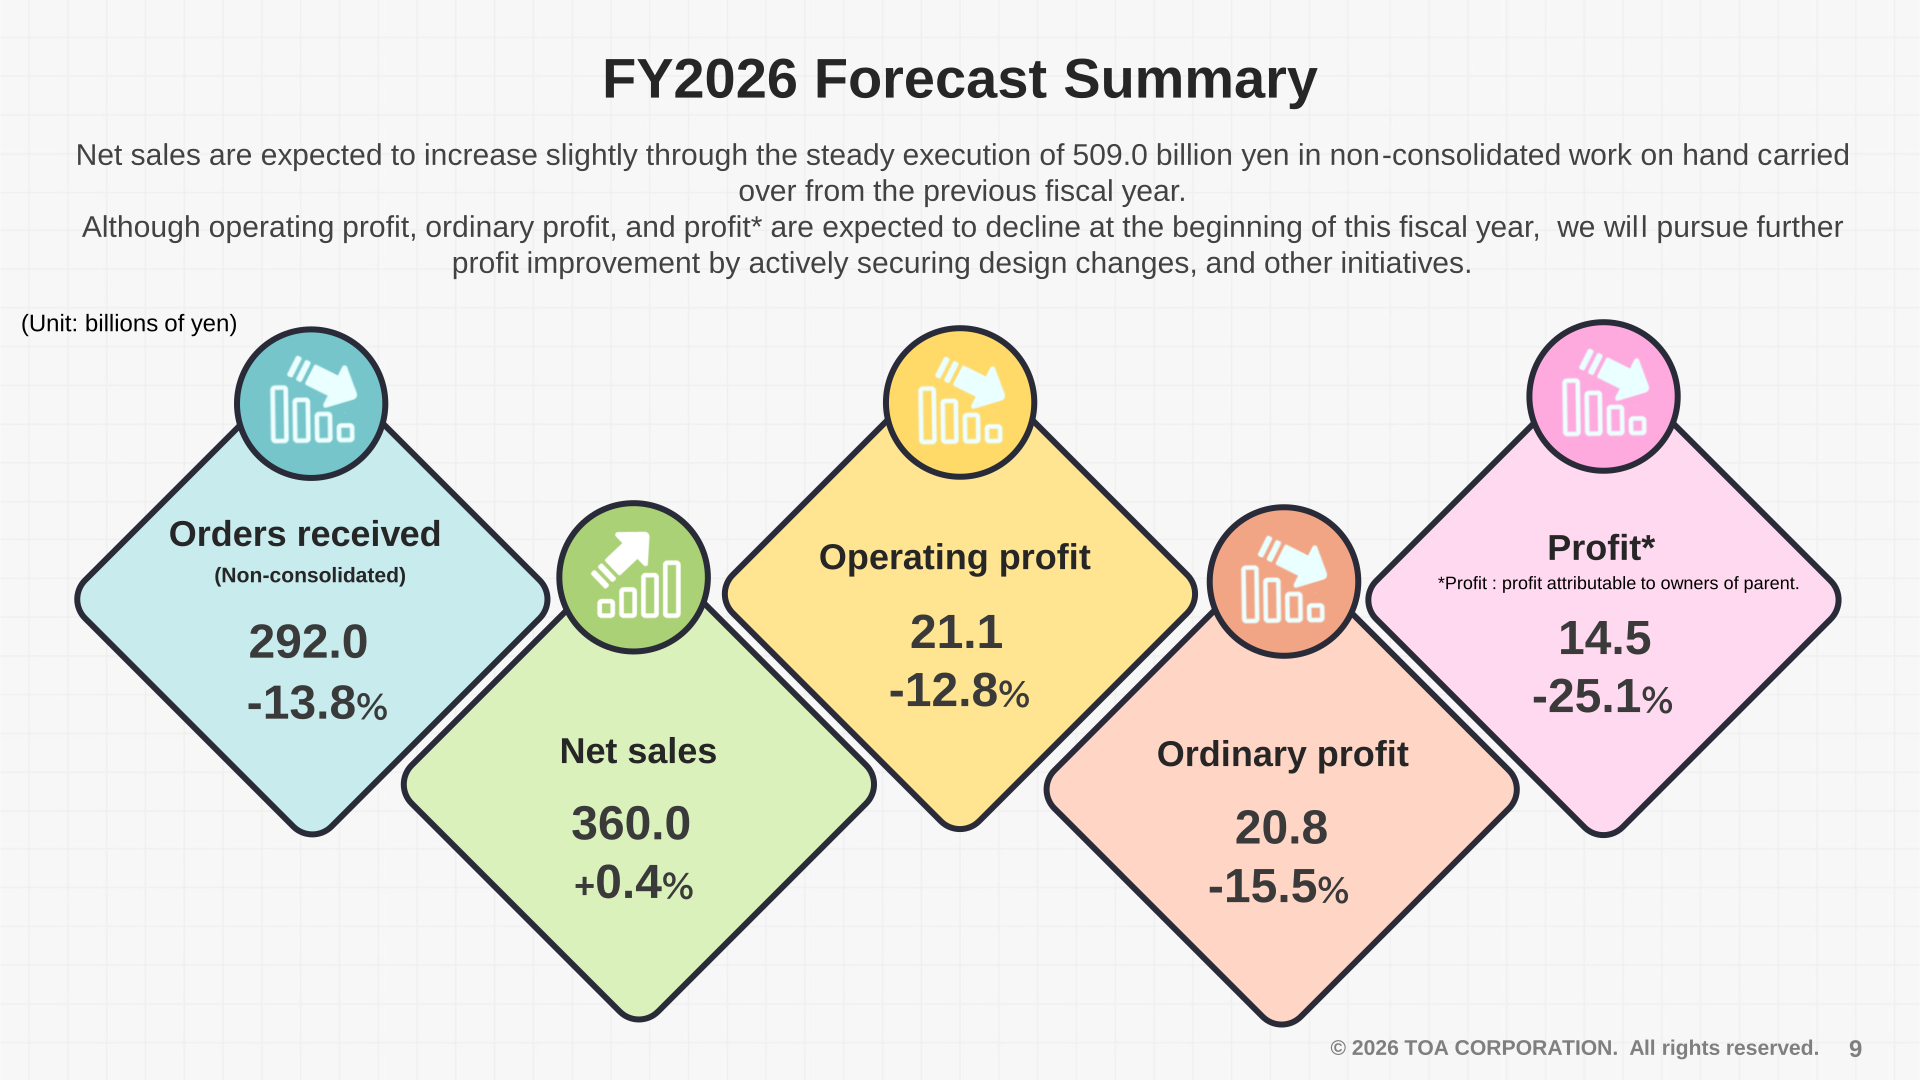
For FY2026, the company forecasts consolidated net sales of 360.0 billion yen (+0.4%), expecting a slight increase through the steady execution of 509.0 billion yen in non-consolidated work on hand carried over from the previous fiscal year. Operating profit is forecast at 21.1 billion yen (-12.8%), ordinary profit at 20.8 billion yen (-15.5%) and profit attributable to owners of parent at 14.5 billion yen (-25.1%). Gross profit is expected to be at the same level as FY2025, but operating profit is expected to decrease due to active investments in human resources and DX (digital transformation). Non-consolidated orders received are forecast to fall 13.8% to 292.0 billion yen as priority is placed on executing abundant construction on hand, despite what the company describes as an extremely favorable market environment driven by national resilience initiatives and increased defense spending. The company adds that although profits are expected to decline at the beginning of this fiscal year, it will pursue further profit improvement by actively securing design changes and other initiatives.
| Item (Consolidated) | FY2025 Actual | FY2026 Forecast | YoY change % |
|---|---|---|---|
| Orders received (non-consolidated) | 338.7 | 292.0 | (13.8%) |
| Net sales | 358.6 | 360.0 | 0.4% |
| Gross profit | 41.8 | 40.6 | (3.0%) |
| SG&A | 17.6 | 19.5 | 10.4% |
| Operating profit | 24.1 | 21.1 | (12.8%) |
| Ordinary profit | 24.6 | 20.8 | (15.5%) |
| Profit attributable to owners of parent | 19.3 | 14.5 | (25.1%) |
By segment, FY2026 net sales are forecast at 167.0 billion yen for domestic civil engineering (+7.0%), 91.0 billion yen for domestic building construction (-3.4%), 85.0 billion yen for overseas (-7.9%) and 17.0 billion yen for Other (+5.5%). Segment operating profit is forecast at 14.3 billion yen for domestic civil engineering (+4.4%), 9.0 billion yen for domestic building construction (+10.3%), 4.5 billion yen for overseas (-39.8%) and 0.9 billion yen for Other (-43.5%).
Shareholder Returns
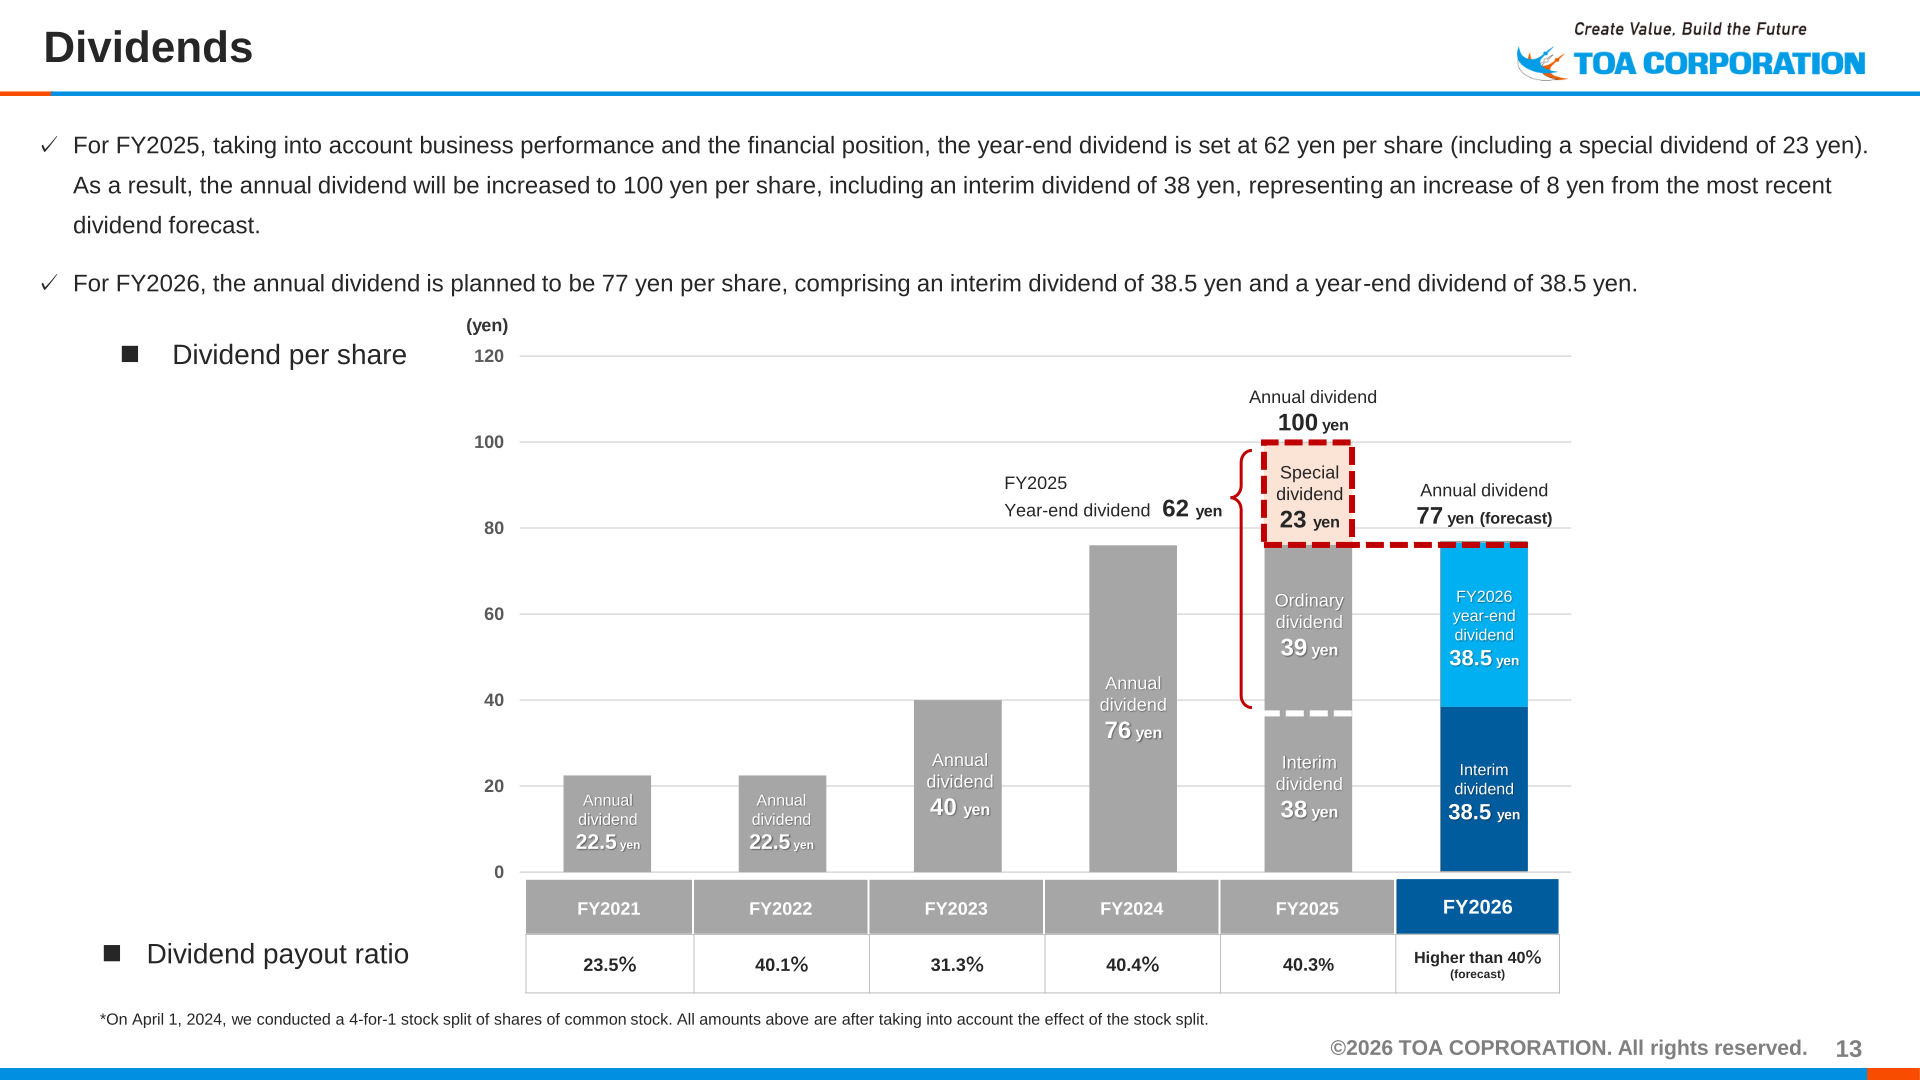
For FY2025, taking into account business performance and the financial position, the year-end dividend is set at 62 yen per share (including a special dividend of 23 yen). As a result, the annual dividend will be increased to 100 yen per share, including an interim dividend of 38 yen, representing an increase of 8 yen from the most recent dividend forecast. For FY2026, the annual dividend is planned to be 77 yen per share, comprising an interim dividend of 38.5 yen and a year-end dividend of 38.5 yen. Under the Medium-term Management Plan, the company will maintain a dividend payout ratio of 40% or higher to ensure stable dividends and provide enhanced shareholder returns as profits increase, and share buybacks will be implemented flexibly as part of shareholder returns, taking into account future business conditions and financial position.
| Item | FY2025 | FY2026 (Forecast) |
|---|---|---|
| Interim dividend per share | 38 yen | 38.5 yen |
| Year-end dividend per share | 62 yen (including a special dividend of 23 yen) | 38.5 yen |
| Annual dividend per share | 100 yen | 77 yen |
| Dividend payout ratio | 40.3% | Higher than 40% |
On cross-shareholdings, the balance excluding deemed holdings was 13.0 billion yen as of the end of March 2026, an increase of 0.5 billion yen from the previous year due to rising stock prices, although 14 stocks worth 2.39 billion yen were sold during FY2025. The ratio to consolidated net assets excluding deemed holdings was 11.0%, and the company aims to reduce it to less than 10% of consolidated net assets during the current Medium-term Management Plan period.
Medium-term Management Plan and Growth Strategy
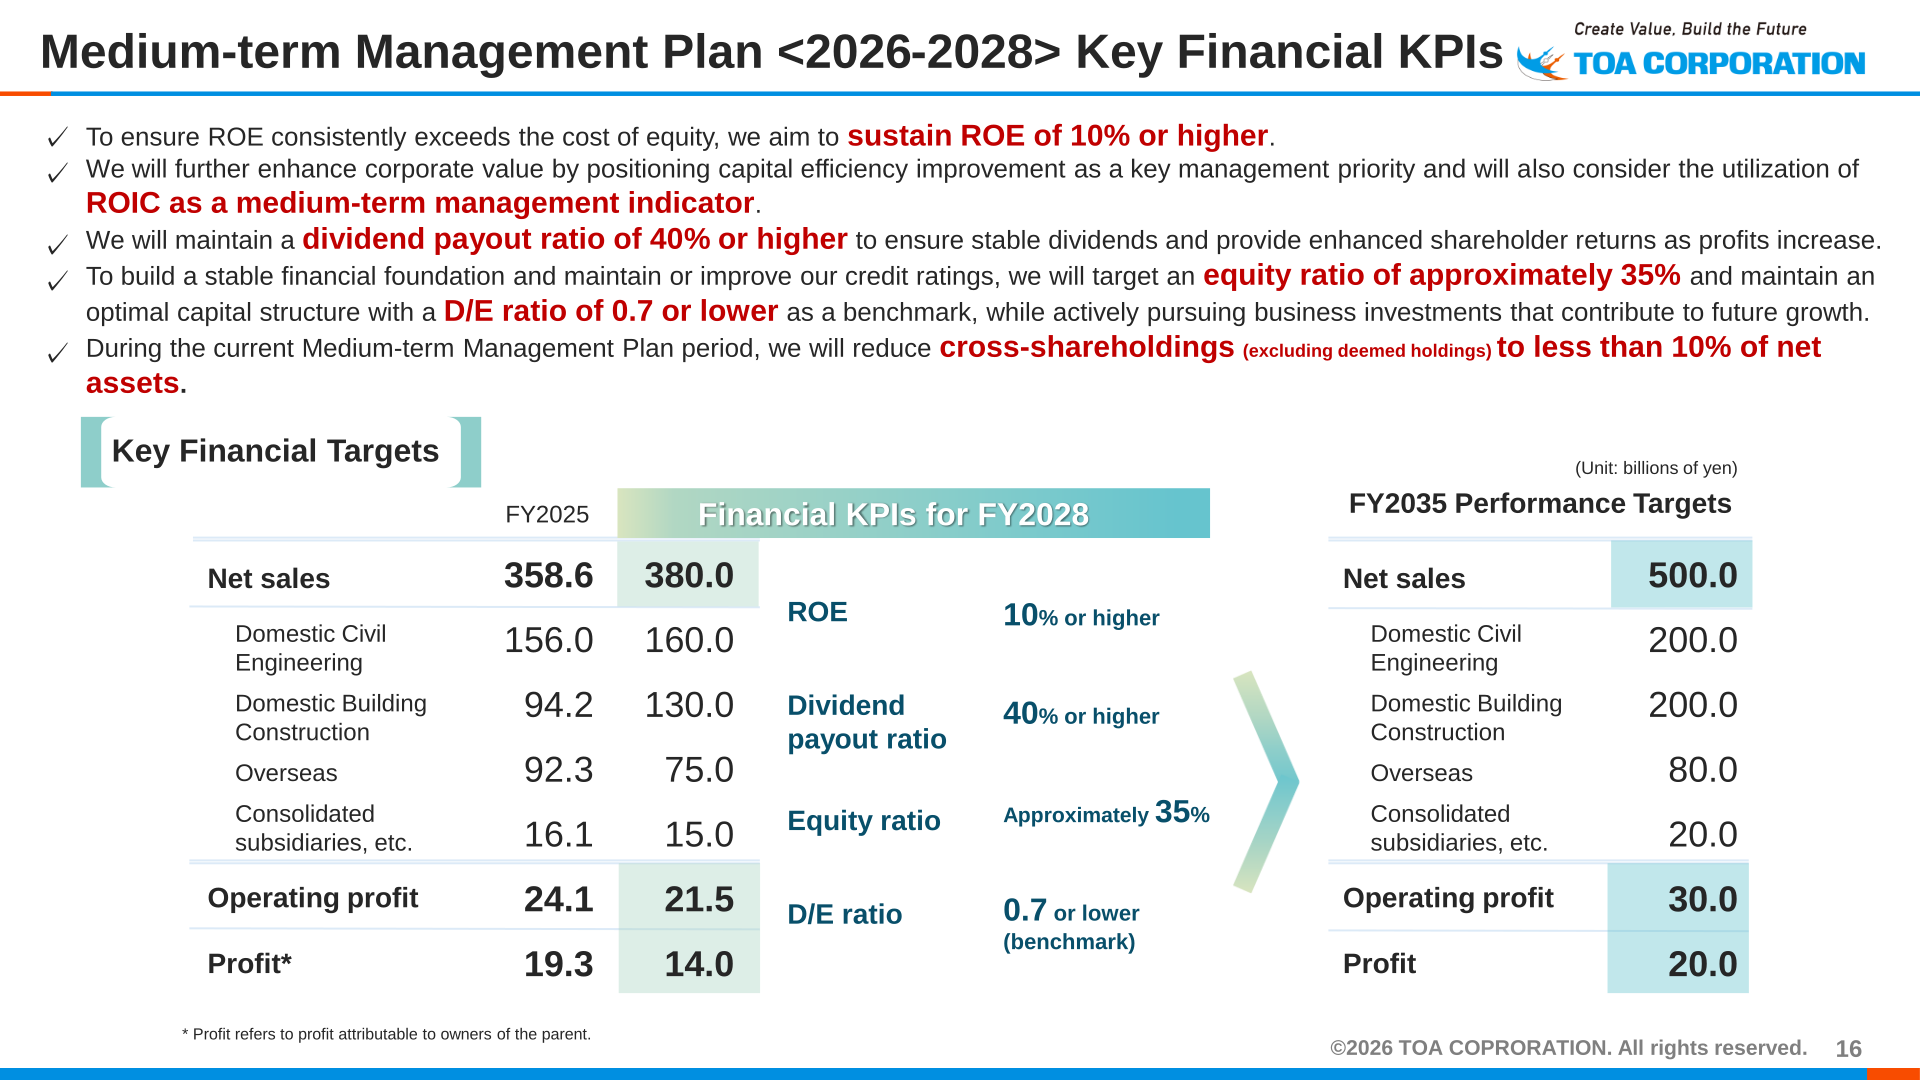
Under the Medium-term Management Plan <2026-2028>, the company targets net sales of 380.0 billion yen, operating profit of 21.5 billion yen and profit of 14.0 billion yen in FY2028, with a segment mix of 160.0 billion yen in domestic civil engineering, 130.0 billion yen in domestic building construction, 75.0 billion yen overseas and 15.0 billion yen from consolidated subsidiaries and others. Longer term, it aims to achieve net sales of 500.0 billion yen and operating profit of 30.0 billion yen by FY2035, with profit of 20.0 billion yen. Key financial KPIs for FY2028 are ROE of 10% or higher, a dividend payout ratio of 40% or higher, an equity ratio of approximately 35% and a D/E ratio of 0.7 or lower as a benchmark.
| Item | FY2025 Actual | FY2028 Plan | FY2035 Target |
|---|---|---|---|
| Net sales | 358.6 | 380.0 | 500.0 |
| Domestic Civil Engineering | 156.0 | 160.0 | 200.0 |
| Domestic Building Construction | 94.2 | 130.0 | 200.0 |
| Overseas | 92.3 | 75.0 | 80.0 |
| Consolidated subsidiaries, etc. | 16.1 | 15.0 | 20.0 |
| Operating profit | 24.1 | 21.5 | 30.0 |
| Profit attributable to owners of parent | 19.3 | 14.0 | 20.0 |
Total investment under the current Medium-term Management Plan will be expanded to 50.0 billion yen (with M&A investments treated separately), of which 25.0 billion yen is allocated to strengthening the management foundation and 25.0 billion yen to growth investment, and shareholder returns are set at 15.0 billion yen plus alpha over the three-year period. In domestic civil engineering the company points to the ongoing national resilience budget, with a first mid-term plan for the implementation of national resilience exceeding 20 trillion yen over five years from FY2026, and to the expansion of the defense budget under the National Defense Strategy of 4 trillion yen for FY2023-FY2027. In domestic building construction it will maintain the logistics sector at 50-60% of net sales, capture replacement demand for refrigerated warehouses and strengthen capabilities for government and public-sector projects. Overseas, it will maintain order intake in Singapore, establish a local subsidiary in the Philippines following Indonesia, and it secured an ODA-funded international airport development project in Timor-Leste in March 2026.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















