
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
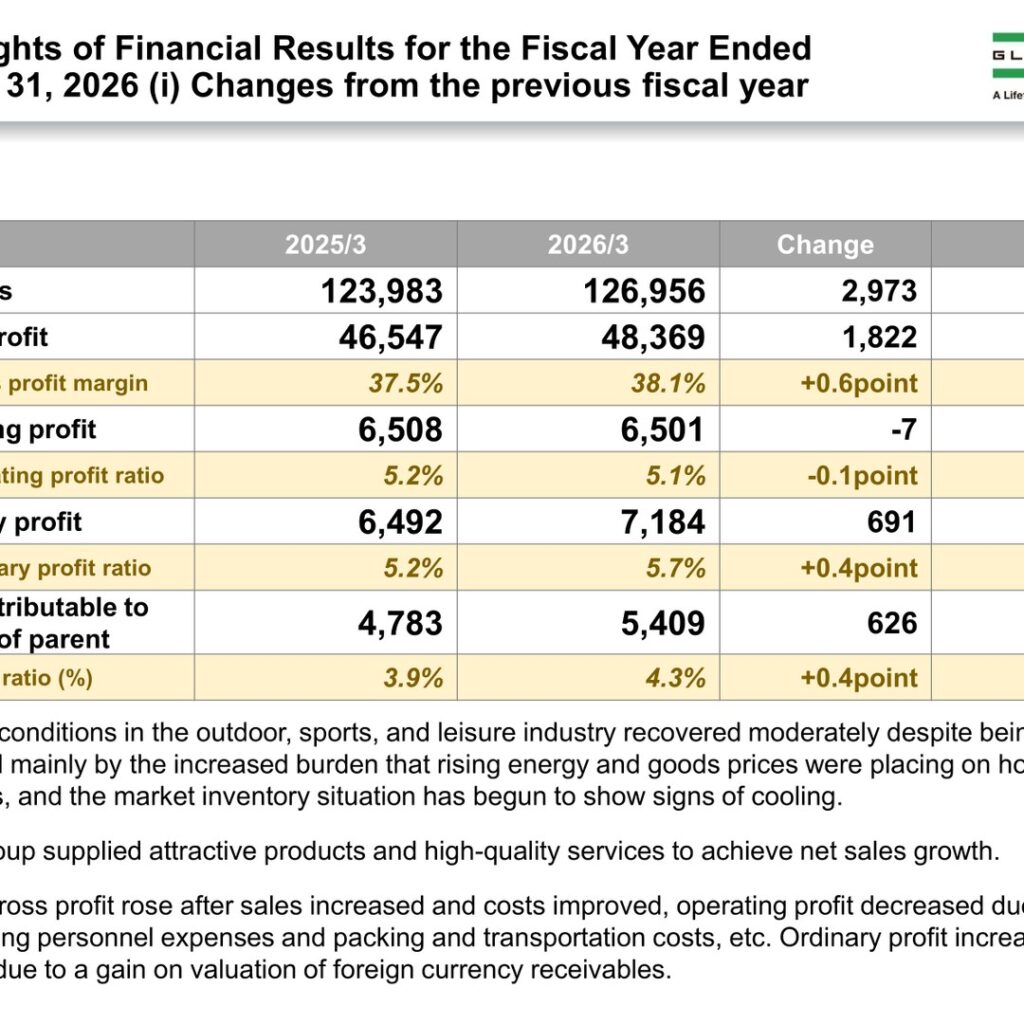
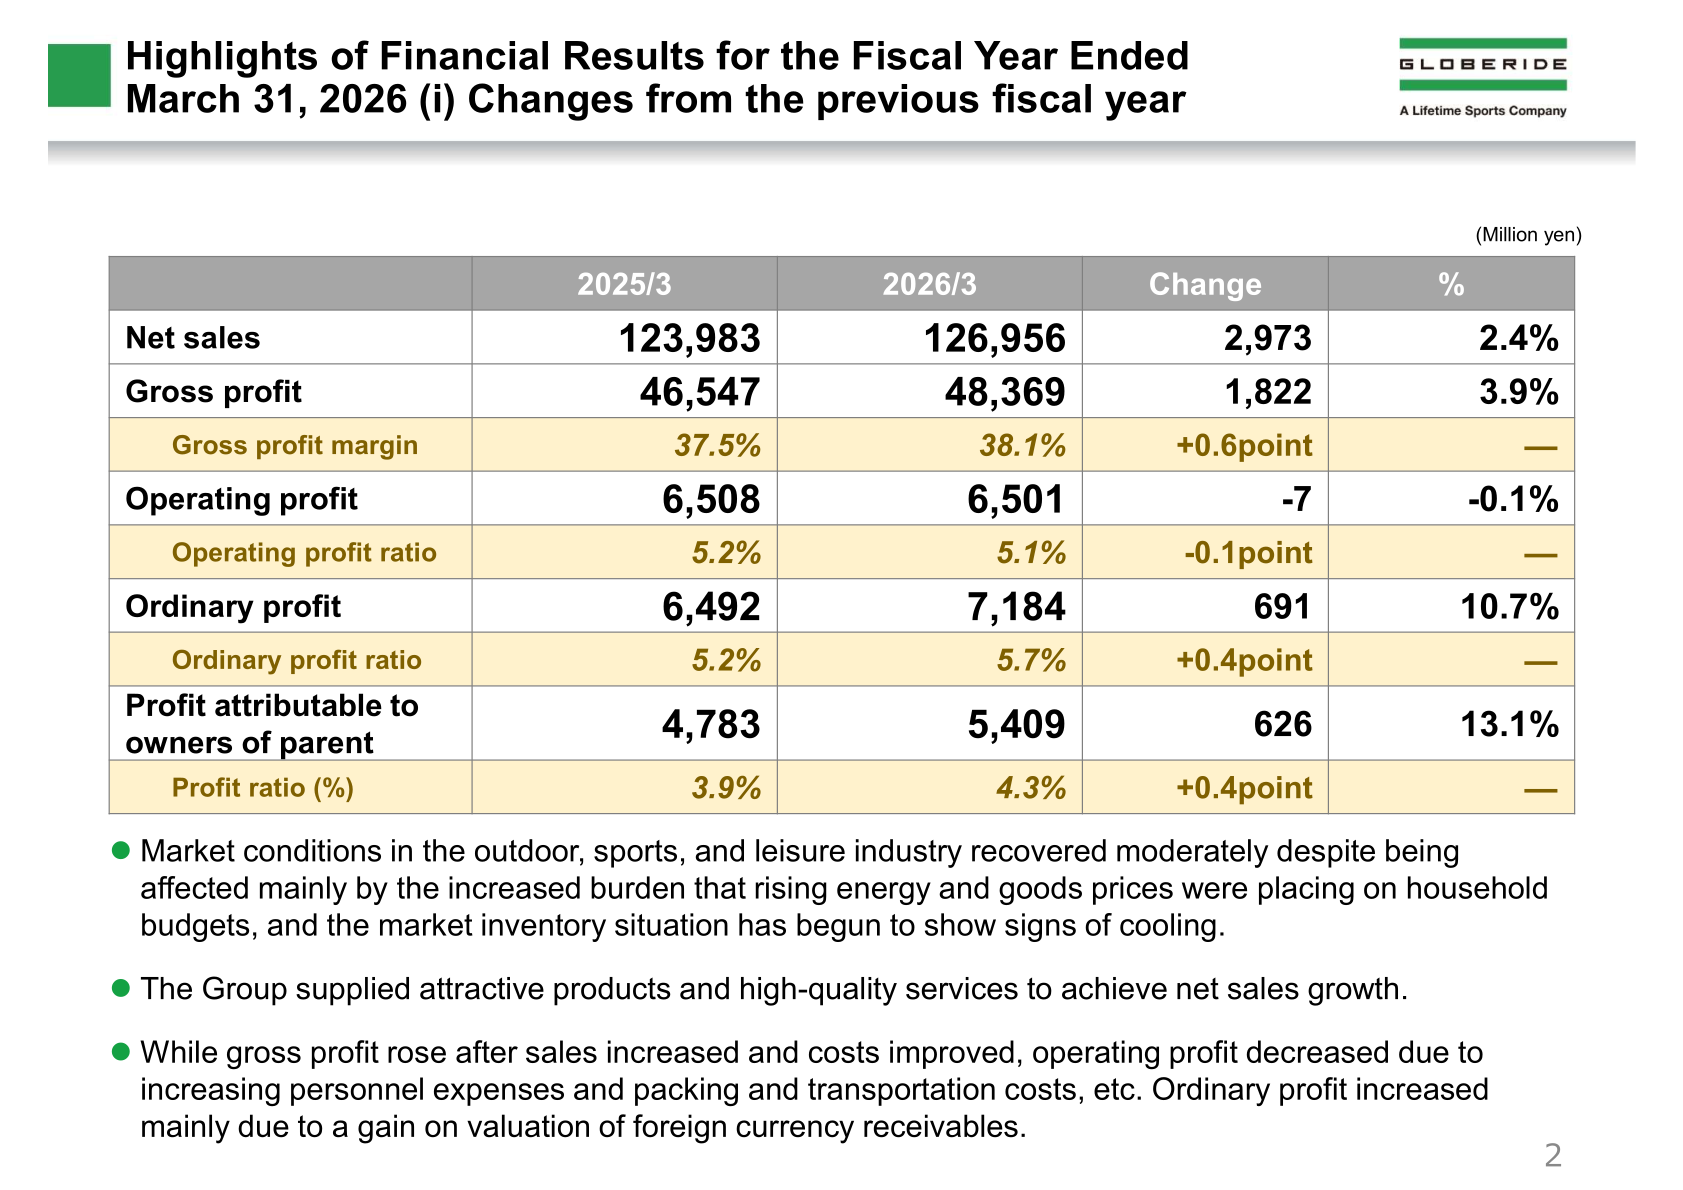
GLOBERIDE, Inc. (7990) reported consolidated net sales of ¥126,956 million for the fiscal year ended March 31, 2026 (the company labels this period “2026/3”; it is referred to as FY2025 in this article per site convention), up 2.4% year on year. Operating profit edged down 0.1% to ¥6,501 million on higher personnel and logistics costs, while ordinary profit rose 10.7% to ¥7,184 million, mainly reflecting a gain on valuation of foreign currency receivables, and profit attributable to owners of parent increased 13.1% to ¥5,409 million. All four headline metrics came in above the company’s initial full-year forecasts, with operating profit up 20.4% and ordinary profit up 30.6% versus the original guidance.
Consolidated Results (Full-Year Actual)
Net sales grew for the second consecutive year as the outdoor, sports and leisure market showed signs of a moderate recovery despite continued pressure on household budgets from rising energy and goods prices. Gross profit rose 3.9% and gross margin improved 0.6 points to 38.1%, but SG&A expenses increased, led by higher personnel expenses following pay raises and higher packing and transportation costs, which pushed operating profit down slightly.
| Item | 2025/3 | 2026/3 | Change | % |
|---|---|---|---|---|
| Net sales | 123,983 | 126,956 | 2,973 | 2.4% |
| Gross profit | 46,547 | 48,369 | 1,822 | 3.9% |
| Gross profit margin | 37.5% | 38.1% | +0.6 point | — |
| Operating profit | 6,508 | 6,501 | -7 | -0.1% |
| Operating profit ratio | 5.2% | 5.1% | -0.1 point | — |
| Ordinary profit | 6,492 | 7,184 | 691 | 10.7% |
| Ordinary profit ratio | 5.2% | 5.7% | +0.4 point | — |
| Profit attributable to owners of parent | 4,783 | 5,409 | 626 | 13.1% |
| Profit ratio | 3.9% | 4.3% | +0.4 point | — |
(Figures in million yen, except percentages and points.) On the balance sheet, total assets increased 5.0% to ¥119,631 million and net assets rose 6.0% to ¥64,929 million, lifting the equity ratio to 54.1% from 53.5% a year earlier. Cash flow from operations rose sharply to ¥8,033 million from ¥2,042 million, and free cash flow turned positive at ¥5,041 million versus −¥2,143 million in the prior year.
Segment Results
By business line, the Fishing business, which accounted for 89.3% of net sales, grew 2.7% year on year to ¥113,382 million. The Golf business declined 4.9% to ¥6,131 million (4.8% of net sales), the Sports business increased 3.2% to ¥7,024 million (5.6% of net sales), and Other businesses rose 10.2% to ¥419 million (0.3% of net sales).
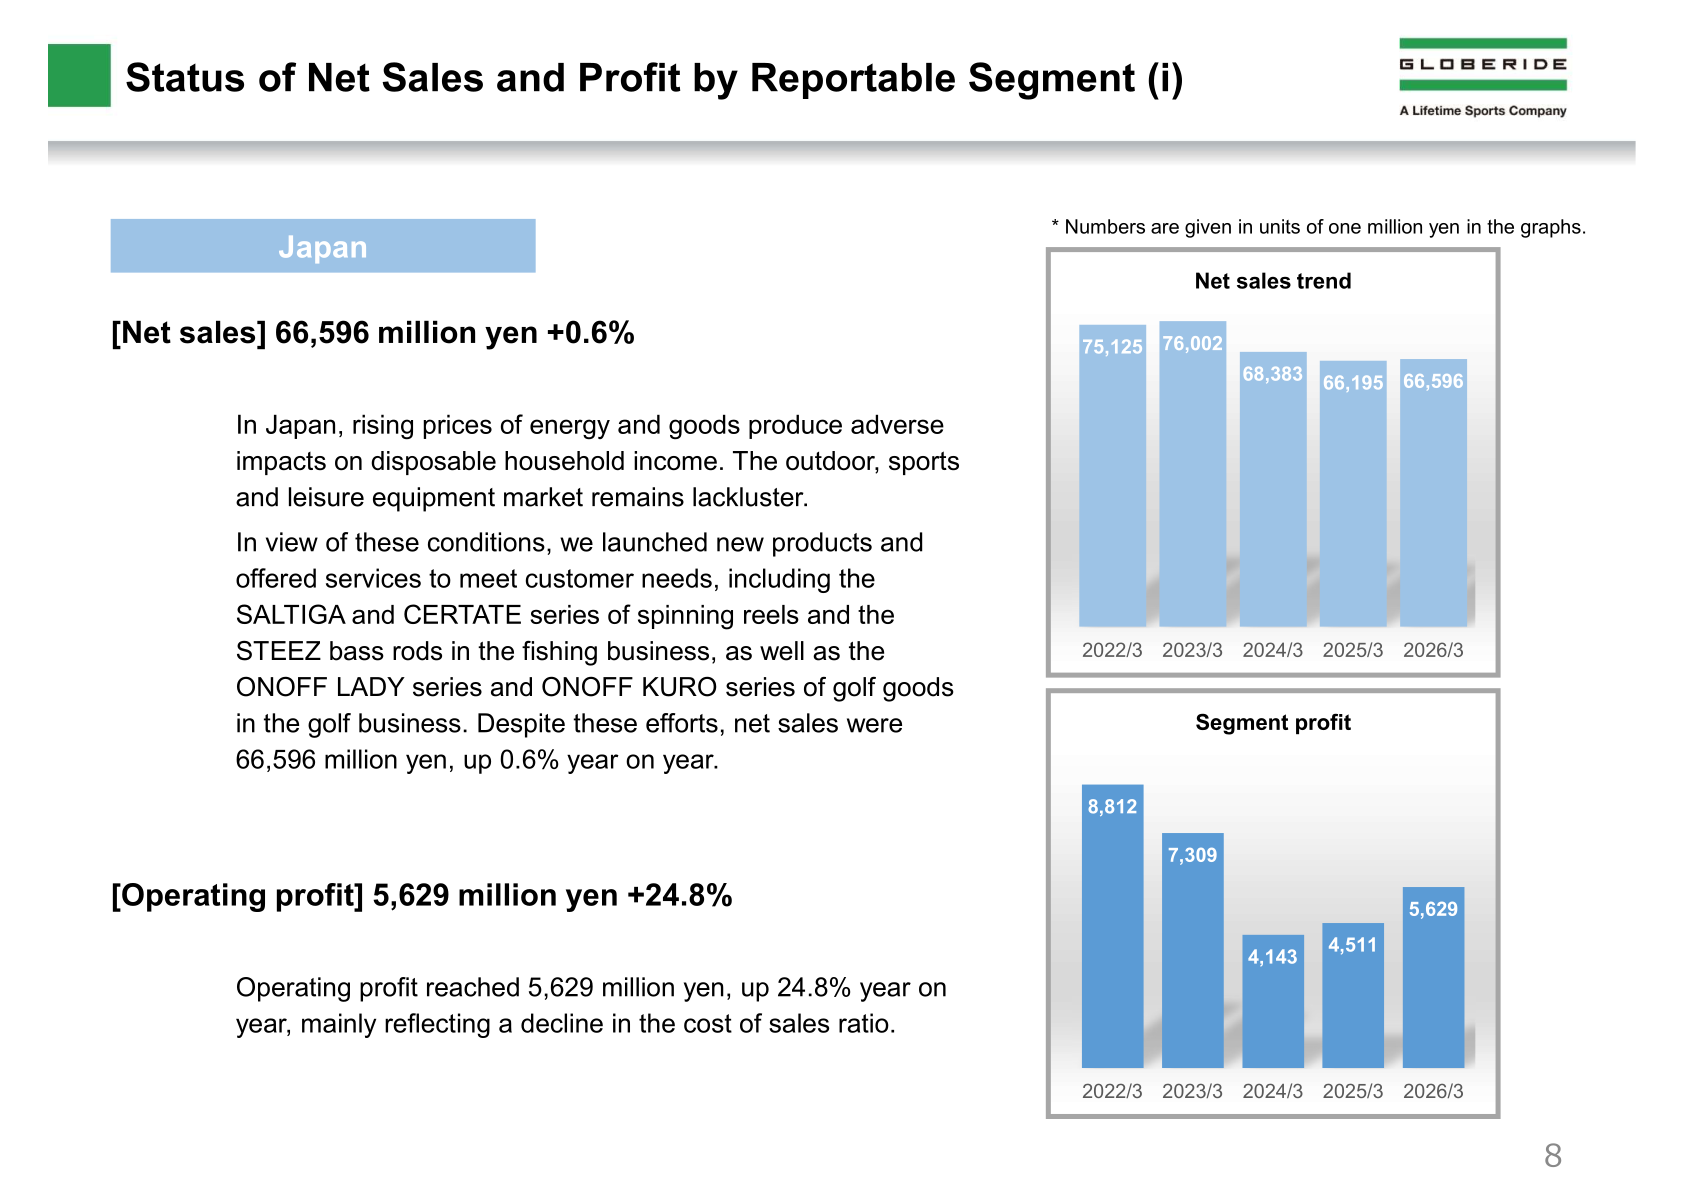
By reportable (geographic) segment, Japan net sales rose 0.6% to ¥66,596 million and segment operating profit jumped 24.8% to ¥5,629 million on a lower cost of sales ratio. In the Americas, net sales increased 2.9% to ¥13,707 million, but the segment posted an operating loss of ¥169 million, versus a ¥39 million profit a year earlier, reflecting higher tariff costs and SG&A expenses. Europe net sales rose 4.4% to ¥17,000 million with operating profit up 2.7% to ¥683 million. Asia & Oceania net sales grew 5.2% to ¥29,651 million, while operating profit declined 5.6% to ¥4,846 million mainly due to the impact of transfer pricing adjustments by the Group’s manufacturers.
| Segment | Metric | 2025/3 | 2026/3 |
|---|---|---|---|
| Japan | Net sales | 66,195 | 66,596 |
| Japan | Operating profit | 4,511 | 5,629 |
| Americas | Net sales | 13,320 | 13,707 |
| Americas | Operating profit | 39 | -169 |
| Europe | Net sales | 16,280 | 17,000 |
| Europe | Operating profit | 665 | 683 |
| Asia & Oceania | Net sales | 28,186 | 29,651 |
| Asia & Oceania | Operating profit | 5,131 | 4,846 |
FY2027/3 Forecast
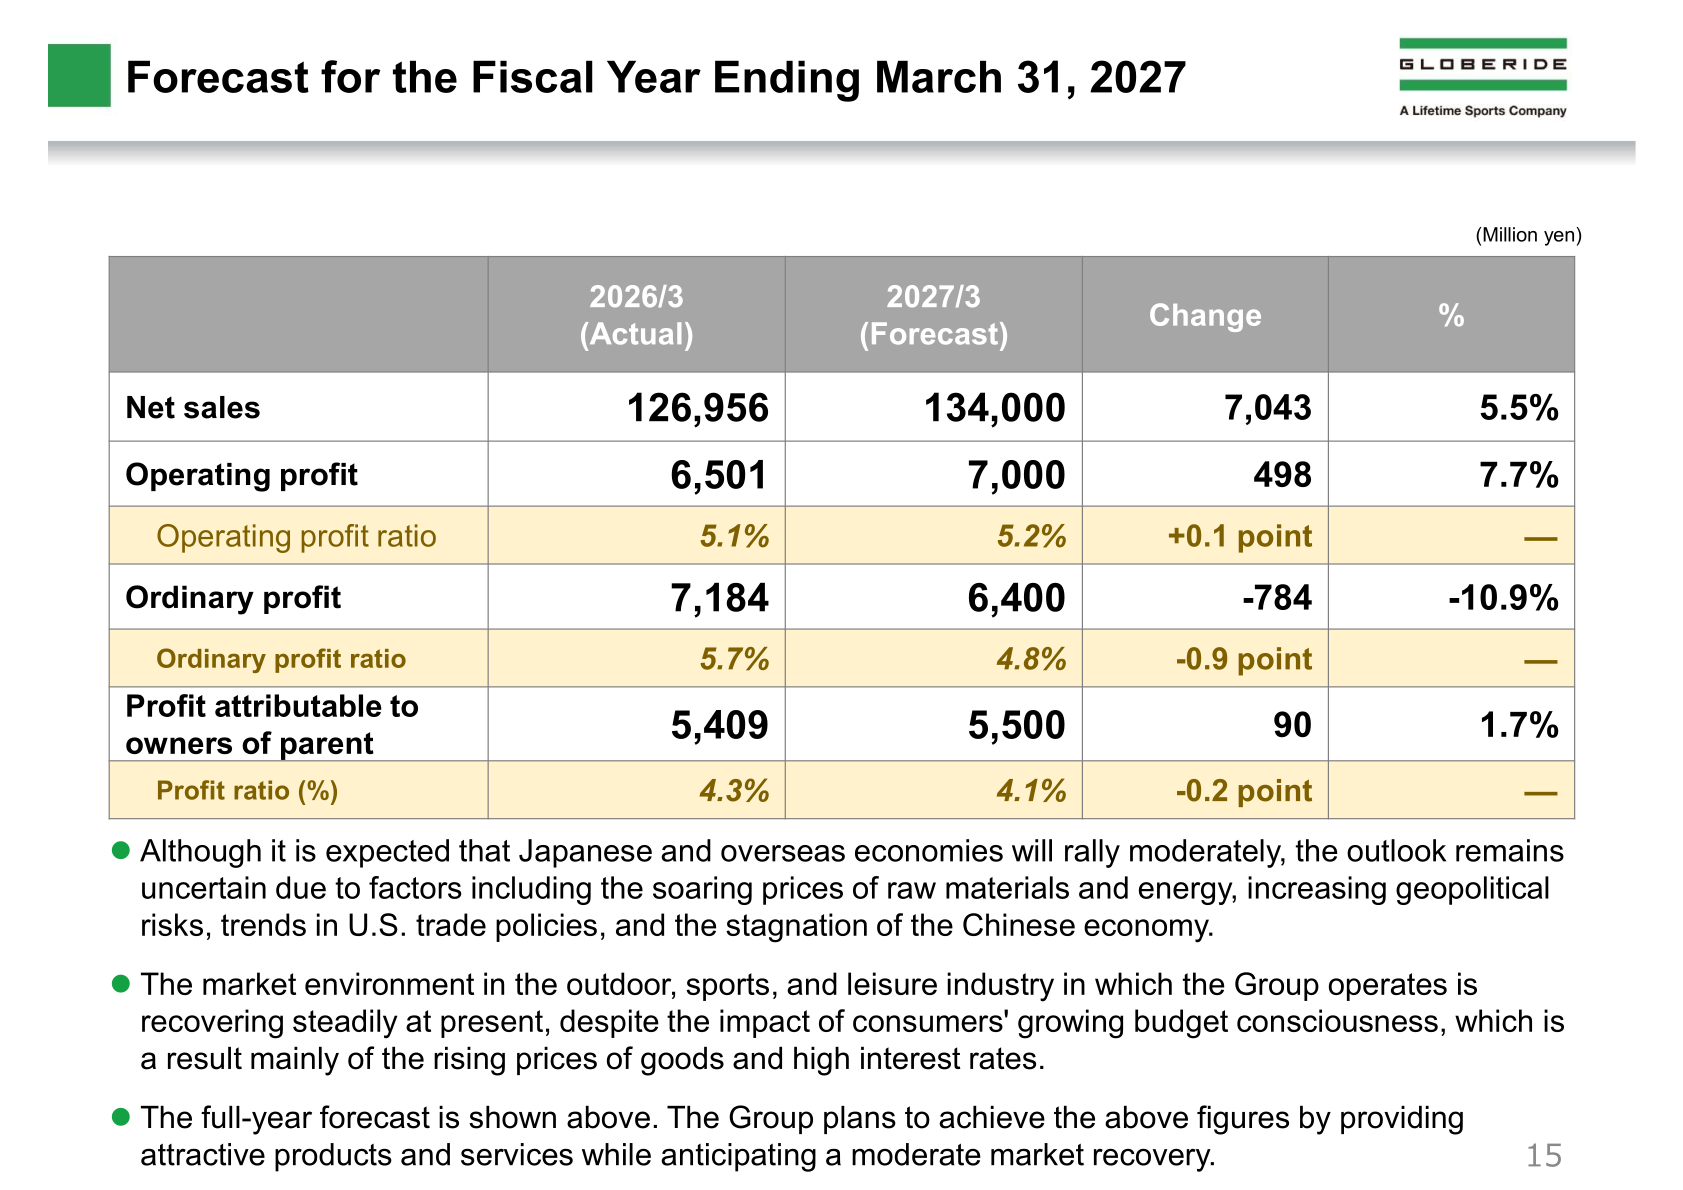
For the fiscal year ending March 31, 2027, GLOBERIDE forecasts net sales of ¥134,000 million, up 5.5% year on year, and operating profit of ¥7,000 million, up 7.7%. Ordinary profit is forecast to decline 10.9% to ¥6,400 million and profit attributable to owners of parent is forecast to rise 1.7% to ¥5,500 million. The company cites an uncertain outlook due to rising raw material and energy prices, geopolitical risk, U.S. trade policy trends and stagnation in the Chinese economy, while expecting the outdoor, sports and leisure market to continue a moderate recovery.
| Item | 2026/3 (Actual) | 2027/3 (Forecast) | Change | % |
|---|---|---|---|---|
| Net sales | 126,956 | 134,000 | 7,043 | 5.5% |
| Operating profit | 6,501 | 7,000 | 498 | 7.7% |
| Operating profit ratio | 5.1% | 5.2% | +0.1 point | — |
| Ordinary profit | 7,184 | 6,400 | -784 | -10.9% |
| Ordinary profit ratio | 5.7% | 4.8% | -0.9 point | — |
| Profit attributable to owners of parent | 5,409 | 5,500 | 90 | 1.7% |
| Profit ratio | 4.3% | 4.1% | -0.2 point | — |
Shareholder Returns
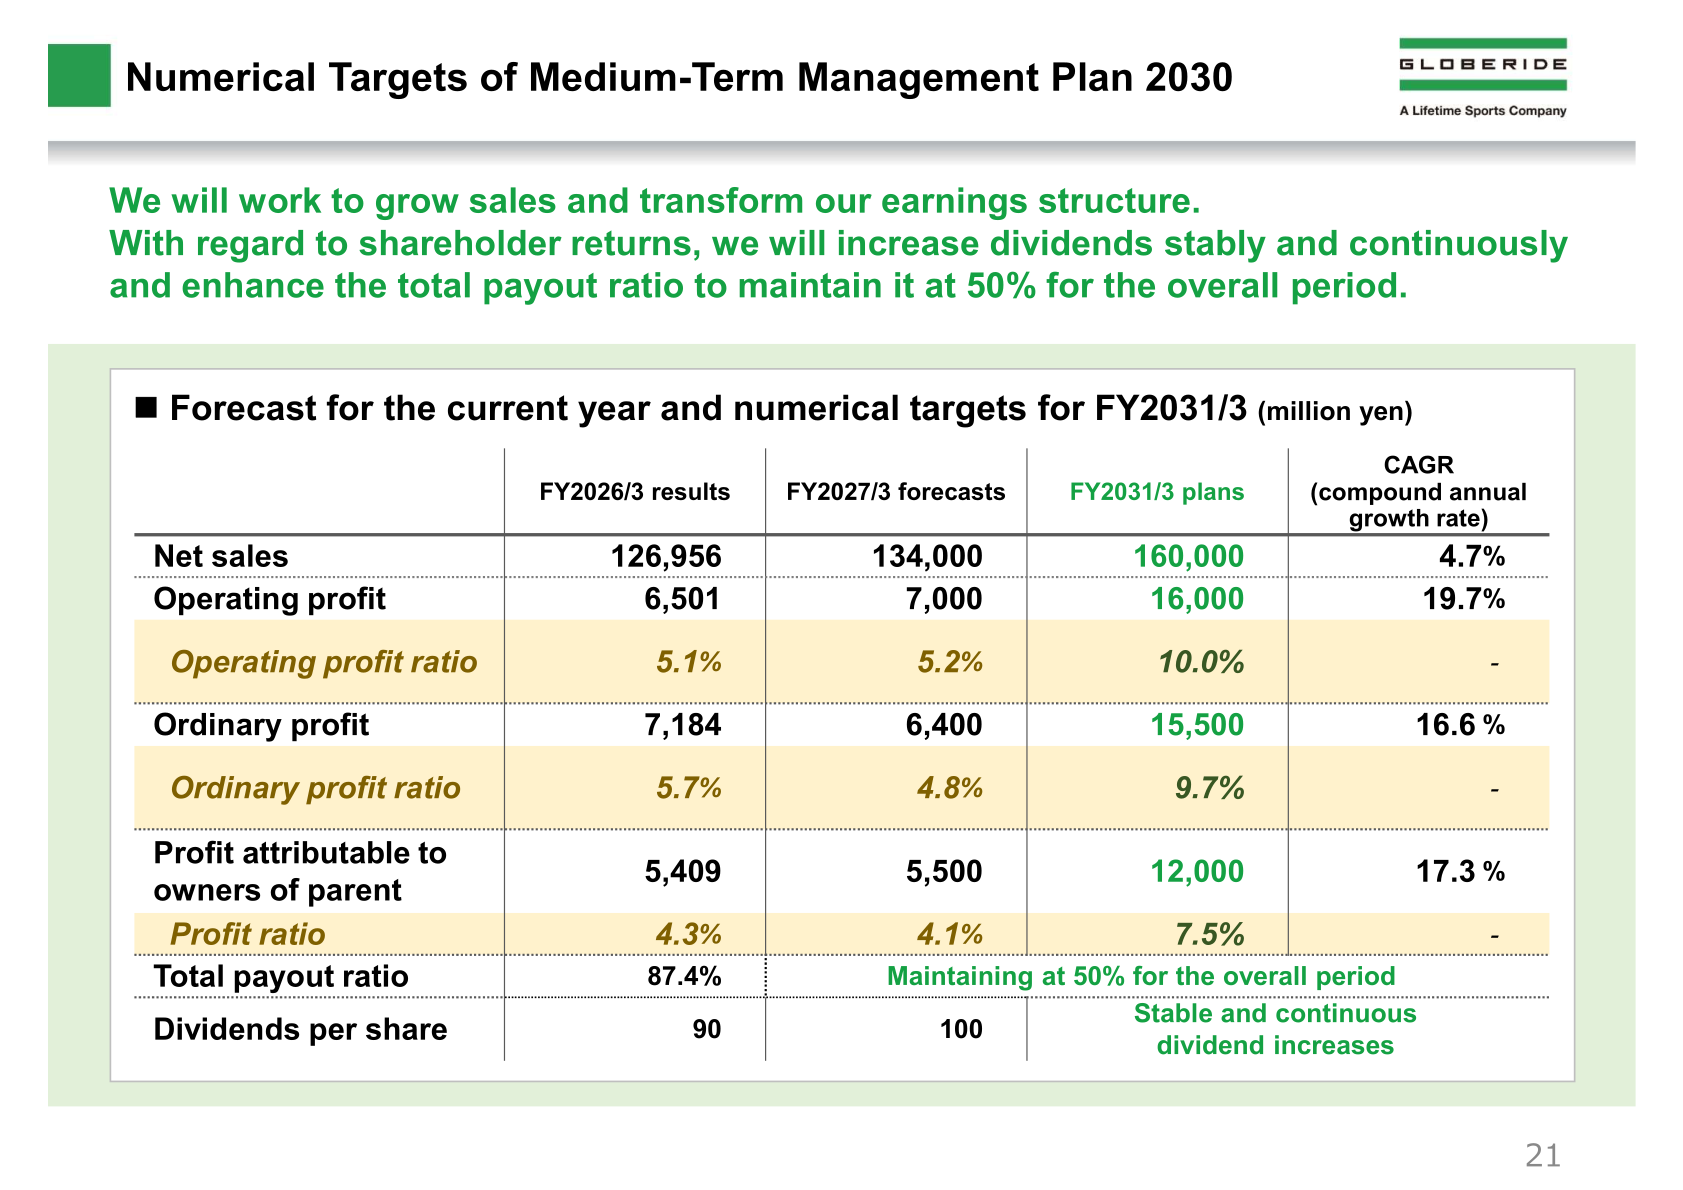
Dividends per share for FY2026/3 (2026/3) totaled ¥90, and the total payout ratio for the year was 87.4%. For FY2027/3, the company forecasts dividends per share of ¥100. Under the basic policy for capital measures, GLOBERIDE aims to increase dividends stably and continuously while maintaining a total payout ratio of approximately 50% over the full period of the Medium-Term Management Plan 2030 (FY2027/3–FY2031/3).
| Item | 2026/3 (Actual) | 2027/3 (Forecast) |
|---|---|---|
| Dividends per share (yen) | 90 | 100 |
| Total payout ratio | 87.4% | — |
Medium-Term Management Plan 2030
Under the newly formulated Medium-Term Management Plan 2030 (FY2027/3–FY2031/3), GLOBERIDE targets net sales of ¥160,000 million, operating profit of ¥16,000 million (a 10.0% operating profit ratio) and profit attributable to owners of parent of ¥12,000 million for FY2031/3, implying a compound annual growth rate of 4.7% for net sales, 19.7% for operating profit and 17.3% for net profit over the plan period. The company aims to achieve an ROE of 12% or higher by FY2031/3, exceeding its estimated cost of shareholders’ equity of 7.6%–9.6%, and to sustain a PBR of 1.0x or higher on a continuous basis; PBR remained below 1.0x as of the end of March 2026.
For cash allocation over the plan period (FY2027/3–FY2031/3), the company expects approximately ¥60.0 billion in cash flow from operations, plus approximately ¥9.0 billion from a review of asset holdings and approximately ¥7.0 billion in procurement, against planned outflows of approximately ¥27.5 billion for growth investment, approximately ¥21.5 billion for the MIRAI Field Project, approximately ¥5.0 billion for renewal investment, and approximately ¥22.0 billion for shareholder returns.
| Category | Amount (billion yen, approx.) |
|---|---|
| CF from operations (inflow) | 60.0 |
| Review of asset holdings (inflow) | 9.0 |
| Procurement (inflow) | 7.0 |
| Growth investment (outflow) | 27.5 |
| Investment in the MIRAI Field Project (outflow) | 21.5 |
| Investment for renewal (outflow) | 5.0 |
| Shareholder returns (outflow) | 22.0 |
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















