
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
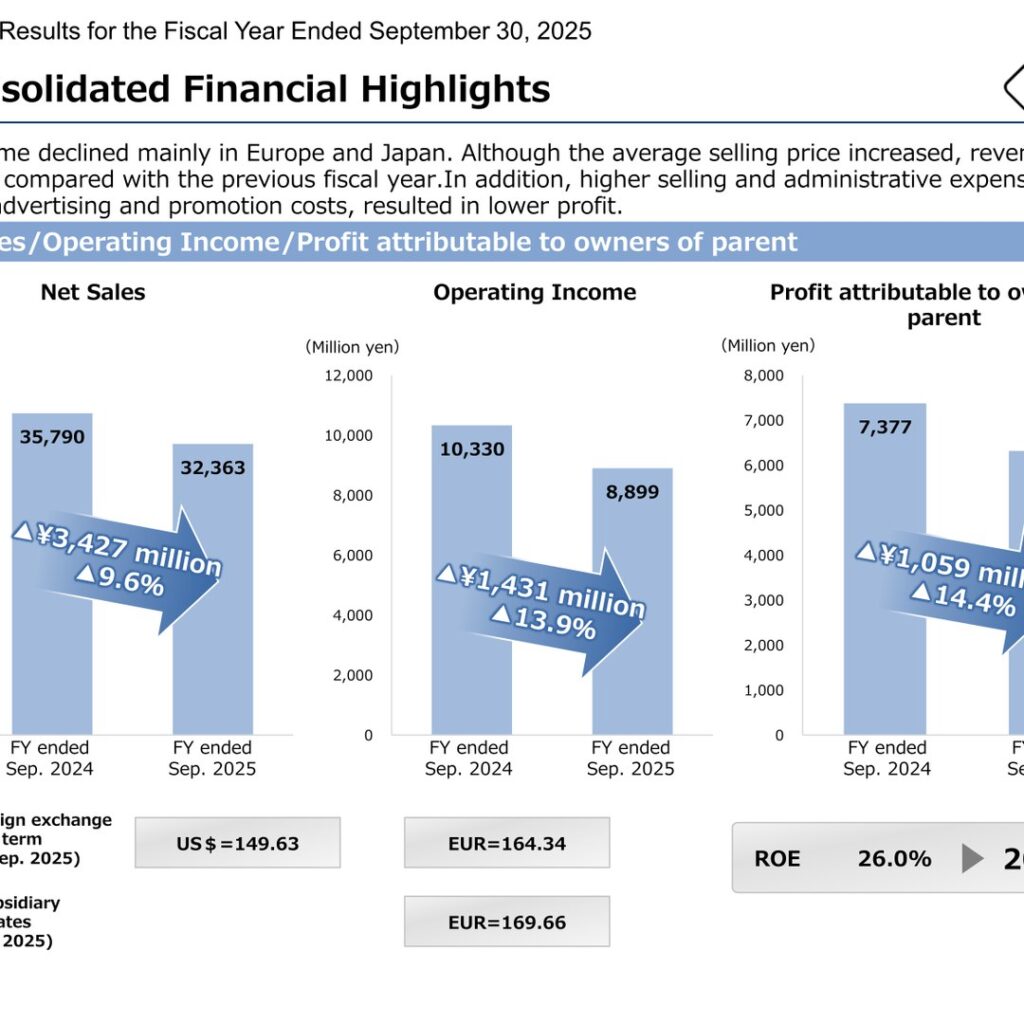
SHOEI Co., Ltd., the premium motorcycle helmet maker, reported consolidated net sales of 32,363 million yen and operating income of 8,899 million yen for the fiscal year ended September 30, 2025, both down from the prior year as sales volume continued to normalize after the pandemic-era outdoor boom. Consolidated sales volume fell 11.9% year on year to 636 thousand units — a level the company says is now comparable to the pre-pandemic September 2021 period. Despite the decline, the company says it achieved its originally forecasted profit, and ROE came in at 20.5% with an operating profit margin of 27.5%.
Consolidated Results (Full-Year Actual)
Sales volume declined mainly in Europe and Japan. Although the average selling price increased, revenue decreased compared with the previous fiscal year. In addition, higher selling and administrative expenses, including advertising and promotion costs, resulted in lower profit.
| Item | FY ended Sep. 2025 (Actual) | FY ended Sep. 2024 (Actual) | Change |
|---|---|---|---|
| Net Sales (million yen) | 32,363 | 35,790 | -¥3,427 million / -9.6% |
| Operating Income (million yen) | 8,899 | 10,330 | -¥1,431 million / -13.9% |
| Profit Attributable to Owners of Parent (million yen) | 6,318 | 7,377 | -¥1,059 million / -14.4% |
| ROE | 20.5% | 26.0% | — |
| Consolidated Sales Volume (thousand units) | 636 | 721 | -85 thousand / -11.9% |
Average foreign exchange rates for the fiscal year ended September 2025 were US$=¥149.63 and EUR=¥164.34 (overseas subsidiary conversion rate as of end of June 2025: EUR=¥169.66). Consolidated production volume declined by 79 thousand units year-on-year to 596 thousand units due to inventory depletion in distribution.
Segment Results (Sales Volume and Net Sales by Region)
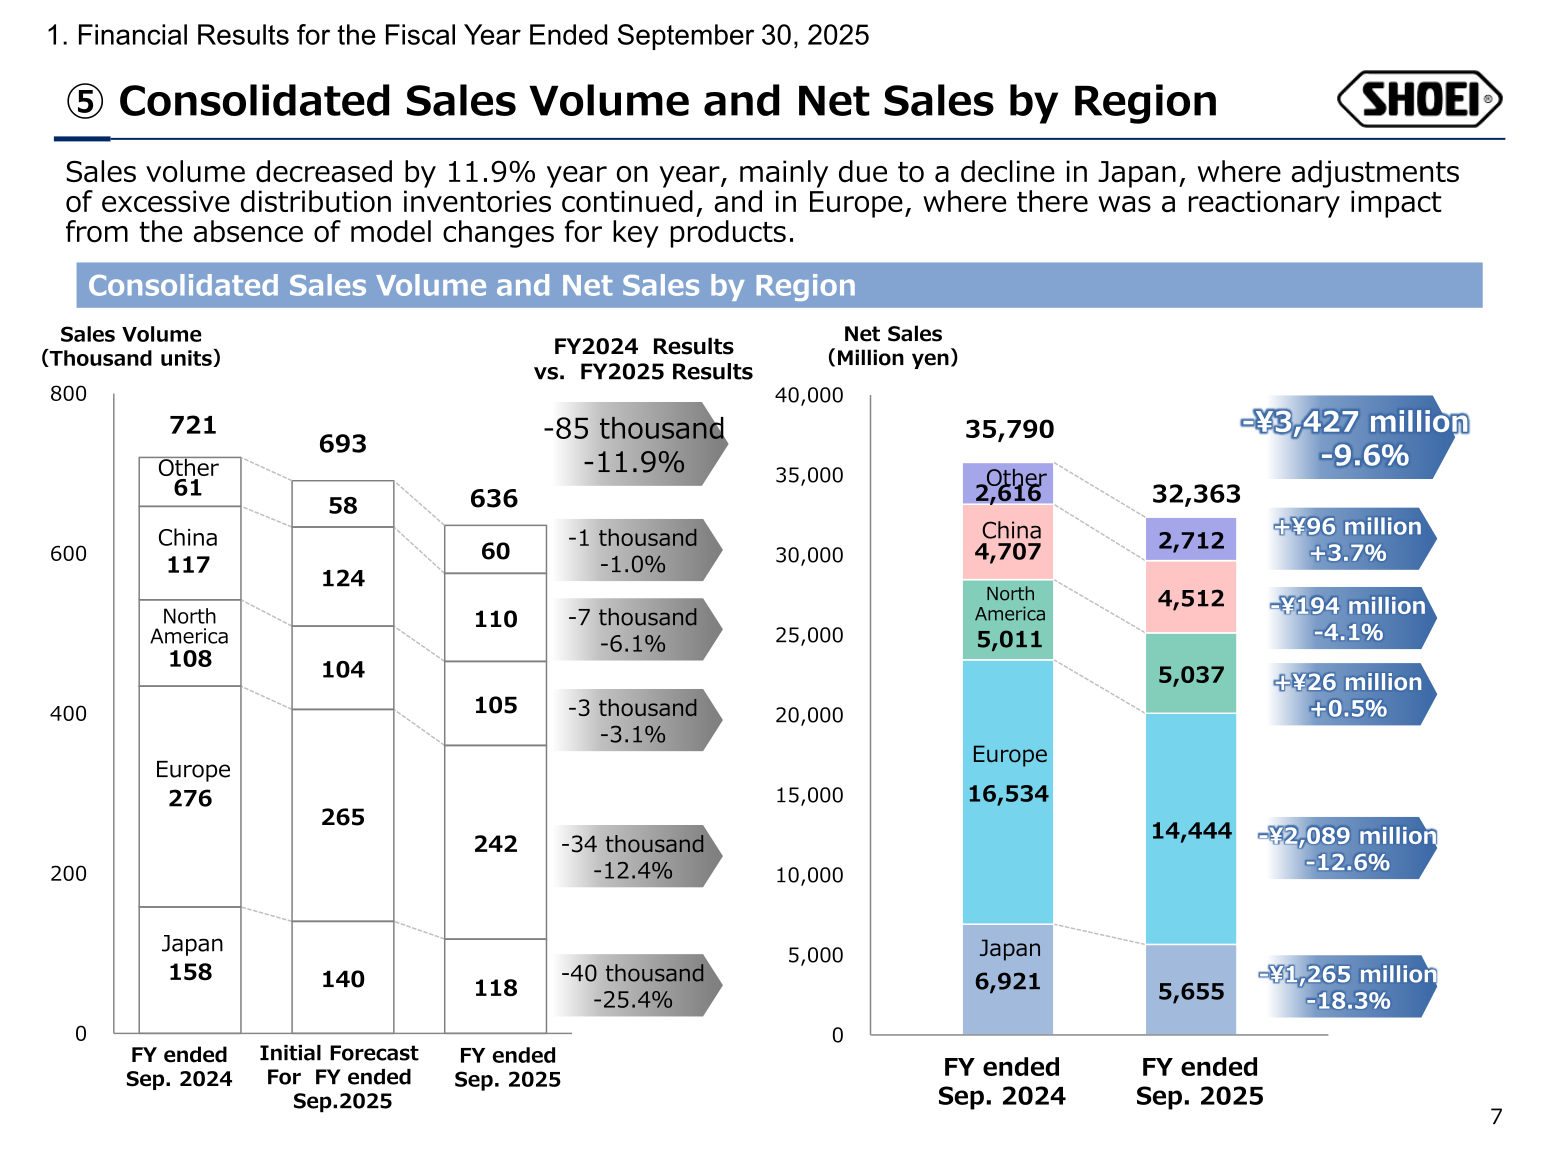
Sales volume decreased by 11.9% year on year, mainly due to a decline in Japan, where adjustments of excessive distribution inventories continued, and in Europe, where there was a reactionary impact from the absence of model changes for key products.
| Region | Sales Volume FY2025 (thousand units) | Sales Volume FY2024 (thousand units) | Net Sales FY2025 (million yen) | Net Sales FY2024 (million yen) |
|---|---|---|---|---|
| Japan | 118 | 158 | 5,655 | 6,921 |
| Europe | 242 | 276 | 14,444 | 16,534 |
| North America | 105 | 108 | 5,037 | 5,011 |
| China | 110 | 117 | 4,512 | 4,707 |
| Other | 60 | 61 | 2,712 | 2,616 |
| Total | 636 | 721 | 32,363 | 35,790 |
FY2026 Forecast
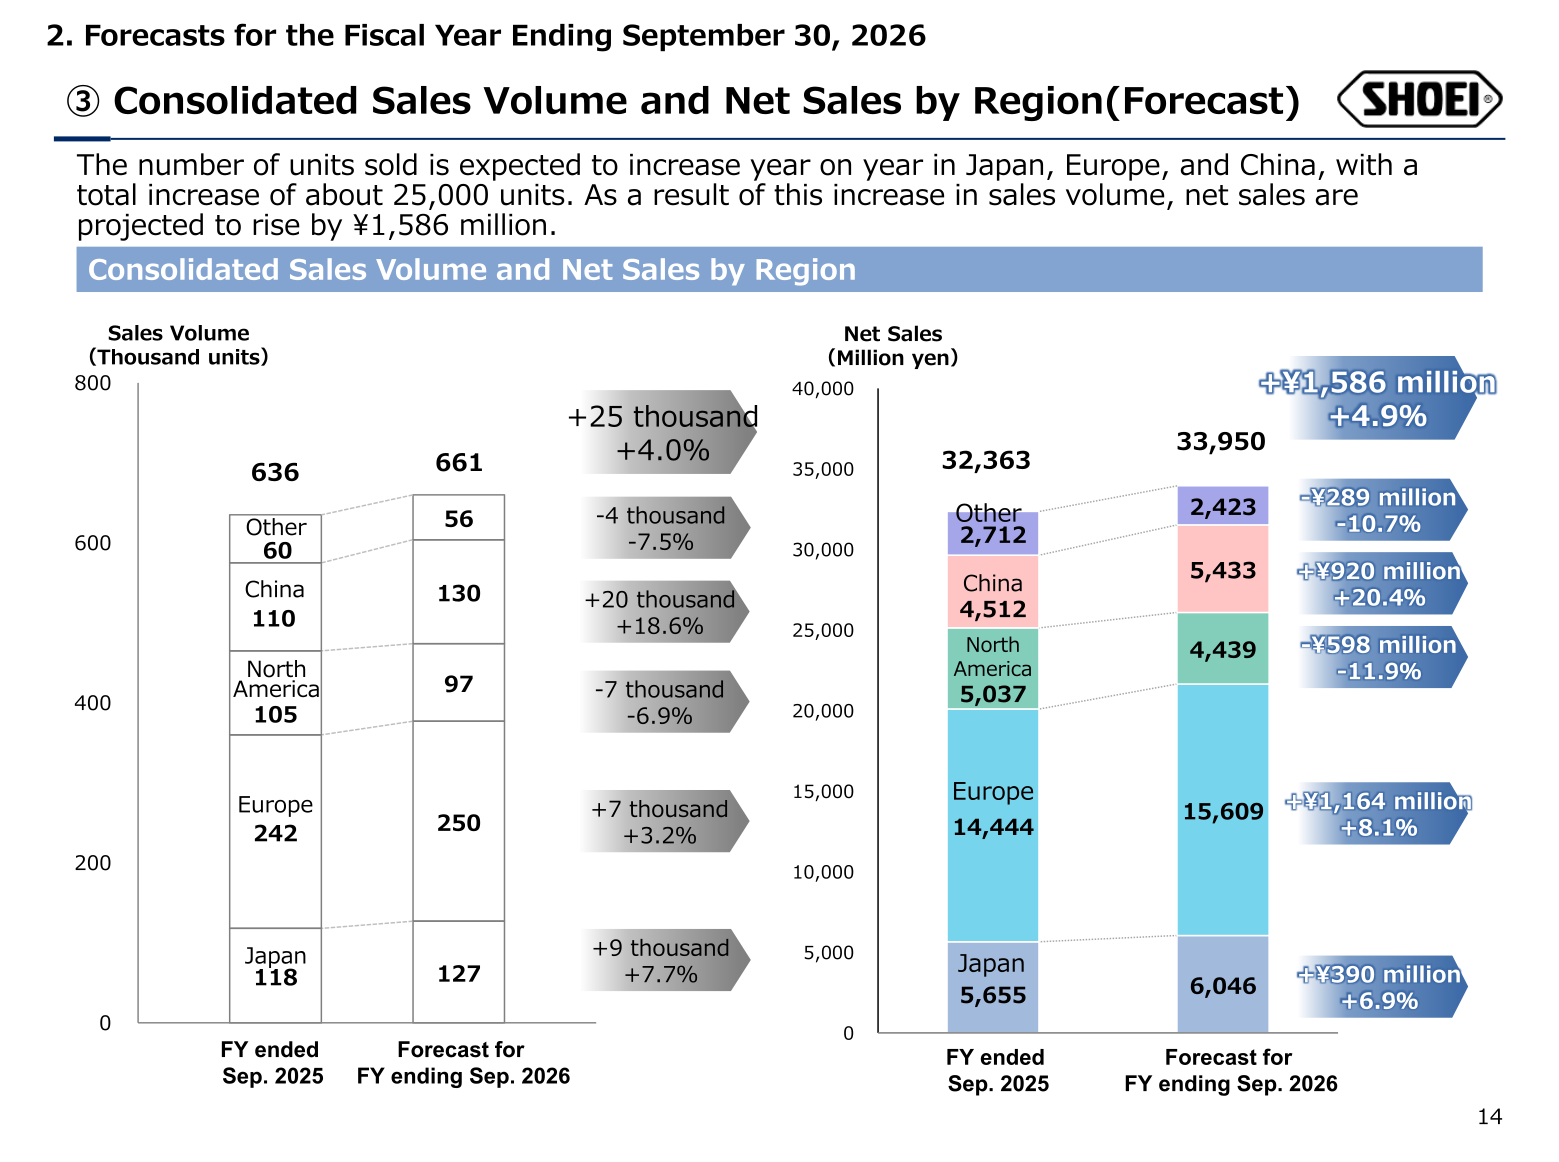
Excess inventory observed in the previous period at certain European and Japanese distributors has been largely normalized. With model changes for key products, consolidated unit sales are expected to increase 4.0% year-on-year, and consolidated net sales are projected to grow 4.9%. However, the reduction of inventory at subsidiaries will reduce the positive impact of unrealized profit compared with the previous period, and taking into account the impact of the U.S. tariff increase, consolidated operating profit is projected to decline 5.9% year-on-year. Foreign exchange rates are assumed at JPY 145 per USD and JPY 174 per EUR.
| Item | Forecast for FY ending Sep. 2026 | FY ended Sep. 2025 (Actual) |
|---|---|---|
| Net Sales (million yen) | 33,950 | 32,363 |
| Operating Income (million yen) | 8,370 | 8,899 |
| Profit Attributable to Owners of Parent (million yen) | 5,940 | 6,318 |
| Consolidated Sales Volume (thousand units) | 661 | 636 |
| Region | Sales Volume Forecast (thousand units) | Sales Volume FY2025 Actual (thousand units) | Net Sales Forecast (million yen) | Net Sales FY2025 Actual (million yen) |
|---|---|---|---|---|
| Japan | 127 | 118 | 6,046 | 5,655 |
| Europe | 250 | 242 | 15,609 | 14,444 |
| North America | 97 | 105 | 4,439 | 5,037 |
| China | 130 | 110 | 5,433 | 4,512 |
| Other | 56 | 60 | 2,423 | 2,712 |
| Total | 661 | 636 | 33,950 | 32,363 |
Based on the U.S. presidential executive order announced in September 2025, a reciprocal tariff rate of 15% has been imposed on helmets. The company is currently discussing its response with the local distributor and estimates the tariff impact at approximately 300 million yen, which has been incorporated into the FY2026 budget. The company also expects the positive impact of unrealized profits at European subsidiaries — which supported operating income in FY2024 and FY2025 as those subsidiaries reduced inventories built up in FY2023 — to decline significantly in FY2026 as inventories have stabilized.
Shareholder Returns
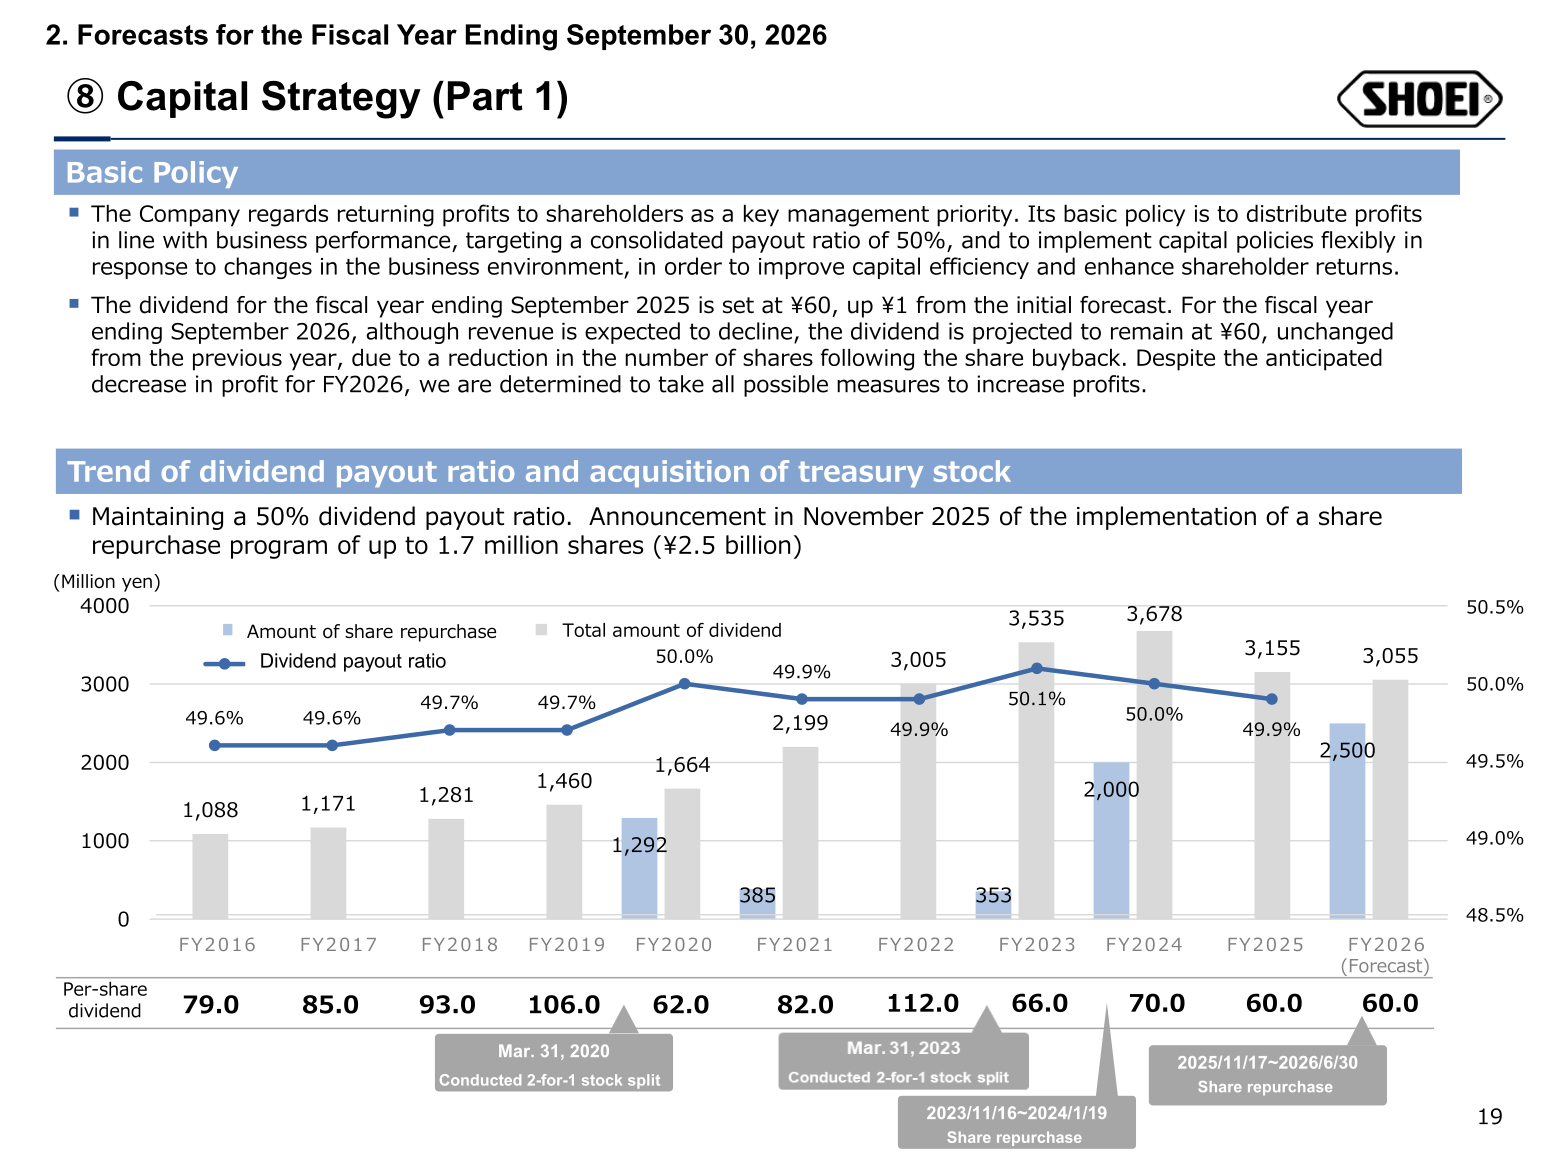
The Company regards returning profits to shareholders as a key management priority. Its basic policy is to distribute profits in line with business performance, targeting a consolidated payout ratio of 50%, and to implement capital policies flexibly in response to changes in the business environment. The dividend for the fiscal year ended September 2025 is set at ¥60 per share, up ¥1 from the initial forecast, with a dividend payout ratio of 49.9% and a total dividend amount of 3,155 million yen. For the fiscal year ending September 2026, although revenue is expected to decline, the dividend is projected to remain at ¥60 per share, unchanged from the previous year, due to a reduction in the number of shares following the share buyback (total dividend amount forecast: 3,055 million yen). In November 2025, the company announced a share repurchase program of up to 1.7 million shares (¥2.5 billion), to be conducted from November 17, 2025 through June 30, 2026.
Growth Strategy and Topics
During the fiscal year, the company launched the J·O2 model in Europe and unveiled the WYVERN ∅ (Zero), a revival of the popular WYVERN series from the 1990s–2000s, with global expansion into the Japanese market in September 2025 and planned expansion into the Asian market. The company also expanded its lineup of collaboration helmets (including a Hatsune Miku collaboration and a Gundam series replica helmet line) and racer replica helmets. Limited sales of a new carbon helmet, made with a new material, started in October 2025 at SHOEI Gallery stores. As a new business venture, the company plans to launch a suitcase business, leveraging similarities in product concept, manufacturing methods and B2C positioning with its premium helmet business; the first model is scheduled to be sold on MAKUAKE in January 2026 at a planned price of ¥49,500 (tax included), with a target of ¥3 billion in sales and several hundred million yen in operating profit within three years. The company also renewed its contracts with riders Marc Márquez and Álex Márquez for an additional two years, through 2026, and plans to open the SHOEI HELMET PARK — a museum, showroom, merchandise shop and dining space adjacent to its Ibaraki factory — in spring 2026.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















