
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
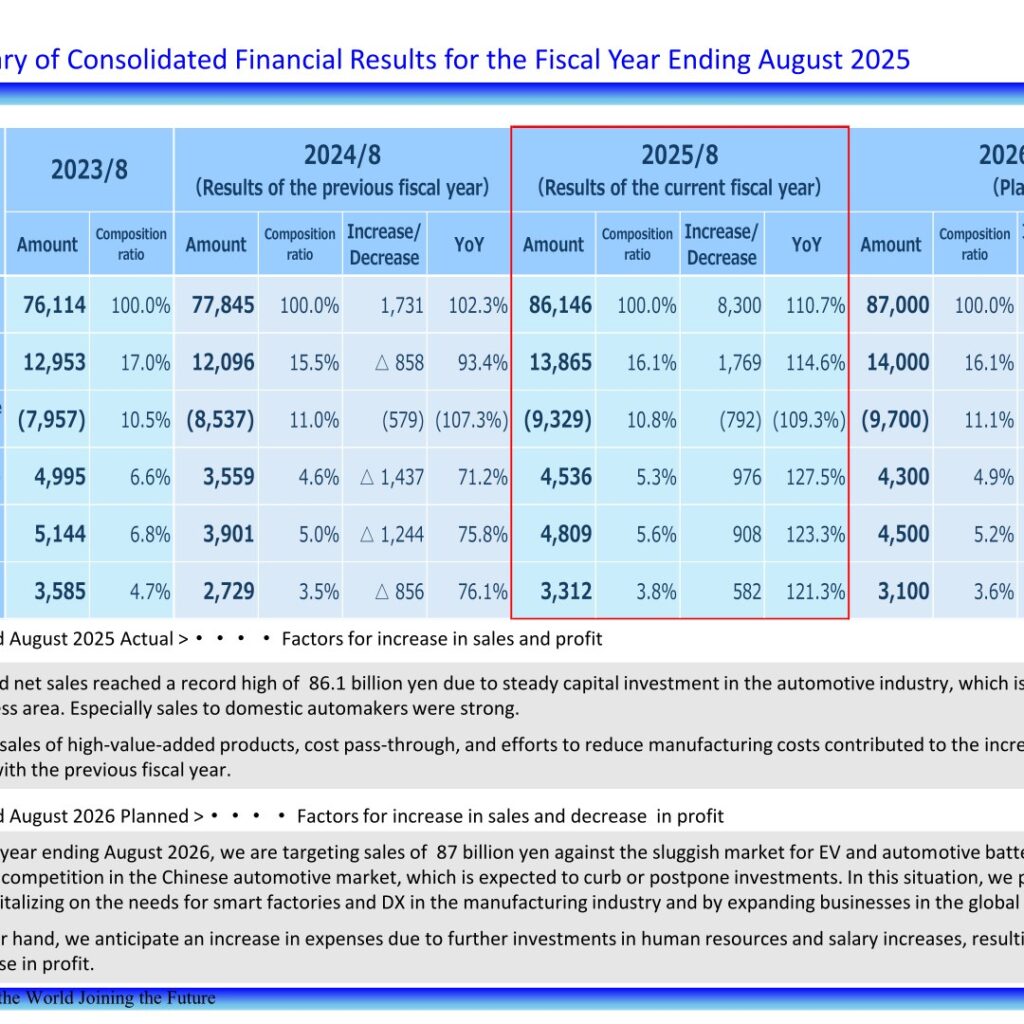
SHINWA Co., Ltd. (7607), an engineering trading company handling metal-joining, industrial machinery and FA-system products for the automotive and manufacturing industries, reported consolidated net sales of 86,146 million yen for the fiscal year ended August 31, 2025 (its 75th fiscal year), a record high and 110.7% of the previous year’s level. Operating income rose to 4,536 million yen (127.5% of the previous year), ordinary profit rose to 4,809 million yen (123.3% of the previous year), and profit attributable to owners of parent rose to 3,312 million yen (121.3% of the previous year). The company attributed the increase mainly to steady capital investment in the automotive industry, its main business area, with particularly strong sales to domestic automakers.
Consolidated Results (Full-Year Actual)
All key profit lines increased year on year in FY2025. Gross margin rose to 13,865 million yen (16.1% of sales) from 12,096 million yen (15.5%), while selling and administrative expenses increased to 9,329 million yen. The company said sales of high-value-added products, cost pass-through, and efforts to reduce manufacturing costs also contributed to the increase in earnings. Figures below are in millions of yen unless noted.
| Item | FY2024 | FY2025 | YoY |
|---|---|---|---|
| Net sales | 77,845 | 86,146 | 110.7% |
| Gross margin | 12,096 | 13,865 | 114.6% |
| Selling & administrative expenses | (8,537) | (9,329) | (109.3%) |
| Operating income | 3,559 | 4,536 | 127.5% |
| Ordinary profit | 3,901 | 4,809 | 123.3% |
| Net profit (attributable to owners of parent) | 2,729 | 3,312 | 121.3% |
Segment Results (by Geographic Region)
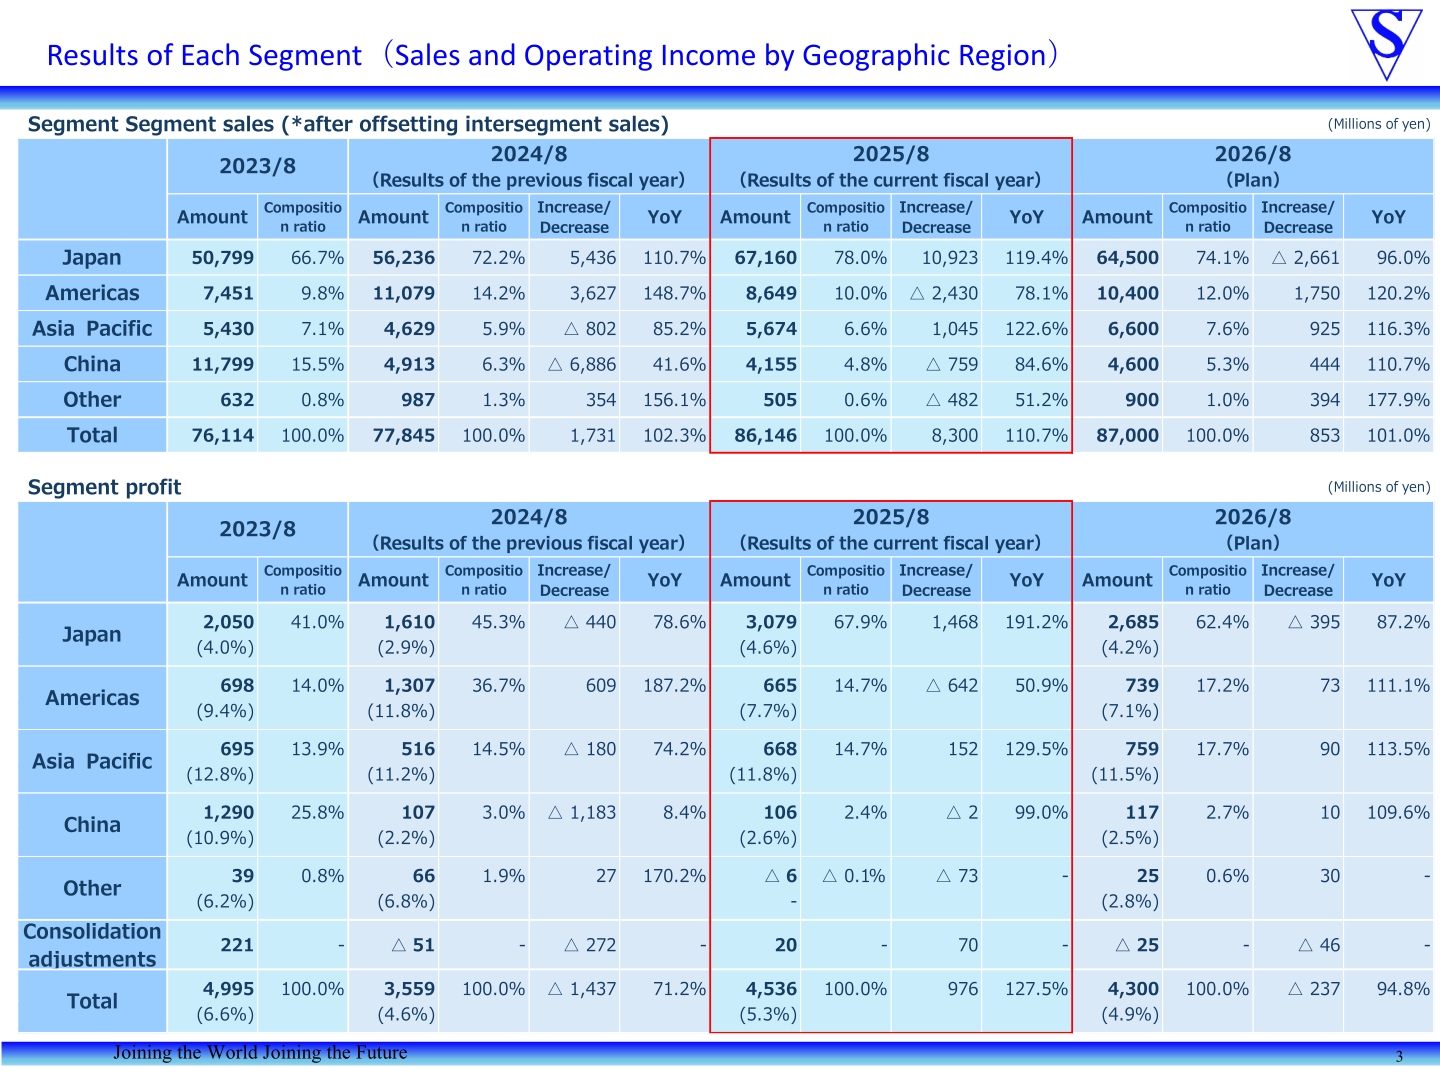
The Japan segment led growth, with sales rising to 67,160 million yen (119.4% of the previous year) and segment profit rising to 3,079 million yen (191.2% of the previous year), mainly due to steady growth in production facilities for EV and automotive batteries and automation projects for in-plant logistics. The Americas segment declined as large-scale projects for Japanese air-conditioner manufacturers in the U.S. and Mexico did not repeat from the prior year. Asia Pacific segment sales and profit increased, partly due to the inclusion of the group’s Indian subsidiary in the scope of consolidation from the fiscal year ended August 2025. The China segment declined amid a slowdown in the overall Chinese economy and restrained capital investment by Japanese automakers facing intensified competition from local automakers.
| Segment | FY2024 Sales | FY2025 Sales | Sales YoY | FY2025 Segment Profit | Profit YoY |
|---|---|---|---|---|---|
| Japan | 56,236 | 67,160 | 119.4% | 3,079 | 191.2% |
| Americas | 11,079 | 8,649 | 78.1% | 665 | 50.9% |
| Asia Pacific | 4,629 | 5,674 | 122.6% | 668 | 129.5% |
| China | 4,913 | 4,155 | 84.6% | 106 | 99.0% |
| Other | 987 | 505 | 51.2% | △6 | – |
| Total | 77,845 | 86,146 | 110.7% | 4,536 | 127.5% |
FY2026 Forecast
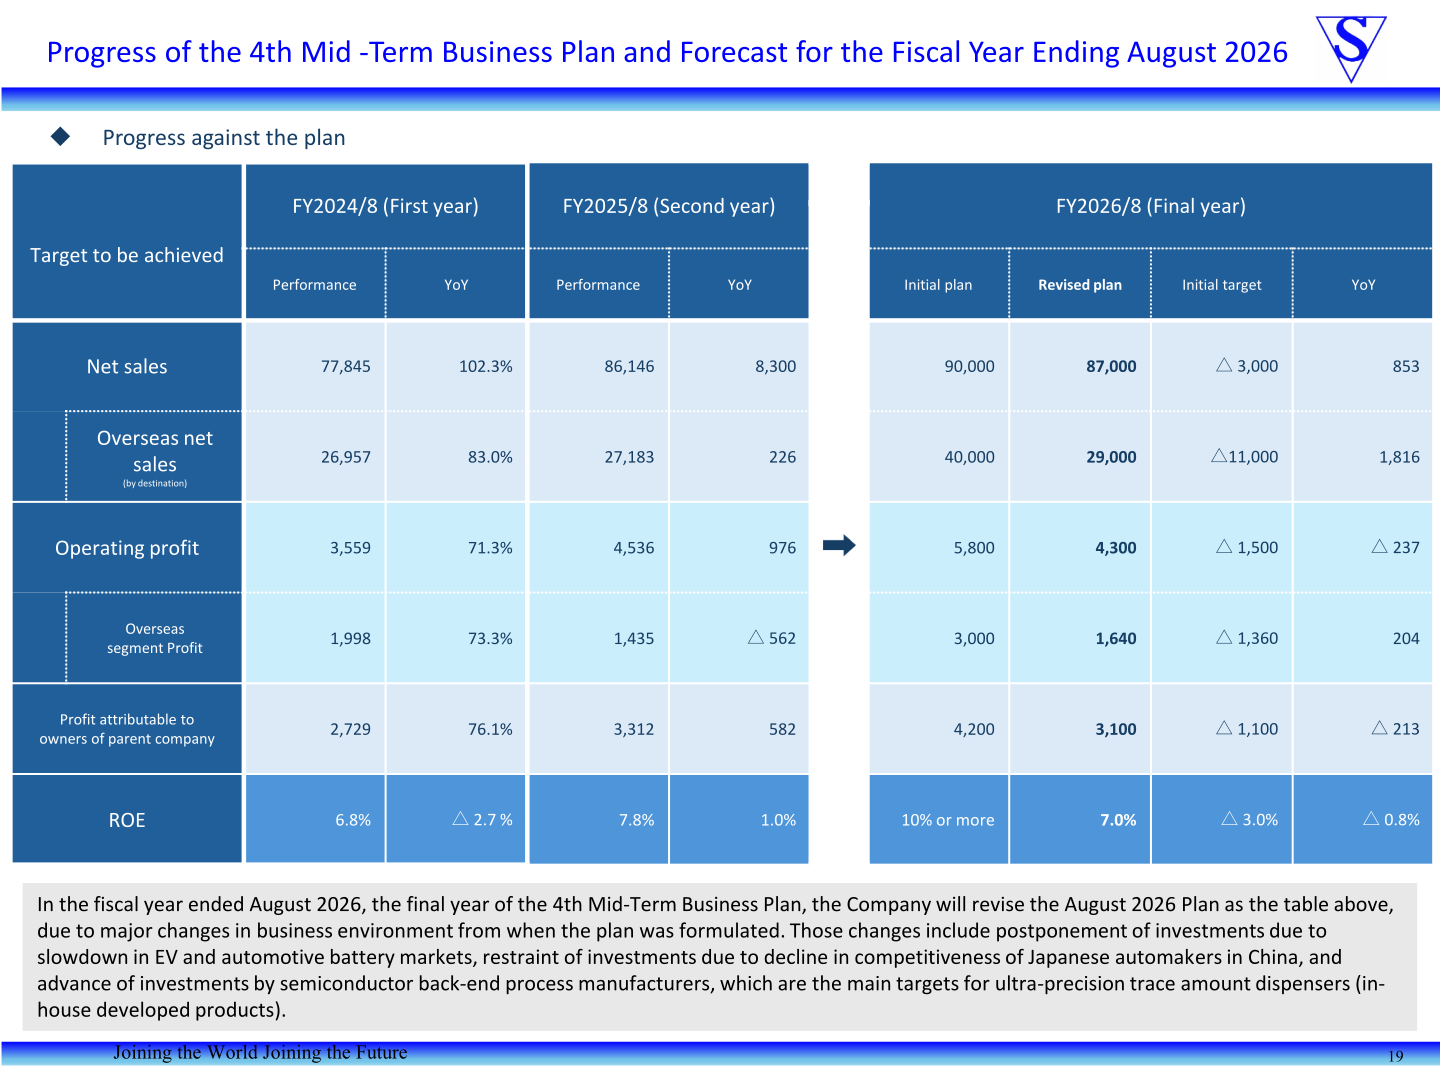
For the fiscal year ending August 2026 (76th fiscal year, the final year of the 4th Mid-Term Business Plan), SHINWA revised its initial plan downward. The company now targets net sales of 87 billion yen against a sluggish EV and automotive battery market and intensifying competition in the Chinese automotive market, which is expected to curb or postpone investment. The company plans to increase sales by capitalizing on demand for smart factories and DX in the manufacturing industry and by expanding business in the Global South, while anticipating an increase in expenses from further investment in human resources and salary increases, resulting in a year-on-year decrease in profit.
| Item | FY2026 Initial Plan | FY2026 Revised Plan | FY2025 (Actual) |
|---|---|---|---|
| Net sales | 90,000 | 87,000 | 86,146 |
| Overseas net sales (by destination) | 40,000 | 29,000 | 27,183 |
| Operating profit | 5,800 | 4,300 | 4,536 |
| Overseas segment profit | 3,000 | 1,640 | 1,435 |
| Profit attributable to owners of parent | 4,200 | 3,100 | 3,312 |
| ROE | 10% or more | 7.0% | 7.8% |
Shareholder Returns
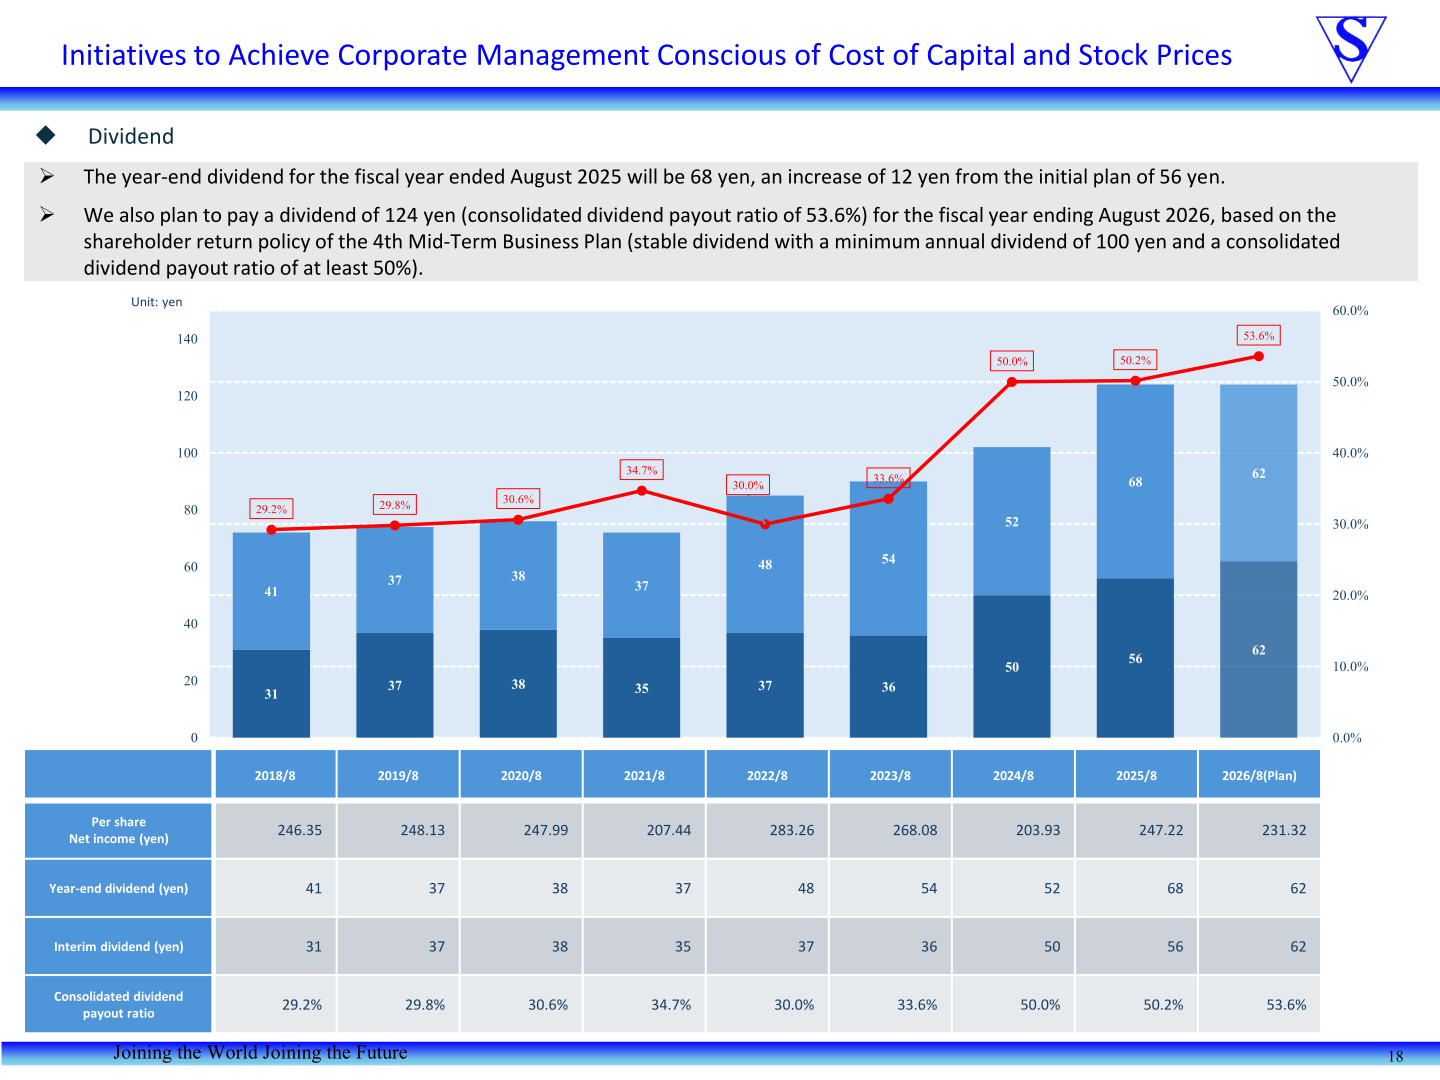
SHINWA raised its year-end dividend for the fiscal year ended August 2025 to 68 yen per share, 12 yen above the initial plan of 56 yen. Combined with the 56 yen interim dividend, the full-year dividend resulted in a consolidated dividend payout ratio of 50.2%. For the fiscal year ending August 2026, the company plans to pay a full-year dividend of 124 yen (interim 62 yen, year-end 62 yen), a consolidated payout ratio of 53.6%, based on the shareholder return policy of its 4th Mid-Term Business Plan: a stable dividend with a minimum annual dividend of 100 yen and a consolidated dividend payout ratio of 50% or more.
| Item | FY2024 | FY2025 | FY2026 (Plan) |
|---|---|---|---|
| Interim dividend (yen) | 50 | 56 | 62 |
| Year-end dividend (yen) | 52 | 68 | 62 |
| Net income per share (yen) | 203.93 | 247.22 | 231.32 |
| Consolidated dividend payout ratio | 50.0% | 50.2% | 53.6% |
Medium-Term Plan / Topics
Under its 4th Mid-Term Business Plan, SHINWA plans to invest a total of approximately 5.5 billion yen (including about 2 billion yen in the fiscal year ending August 2026) between the fiscal year ending August 2026 and the fiscal year ending August 2028 to establish a second Kasugai Plant (tentative name), aimed at growing its Smart Factory Innovation segment. Capital expenditure (including intangible assets) for the fiscal year ended August 2025 was 744 million yen, mainly for machinery and equipment such as laser welders and tools and fixtures for ultra-precision trace-amount dispensers in the manufacturing division; the company plans capital expenditure of 1,232 million yen in the fiscal year ending August 2026 for visual inspection machines for vehicle bodies and laser welding machines. Depreciation and amortization was 800 million yen in the fiscal year ended August 2025, reflecting the fiscal year ended August 2023 upgrade of a new Core IT Infrastructure System and the establishment of the Kasugai Works and SFiC Laboratories, and is expected to remain at a high level from the fiscal year ending August 2026. R&D expenses were 157 million yen in the fiscal year ended August 2025, related to the development of automotive battery components and related technologies and new models of its Ultra Precision Dispensing Equipment; the company plans to reduce R&D expenditures by 21.6% year on year to 123 million yen in the fiscal year ending August 2026 due to a slowdown in the EV and automotive battery industries. The company also stated that demand for its in-house developed ultra-precision dispenser ‘Quspa’ is expected to remain slow in the fiscal year ending August 2026, but that it expects to see a medium-term surge in demand for high-end dispensing applications suitable to Quspa for next-generation AI GPU and data-center fields.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















