
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
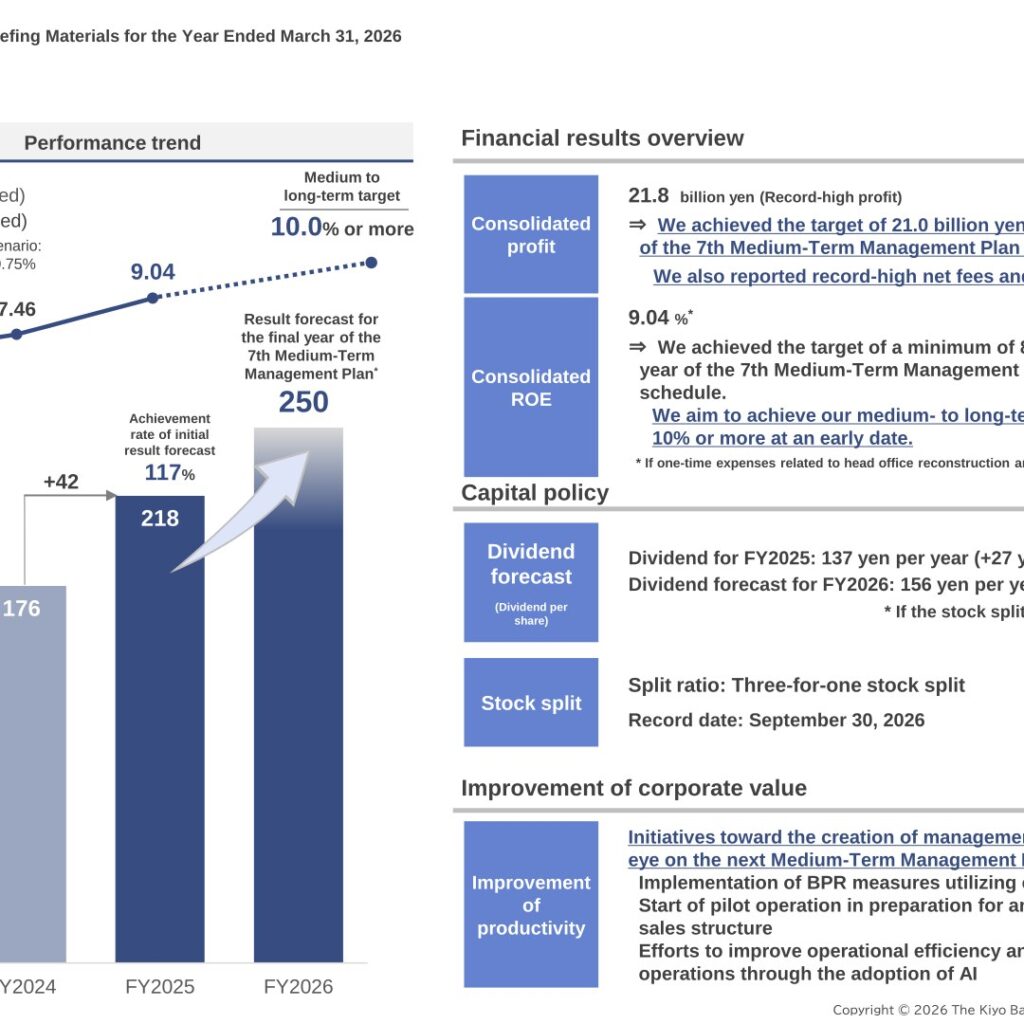
The Kiyo Bank, Ltd. (TSE Prime: 8370) reported record-high results for the fiscal year ended March 31, 2026. Consolidated profit attributable to owners of parent rose to 21.8 billion yen, a record high, up 4.2 billion yen year on year, mainly due to increases in net interest income and net fees and commissions, although expenses and credit costs also rose. Consolidated ROE reached 9.04%, and profit from customer services — the bank’s indicator of core-business earning power — reached a record 22.8 billion yen. The bank achieved the final-year targets of its 7th Medium-Term Management Plan for both profit (21.0 billion yen or more) and ROE (8% or more) one year ahead of schedule.
Consolidated Results (Full-Year Actual)
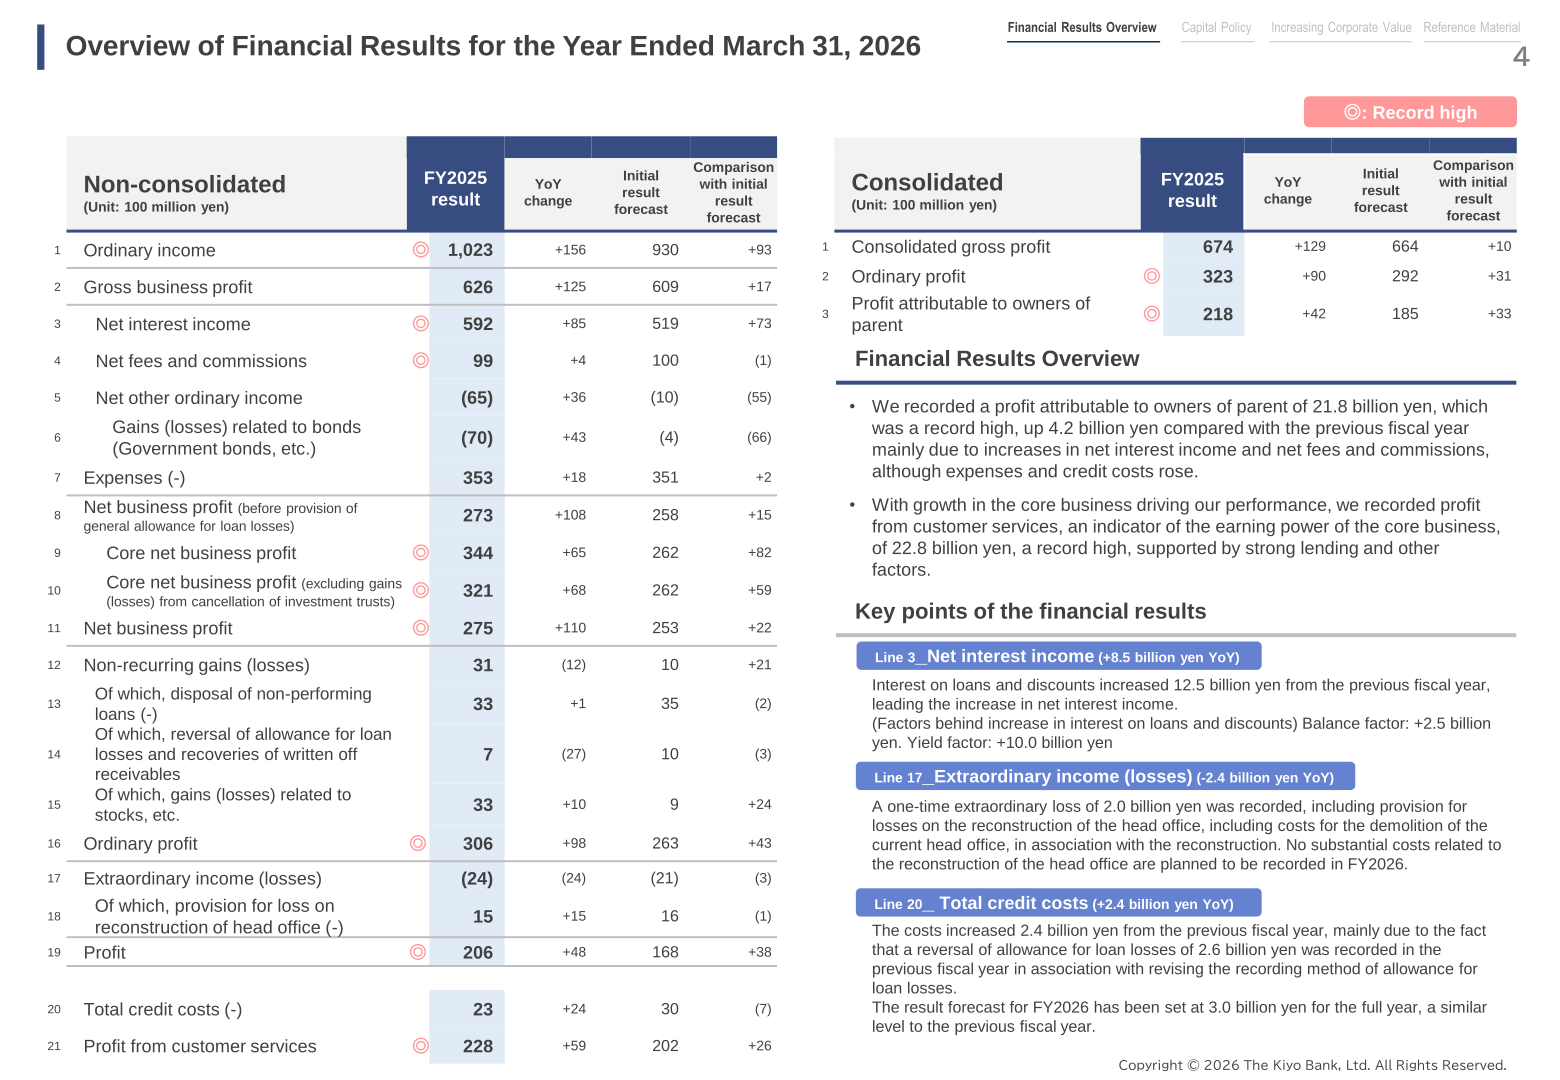
Consolidated gross profit, ordinary profit and profit attributable to owners of parent all increased year on year and exceeded the bank’s initial forecast for the year (unit: 100 million yen).
| Item | FY2025 Result | YoY Change | Initial Forecast | vs. Initial Forecast |
|---|---|---|---|---|
| Consolidated gross profit | 674 | +129 | 664 | +10 |
| Ordinary profit | 323 | +90 | 292 | +31 |
| Profit attributable to owners of parent | 218 | +42 | 185 | +33 |
On a non-consolidated basis, net interest income, net fees and commissions, core net business profit, net business profit, ordinary profit, profit and profit from customer services all reached record highs, as marked ◎ in the source materials (unit: 100 million yen).
| Item (Non-Consolidated) | FY2025 Result | YoY Change | Initial Forecast | vs. Initial Forecast |
|---|---|---|---|---|
| Ordinary income | 1,023 | +156 | 930 | +93 |
| Net interest income | 592 | +85 | 519 | +73 |
| Net fees and commissions | 99 | +4 | 100 | (1) |
| Expenses (-) | 353 | +18 | 351 | +2 |
| Core net business profit | 344 | +65 | 262 | +82 |
| Net business profit | 275 | +110 | 253 | +22 |
| Ordinary profit | 306 | +98 | 263 | +43 |
| Profit | 206 | +48 | 168 | +38 |
| Total credit costs (-) | 23 | +24 | 30 | (7) |
| Profit from customer services | 228 | +59 | 202 | +26 |
Net Interest Income, Loans and Deposits
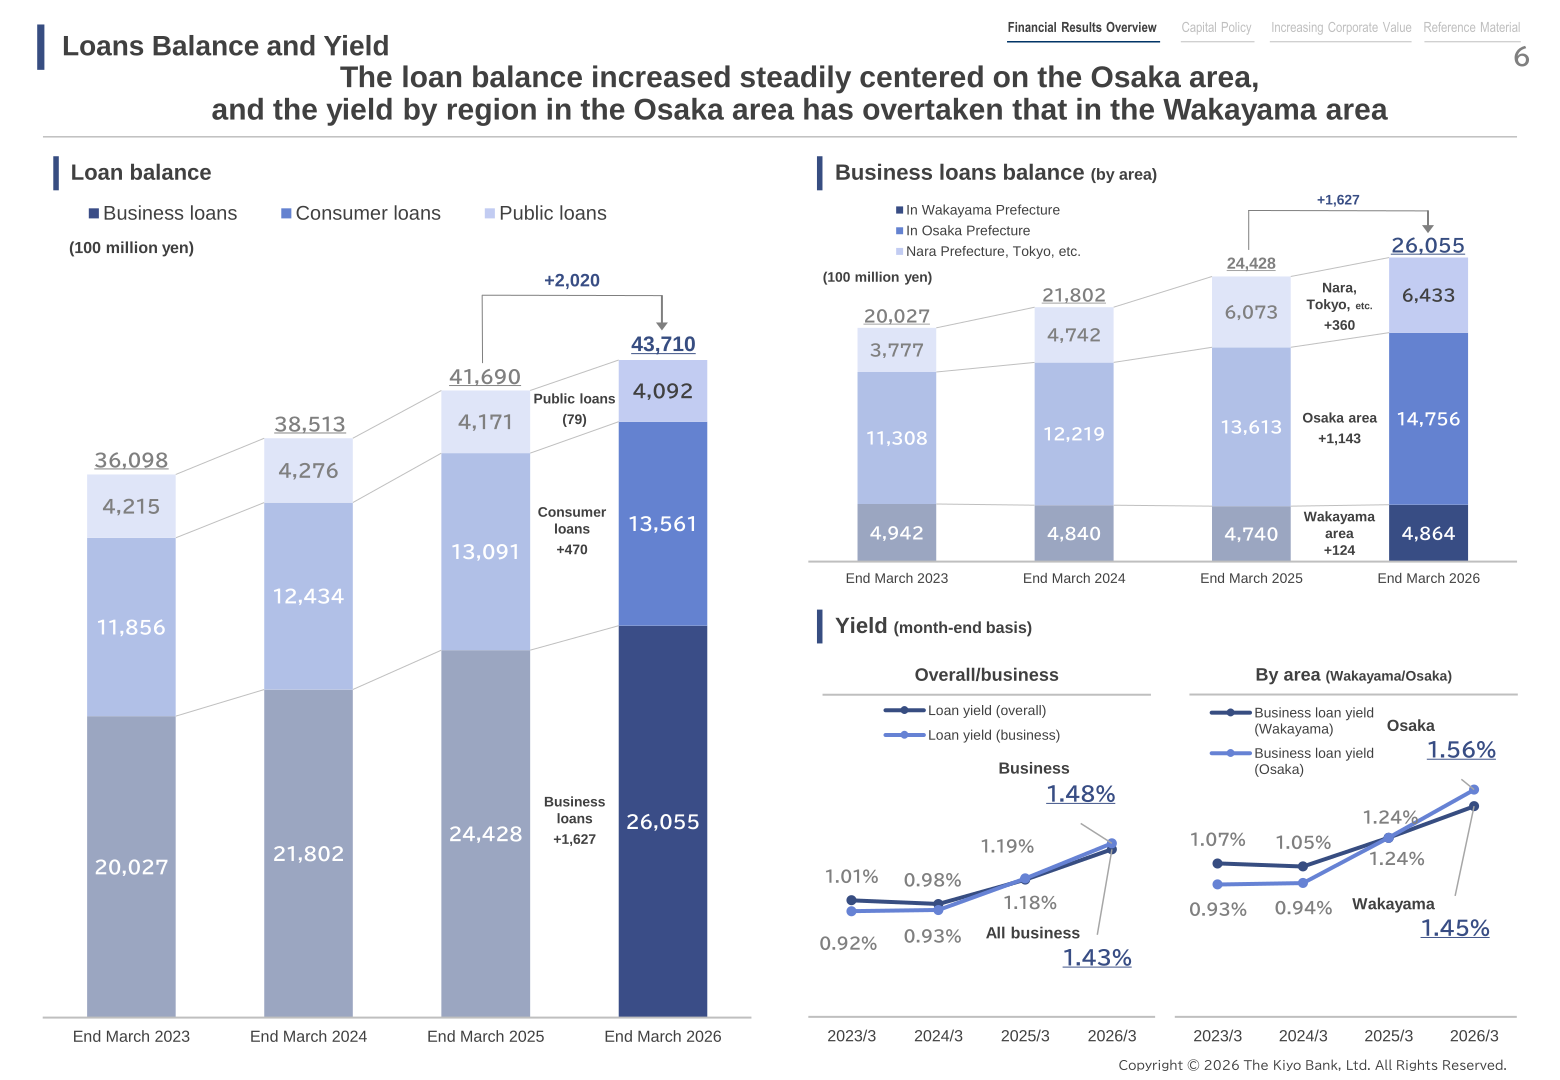
Net interest income broke its past highest record, reaching 592 (100 million yen), up 85 (+8.5 billion yen) year on year, primarily due to an increase in interest on loans and discounts, which rose to 552, an increase of 12.5 billion yen from the previous fiscal year (balance factor +2.5 billion yen, yield factor +10.0 billion yen). The difference between the average yield on loans and deposits was on a widening trend, with the loan yield reaching 1.43% and the deposit yield 0.28% as of March 2026. The loan balance increased steadily, centered on the Osaka area, and the loan yield by region in the Osaka area (1.56%) overtook that in the Wakayama area (1.45%) for the first time. Total loans and bills discounted reached 43,710 (100 million yen), up 2,020 year on year, of which business loans reached 26,055, up 1,627.
Expenses, OHR and Credit Costs
Non-consolidated expenses rose to 353 (100 million yen), up 18 year on year, comprising personnel expenses of 190 (+9), non-personnel expenses of 137 (+5) and taxes of 25. Core OHR (expenses divided by core gross business profit) improved to 50.6%, down 3.9 points year on year and below the bank’s estimate of the average of regional banks nationwide for FY2025 of 57.6%. Total credit costs were 23 (100 million yen), up 24 year on year, as a reversal of allowance for loan losses of 26 recorded in the previous fiscal year (associated with revising the recording method of allowance for loan losses) was not repeated. The non-performing loan ratio (Disclosed Claims under the Financial Reconstruction Law basis) improved to 1.34% as of March 2026, down from 1.44% a year earlier.
FY2026 Forecast
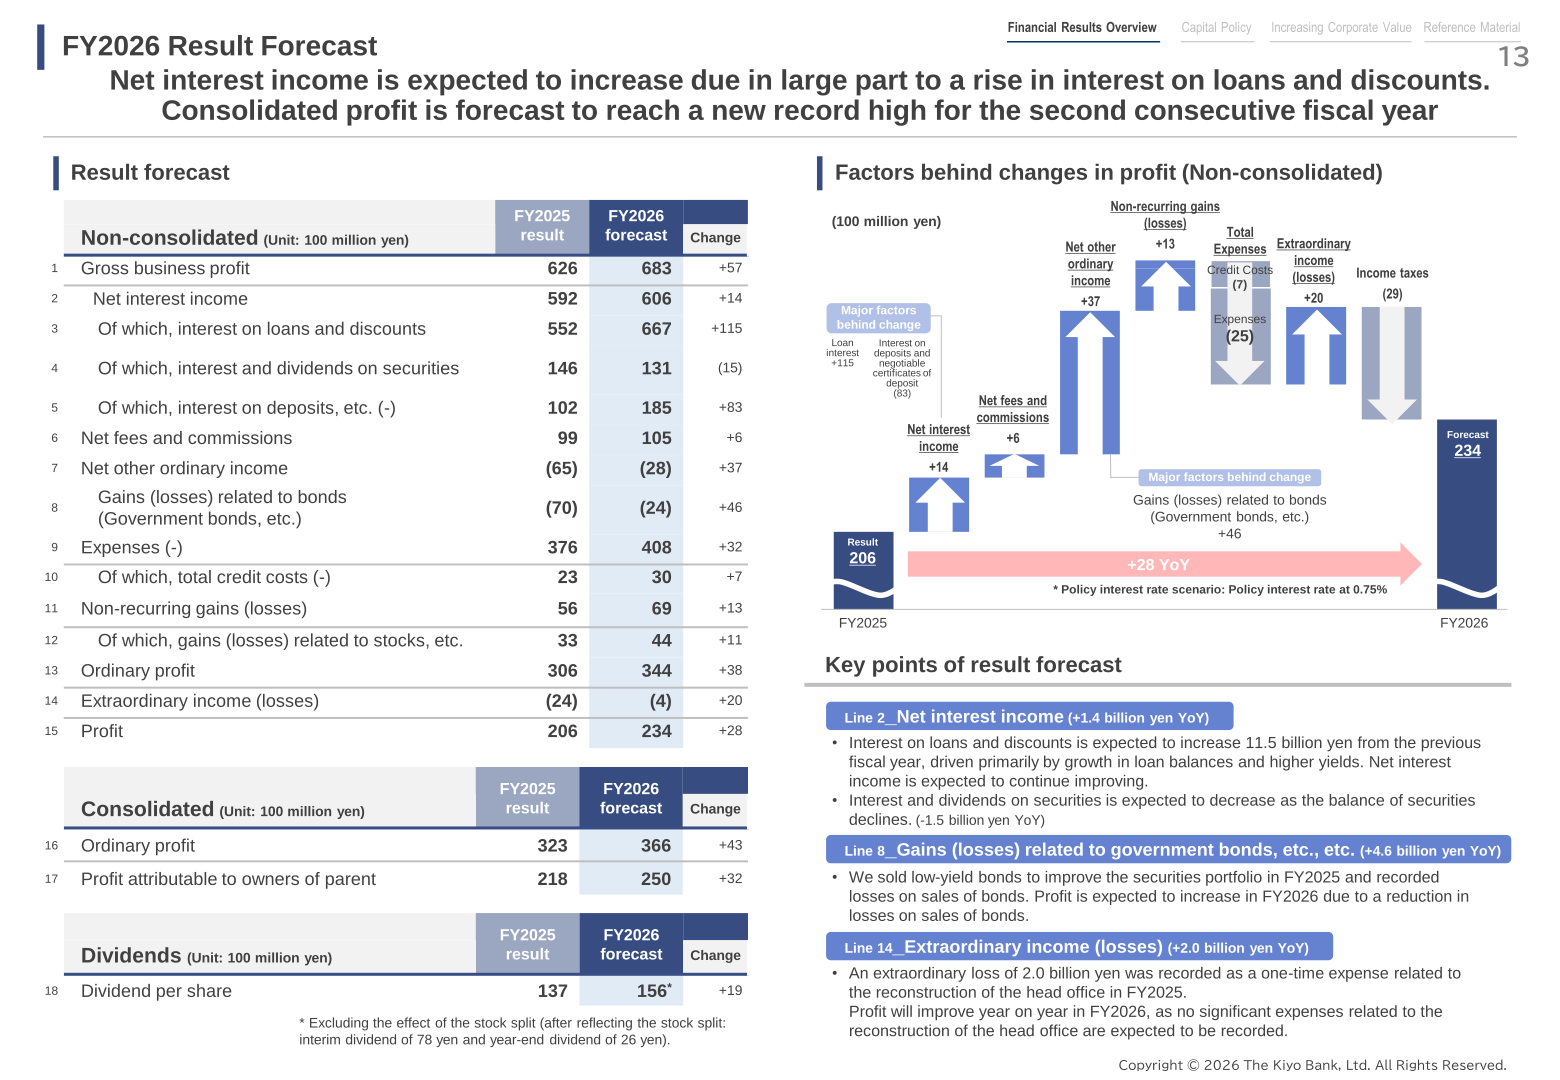
The bank forecasts a second consecutive record-high consolidated profit for FY2026, driven mainly by a further rise in interest on loans and discounts (unit: 100 million yen unless noted).
| Item | FY2025 (Actual) | FY2026 (Forecast) | Change |
|---|---|---|---|
| Gross business profit (Non-consolidated) | 626 | 683 | +57 |
| Net interest income (Non-consolidated) | 592 | 606 | +14 |
| Net fees and commissions (Non-consolidated) | 99 | 105 | +6 |
| Expenses (-) (Non-consolidated) | 376 | 408 | +32 |
| Ordinary profit (Non-consolidated) | 306 | 344 | +38 |
| Profit (Non-consolidated) | 206 | 234 | +28 |
| Ordinary profit (Consolidated) | 323 | 366 | +43 |
| Profit attributable to owners of parent (Consolidated) | 218 | 250 | +32 |
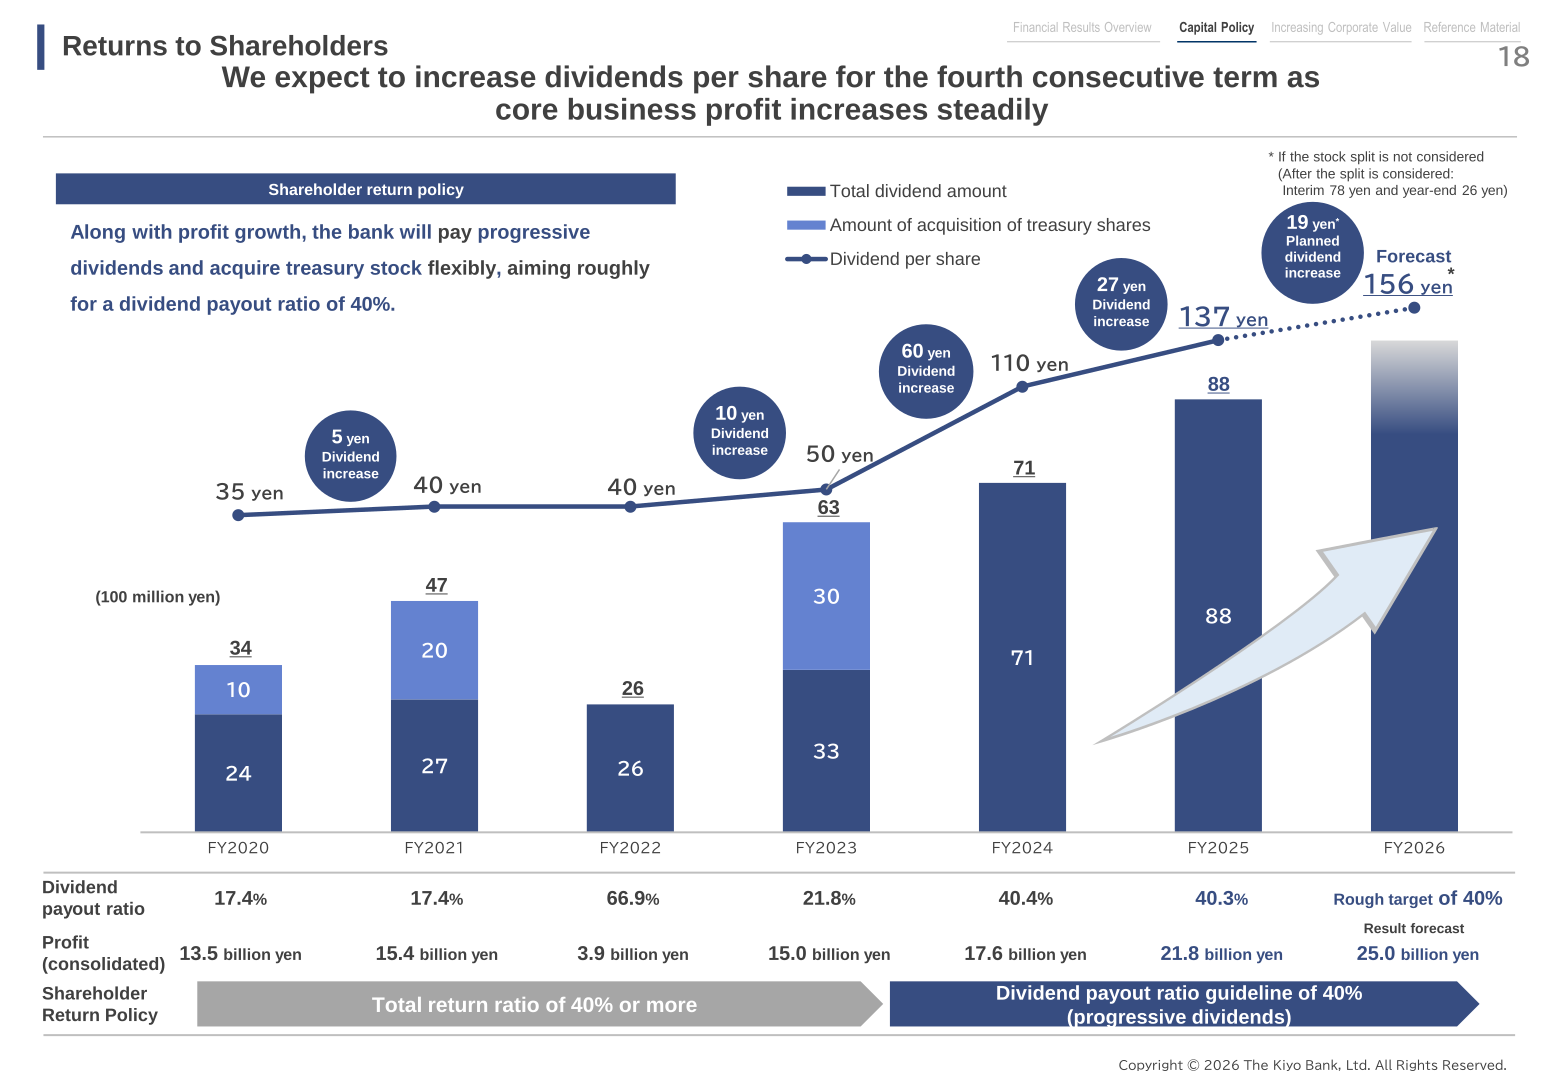
| Dividend per share (yen) | 137 | 156* | +19 |
*The FY2026 dividend forecast of 156 yen excludes the effect of the bank’s planned three-for-one stock split; after reflecting the split, it is equivalent to an interim dividend of 78 yen and a year-end dividend of 26 yen. The FY2026 result forecast assumes a policy interest rate of 0.75%. Interest and dividends on securities are expected to decrease 1.5 billion yen year on year as the securities balance declines, and an extraordinary loss of 2.0 billion yen recorded in FY2025 for head office reconstruction is not expected to recur in FY2026.
Capital Policy and Shareholder Returns
The bank’s shareholder return policy is to pay progressive dividends and acquire treasury stock flexibly, aiming roughly for a dividend payout ratio of 40%. The dividend per share has been raised for four consecutive terms, and the FY2025 payout ratio was 40.3%. Consolidated equity capital reached 2,422 (100 million yen) as of March 2026, with a consolidated capital adequacy ratio of 12.26%, which the bank considers to be trending within the scope of its plan toward an appropriate level of about 10 to 11% (the target for the final year of the 7th Medium-Term Management Plan). The Board of Directors resolved on May 14, 2026 to implement a three-for-one stock split (record date September 30, 2026; effective date October 1, 2026) and to introduce a shareholder benefit program offering catalog gifts of Wakayama Prefecture products.
| Item | FY2020 | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 | FY2026 (Forecast) |
|---|---|---|---|---|---|---|---|
| Dividend per share (yen) | 35 | 40 | 40 | 50 | 110 | 137 | 156* |
| Dividend payout ratio | 17.4% | 17.4% | 66.9% | 21.8% | 40.4% | 40.3% | Rough target of 40% |
Medium-Term Plan / Topics
Under the 7th Medium-Term Management Plan (April 2024 – March 2027, concept: “KX — Kiyo transformation”), the bank reformed its business model to one with transactions with SMEs as the start line, focused on the Wakayama and Osaka areas. In April 2026 the bank established a new IR Promotion Office to strengthen engagement activities with investors, and it is pursuing BPR measures with external consultants and expanded use of AI tools (an “AI Policy” was established in May 2026) in preparation for the next Medium-Term Management Plan. The bank continues to reduce cross-shareholdings, with a cumulative reduction of 9.4 billion yen on a market value basis versus the end of March 2024, against a plan target of 10.0 billion yen.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















