
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Akita Bank does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials (its FY3/2026 results briefing materials), with figures transcribed as reported. The source document labels the period as the fiscal year ended March 31, 2026 (FY3/2026); on this site the most recently completed fiscal year is classified as FY2025.
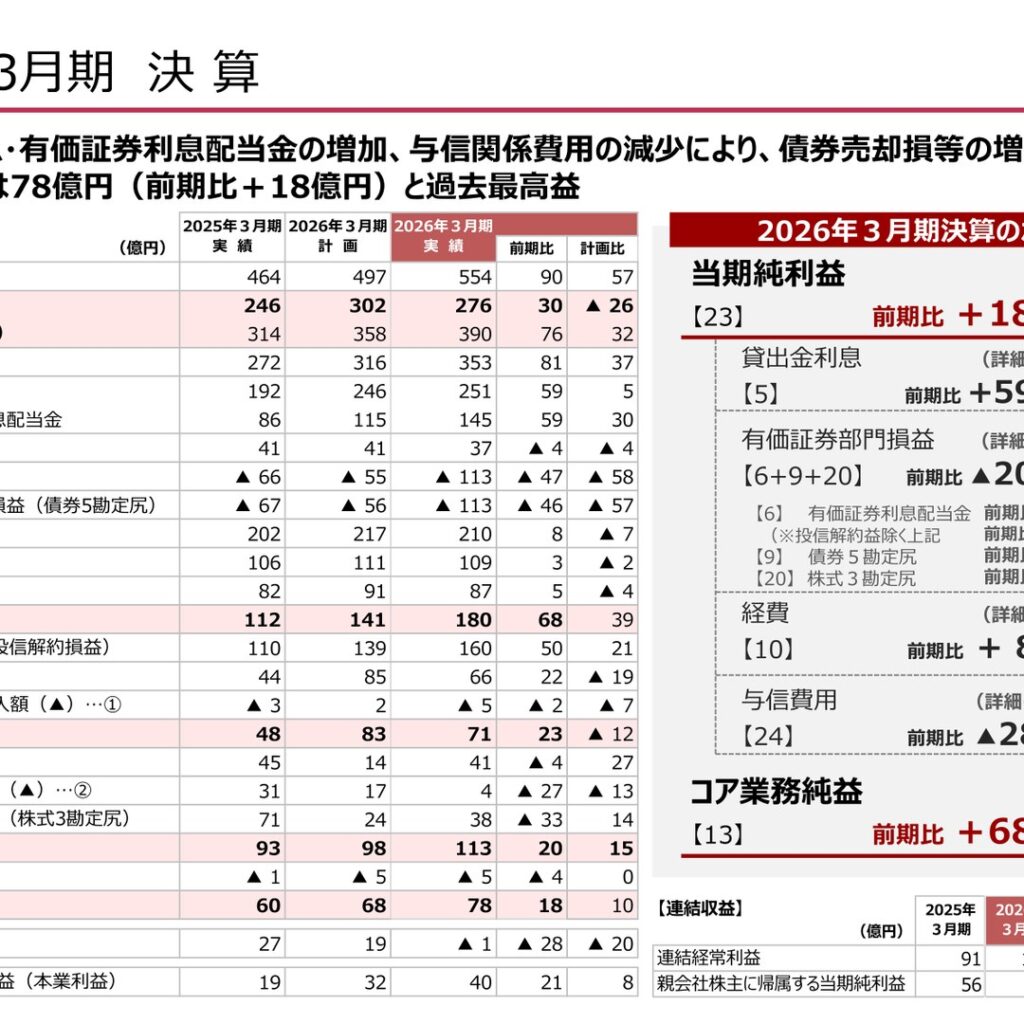
In its (non-consolidated) financial results for the fiscal year ended March 31, 2026, Akita Bank posted ordinary income of ¥55,400 million (up ¥9,000 million year on year) and core net business profit of ¥18,000 million (up ¥6,800 million). Growth in interest on loans and interest and dividends on securities, together with a decrease in credit-related expenses, offset an increase in losses on bond sales and other items, and net income reached ¥7,800 million (up ¥1,800 million), a record high. On a consolidated basis as well, both ordinary profit, at ¥11,200 million (up ¥2,100 million, +23.1%), and profit attributable to owners of parent, at ¥7,700 million (up ¥2,100 million, +37.5%), increased.
Results (FY3/2026 Actual)
On a non-consolidated basis, net interest income rose ¥8,100 million year on year to ¥35,300 million on higher interest on loans and interest and dividends on securities, while net fees and commissions decreased ¥400 million to ¥3,700 million, reflecting the carryover of business succession and M&A support deals into the next fiscal year and higher expenses such as loan insurance premiums. Expenses increased ¥800 million year on year to ¥21,000 million due to factors including employee wage increases and the maintenance and renewal of head-office and branch facilities, while the OHR (non-consolidated, core gross business profit basis) improved into the 50% range, coming to 53.89% (64.33% in the previous fiscal year). Credit costs came to -¥100 million (a net recovery), down ¥2,800 million year on year, reflecting the fading of a special factor booked in the previous fiscal year and a decline in the expected loss ratio.
| Item | FY3/2026 | FY3/2025 | Change |
|---|---|---|---|
| Ordinary income (Non-Consolidated) | ¥55,400 million | ¥46,400 million | +¥9,000 million |
| Net interest income (Non-Consolidated) | ¥35,300 million | ¥27,200 million | +¥8,100 million |
| Net fees and commissions (Non-Consolidated) | ¥3,700 million | ¥4,100 million | ▲¥400 million |
| Expenses (Non-Consolidated) | ¥21,000 million | ¥20,200 million | +¥800 million |
| Core net business profit (Non-Consolidated) | ¥18,000 million | ¥11,200 million | +¥6,800 million |
| Ordinary profit (Non-Consolidated) | ¥11,300 million | ¥9,300 million | +¥2,000 million |
| Net income (Non-Consolidated) | ¥7,800 million | ¥6,000 million | +¥1,800 million |
| Ordinary profit (Consolidated) | ¥11,200 million | ¥9,100 million | +¥2,100 million (+23.1%) |
| Profit attributable to owners of parent (Consolidated) | ¥7,700 million | ¥5,600 million | +¥2,100 million (+37.5%) |
Income and Expense Breakdown (Non-Consolidated)
Securities-related gains/losses came to a total of ¥7,000 million (down ¥2,000 million year on year), as an increase in interest and dividend income was outweighed by wider losses on bond sales and other items within gains/losses on Japanese government bonds and other bonds (bond-related five accounts) amid rising interest rates. The consolidated capital adequacy ratio fell 0.71 point year on year to 11.26%, reflecting an increase in risk assets associated with loan growth.
| Item | FY3/2026 | FY3/2025 | Change |
|---|---|---|---|
| Interest and dividends on securities | ¥14,500 million | ¥8,600 million | +¥5,900 million |
| Gains/losses on JGBs and other bonds (bond-related five accounts) | ▲¥11,300 million | ▲¥6,700 million | ▲¥4,600 million |
| Gains/losses on stocks (stock-related three accounts) | ¥3,800 million | ¥7,100 million | ▲¥3,300 million |
| Total securities-related gains/losses | ¥7,000 million | ¥9,000 million | ▲¥2,000 million |
| Personnel expenses | ¥10,900 million | ¥10,600 million | +¥300 million |
| Non-personnel expenses | ¥8,700 million | ¥8,200 million | +¥500 million |
| Credit costs | ▲¥100 million | ¥2,700 million | ▲¥2,800 million |
| Disposal of non-performing loans | ¥400 million | ¥3,100 million | ▲¥2,700 million |
Forecast for the Fiscal Year Ending March 2027
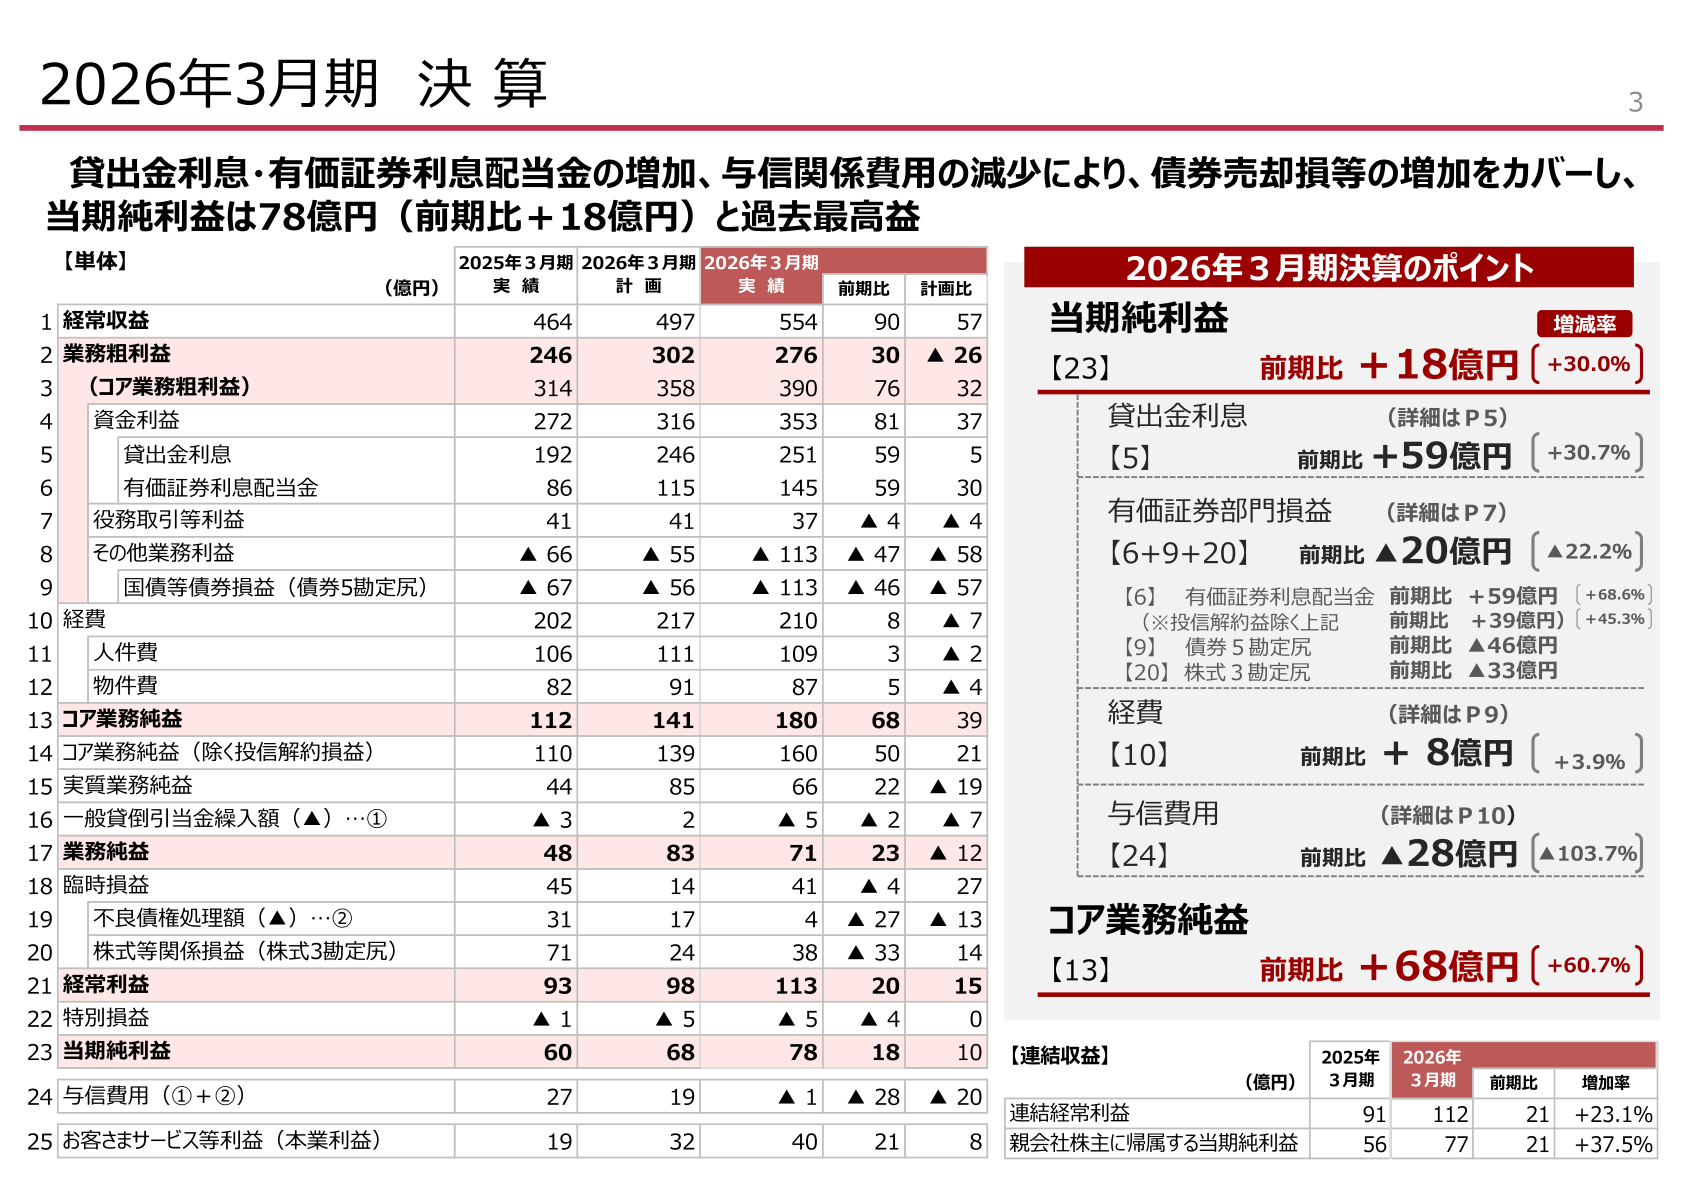
For the fiscal year ending March 31, 2027, Akita Bank forecasts non-consolidated ordinary profit of ¥13,100 million and net income of ¥8,500 million (up ¥700 million year on year). On a consolidated basis, the company expects ordinary profit of ¥13,100 million (up ¥1,900 million, +14.5%) and profit attributable to owners of parent of ¥8,500 million (up ¥900 million, +11.8%). Core net business profit is planned to decrease ¥2,500 million year on year to ¥15,500 million, reflecting the fading of gains from the cancellation of investment trusts and higher expenses, while net income is planned to increase as an improvement in gains/losses on Japanese government bonds and other bonds offsets higher expenses and credit costs. Credit costs are planned at ¥1,900 million, up ¥2,000 million year on year, reflecting the fading of a special factor from the previous fiscal year, among other reasons.
| Item | Forecast (FY3/2027) | Previous Year (FY3/2026 Actual) |
|---|---|---|
| Ordinary income (Non-Consolidated) | ¥55,000 million | ¥55,400 million |
| Core net business profit (Non-Consolidated) | ¥15,500 million | ¥18,000 million |
| Ordinary profit (Non-Consolidated) | ¥13,100 million | ¥11,300 million |
| Net income (Non-Consolidated) | ¥8,500 million | ¥7,800 million |
| Ordinary profit (Consolidated) | ¥13,100 million | ¥11,200 million |
| Profit attributable to owners of parent (Consolidated) | ¥8,500 million | ¥7,600 million |
| Credit costs (Non-Consolidated) | ¥1,900 million | ▲¥100 million |
Shareholder Returns
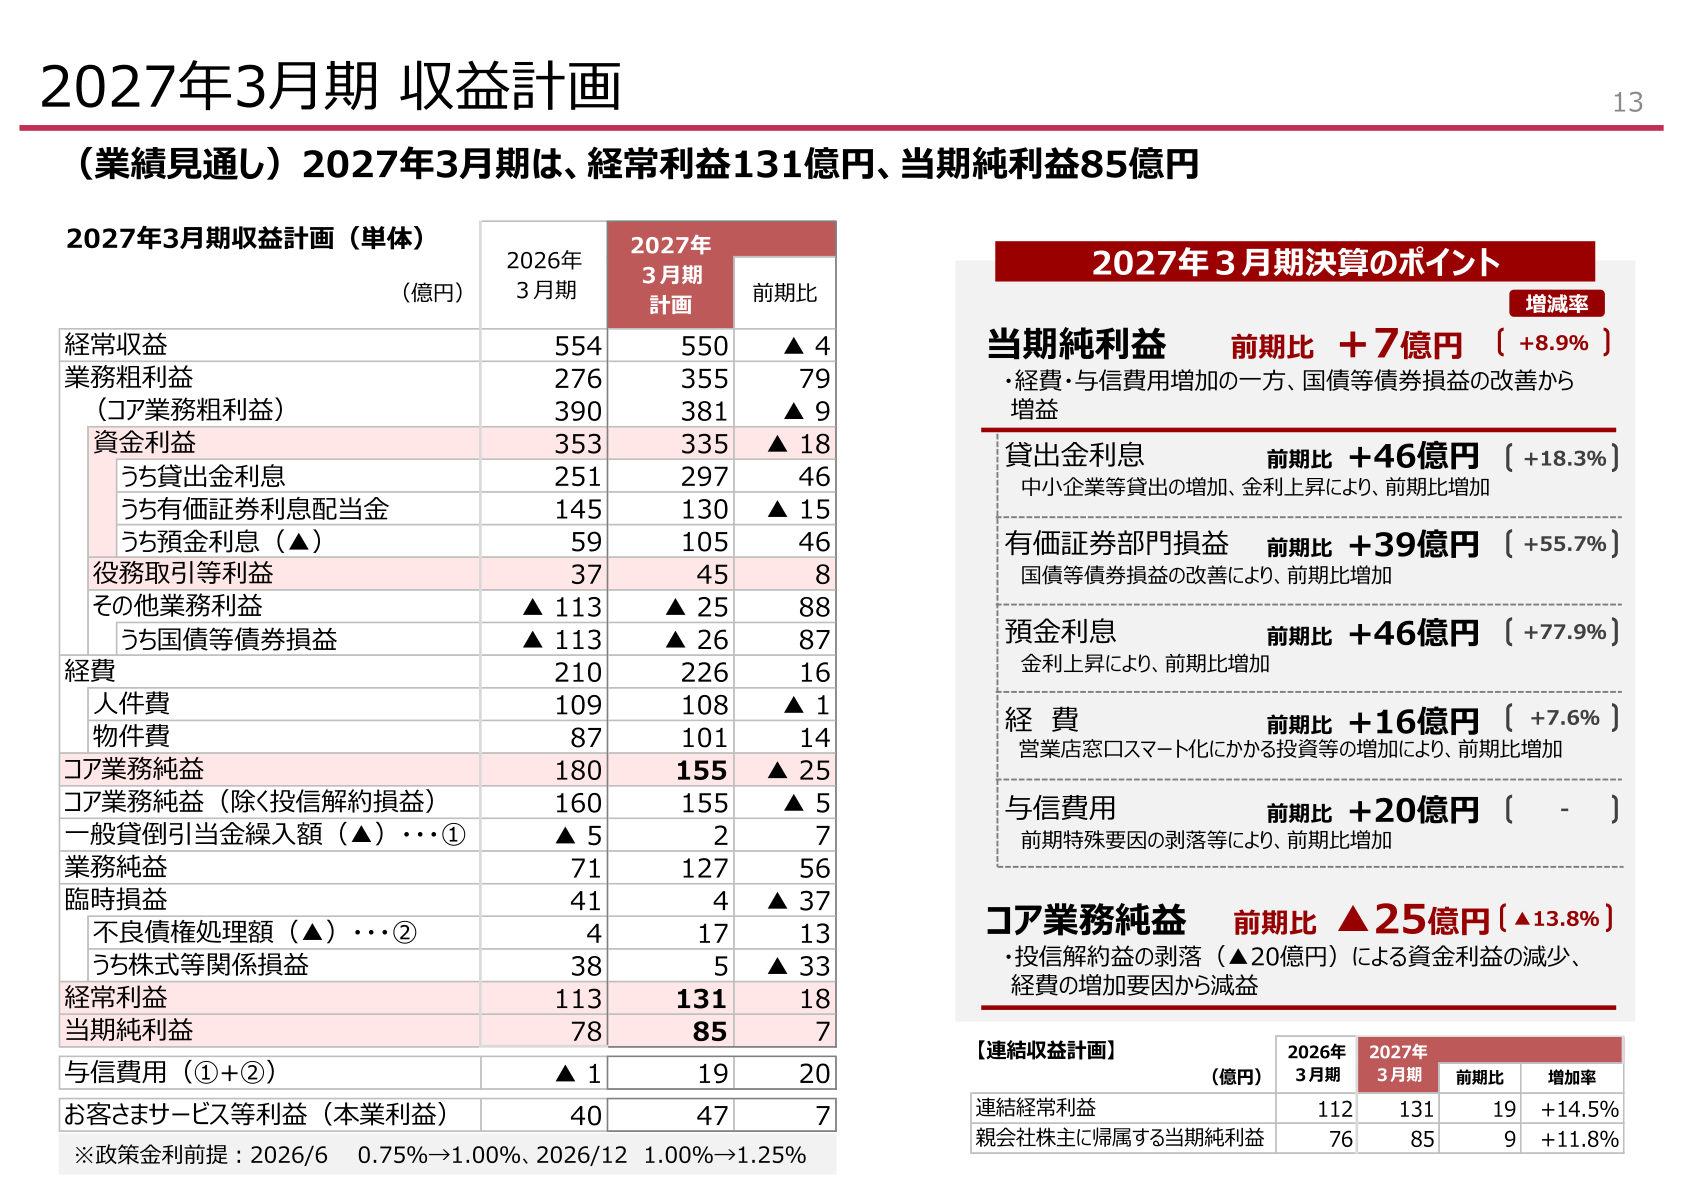
Given the public nature of banking, Akita Bank’s basic dividend policy is to maintain financial soundness and secure the retained earnings needed for the smooth supply of funds while maintaining a stable dividend, targeting a consolidated payout ratio of 40% or more of profit attributable to owners of parent and aiming to increase the dividend per share through profit growth. For the fiscal year ended March 31, 2026, the interim dividend was ¥75 (up ¥30 year on year) and the year-end dividend was ¥100 (up ¥40), bringing the consolidated payout ratio to 40.4% (37.0% in the previous fiscal year). For the fiscal year ending March 31, 2027, the company plans an interim and a year-end dividend of ¥100 each.
| Item | FY3/2026 | FY3/2025 | Change |
|---|---|---|---|
| Interim dividend | ¥75 | ¥45 | +¥30 |
| Year-end dividend | ¥100 | ¥60 | +¥40 |
| Payout ratio (Consolidated) | 40.4% | 37.0% | — |
Medium-Term Management Plan
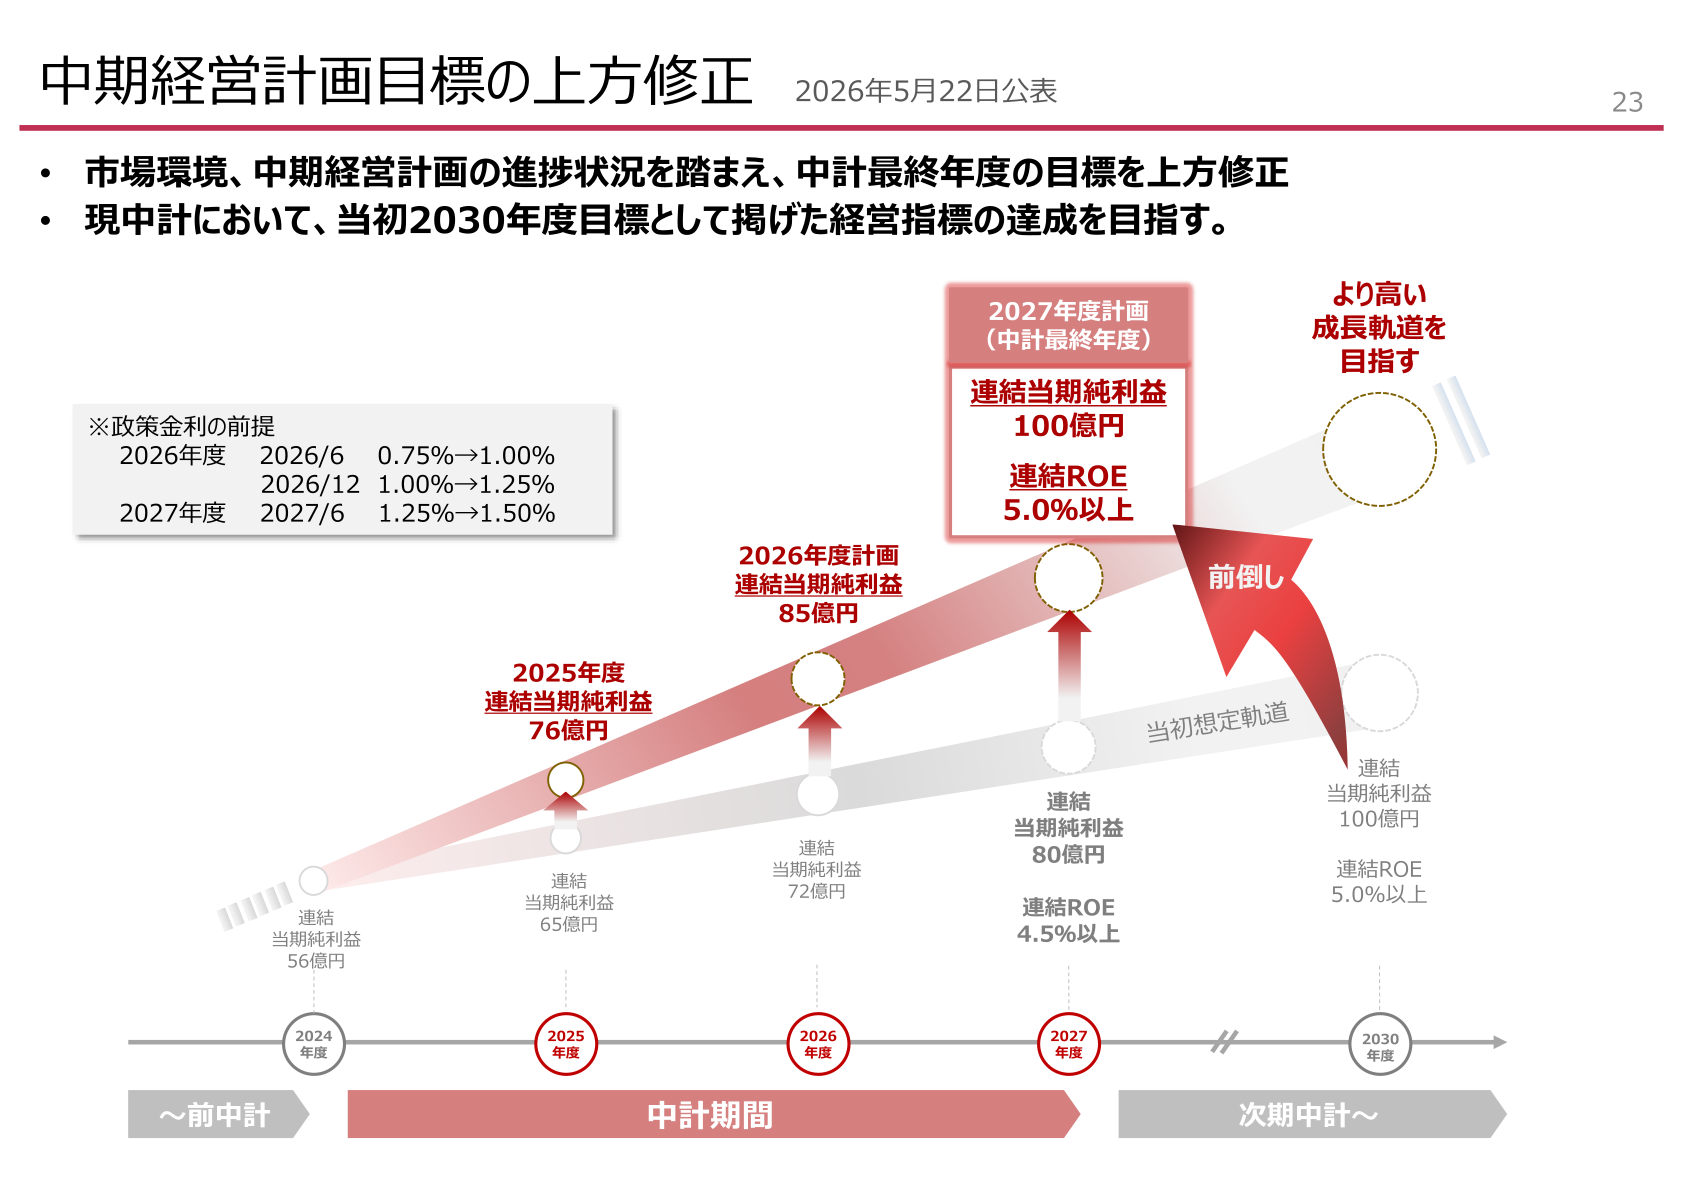
Under the second-phase medium-term management plan (fiscal 2025 through fiscal 2027), the company revised upward its targets for the final year of the plan (fiscal 2027) from the figures announced on May 22, 2026. The revised fiscal 2027 targets are net income (consolidated) of ¥10,000 million or more, ROE (consolidated) of 5.0% or more, a capital adequacy ratio (consolidated) of around 11%, and an OHR (non-consolidated, core gross business profit basis) of below 60% — the same levels previously set out as the target for fiscal 2030. The company states that achievement of the plan’s original final-year target of net income of ¥8,000 million or more is now within sight for fiscal 2026. In addition, the Bank has reduced its cross-shareholdings (listed shares) by ¥22,000 million in market value and 42 issues compared with the end of March 2017, and plans to continue the reduction going forward.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















