
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: The Chiba Kogyo Bank does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials, with figures transcribed as reported. As a bank, the company reports Japanese GAAP bank-specific line items such as gross operating profit, core net business profit, and actual credit cost; these are used here as reported, without restating them to general corporate P&L terms. The source labels periods by Japanese fiscal year-end (e.g., “2026年3月期” = the fiscal year ended March 31, 2026); in this site’s FY-naming convention, that period is labeled “FY2025,” the fiscal year ended March 31, 2025 is labeled “FY2024,” and the fiscal year ending March 31, 2027 (forecast) is labeled “FY2026.” Unless noted otherwise, monetary figures in the tables below are shown in units of ¥100 million (oku yen), matching the source’s own tables; figures in the running text are expressed in billion/million yen for readability, without changing the reported digits.
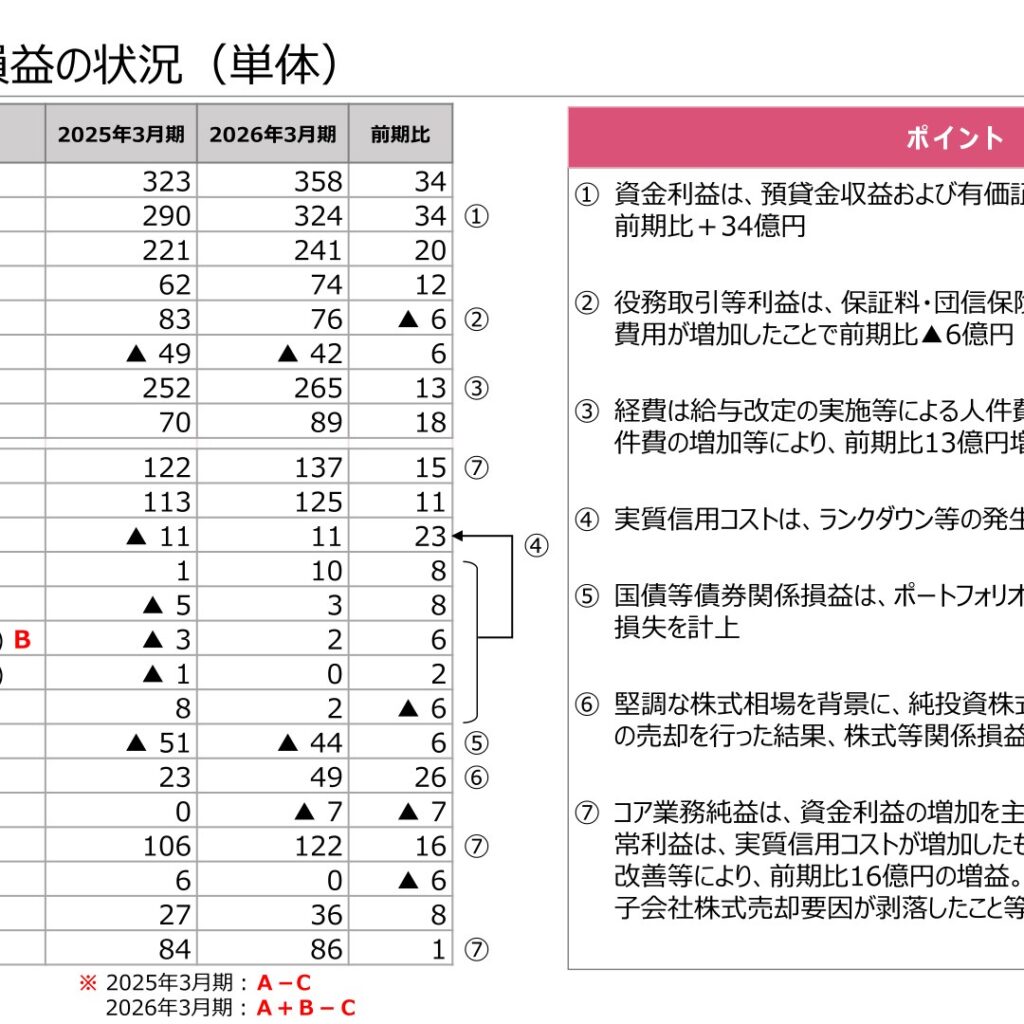
The Chiba Kogyo Bank’s non-consolidated results for the fiscal year ended March 31, 2026 showed higher profit, driven mainly by an increase in net interest income: gross operating profit of 35.8 billion yen (+3.4 billion yen year on year), core net business profit of 13.7 billion yen (+1.5 billion yen), ordinary profit of 12.2 billion yen (+1.6 billion yen), and net income of 8.6 billion yen (+0.1 billion yen). Although the actual credit cost increased, ordinary profit rose 1.6 billion yen year on year on an improvement in gains and losses related to securities, among other factors. At the same time, on March 25, 2026, the bank announced that it had reached a final agreement on a business integration with The Chiba Bank, Ltd., and also set out a plan to establish a joint holding company effective April 1, 2027.
Non-Consolidated Results (FY2025 Actual, Fiscal Year Ended March 31, 2026)
On a non-consolidated basis, gross operating profit was 35.8 billion yen, driven mainly by a 3.4 billion yen year-on-year increase in net interest income on higher deposit-and-lending income and higher interest and dividends on securities. Expenses increased 1.3 billion yen year on year to 26.5 billion yen, due to higher personnel expenses from the salary revision and higher non-personnel expenses from investment, among other factors. Net business profit was 8.9 billion yen (+1.8 billion yen year on year), and core net business profit was 13.7 billion yen (+1.5 billion yen). The actual credit cost was 1.1 billion yen, reflecting rank-downs and other factors. Gains/losses on bonds such as government bonds were a loss of 4.4 billion yen due to portfolio rebalancing and other factors, while gains/losses on stocks, etc., were a gain of 4.9 billion yen against a backdrop of firm stock-market conditions; as a result, ordinary profit was 12.2 billion yen (+1.6 billion yen), and net income was 8.6 billion yen (+0.1 billion yen), as the factor of the sale of subsidiary shares recorded in the previous fiscal year fell away, among other factors.
| Item | FY2024 | FY2025 | Change |
|---|---|---|---|
| Gross operating profit | 323 | 358 | 34 |
| Net interest income | 290 | 324 | 34 |
| Net fees and commissions | 83 | 76 | -6 |
| Net other operating income | -49 | -42 | 6 |
| Expenses | 252 | 265 | 13 |
| Net business profit | 70 | 89 | 18 |
| Core net business profit | 122 | 137 | 15 |
| Actual credit cost | -11 | 11 | 23 |
| Gains/losses on bonds | -51 | -44 | 6 |
| Gains/losses on stocks, etc. | 23 | 49 | 26 |
| Ordinary profit | 106 | 122 | 16 |
| Extraordinary gains/losses | 6 | 0 | -6 |
| Total income taxes | 27 | 36 | 8 |
| Net income | 84 | 86 | 1 |
Breakdown of Net Interest Income and Fee Income (Non-Consolidated)
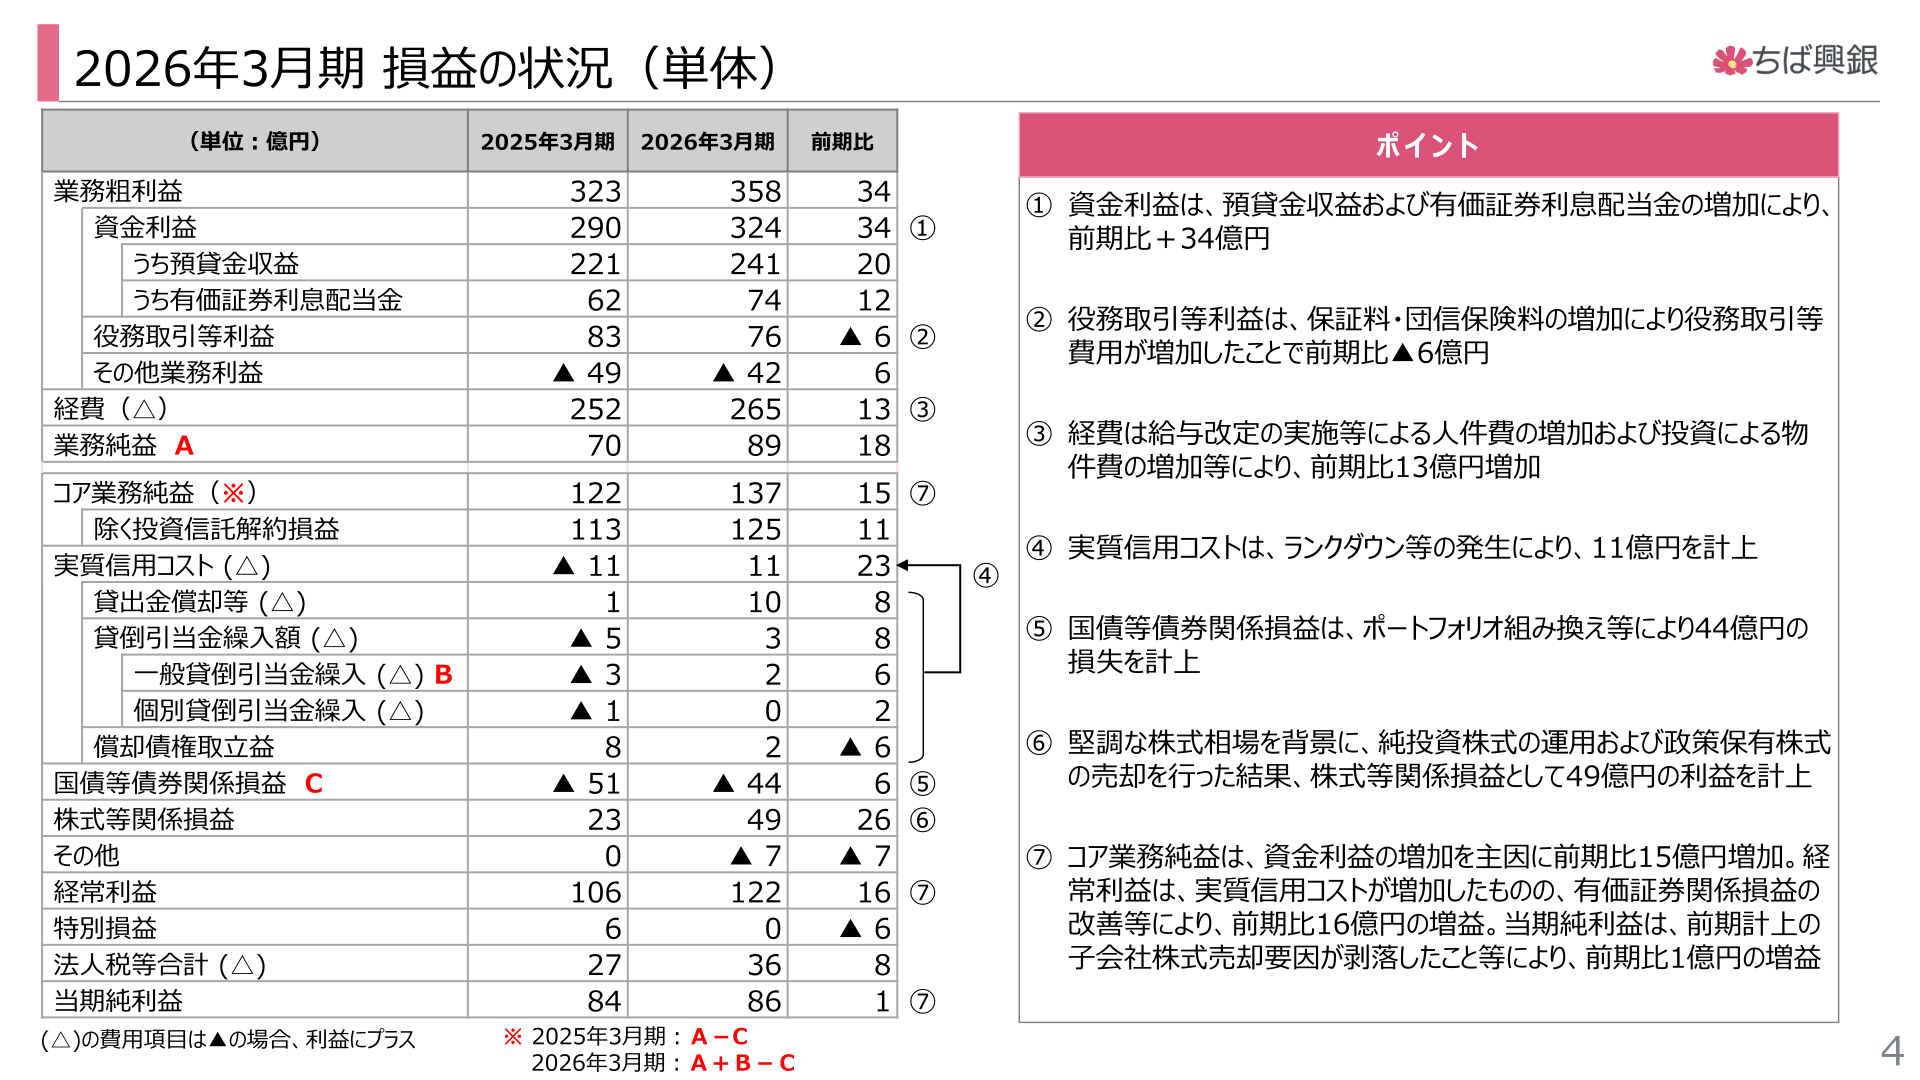
Net interest income: interest on loans rose 6.50 billion yen year on year, mainly reflecting a rise in the yen loan yield that tracked the rise in the policy interest rate, while interest on deposits also increased 4.49 billion yen year on year; as a result, net interest income overall increased 3.4 billion yen year on year to 32.4 billion yen. Interest and dividends on securities were 7.4 billion yen, up 1.24 billion yen year on year. Net fees and commissions were 7.64 billion yen, down 0.65 billion yen year on year: investment trust fees and corporate-related fees increased, but fees and commissions expenses increased 0.66 billion yen year on year on higher guarantee fees and group credit life insurance premiums.
| Item | FY2025 | Change |
|---|---|---|
| Net interest income | 324 | 34 |
| Deposit-and-lending income | 241 | 20 |
| Interest on loans | 305 | 65 |
| Interest on deposits | 63 | 44 |
| Interest and dividends on securities | 74 | 12 |
| of which, gains on redemption/cancellation of investment trusts | 11 | 3 |
| Other | 8 | 1 |
| Item | FY2025 | Change |
|---|---|---|
| Net fees and commissions | 76.4 | -6.5 |
| Fees and commissions income | 127.0 | 0.1 |
| of which, investment trust fees | 27.9 | 3.7 |
| of which, insurance sales commissions | 8.2 | -5.2 |
| of which, corporate-related fees | 55.2 | 1.7 |
| Fees and commissions expenses | 50.5 | 6.6 |
| of which, guarantee fees and group credit life insurance premiums | 43.3 | 6.6 |
FY2026 Forecast (Non-Consolidated, Fiscal Year Ending March 31, 2027)
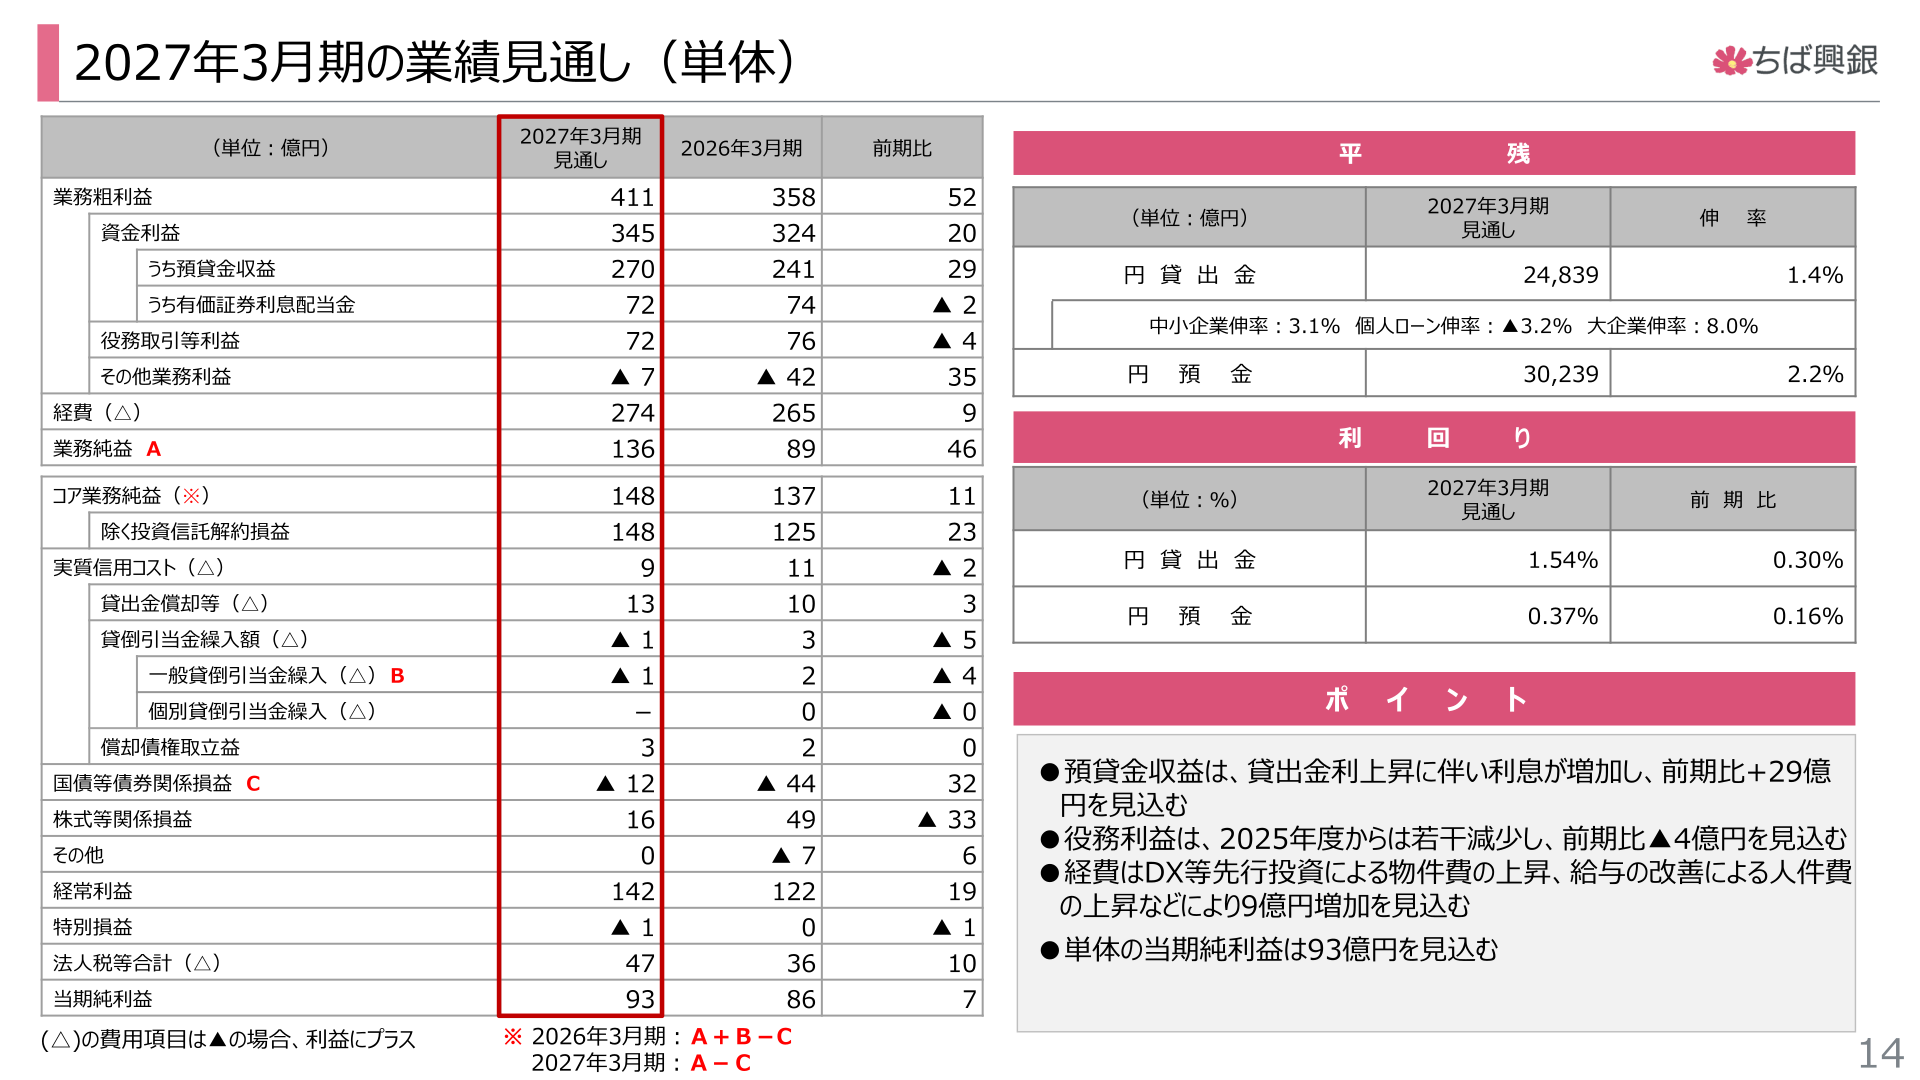
The non-consolidated earnings forecast for the fiscal year ending March 31, 2027 calls for gross operating profit of 41.1 billion yen (+5.2 billion yen year on year), core net business profit of 14.8 billion yen (+1.1 billion yen), ordinary profit of 14.2 billion yen (+1.9 billion yen), and net income of 9.3 billion yen (+0.7 billion yen). Deposit-and-lending income is expected to increase 2.9 billion yen year on year on higher interest income accompanying the rise in the loan interest rate, while fee income is expected to decrease 0.4 billion yen year on year. Expenses are expected to increase 0.9 billion yen, due to a rise in non-personnel expenses from upfront investment in DX and other areas and a rise in personnel expenses from the salary improvement, among other factors.
| Item | FY2026 (Forecast) | FY2025 (Actual) | Change |
|---|---|---|---|
| Gross operating profit | 411 | 358 | 52 |
| Net interest income | 345 | 324 | 20 |
| Net fees and commissions | 72 | 76 | -4 |
| Expenses | 274 | 265 | 9 |
| Net business profit | 136 | 89 | 46 |
| Core net business profit | 148 | 137 | 11 |
| Ordinary profit | 142 | 122 | 19 |
| Net income | 93 | 86 | 7 |
Shareholder Returns
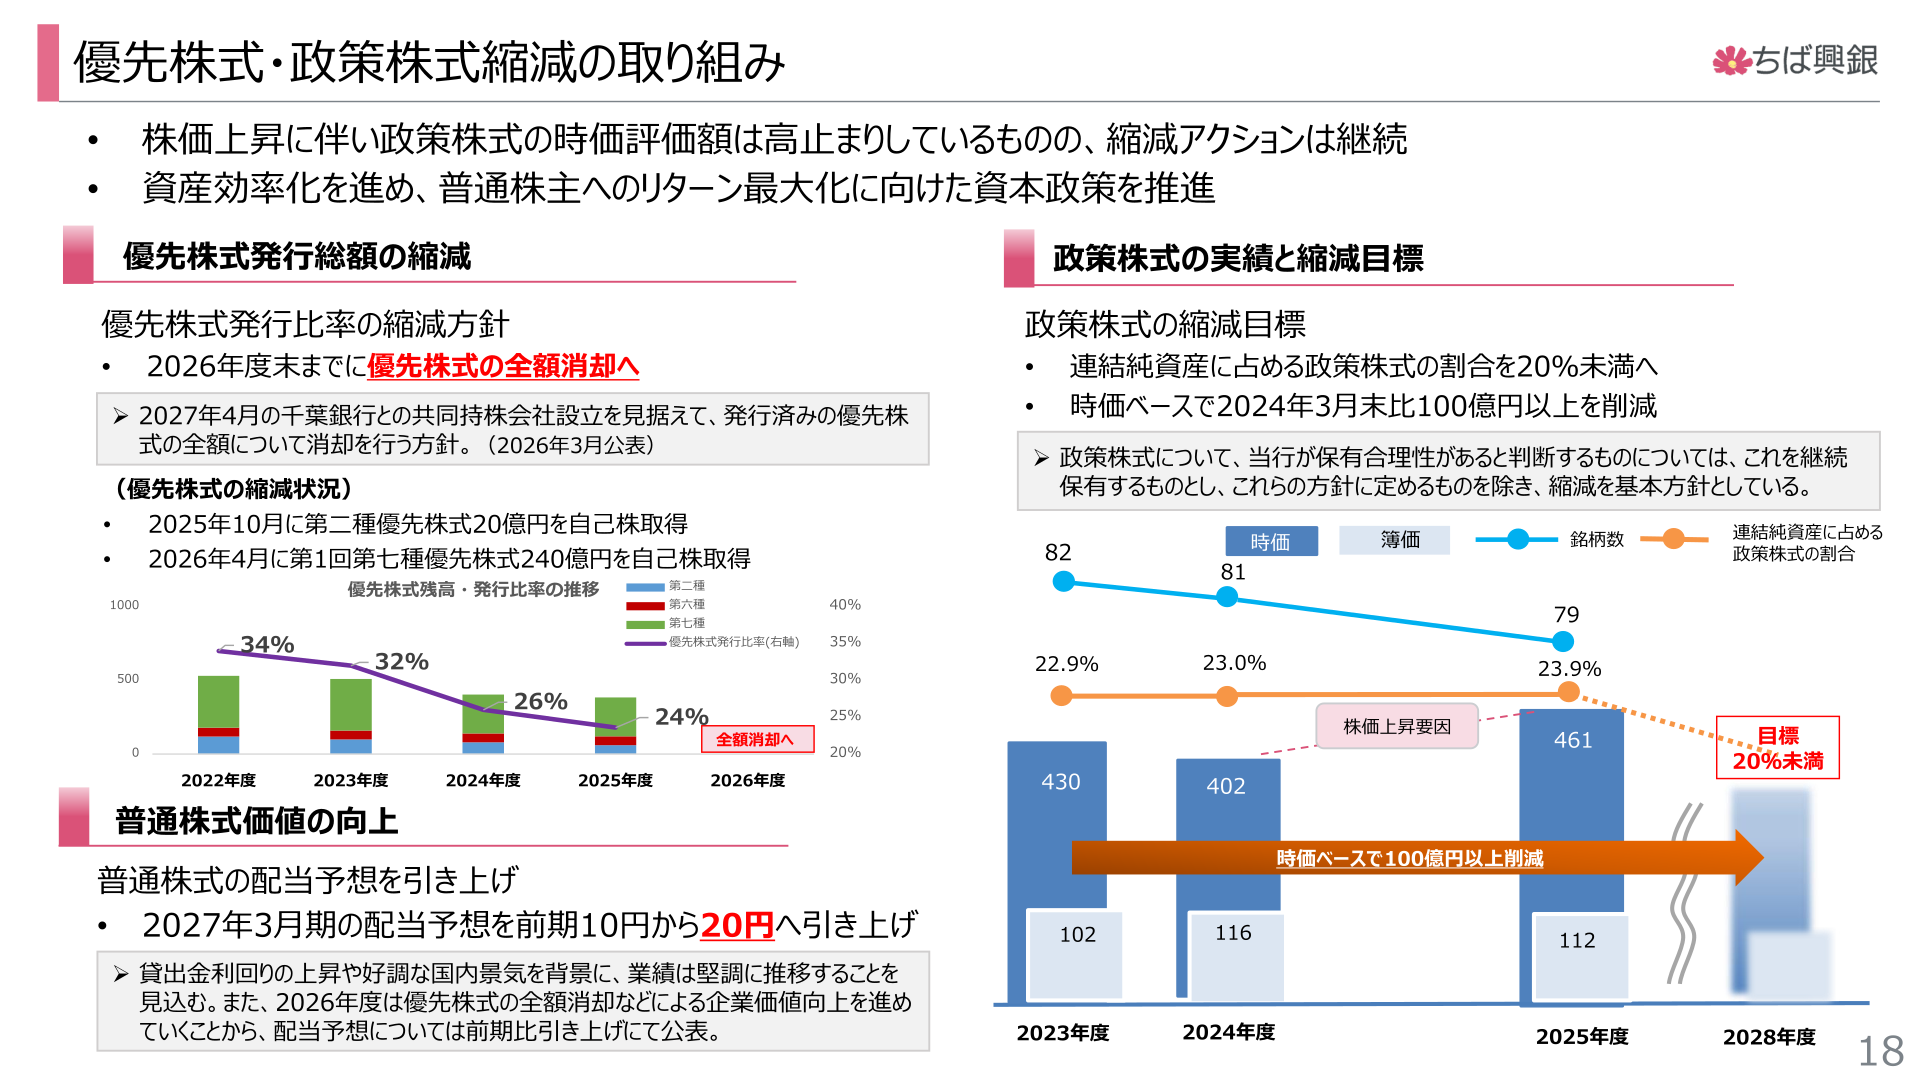
The annual dividend per share was 10.0 yen in both the fiscal year ended March 31, 2025 and the fiscal year ended March 31, 2026, and the bank announced a policy of raising the dividend to 20.0 yen for the fiscal year ending March 31, 2027 (forecast). On dividends, the bank states that it will work to build up retained earnings and strengthen its capital base while implementing stable, sustained dividends. In addition, under a policy of aiming to fully retire its preferred shares by the end of fiscal 2026, the bank acquired 2.0 billion yen of Class 2 preferred shares as treasury stock in October 2025, and 24.0 billion yen of Series 7, No. 1 preferred shares as treasury stock in April 2026. On policy (cross-)shareholdings as well, the bank is proceeding with reductions, targeting a ratio of such shareholdings to consolidated net assets of below 20%, and a reduction on a market-value basis of 10.0 billion yen or more compared with the end of March 2024.
Medium-Term Management Plan and Business Integration with The Chiba Bank
Under the medium-term management plan “Shiawase Design: Kizuna Project 2028” (fiscal 2025-fiscal 2027), the fiscal 2025 results for the plan’s management indicators were: consolidated net income for the period of 8.6 billion yen (+1.2 billion yen year on year; a fiscal 2027 target level of 11.0 billion yen or more), non-consolidated core OHR of 65.9% (-1.5 percentage points year on year; a target level of below 65%), and a consolidated capital adequacy ratio of 9.1% (± 0 percentage points year on year; a target level of 8.5% or above), among other indicators. In addition, on March 25, 2026, the bank announced that it had reached a final agreement on a business integration with The Chiba Bank, Ltd., under which the two banks plan to establish a joint holding company effective April 1, 2027 through a joint share transfer (the shares of both banks are scheduled to be delisted on March 30, 2027). The bank expects the synergy effects of the integration, on a net-business-profit basis, to be 4.0-6.0 billion yen in fiscal 2028 and 12.0-16.0 billion yen in fiscal 2031.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















