
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
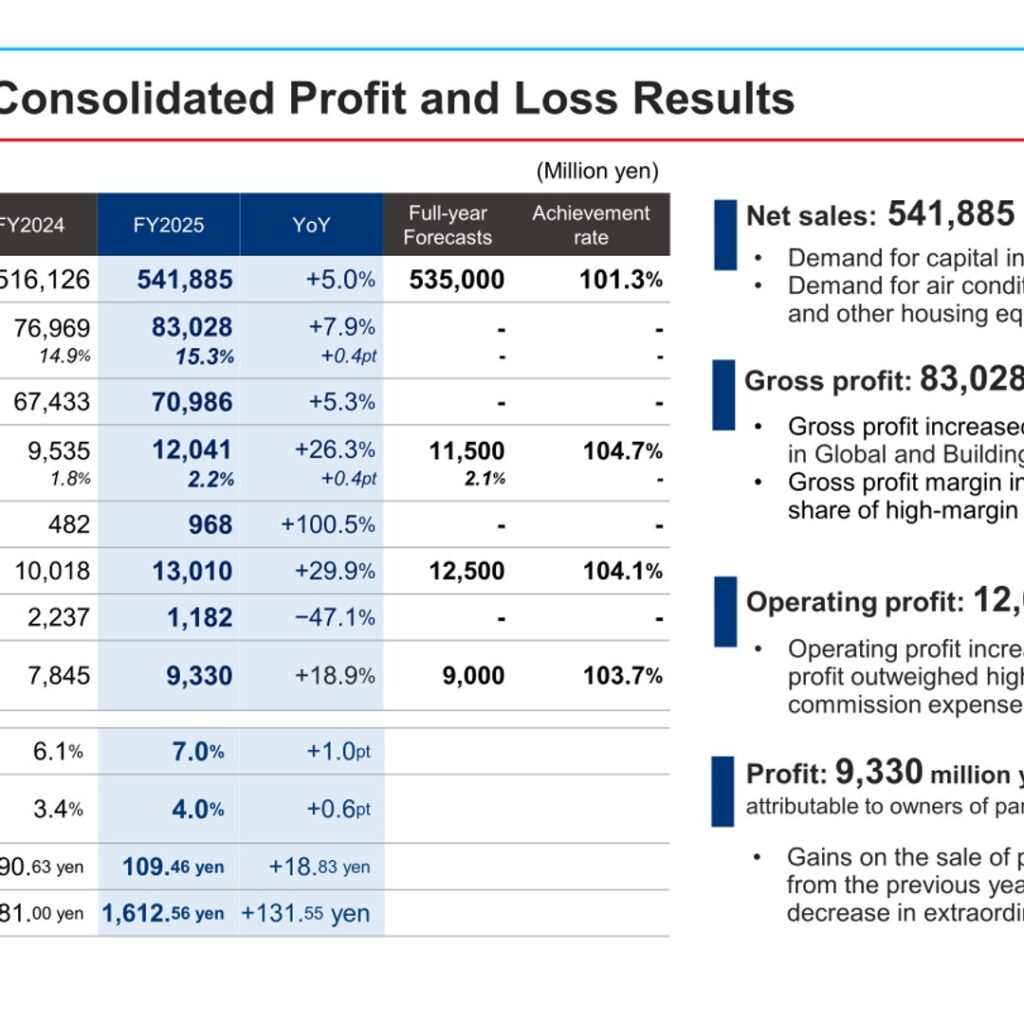
Yamazen Corporation reported record consolidated net sales of 541,885 million yen for FY2025 (the fiscal year ended March 2026), up 5.0% year on year, as capital investment demand overseas increased and demand for air conditioning, water heating equipment and other housing equipment remained strong. Gross profit rose 7.9% to 83,028 million yen and the gross profit margin improved to 15.3% on an increased share of high-margin Global and Home Products sales. Operating profit increased 26.3% to 12,041 million yen, and profit attributable to owners of parent rose 18.9% to 9,330 million yen. Results exceeded the company’s full-year forecasts across all major line items, with net sales at 101.3% of forecast, operating profit at 104.7%, ordinary profit at 104.1% and profit attributable to owners of parent at 103.7%.
Consolidated Results (Full-Year Actual)
Net sales increased as capital investment demand overseas grew and demand for air conditioning, water heating equipment and other housing equipment remained strong. Gross profit increased due to sales growth mainly in the Global and Building Materials businesses, and the gross profit margin rose on an increased share of high-margin Global and Home Products sales. Operating profit increased as the rise in gross profit outweighed higher personnel expenses and commission expenses. Extraordinary gain decreased as gains on the sale of policy shareholdings fell from the previous year, resulting in a reactionary decrease in extraordinary gain.
| Item | FY2024 | FY2025 | YoY |
|---|---|---|---|
| Net sales | 516,126 | 541,885 | +5.0% |
| Gross profit (margin) | 76,969 (14.9%) | 83,028 (15.3%) | +7.9% (+0.4pt) |
| SG&A expenses | 67,433 | 70,986 | +5.3% |
| Operating profit (margin) | 9,535 (1.8%) | 12,041 (2.2%) | +26.3% (+0.4pt) |
| Non-operating profit/loss | 482 | 968 | +100.5% |
| Ordinary profit | 10,018 | 13,010 | +29.9% |
| Extraordinary gain/loss | 2,237 | 1,182 | -47.1% |
| Profit attributable to owners of parent | 7,845 | 9,330 | +18.9% |
| ROE (Return on Equity) | 6.1% | 7.0% | +1.0pt |
| ROA (Ratio of ordinary profit to total assets) | 3.4% | 4.0% | +0.6pt |
| EPS (Earnings per share) | 90.63 yen | 109.46 yen | +18.83 yen |
| BPS (Book value per share) | 1,481.00 yen | 1,612.56 yen | +131.55 yen |
Segment Results
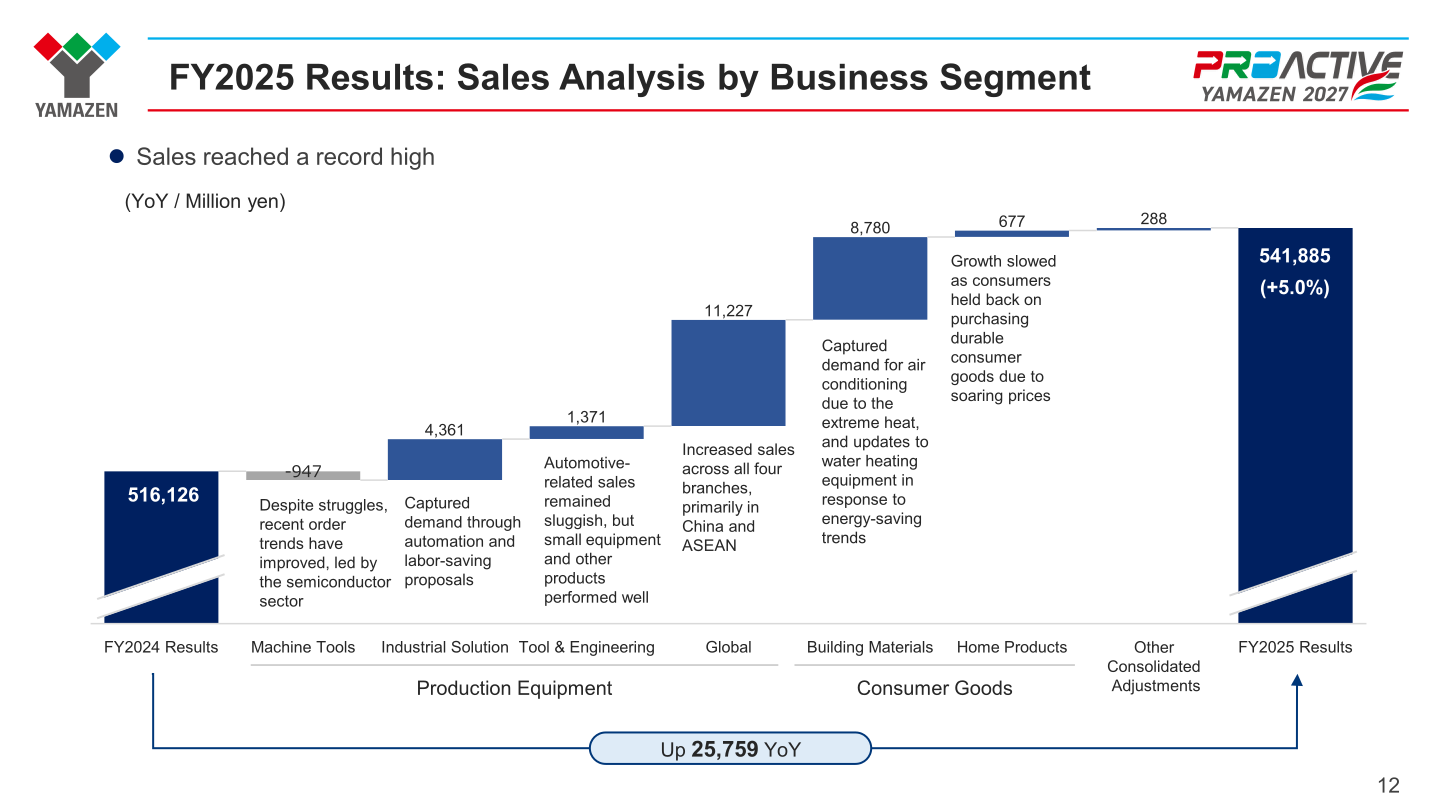
By segment, Global net sales rose 13.1% as the company captured demand related to aerospace, power generation and data centers in North America and to AI and semiconductors in Taiwan, together with continued capital investment by domestic-demand-oriented companies in China and ASEAN. Industrial Solution net sales grew 4.6% on high needs for automation and labor-saving solutions due to labor shortages, while Machine Tools net sales declined 1.3% as capital investment appetite among small and midsize manufacturers remained weak, although recent order trends have improved, led by the semiconductor sector. In Consumer Goods, Building Materials net sales rose 11.2% as sales of air conditioning equipment were strong due to extreme heat and replacement demand for water heaters and other energy-saving products remained firm, while Home Products net sales edged up 0.7% as growth slowed on consumers holding back purchases of durable consumer goods amid soaring prices.
| Segment | FY2024 | FY2025 | YoY |
|---|---|---|---|
| Net sales – Machine Tools | 72,217 | 71,270 | -1.3% |
| Net sales – Industrial Solution | 95,049 | 99,411 | +4.6% |
| Net sales – Tool & Engineering | 80,204 | 81,575 | +1.7% |
| Net sales – Domestic Total | 247,471 | 252,257 | +1.9% |
| Net sales – Global | 85,733 | 96,961 | +13.1% |
| Net sales – Production Equipment Total | 333,205 | 349,218 | +4.8% |
| Segment profit – Production Equipment Total (margin) | 8,291 (2.5%) | 10,423 (3.0%) | +25.7% (+0.5pt) |
| Net sales – Building Materials | 78,623 | 87,403 | +11.2% |
| Segment profit – Building Materials (margin) | 3,192 (4.1%) | 3,662 (4.2%) | +14.7% (+0.1pt) |
| Net sales – Home Products | 100,883 | 101,560 | +0.7% |
| Segment profit – Home Products (margin) | 4,449 (4.4%) | 4,810 (4.7%) | +8.1% (+0.3pt) |
| Net sales – Consumer Goods Total | 179,506 | 188,964 | +5.3% |
| Segment profit – Consumer Goods Total (margin) | 7,641 (4.3%) | 8,473 (4.5%) | +10.9% (+0.2pt) |
| Net sales – Other | 3,414 | 3,702 | +8.4% |
| Segment profit – Other | -6,396 | -6,854 | – |
| Net sales – Consolidated | 516,126 | 541,885 | +5.0% |
| Segment profit – Consolidated (margin) | 9,535 (1.8%) | 12,041 (2.2%) | +26.3% (+0.4pt) |
FY2026 Forecast
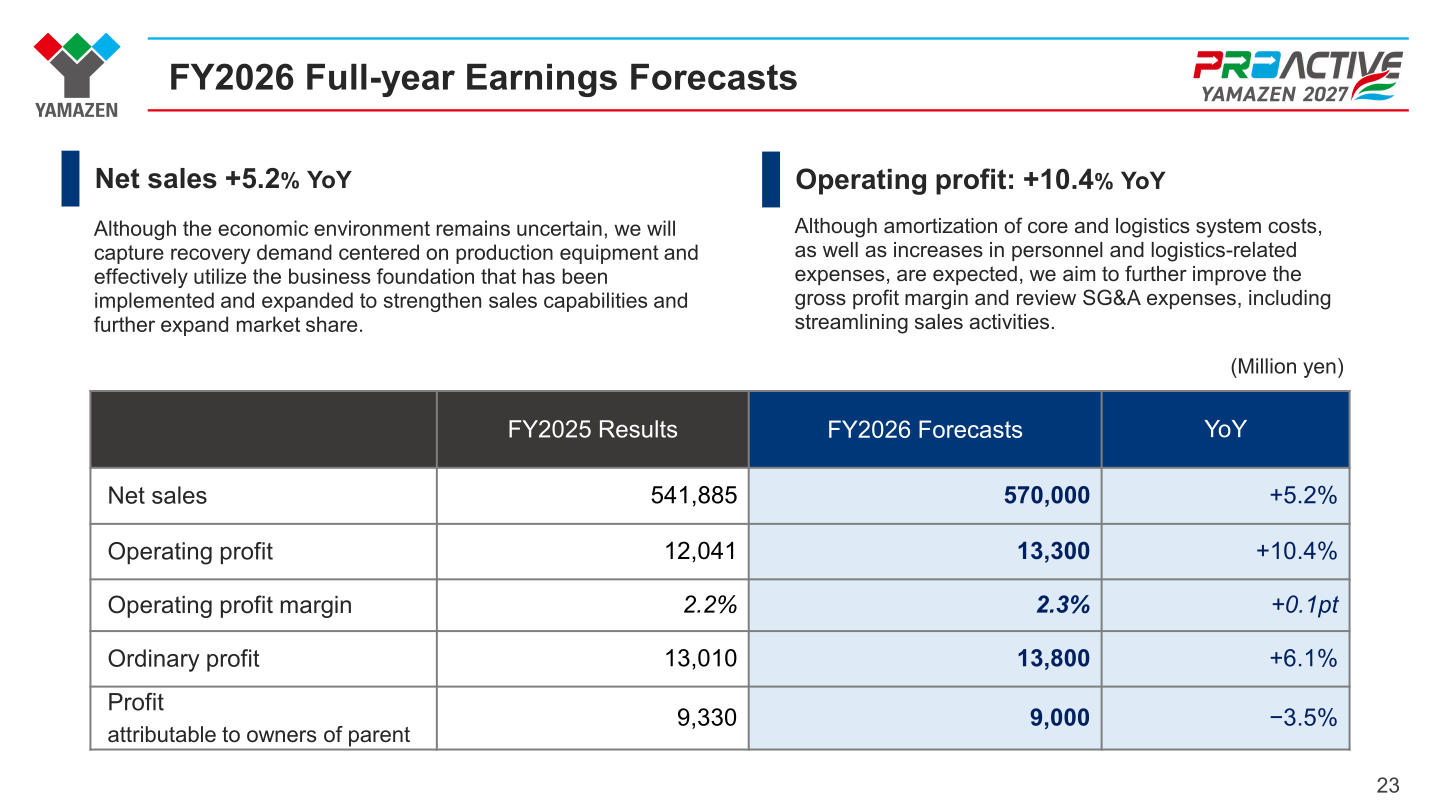
For FY2026, Yamazen forecasts net sales growth of 5.2% year on year, aiming to capture recovery demand centered on production equipment while utilizing its expanded business foundation to strengthen sales capabilities and further expand market share. Operating profit is forecast to rise 10.4%; although amortization of core and logistics system costs and higher personnel and logistics-related expenses are expected, the company aims to further improve the gross profit margin and review SG&A expenses, including streamlining sales activities. Profit attributable to owners of parent is forecast to decline 3.5% to 9,000 million yen.
| Item | FY2025 Results | FY2026 Forecast | YoY |
|---|---|---|---|
| Net sales | 541,885 | 570,000 | +5.2% |
| Operating profit (margin) | 12,041 (2.2%) | 13,300 (2.3%) | +10.4% (+0.1pt) |
| Ordinary profit | 13,010 | 13,800 | +6.1% |
| Profit attributable to owners of parent | 9,330 | 9,000 | -3.5% |
Shareholder Returns
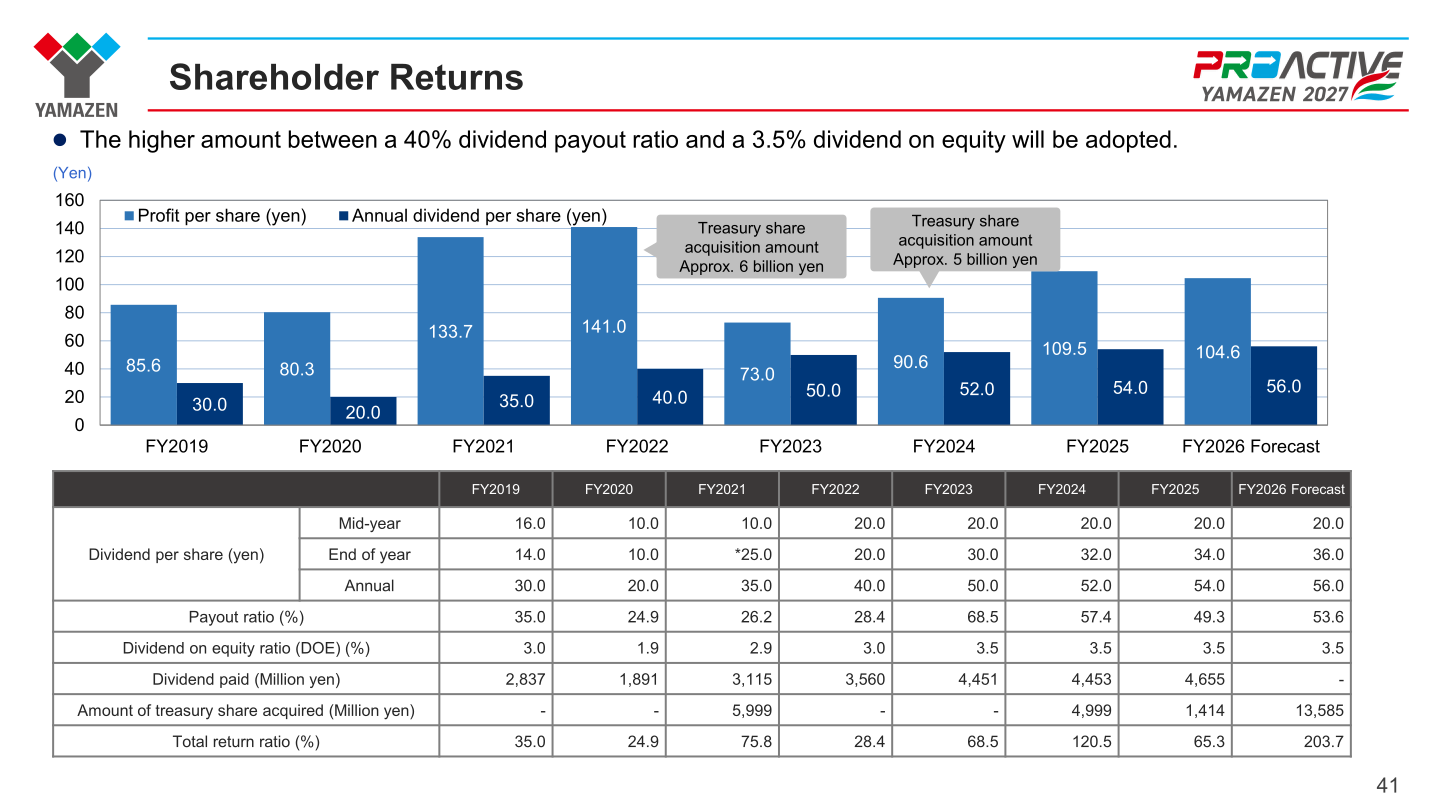
Yamazen’s dividend policy is to adopt the higher amount between a 40% dividend payout ratio and a 3.5% dividend on equity ratio (DOE). The FY2025 annual dividend per share was 54.0 yen (mid-year 20.0 yen, year-end 34.0 yen), up from 52.0 yen in FY2024, for a payout ratio of 49.3% and a DOE of 3.5%. The company also acquired 1,414 million yen of treasury shares in FY2025, for a total return ratio of 65.3%. For FY2026, the company forecasts an annual dividend of 56.0 yen per share (mid-year 20.0 yen, year-end 36.0 yen) and plans to acquire approximately 13,585 million yen of treasury shares, lifting the forecast total return ratio to 203.7%. Separately, the company introduced a new shareholder benefit program, under which shareholders of record as of March 31, 2026 holding 100-299 shares receive a 3,000 yen coupon and those holding 300 shares or more receive a 5,000 yen coupon, usable on the company’s Yamazen Bizcom e-commerce site.
| Item | FY2024 | FY2025 | FY2026 Forecast |
|---|---|---|---|
| Dividend per share – Mid-year | 20.0 yen | 20.0 yen | 20.0 yen |
| Dividend per share – End of year | 32.0 yen | 34.0 yen | 36.0 yen |
| Dividend per share – Annual | 52.0 yen | 54.0 yen | 56.0 yen |
| Payout ratio | 57.4% | 49.3% | 53.6% |
| Dividend on equity ratio (DOE) | 3.5% | 3.5% | 3.5% |
| Amount of treasury shares acquired | 4,999 million yen | 1,414 million yen | 13,585 million yen |
| Total return ratio | 120.5% | 65.3% | 203.7% |
Medium-Term Plan / Topics
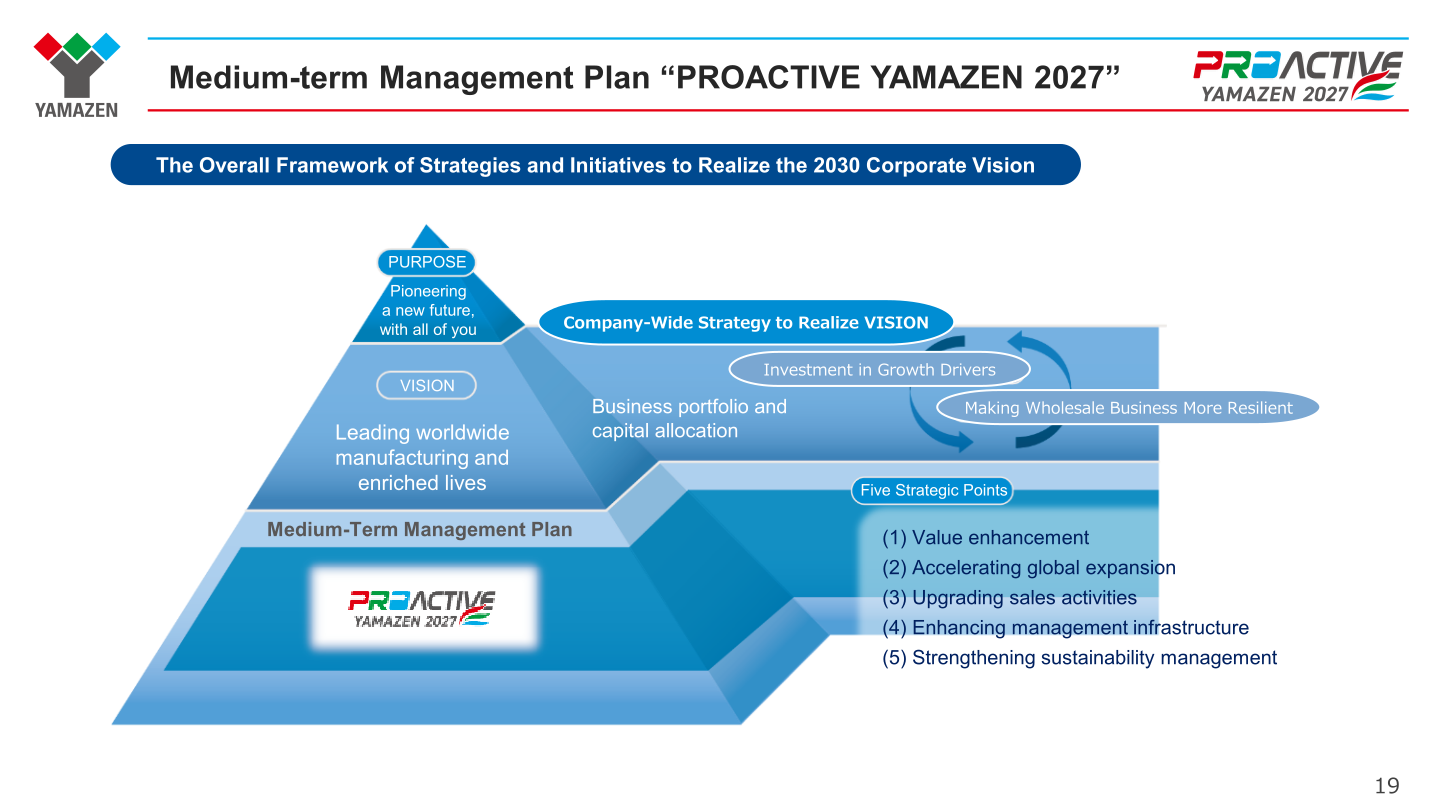
As part of its initiatives to further enhance corporate value under the medium-term management plan “PROACTIVE YAMAZEN 2027” (announced in May 2025), Yamazen entered into a strategic partnership with Advantage Partners (“AP”) and arranged financing through the issuance of convertible bonds with share subscription rights. The bonds were contracted on February 12, 2026 and issued on March 3, 2026, with an aggregate principal amount of 28.0 billion yen (27,979,000,000 yen), a 0.0% interest rate and a 5-year maturity. The initial conversion price was set at 1,543 yen (105% of the average closing price over the three months prior to the issuance resolution date), with a reference share price for conversion restrictions of 1,851 yen; a par-value cash settlement provision was included with the aim of limiting shareholder dilution. Over the six cumulative fiscal years from FY2025 to FY2030, the company plans cash inflows of more than 100 billion yen in cumulative operating cash flow plus 28 billion yen from the proposed CB and 25 billion yen of additional borrowings, SB, CB and PO, to be allocated to cash outflows of 50 billion or more for M&A, 25 billion yen for capital investments, and 50 billion yen for shareholder returns (including the acquisition of treasury shares totaling 15 billion yen), in addition to 28 billion yen for the par-value cash settlement of the proposed CB. For the final year of the medium-term plan (FY2027), the company targets an operating profit margin of 2.7%, ROE of 8.0%, basic operating cash flow of 14 billion yen (14,000 million yen), and a shareholders’ equity ratio of 40-45%.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















