
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
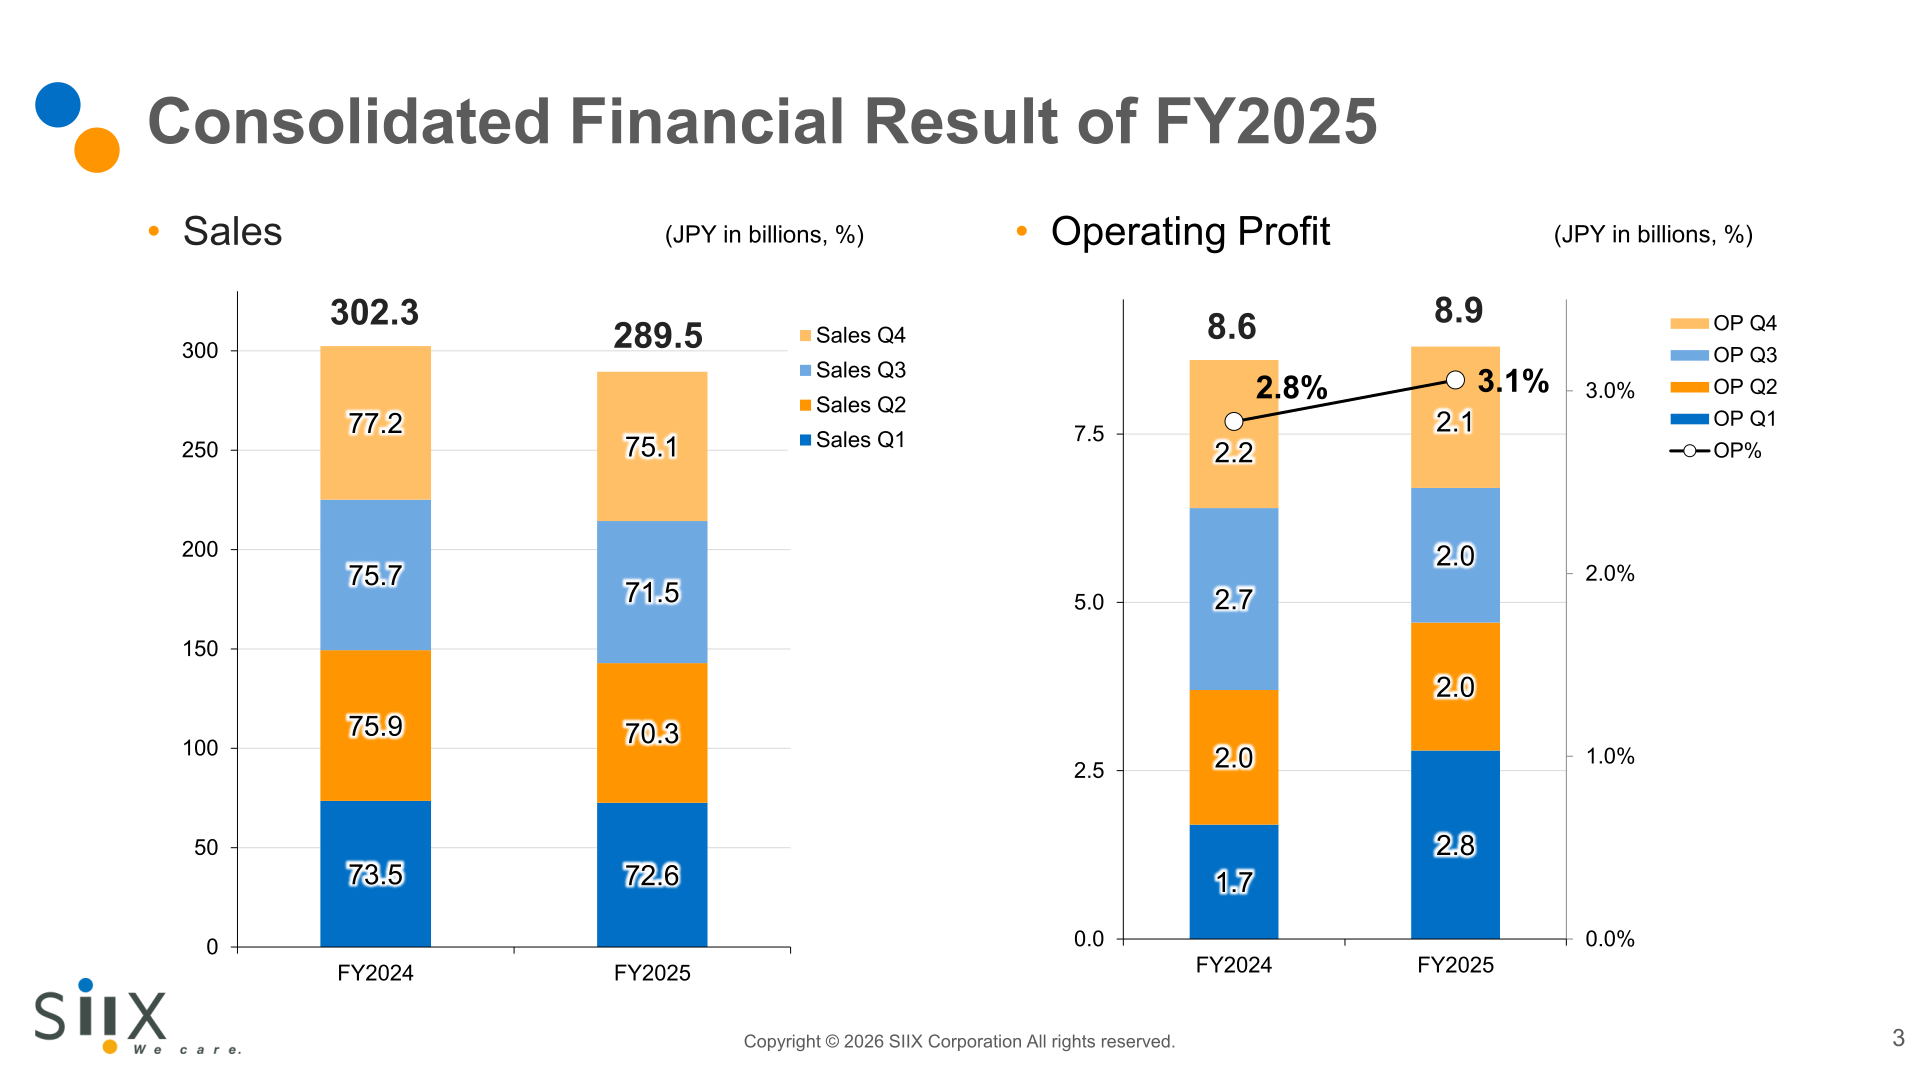
SIIX Corporation reported consolidated results for FY2025 (fiscal year ended December 31, 2025) with net sales of ¥289,491 million, down 4.2% year on year. Operating income rose 3.4% to ¥8,853 million and ordinary income rose 11.4% to ¥9,232 million, but profit attributable to owners of parent fell 33.7% to ¥2,488 million due to larger extraordinary losses and higher income taxes. For FY2026, the company forecasts sales of ¥300,000 million and operating income of ¥9,500 million, and plans to raise the annual dividend to ¥50.0 per share, which would mark the 20th consecutive fiscal year of dividend increases.
Consolidated Results (Full-Year Actual)
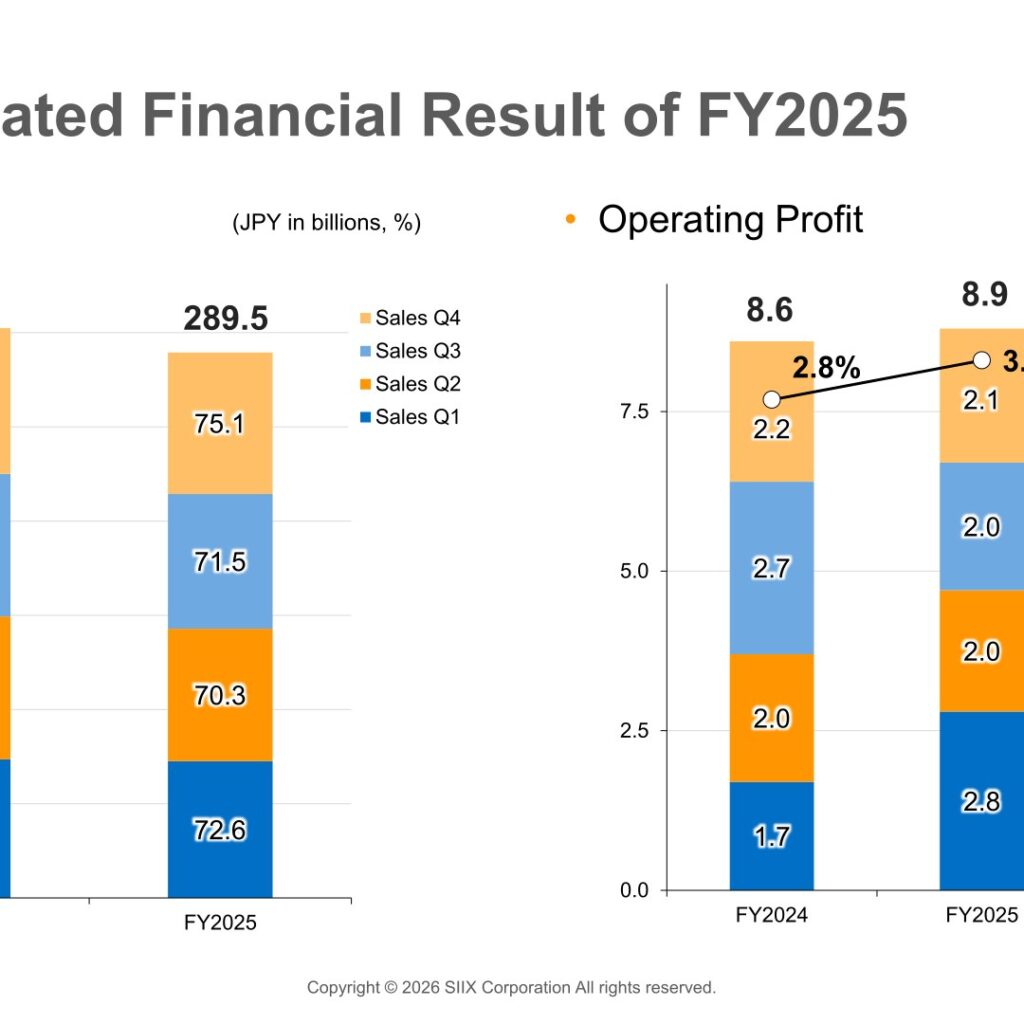
In FY2025, consolidated net sales decreased 4.2% year on year to ¥289,491 million; on a real basis, excluding a positive foreign-exchange impact of ¥860 million, sales declined ¥13,683 million (-4.5%). Gross profit decreased 1.4% to ¥28,210 million, with gross margin improving to 9.7% from 9.5%. SG&A expenses decreased 3.5% to ¥19,356 million. Operating income increased 3.4% to ¥8,853 million (operating margin 3.1%), and ordinary income increased 11.4% to ¥9,232 million (margin 3.2%). Extraordinary losses widened to ¥2,613 million from ¥2,322 million, and income taxes increased 83.8% to ¥4,141 million, resulting in profit attributable to owners of parent of ¥2,488 million, down 33.7% year on year.
| Item (JPY millions) | FY2024 | FY2025 | Change |
|---|---|---|---|
| Sales | 302,314 | 289,491 | -12,822 (-4.2%) |
| Gross Profit | 28,607 | 28,210 | -396 (-1.4%) |
| SGA | 20,047 | 19,356 | -691 (-3.5%) |
| Operating Income | 8,559 | 8,853 | +294 (+3.4%) |
| Ordinary Income | 8,288 | 9,232 | +943 (+11.4%) |
| Profit attributable to owners of parent | 3,754 | 2,488 | -1,266 (-33.7%) |
Segment Results
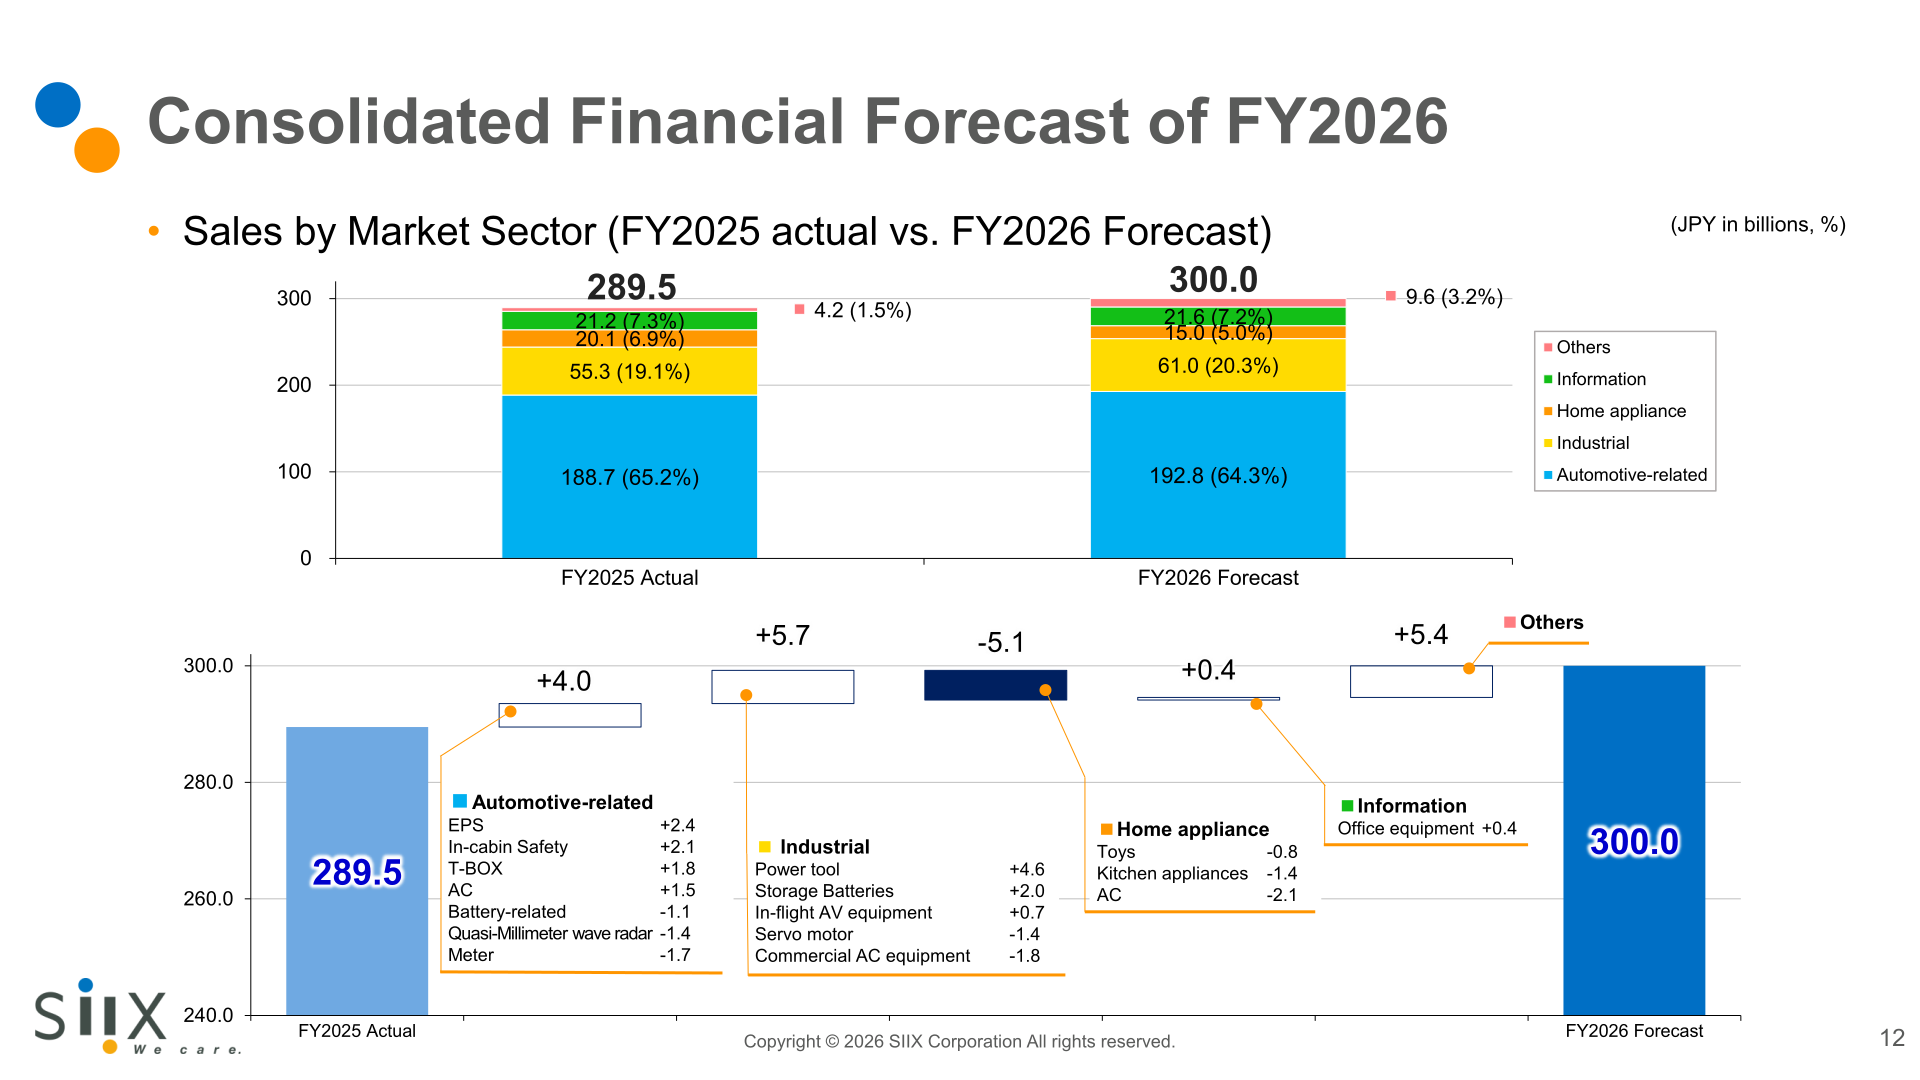
By market sector, sales of automotive-related equipment, the largest category, decreased to ¥188.7 billion (65.2% of total sales) from ¥197.9 billion (65.5%) a year earlier, as shipments of automotive-related equipment decreased in Japan, China, the Americas and Europe. Industrial equipment sales decreased to ¥55.3 billion (19.1%) from ¥56.3 billion (18.6%), and home appliance sales decreased to ¥20.1 billion (6.9%) from ¥24.8 billion (8.2%). Information equipment sales increased to ¥21.2 billion (7.3%) from ¥18.2 billion (6.0%), driven by growth in office equipment. Sales in the Others category were ¥4.2 billion (1.5%), down from ¥5.1 billion (1.7%).
| Market Sector | FY2024 (¥bn, %) | FY2025 (¥bn, %) |
|---|---|---|
| Automotive-related equipment | 197.9 (65.5%) | 188.7 (65.2%) |
| Industrial equipment | 56.3 (18.6%) | 55.3 (19.1%) |
| Home appliances | 24.8 (8.2%) | 20.1 (6.9%) |
| Information equipment | 18.2 (6.0%) | 21.2 (7.3%) |
| Others | 5.1 (1.7%) | 4.2 (1.5%) |
| Total | 302.3 | 289.5 |
By region, sales decreased in Japan to ¥56.6 billion, in China to ¥57.5 billion, in ASEAN to ¥93.1 billion, in the Americas to ¥60.1 billion, and in Europe to ¥21.4 billion, while the CDMO business (bio-antibody drugs) recorded no sales. On operating profit by region, ASEAN improved to ¥4.67 billion (margin 4.2%) on manufacturing cost reductions and other initiatives, and the Americas improved to ¥4.28 billion (margin 5.7%) on reduced manufacturing and transportation costs; China turned to an operating profit of ¥0.79 billion (margin 1.0%) on profitability improvement from cost reductions. Japan’s operating profit decreased to ¥0.90 billion (margin 1.0%) on reduced sales, and Europe and the CDMO business posted operating losses of ¥1.30 billion and ¥1.01 billion respectively, reflecting reduced demand for automotive-related products and increased CDMO research and development expenses.
| Region | FY2024 Sales (¥bn) | FY2025 Sales (¥bn) | FY2024 OP (¥bn, %) | FY2025 OP (¥bn, %) |
|---|---|---|---|---|
| Japan | 58.0 | 56.6 | 1.34 (1.4%) | 0.90 (1.0%) |
| China | 61.1 | 57.5 | 0.03 (0.0%) | 0.79 (1.0%) |
| ASEAN | 94.1 | 93.1 | 4.36 (3.8%) | 4.67 (4.2%) |
| Americas | 63.1 | 60.1 | 4.18 (5.5%) | 4.28 (5.7%) |
| Europe | 25.3 | 21.4 | -1.22 (-) | -1.30 (-) |
| CDMO | 0.0 | 0.0 | -0.77 (-) | -1.01 (-) |
| Other | 0.7 | 0.8 | 0.64 (-) | 0.52 (-) |
| Total | 302.3 | 289.5 | 8.56 (2.8%) | 8.85 (3.1%) |
FY2026 Forecast
For FY2026 (fiscal year ending December 31, 2026), SIIX forecasts consolidated net sales of ¥300,000 million, up 3.6% year on year, operating income of ¥9,500 million (margin 3.2%), up 7.3%, and ordinary income of ¥9,000 million (margin 3.0%), down 2.5%. Profit attributable to owners of parent is forecast at ¥6,000 million (margin 2.0%), up 141.1% from FY2025, with forecast earnings per share of ¥127.29 versus ¥52.82 in FY2025. The forecast assumes an exchange rate of ¥150.00 to the US dollar, compared with ¥149.71 in FY2025. By region, operating profit is expected to improve in ASEAN to ¥5.28 billion and turn positive in Europe at ¥0.13 billion, while the Americas is expected to decline to ¥3.90 billion on weakness in automotive-related equipment and the CDMO business is expected to post a wider loss of ¥1.35 billion due to increased research and development expenses.
| Item | FY2025 (Actual) | FY2026 (Forecast) | Change |
|---|---|---|---|
| Sales (JPY millions) | 289,491 | 300,000 | +10,508 (+3.6%) |
| Operating income (JPY millions, margin) | 8,853 (3.1%) | 9,500 (3.2%) | +646 (+7.3%) |
| Ordinary income (JPY millions, margin) | 9,232 (3.2%) | 9,000 (3.0%) | -232 (-2.5%) |
| Profit attributable to owners of parent (JPY millions, margin) | 2,488 (0.9%) | 6,000 (2.0%) | +3,511 (+141.1%) |
| Net income per share (JPY) | 52.82 | 127.29 | +74.47 (+141.0%) |
Shareholder Returns
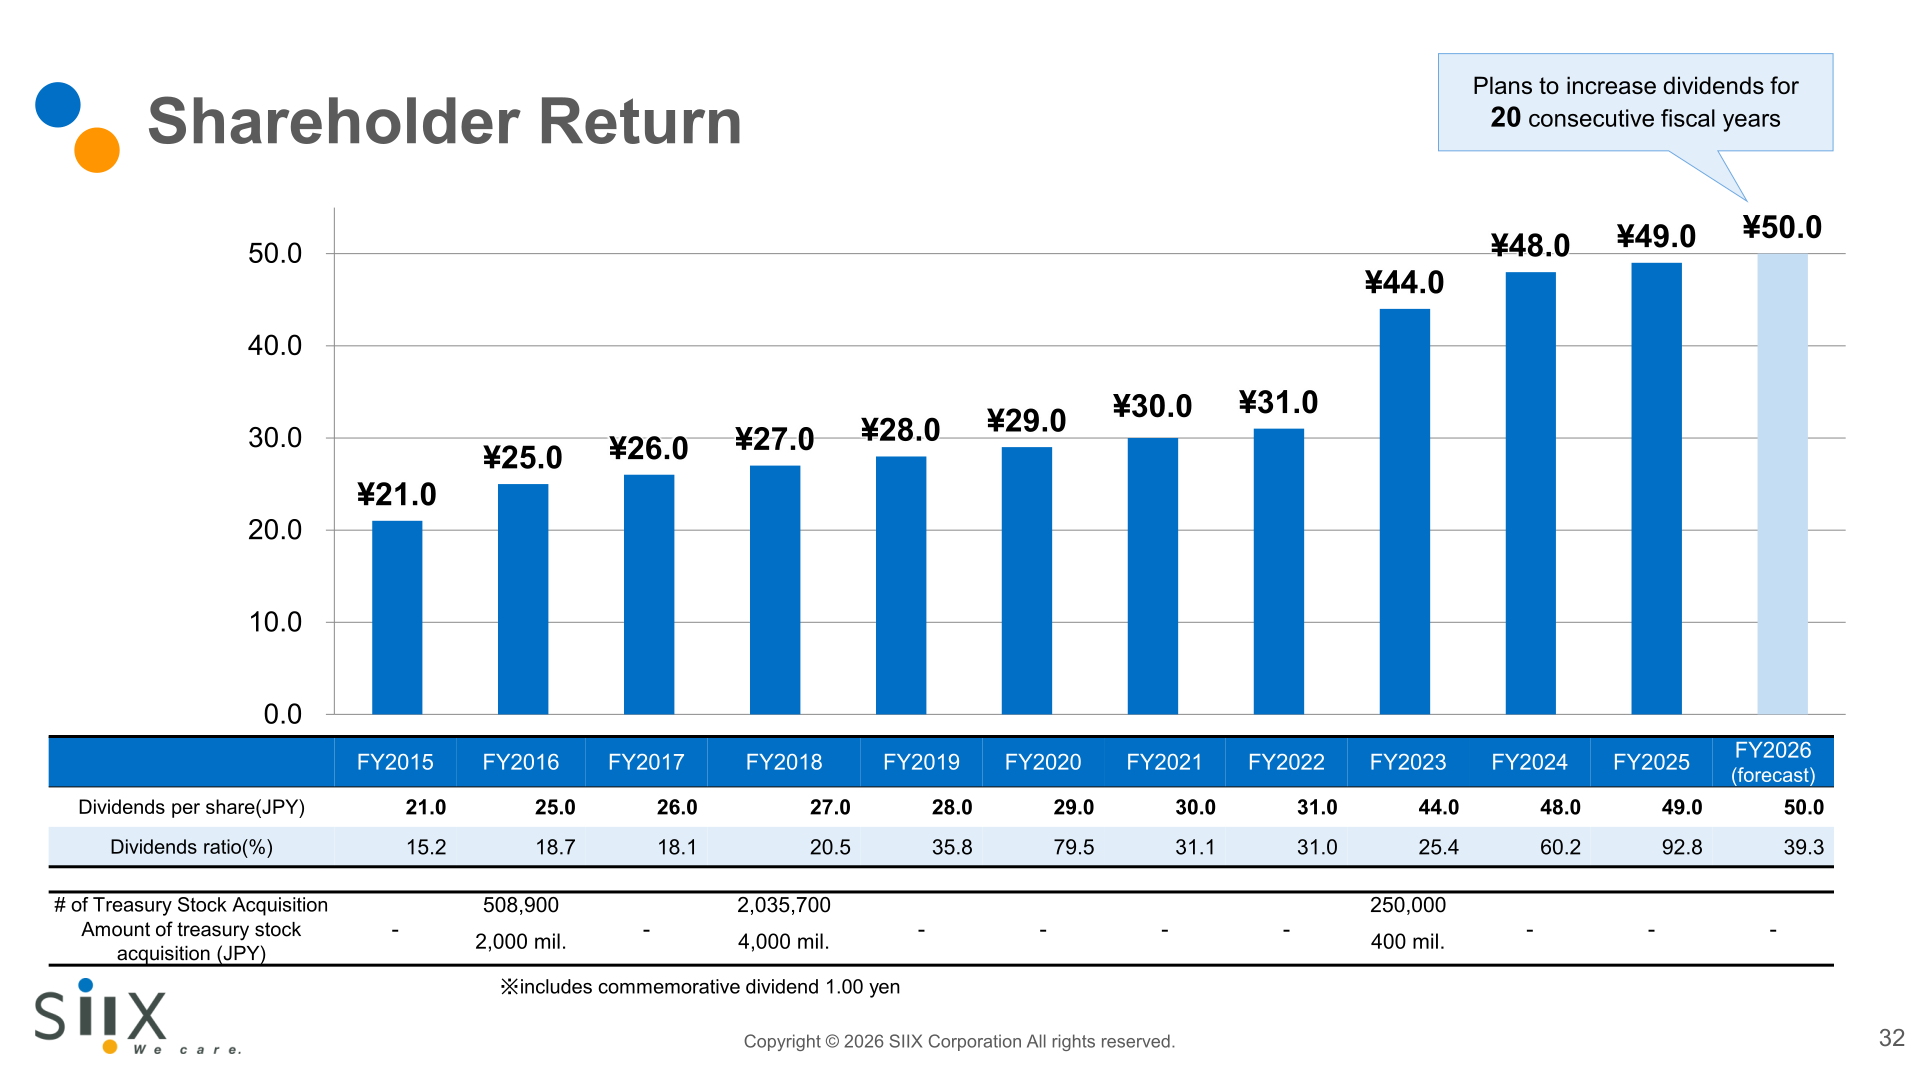
SIIX plans to pay a dividend per share of ¥50.0 for FY2026, up from ¥49.0 in FY2025 (which included a ¥1.00 commemorative dividend), which the company states would extend its record of dividend increases to 20 consecutive fiscal years. The FY2025 dividend payout ratio was 92.8%, and the FY2026 payout ratio is forecast at 39.3%. Dividends per share have risen from ¥21.0 in FY2015 to ¥25.0 (FY2016), ¥26.0 (FY2017), ¥27.0 (FY2018), ¥28.0 (FY2019), ¥29.0 (FY2020), ¥30.0 (FY2021), ¥31.0 (FY2022), ¥44.0 (FY2023), ¥48.0 (FY2024), ¥49.0 (FY2025) and a forecast ¥50.0 (FY2026).
Medium-Term Plan / Topics
SIIX is developing a CDMO (Contract Development and Manufacturing Organization) business for antibody drugs through its subsidiary Renzoku Biologics Inc., with a short-term vision (through 2028) of building GMP manufacturing capacity of 50-200L scale for clinical products and establishing a Centre of Excellence in biomanufacturing, and a mid-term vision (through 2031) of establishing 500L-scale GMP capacity and facilities for commercial production. The company is constructing process development labs and a manufacturing site at Kanagawa Science Park in Sagamihara, with first-generation process validation for cell line development, upstream/downstream processes and analytics scheduled for completion in 2027. Other topics disclosed include collaboration with Hagiya New Techno to expand domestic manufacturing capacity, and market development in collaboration with Sakata Inx.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















