
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note on fiscal-year labels: KONDOTEC INC. calls the fiscal year ended March 31, 2026 “FY2026” and the following year “FY2027”. This site classifies the most recently completed fiscal year as FY2025, but all labels in the text, tables and charts below follow the company’s own presentation.
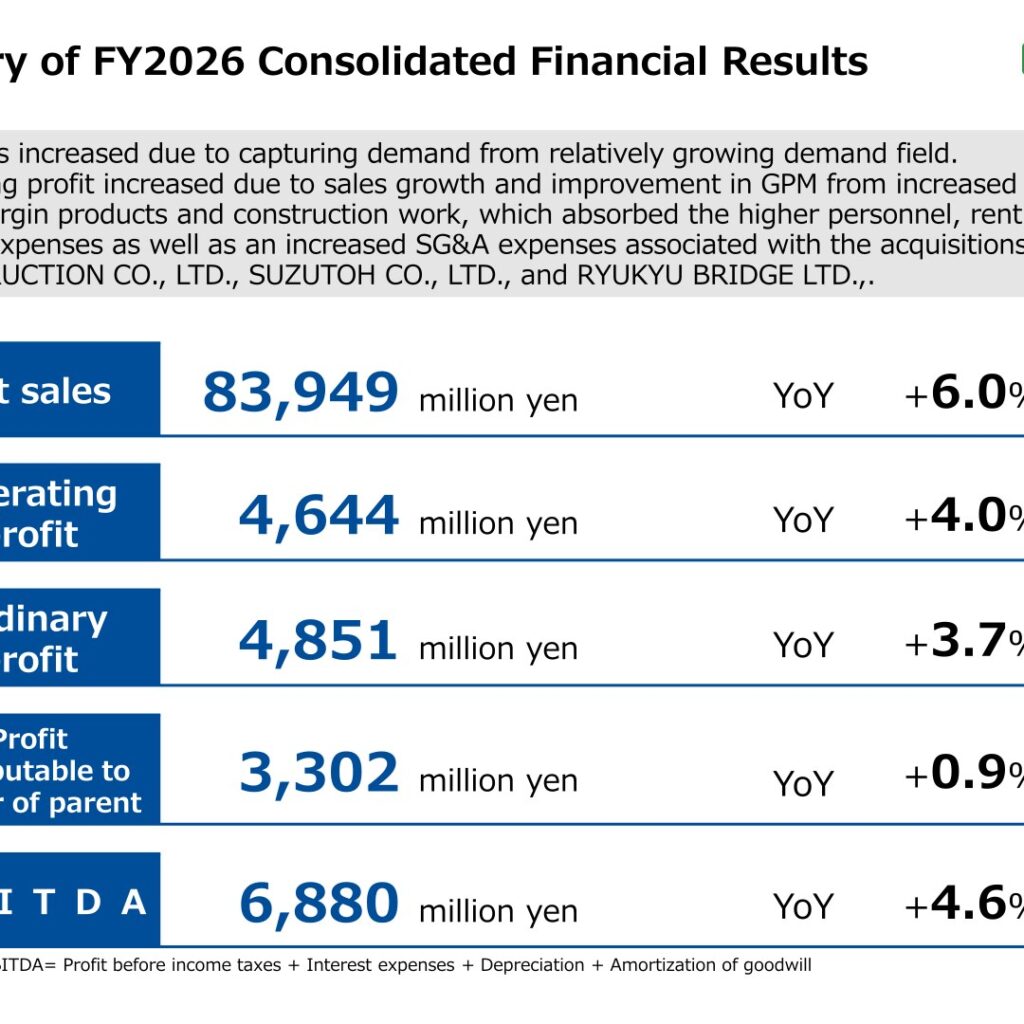
KONDOTEC INC. (Tokyo Stock Exchange Prime Market, Securities Code: 7438) reported FY2026 (fiscal year ended March 31, 2026) consolidated net sales of 83,949 million yen, up 6.0% year on year, with operating profit of 4,644 million yen (+4.0%), ordinary profit of 4,851 million yen (+3.7%), profit attributable to owner of parent of 3,302 million yen (+0.9%) and EBITDA of 6,880 million yen (+4.6%). The company states that net sales increased due to capturing demand from relatively growing demand field, and that operating profit increased due to sales growth and improvement in GPM from increased sales of high-margin products and construction work, which absorbed the higher personnel, rent, and freight expenses as well as an increased SG&A expenses associated with the acquisitions of UEDA CONSTRUCTION CO., LTD., SUZUTOH CO., LTD., and RYUKYU BRIDGE LTD. For FY2027 the company forecasts net sales of 91,000 million yen and operating profit of 4,950 million yen.
Consolidated Results (Full-Year Actual)
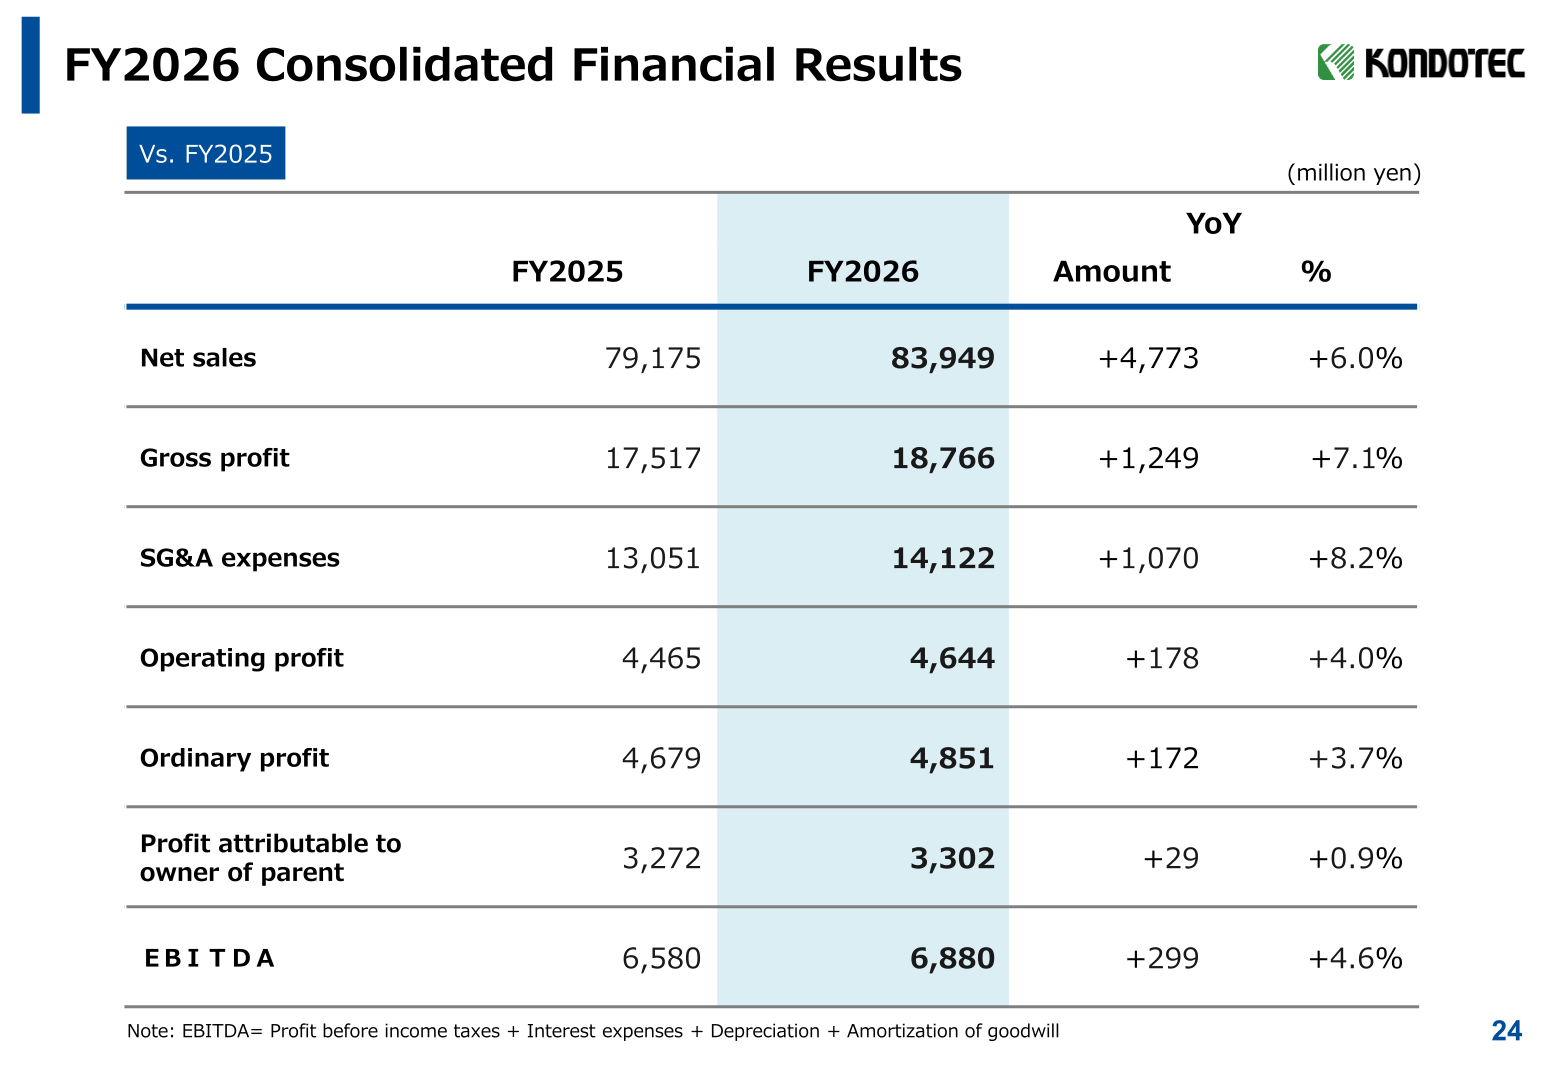
All four profit lines rose year on year. Gross profit grew 7.1% to 18,766 million yen while SG&A expenses rose 8.2% to 14,122 million yen. The materials note that EBITDA is defined as profit before income taxes + interest expenses + depreciation + amortization of goodwill.
| Item (million yen) | FY2025 | FY2026 | Change (amount) | Change (%) |
|---|---|---|---|---|
| Net sales | 79,175 | 83,949 | +4,773 | +6.0% |
| Gross profit | 17,517 | 18,766 | +1,249 | +7.1% |
| SG&A expenses | 13,051 | 14,122 | +1,070 | +8.2% |
| Operating profit | 4,465 | 4,644 | +178 | +4.0% |
| Ordinary profit | 4,679 | 4,851 | +172 | +3.7% |
| Profit attributable to owner of parent | 3,272 | 3,302 | +29 | +0.9% |
| EBITDA | 6,580 | 6,880 | +299 | +4.6% |
Against the company’s own full-year forecast, net sales of 83,949 million yen came in 1,050 million yen (△1.2%) below the 85,000 million yen forecast and gross profit was 633 million yen (△3.3%) below the 19,400 million yen forecast, but SG&A expenses of 14,122 million yen were 677 million yen (△4.6%) lower than the 14,800 million yen forecast. As a result, operating profit exceeded the forecast by 44 million yen (+1.0%) and ordinary profit by 51 million yen (+1.1%), while profit attributable to owner of parent was 47 million yen (△1.4%) below the 3,350 million yen forecast. The gross profit margin was 22.4% versus a forecast of 22.8%.
Segment Results
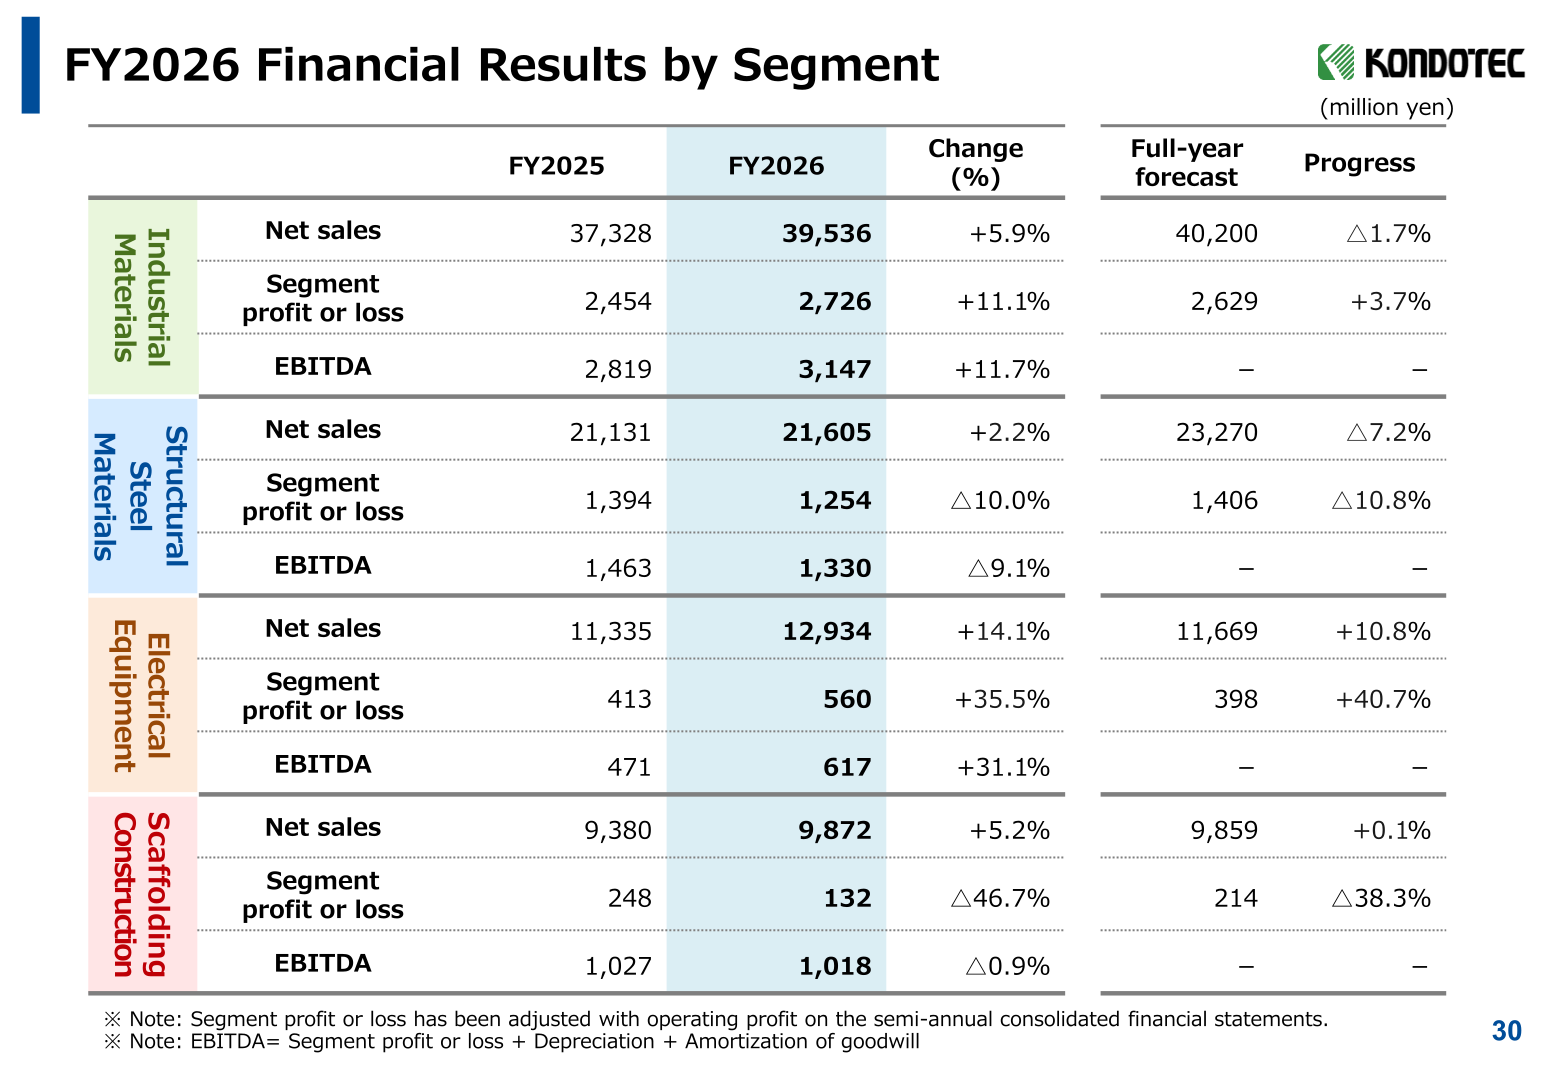
Industrial Materials, the largest segment at 47% of FY2026 net sales, grew 5.9% with segment profit up 11.1%, helped by higher orders from large customers, price pass-through and contributions from newly acquired SUZUTOH CO., LTD. and RYUKYU BRIDGE LTD. Electrical Equipment posted the strongest growth, with net sales up 14.1% and segment profit up 35.5%, which the company attributes to robust sales of power distribution panels, electrical wires, solar power equipment and air-conditioning equipment, driven by large-scale capital investment ahead of the 2027 Building Energy Efficiency Act and LED replacement demand following the discontinuation of fluorescent lamp production in 2027. Structural Steel Materials grew sales 2.2% but segment profit fell 10.0%, and Scaffolding Construction grew sales 5.2% while segment profit fell 46.7%.
| Segment | Item (million yen) | FY2025 | FY2026 | YoY change (%) | FY2027 Forecast |
|---|---|---|---|---|---|
| Industrial Materials | Net sales | 37,328 | 39,536 | +5.9% | 44,416 |
| Industrial Materials | Segment profit or loss | 2,454 | 2,726 | +11.1% | 3,119 |
| Industrial Materials | EBITDA | 2,819 | 3,147 | +11.7% | - |
| Structural Steel Materials | Net sales | 21,131 | 21,605 | +2.2% | 23,371 |
| Structural Steel Materials | Segment profit or loss | 1,394 | 1,254 | △10.0% | 1,184 |
| Structural Steel Materials | EBITDA | 1,463 | 1,330 | △9.1% | - |
| Electrical Equipment | Net sales | 11,335 | 12,934 | +14.1% | 13,348 |
| Electrical Equipment | Segment profit or loss | 413 | 560 | +35.5% | 542 |
| Electrical Equipment | EBITDA | 471 | 617 | +31.1% | - |
| Scaffolding Construction | Net sales | 9,380 | 9,872 | +5.2% | 9,863 |
| Scaffolding Construction | Segment profit or loss | 248 | 132 | △46.7% | 151 |
| Scaffolding Construction | EBITDA | 1,027 | 1,018 | △0.9% | - |
By share of FY2026 net sales, Industrial Materials accounted for 47% (39,536 million yen), Structural Steel Materials 26% (21,605 million yen), Electrical Equipment 15% (12,934 million yen) and Scaffolding Construction 12% (9,872 million yen). As of end March 2026 the group operated 106 operating sites (Industrial Materials 38, Structural Steel Materials 20, Electrical Equipment 12, Scaffolding Construction 36), with 1,531 consolidated employees and 829 at the parent.
FY2027 Forecast
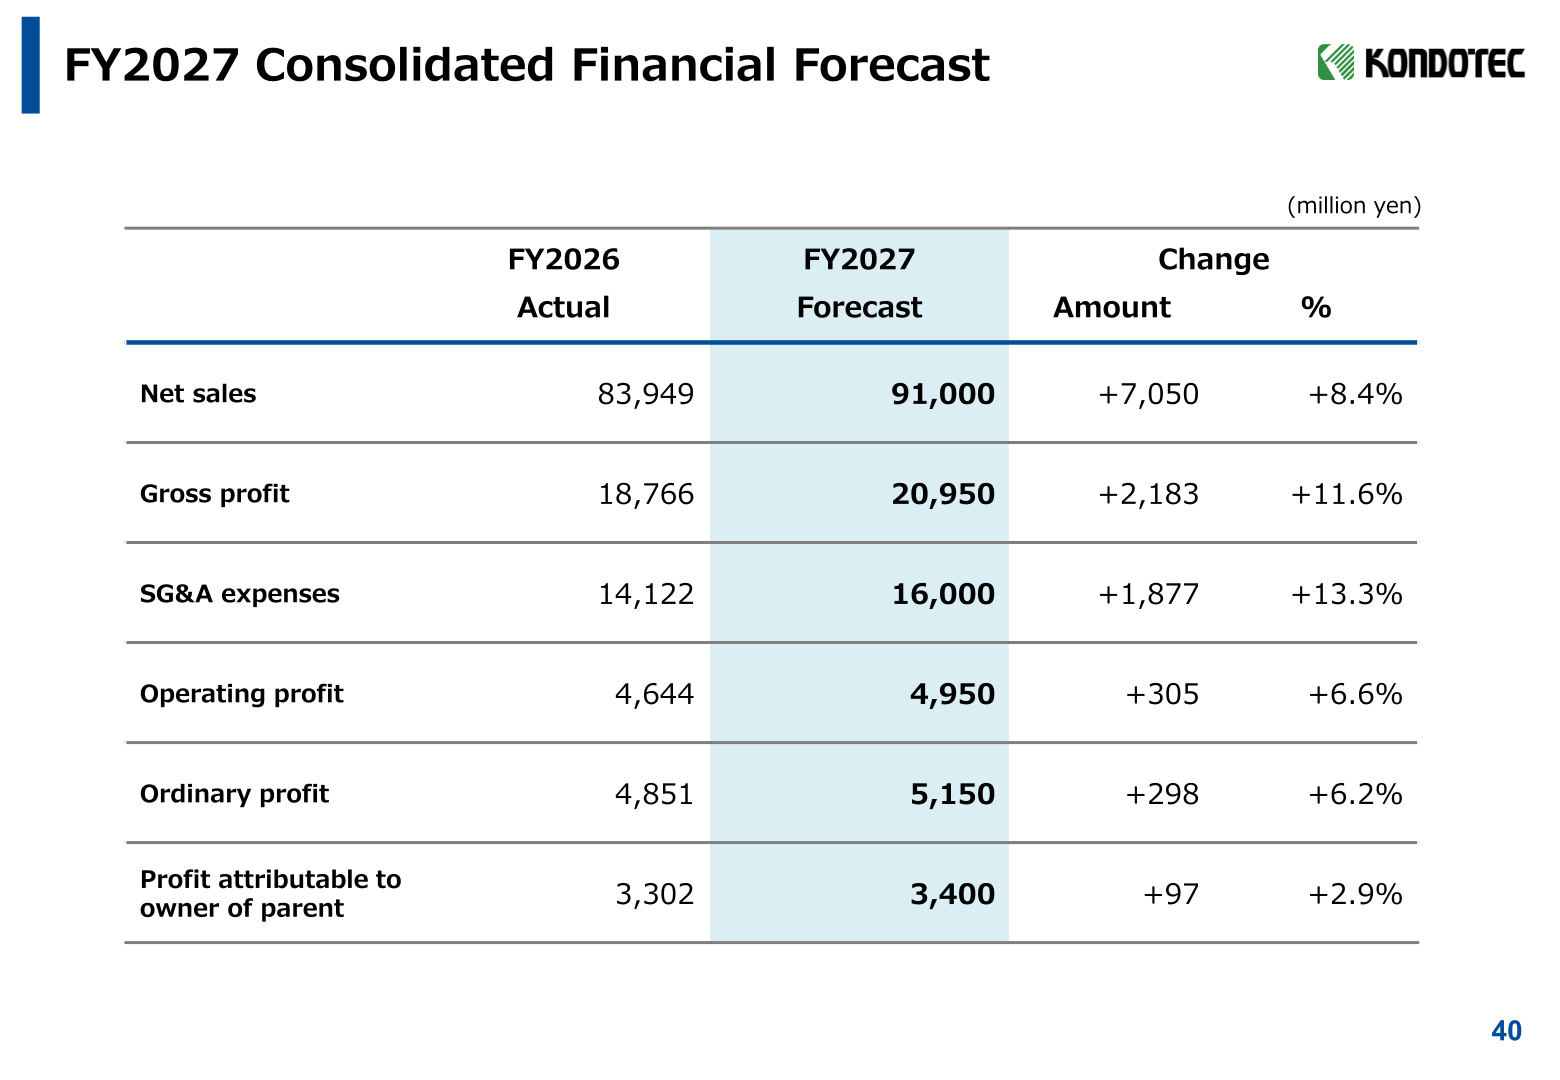
For FY2027 (fiscal year ending March 31, 2027), the company forecasts net sales of 91,000 million yen, up 8.4% year on year, operating profit of 4,950 million yen (+6.6%), ordinary profit of 5,150 million yen (+6.2%) and profit attributable to owner of parent of 3,400 million yen (+2.9%). Gross profit is forecast at 20,950 million yen (+11.6%) against SG&A expenses of 16,000 million yen (+13.3%). By segment, Industrial Materials is expected to grow sales 12.3% to 44,416 million yen with segment profit up 14.4% to 3,119 million yen, while Structural Steel Materials and Electrical Equipment segment profit are forecast to decline 5.6% and 3.3% respectively.
| Item (million yen) | FY2026 Actual | FY2027 Forecast | Change (amount) | Change (%) |
|---|---|---|---|---|
| Net sales | 83,949 | 91,000 | +7,050 | +8.4% |
| Gross profit | 18,766 | 20,950 | +2,183 | +11.6% |
| SG&A expenses | 14,122 | 16,000 | +1,877 | +13.3% |
| Operating profit | 4,644 | 4,950 | +305 | +6.6% |
| Ordinary profit | 4,851 | 5,150 | +298 | +6.2% |
| Profit attributable to owner of parent | 3,302 | 3,400 | +97 | +2.9% |
Shareholder Returns
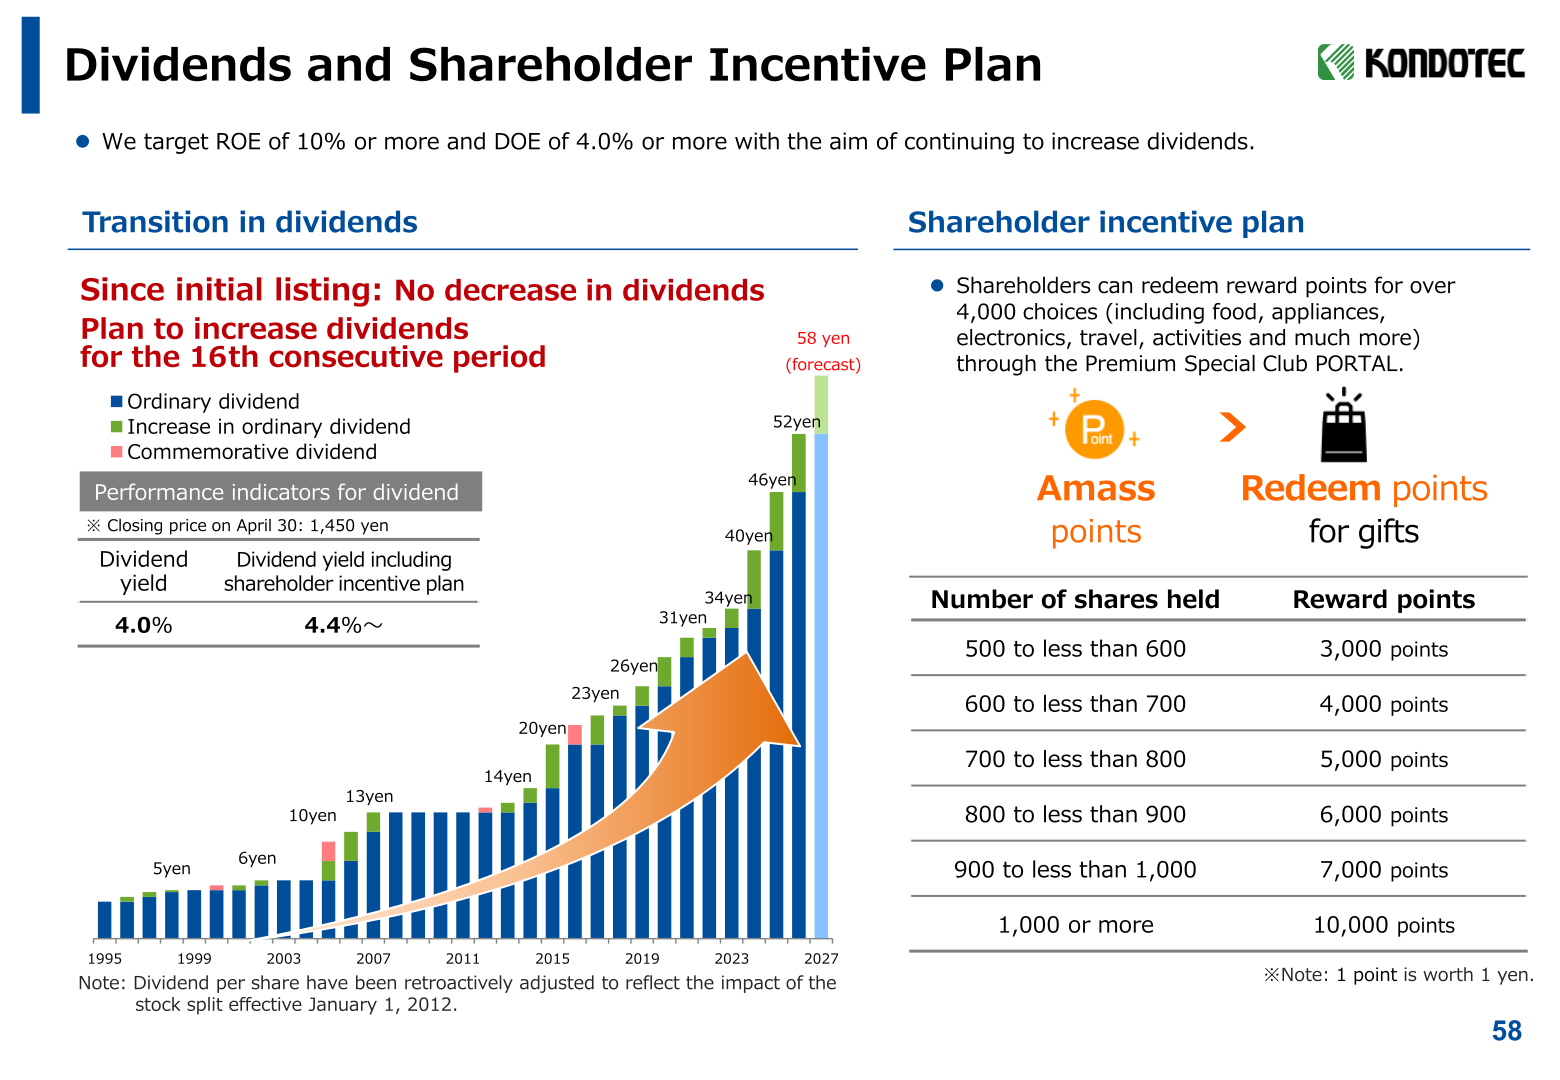
KONDOTEC targets ROE of 10% or more and DOE of 4.0% or more as medium- to long-term targets, with the aim of continuing to increase dividends. The dividend per share for FY2026 was 52.00 yen, and the FY2027 forecast is 58.00 yen. The materials state that the company has not decreased its dividend since its initial listing and plans to increase dividends for the 16th consecutive period. The presentation shows a dividend yield of 4.0%, or 4.4% or more including the shareholder incentive plan, based on the closing price on April 30 of 1,450 yen. Under the shareholder incentive plan, holders of 500 to less than 600 shares receive 3,000 reward points, rising in steps to 10,000 points for holders of 1,000 shares or more (1 point is worth 1 yen), redeemable for over 4,000 choices through the Premium Special Club PORTAL.
| Item | FY2025 (25/3) | FY2026 (26/3) | Medium- to long-term target |
|---|---|---|---|
| Dividend per share (yen) | 46.00 | 52.00 | - |
| ROE (%) | 9.3 | 8.8 | 10% or more |
| DOE (%) | 3.3 | 3.6 | 4% or more |
| Net assets (million yen) | 38,350 | 40,566 | - |
Per-share figures shown in the materials include profit attributable to owners of parent per share of 128.95 yen for FY2026 and net assets per share of 1,503.22 yen as of end March 2026. Based on the April 30, 2026 closing price of 1,450 yen, the presentation cites a PER of 10.9 and a PBR of 1.0, with EPS of 132.63 yen on the FY2027 forecast.
Management Strategies and Topics
KONDOTEC targets consolidated sales of 100 billion yen in the 2020s by strengthening the earnings capability of existing core businesses and expanding into fields with growth prospects, combining organic growth strategies (cultivation of new customers, offer of new products and merchandise, diversifying sales methods, expansion of operating sites, response to natural disasters) with periphery-strengthening growth strategies (increasing presence in foreign markets, entering into neighborhood, utilizing digital technologies). The materials note a medium-term management plan covering FY2027–FY2029.
During FY2026 the company made two acquisitions: SUZUTOH CO., LTD. (Chiyoda-ku, Tokyo; capital stock 100 million yen as of March 31, 2025), a manufacturer and supplier of “Safety steel site hoarding”, in November 2025, and RYUKYU BRIDGE LTD. (Urasoe, Okinawa; capital stock 8 million yen as of May 31, 2025), a manufacturer and seller of construction materials, in December 2025. SUZUTOH recorded FY2025 net sales of 2,733 million yen, operating profit of 64 million yen, ordinary profit of 59 million yen and EBITDA of 128 million yen; RYUKYU BRIDGE recorded net sales of 577 million yen, operating profit of 31 million yen, ordinary profit of 32 million yen and EBITDA of 39 million yen. The reconstruction of the Osaka head office was completed in November 2025 and operations started on December 1, 2025; the building has obtained ZEB-Ready certification.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















