
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: PKSHA Technology’s fiscal year ends in September, and its materials label the fiscal year ended September 2025 as “FY9/2025”; this site classifies it as FY2025. Labels in the body and tables follow the company’s materials.
PKSHA Technology Inc. (TSE Prime 3993) reported FY9/2025 (IFRS) net sales of 21,771 million yen (+28.9% YoY), adjusted EBITDA of 5,443 million yen (+31.5% YoY) and business profit of 3,922 million yen (+25.6% YoY), with both the AI Research & Solution and AI SaaS businesses delivering strong growth. All of these exceeded the full-year forecasts, with a progress rate of 117.1% for business profit. In the AI SaaS segment, ARR grew +37.7% YoY and the number of customers reached 4,465 companies. For FY9/2026, the company forecasts net sales of 35,000 million yen, adjusted EBITDA of 6,700 million yen and business profit of 5,000 million yen, and it will shift to three reporting segments with the addition of “AI Powered Worker”.
Consolidated Results (Full-Year Actual)
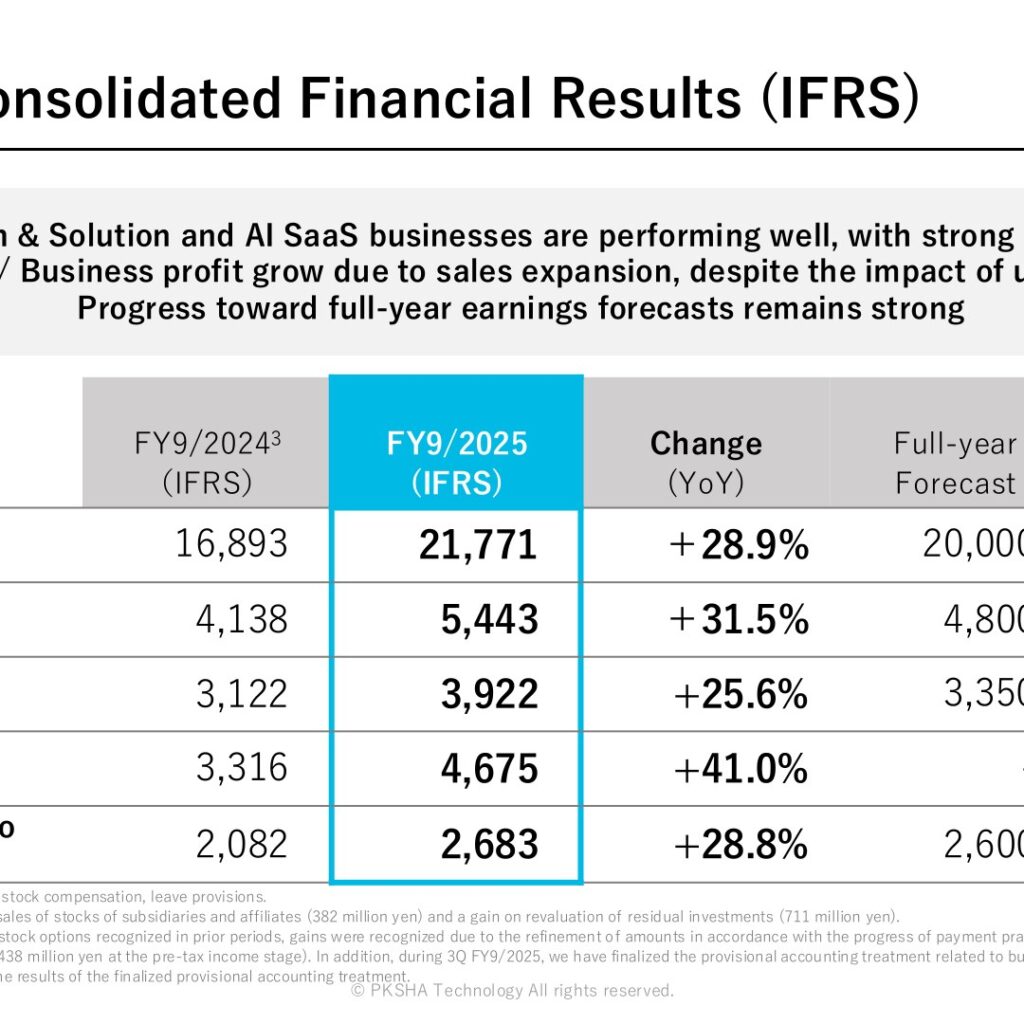
Net sales rose to 21,771 million yen (+28.9% YoY), adjusted EBITDA to 5,443 million yen (+31.5%) and business profit to 3,922 million yen (+25.6%). Profit before tax was 4,675 million yen (+41.0%) and profit attributable to owners of parent was 2,683 million yen (+28.8%). The company states that the AI Research & Solution and AI SaaS businesses performed well with strong sales growth, and that adjusted EBITDA and business profit grew due to sales expansion despite the impact of upfront investments. Adjusted EBITDA is defined in the materials as EBITDA minus stock compensation and leave provisions.
| Item (Millions of yen) | FY9/2025 (IFRS) | FY9/2024 (IFRS) | Change (YoY) | Full-year Forecast | Progress rate on forecast |
|---|---|---|---|---|---|
| Net sales | 21,771 | 16,893 | +28.9% | 20,000 | 108.9% |
| Adjusted EBITDA | 5,443 | 4,138 | +31.5% | 4,800 | 113.4% |
| Business profit | 3,922 | 3,122 | +25.6% | 3,350 | 117.1% |
| Profit before tax | 4,675 | 3,316 | +41.0% | – | – |
| Profit attributable to owners of parent | 2,683 | 2,082 | +28.8% | 2,600 | 103.2% |
Segment Results
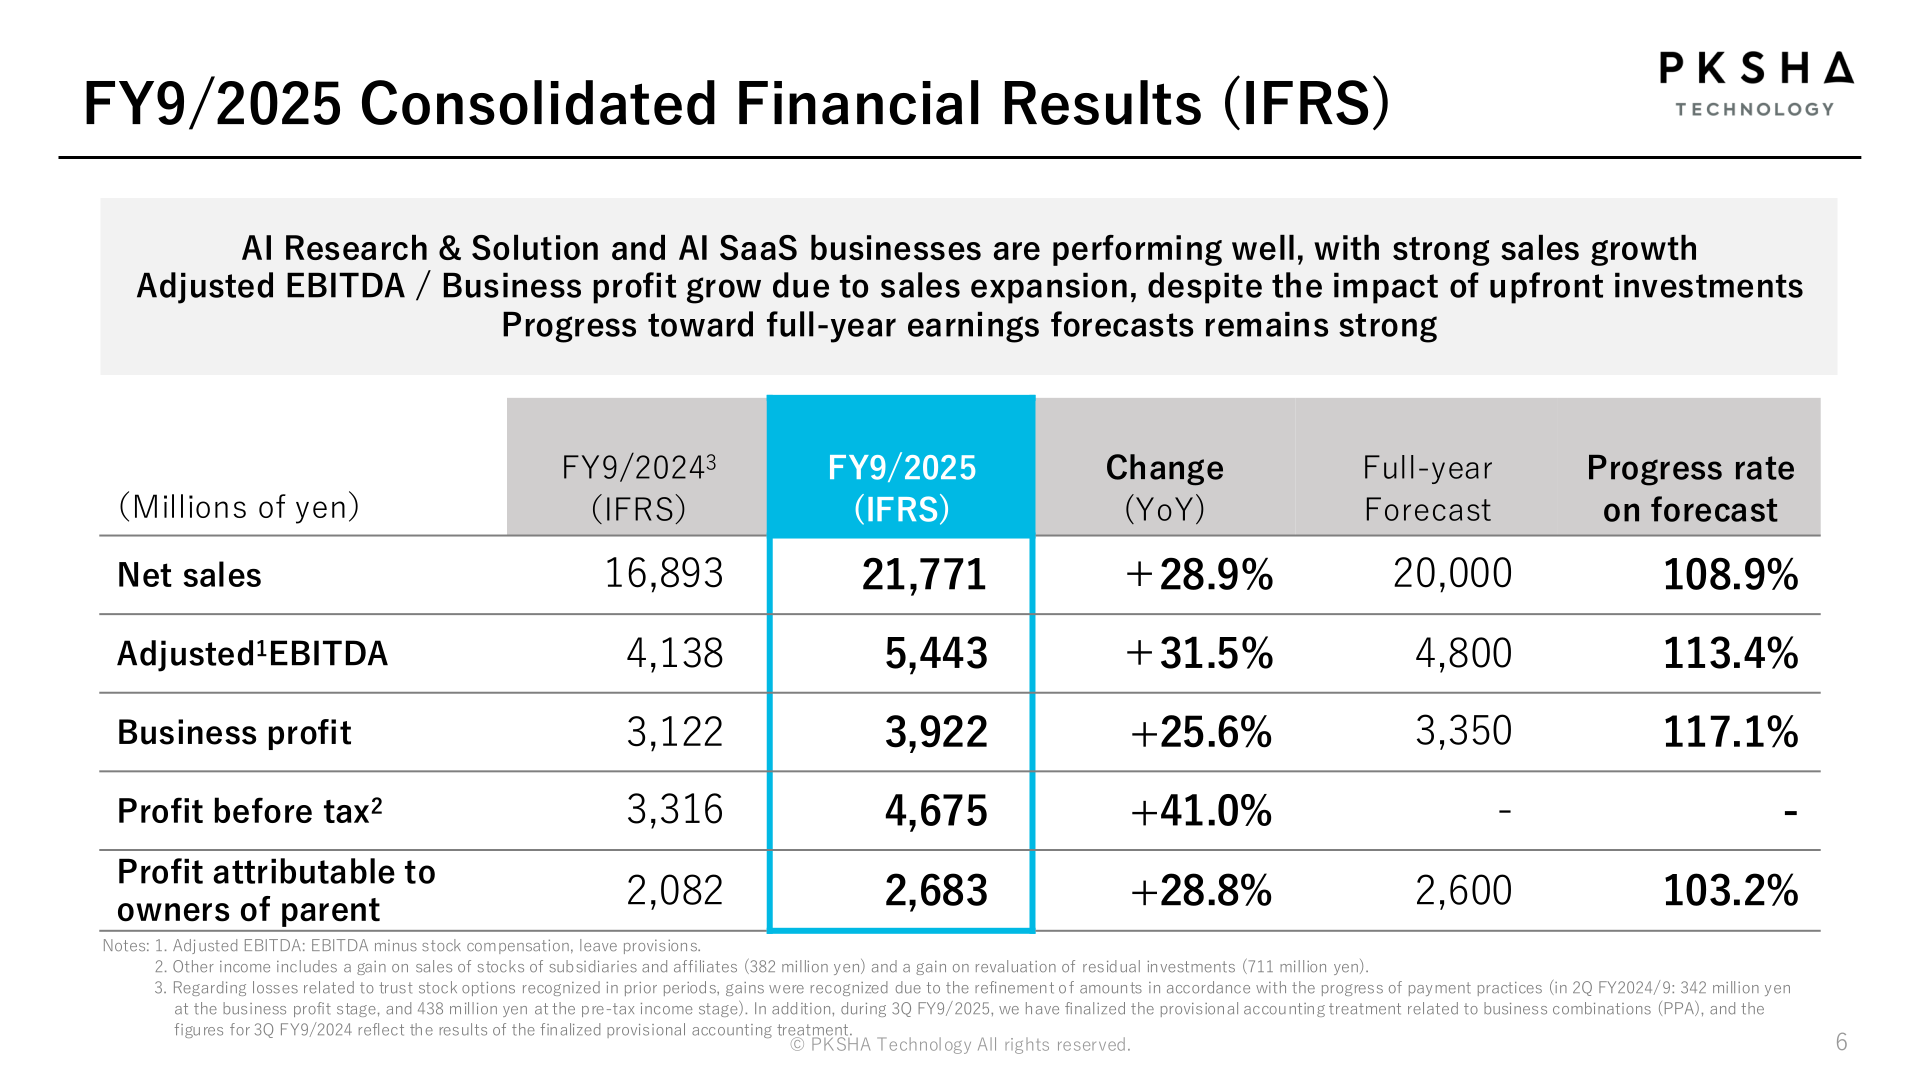
AI Research & Solution: net sales rose to 12,892 million yen (+28.8% YoY) and segment income to 2,451 million yen (+27.0%). The company notes that strong demand driven by the momentum of Generative AI/LLMs continued, leading to solid performance in solution projects, and that profitability improved YoY through sales growth and higher productivity in high-margin solutions. Adjusted EBITDA margin was 23.5% (22.9% in FY9/2024).
AI SaaS: net sales rose to 9,049 million yen (+28.7% YoY) and segment income to 3,125 million yen (+25.3%), while adjusted EBITDA margin was 43.8% (▲0.6%pt). The company says the segment achieved both high profitability and growth while continuing to invest in talent acquisition and product development. The segment profit adjustment was ▲1,654 million yen (▲1,302 million yen in FY9/2024).
| Segment | Metric (Millions of yen) | FY9/2025 | FY9/2024 | YoY change |
|---|---|---|---|---|
| AI Research & Solution | Net sales | 12,892 | 10,008 | +28.8% |
| AI Research & Solution | Segment income | 2,451 | 1,929 | +27.0% |
| AI Research & Solution | Adjusted EBITDA | 3,024 | 2,293 | +31.9% |
| AI Research & Solution | Adjusted EBITDA margin | 23.5% | 22.9% | — |
| AI SaaS | Net sales | 9,049 | 7,031 | +28.7% |
| AI SaaS | Segment income | 3,125 | 2,495 | +25.3% |
| AI SaaS | Adjusted EBITDA | 3,960 | 3,122 | +26.8% |
| AI SaaS | Adjusted EBITDA margin | 43.8% | 44.4% | ▲0.6%pt |
| Segment profit adjustment | — | ▲1,654 | ▲1,302 | — |
In the AI SaaS segment, ARR reached 9,348 million yen (+37.7% YoY) at the end of 4Q FY9/2025, NRR was 108.2% (+7.8%pt YoY), and the number of customers was 4,465 companies (+1,377 companies YoY). ARR, NRR and the number of customers are calculated based on recurring (stock-type) revenue. The company states that its competitive AI SaaS products are in use at over 4,400 companies and that approximately 7,000 “AI Agents” are in operation in all 47 prefectures.
| AI SaaS KPI | 4Q FY9/2025 | 4Q FY9/2024 | Change (YoY) |
|---|---|---|---|
| ARR (Millions of yen) | 9,348 | 6,789 | +37.7% |
| NRR | 108.2% | 100.4% | +7.8%pt |
| Number of customers | 4,465 | 3,088 | +1,377 |
FY9/2026 Forecast
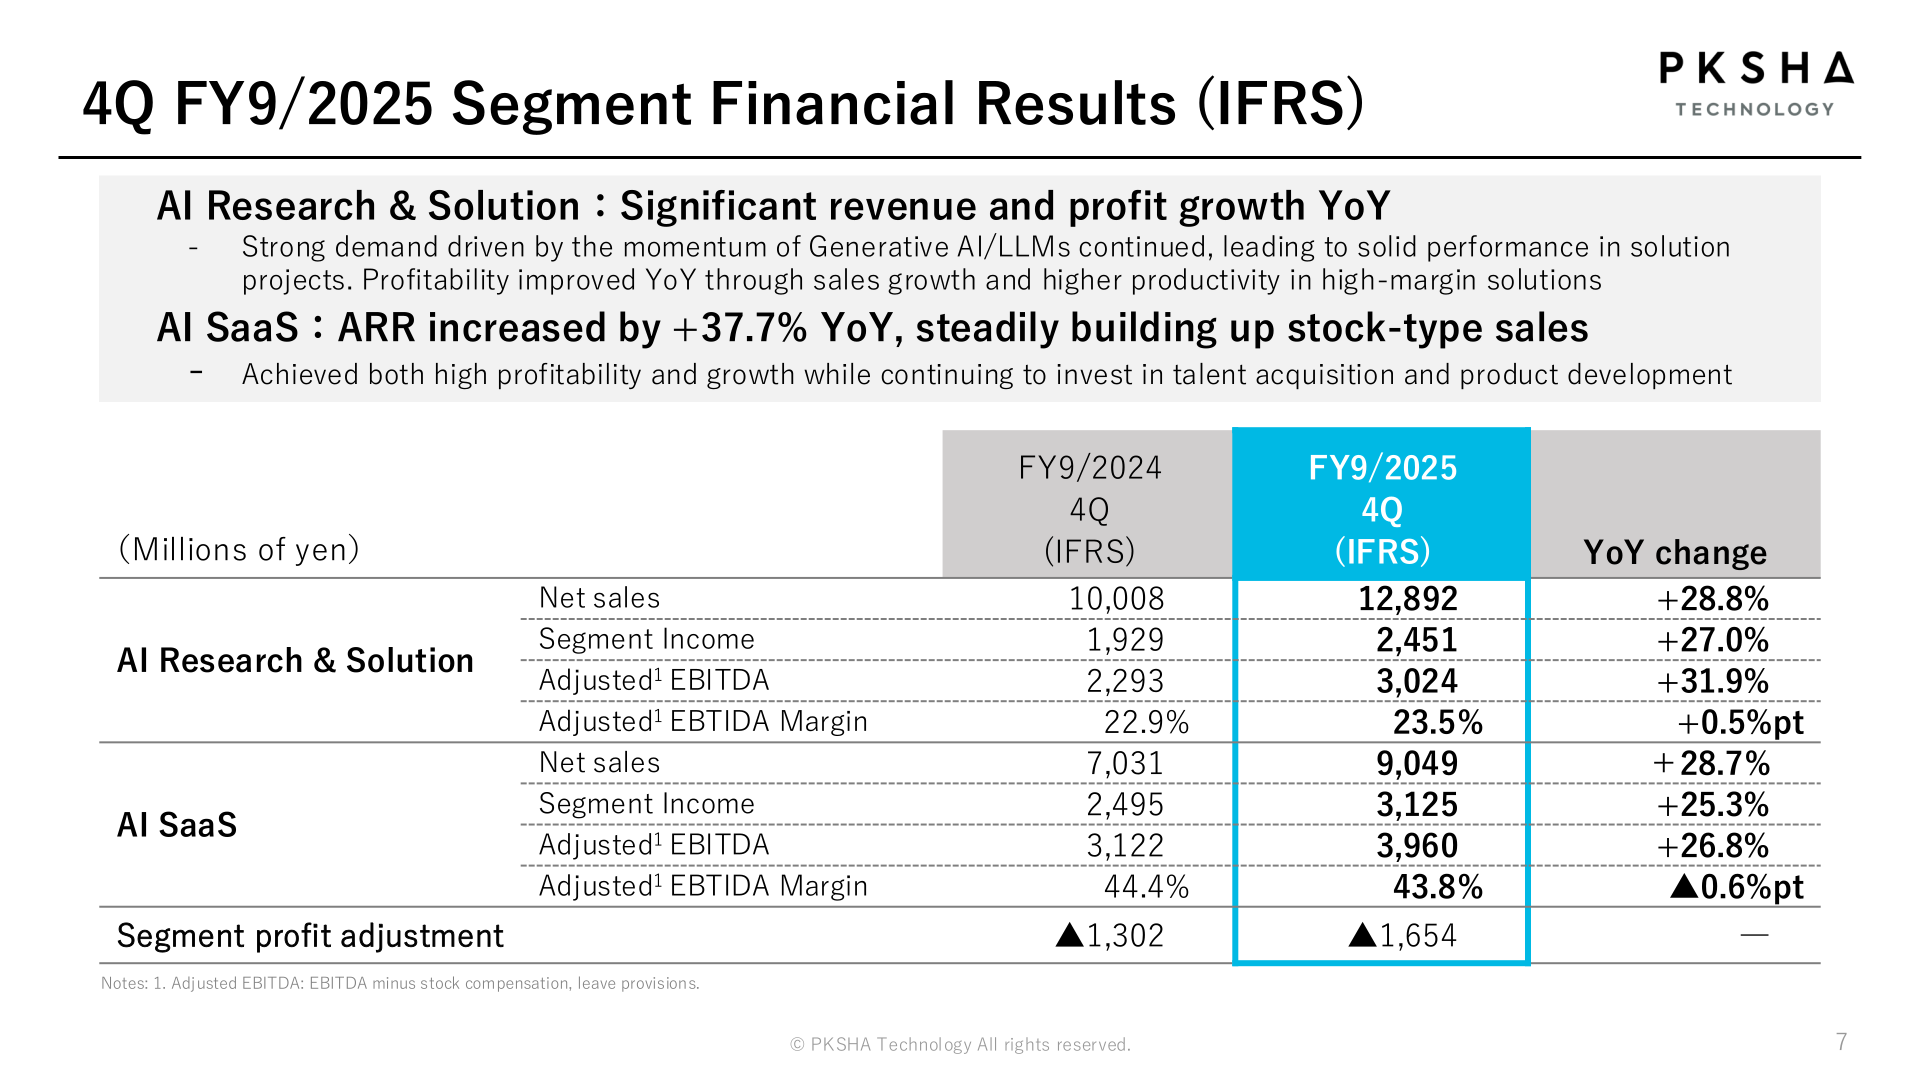
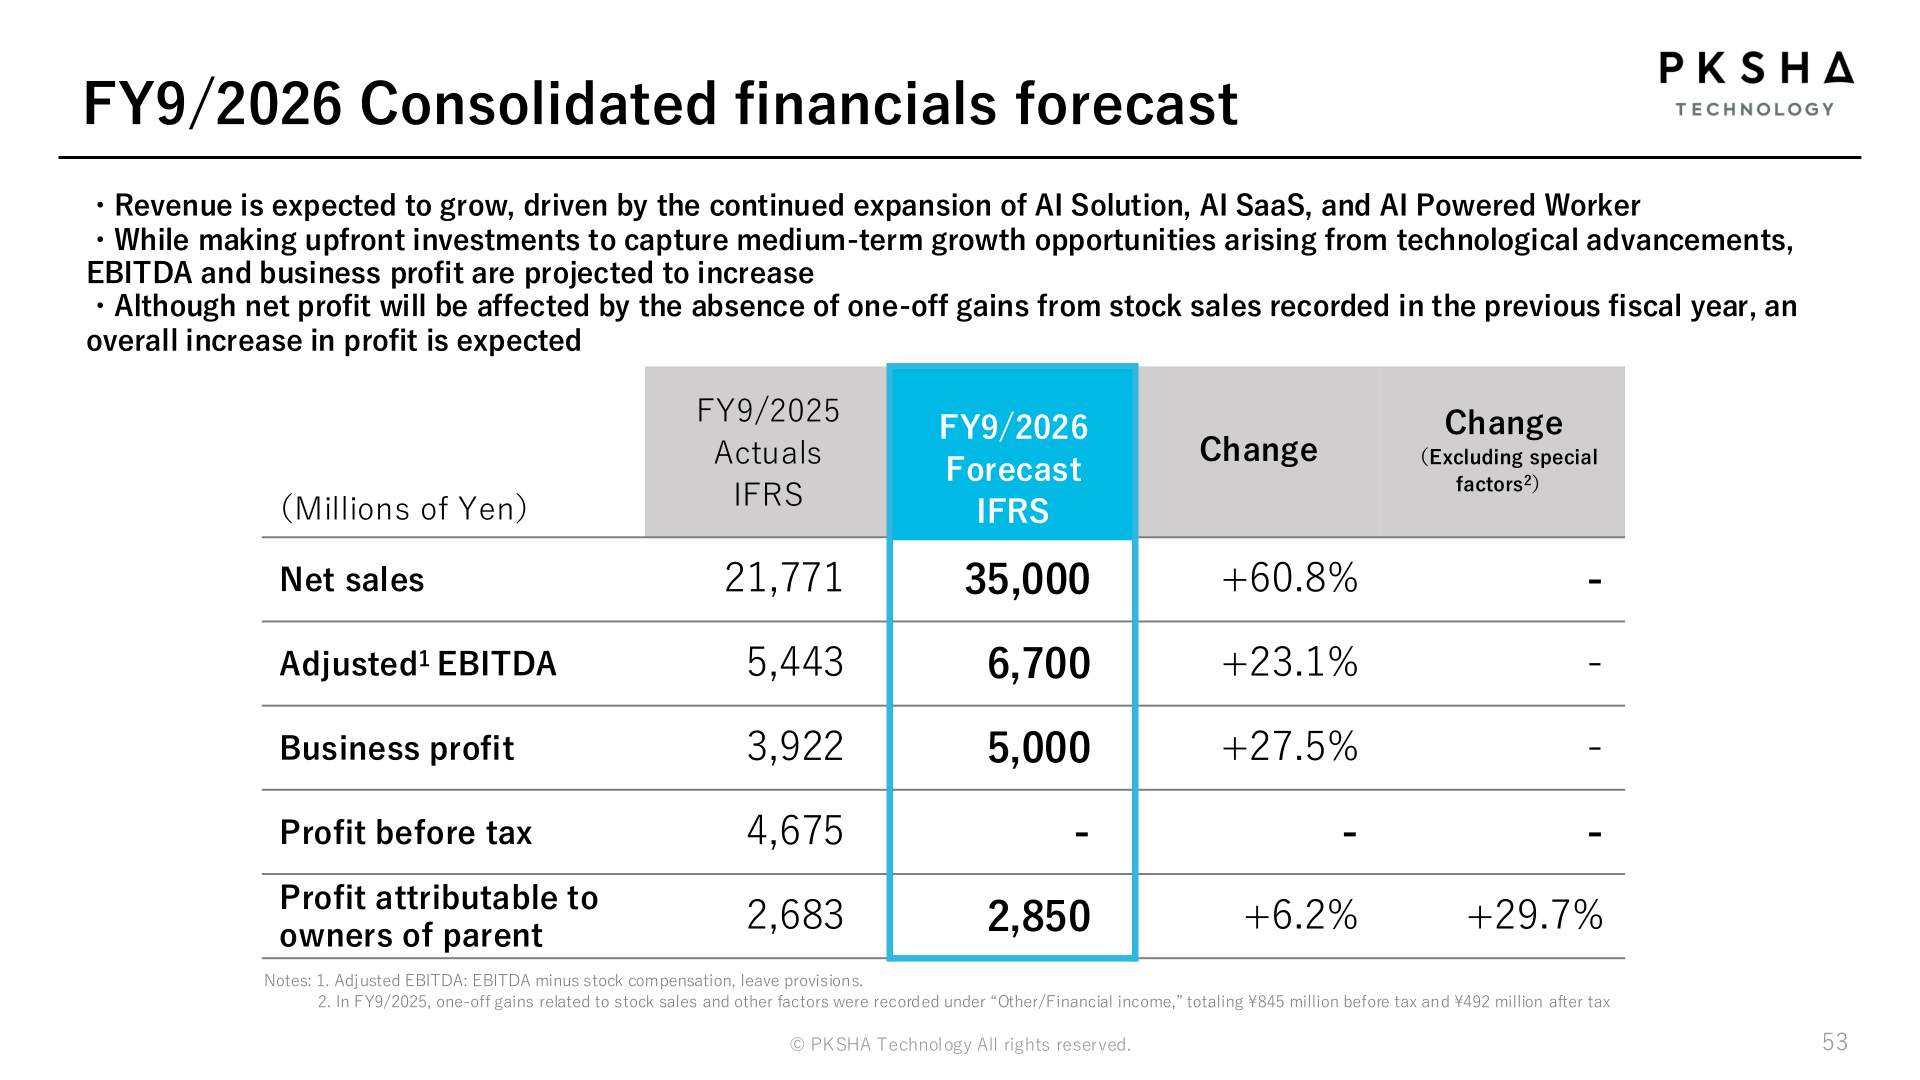
For FY9/2026, the company forecasts net sales of 35,000 million yen (+60.8%), adjusted EBITDA of 6,700 million yen (+23.1%), business profit of 5,000 million yen (+27.5%) and profit attributable to owners of parent of 2,850 million yen (+6.2%). Revenue is expected to grow, driven by the continued expansion of AI Solution, AI SaaS and AI Powered Worker, and EBITDA and business profit are projected to increase while the company makes upfront investments to capture medium-term growth opportunities. Net profit will be affected by the absence of one-off gains from stock sales recorded in FY9/2025 (totaling ¥845 million before tax and ¥492 million after tax); excluding these special factors, the change in profit attributable to owners of parent is +29.7%.
| Item (Millions of yen) | FY9/2026 Forecast (IFRS) | FY9/2025 Actuals (IFRS) | Change | Change (excluding special factors) |
|---|---|---|---|---|
| Net sales | 35,000 | 21,771 | +60.8% | – |
| Adjusted EBITDA | 6,700 | 5,443 | +23.1% | – |
| Business profit | 5,000 | 3,922 | +27.5% | – |
| Profit before tax | – | 4,675 | – | – |
| Profit attributable to owners of parent | 2,850 | 2,683 | +6.2% | +29.7% |
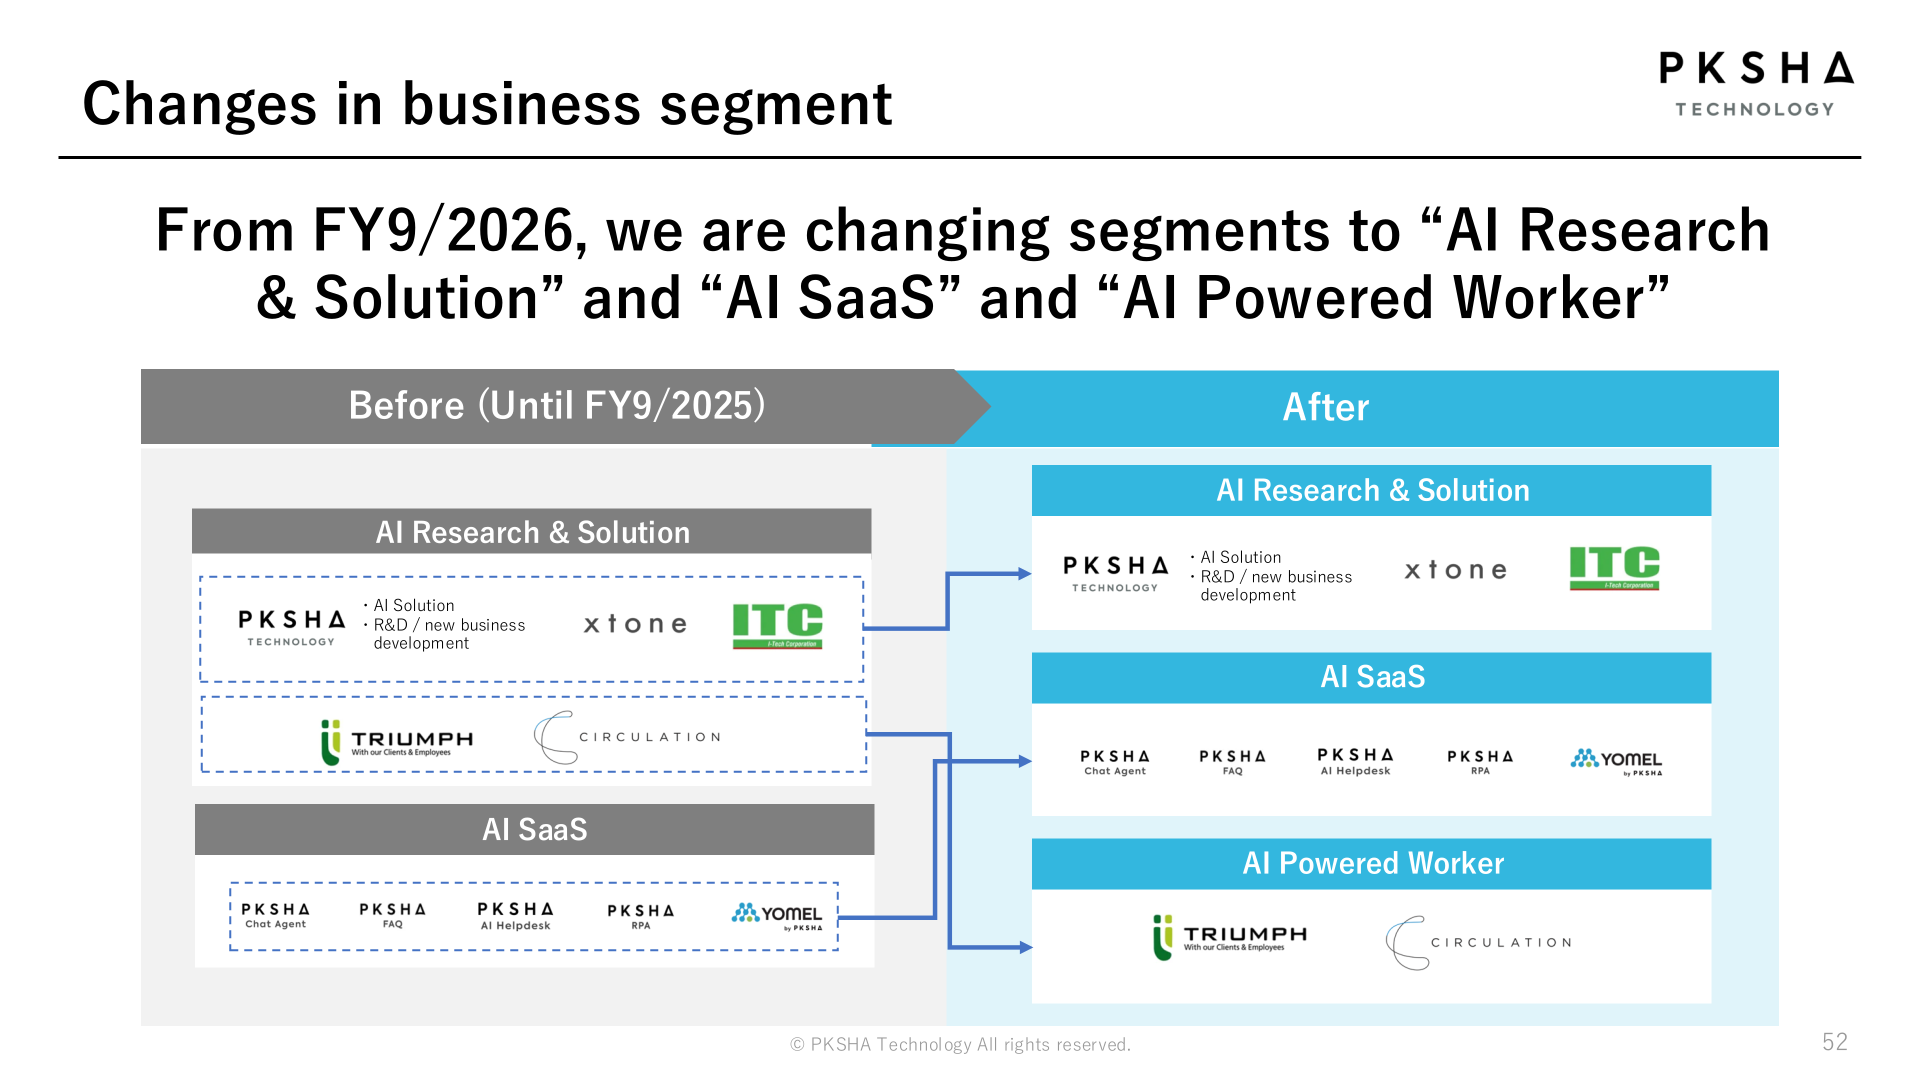
From FY9/2026, the company is changing its reporting segments from two (AI Research & Solution and AI SaaS) to three: “AI Research & Solution”, “AI SaaS” and “AI Powered Worker”. Under the new structure, TRIUMPH and Circulation move into the AI Powered Worker segment. The company describes an AI Powered Worker as a worker who leverages their experience and skills together with a wide range of AI to deliver value with significantly higher productivity.
Shareholder Returns
The presentation material does not discuss dividends, share buybacks or other shareholder return policies. This cannot be confirmed from the materials.
Business Direction and Topics
The company states that the AI market has entered a phase where AI application-building capability is critical, and that its AI delivery model has deepened and expanded into a “3 business structure (Phase3.0)”. In AI Solution, it cites continued expansion driven by AI agentization and says it is exploring expansion into the Physical AI domain. In AI SaaS, Communication AI is expanding from the contact-center (CX) domain into internal (EX) operations, and the company has created an AI Native specialist organization. Circulation Co., Ltd. joined the group in August 2025. Over the medium to long term, the company aims to scale toward ¥100bn in sales and ¥30bn in EBITDA by expanding AI-First businesses and products across all industries.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















