
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
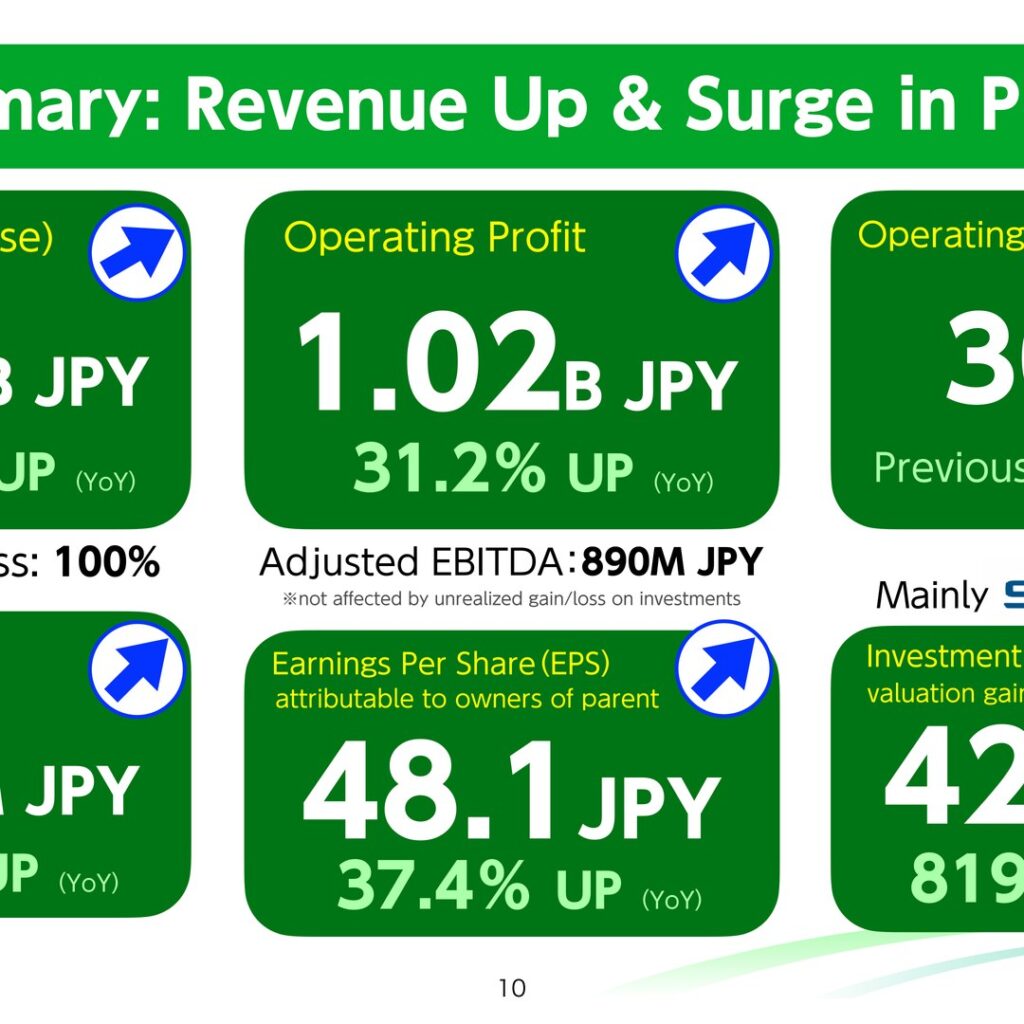
Asteria Corporation (TSE Prime: 3853), an enterprise software product company, reported IFRS results for FY2025 (the fiscal year ended March 2026) with revenue of 3.39B JPY (6.9% up YoY) and operating profit of 1.02B JPY (31.2% up YoY), for an operating profit margin of 30.2% (previous period: 24.6%). The company attributes the results to strong software performance, SpaceX valuation gains and more, with investment business valuation gains and losses of 420M JPY (819.1% up YoY). For FY2026 (ending March 2027) it forecasts revenue of 3,700M JPY and operating profit of 1,100M JPY, and plans to raise the year-end dividend to 10.0 JPY per share under a progressive dividend policy.
Consolidated Results (Full-Year Actual)
Revenue rose to 3,389M JPY from 3,171M JPY in the previous fiscal year, with the software business accounting for 100% of revenue. Gross profit was 2,988M JPY (previous year: 2,833M JPY), for a gross profit margin of 88%. Operating profit increased to 1,025M JPY from 781M JPY, and net profit attributable to owners of parent rose to 799M JPY from 589M JPY. On the summary slide, net profit is shown as 830M JPY (42.1% up YoY) and earnings per share attributable to owners of parent as 48.1 JPY (37.4% up YoY). Adjusted EBITDA, which is not affected by unrealized gain/loss on investments, was 890M JPY.
| Item (M JPY) | FY2025 (2026/3) | FY2024 (2025/3) | YoY |
|---|---|---|---|
| Revenue | 3,389 | 3,171 | 6.9% up |
| Gross profit | 2,988 | 2,833 | ― |
| Operating profit | 1,025 | 781 | 31.2% up |
| Operating profit margin | 30.2% | 24.6% | ― |
| Net profit attributable to owners of parent | 799 | 589 | ― |
| EPS attributable to owners of parent (JPY) | 48.1 | ― | 37.4% up |
| Adjusted EBITDA | 890 | ― | ― |
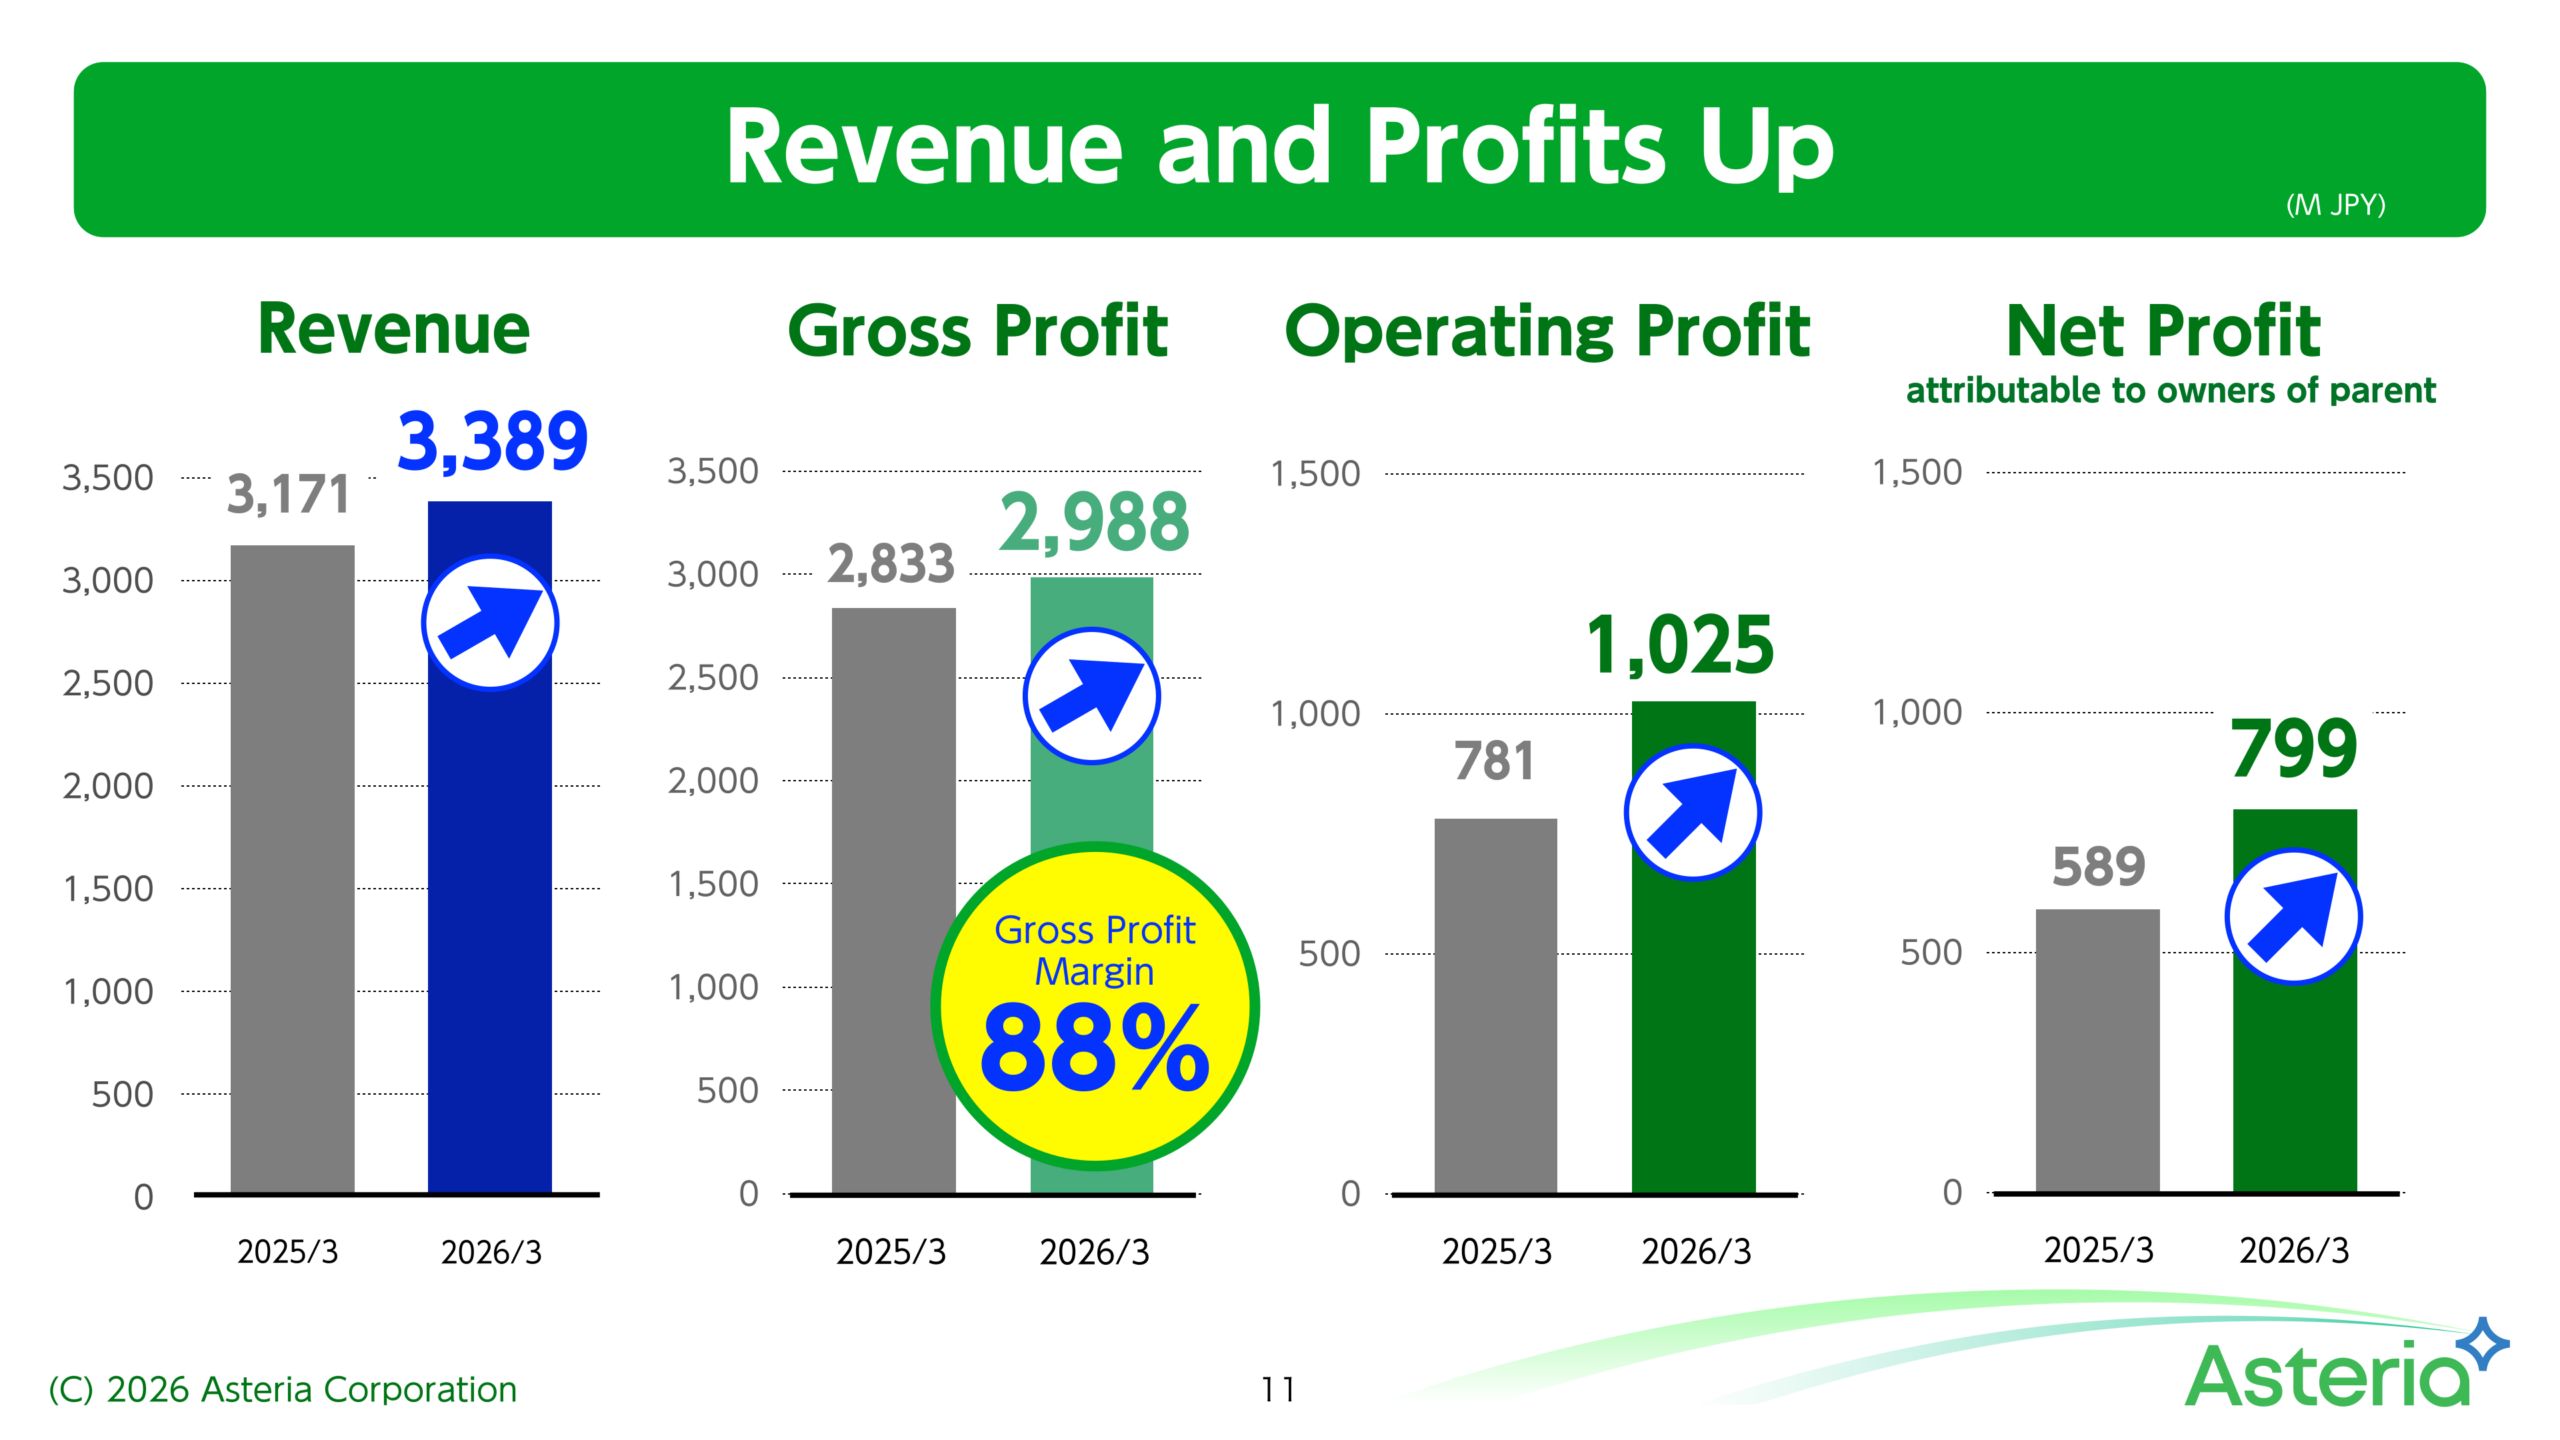
Against the company’s forecasts for the year, revenue of 3,389M JPY represented 97% achievement of the 3,500M JPY forecast, while operating profit of 1,025M JPY (forecast: 900M JPY) and net profit attributable to owners of parent of 799M JPY (forecast: 700M JPY) each reached 114% achievement. In the revenue-to-operating-profit bridge, revenue of 3,389M JPY less COGS of (401)M JPY and SG&A of (2,433)M JPY, plus investment income, etc. of 469M JPY, resulted in operating profit of 1,025M JPY. From operating profit, financial gains/losses of (51)M JPY led to pre-tax profit of 974M JPY; after corporate income taxes etc. of (143)M JPY and NCI of (32)M JPY, net profit attributable to owners of parent was 799M JPY.
SG&A expenses rose to 2,433M JPY from 2,106M JPY. By category, HR & recruitment was 1,086M JPY (44.7% of SG&A, +4.1% YoY), marketing 307M JPY (12.6%, +61.7%), R&D 275M JPY (11.3%, +16.5%), outsourcing (subcontracting fees + remuneration + transaction fees) 336M JPY (13.8%, +30.6%) and other 428M JPY (17.6%, +12.8%). The company cites Q4 product marketing and sales promotion in anticipation of investment gains, and M&A-related advisory fees, as the main reasons for the increase.
Segment Results
Asteria reports a software business and an investment business. Segment profits for FY2025 were 583M JPY in the software business and 394M JPY in the investment business. The software business accounted for 100% of revenue, while the investment business recorded valuation gains and losses of 420M JPY (819.1% up YoY), mainly related to SpaceX. Year-on-year segment profit comparisons cannot be confirmed from the materials.
| Segment | Metric | FY2025 (2026/3) | FY2024 (2025/3) |
|---|---|---|---|
| Software business | Segment profit | 583M JPY | ― |
| Software business | Share of revenue | 100% | ― |
| Investment business | Segment profit | 394M JPY | ― |
| Investment business | Valuation gains and losses | 420M JPY (819.1% up YoY) | ― |
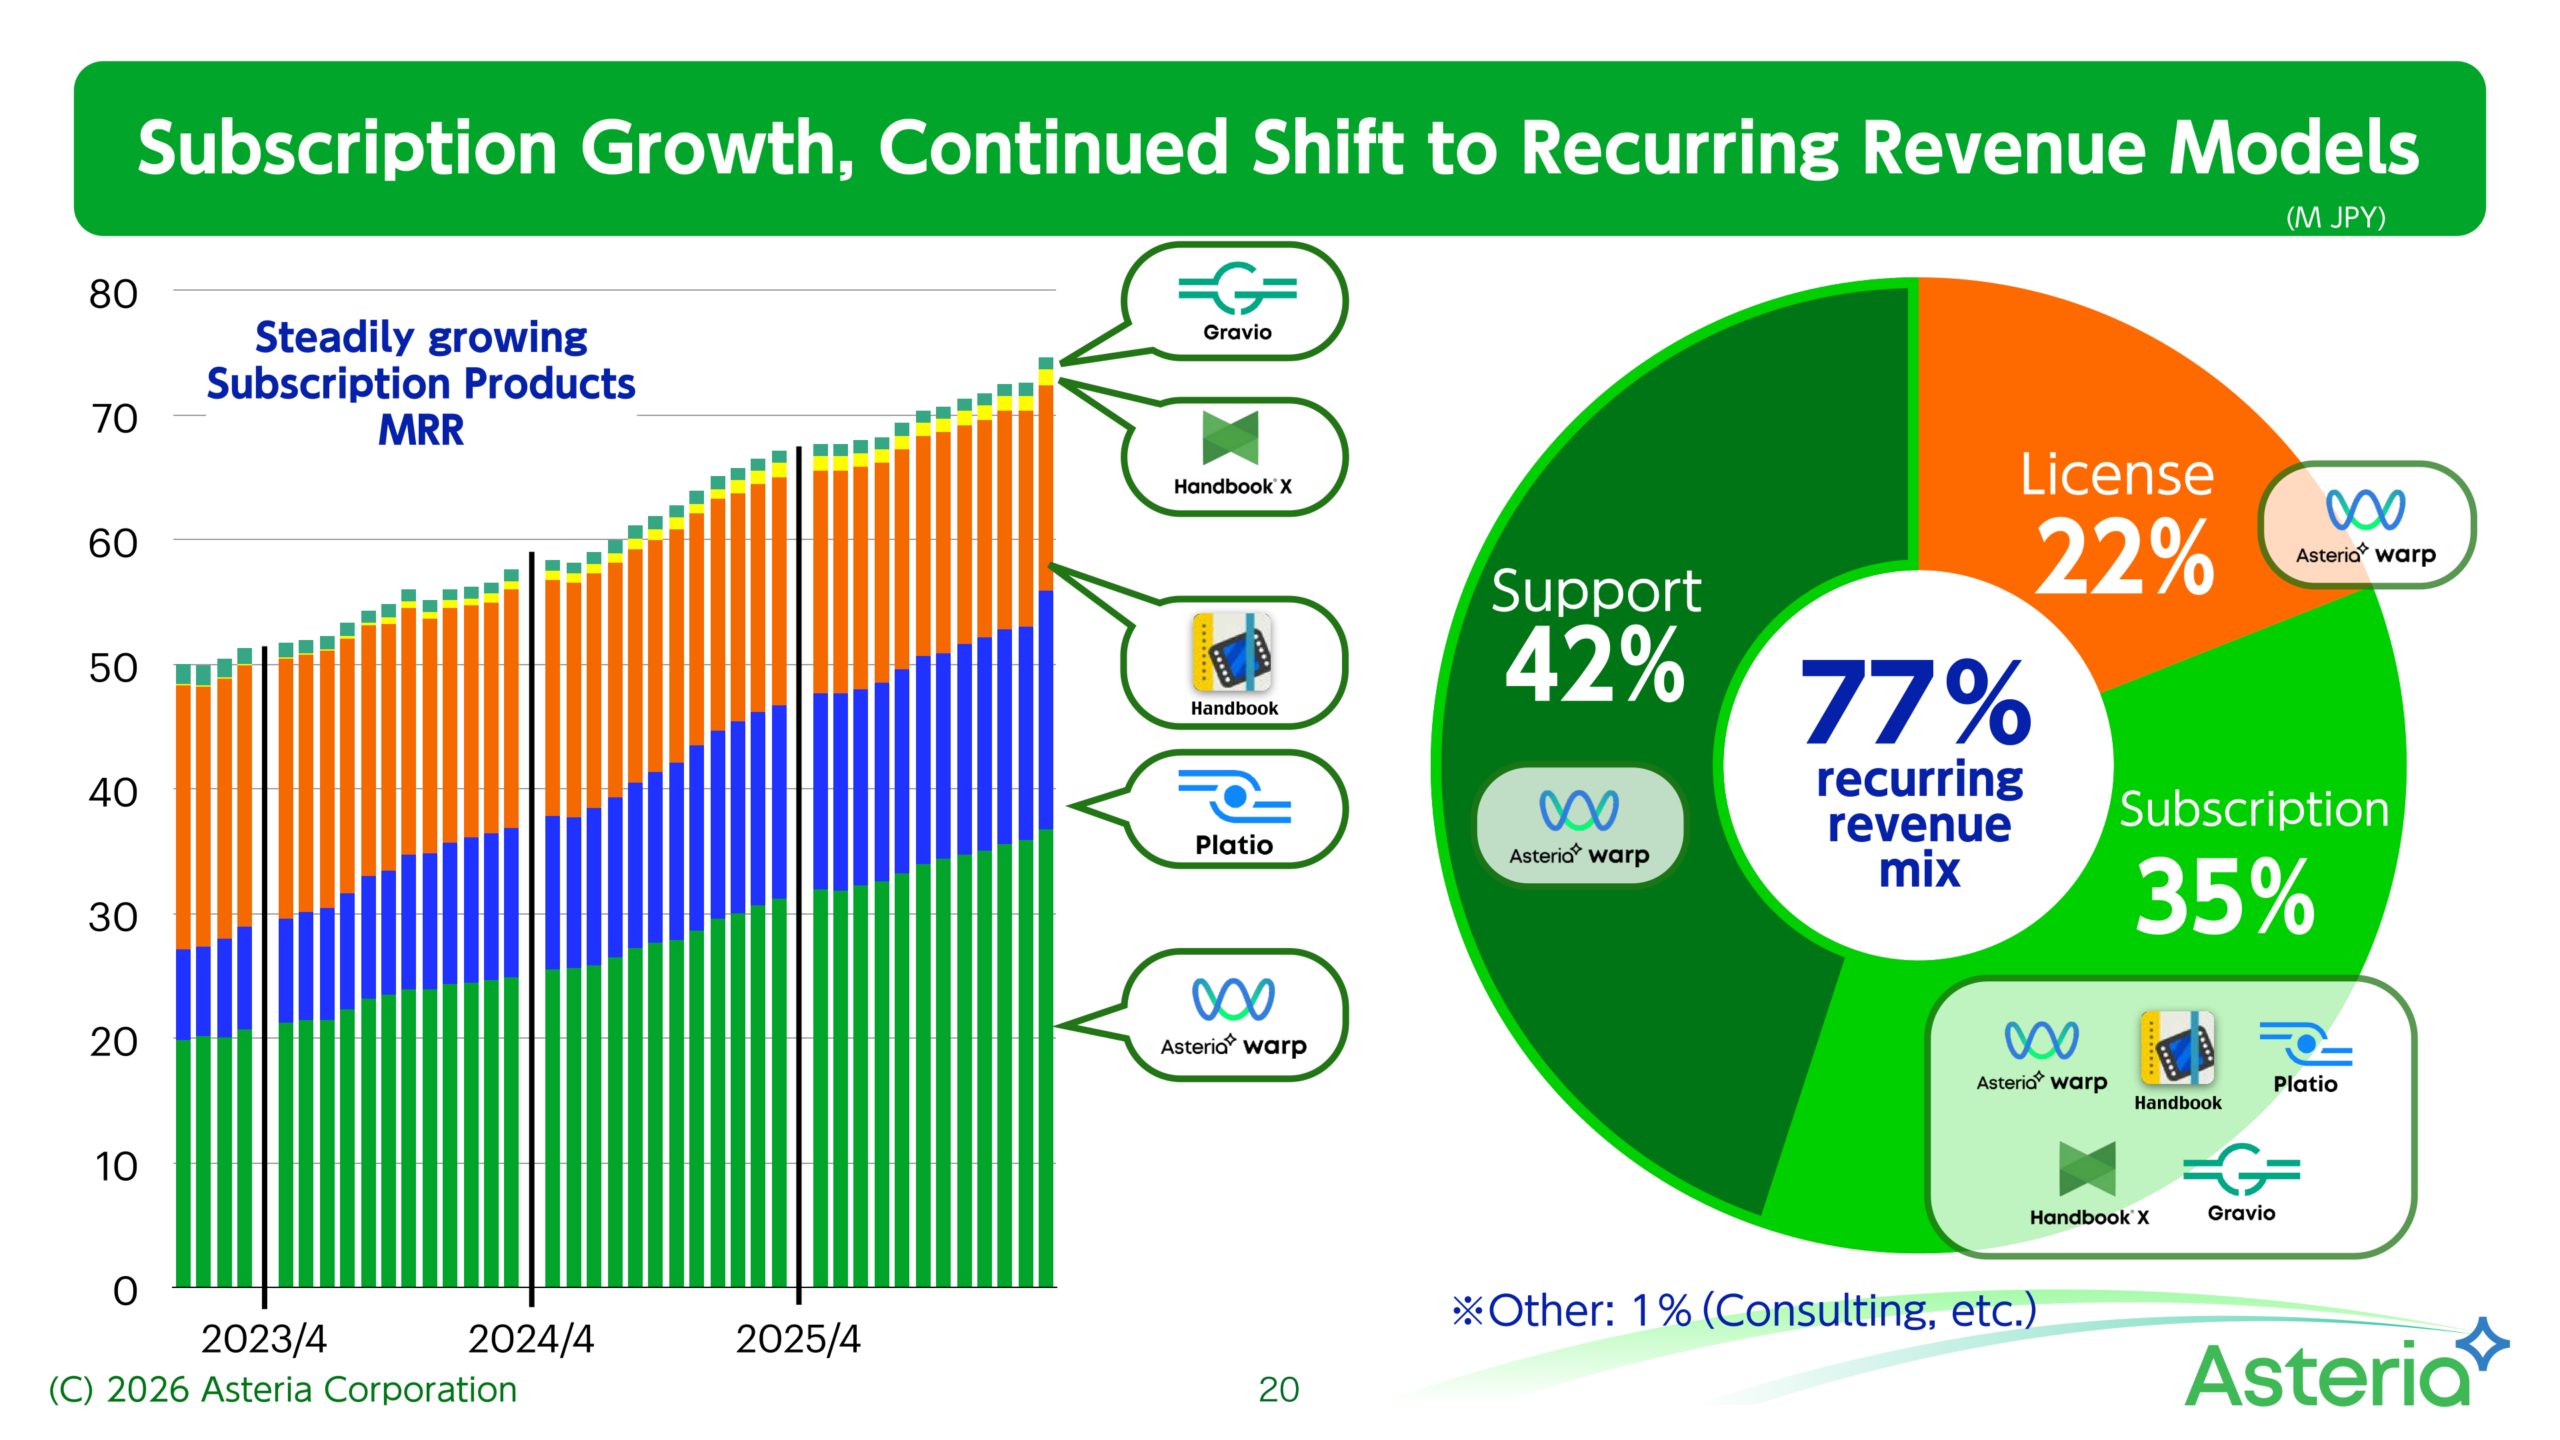
Within the software business, recurring revenue reached a 77% share of the revenue mix: support 42%, subscription 35% and license 22%, with other (consulting, etc.) at 1%. For the flagship ASTERIA Warp data integration product, adopted by more than 10,000 companies, subscription revenue rose 34% YoY, driven by an accelerating shift to subscriptions and Warp Cloud revenue expansion. Platio surpassed ARR of 200M JPY, with MRR growth driven by price increases. During the year, MikoSea joined the Group (now “Asteria Canvas Inc.”), expanding the company’s no-code portfolio.
Financial Position and Cash Flows
As of March 31, 2026, total assets were 10,595M JPY (March 2025: 7,858M JPY), total liabilities 2,645M JPY (1,618M JPY) and total equity 7,950M JPY (6,239M JPY). Cash and cash equivalents were 3,260M JPY (2,814M JPY), the equity ratio was 75% and PBR was 3.07. Investments & other assets rose to 5,385M JPY from 3,575M JPY. The company states that 1 billion yen of its cash and deposits is to be held in the stablecoin JPYC, approximately 1/3 of its cash and cash equivalents. Cash flow from operating activities was 571M JPY (FY2024: 829M JPY), cash flow from investment activities was (720)M JPY (FY2024: 772M JPY) and cash flow from financing activities was 541M JPY (FY2024: (517)M JPY).
FY2026 Forecast
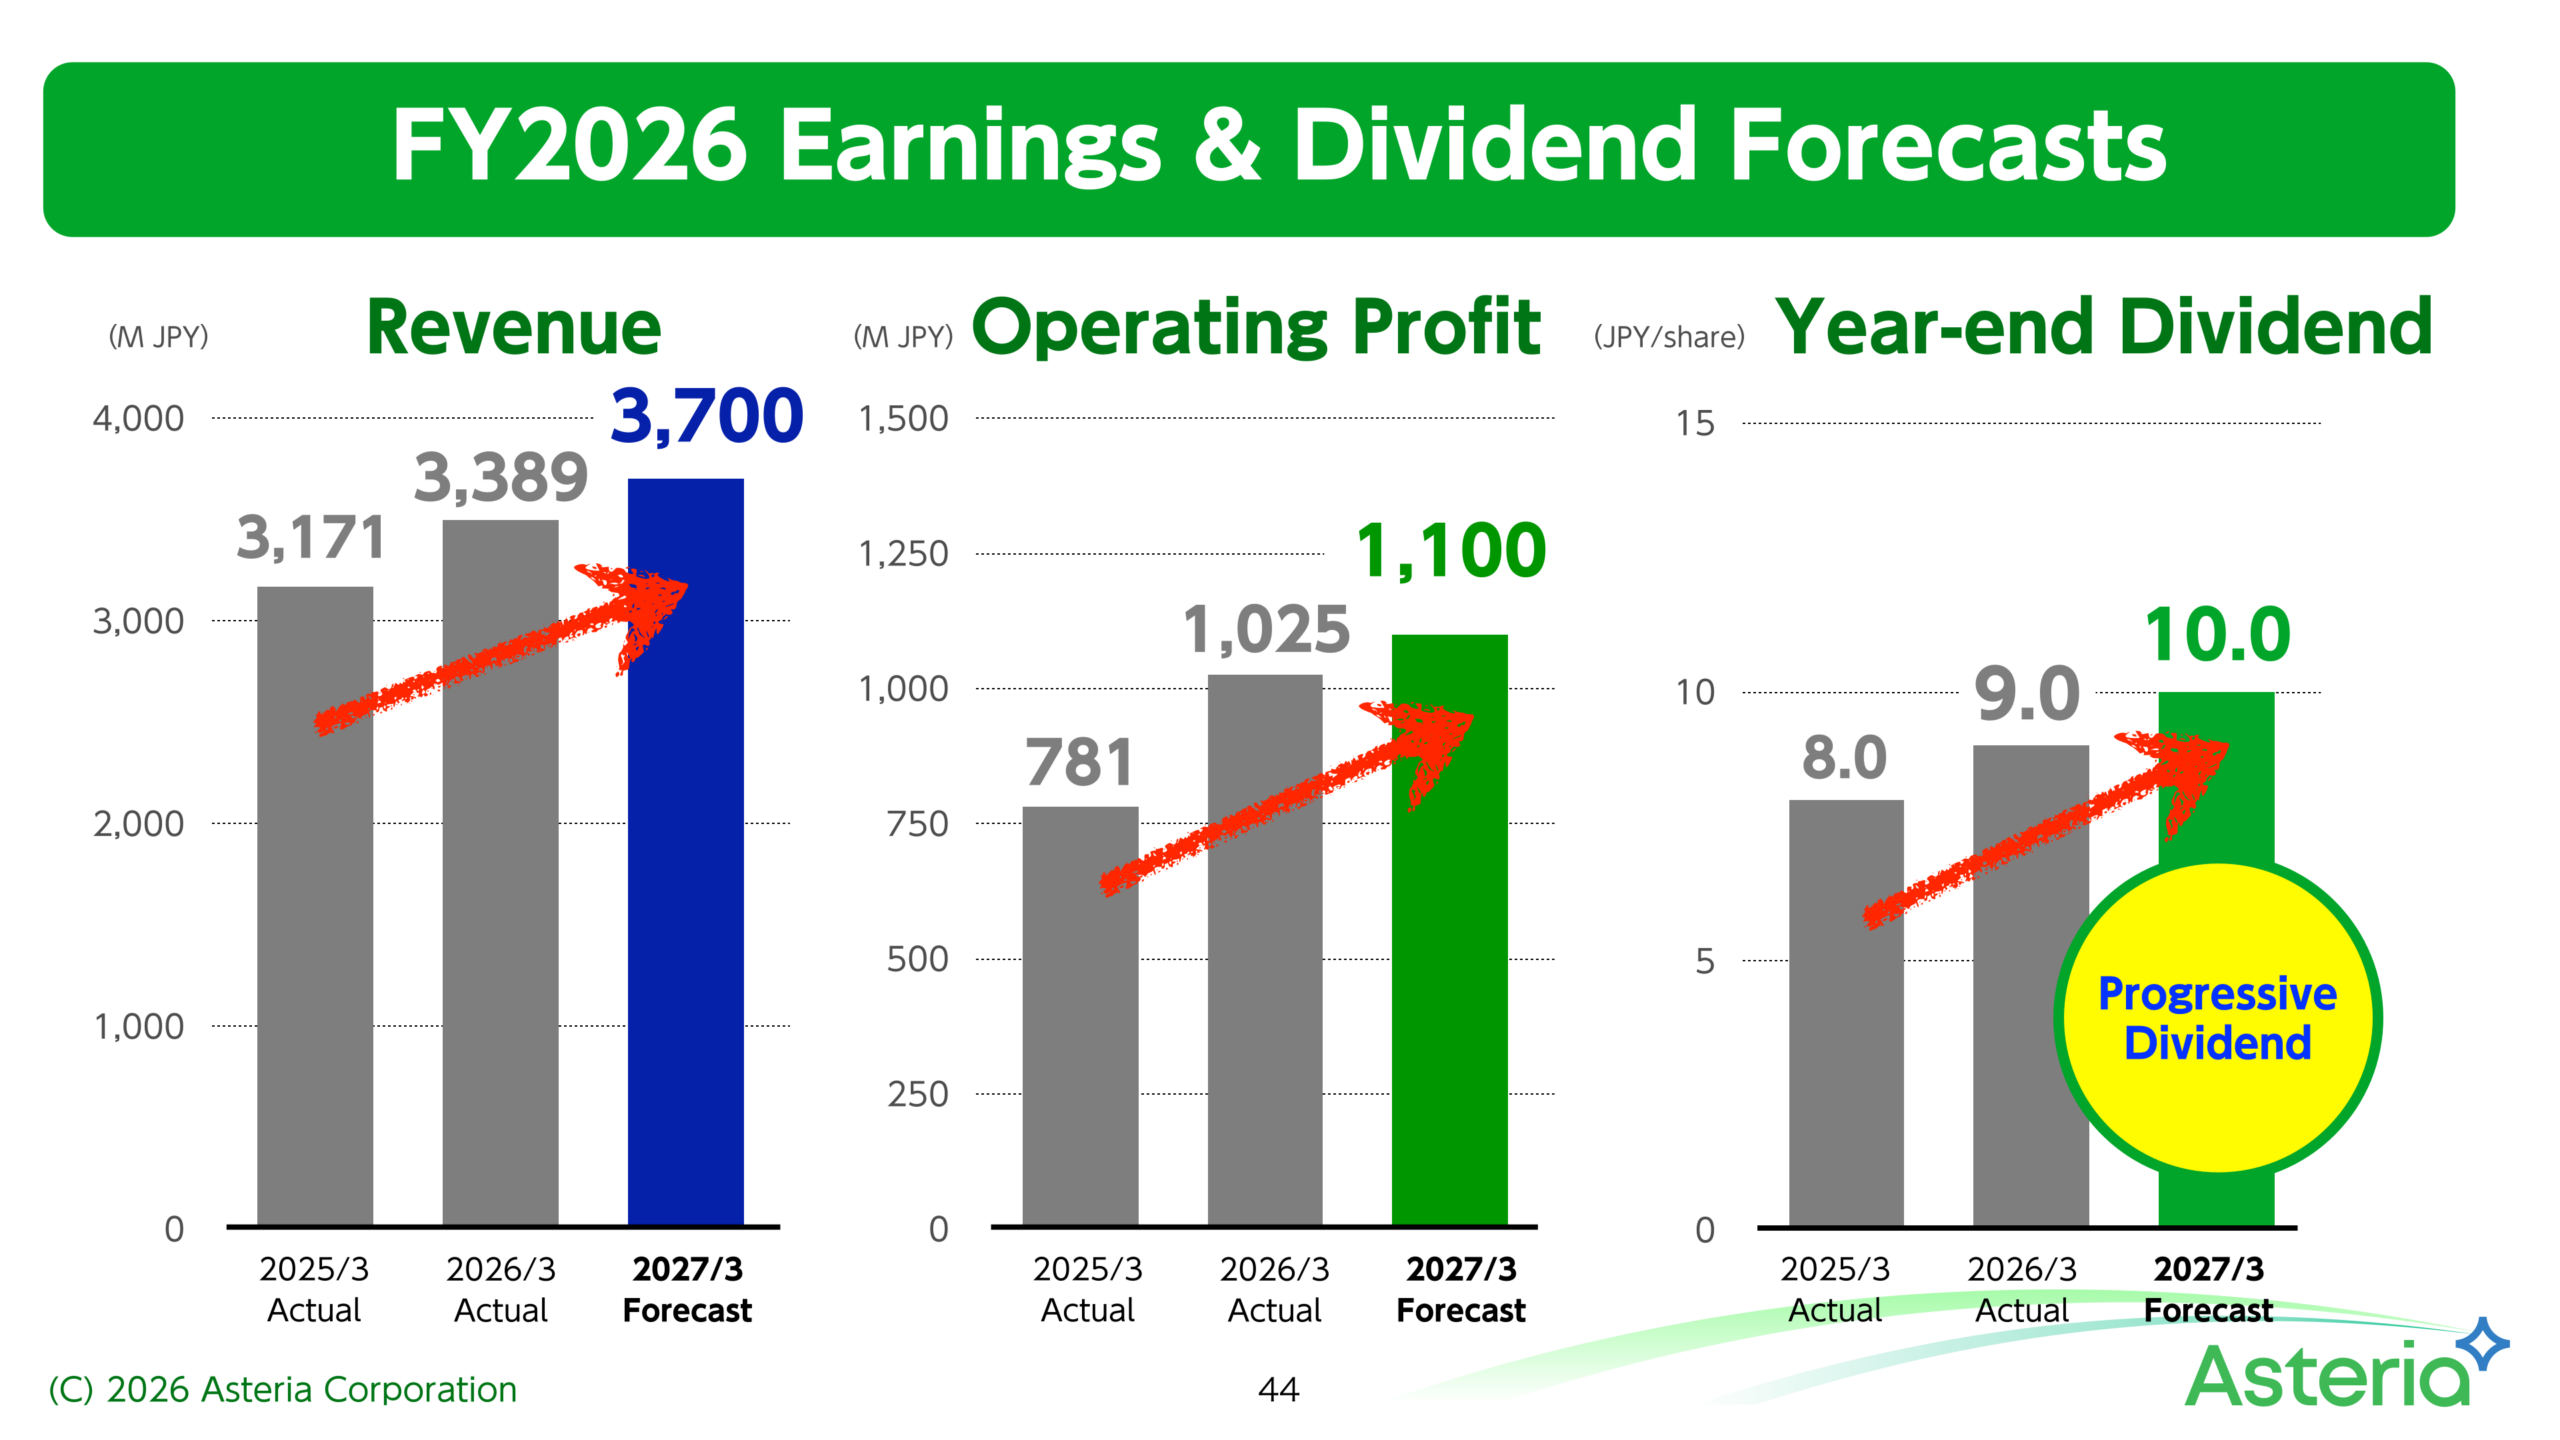
For FY2026 (ending March 2027), Asteria forecasts revenue of 3,700M JPY and operating profit of 1,100M JPY, compared with FY2025 actual results of 3,389M JPY and 1,025M JPY, respectively. A net profit forecast cannot be confirmed from the materials.
| Item | FY2026 Forecast (2027/3) | FY2025 Actual (2026/3) | FY2024 Actual (2025/3) |
|---|---|---|---|
| Revenue (M JPY) | 3,700 | 3,389 | 3,171 |
| Operating profit (M JPY) | 1,100 | 1,025 | 781 |
| Year-end dividend (JPY/share) | 10.0 | 9.0 | 8.0 |
Shareholder Returns
The year-end dividend for FY2025 was 9.0 JPY per share, up from 8.0 JPY in the previous fiscal year, and the company forecasts 10.0 JPY for FY2026 under a progressive dividend policy. Asteria has also added the stablecoin JPYC as an option in its shareholder benefit program alongside QUO cards. Benefit values depend on the number of shares owned and the length of continuous ownership: holders of 500-999 shares receive JPY 1,000 equivalent (1-3 years) or JPY 2,000 equivalent (3+ years); holders of 1,000-4,999 shares receive JPY 2,000 or JPY 3,000 equivalent; and holders of over 5,000 shares receive JPY 3,000 or JPY 5,000 equivalent.
Medium-Term Management Plan and Strategy
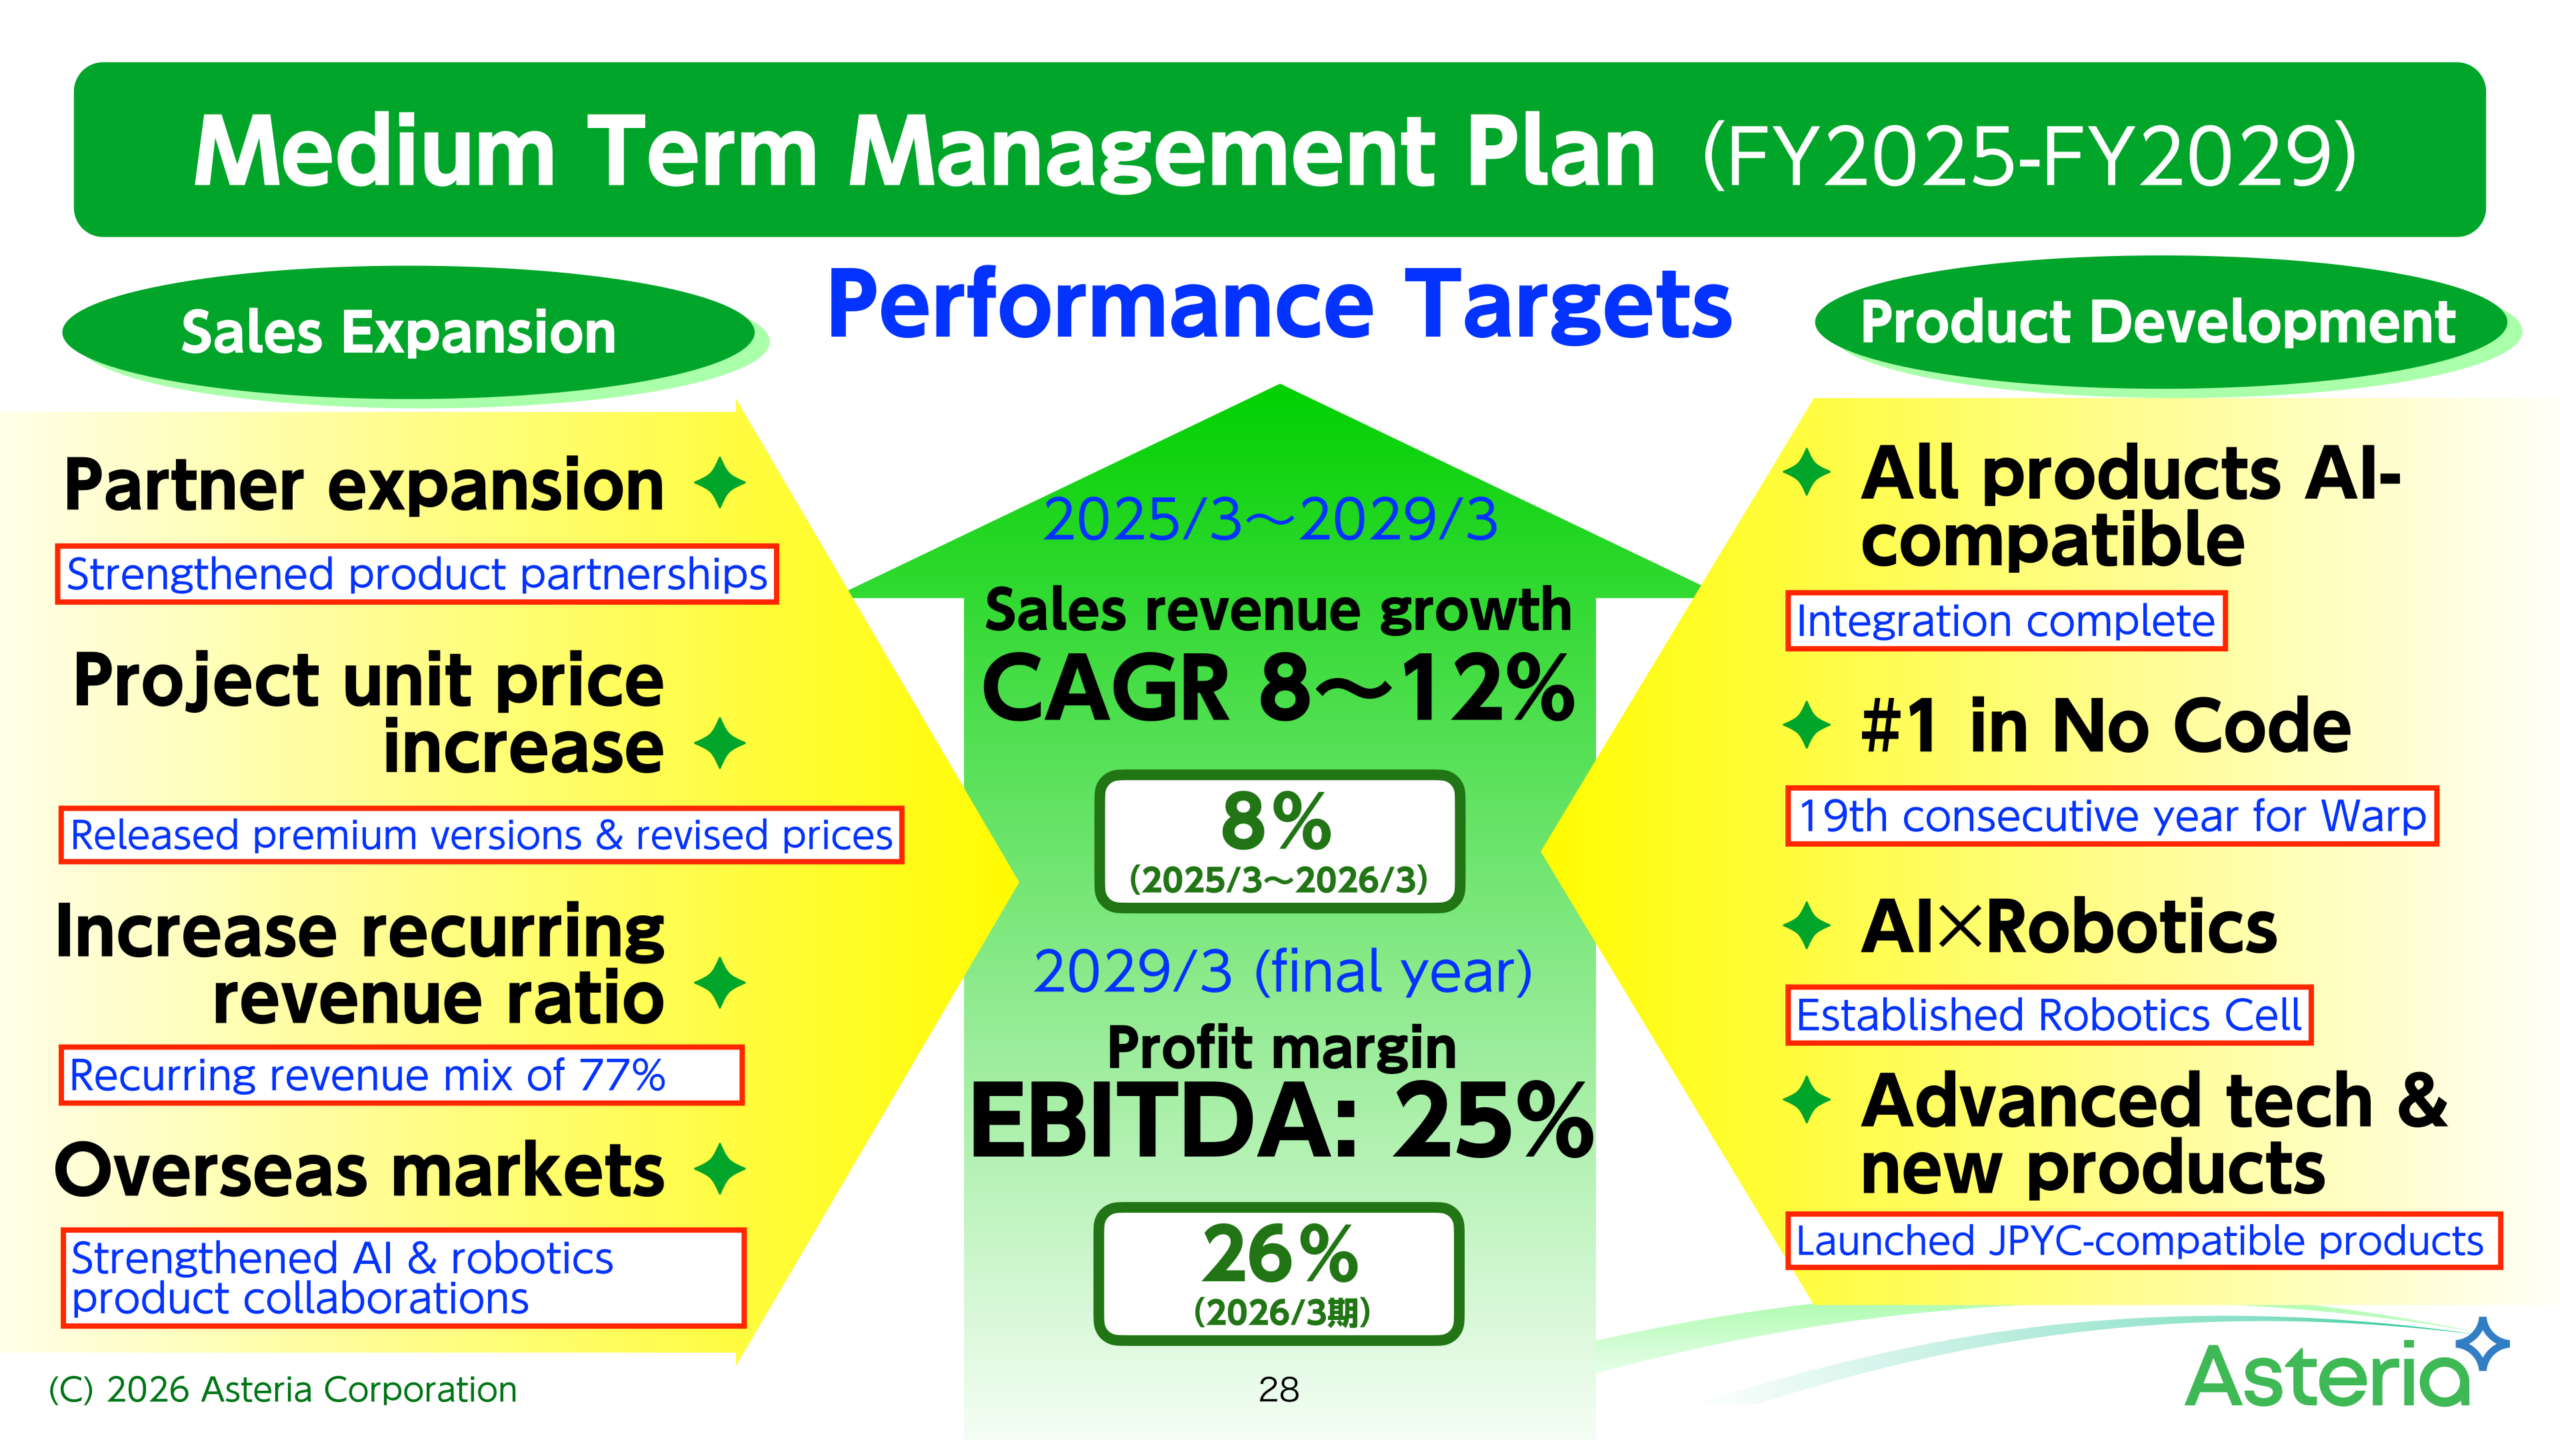
Under its Medium Term Management Plan (FY2025-FY2029), Asteria targets sales revenue growth at a CAGR of 8-12% over 2025/3-2029/3 and an EBITDA profit margin of 25% in the final year (2029/3). Results in the first year were 8% revenue growth (2025/3-2026/3) and an EBITDA margin of 26% (2026/3). Progress cited by the company includes making all products AI-compatible (integration complete), “#1 in No Code” (19th consecutive year for Warp), establishing a Robotics Cell, launching JPYC-compatible products, releasing premium versions and revising prices, and a recurring revenue mix of 77%.
As AI commoditizes software, Asteria has launched an “Asset-Hook” strategy, which seeks competitive advantage by connecting irreplaceable assets: people, physical assets such as robots and equipment, and institutional systems such as regulations and payment infrastructure. To pursue this, the company established cell-based organizational units: a Stablecoin Cell (March 2026), and a Physical AI Cell and a Robotics Cell (April 2026). In stablecoins, Asteria positions itself as a hub connecting individuals and businesses to stablecoins through apps, data integration and stablecoins, and is driving JPYC treasury adoption with holdings of 1B JPY.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















