
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Yossix Holdings does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials, with figures transcribed as reported. The company’s materials label the period as the fiscal year ended March 2026; on this site it is classified as FY2025 (the most recently completed full year), while the body, tables and figures keep the labels used in the materials.
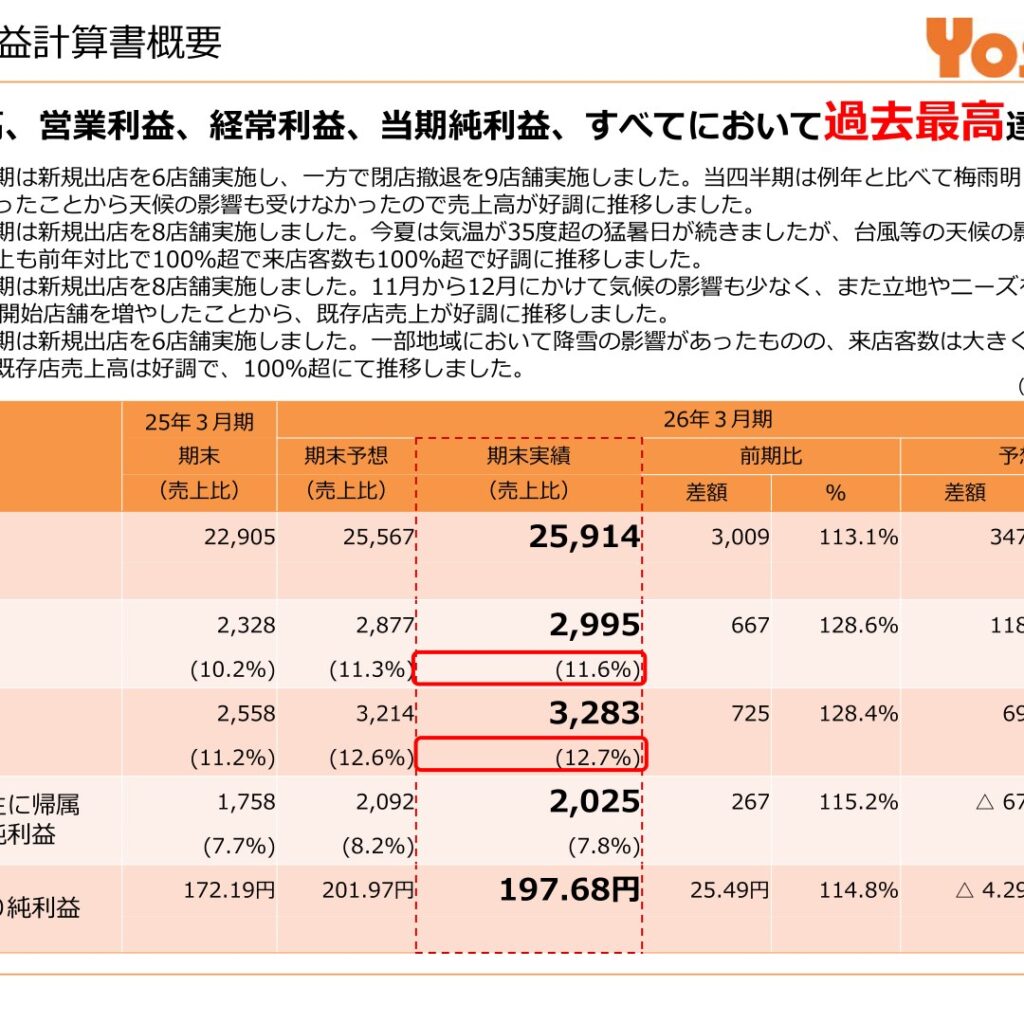
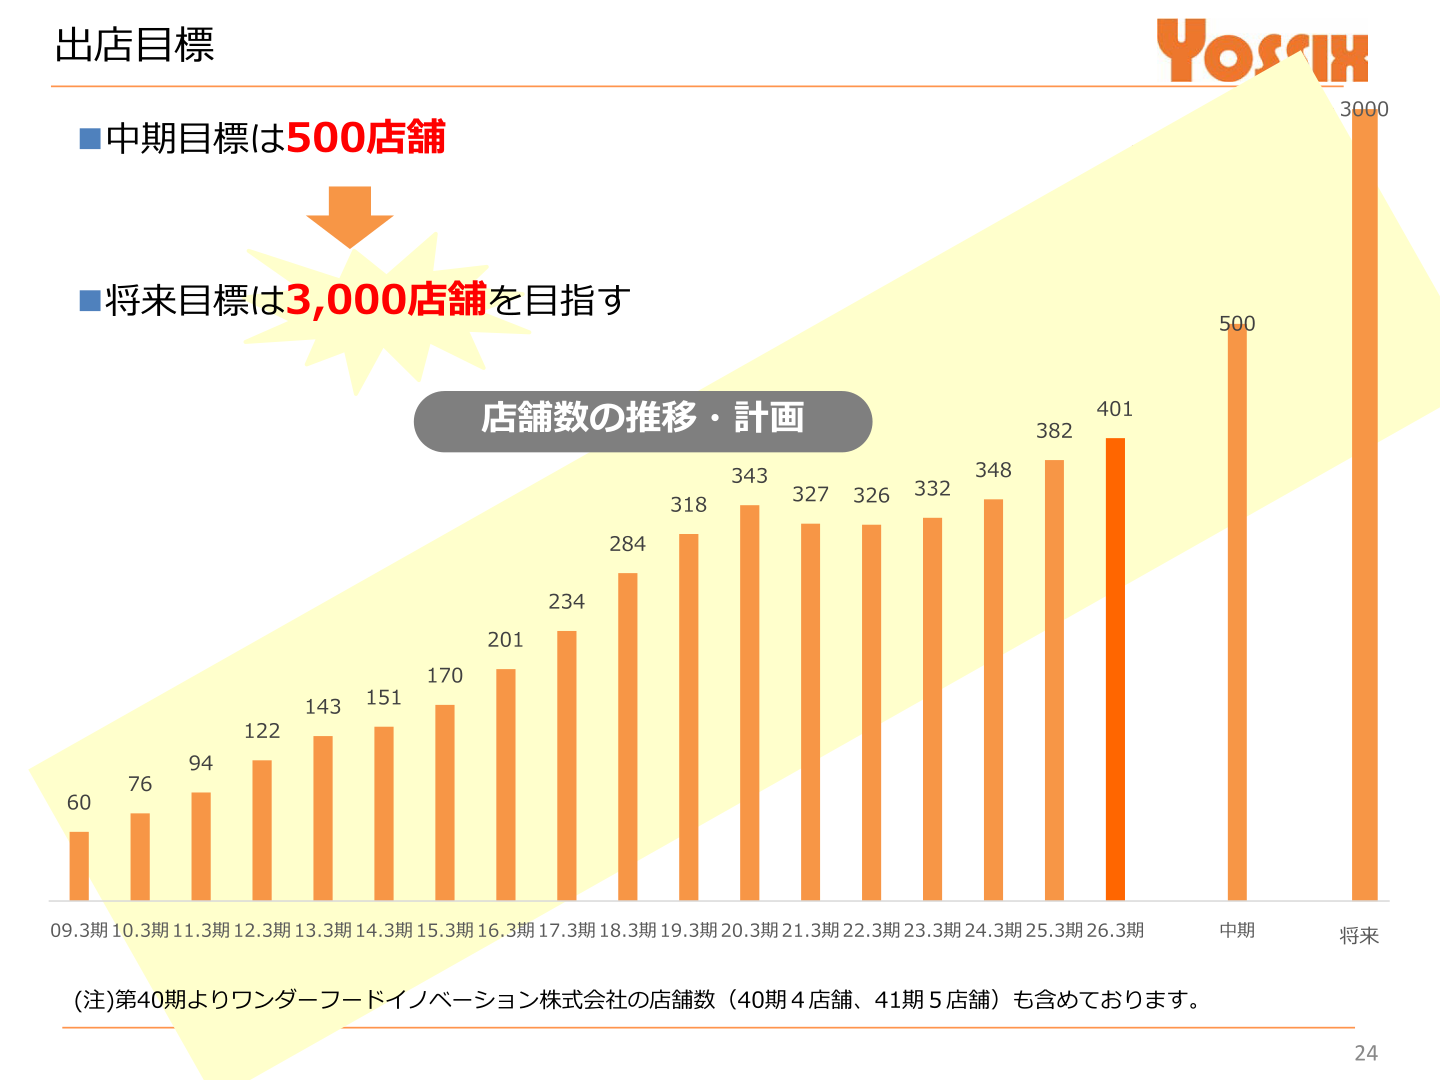
Yossix Holdings Co., Ltd. posted consolidated results for the fiscal year ended March 2026 of net sales of 25,914 million yen (113.1% of the prior year), operating profit of 2,995 million yen (128.6%), ordinary profit of 3,283 million yen (128.4%), and profit attributable to owners of parent of 2,025 million yen (115.2%). The materials state that record highs were achieved in net sales, operating profit, ordinary profit, and net income across the board. With relatively few weather-related factors, same-store sales ran above the prior year throughout all four quarters, driving the increases in both sales and profit. The company opened 28 new stores and closed or withdrew from 9, bringing the number of stores to 401 (as of March 31, 2026).
Consolidated Results (Full Year)
In the first quarter, the early end of the rainy season made the period less susceptible to weather effects; in the second and third quarters, the impact of extreme heat and typhoons was small, and both same-store sales and customer counts ran above 100% of the prior year; in the fourth quarter, although some regions were affected by snowfall, customer counts did not decline significantly. As a result, sales increased for the full year. While the prices of ingredients, personnel costs, and utilities continued to rise, the company maintained and improved its cost-of-sales ratio through regular price revisions of its izakaya menu (implemented four times a year) and the use of its procurement routes, and secured profit growth by absorbing the higher costs with the increase in sales.
| Item | FY ended Mar 2026 (Actual) | FY ended Mar 2025 (Actual) | YoY |
|---|---|---|---|
| Net sales | 25,914 million yen | 22,905 million yen | 113.1% (+3,009 million yen) |
| Operating profit | 2,995 million yen (11.6%) | 2,328 million yen (10.2%) | 128.6% (+667 million yen) |
| Ordinary profit | 3,283 million yen (12.7%) | 2,558 million yen (11.2%) | 128.4% (+725 million yen) |
| Profit attributable to owners of parent | 2,025 million yen (7.8%) | 1,758 million yen (7.7%) | 115.2% (+267 million yen) |
| Net income per share | 197.68 yen | 172.19 yen | 114.8% (+25.49 yen) |
Results by Business Format
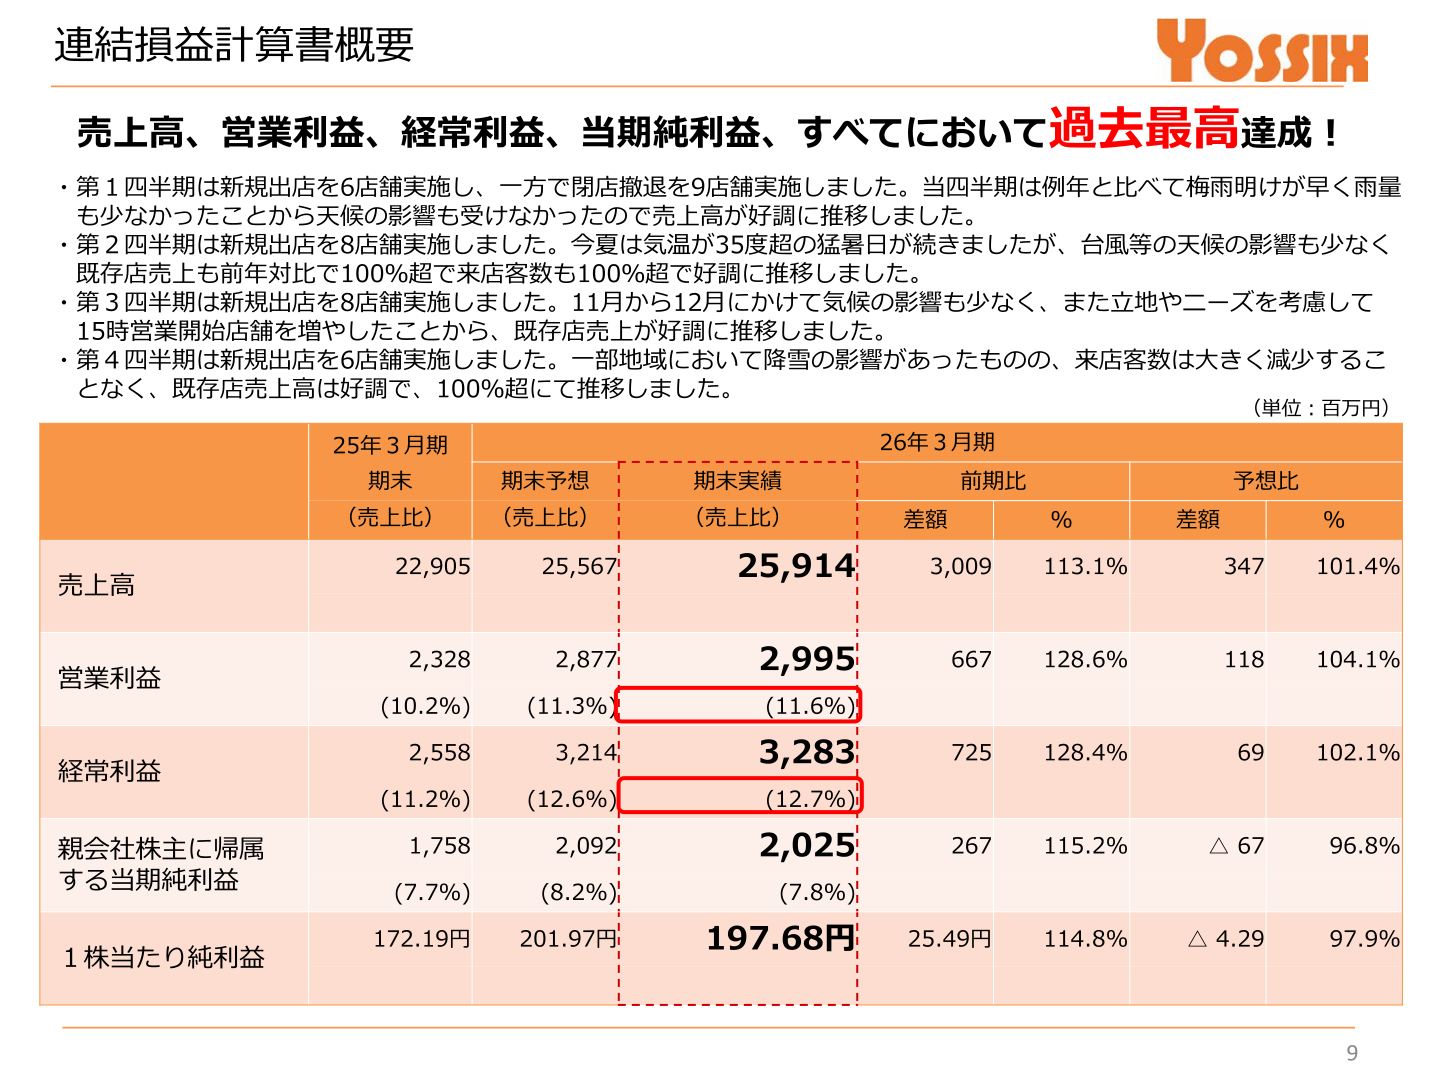
The group’s core business format is Yatazushi. Of the 396 stores as of the end of the fiscal year ended March 2026, Yatazushi (including 2 franchise stores) accounted for 363 stores, or 92% of the total. In addition, the company operates the okonomiyaki and teppanyaki izakaya Nipachi, the Osaka-style and kushikatsu izakaya Koreya, Hitokuchi Gyoza no Itadaki, and other formats.
| Business Format | Number of Stores | Share |
|---|---|---|
| Yatazushi (incl. 2 franchise stores) | 363 | 92% |
| Nipachi (incl. Nipachi) | 11 | 3% |
| Yataya | 1 | 0% |
| Koreya | 2 | 0% |
| Hitokuchi Gyoza no Itadaki | 15 | 4% |
| Other | 4 | 1% |
Store Network Development
From the 35th term to the 41st term (fiscal year ended March 2026), the number of stores increased from 343 to 401. During the period, the company opened 28 new stores (20 Yatazushi, 6 Hitokuchi Gyoza no Itadaki, 1 Ebi-dote Shokudo (M&A), and 1 Hanaka) while closing or withdrawing from 9 stores (1 of which was a franchise).
| Term | Number of Stores |
|---|---|
| 35th term | 343 |
| 36th term | 327 |
| 37th term | 326 |
| 38th term | 332 |
| 39th term | 348 |
| 40th term | 382 |
| 41st term | 401 |
Full-Year Forecast
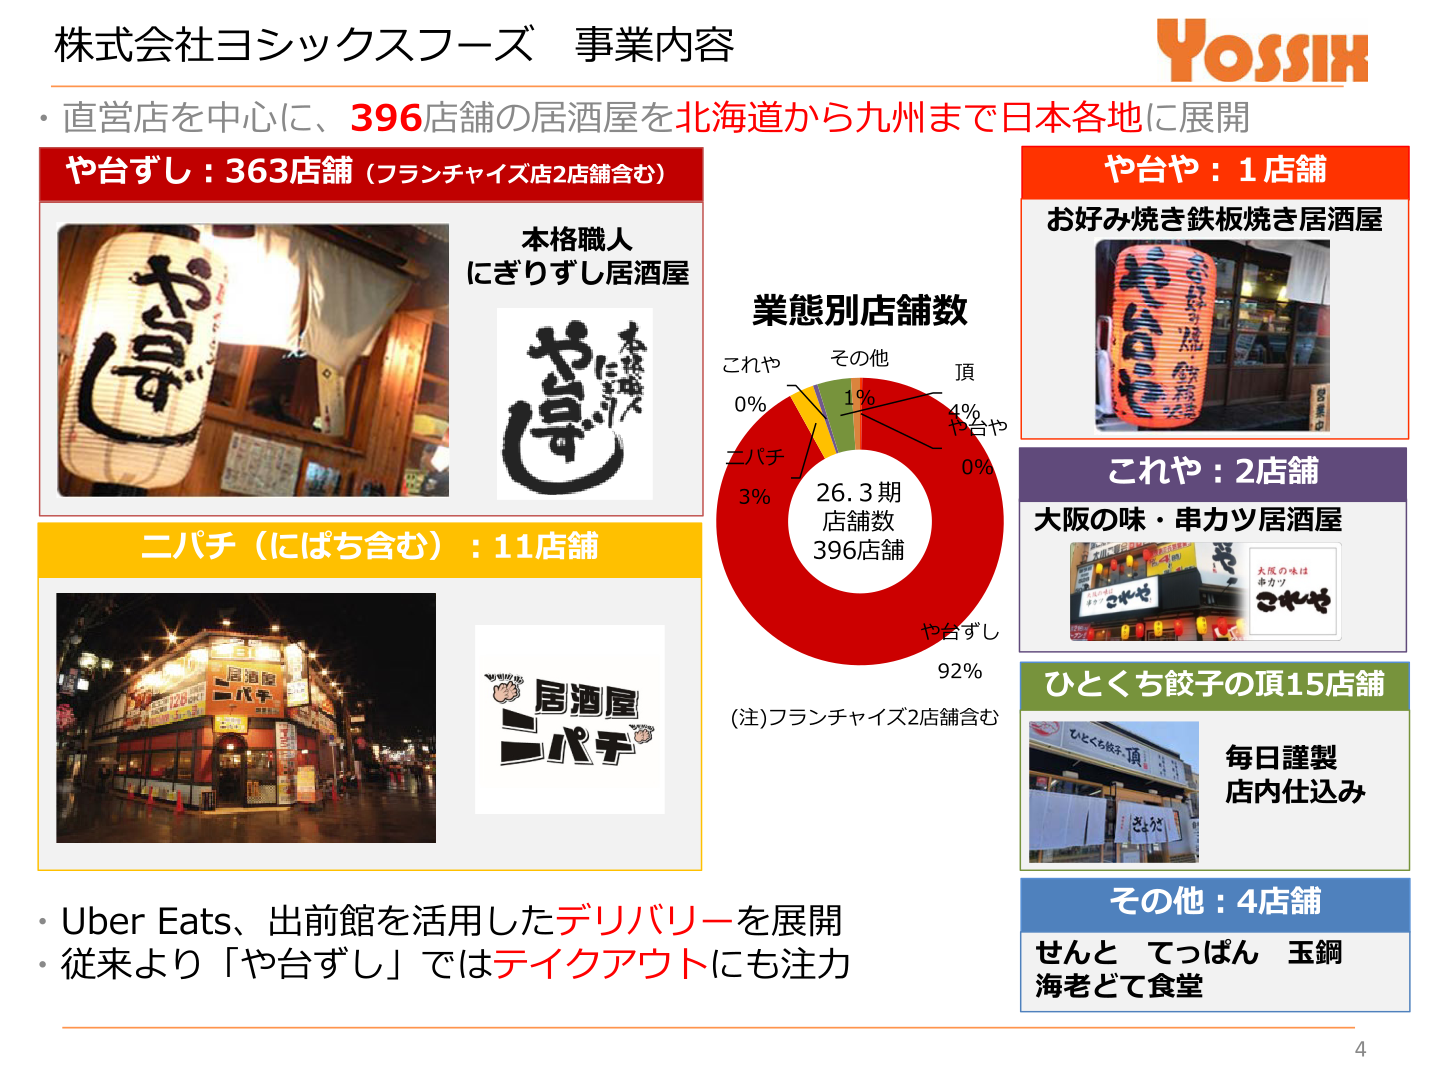
For the fiscal year ending March 2027, the company plans net sales of 28,549 million yen (110.2% of the prior year), operating profit of 3,128 million yen (104.4%), ordinary profit of 3,445 million yen (104.9%), and profit attributable to owners of parent of 2,359 million yen (116.5%), projecting increases in both sales and profit. While planning 35 new store openings, it expects the operating profit margin and ordinary profit margin to decline slightly owing to rising ingredient prices and increased personnel costs.
| Item | FY ending Mar 2027 (Forecast) | FY ended Mar 2026 (Actual) | YoY |
|---|---|---|---|
| Net sales | 28,549 million yen | 25,914 million yen | 110.2% (+2,635 million yen) |
| Operating profit | 3,128 million yen (11.0%) | 2,995 million yen (11.6%) | 104.4% (+133 million yen) |
| Ordinary profit | 3,445 million yen (12.1%) | 3,283 million yen (12.7%) | 104.9% (+162 million yen) |
| Profit attributable to owners of parent | 2,359 million yen (8.3%) | 2,025 million yen (7.8%) | 116.5% (+334 million yen) |
| Net income per share | 230.10 yen | 197.68 yen | 116.4% (+32.42 yen) |
Shareholder Returns
These materials contain no information regarding shareholder returns such as dividends or share buybacks.
Medium-Term Plan / Topics
As medium-term targets, the company has set an ordinary profit margin of over 10%, 500 stores, and net sales of 30.0 billion yen, and its policy is to expand its business around the Inaka (rural) Strategy, which involves opening small and mid-sized directly-managed stores in prime-1.5 and prime-2 locations in front of stations with 6,000 or more boarding passengers, and the Established-Store Theory, which involves low-cost store openings via small and mid-sized directly-managed stores of about 30 to 40 tsubo. As longer-term targets, it aims for 3,000 stores and net sales of 180.0 billion yen. As topics, in addition to opening a new format, Tamagane, in Nagoya to address entertainment and inbound demand, the company began operating the shrimp-fry specialty store Ebi-dote Shokudo as its own store as of July 1, 2025.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















