
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
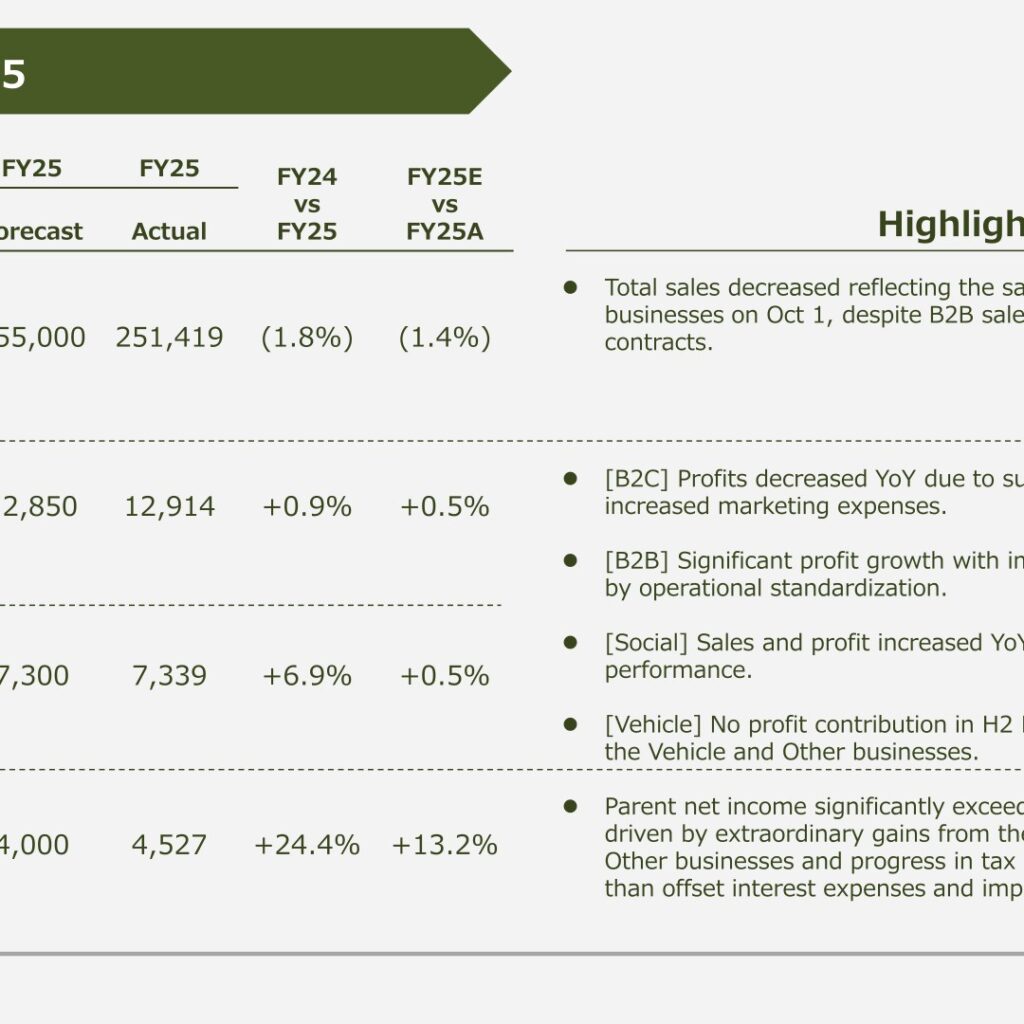
Oisix ra daichi Inc. reported FY25 (fiscal year ended March 31, 2026) sales of JPY 251.4 billion, down 1.8% YoY, while profit at all levels surpassed the previous year: EBITDA of JPY 12.9 billion (up 0.9% YoY), operating profit of JPY 7.3 billion (up 6.9% YoY), and parent net income of JPY 4.5 billion (up 24.4% YoY). The sales decline reflected the October 2025 sale of the Vehicle and Other businesses; excluding that impact, sales rose 3% and operating profit rose 21% YoY. Free cash flow turned positive at JPY 11.3 billion for the first time in five years.
Consolidated Results (Full-Year Actual)
EBITDA and operating profit met the full-year forecast despite the sales decline following the sale of the Vehicle and Other businesses, while parent net income landed 13% above the full-year forecast, driven by extraordinary gains from the sale and progress in tax optimization. The company completed a group reorganization in FY25 that included the divestiture, the merging of B2B subsidiaries, its first-ever dividend, and a treasury stock cancellation, which strengthened its financial foundation and improved EPS and ROE.
| Item (JPY MM) | FY24 Actual | FY25 Actual | YoY |
|---|---|---|---|
| Sales | 256,009 | 251,419 | (1.8%) |
| EBITDA | 12,800 | 12,914 | +0.9% |
| Operating Profit | 6,864 | 7,339 | +6.9% |
| Parent Net Income | 3,638 | 4,527 | +24.4% |
Segment Results
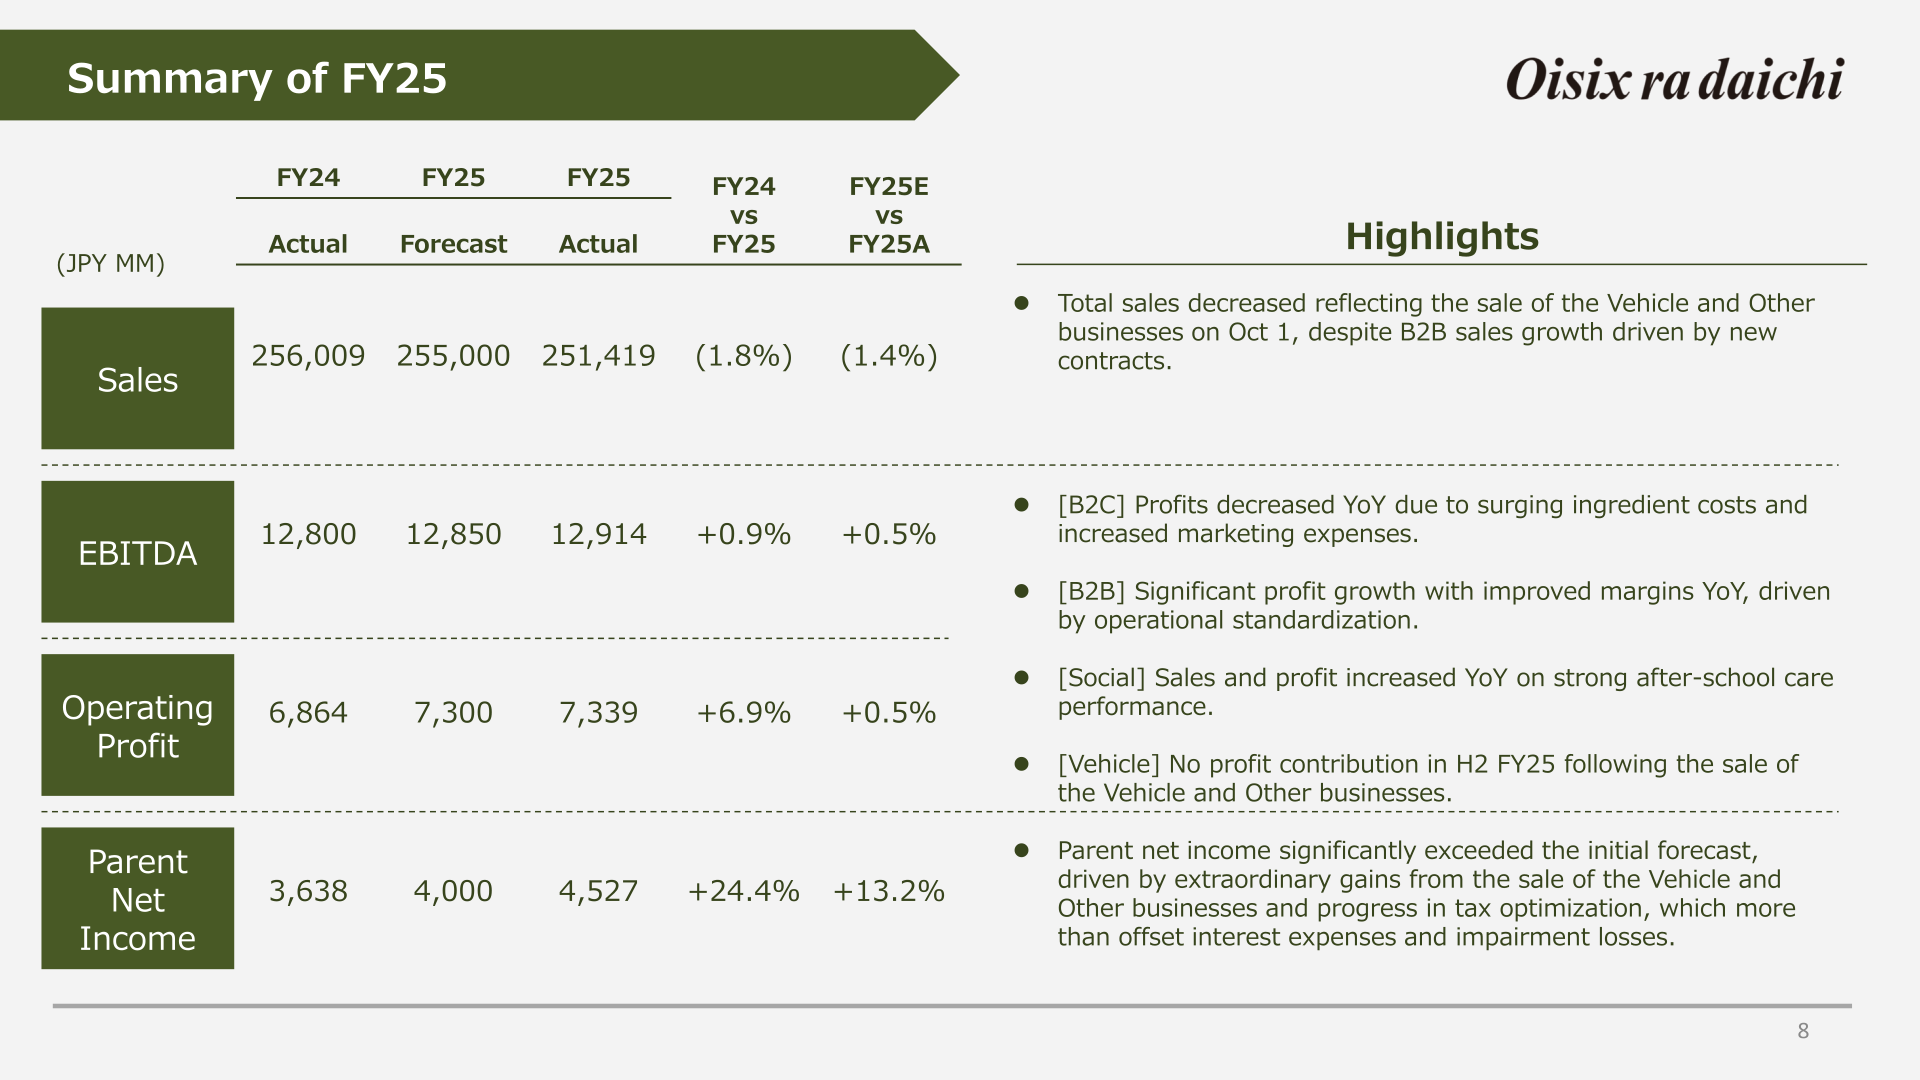
By sales, B2C Subscription was JPY 94,286 million (down 3% YoY), within which the Oisix service grew 1% to JPY 60,114 million; B2B Subscription rose 9% to JPY 83,385 million and Social Service rose 10% to JPY 40,378 million, while Vehicle Operation Service fell 46% to JPY 14,584 million following the mid-year divestiture. On segment EBITDA, B2C Subscription declined 9% to JPY 11,284 million (12.0% margin) on surging ingredient costs and higher marketing spend, while B2B Subscription rose 62% to JPY 4,062 million (4.9% margin) as price optimization and operational standardization improved profitability. The company adopted ‘Segment EBITDA’ as a key disclosure metric from FY25 actual results.
| Segment — Sales (JPY MM) | FY24 | FY25 | YoY |
|---|---|---|---|
| B2C Subscription | 97,152 | 94,286 | (3%) |
| Oisix | 59,662 | 60,114 | +1% |
| Other (Daichi + Radish + PC) | 37,489 | 34,172 | (9%) |
| B2B Subscription | 76,576 | 83,385 | +9% |
| Social Service | 36,559 | 40,378 | +10% |
| Vehicle Operation Service | 27,174 | 14,584 | (46%) |
| Other Business | 21,138 | 21,702 | +3% |
| Consolidation Adjustments | (2,592) | (2,918) | – |
| Sales | 256,009 | 251,419 | (2%) |
| Sales (excluding vehicle’s) | 228,834 | 236,835 | +3% |
| Segment — Segment EBITDA (JPY MM) | FY24 | FY25 | YoY | Margin |
|---|---|---|---|---|
| B2C Subscription | 12,343 | 11,284 | (9%) | 12.0% |
| Oisix | 9,148 | 8,362 | (9%) | 13.9% |
| Other (Daichi + Radish + PC) | 3,195 | 2,921 | (9%) | 8.5% |
| B2B Subscription | 2,503 | 4,062 | +62% | 4.9% |
| Social Service | 1,546 | 1,839 | +19% | 4.6% |
| Vehicle Operation Service | 2,848 | 1,866 | (34%) | 12.8% |
| Other Business | 1,331 | 1,000 | (25%) | 4.6% |
| Corporate Expenses and Others | (13,709) | (12,714) | – | – |
| Operating Profit | 6,864 | 7,339 | +7% | 2.9% |
| EBITDA | 12,800 | 12,914 | +1% | 5.1% |
FY26 Forecast
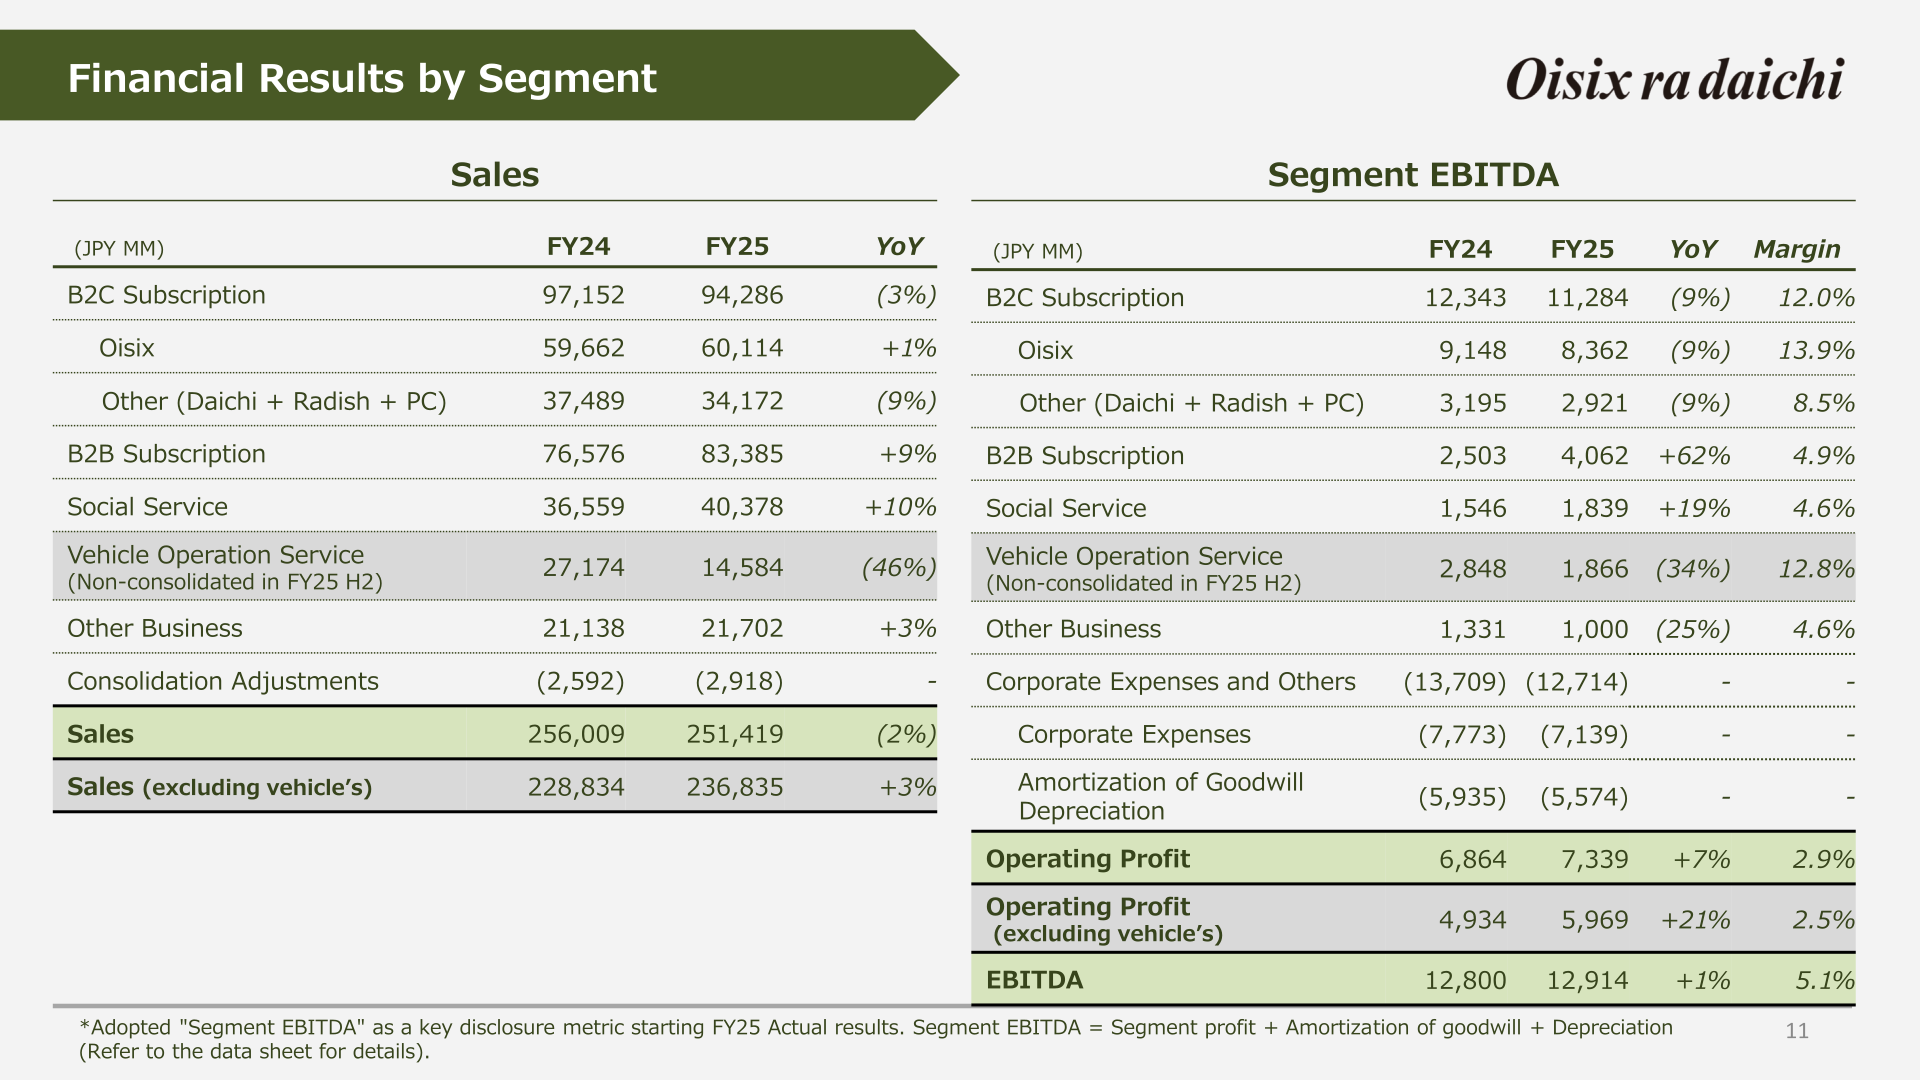
For FY26 (the year following the fiscal year ended March 31, 2026), the company forecasts sales of JPY 252.0 billion (up 0.2% YoY), EBITDA of JPY 13.4 billion (up 3.8% YoY), operating profit of JPY 8.7 billion (up 18.5% YoY), and parent net income of JPY 4.6 billion (up 1.6% YoY). Top-line growth and improved B2B profitability are expected to compensate for the JPY 14.5 billion sales and JPY 1.3 billion operating profit impact from the divested businesses; excluding that impact, the company anticipates sales up 6% and operating profit up 46% YoY.
| Item (JPY MM) | FY25 Actual | FY26 Forecast | YoY |
|---|---|---|---|
| Sales | 251,419 | 252,000 | +0.2% |
| EBITDA | 12,914 | 13,400 | +3.8% |
| Operating Profit | 7,339 | 8,700 | +18.5% |
| Parent Net Income | 4,527 | 4,600 | +1.6% |
Shareholder Returns
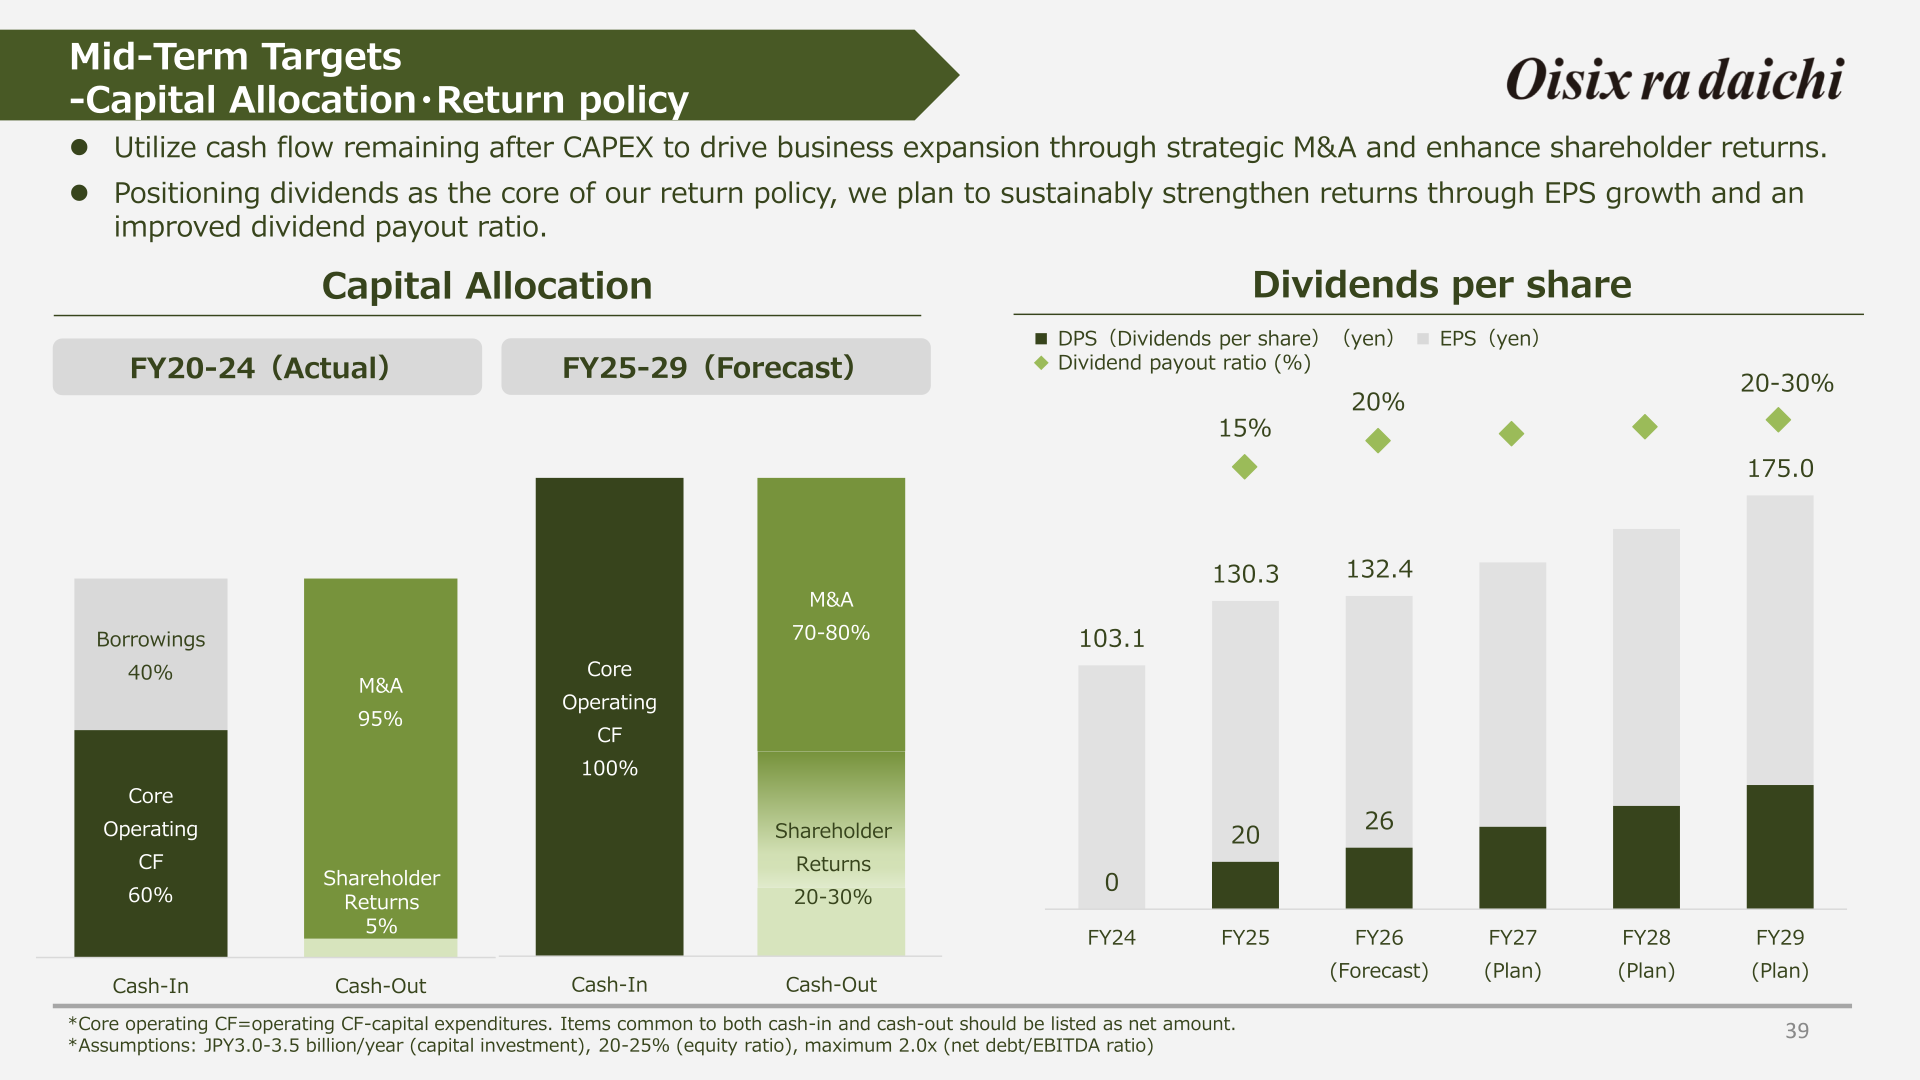
Positioning dividends as the core of its return policy, the company increased its FY25 dividend on the profit upside and is raising the dividend payout ratio from 15% to 20% starting from FY26. Dividends per share were JPY 20 for FY25 (versus JPY 0 in FY24) with a JPY 26 forecast for FY26. In FY25 the company paid its first-ever dividend since listing and cancelled treasury shares. It plans to sustainably strengthen returns through EPS growth and an improved dividend payout ratio.
Mid-Term Targets
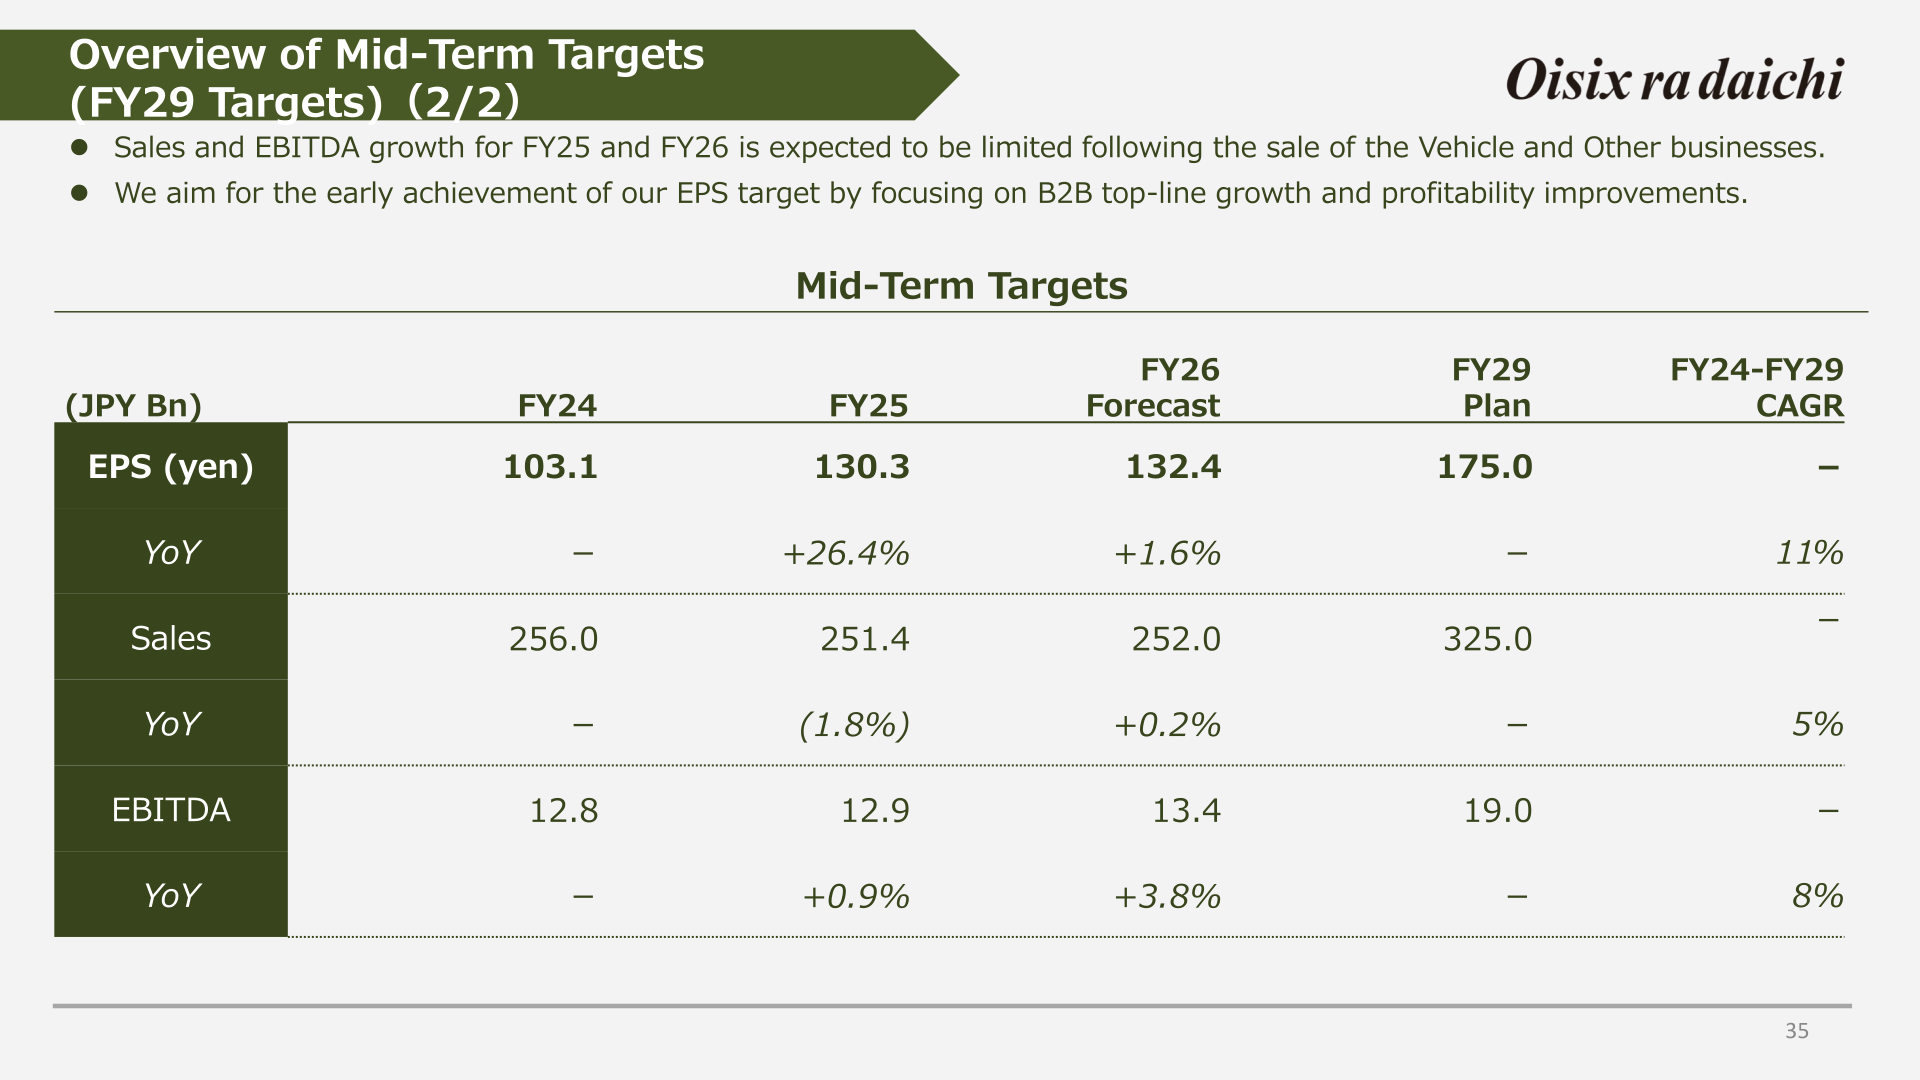
The company updated its FY29 Mid-Term Targets, raising the sales target to JPY 325 billion and targeting EBITDA of JPY 19 billion. It maintained EPS of JPY 175 (CAGR 11% from FY24) as its top-priority management goal and transitioned its key management indicators to EBITDA for both segments and consolidated disclosure. It also plans to change its trade name back to ‘Oisix Inc.’ (planned July 2026).
| Item | FY24 | FY25 | FY26 Forecast | FY29 Plan | FY24-FY29 CAGR |
|---|---|---|---|---|---|
| EPS (yen) | 103.1 | 130.3 | 132.4 | 175.0 | 11% |
| Sales (JPY Bn) | 256.0 | 251.4 | 252.0 | 325.0 | 5% |
| EBITDA (JPY Bn) | 12.8 | 12.9 | 13.4 | 19.0 | 8% |
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















