
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Kurabo Industries labels its most recent completed fiscal year as “FY3/26” (the fiscal year ended March 31, 2026); on this site it is classified as FY2025. The figures, tables and segment labels below follow the company’s presentation — FY3/26 for the year just ended, FY3/25 for the prior year, and FY3/27 for the current-year forecast.
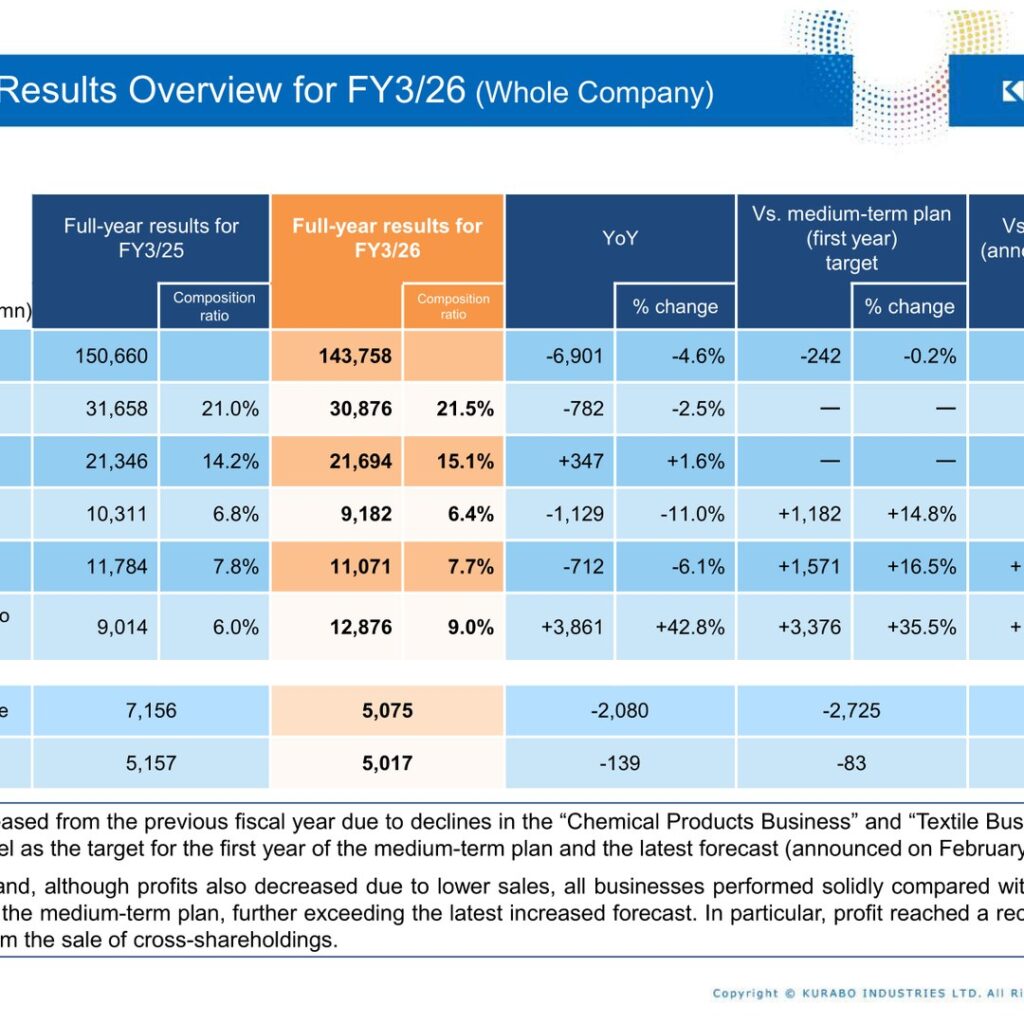
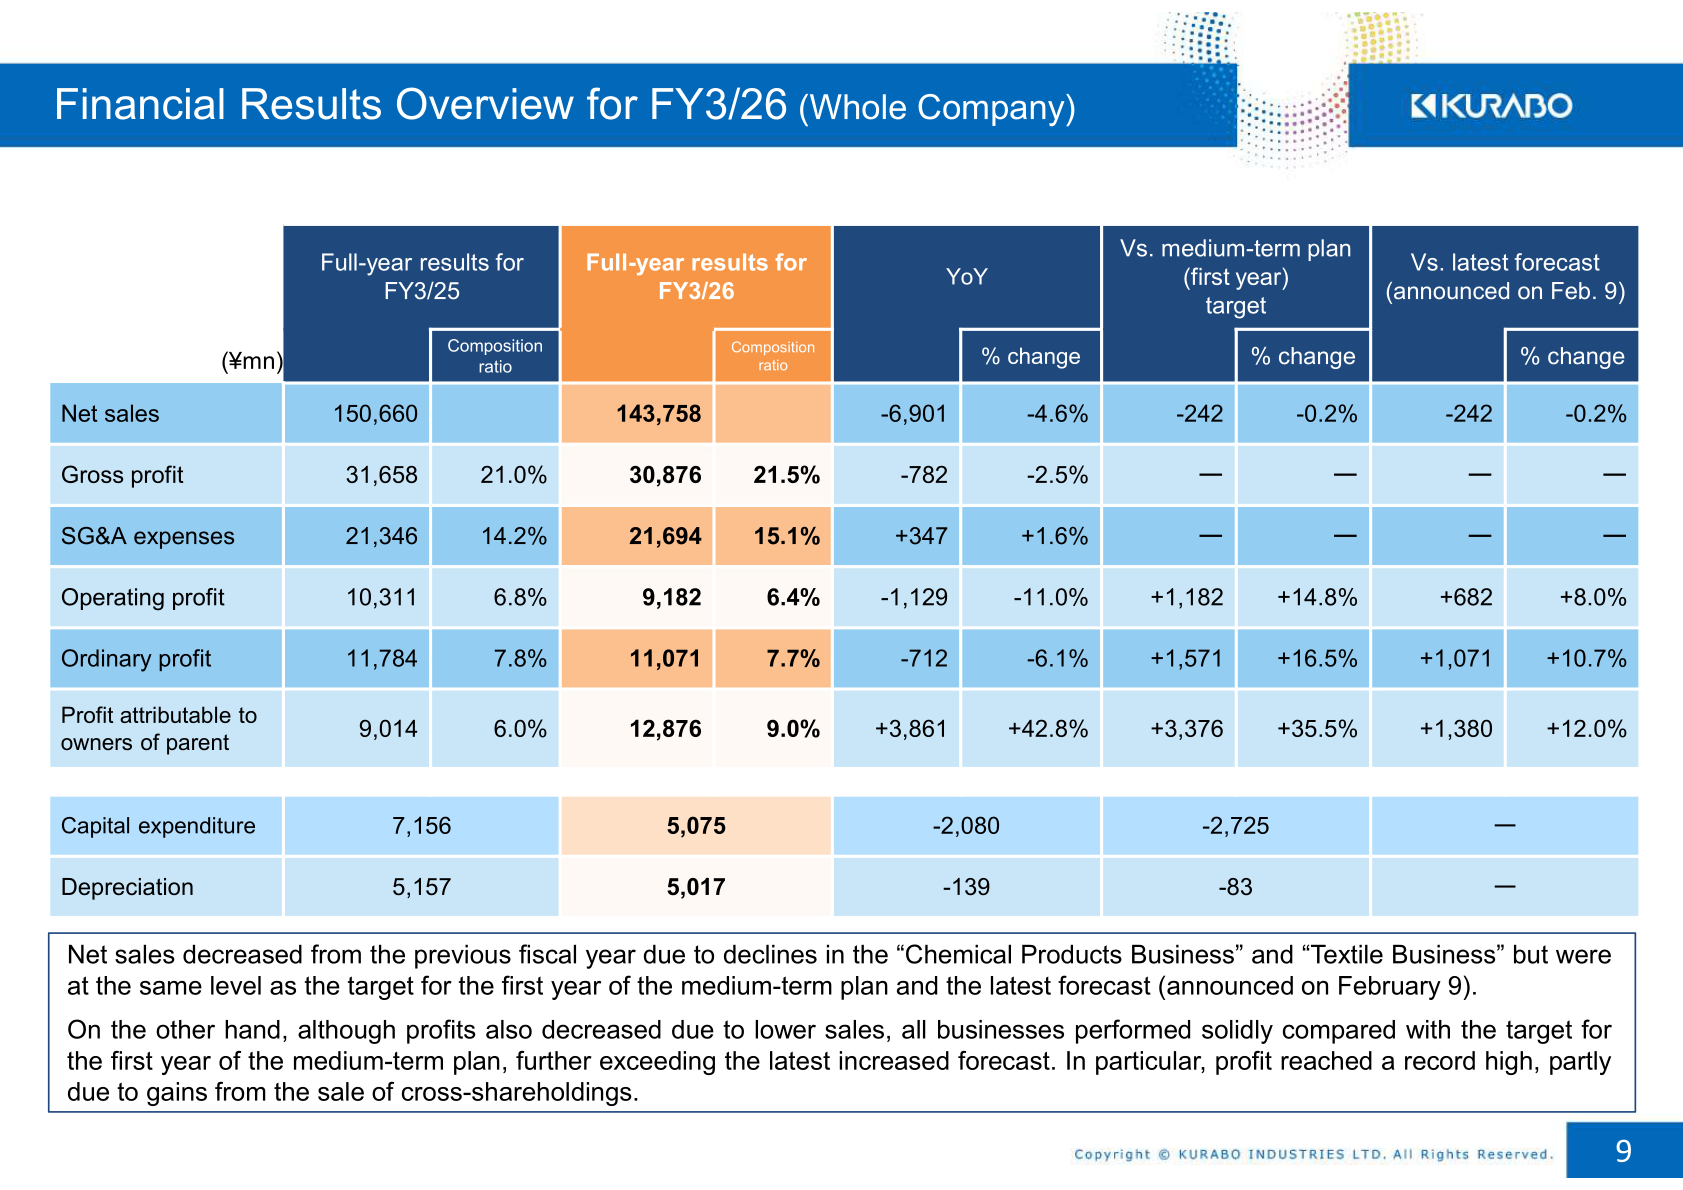
For FY3/26 (ended March 31, 2026), net sales fell 4.6% year on year to ¥143,758 million and operating profit declined 11.0% to ¥9,182 million, as the mainstay High-performance plastic products business slowed amid an adjustment phase in semiconductor manufacturing-related markets. However, profit attributable to owners of parent rose 42.8% to a record ¥12,876 million, lifted by extraordinary income including gains on the sale of cross-shareholdings. Profit at every level exceeded both the first-year targets of the medium-term plan “Accelerate ’27” and the latest forecast announced on February 9. The annual dividend was raised to ¥307 per share, up ¥127 year on year.
Consolidated Results (Full-Year Actual)
Net sales declined due to lower sales in the Chemical Products Business and Textile Business, though sales were roughly in line with the medium-term plan’s first-year target and the latest forecast. Profits also decreased on lower sales but exceeded plan and the latest increased forecast, and net profit reached a record high, partly due to gains on the sale of cross-shareholdings.
| Item (¥mn) | FY3/26 | FY3/25 | YoY change | YoY % |
|---|---|---|---|---|
| Net sales | 143,758 | 150,660 | -6,901 | -4.6% |
| Gross profit | 30,876 | 31,658 | -782 | -2.5% |
| SG&A expenses | 21,694 | 21,346 | +347 | +1.6% |
| Operating profit | 9,182 | 10,311 | -1,129 | -11.0% |
| Ordinary profit | 11,071 | 11,784 | -712 | -6.1% |
| Profit attributable to owners of parent | 12,876 | 9,014 | +3,861 | +42.8% |
| Capital expenditure | 5,075 | 7,156 | -2,080 | — |
| Depreciation | 5,017 | 5,157 | -139 | — |
On the balance sheet, the equity ratio rose 2.6pt to 65.5% and ROE improved 2.6pt to 10.2%, while ROA was 4.7% and ROIC 4.6%. Operating cash flow was ¥14,586 million, up from ¥11,048 million in FY3/25.
Segment Results
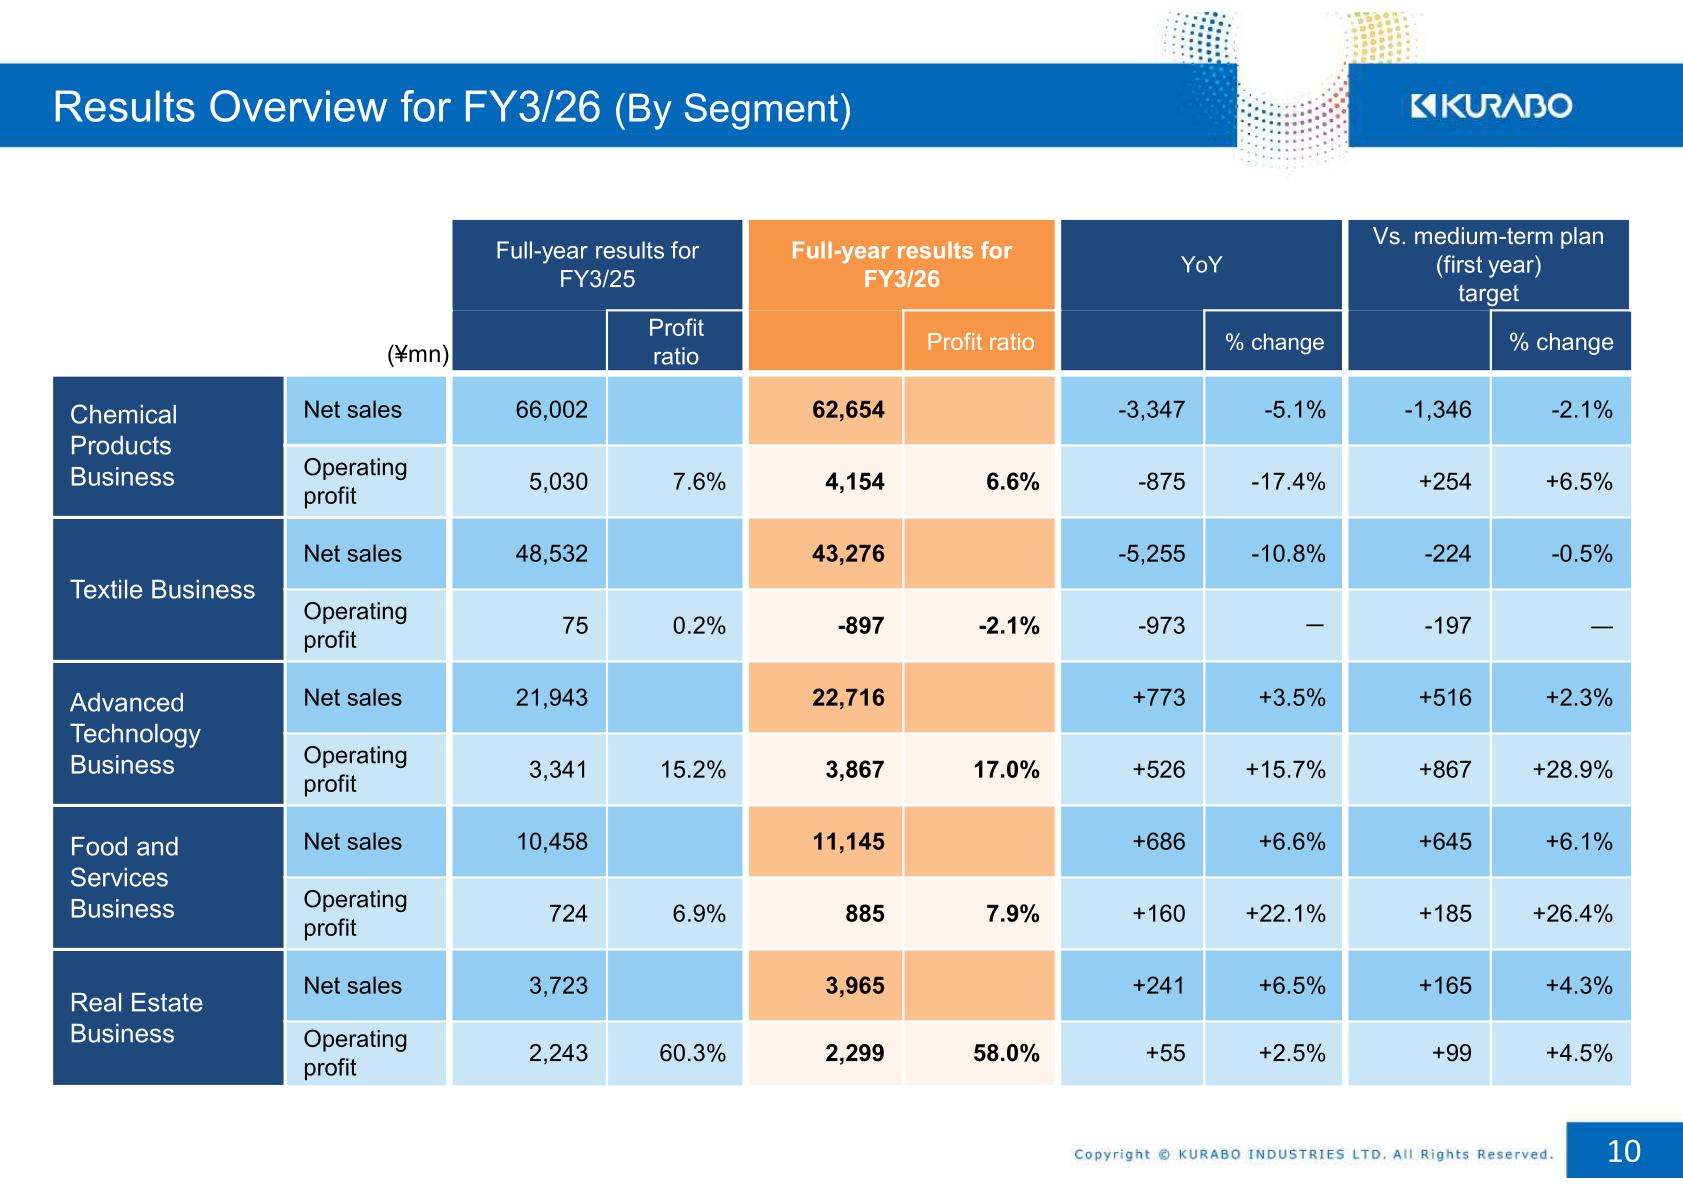
By segment, the Chemical Products Business and Textile Business saw lower sales and profit, while the Advanced Technology Business posted a record-high operating profit and the Food and Services and Real Estate businesses grew. The Textile Business recorded an operating loss, partly due to non-recurring costs related to the closure of the Anjo Mill.
| Segment | Net sales FY3/26 | Net sales FY3/25 | Operating profit FY3/26 | Operating profit FY3/25 |
|---|---|---|---|---|
| Chemical Products Business | 62,654 | 66,002 | 4,154 | 5,030 |
| Textile Business | 43,276 | 48,532 | -897 | 75 |
| Advanced Technology Business | 22,716 | 21,943 | 3,867 | 3,341 |
| Food and Services Business | 11,145 | 10,458 | 885 | 724 |
| Real Estate Business | 3,965 | 3,723 | 2,299 | 2,243 |
FY3/27 Forecast
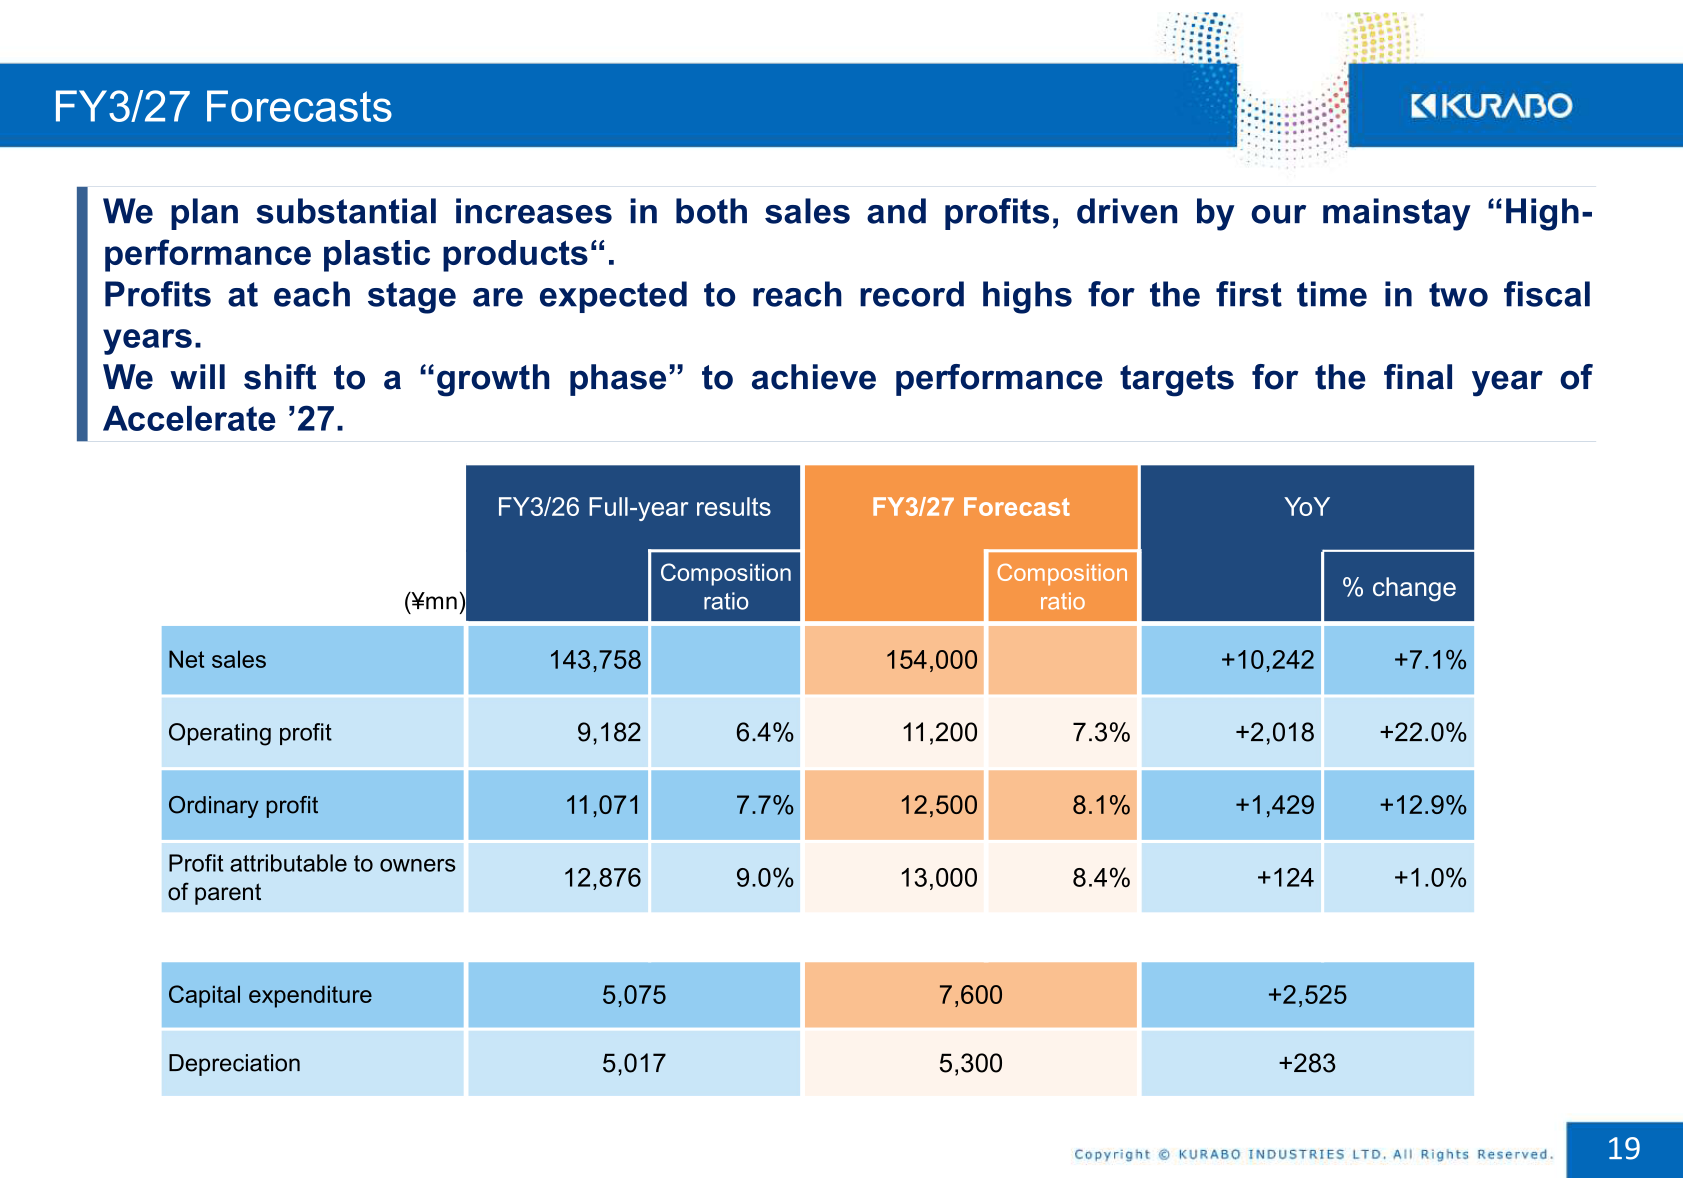
For FY3/27, the company forecasts substantial gains in both sales and profit, driven by the mainstay High-performance plastic products business amid a semiconductor market recovery. Profit at each stage is expected to reach record highs for the first time in two fiscal years.
| Item (¥mn) | FY3/27 Forecast | FY3/26 Actual | YoY % |
|---|---|---|---|
| Net sales | 154,000 | 143,758 | +7.1% |
| Operating profit | 11,200 | 9,182 | +22.0% |
| Ordinary profit | 12,500 | 11,071 | +12.9% |
| Profit attributable to owners of parent | 13,000 | 12,876 | +1.0% |
| Segment | Net sales (Forecast) | Operating profit (Forecast) |
|---|---|---|
| Chemical Products Business | 68,000 | 5,500 |
| Textile Business | 45,600 | 400 |
| Advanced Technology Business | 25,000 | 3,400 |
| Food and Services Business | 11,500 | 900 |
| Real Estate Business | 3,900 | 2,200 |
Shareholder Returns
The dividend policy targets a 4% dividend on equity (DOE), with treasury share purchases of ¥20 billion planned over the Accelerate ’27 period. For FY3/26, the annual dividend was raised to ¥307 per share (interim ¥141, year-end ¥166), an increase of ¥127 year on year and ¥25 above the forecast; the total return ratio was 91.8%. For FY3/27, the company forecasts an annual dividend of ¥331 per share on a pre-split basis (interim ¥166 pre-split, year-end ¥33 post-split), which would mark a fourth consecutive year of dividend increases. A 5-for-1 stock split of common shares is scheduled for October 1, 2026. As resolved on November 11, 2025, the company may repurchase up to 1,000,000 shares for up to ¥7 billion through September 30, 2026; through March 31, 2026 it had purchased 535,000 shares for ¥4.2 billion.
Medium-Term Plan “Accelerate ’27”
Under the three-year medium-term plan “Accelerate ’27,” the company targets final-year (FY3/28) net sales of ¥165 billion and operating profit of ¥13 billion, along with ROE of 10.0% and ROIC of 7.9%. In the plan’s first year, profit at every level exceeded the initial plan, and ROE of 10.2% already surpassed the 10% target, while ROIC of 4.6% remains below the 8%-or-more goal. Cumulative first-year cash allocation included growth investment and shareholder returns funded by operating cash flow and sales of non-operating assets. The company aims to sustain a P/B ratio of 1x or more by advancing business portfolio reform, reducing cross-shareholdings (¥7.3 billion sold in FY3/26), and enhancing shareholder returns.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















