
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Kitanotatsujin Corporation labels the fiscal year ended February 28, 2026 as “FY2026” in its materials, while this site classifies each company’s most recent completed fiscal year as FY2025; the labels used in the text, tables and segment data below follow the company’s materials.
For the fiscal year ended February 28, 2026 (FY2026 in the company’s notation), Kitanotatsujin Corporation posted consolidated net sales of ¥11,210 million and consolidated operating profit of ¥1,000 million, both above the company’s forecast. Against the previous fiscal year, net sales fell 5.2% and operating profit fell 40.3%, as the accumulation of sales from regular customers decreased after new customer acquisitions at J NORTH FARM, which had declined in FY2024, recovered only slowly in FY2025. The number of new customer acquisitions bottomed out in the third quarter of FY2025 and rose for a fifth consecutive quarter in the fourth quarter of FY2026. For FY2027 the company forecasts record consolidated net sales of ¥15,962 million, up 42.4% year on year, with operating profit up slightly at ¥1,059 million.
Consolidated Results (Full-Year Actual)
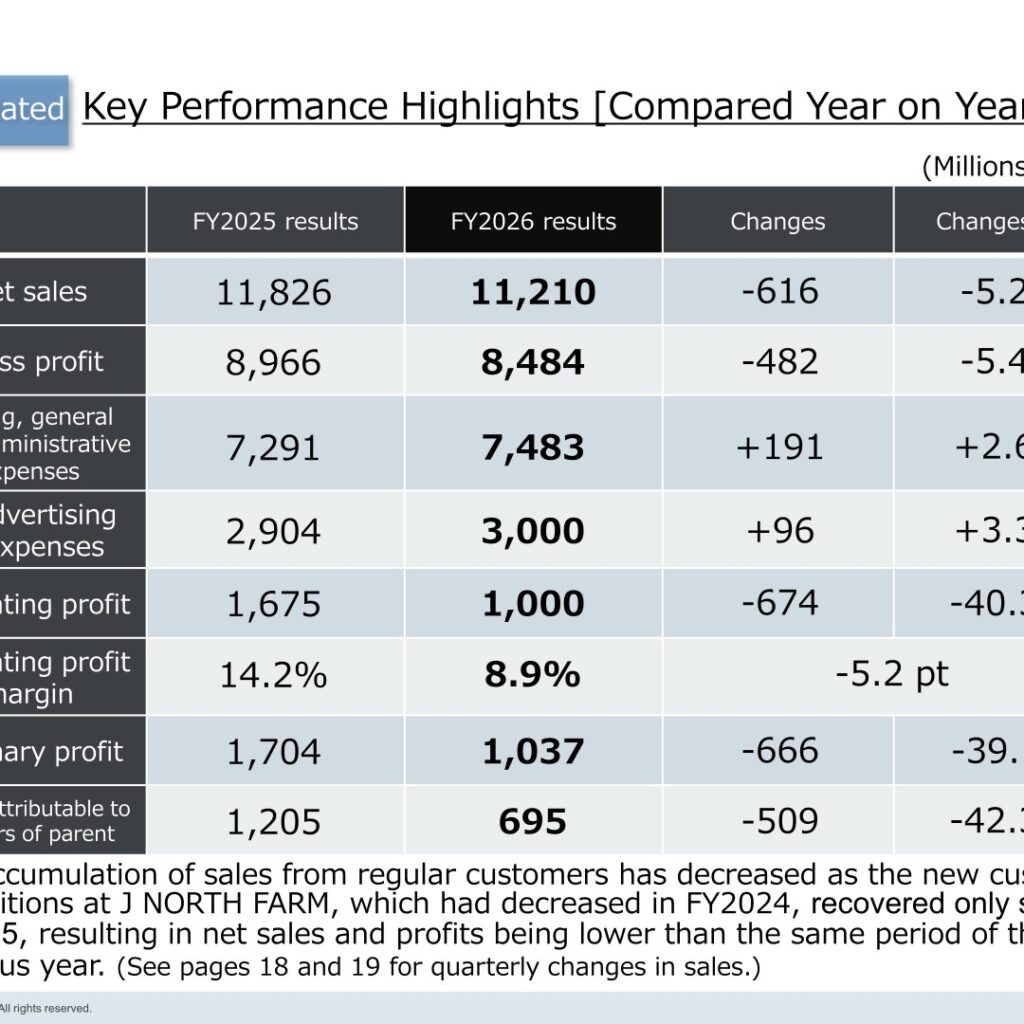
On a year-on-year basis, net sales, gross profit and all profit lines declined, while selling, general and administrative expenses and advertising expenses increased. The operating profit margin fell from 14.2% to 8.9%. The company explains that the accumulation of sales from regular customers decreased as new customer acquisitions at J NORTH FARM, which had decreased in FY2024, recovered only slowly in FY2025, resulting in net sales and profits being lower than the same period of the previous year.
| Item (Millions of yen) | FY2025 results | FY2026 results | Changes | Changes (%) |
|---|---|---|---|---|
| Net sales | 11,826 | 11,210 | -616 | -5.2% |
| Gross profit | 8,966 | 8,484 | -482 | -5.4% |
| Selling, general and administrative expenses | 7,291 | 7,483 | +191 | +2.6% |
| Advertising expenses | 2,904 | 3,000 | +96 | +3.3% |
| Operating profit | 1,675 | 1,000 | -674 | -40.3% |
| Operating profit margin | 14.2% | 8.9% | -5.2 pt | ー |
| Ordinary profit | 1,704 | 1,037 | -666 | -39.1% |
| Profit attributable to owners of parent | 1,205 | 695 | -509 | -42.3% |
Compared with the company’s forecast, results came in higher across the board: net sales of ¥11,210 million against a forecast of ¥10,289 million (+921, or +9.0%) and operating profit of ¥1,000 million against ¥897 million (+103, or +11.6%). Ordinary profit was ¥1,037 million against ¥911 million (+13.8%) and profit attributable to owners of parent was ¥695 million against ¥622 million (+11.9%). Advertising expenses also exceeded the forecast, at ¥3,000 million against ¥2,661 million (+12.7%), because new customer acquisitions at J NORTH FARM outperformed the plan; profits nevertheless increased, driven by the accumulation of regular sales and strong e-commerce mall sales.
Segment Results
The company reports a single Health & Beauty Care business, broken down by operating company and brand. Non-consolidated financial results occupy a significant portion of consolidated financial results. KARAKON DIRECT Co., Ltd. has been included in the consolidated financial results since the fourth quarter of FY2026, following the acquisition of all shares of Rebirth Chain Consulting Co., Ltd. (current KARAKON DIRECT Co., Ltd.) on December 1, 2025.
| Business (Millions of yen) | 1Q | 2Q | 3Q | 4Q | FY2026 Total |
|---|---|---|---|---|---|
| J NORTH FARM | 2,366 | 2,427 | 2,533 | 2,701 | 10,028 |
| SALONMOON Co., Ltd. | 211 | 208 | 226 | 251 | 898 |
| KARAKON DIRECT Co., Ltd. | ー | ー | ー | 236 | 236 |
| Others (e-cigarette “SPADE.”) | 18 | 13 | 8 | 6 | 46 |
| Total net sales | 2,596 | 2,649 | 2,768 | 3,195 | 11,210 |
| Operating profit | 240 | 264 | 252 | 243 | 1,000 |
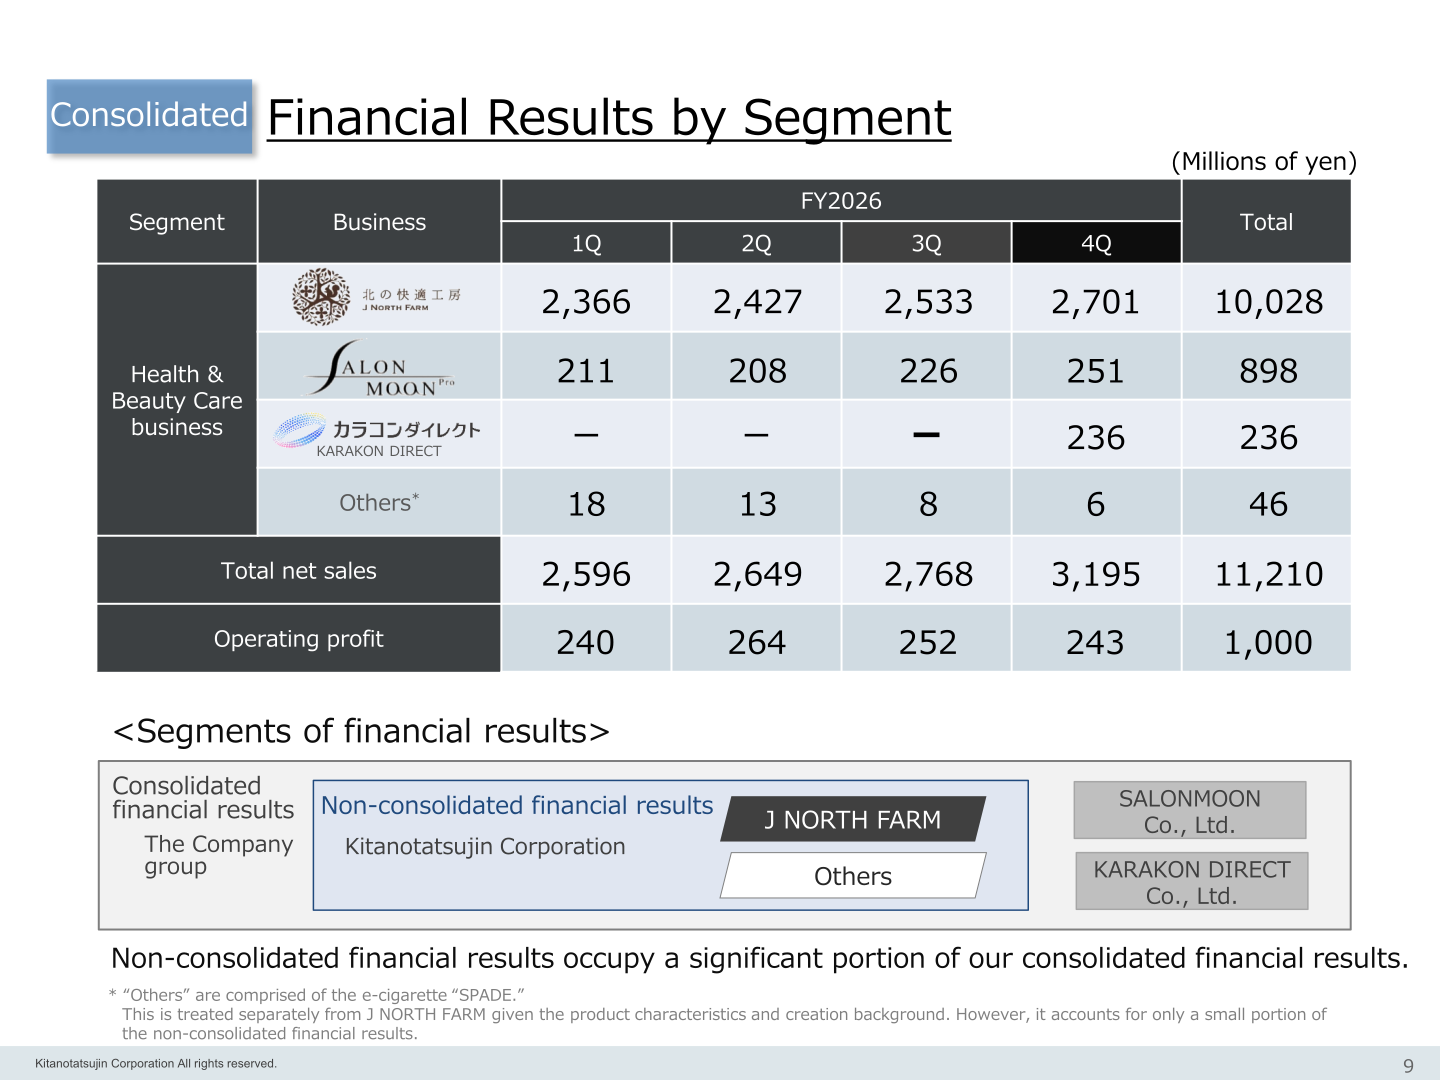
Within the non-consolidated business, J NORTH FARM net sales of ¥10,028 million exceeded the forecast of ¥9,235 million by 8.6%, and sales profit was ¥3,943 million against a forecast of ¥3,805 million (+3.6%). New sales were ¥1,736 million (+24.6% versus forecast) with an initial ROAS of 64.0% against a forecast of 56.3%; regular and other sales were ¥6,410 million (+3.4%); and e-commerce mall sales were ¥1,881 million (+14.7%). In the fourth quarter of FY2026, e-commerce mall net sales rose 8% quarter on quarter and 47% year on year, and in November 2025 monthly revenue exceeded ¥100 million on Amazon, a record high.
FY2027 Forecast
For the fiscal year ending February 28, 2027, the company forecasts a record high for consolidated net sales at ¥15,962 million, up 42.4% year on year, while profits are expected to increase only slightly, reflecting accelerated upfront investments supported by strong new acquisitions. The operating profit margin is forecast to decline from 8.9% to 6.6%. By company, the increase in net sales is attributed to Kitanotatsujin +¥3,753 million, KARAKON DIRECT +¥932 million (a full-year contribution in FY2027 against a three-month contribution in FY2026) and SALONMOON +¥65 million.
| Item (Millions of yen) | FY2026 results | FY2027 forecast | Changes | Changes (%) |
|---|---|---|---|---|
| Net sales | 11,210 | 15,962 | +4,751 | +42.4% |
| Operating profit | 1,000 | 1,059 | +58 | +5.9% |
| Operating profit margin | 8.9% | 6.6% | -2.3 pt | ー |
| Ordinary profit | 1,037 | 1,080 | +43 | +4.2% |
| Profit attributable to owners of parent | 695 | 734 | +38 | +5.5% |
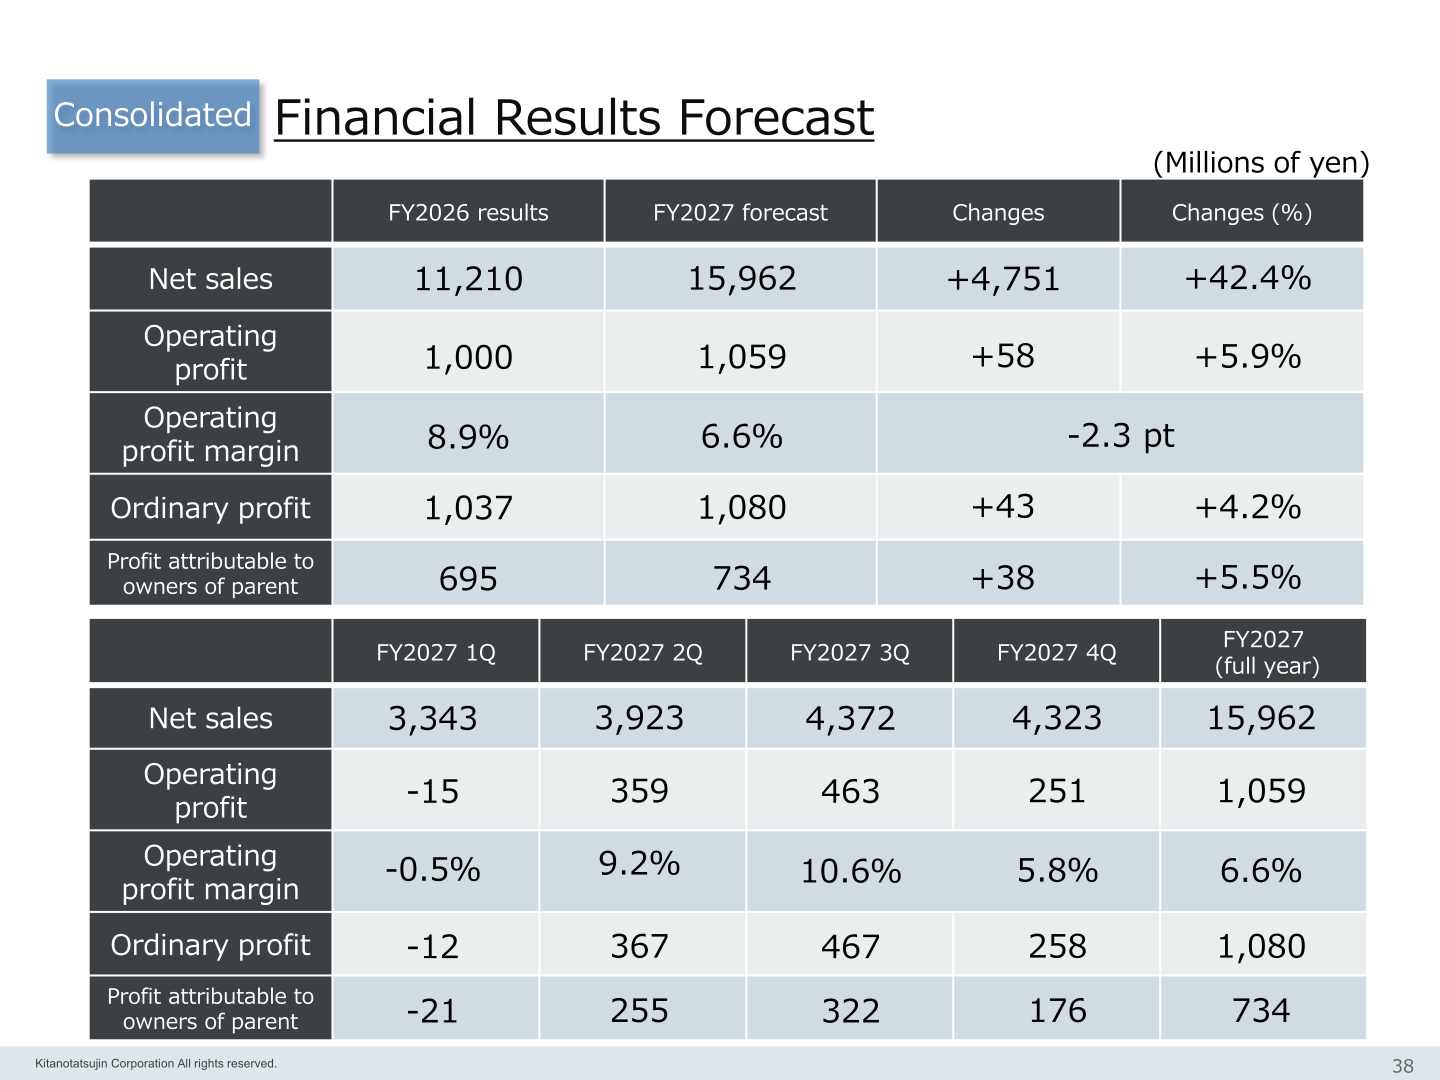
By quarter, the FY2027 forecast is for net sales of ¥3,343 million in the first quarter, ¥3,923 million in the second, ¥4,372 million in the third and ¥4,323 million in the fourth, with an operating loss of ¥15 million in the first quarter followed by operating profit of ¥359 million, ¥463 million and ¥251 million. The company explains that some products have been facing shipping delays due to inventory shortages as new acquisitions remain strong; pre-orders were accepted from new customers without suspending advertising placement to avoid opportunity loss, so the related net sales and operating profit are recorded with a delay, producing an operating loss in the first quarter of FY2027. The company also states that the assumptions behind the forecast have changed: contributions from the launch of new products and the resulting acquisitions of new customers are now incorporated based on certain reasonable assumptions, which was not the case in previous forecasts.
Shareholder Returns
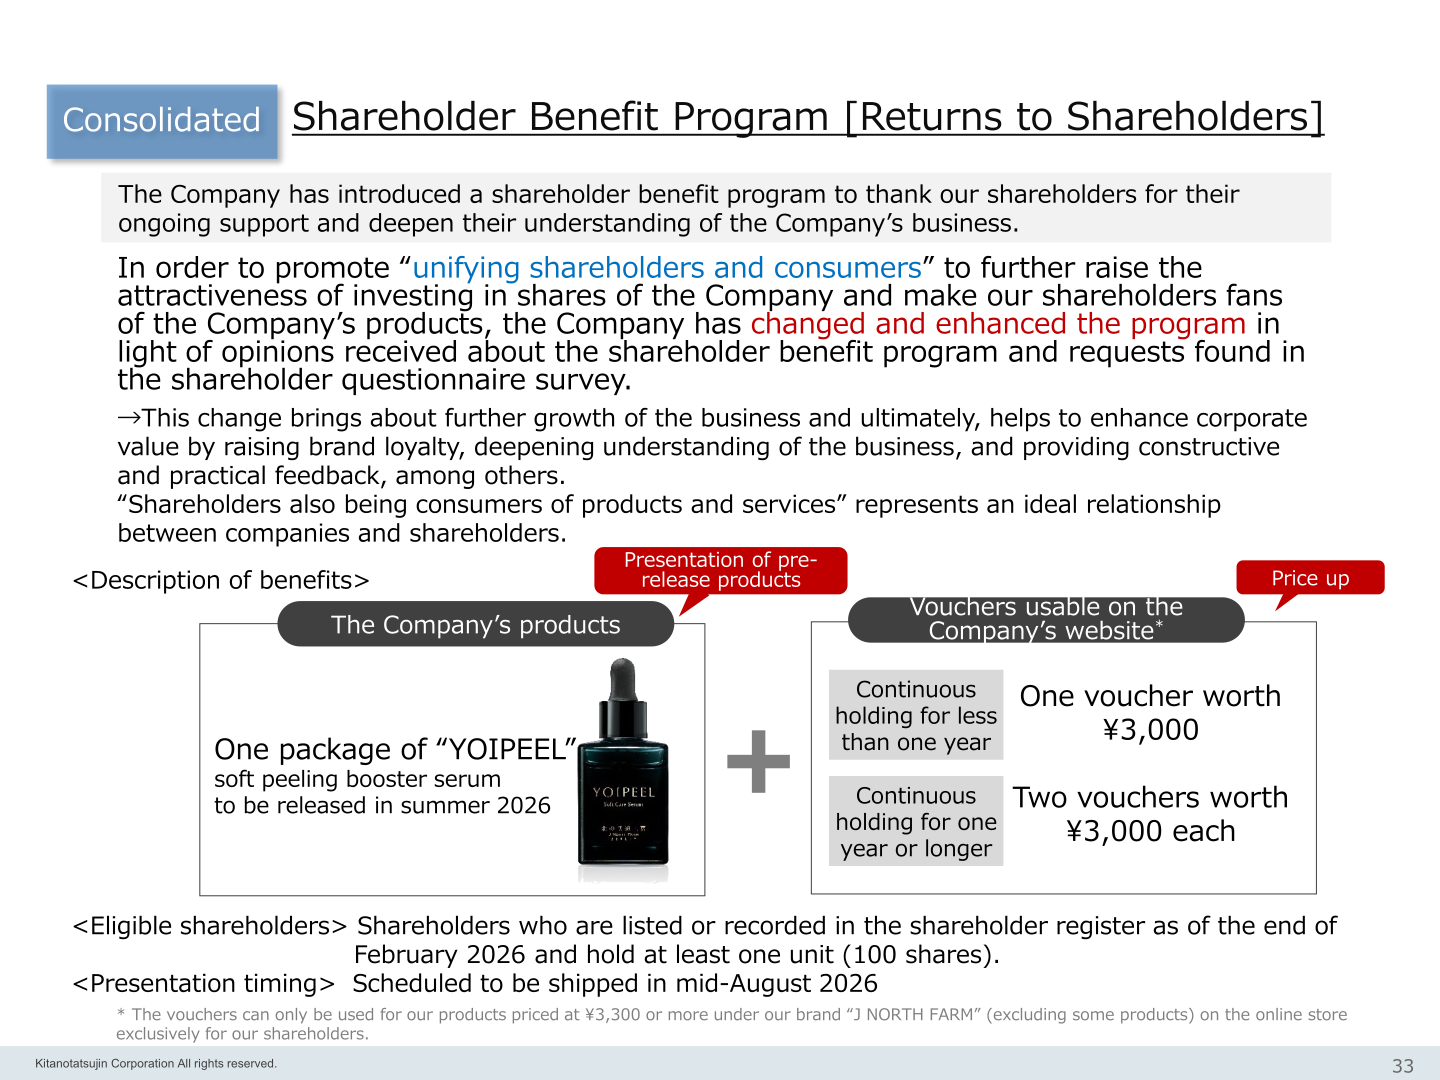
Cash dividends per share for FY2026 are ¥3.50 (planned), unchanged from ¥3.50 in FY2025, with a dividend payout ratio of 70.1% (planned) against 40.4% in FY2025. Dividends paid during FY2026 were ¥542 million as shown in the consolidated statements of cash flows. The company also operates a shareholder benefit program for shareholders listed or recorded in the shareholder register as of the end of February 2026 who hold at least one unit (100 shares), scheduled to be shipped in mid-August 2026: one package of “YOIPEEL” soft peeling booster serum to be released in summer 2026, plus one voucher worth ¥3,000 for holdings of less than one year and two vouchers worth ¥3,000 each for continuous holding of one year or longer. The provision for this shareholder benefit, to be delivered in FY2027, was recorded in the fourth quarter of FY2026 and was one reason operating profit declined quarter on quarter.
| Item | FY2025 (consolidated) | FY2026 (consolidated) |
|---|---|---|
| Cash dividends per share (yen) | 3.50 | 3.50 (planned) |
| Dividend payout ratio (%) | 40.4 | 70.1 (planned) |
| ROE (%) | 16.2 | 8.7 |
| ROA (%) | 13.5 | 7.5 |
| Equity ratio (%) | 85.9 | 84.8 |
| Number of shareholders | 100,470 | 129,554 |
Medium-Term Plan and Topics
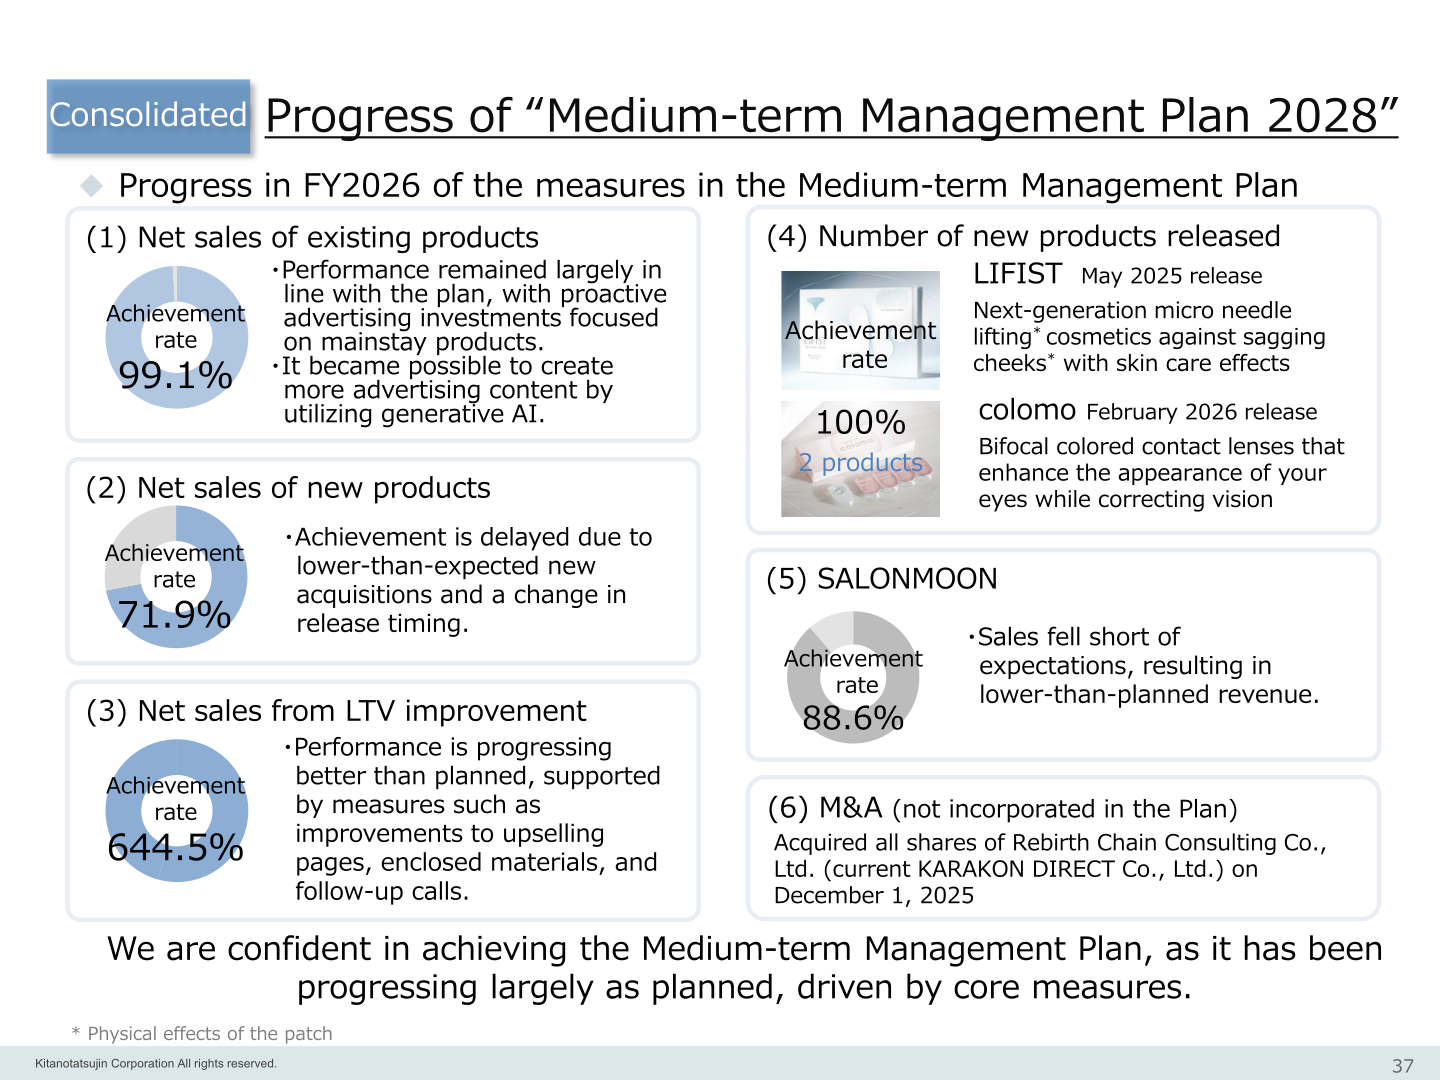
On the progress in FY2026 of the measures in “Medium-term Management Plan 2028,” the company reports achievement rates of 99.1% for net sales of existing products, 71.9% for net sales of new products (delayed due to lower-than-expected new acquisitions and a change in release timing), 644.5% for net sales from LTV improvement, 100% for the number of new products released (two products: LIFIST, released May 2025, and colomo, released February 2026) and 88.6% for SALONMOON. The acquisition of Rebirth Chain Consulting Co., Ltd. (current KARAKON DIRECT Co., Ltd.) on December 1, 2025 was not incorporated in the Plan. The company states that it is confident in achieving the Medium-term Management Plan, as it has been progressing largely as planned, driven by core measures.
The company attributes the strength in customer acquisition mainly to an increasingly sophisticated advertising content creation process using generative AI, combined with internally accumulated data on customers, advertising and sales. It also separated product “planning” and “development” into different phases and established a product planning and marketing team under the direct control of the President, aiming for a structure where 10 products can be released annually in FY2029 and thereafter. On capital efficiency, the company states that ROE is in a decreasing trend due to lowering profitability and that the cost of equity estimated by its CAPM is approximately 7%, while noting that it does not think exceeding the cost of capital calculated by this model meets investors’ needs.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















