
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
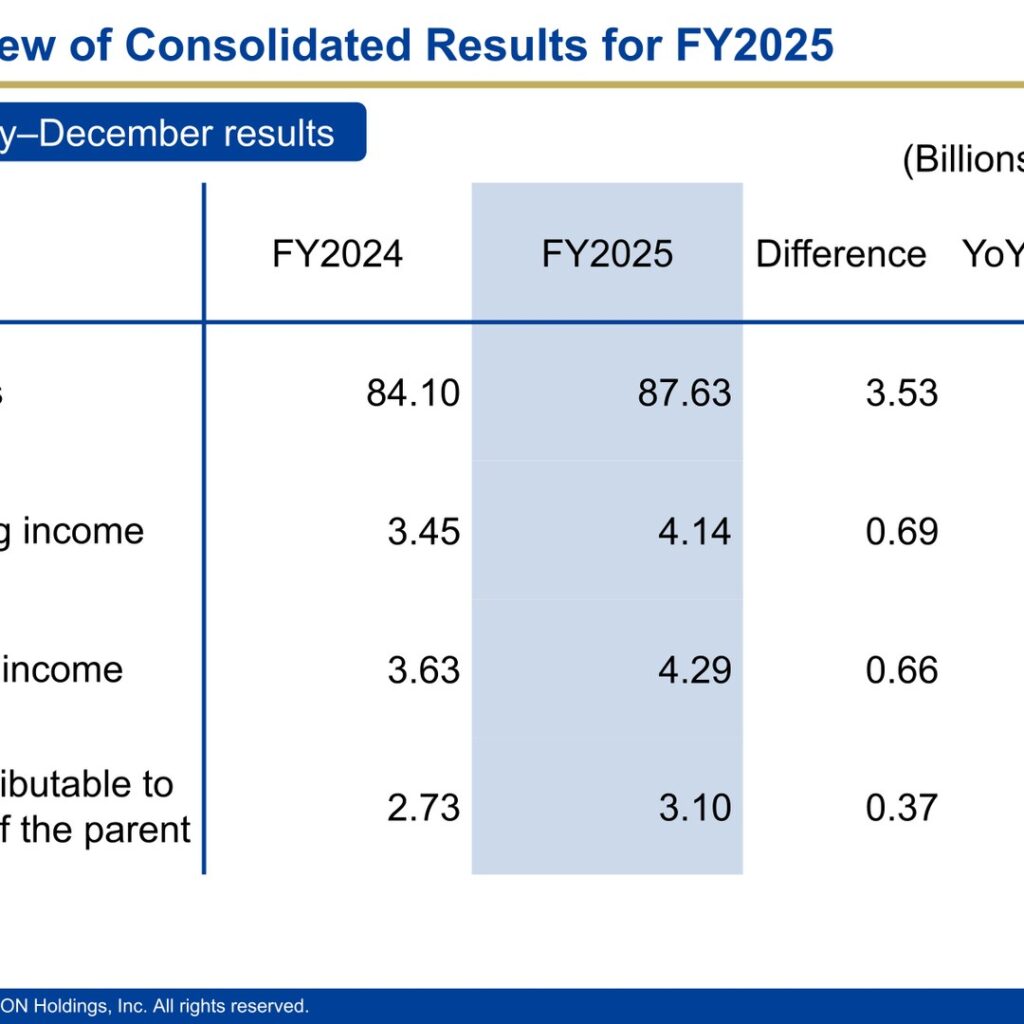
OENON Holdings reported net sales of 87.63 billion yen for FY2025, the January-December 2025 fiscal year, up 3.53 billion yen or 4% year on year. Operating income rose 0.69 billion yen to 4.14 billion yen (up 20%), ordinary income rose 0.66 billion yen to 4.29 billion yen (up 18%), and profit attributable to owners of the parent rose 0.37 billion yen to 3.10 billion yen (up 14%). Growth was led by chu-hi (RTD), where sales increased 2.8 billion yen to 19.7 billion yen. For FY2026 the company guides to higher net sales of 89.00 billion yen but lower profit at every level.
Consolidated Results (Full-Year Actual)
The results briefing materials cover the January-December 2025 fiscal year, which the company labels FY2025. All figures below are presented in billions of yen, as shown in the materials. On the business environment, the materials state that in response to rising prices consumers are defending their lifestyles by becoming more selective in their spending and that, overall, sales of alcoholic beverages are sluggish, while in anticipation of the October 2026 revision to the Liquor Tax Act there is a shift back toward beer and a strategic strengthening of RTD products.
| Item (Billions of yen) | FY2024 | FY2025 | Difference | YoY change |
|---|---|---|---|---|
| Net sales | 84.10 | 87.63 | 3.53 | 4% |
| Operating income | 3.45 | 4.14 | 0.69 | 20% |
| Ordinary income | 3.63 | 4.29 | 0.66 | 18% |
| Profit attributable to owners of the parent | 2.73 | 3.10 | 0.37 | 14% |
Segment Results
All three reporting segments grew sales in FY2025. Alcoholic beverages, the core segment, rose 2.9 billion yen to 81.6 billion yen; enzymes and pharmaceuticals rose 0.5 billion yen to 4.6 billion yen; and real estate rose 0.2 billion yen to 1.4 billion yen.
| Sales (Billions of yen) | FY2024 | FY2025 | Difference | YoY change |
|---|---|---|---|---|
| Alcoholic beverages | 78.7 | 81.6 | 2.9 | 4% |
| Enzymes and pharmaceuticals | 4.2 | 4.6 | 0.5 | 12% |
| Real estate | 1.2 | 1.4 | 0.2 | 15% |
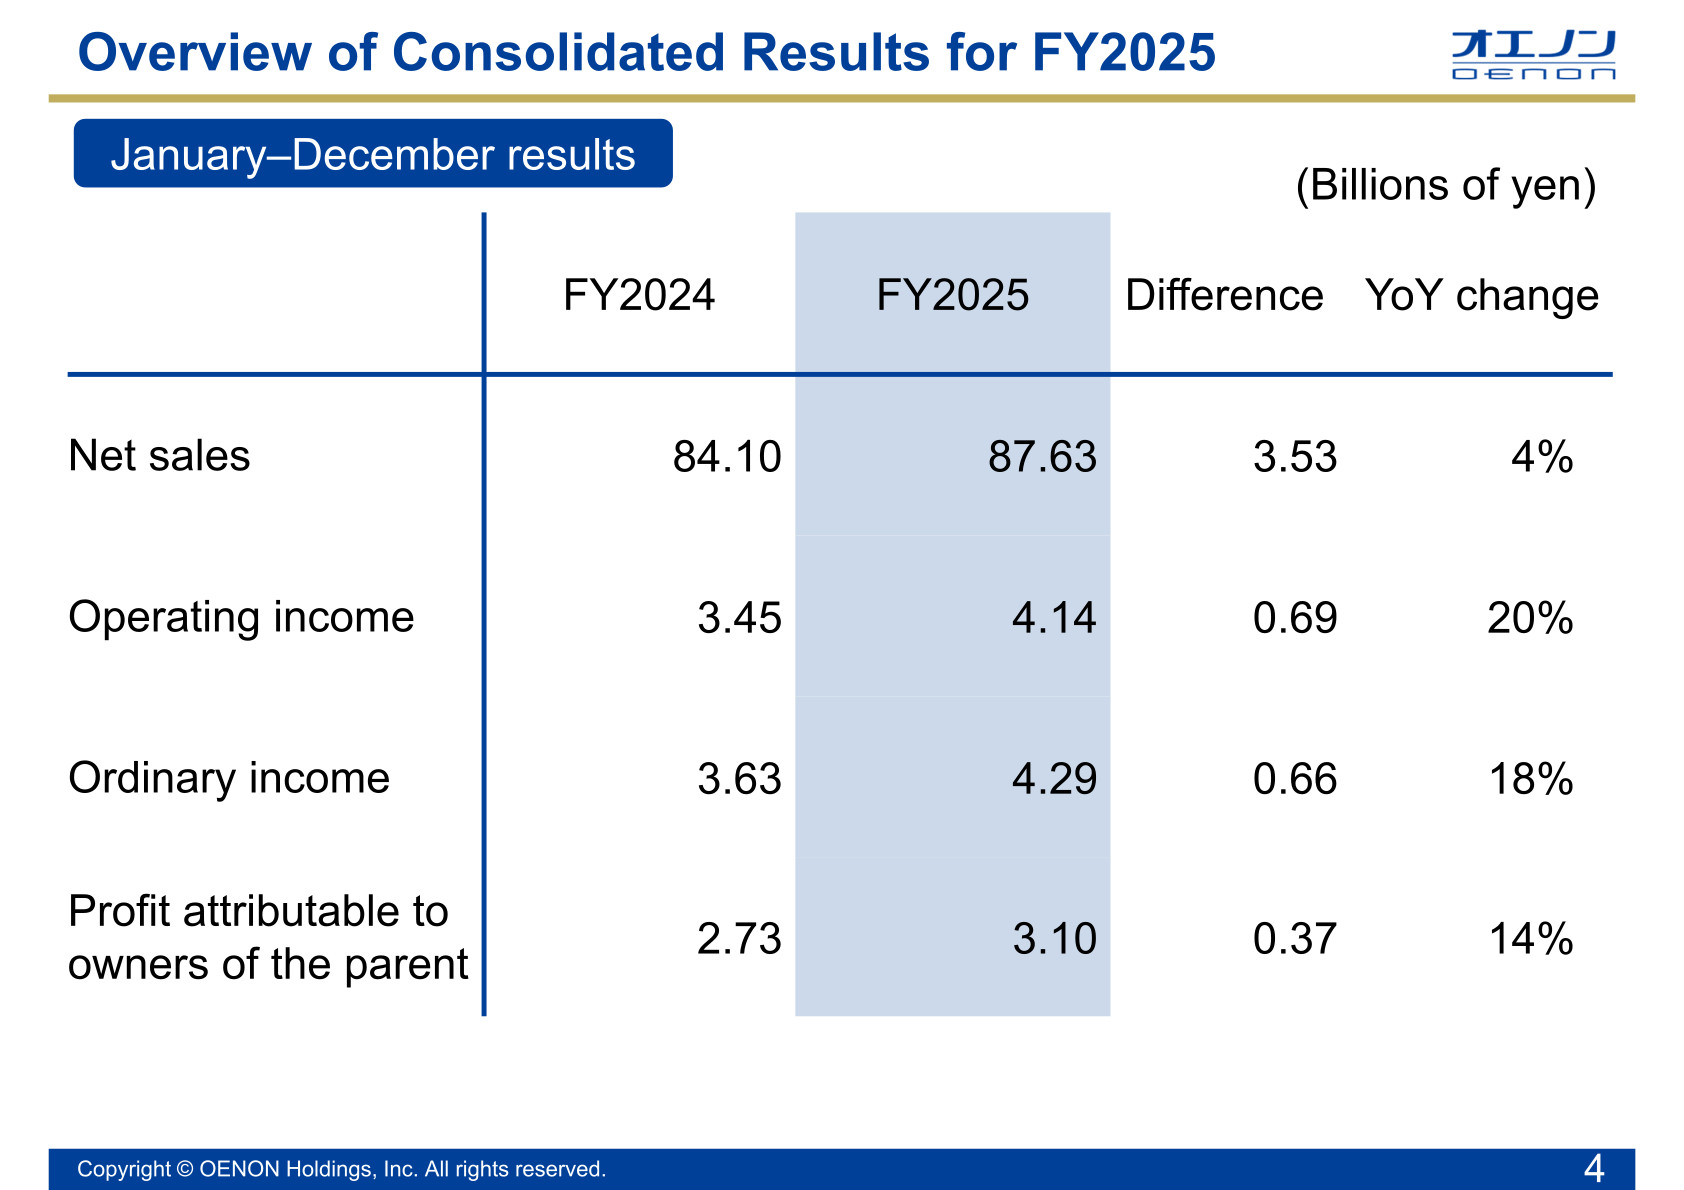
Within alcoholic beverages, chu-hi (RTD) was the sole large mover, up 16% to 19.7 billion yen, which the materials break down into own-brand products +0.3 and store-brand products +2.5. Otsu-type shochu (including kou-otsu blended shochu) was little changed at 24.2 billion yen, with Hakata no Hana +0.0, SUGO-MUGI +0.5 and store-brand products (0.4).
| Sales (Billions of yen) | FY2024 | FY2025 | Difference | YoY change |
|---|---|---|---|---|
| Alcoholic beverages | 78.7 | 81.6 | 2.9 | 4% |
| Kou-type shochu | 12.1 | 12.2 | 0.1 | 0% |
| Otsu-type shochu (including kou-otsu blended shochu) | 24.1 | 24.2 | 0.1 | 0% |
| Chu-hi (RTD) | 16.9 | 19.7 | 2.8 | 16% |
| Brewing and industrial alcohol | 13.5 | 13.6 | 0.1 | 0% |
| Wine and spirits | 5.3 | 5.4 | 0.1 | 1% |
In enzymes and pharmaceuticals, enzymes sales rose 0.2 billion yen to 3.2 billion yen (up 10%), contract manufacturing rose 0.2 billion yen to 1.1 billion yen (up 32%), and diagnostic medicines declined 0.1 billion yen to 0.3 billion yen (down 16%). The materials attribute the increase to exports and note YNL: +0.2.
| Operating income (Billions of yen) | FY2024 | FY2025 | Difference | YoY change |
|---|---|---|---|---|
| Alcoholic beverages | 2.30 | 2.56 | 0.26 | 11% |
| Enzymes and pharmaceuticals | 0.53 | 0.80 | 0.27 | 51% |
| Real estate | 0.62 | 0.78 | 0.16 | 26% |
The bridge for alcoholic beverage operating income shows lower ingredient costs of +0.92 and higher sales of +0.45, partly offset by higher SG&A expenses of (0.54), higher manufacturing costs of (0.32) and changes in the product mix of (0.25). The materials note transportation expenses of (0.3) and personnel costs of (0.2) within SG&A, and repair expenses of (0.4) within manufacturing costs. For enzymes and pharmaceuticals, the bridge shows an increase in marginal profit on exports of +0.23, an increase in marginal profit on domestic sales of +0.17 and an FX impact of +0.04, against higher fixed costs and others of (0.17), with export YNL: +0.24, contract manufacturing: +0.21 and factory repair expenses and others: (0.09) cited alongside.
FY2026 Forecast
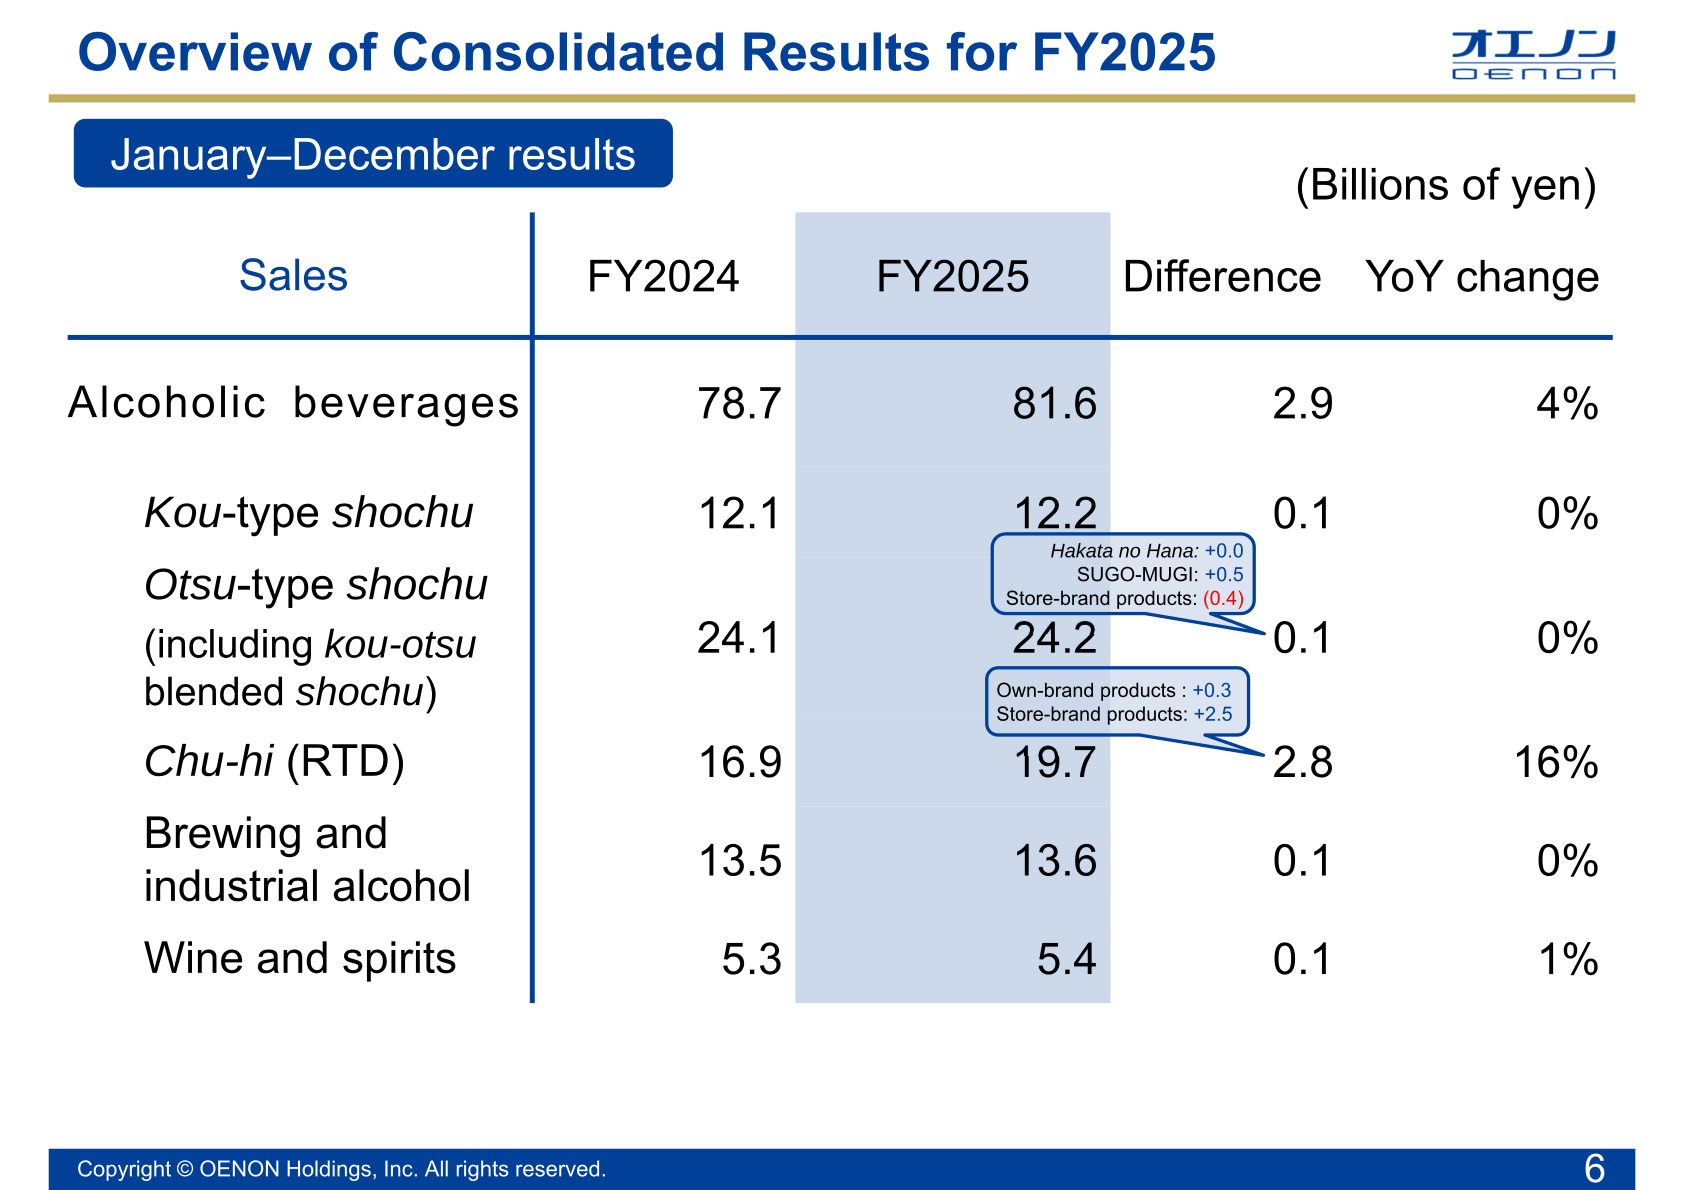
For FY2026 the company forecasts net sales of 89.00 billion yen, up 1.37 billion yen or 2%, with operating income of 3.95 billion yen, down 0.19 billion yen or 4%, ordinary income of 4.00 billion yen, down 0.29 billion yen or 7%, and profit attributable to owners of the parent of 2.90 billion yen, down 0.20 billion yen or 6%.
| Item (Billions of yen) | FY2025 | FY2026 Forecast | Difference | YoY change |
|---|---|---|---|---|
| Net sales | 87.63 | 89.00 | 1.37 | 2% |
| Operating income | 4.14 | 3.95 | (0.19) | (4)% |
| Ordinary income | 4.29 | 4.00 | (0.29) | (7)% |
| Profit attributable to owners of the parent | 3.10 | 2.90 | (0.20) | (6)% |
| Sales (Billions of yen) | FY2025 | FY2026 Forecast | Difference | YoY change |
|---|---|---|---|---|
| Alcoholic beverages | 81.6 | 82.6 | 1.0 | 1% |
| Ko-type shochu | 12.2 | 12.1 | (0.1) | (1)% |
| Otsu-type shochu (including ko-otsu blended shochu) | 24.2 | 24.4 | 0.2 | 1% |
| Chu-hi (RTD) | 19.7 | 20.2 | 0.5 | 3% |
| Brewing and industrial alcohol | 13.6 | 13.6 | 0.0 | 1% |
| Wine and spirits | 5.4 | 5.6 | 0.2 | 4% |
| Enzymes and pharmaceuticals | 4.6 | 5.0 | 0.4 | 8% |
| Real estate | 1.4 | 1.4 | 0.0 | 0% |
By segment, operating income is forecast to fall in alcoholic beverages and rise in the other two segments. The forecast slide shows operating income of 2.30 billion yen for alcoholic beverages, a difference of (0.26) or (10)%; 0.87 billion yen for enzymes and pharmaceuticals, a difference of 0.06 or 8%; and 0.78 billion yen for real estate, a difference of 0.01 or 1%. The bridge for alcoholic beverages shows higher sales and higher unit prices of +0.80 and SG&A expenses and others of +0.02, against cost of sales of (1.08), within which an FX impact of (0.45) is noted.
| Operating income (Billions of yen) | FY2026 Forecast | Difference | YoY change |
|---|---|---|---|
| Alcoholic beverages | 2.30 | (0.26) | (10)% |
| Enzymes and pharmaceuticals | 0.87 | 0.06 | 8% |
| Real estate | 0.78 | 0.01 | 1% |
Priorities for FY2026
The materials set out priorities by category. For chu-hi (RTD) and chu-hi base spirit, the company cites the narrowing price gap with beer, diversification of chu-hi products and outflow of existing chu-hi consumers toward chu-hi base spirit; it shows the unification of tax rates due to the liquor tax revision on a 350ml-equivalent basis, and forecasts chu-hi base spirit sales of 1.7 billion yen in 2026 against 1.6 billion yen in 2025 and 1.4 billion yen in 2024. For otsu-type shochu, an April price increase on Hakata no Hana, growth in ko-otsu blended shochu, and a broader lineup of TanTakaTan (non-carbonated) and KOKOYOI (aroma-focused), both launched in September 2025. Sake sales are shown flat at 3.6 billion yen across 2024, 2025 and 2026 (forecast), with renovation of FUKUTOKUCHO’s Nirasaki paper carton bottle line raising production efficiency by approximately 13% and reducing the workforce by four; operations are planned to start in September 2026 with an investment of approximately 0.6 billion yen.
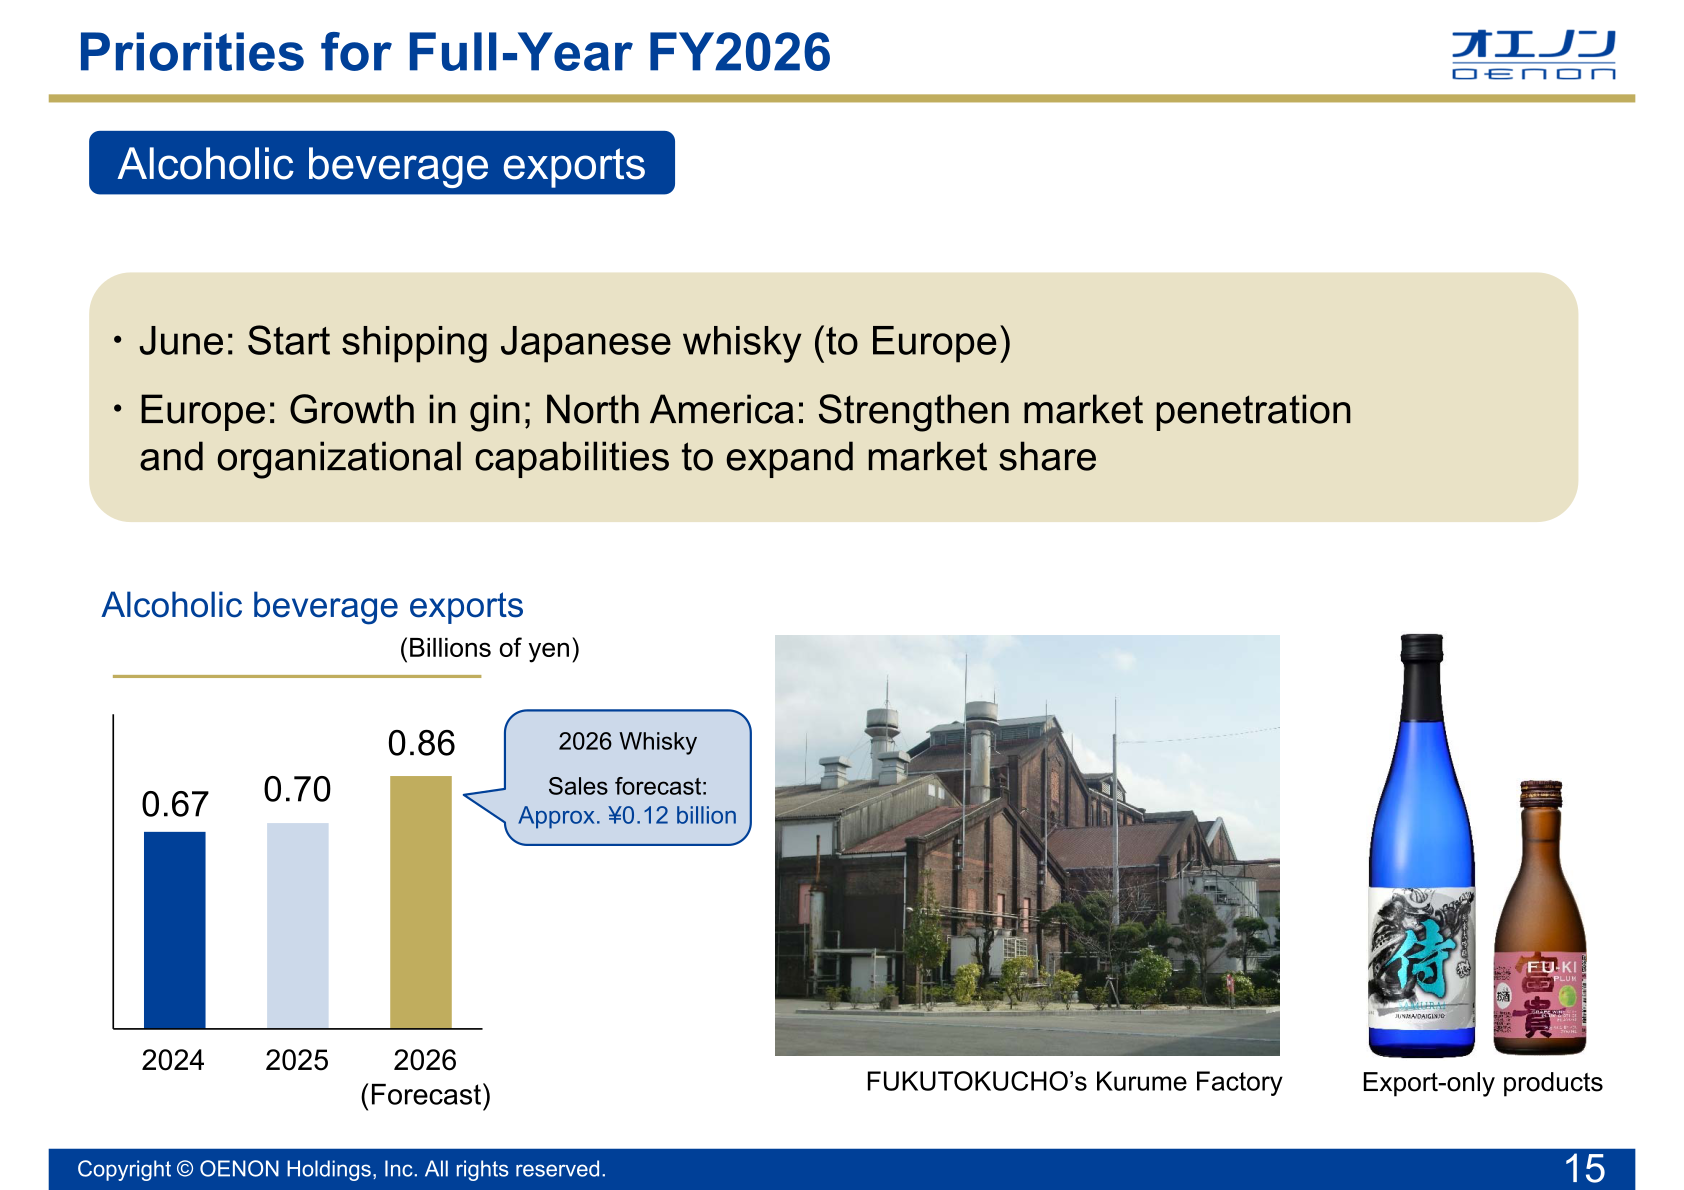
In exports, the company plans to start shipping Japanese whisky to Europe in June, with a 2026 whisky sales forecast of approximately 0.12 billion yen, and targets growth in gin in Europe and greater market penetration in North America. Alcoholic beverage exports are shown at 0.67 billion yen in 2024, 0.70 billion yen in 2025 and 0.86 billion yen in the 2026 forecast. In enzymes, the company plans to respond to strong overseas demand for lactase and to strengthen the operational structure for the lactic acid bacteria contract business, supported by a large-scale capital investment at GODO SHUSEI’s enzymes and pharmaceuticals factory of approximately 0.9 billion yen, broken down into lactase 0.5 billion yen, contract manufacturing 0.2 billion yen and facility/infrastructure 0.2 billion yen.
Shareholder Returns
The results briefing materials do not contain a dividend or shareholder return slide. This cannot be confirmed from the materials.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















