
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Shin Nippon Biomedical Laboratories (SNBL) labels the fiscal year ended March 31, 2026 as “FY3/26” in its materials, while this site classifies the most recently completed fiscal year as FY2025. All labels, units and figures in the text and tables below follow the company’s presentation.
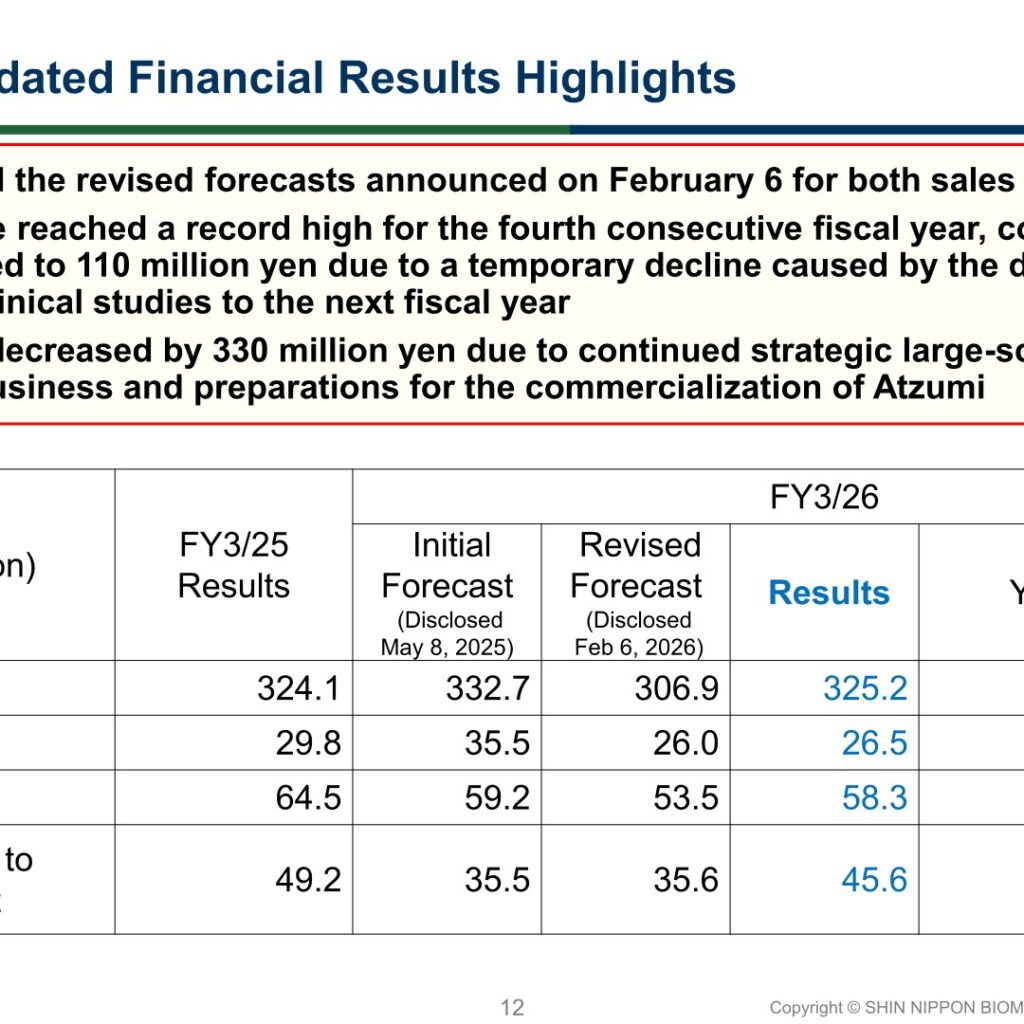
SNBL reported revenue of ¥325.2 hundred million (¥32,524 million) for the fiscal year ended March 31, 2026, a record high for the fourth consecutive fiscal year, but revenue growth was limited to ¥110 million because several large-scale nonclinical studies were deferred to the following fiscal year. Operating profit fell 11.1% to ¥26.5 hundred million as the company continued large-scale strategic investment in the nonclinical business and prepared for the commercialization of Satsuma’s intranasal migraine drug Atzumi. Results nevertheless exceeded the revised forecasts announced on February 6, 2026 for both sales and profit. Order intake in the nonclinical CRO business rose 11.3% year on year to ¥35.7 billion, a new record high.
Consolidated Results (Full-Year Actual)
Against the initial forecast disclosed on May 8, 2025 and the revised forecast disclosed on February 6, 2026, actual revenue, operating profit, ordinary profit and profit attributable to owners of parent all came in above the revised plan. Ordinary profit declined ¥6.2 hundred million year on year, reflecting a smaller contribution from equity-method earnings.
| Item (¥100 million) | FY3/25 Results | FY3/26 Initial Forecast (Disclosed May 8, 2025) | FY3/26 Revised Forecast (Disclosed Feb 6, 2026) | FY3/26 Results | YoY Change | YoY % |
|---|---|---|---|---|---|---|
| Revenue | 324.1 | 332.7 | 306.9 | 325.2 | +1.1 | +0.3% |
| Operating Profit | 29.8 | 35.5 | 26.0 | 26.5 | -3.3 | -11.1% |
| Ordinary Profit | 64.5 | 59.2 | 53.5 | 58.3 | -6.2 | -9.6% |
| Profit Attributable to Owners of Parent | 49.2 | 35.5 | 35.6 | 45.6 | -3.6 | -7.3% |
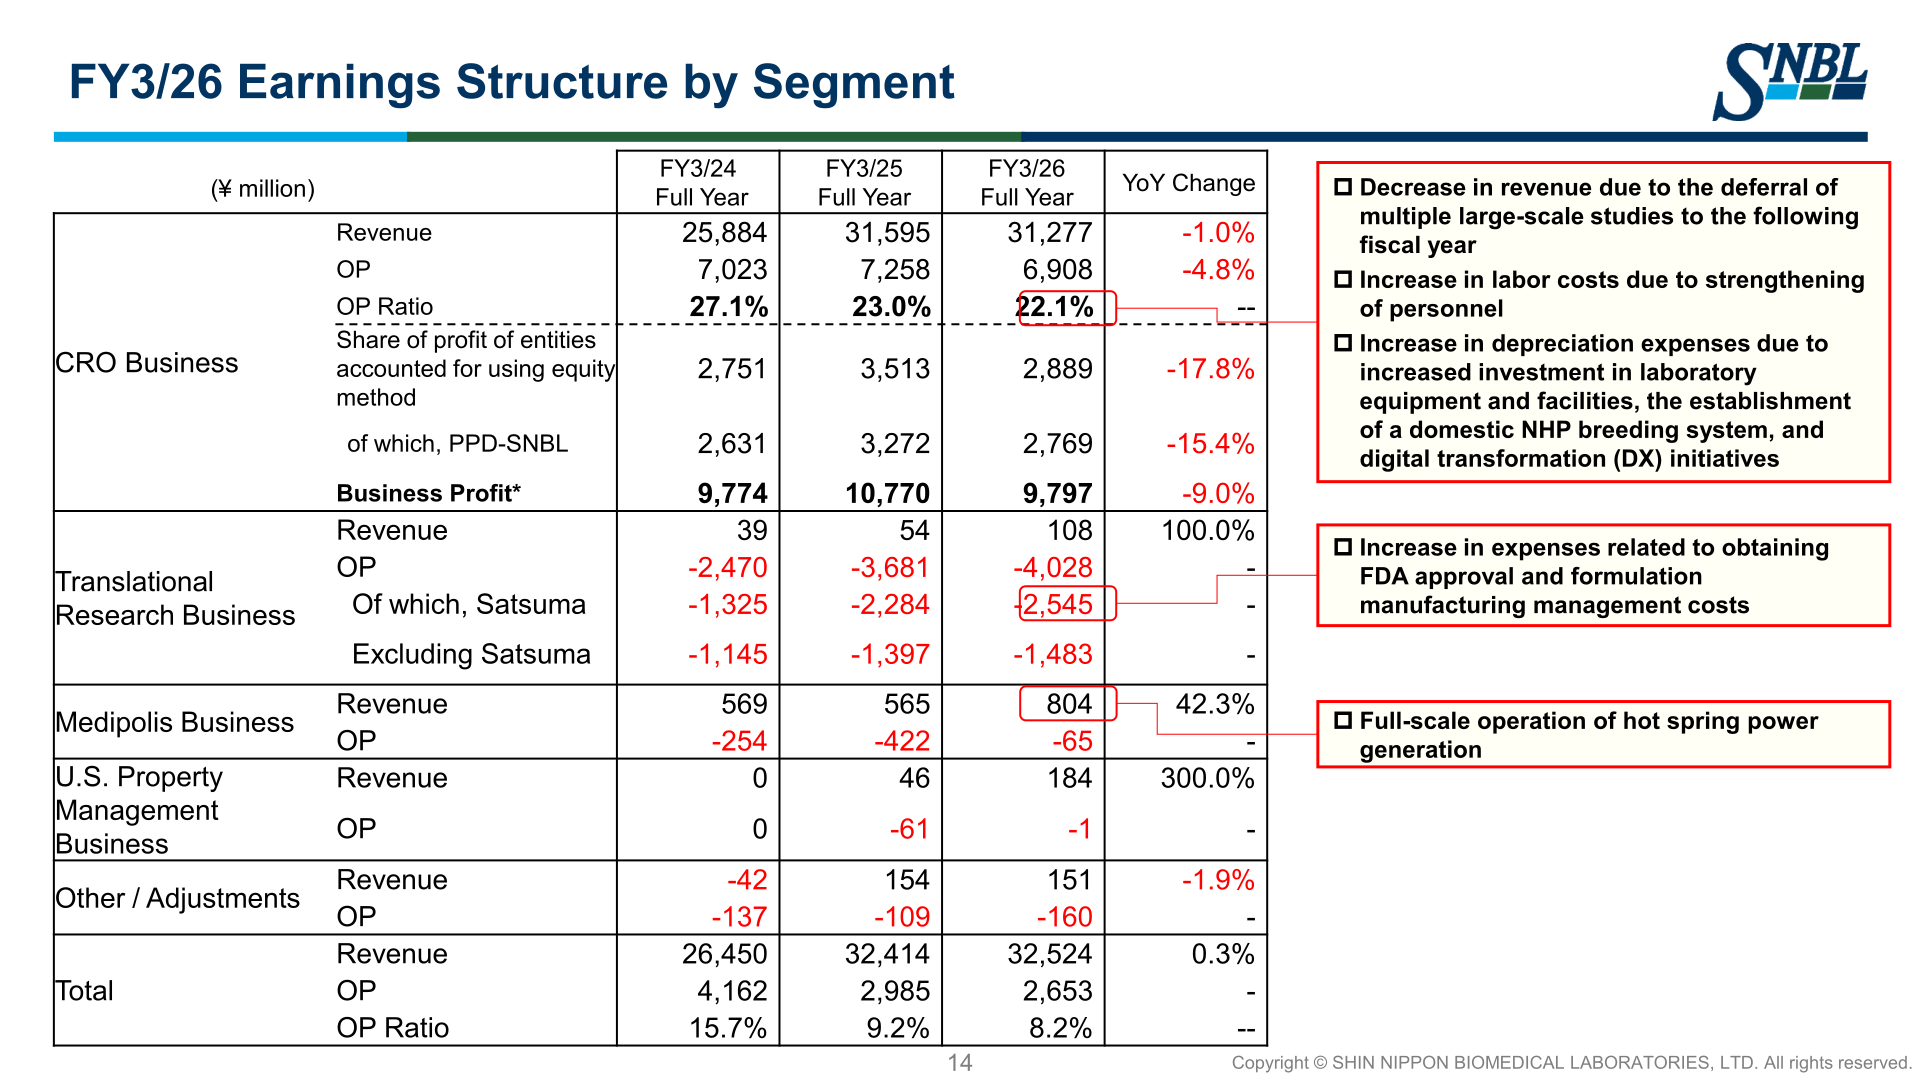
On the ¥ million basis shown in the earnings-structure slide, revenue rose from ¥32,414 million to ¥32,524 million (+¥110 million) while cost of revenue increased ¥833 million to ¥16,286 million, cutting gross profit to ¥16,238 million (-¥723 million) and the gross profit ratio to 49.9% from 52.3%. Depreciation expenses within cost of revenue rose ¥799 million to ¥2,905 million on strategic investment in laboratory equipment and facilities and the build-out of a domestic NHP breeding system, and labor cost rose ¥526 million to ¥8,725 million on workforce expansion. SG&A expenses fell ¥392 million to ¥13,584 million. Share of profit of entities accounted for using the equity method fell ¥733 million to ¥2,780 million, of which PPD-SNBL accounted for ¥2,769 million (down from ¥3,272 million).
Segment Results
CRO business revenue slipped 1.0% to ¥31,277 million on the deferral of multiple large-scale studies, with operating profit down 4.8% to ¥6,908 million and business profit — defined by the company as the sum of operating profit and the share of profit of entities accounted for using the equity method — down 9.0% to ¥9,797 million. The Translational Research business widened its operating loss to ¥4,028 million, of which Satsuma accounted for ¥2,545 million, on higher expenses related to obtaining FDA approval and formulation manufacturing management costs. The Medipolis business narrowed its operating loss to ¥65 million, an improvement of ¥357 million year on year, on full-scale operation of hot spring power generation.
| Segment | Metric (¥ million) | FY3/25 Full Year | FY3/26 Full Year | YoY Change |
|---|---|---|---|---|
| CRO Business | Revenue | 31,595 | 31,277 | -1.0% |
| CRO Business | OP | 7,258 | 6,908 | -4.8% |
| CRO Business | of which, PPD-SNBL (equity method) | 3,272 | 2,769 | -15.4% |
| CRO Business | Business Profit* | 10,770 | 9,797 | -9.0% |
| Translational Research Business | Revenue | 54 | 108 | 100.0% |
| Translational Research Business | OP | -3,681 | -4,028 | – |
| Translational Research Business | OP: of which, Satsuma | -2,284 | -2,545 | – |
| Medipolis Business | Revenue | 565 | 804 | 42.3% |
| Medipolis Business | OP | -422 | -65 | – |
| U.S. Property Management Business | Revenue | 46 | 184 | 300.0% |
| U.S. Property Management Business | OP | -61 | -1 | – |
| Other / Adjustments | Revenue | 154 | 151 | -1.9% |
| Other / Adjustments | OP | -109 | -160 | – |
| Total | Revenue | 32,414 | 32,524 | 0.3% |
| Total | OP | 2,985 | 2,653 | – |
| Total | OP Ratio | 9.2% | 8.2% | — |
*Business Profit is a sum of operating profit and the share of profit of entities accounted for using the equity method.
Nonclinical Order Intake and Order Backlog
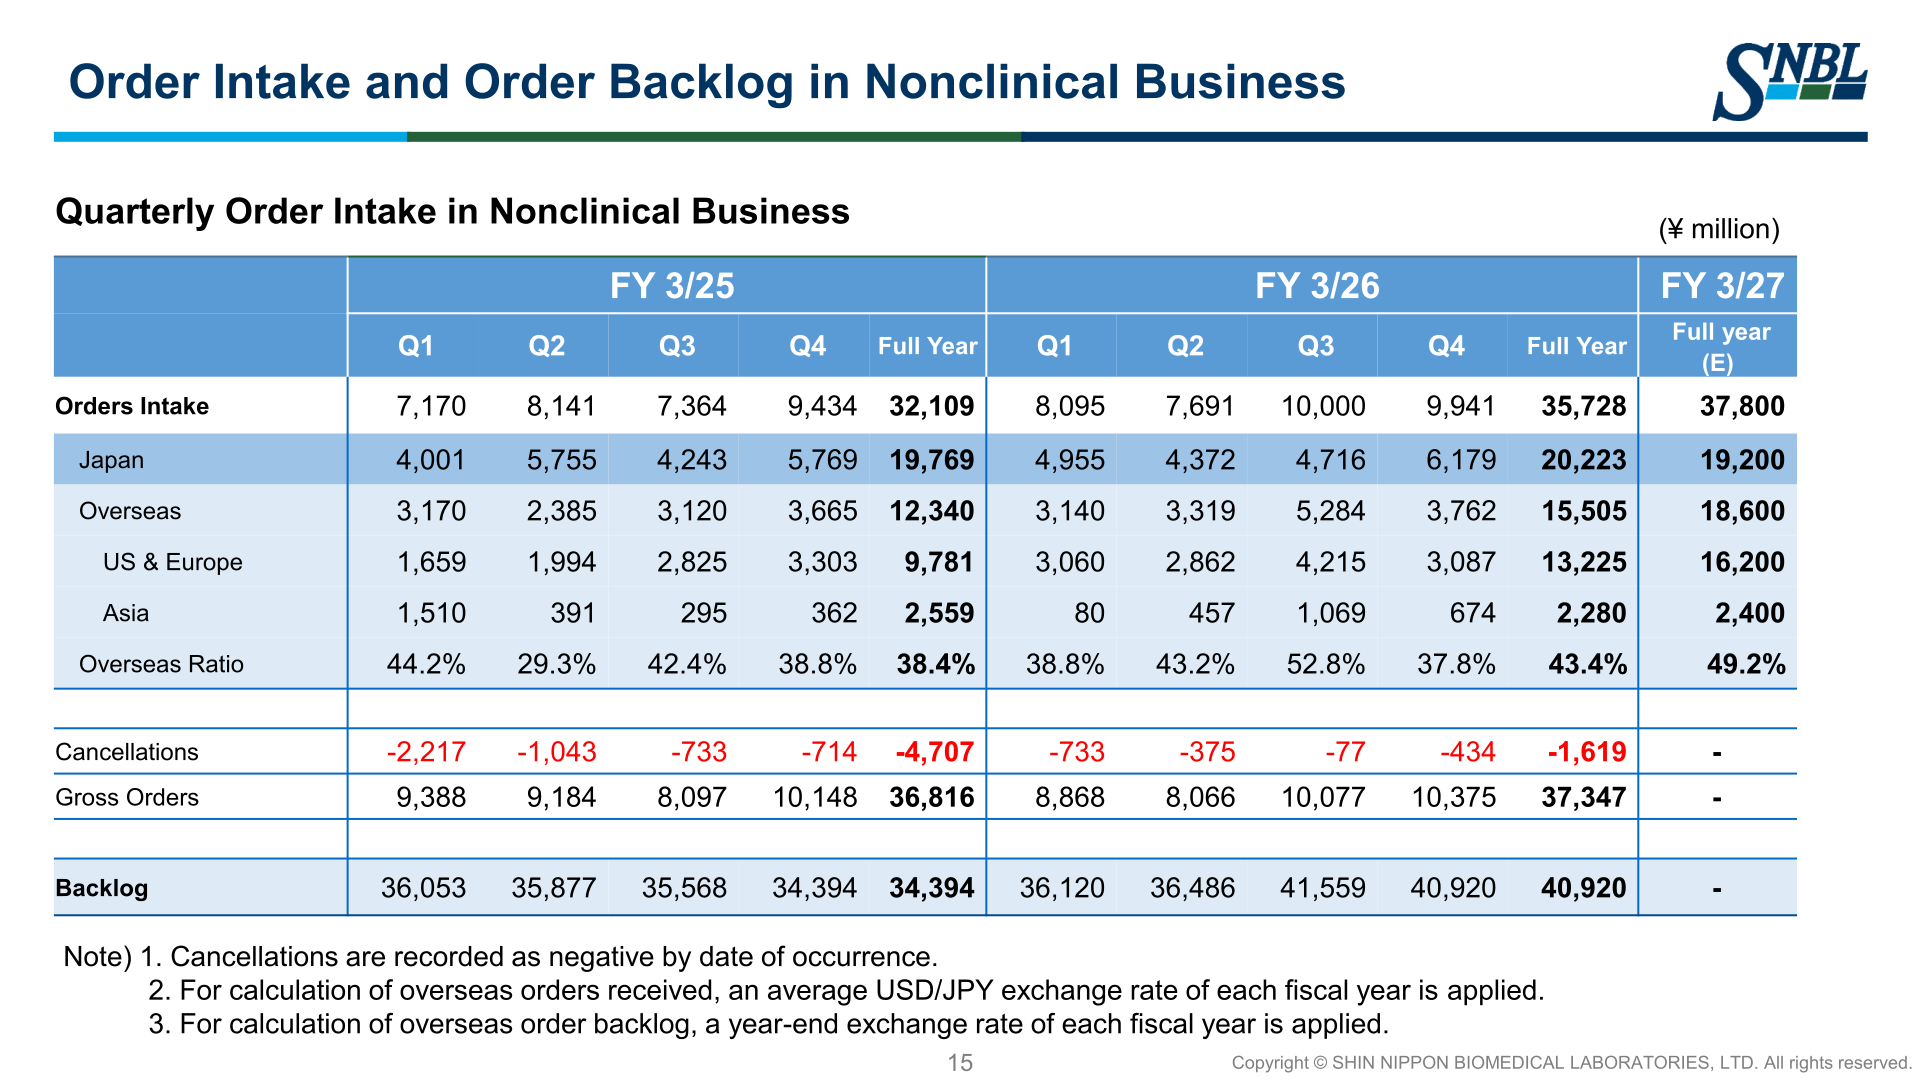
Order intake in the nonclinical business — a metric distinct from reported revenue — reached ¥35,728 million for the full year, up from ¥32,109 million, with overseas orders rising to ¥15,505 million and the overseas ratio climbing to 43.4% from 38.4%. Orders from EU and U.S. clients increased ¥3,444 million year on year (+35%), domestic orders increased ¥455 million (+2%), and Asian orders decreased ¥279 million (-11%). Year-end order backlog stood at ¥40,920 million against ¥34,394 million a year earlier. Cancellations, which are recorded as negatives by date of occurrence, narrowed to ¥1,619 million from ¥4,707 million.
| Nonclinical Business (¥ million) | FY3/25 Full Year | FY3/26 Full Year | FY3/27 Full Year (E) |
|---|---|---|---|
| Order Intake | 32,109 | 35,728 | 37,800 |
| Japan | 19,769 | 20,223 | 19,200 |
| Overseas | 12,340 | 15,505 | 18,600 |
| US & Europe | 9,781 | 13,225 | 16,200 |
| Asia | 2,559 | 2,280 | 2,400 |
| Overseas Ratio | 38.4% | 43.4% | 49.2% |
| Cancellations | -4,707 | -1,619 | – |
| Gross Orders | 36,816 | 37,347 | – |
| Backlog | 34,394 | 40,920 | – |
FY3/27 Forecast
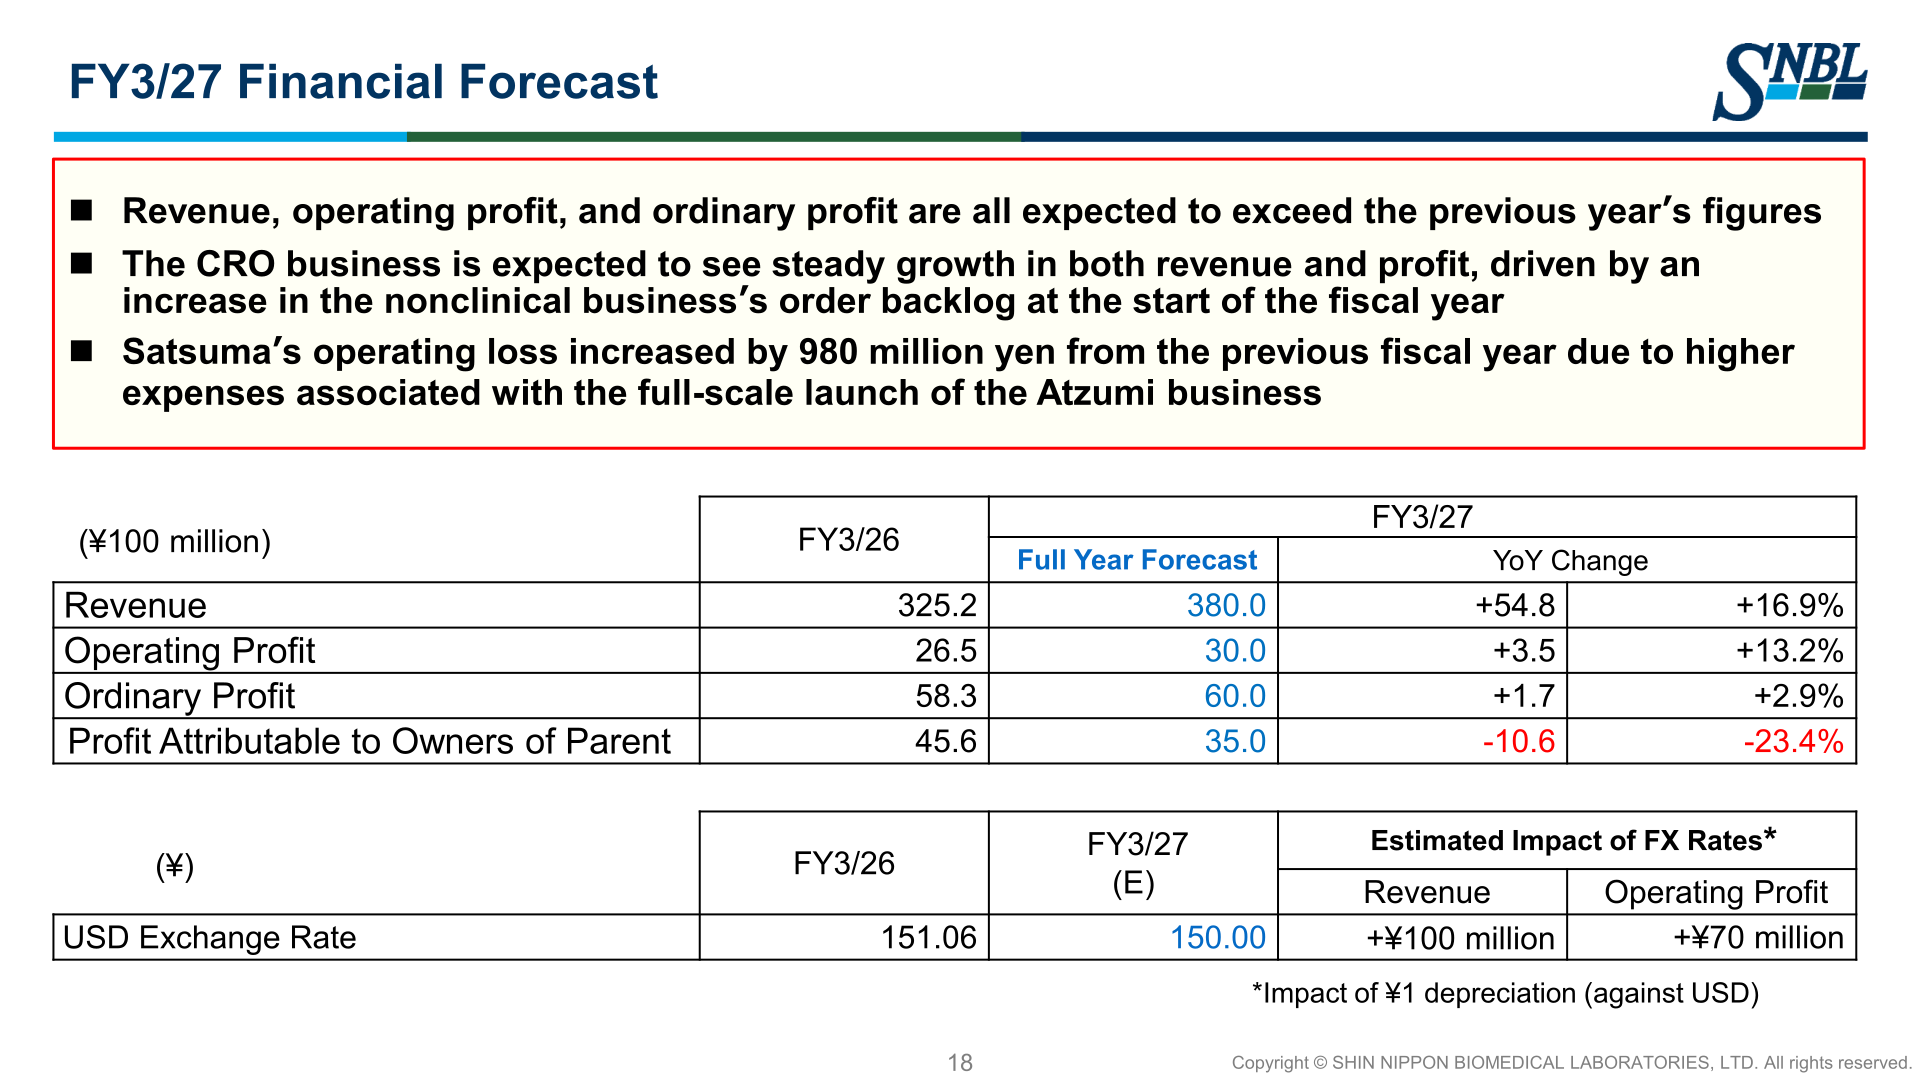
For the fiscal year ending March 31, 2027 SNBL forecasts revenue, operating profit and ordinary profit all above the prior year, with the CRO business expected to grow in both revenue and profit on the higher nonclinical order backlog carried into the year. Profit attributable to owners of parent is forecast to decline 23.4% to ¥35.0 hundred million. Satsuma’s operating loss is projected to widen by ¥980 million from the previous fiscal year on higher expenses associated with the full-scale launch of the Atzumi business. On a segment basis the company forecasts CRO business revenue of ¥36,682 million (+17.3%) and CRO operating profit of ¥8,927 million (+29.2%). The forecast assumes a USD exchange rate of ¥150.00 versus ¥151.06 in FY3/26; the company states that a ¥1 depreciation against the U.S. dollar has an estimated impact of +¥100 million on revenue and +¥70 million on operating profit.
| Item (¥100 million) | FY3/26 Full Year | FY3/27 Full Year Forecast | YoY Change | YoY % |
|---|---|---|---|---|
| Revenue | 325.2 | 380.0 | +54.8 | +16.9% |
| Operating Profit | 26.5 | 30.0 | +3.5 | +13.2% |
| Ordinary Profit | 58.3 | 60.0 | +1.7 | +2.9% |
| Profit Attributable to Owners of Parent | 45.6 | 35.0 | -10.6 | -23.4% |
Shareholder Returns
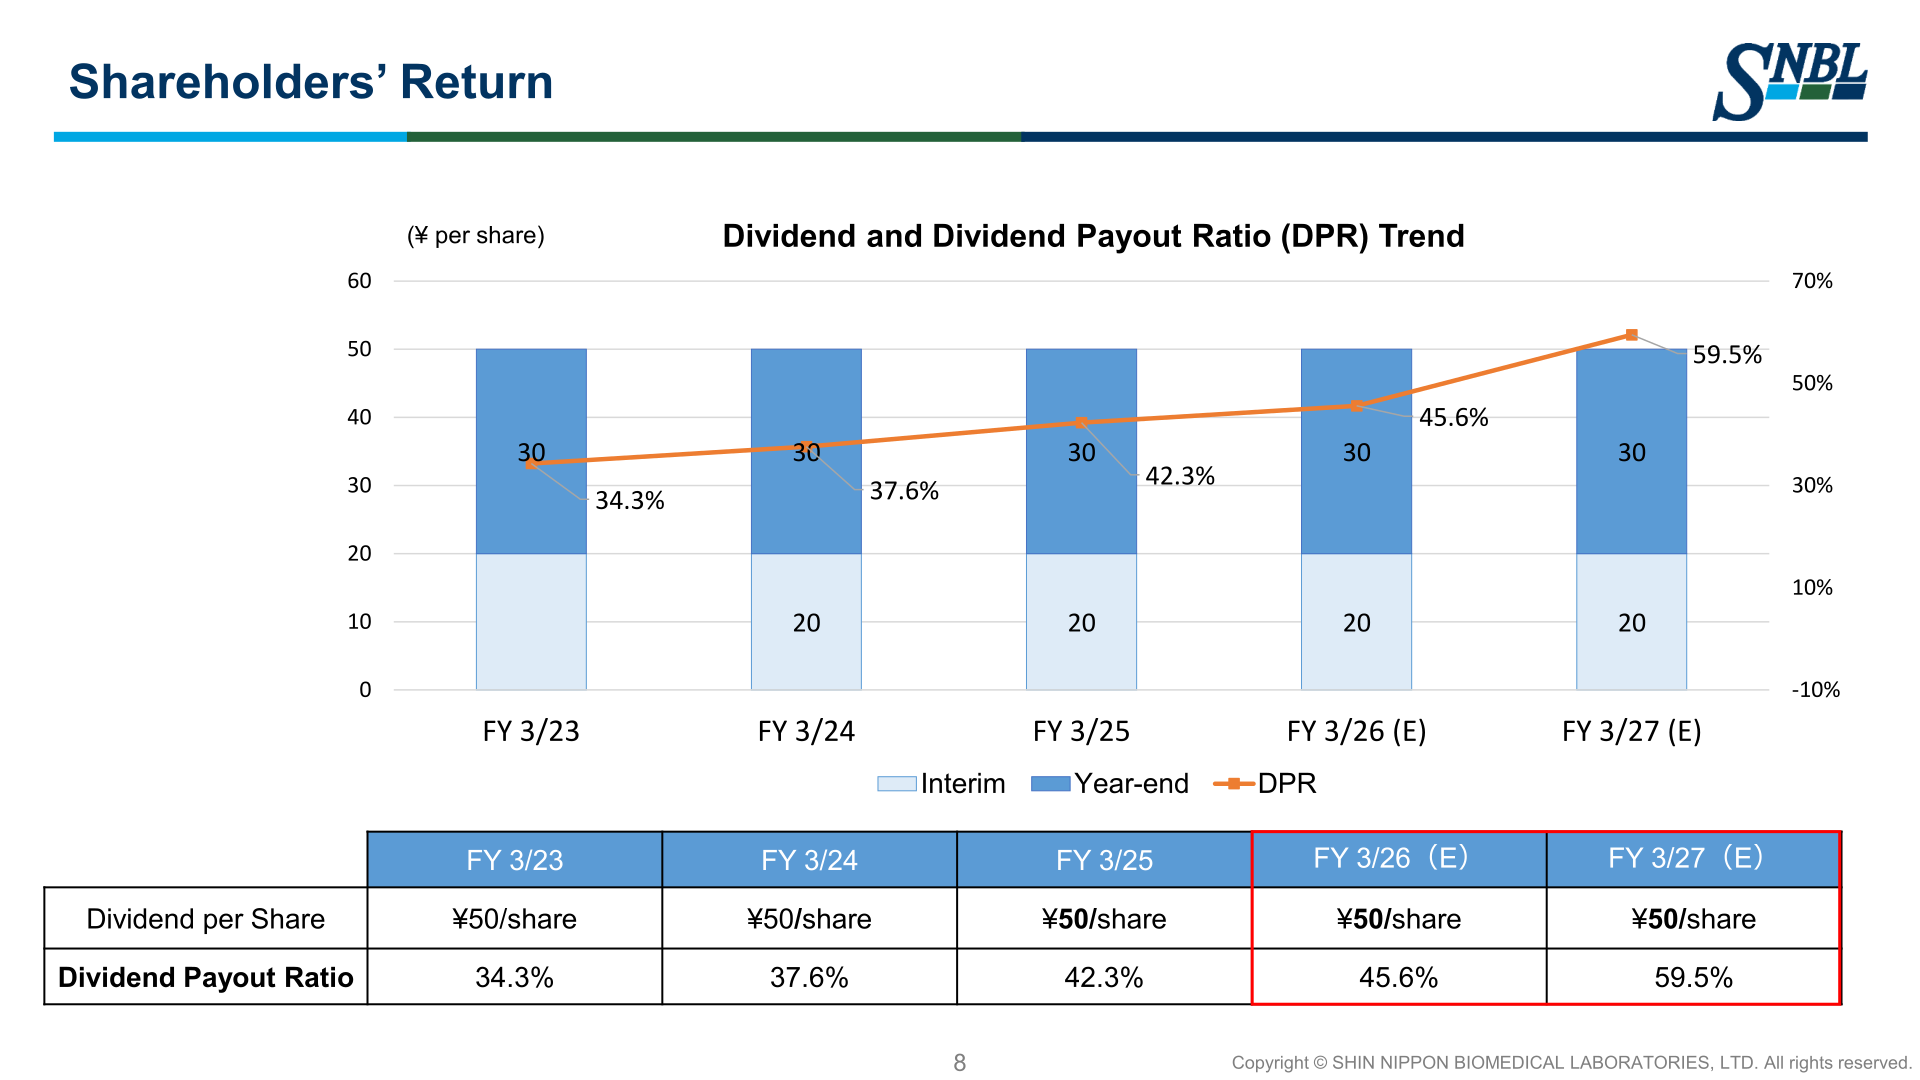
SNBL plans to maintain an annual dividend of ¥50 per share. Cash dividends per share were ¥50.0 in FY3/26, with a dividend payout ratio of 45.6%, and the company plans ¥50.0 per share again in FY3/27, implying a payout ratio of 59.5%.
| Item | FY3/24 | FY3/25 | FY3/26 | FY3/27 (E) |
|---|---|---|---|---|
| Cash dividends per share (yen) | 50.0 | 50.0 | 50.0 | 50.0 |
| Dividend payout ratio (%) | 37.6% | 42.3% | 45.6% | 59.5% |
Strategic Investment and Topics
SNBL describes itself as being in a strategic investment phase, with capital expenditure of ¥11,390 million in FY3/25 and ¥5,304 million in FY3/26 against a planned ¥11,086 million in FY3/27, while depreciation rose from ¥2,496 million to ¥3,318 million and is planned at ¥3,948 million. To further capture demand from U.S. and European clients the company has begun preparations for the construction of a world-class NHP laboratory compliant with EU standards at the Kagoshima head office site, with construction of the EU Laboratory Building scheduled for completion in autumn 2027. Consolidated headcount, excluding part-time and temporary employees, rose to 1,522 at the end of FY3/26 from 1,436, with 1,676 planned for FY3/27; the company hired 114 new graduates in April 2025 and 150 in April 2026.
In the Translational Research business, Satsuma has shifted from a complete transfer of manufacturing and sales rights to retaining those rights and leading commercialization of Atzumi itself while pursuing flexible business partnerships. The company cites projected peak sales for Atzumi exceeding $200 million in the U.S. alone. In the nasal vaccine program, SNBL received the highest “A” rating in the AMED interim evaluation and aims to complete a Phase I clinical trial within the next three years. In March 2026 SNBL was selected as a Nadeshiko Brand 2026 company — one of only 26 companies from approximately 3,900 listed companies — for its work on women’s empowerment, and it plans to appoint a new Representative Director and President.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















