
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
ITmedia Inc. reported FY25 (the fiscal year ended March 31, 2026) revenue of 8,311 million yen, up 2.6% year on year, while operating income declined 13.0% to 1,765 million yen and net income fell 20.4% to 1,191 million yen. A 15.1% revenue increase in the BtoC Media Business offset a 0.2% decline in the BtoB Media Business, but BtoB profit fell 29.1%. For the fiscal year ending March 2027 the company plans revenue of 9,200 million yen, saying it aims to “achieve record-high revenue” and deliver its “first profit increase in four fiscal year.” The company has voluntarily applied IFRS since 1Q FY16.
Consolidated Results (Full-Year Actual)
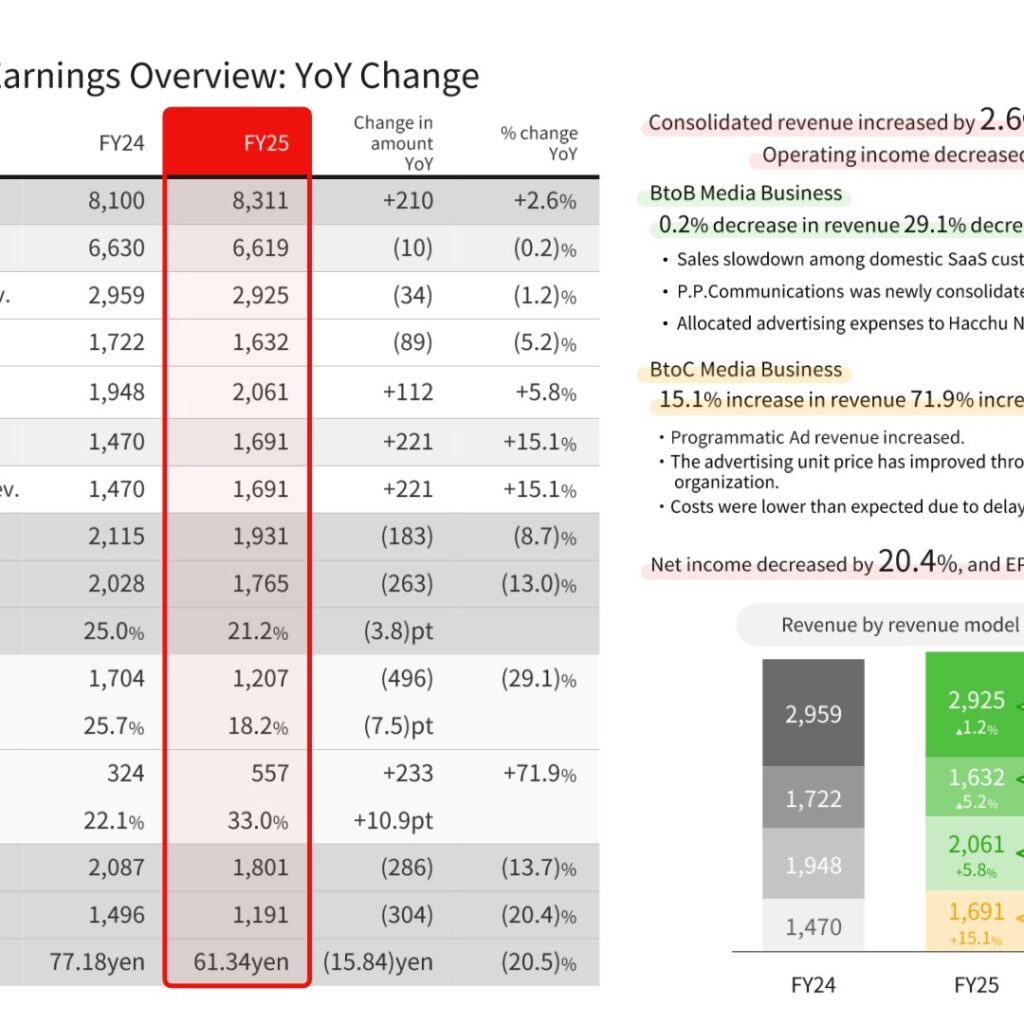
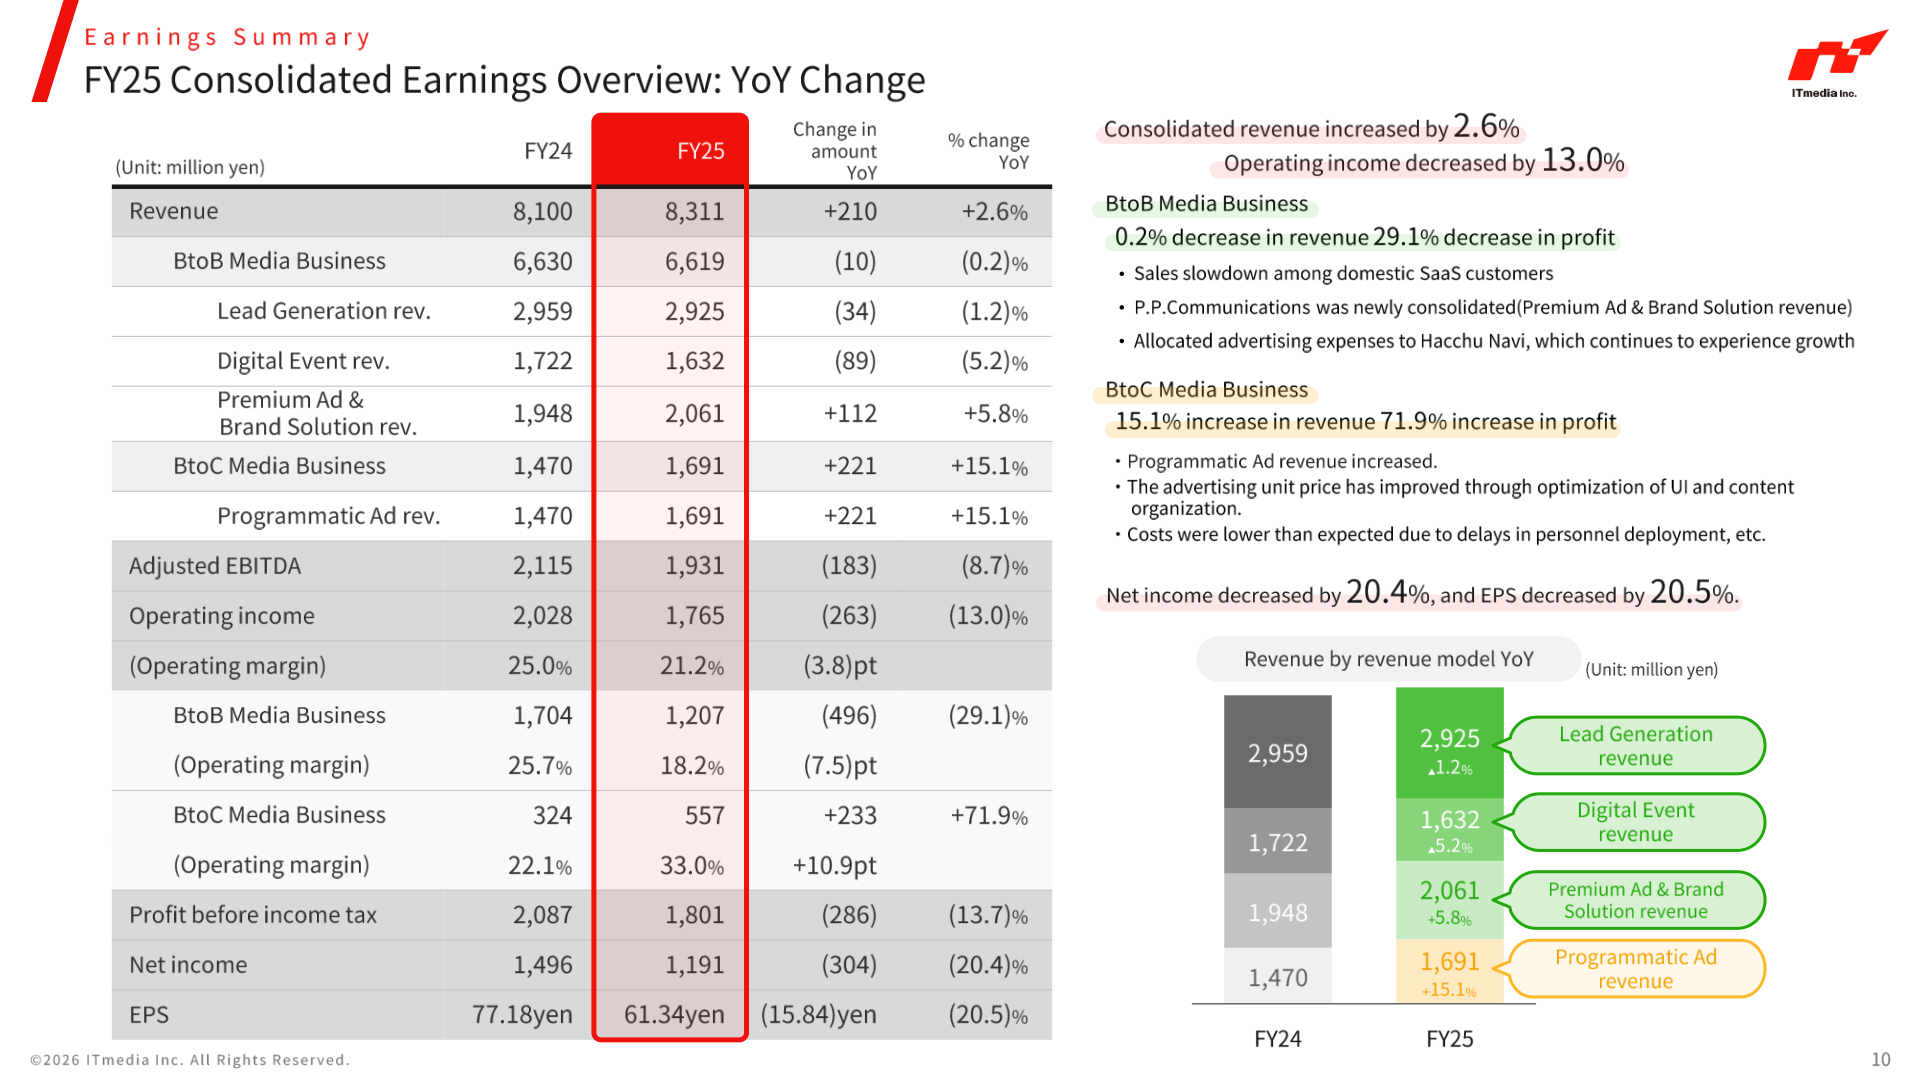
Consolidated revenue increased by 2.6% and operating income decreased by 13.0%. The operating margin narrowed 3.8pt to 21.2%. Adjusted EBITDA — a metric the company introduced as EBITDA with one-time M&A-related expenses added back — was 1,931 million yen, down 8.7%. EPS fell 20.5% to 61.34 yen.
| Item (million yen) | FY25 | FY24 | Change YoY | % change YoY |
|---|---|---|---|---|
| Revenue | 8,311 | 8,100 | +210 | +2.6 % |
| BtoB Media Business | 6,619 | 6,630 | (10) | (0.2) % |
| Lead Generation rev. | 2,925 | 2,959 | (34) | (1.2) % |
| Digital Event rev. | 1,632 | 1,722 | (89) | (5.2) % |
| Premium Ad & Brand Solution rev. | 2,061 | 1,948 | +112 | +5.8 % |
| BtoC Media Business | 1,691 | 1,470 | +221 | +15.1 % |
| Programmatic Ad rev. | 1,691 | 1,470 | +221 | +15.1 % |
| Adjusted EBITDA | 1,931 | 2,115 | (183) | (8.7) % |
| Operating income | 1,765 | 2,028 | (263) | (13.0) % |
| (Operating margin) | 21.2 % | 25.0 % | (3.8)pt | – |
| Profit before income tax | 1,801 | 2,087 | (286) | (13.7) % |
| Net income | 1,191 | 1,496 | (304) | (20.4) % |
| EPS | 61.34yen | 77.18yen | (15.84)yen | (20.5) % |
Segment Results
In the BtoB Media Business, revenue decreased 0.2% and operating income decreased 29.1% to 1,207 million yen, with the operating margin down 7.5pt to 18.2%. The company cites a sales slowdown among domestic SaaS customers, the new consolidation of P.P.Communications (recorded in Premium Ad & Brand Solution revenue), and advertising expenses allocated to Hacchu Navi, which continues to experience growth. In the BtoC Media Business, revenue rose 15.1% and operating income rose 71.9% to 557 million yen, lifting the operating margin 10.9pt to 33.0%; Programmatic Ad revenue increased, the advertising unit price improved through optimization of UI and content organization, and costs were lower than expected due to delays in personnel deployment.
| Segment (million yen) | Metric | FY25 | FY24 | Change YoY | % change YoY |
|---|---|---|---|---|---|
| BtoB Media Business | Revenue | 6,619 | 6,630 | (10) | (0.2) % |
| BtoB Media Business | Operating income | 1,207 | 1,704 | (496) | (29.1) % |
| BtoB Media Business | (Operating margin) | 18.2 % | 25.7 % | (7.5)pt | – |
| BtoC Media Business | Revenue | 1,691 | 1,470 | +221 | +15.1 % |
| BtoC Media Business | Operating income | 557 | 324 | +233 | +71.9 % |
| BtoC Media Business | (Operating margin) | 33.0 % | 22.1 % | +10.9pt | – |
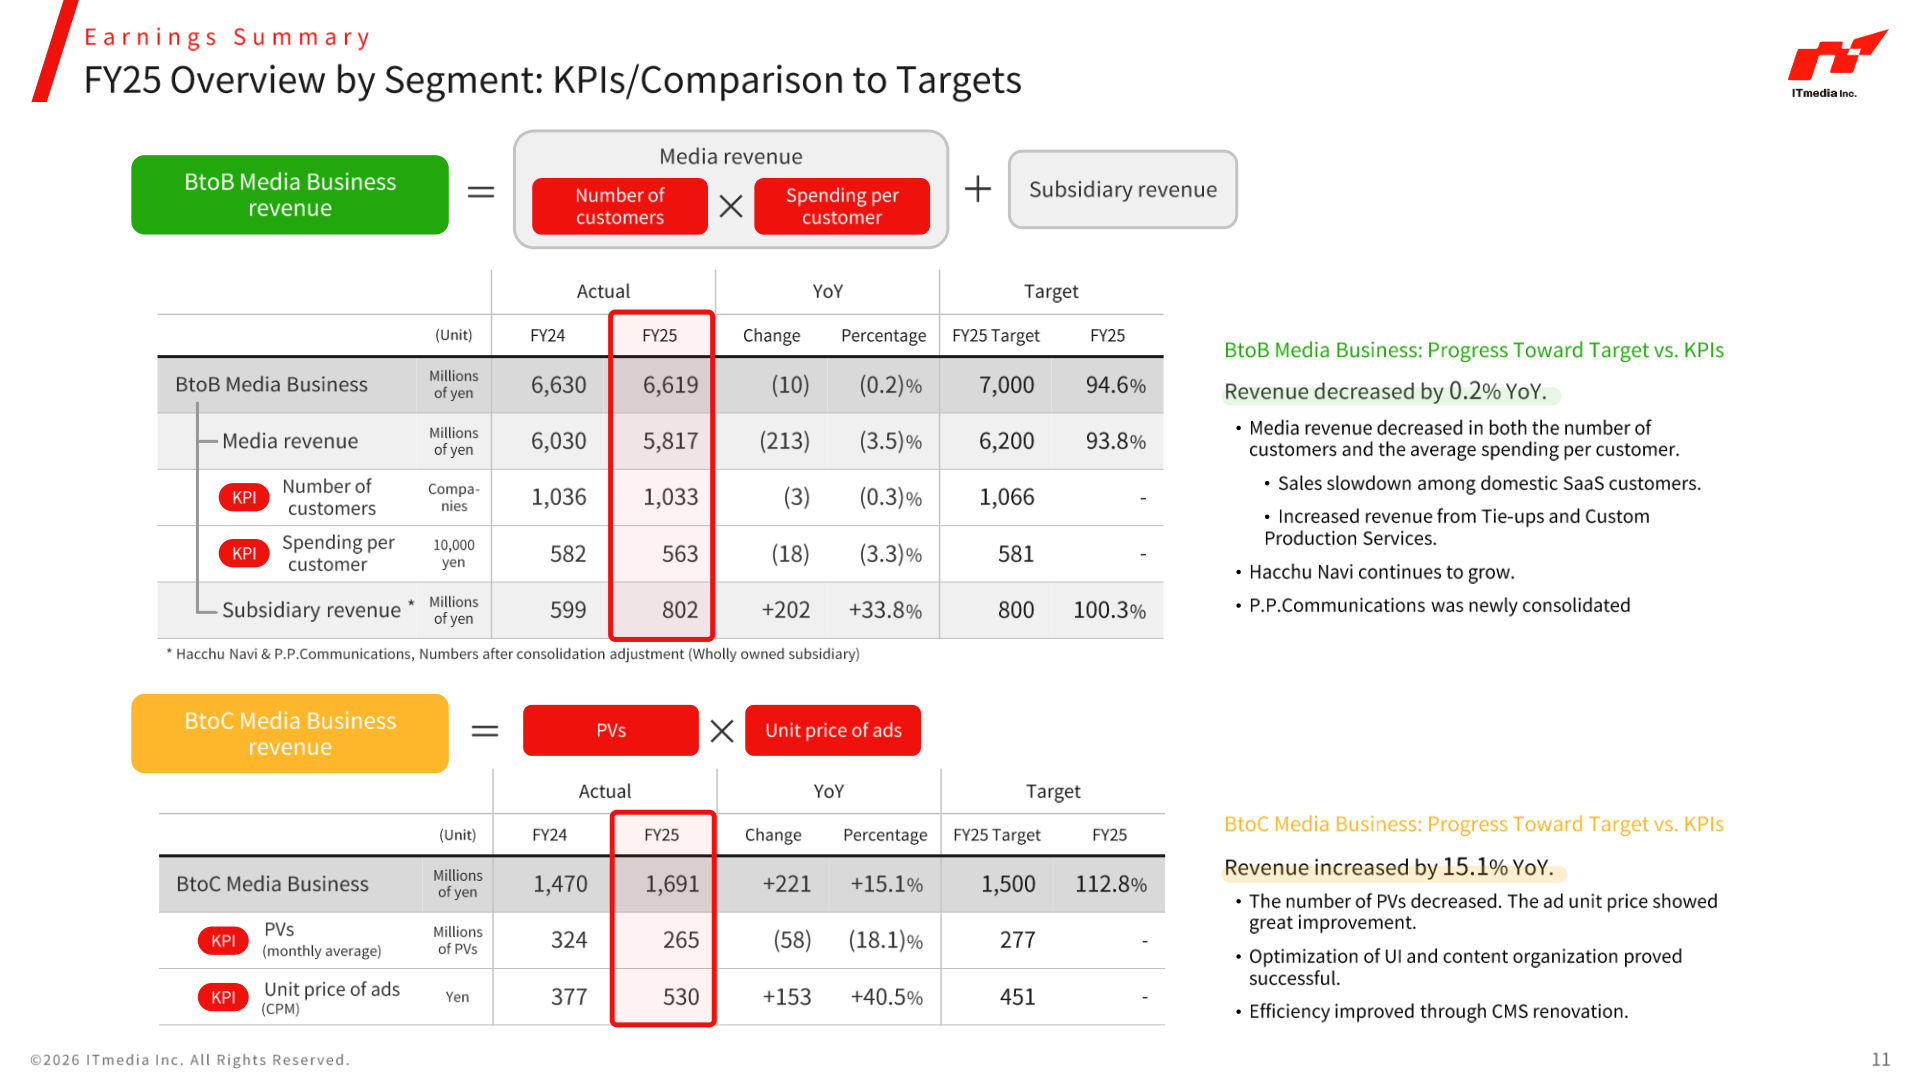
Against the company’s own FY25 targets, the BtoB Media Business reached 94.6% of plan and the BtoC Media Business reached 112.8%. BtoB media revenue declined in both the number of customers and spending per customer, while subsidiary revenue (Hacchu Navi and P.P.Communications, after consolidation adjustment) grew 33.8%. In BtoC, monthly average PVs fell 18.1% but the CPM ad unit price rose 40.5%.
| KPI | Unit | FY24 | FY25 | Change | Percentage | FY25 Target | Target FY25 |
|---|---|---|---|---|---|---|---|
| BtoB Media Business | Millions of yen | 6,630 | 6,619 | (10) | (0.2) % | 7,000 | 94.6 % |
| Media revenue | Millions of yen | 6,030 | 5,817 | (213) | (3.5) % | 6,200 | 93.8 % |
| Number of customers | Companies | 1,036 | 1,033 | (3) | (0.3) % | 1,066 | – |
| Spending per customer | 10,000 yen | 582 | 563 | (18) | (3.3) % | 581 | – |
| Subsidiary revenue | Millions of yen | 599 | 802 | +202 | +33.8 % | 800 | 100.3 % |
| BtoC Media Business | Millions of yen | 1,470 | 1,691 | +221 | +15.1 % | 1,500 | 112.8 % |
| PVs (monthly average) | Millions of PVs | 324 | 265 | (58) | (18.1) % | 277 | – |
| Unit price of ads (CPM) | Yen | 377 | 530 | +153 | +40.5 % | 451 | – |
Topics
Key FY25 initiatives disclosed in the materials include the free release of the Pipeline Dashboard customer data management platform, growth of the “ITmedia AI+” media, which recorded a record high 3 million PVs in July 2025, and a partnership with Perplexity under which ITmedia joined the Perplexity Publishers’ Program with permission to use its content and revenue sharing. The company also notes that the impact of AI search is gradually expanding worldwide with a decrease in traffic from traditional Google searches in some areas. Hacchu Navi member companies reached 8,000 in January 2026 (from 7,000 in May 2025 and 5,000 in February 2024), industry DX partnerships progressed to 29 companies against a mid-term goal of 100, and the number of ITmedia IDs exceeded 2 million.
On M&A, the company acquired shares of P.P.Communications Inc. and recorded 28 million yen in related expenses in Q3, and acquired shares of Majisemi Co., Ltd., recording 36 million yen in related expenses in Q4; Majisemi became a wholly owned subsidiary on April 1, 2026. Majisemi provides a subscription-based “Webinar as a Service” offering, and the materials cite synergies from data integration and intent data enrichment and from expanding resources and share of digital events in the technology field.
Full-Year Forecast (Fiscal Year Ending March 2027)
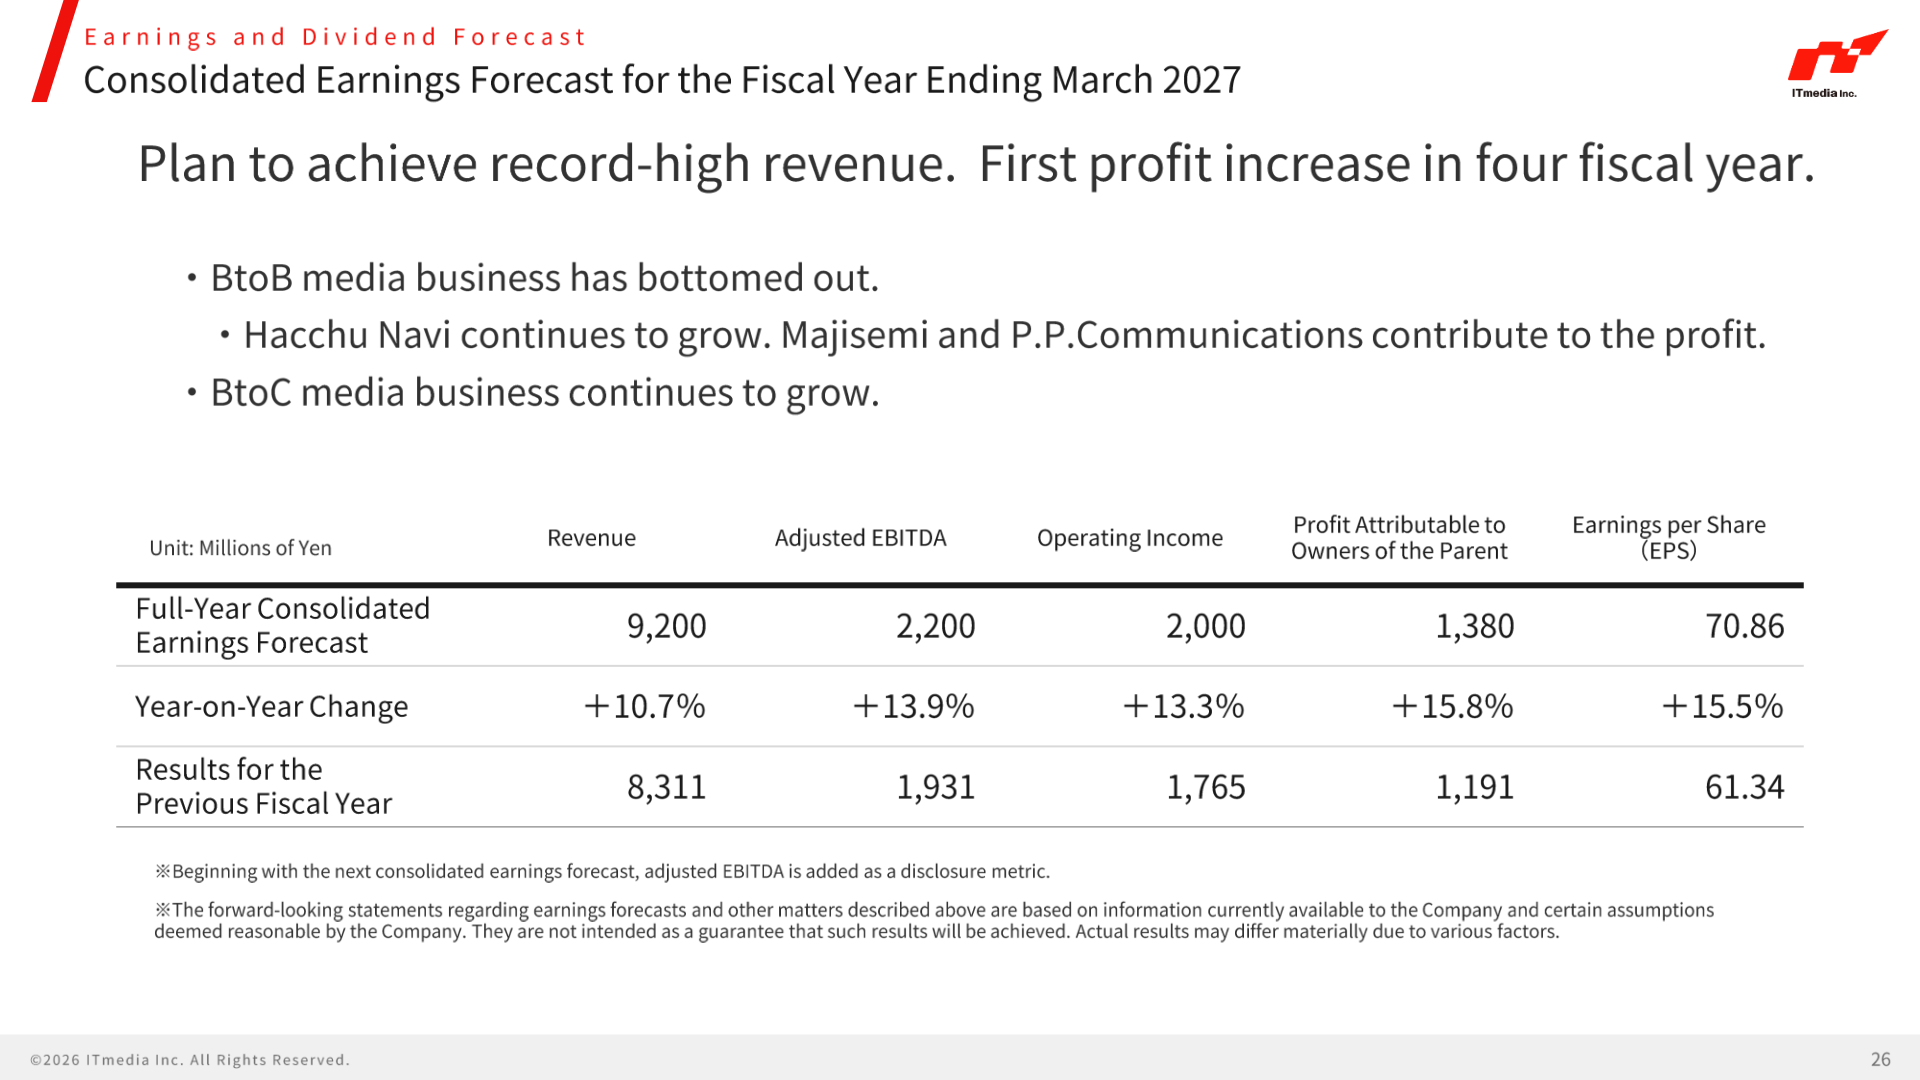
The company forecasts revenue of 9,200 million yen (+10.7%), Adjusted EBITDA of 2,200 million yen (+13.9%), operating income of 2,000 million yen (+13.3%), profit attributable to owners of the parent of 1,380 million yen (+15.8%) and EPS of 70.86 yen (+15.5%). The materials state that the BtoB media business has bottomed out, that Hacchu Navi continues to grow with Majisemi and P.P.Communications contributing to profit, and that the BtoC media business continues to grow. Beginning with this forecast, Adjusted EBITDA is added as a disclosure metric.
| Item (millions of yen) | Full-Year Consolidated Earnings Forecast | Year-on-Year Change | Results for the Previous Fiscal Year |
|---|---|---|---|
| Revenue | 9,200 | +10.7 % | 8,311 |
| Adjusted EBITDA | 2,200 | +13.9 % | 1,931 |
| Operating Income | 2,000 | +13.3 % | 1,765 |
| Profit Attributable to Owners of the Parent | 1,380 | +15.8 % | 1,191 |
| Earnings per Share (EPS) | 70.86 | +15.5 % | 61.34 |
Shareholder Returns
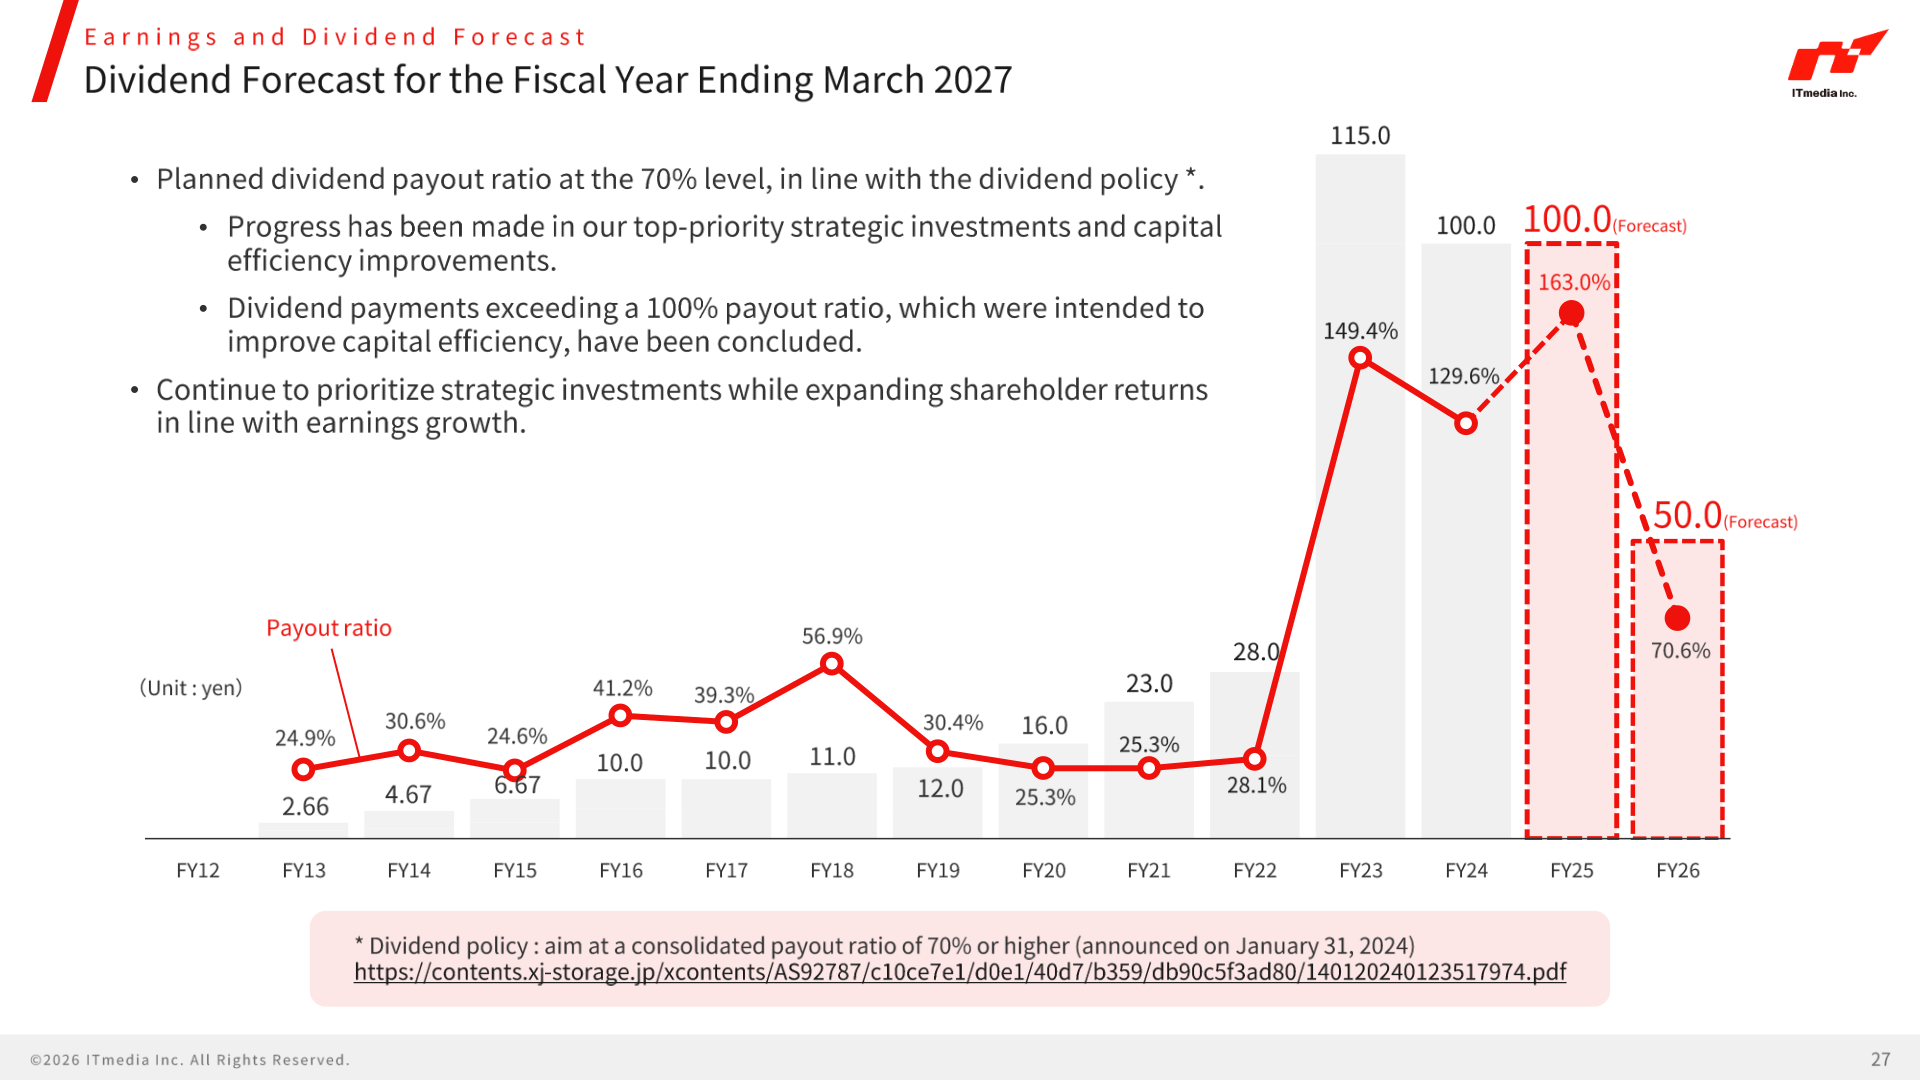
The company’s dividend policy, announced on January 31, 2024, aims at a consolidated payout ratio of 70% or higher. The dividend chart shows an annual dividend of 100.0 yen for FY25 with a payout ratio of 163.0% (labeled “Forecast” in the materials), following 100.0 yen in FY24 (129.6%) and 115.0 yen in FY23 (149.4%). For FY26 the company plans 50.0 yen, a payout ratio of 70.6%, stating that the planned payout ratio is at the 70% level in line with the dividend policy, that progress has been made in top-priority strategic investments and capital efficiency improvements, and that dividend payments exceeding a 100% payout ratio, which were intended to improve capital efficiency, have been concluded. It adds that it will continue to prioritize strategic investments while expanding shareholder returns in line with earnings growth.
| Item (unit: yen) | FY23 | FY24 | FY25 | FY26 |
|---|---|---|---|---|
| Dividend per share | 115.0 | 100.0 | 100.0 (Forecast) | 50.0 (Forecast) |
| Payout ratio | 149.4% | 129.6% | 163.0% | 70.6% |
Financial Policy and Mid-Term Targets
Under the cash flow allocation policy disclosed in May 2025, cash inflow of 20–25 billion yen comprises retained earnings of 7.6 billion yen (as of March 31, 2025), operating cash flow of 10–13 billion yen for the period of the plan and leveraged debt of 3–5 billion yen, against capital utilization of 14.5–20 billion yen including growth investments of 6–10 billion yen and shareholder returns of 8.5–10 billion yen. Within growth investments, the company sets investments for existing businesses and R&D at 1–2 billion yen and a medium-term investment limit for strategic investments and new businesses (M&A investment limit) of 5–8 billion yen.
The mid-term targets, also disclosed in May 2025, are to be achieved in FY29: EPS of 140 yen, with operating income of 3,000–4,000 million yen and net income of around 2,700 million yen. The company frames these around growth investment as a top priority, financial soundness and capital efficiency. It also notes a briefing session on its business and medium-term strategy for institutional investors and analysts held on May 26, 2026.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















