
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: MIXI, Inc. labels the fiscal year ended March 31, 2026 as “FY2026”. On this site that year is classified as FY2025 because it is the company’s most recently completed full fiscal year; all labels in the text, tables and segment data below are kept exactly as they appear in the company’s materials.
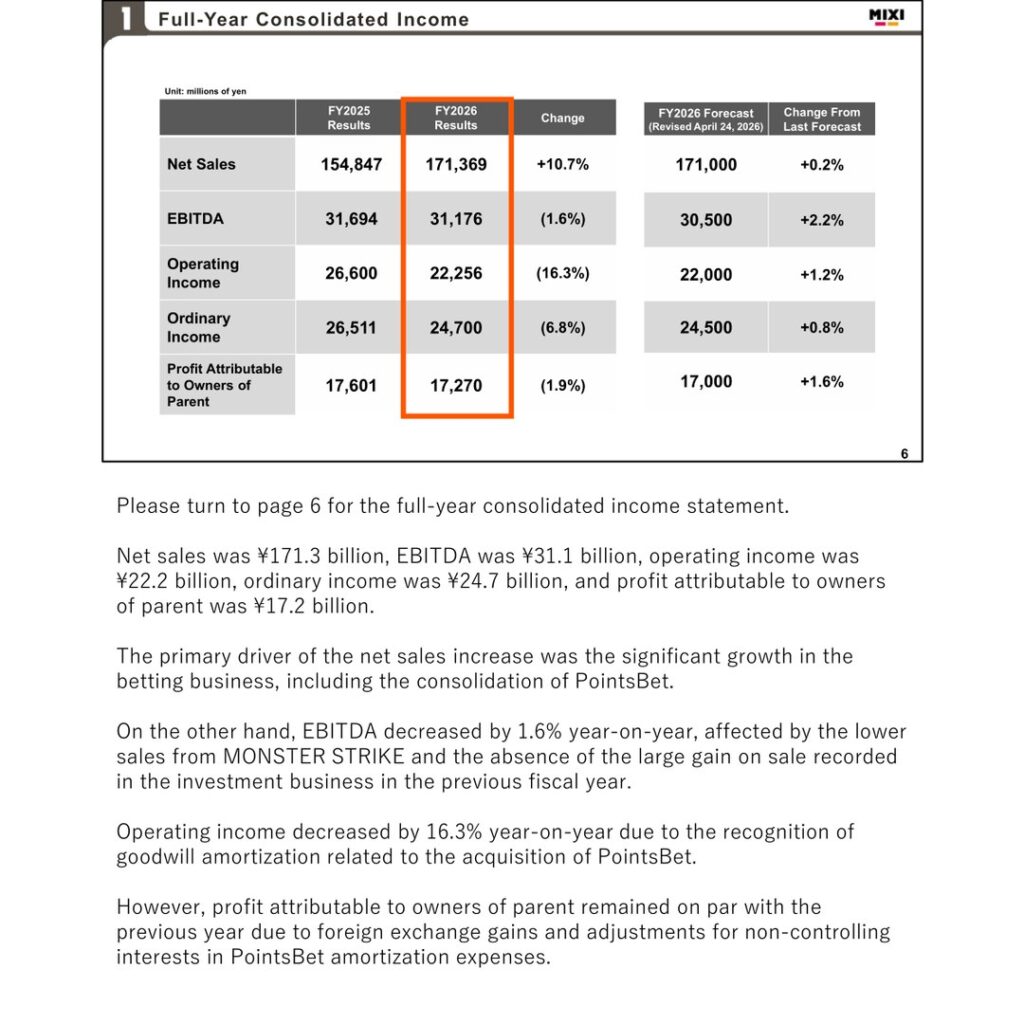
MIXI, Inc. reported full-year net sales of 171,369 million yen for FY2026 (April 1, 2025 – March 31, 2026), up 10.7% year on year, driven mainly by the recent consolidation of PointsBet and growth in the betting businesses. EBITDA declined 1.6% to 31,176 million yen on lower MONSTER STRIKE sales and the absence of the large gain on sale recorded in the investment business in the previous fiscal year, while operating income fell 16.3% to 22,256 million yen as goodwill and other amortization related to the PointsBet acquisition was recognized. Profit attributable to owners of parent was 17,270 million yen, down 1.9% and broadly flat year on year, helped by foreign exchange gains. All five headline lines came in above the forecast revised on April 24, 2026.
Consolidated Results (Full-Year Actual)
In the company’s own words, net sales was ¥171.3 billion, EBITDA was ¥31.1 billion, operating income was ¥22.2 billion, ordinary income was ¥24.7 billion, and profit attributable to owners of parent was ¥17.2 billion. The primary driver of the net sales increase was the significant growth in the betting business, including the consolidation of PointsBet.
| Item | FY2026 Results | FY2025 Results | Change | FY2026 Forecast (Revised April 24, 2026) | Change From Last Forecast |
|---|---|---|---|---|---|
| Net Sales | 171,369 | 154,847 | +10.7% | 171,000 | +0.2% |
| EBITDA | 31,176 | 31,694 | (1.6%) | 30,500 | +2.2% |
| Operating Income | 22,256 | 26,600 | (16.3%) | 22,000 | +1.2% |
| Ordinary Income | 24,700 | 26,511 | (6.8%) | 24,500 | +0.8% |
| Profit Attributable to Owners of Parent | 17,270 | 17,601 | (1.9%) | 17,000 | +1.6% |
For the fourth quarter (January 2026 – March 2026), net sales were 54,944 million yen (+23.5% YoY) and EBITDA was 13,213 million yen (+19.6% YoY), both up around 20% on favorable performance by the betting businesses and the recent consolidation of PointsBet. Operating income was 9,087 million yen ((5.0%)), ordinary income 9,609 million yen ((1.7%)) and profit attributable to owners of parent 6,707 million yen ((6.7%)), with the decline in operating income attributed to higher software amortization expenses following the finalization of the purchase price allocation for PointsBet.
On the balance sheet, total assets rose to 280,405 million yen at the end of March 2026 from 225,544 million yen a year earlier, with non-current assets up to 104,064 million yen from 55,612 million yen due to an increase in goodwill and other items from the acquisition of subsidiaries. Net assets were 189,466 million yen against 181,333 million yen. Cash flow from operating activities was 19,287 million yen (27,476 million yen in FY2025), cash flow from investing activities was (31,552) million yen and cash flow from financing activities was 14,161 million yen, leaving cash and cash equivalents at end of period of 111,190 million yen.
Segment Results
Sports and Lifestyle both expanded, while Digital Entertainment contracted. MIXI reports segment profit on an EBITDA basis (segment income before depreciation and amortization).
| Segment | FY2026 Net Sales | FY2025 Net Sales | FY2026 EBITDA | FY2025 EBITDA |
|---|---|---|---|---|
| Sports | 65,848 | 40,206 | 5,088 | 1,999 |
| Lifestyle | 17,159 | 14,795 | 876 | (128) |
| Digital Entertainment | 83,889 | 94,082 | 43,050 | 44,287 |
| Investment | 4,440 | — | 1,001 | — |
| Adjustments | 33 | — | (18,842) | — |
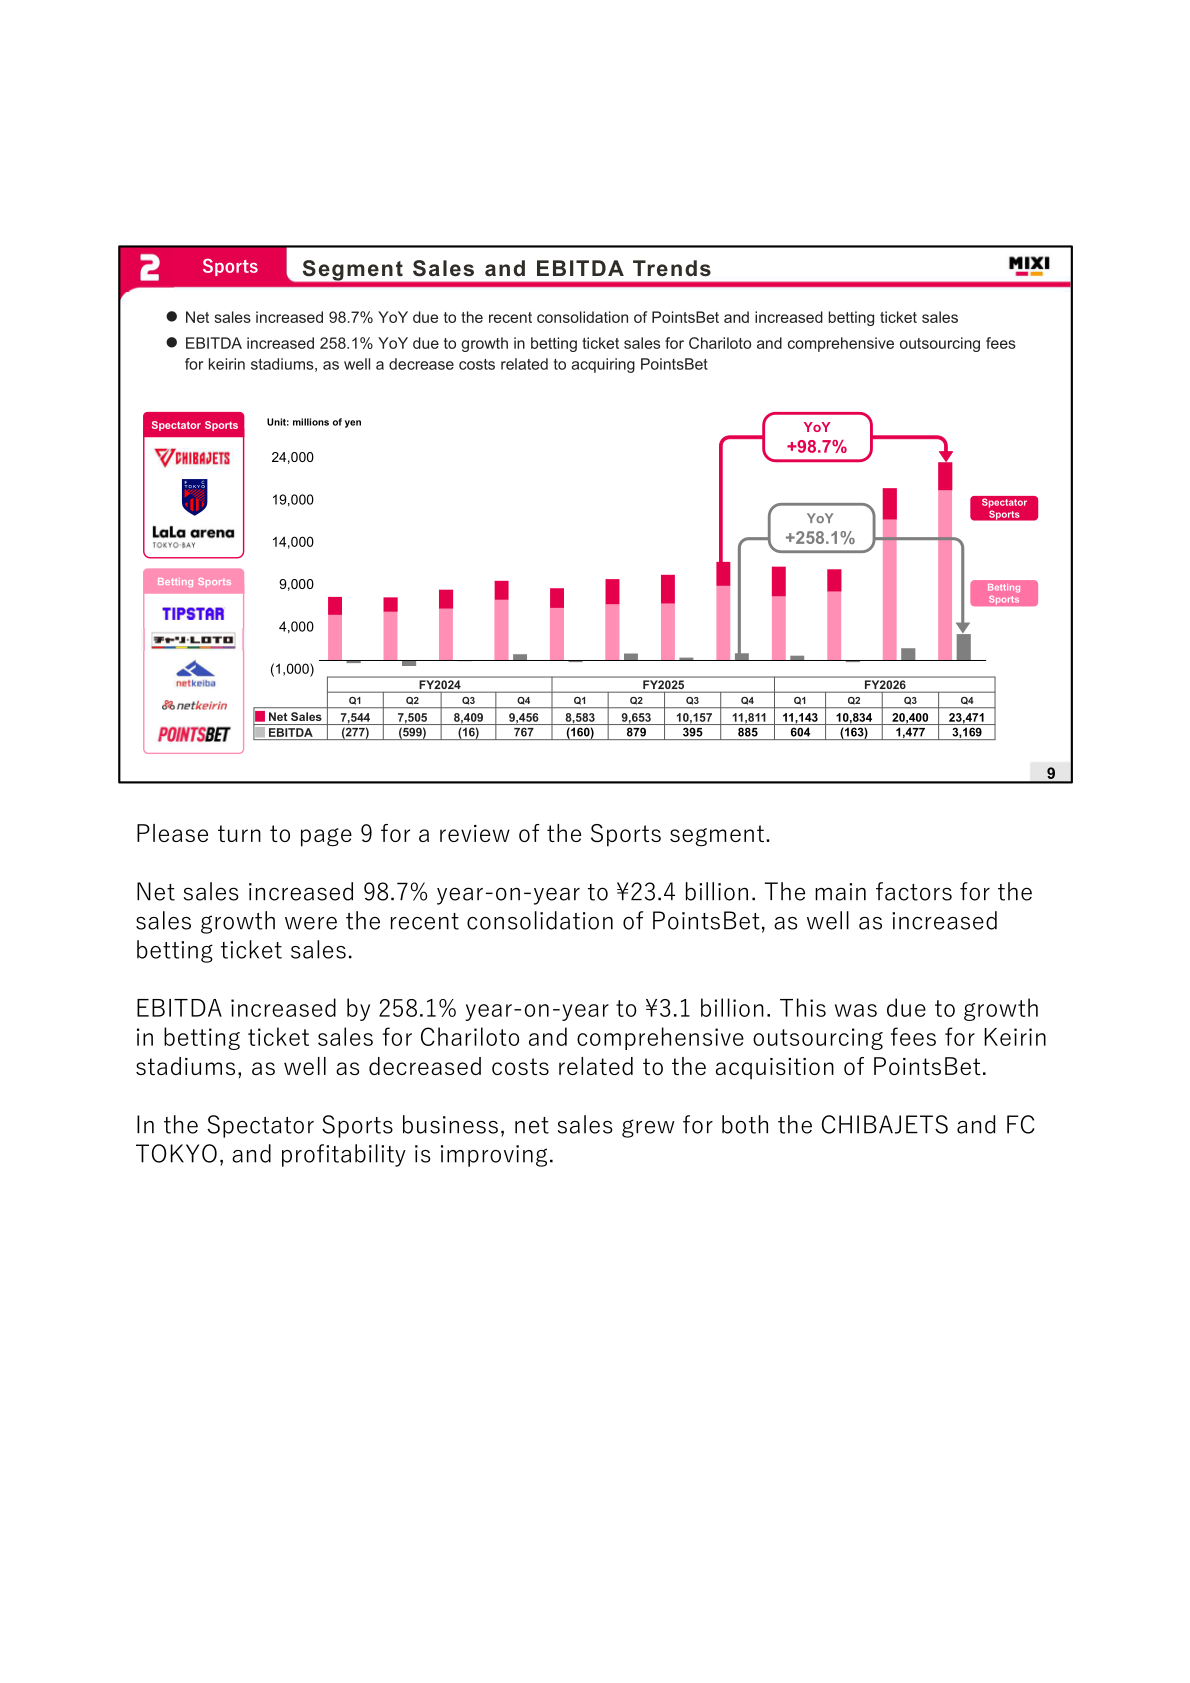
Sports: annual net sales grew at a 5-year CAGR of 37% and EBITDA exceeded 5 billion yen this fiscal year, marking progress toward becoming the second pillar of business. In the fourth quarter, segment net sales increased 98.7% YoY to 23,471 million yen and segment EBITDA increased 258.1% YoY to 3,169 million yen, on the recent consolidation of PointsBet, increased betting ticket sales, comprehensive outsourcing fees for keirin stadiums and a decrease in costs related to acquiring PointsBet. Net sales for the betting businesses increased 126.1% YoY in the quarter (an increase of 55.7% YoY excluding the PointsBet consolidation); Chariloto net sales increased 71.4% YoY and TIPSTAR net sales increased 55.8% YoY. TIPSTAR MAU reached 200,000, and Chariloto’s total sales from comprehensive outsourcing and betting tickets increased 20.7% YoY.
The purchase price allocation for PointsBet has been finalized. Total goodwill (Australia, Canada) of AUD 169.4 million is amortized over 12 years and total intangible assets of AUD 273.4 million comprise software of AUD 117.1 million (4 years), trademark rights in Australia of AUD 56.9 million (19 years), customer-related assets in Australia of AUD 88.0 million (11 years) and customer-related assets in Canada of AUD 11.4 million (14 years), for a total of AUD 442.8 million. The company notes that AUD $117 million (approximately JPY ¥11.42 billion) was recognized as software expenses and will be amortized over four years, resulting in a temporary increase in amortization expenses, and that amortization expenses will significantly decrease from FY30 Q3 onward.
Lifestyle: net sales maintained a 5-year 20% CAGR despite shrinking sales related to New Year cards, and EBITDA achieved profitability as initially expected on the growing number of families using the FamilyAlbum Premium plan, GPS Guardian and photo prints. Fourth-quarter net sales rose 31.4% YoY to 4,465 million yen. Sales in FamilyAlbum’s focus areas increased 37.5% YoY, advertising now accounts for 4.0% of total sales, and the service reached 30 million users and 12 million MAU. As of April 30, 2026, 42.7% of total users are from overseas, with around 20% of the total being from North America.
Digital Entertainment: the 5-year CAGR for net sales remained at negative 2% while EBITDA grew at a 5-year CAGR of 3% as cost efficiencies improved. Fourth-quarter net sales declined 8.5% YoY to 26,204 million yen, with the decline limited by higher ARPU from New Year measures, TV broadcasting of anime in Q3 and collaborations with popular IPs, and EBITDA rose 1.2% YoY to 16,000 million yen on cost optimizations. MONSTER STRIKE exceeded a cumulative 65 million users globally in December 2025, and STRIKE WORLD, the global version of MONSTER STRIKE, began full-scale operations in India in April.
Investment: fourth-quarter net sales were 803 million yen and EBITDA was (382) million yen, while full-year EBITDA remained in the black. Total funds in use moved from 30,571 million yen at the end of FY2025 Q4 to 31,898 million yen at the end of FY2026 Q4.
FY2027 Forecast
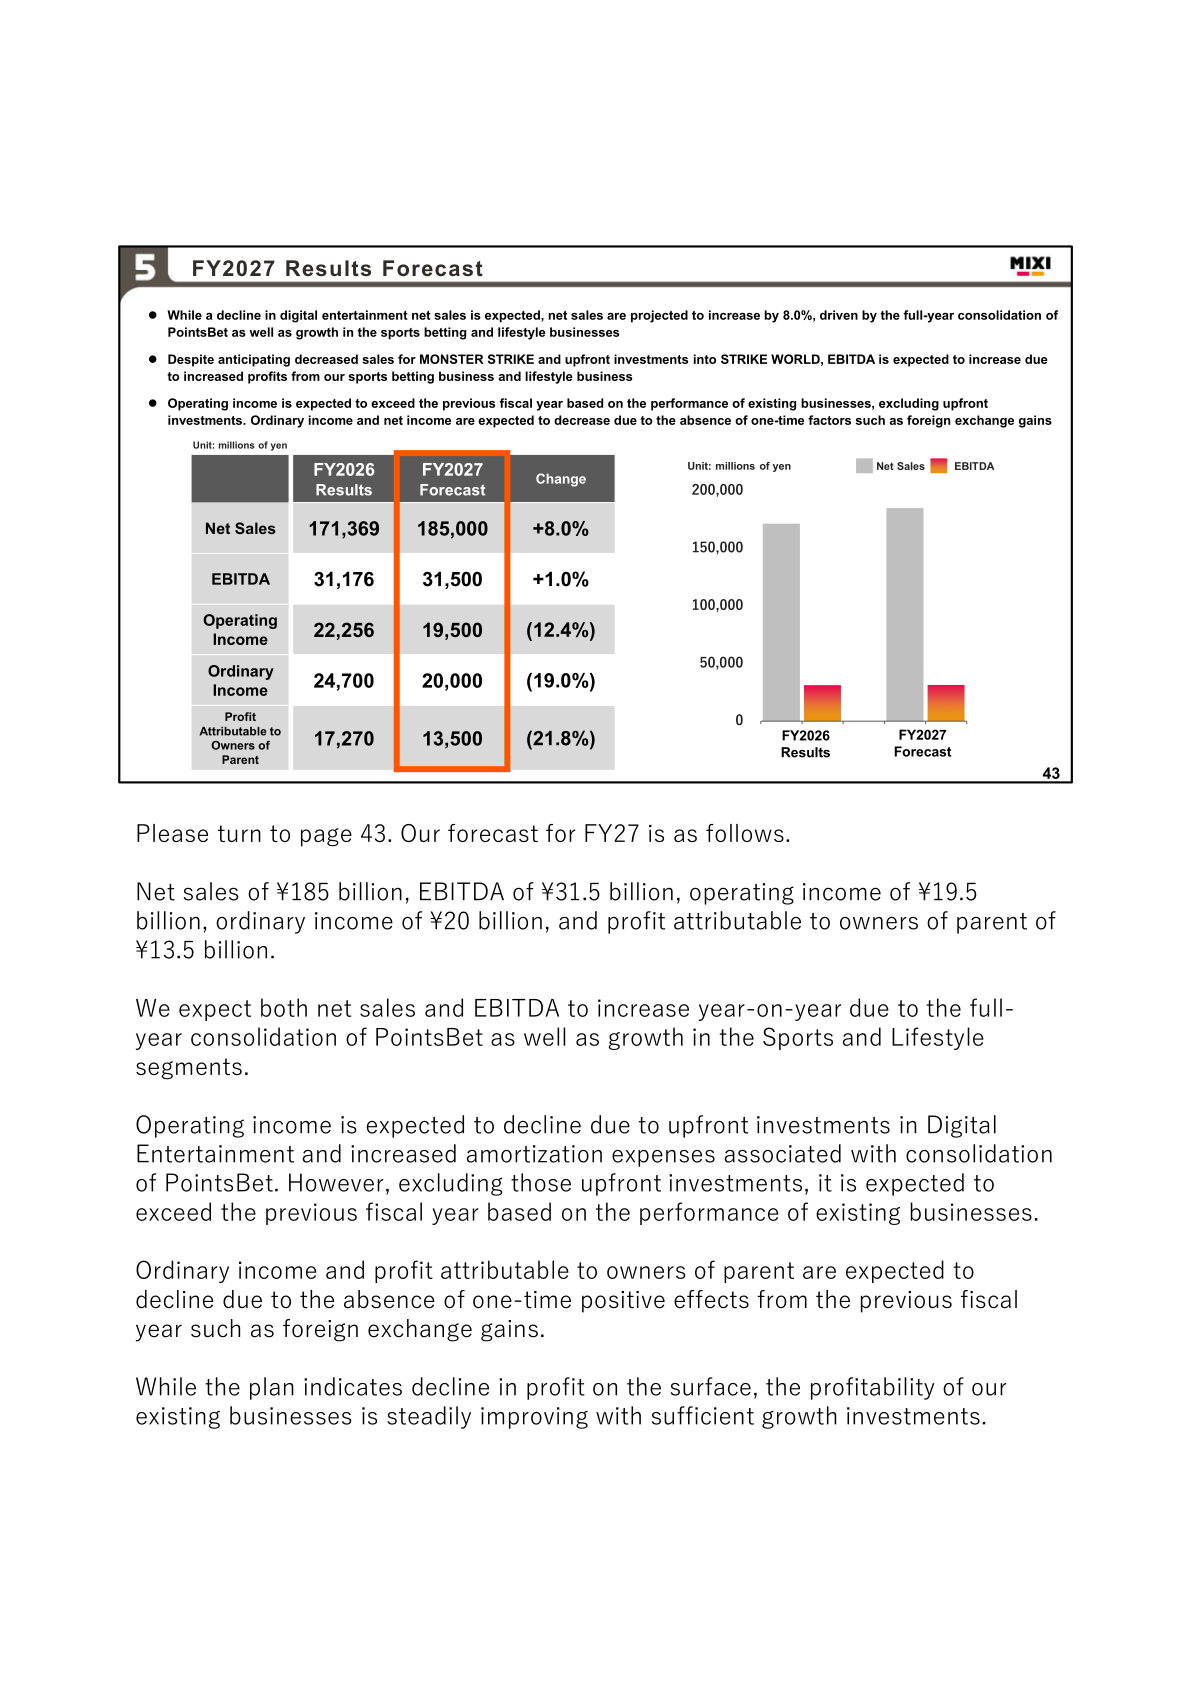
For FY2027, MIXI forecasts net sales of 185,000 million yen, up 8.0%, driven by the full-year consolidation of PointsBet as well as growth in the sports betting and lifestyle businesses, even though a decline in Digital Entertainment net sales is expected. EBITDA is forecast to rise 1.0% to 31,500 million yen. Operating income, ordinary income and net income are forecast to decline: operating income on upfront investments and increased amortization expenses associated with the PointsBet consolidation, and ordinary income and net income on the absence of one-time factors such as foreign exchange gains.
| Item | FY2027 Forecast | FY2026 Results | Change |
|---|---|---|---|
| Net Sales | 185,000 | 171,369 | +8.0% |
| EBITDA | 31,500 | 31,176 | +1.0% |
| Operating Income | 19,500 | 22,256 | (12.4%) |
| Ordinary Income | 20,000 | 24,700 | (19.0%) |
| Profit Attributable to Owners of Parent | 13,500 | 17,270 | (21.8%) |
| Segment | FY2026 Net Sales (Results) | FY2027 Net Sales (Forecast) | Change | FY2026 EBITDA (Results) | FY2027 EBITDA (Forecast) | Change |
|---|---|---|---|---|---|---|
| Sports (Entire Segment) | 65,848 | 86,000 | +30.6% | 5,088 | 9,000 | +76.9% |
| Sports — Betting Sports | 52,636 | 73,500 | +39.6% | — | — | — |
| Sports — Spectator Sports | 13,212 | 12,500 | (5.4%) | — | — | — |
| Lifestyle | 17,159 | 19,500 | +13.6% | 876 | 2,500 | +185.4% |
| Digital Entertainment | 83,889 | 77,500 | (7.6%) | 43,050 | 38,500 | (10.6%) |
| Investment | 4,440 | 2,000 | (55.0%) | 1,001 | 0 | — |
| Adjustments | 33 | 0 | — | (18,842) | (18,500) | — |
Betting Sports sales and profit are expected to increase on the full-year consolidation of PointsBet and growth in TIPSTAR and other businesses, while Spectator Sports is planned conservatively with one-time income sources such as transfer fees excluded. In Digital Entertainment, MONSTER STRIKE sales are expected to decrease and no sales are assumed for STRIKE WORLD, with upfront investments of 3.5 billion yen anticipated including costs for other business development. Betting Sports and Spectator Sports figures are internal management figures and have not been audited.
Shareholder Returns
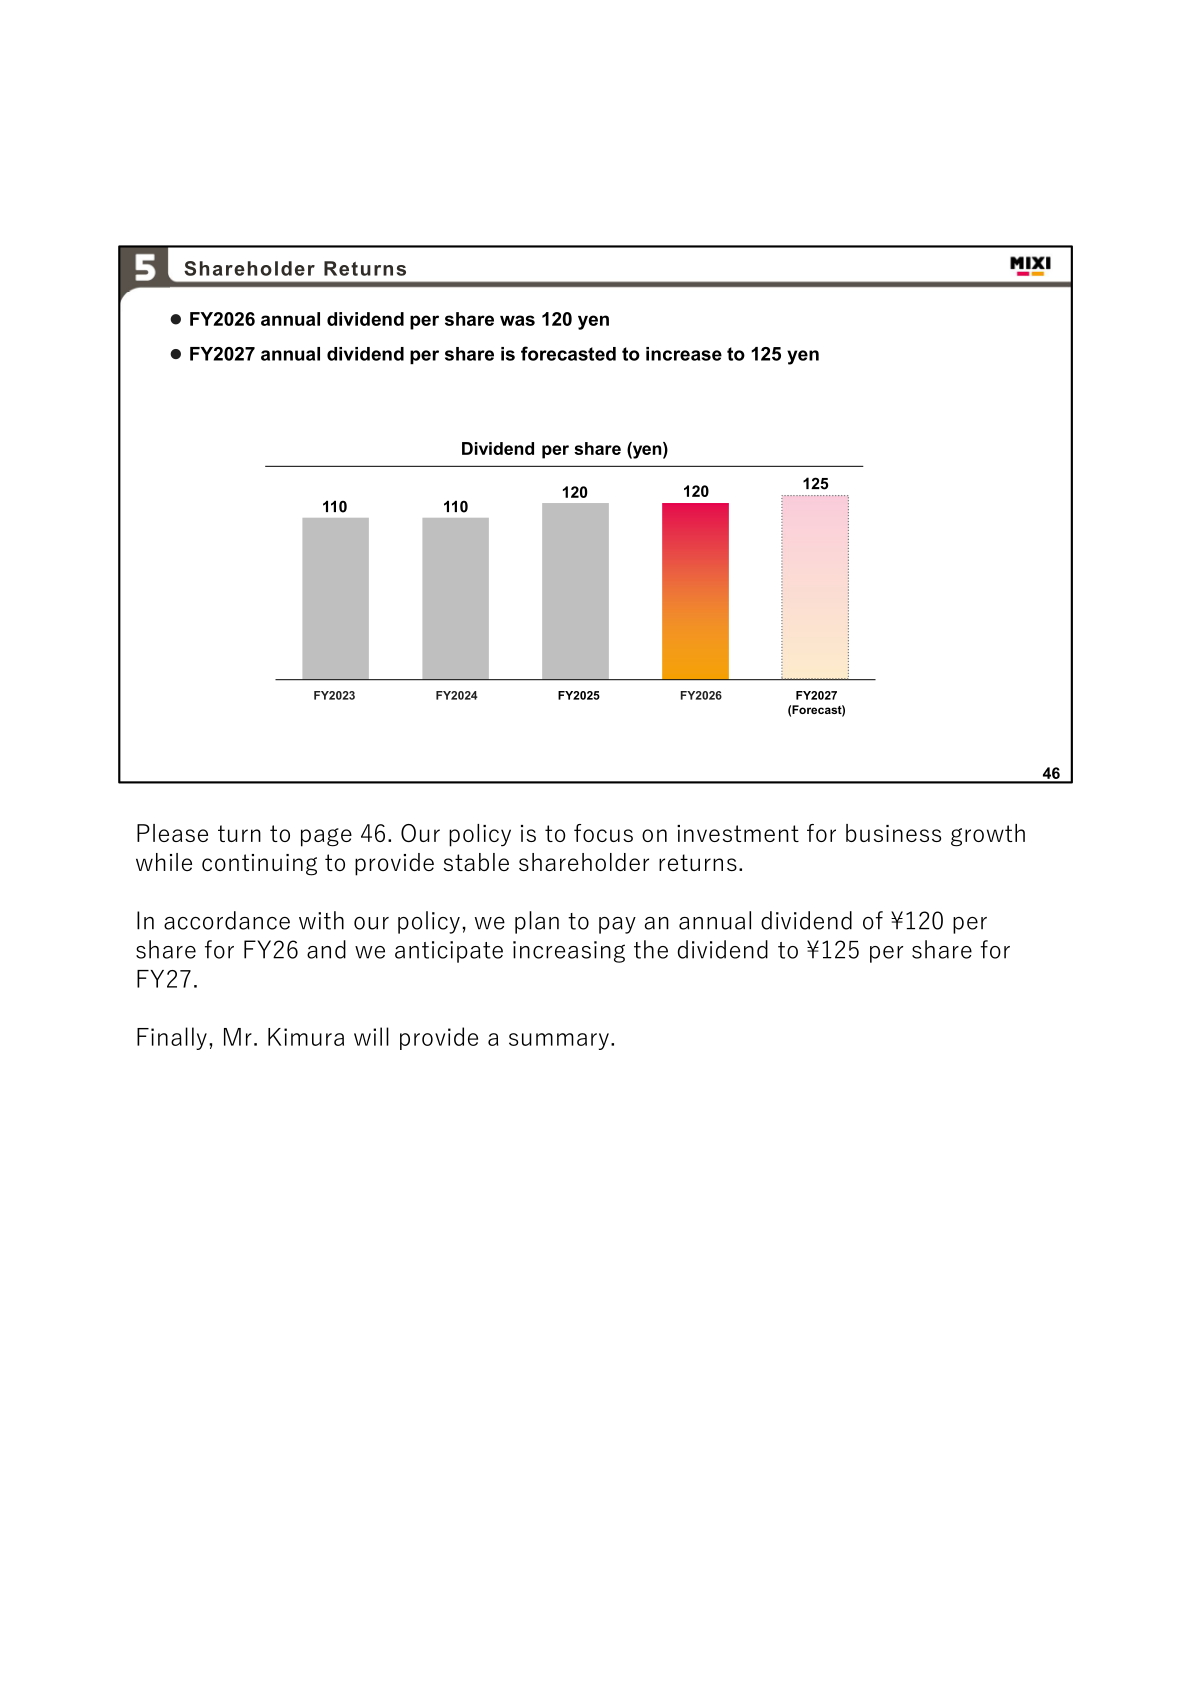
The FY2026 annual dividend per share was 120 yen, and the FY2027 annual dividend per share is forecasted to increase to 125 yen. MIXI also revised its shareholder return policy: whereas the previous policy aimed for a payout ratio of 20% or dividend on equity (DOE) of 5% with the policy reviewed annually, the future policy aims for a payout ratio of 40% or a DOE of 5%. Other policies are unchanged — retire up to 5% of treasury shares and flexibly carry out share buybacks as needed. The company states that starting FY2027 its basic policy is to aim for a consolidated dividend payout ratio of 40% or a DOE of 5%. The change reflects that the three-year average ROE has reached a level that exceeds the cost of shareholders’ equity, which MIXI recognizes at 7.40% against a WACC of 6.18% as of March 31, 2026.
Medium-Term Vision
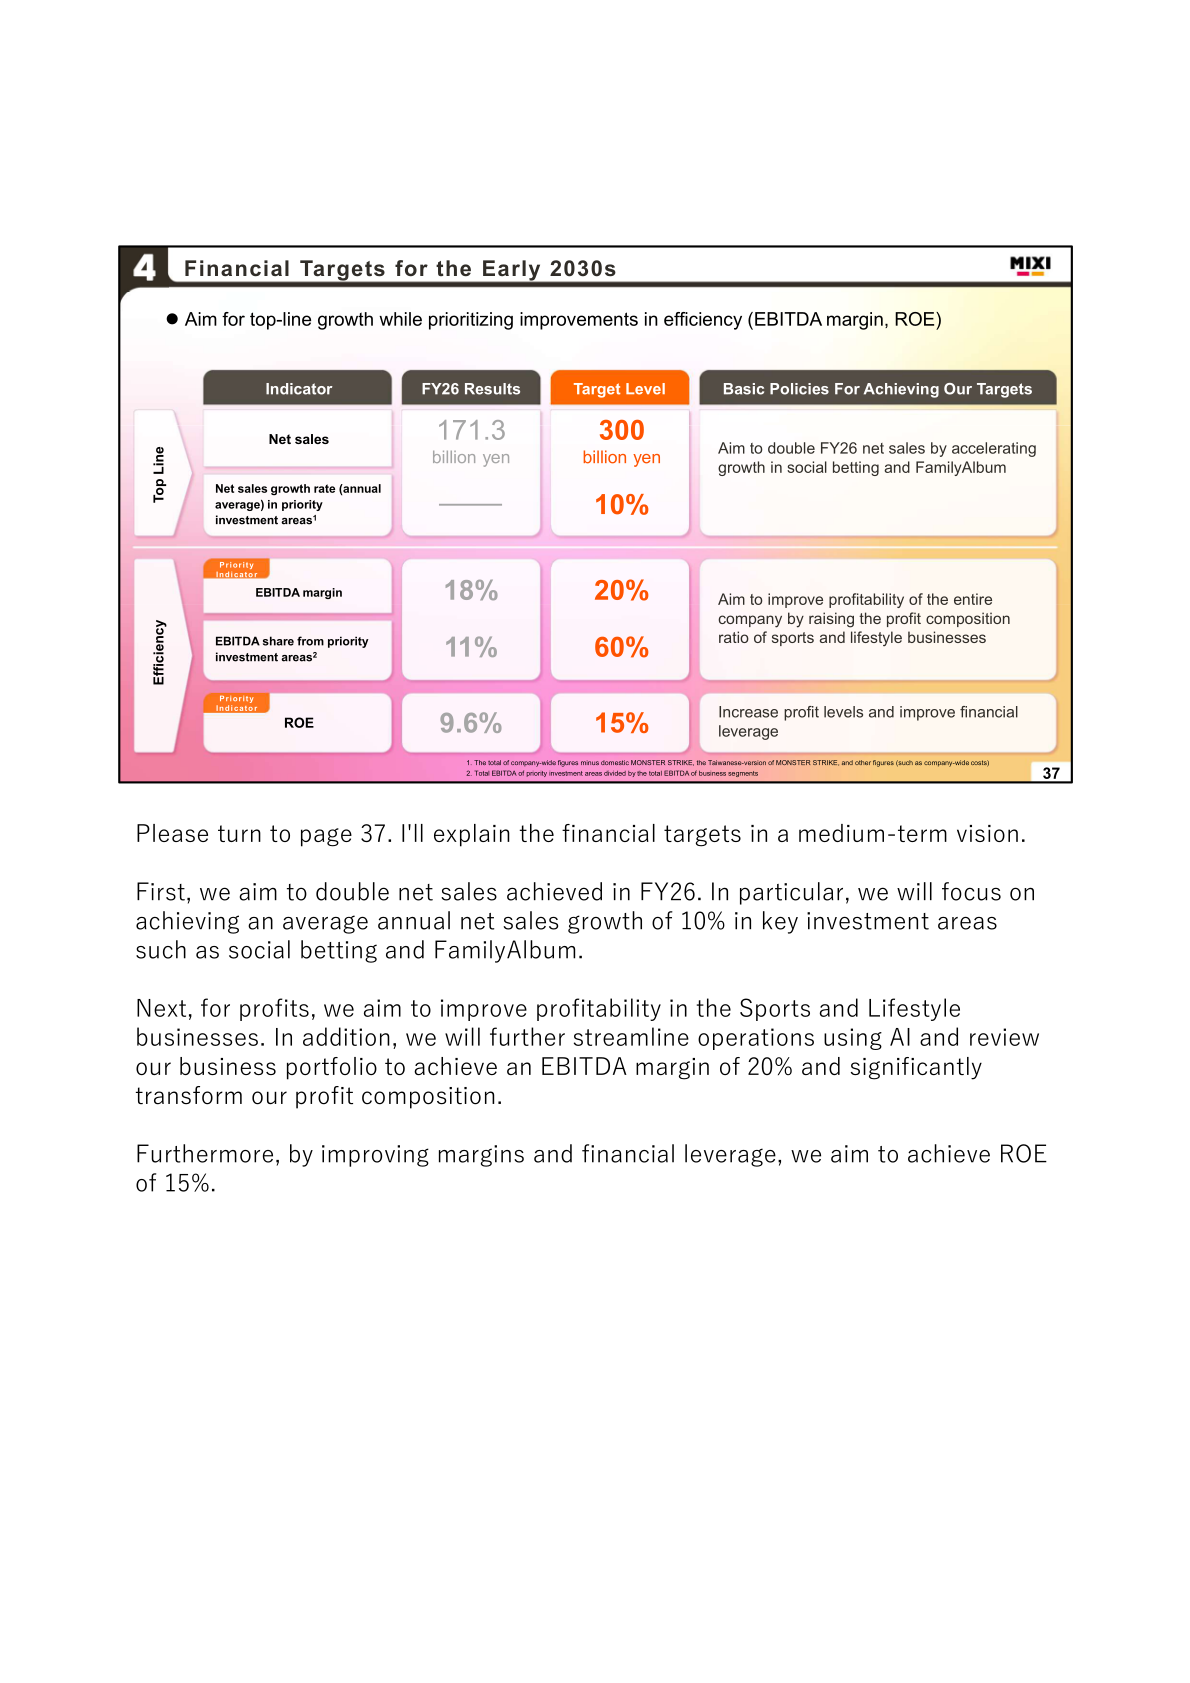
MIXI has defined its economic sphere as the “We-Time Economy”, which it sizes at a global market of US$10-15 trillion based on its own estimates, and set financial targets for the early 2030s. Against FY26 results of 171.3 billion yen in net sales, an 18% EBITDA margin, an 11% EBITDA share from priority investment areas and ROE of 9.6%, the target levels are net sales of 300 billion yen, an EBITDA margin of 20%, an EBITDA share from priority investment areas of 60%, ROE of 15%, and an annual average net sales growth rate of 10% in priority investment areas. By segment, the target scales are net sales surpassing 120 billion yen in Sports, 40 billion yen in Lifestyle and 90 billion yen in Digital Entertainment.
MIXI manages its business portfolio along two axes — net sales growth rate and excess return on capital, defined as the difference between EBITDA margin and the target EBITDA margin (hurdle rate) derived from WACC, recognized as 6.18% — and classifies businesses into four stages, with restructuring or withdrawal reviewed when performance indicators do not improve over a certain period. On governance, an independent outside director was appointed as chair of the Nomination and Compensation Committee in June 2025, and a new director compensation policy linked to the medium-term vision is scheduled to be submitted for approval at the General Meeting of Shareholders held in June 2026.
On AI, the company reports that its company-wide AI utilization rate exceeded 99% in FY26, reducing monthly workloads by approximately 17,600 hours and achieving annual cost reductions of approximately ¥1 billion.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















