
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Sanki Engineering does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials, with figures transcribed as reported. The company refers to this period as fiscal 2025 (the fiscal year ended March 31, 2026), which this site classifies as FY2025; the labels used in the text and tables below follow the source materials.
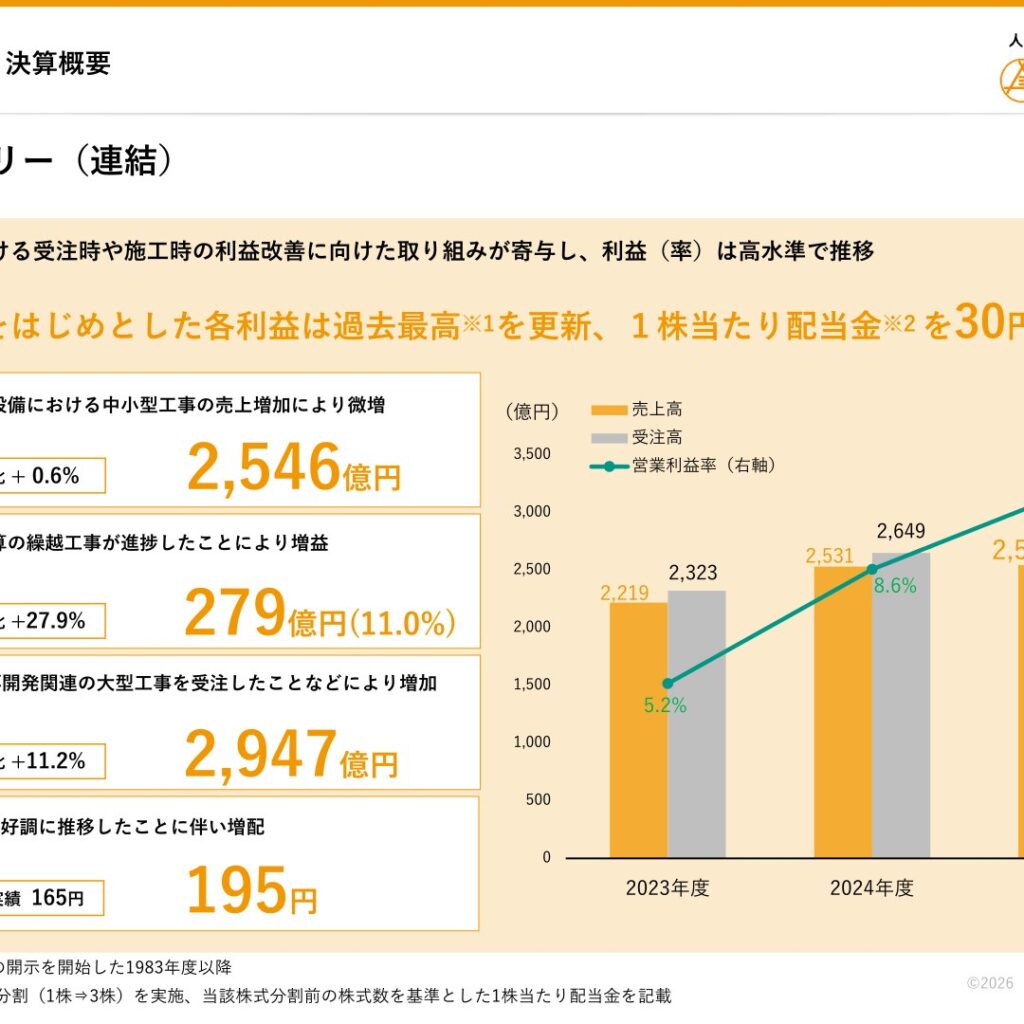
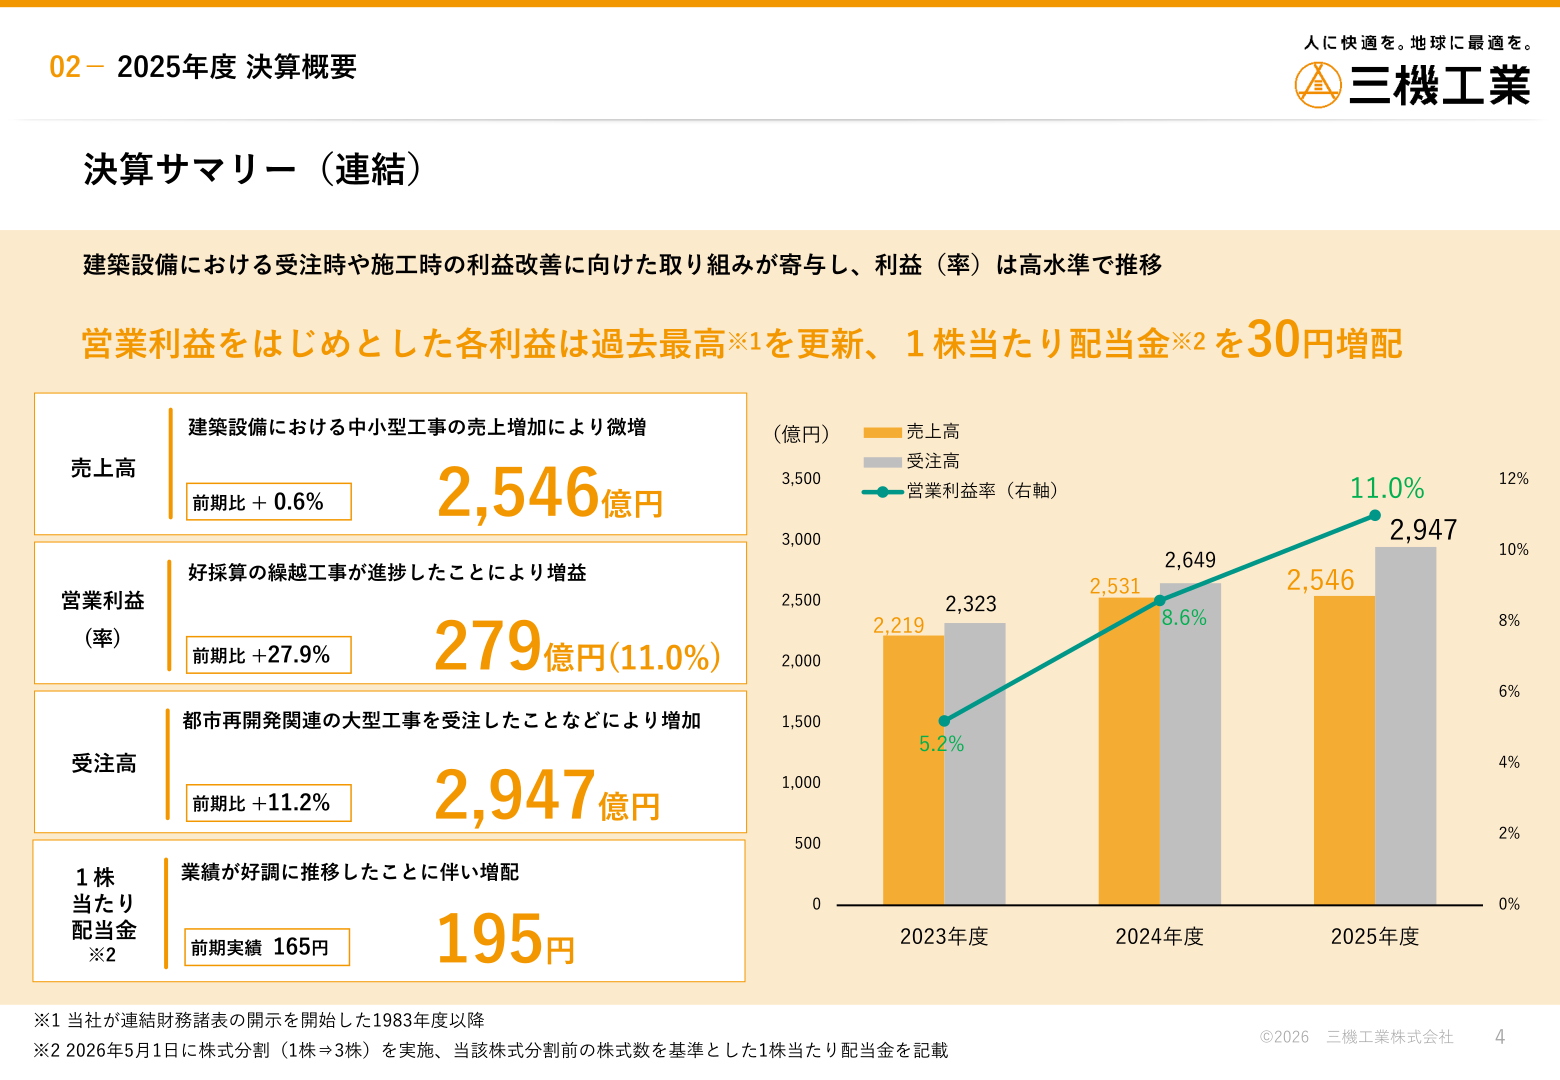
For fiscal 2025 (the fiscal year ended March 31, 2026), Sanki Engineering posted net sales of 254.6 billion yen (up 0.6% year on year), operating profit of 27.9 billion yen (up 27.9%, operating margin 11.0%), ordinary profit of 29,287 million yen (up 26.9%), and profit attributable to owners of parent of 23,688 million yen (up 37.7%), for higher sales and higher profit. Increased sales of small and medium-sized projects in the facilities construction business and progress on high-margin carried-over projects won in recent years lifted operating profit and every other profit line to record highs (the highest since fiscal 1983, when the company began disclosing consolidated financial statements). Orders received came to 294.7 billion yen (up 11.2%) and the backlog carried into the next fiscal year to 250,794 million yen (up 19.0%), both increasing. The annual dividend per share was set at 195 yen, an increase of 30 yen from the previous fiscal year.
Consolidated Results (Fiscal Year Ended March 31, 2026, Actual)
Consolidated results were net sales of 254,674 million yen (up 1,538 million yen, or 0.6%, year on year), gross profit of 56,070 million yen (up 8,575 million yen, or 18.1%, gross margin 22.0%), operating profit of 27,991 million yen (up 6,098 million yen, or 27.9%, operating margin 11.0%), ordinary profit of 29,287 million yen (up 6,215 million yen, or 26.9%, ordinary profit margin 11.5%), and profit attributable to owners of parent of 23,688 million yen (up 6,485 million yen, or 37.7%, net margin 9.3%). Net sales edged up because, although the period fell between the completion and start-up of large projects, sales of small and medium-sized projects in facilities construction were firm. On the profit side, progress on high-margin carried-over projects won in recent years in facilities construction and profit improvement at the construction stage contributed to the increase. Orders received rose by 29,773 million yen (11.2%), from 264,965 million yen to 294,738 million yen, pushed up by orders for large urban redevelopment projects in facilities construction. As a result, the backlog carried into the next fiscal year rose by 40,063 million yen (19.0%), from 210,731 million yen to 250,794 million yen, securing an ample carried-over order book.
Earnings per share (EPS) was 153.51 yen (previous fiscal year: 108.77 yen), return on equity (ROE) was 20.8% (previous fiscal year: 16.3%), ordinary profit to total assets (ROA) was 13.9% (previous fiscal year: 11.4%), net assets per share (BPS) was 794.14 yen (previous fiscal year: 683.87 yen), and the equity ratio was 55.3% (previous fiscal year: 52.9%). EPS and BPS are calculated on the post-split share count, reflecting the share split (one share into three) implemented on May 1, 2026.
| Item | FY ended March 2025 | FY ended March 2026 | YoY change | Change (%) |
|---|---|---|---|---|
| Net sales | 253,136 | 254,674 | 1,538 | 0.6 |
| Gross profit (margin) | 47,495(18.8%) | 56,070(22.0%) | 8,575(3.2pt) | 18.1 |
| Operating profit (margin) | 21,893(8.6%) | 27,991(11.0%) | 6,098(2.4pt) | 27.9 |
| Ordinary profit (margin) | 23,071(9.1%) | 29,287(11.5%) | 6,215(2.4pt) | 26.9 |
| Profit attributable to owners of parent (margin) | 17,203(6.8%) | 23,688(9.3%) | 6,485(2.5pt) | 37.7 |
| Orders received | 264,965 | 294,738 | 29,773 | 11.2 |
| Backlog carried to next fiscal year | 210,731 | 250,794 | 40,063 | 19.0 |
Segment (Business) Results
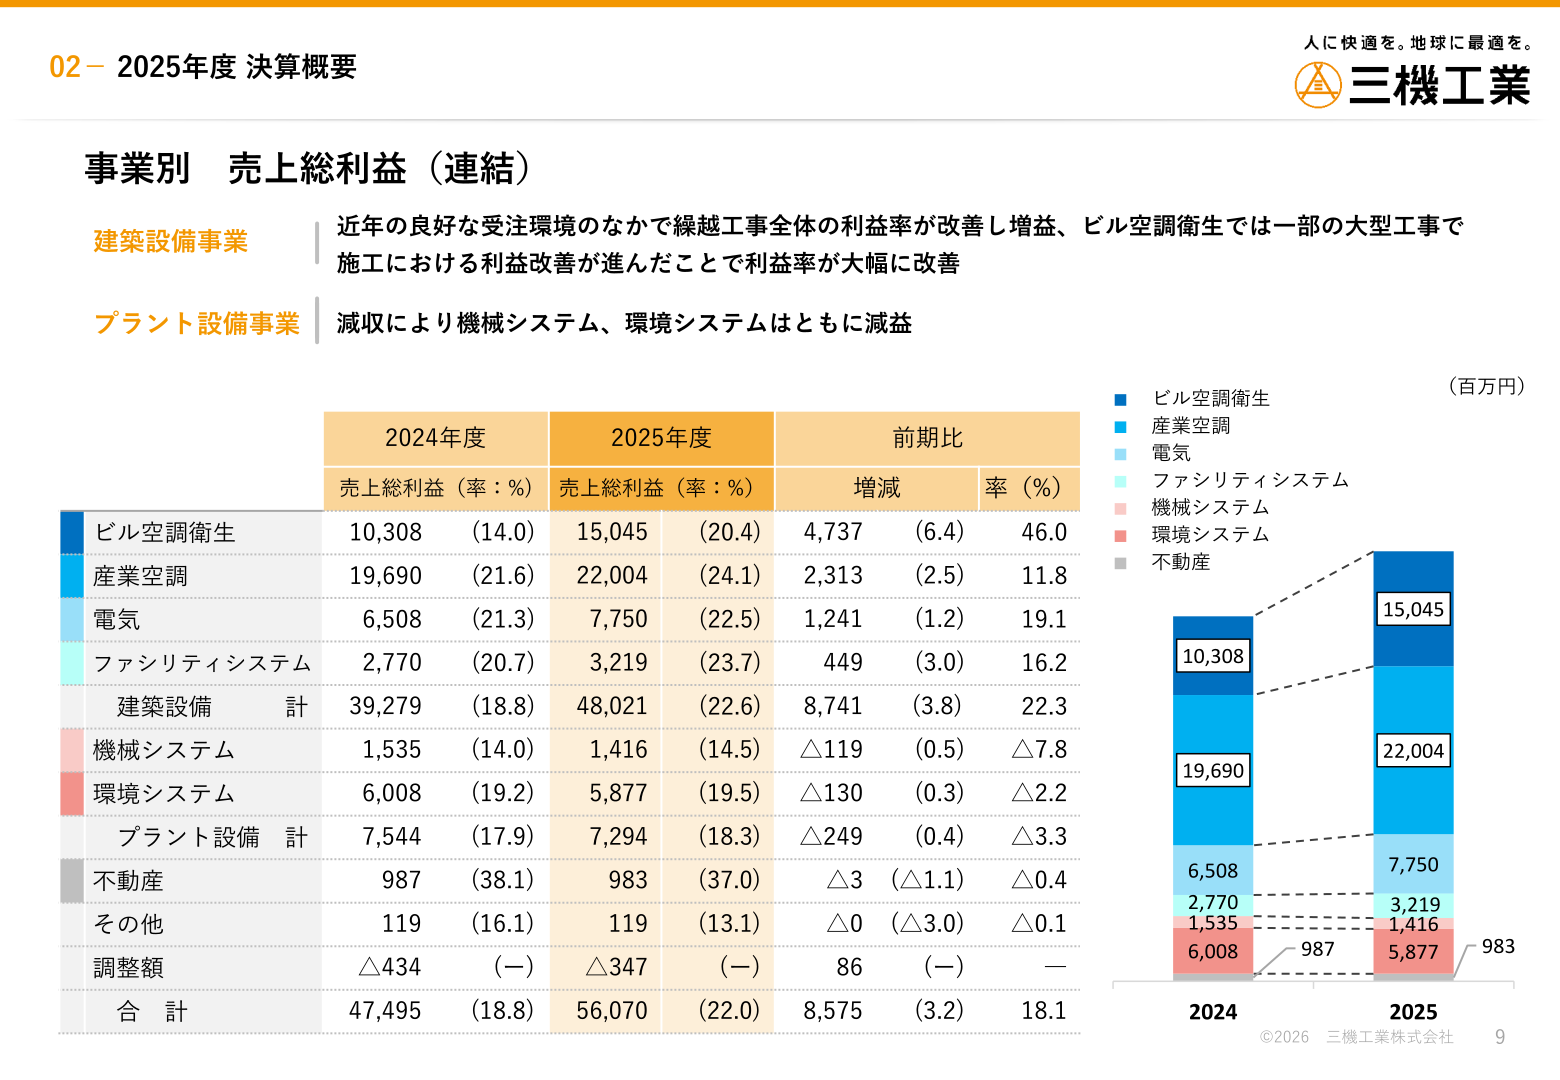
The business segments consist of four categories: the facilities construction business (HVAC & plumbing for buildings, industrial HVAC, electrical systems and facility systems), the machinery systems business, the environmental systems business and the real estate business. The fiscal 2025 sales mix was 83% for the facilities construction business, 12% for the environmental systems business, 4% for the machinery systems business and 1% for the real estate business. In net sales by business (consolidated), facilities construction total was 212,908 million yen (up 3,926 million yen, or 1.9%, year on year), of which electrical systems rose by 3,860 million yen (12.6%), from 30,553 million yen to 34,414 million yen. This was mainly due to progress on a large project for an EV battery plant ordered in the previous fiscal year. HVAC & plumbing for buildings and industrial HVAC finished roughly level with the previous fiscal year, as increased sales of small and medium-sized projects offset lower sales of large projects. By contrast, machinery systems declined by 1,167 million yen (10.7%), from 10,934 million yen to 9,767 million yen, and environmental systems declined by 1,193 million yen (3.8%), from 31,300 million yen to 30,107 million yen; both saw lower sales because fewer large projects progressed than in the previous fiscal year. In operating profit by business (consolidated), HVAC & plumbing for buildings rose by 4,296 million yen (133.2%), from 3,226 million yen to 7,522 million yen, with its margin improving from 4.4% to 10.2%, while machinery systems widened its loss from △562 million yen to △865 million yen and environmental systems fell by 689 million yen (38.4%), from 1,793 million yen to 1,104 million yen. On the order front, HVAC & plumbing for buildings increased 81.8%, from 69,564 million yen to 126,440 million yen, on orders for large urban redevelopment and data center related projects.
| Segment | FY ended March 2025 (million yen) | FY ended March 2026 (million yen) | YoY change | Change (%) |
|---|---|---|---|---|
| HVAC & Plumbing for Buildings | 73,782 | 73,798 | 15 | 0.0 |
| Industrial HVAC | 91,264 | 91,137 | △126 | △0.1 |
| Electrical Systems | 30,553 | 34,414 | 3,860 | 12.6 |
| Facility Systems | 13,381 | 13,558 | 176 | 1.3 |
| Facilities Construction total | 208,981 | 212,908 | 3,926 | 1.9 |
| Machinery Systems | 10,934 | 9,767 | △1,167 | △10.7 |
| Environmental Systems | 31,300 | 30,107 | △1,193 | △3.8 |
| Plant Systems total | 42,235 | 39,874 | △2,360 | △5.6 |
| Real Estate | 2,592 | 2,655 | 62 | 2.4 |
| Other | 739 | 905 | 166 | 22.5 |
| Adjustments | △1,413 | △1,669 | △256 | ― |
| Total | 253,136 | 254,674 | 1,538 | 0.6 |
Full-Year Forecast
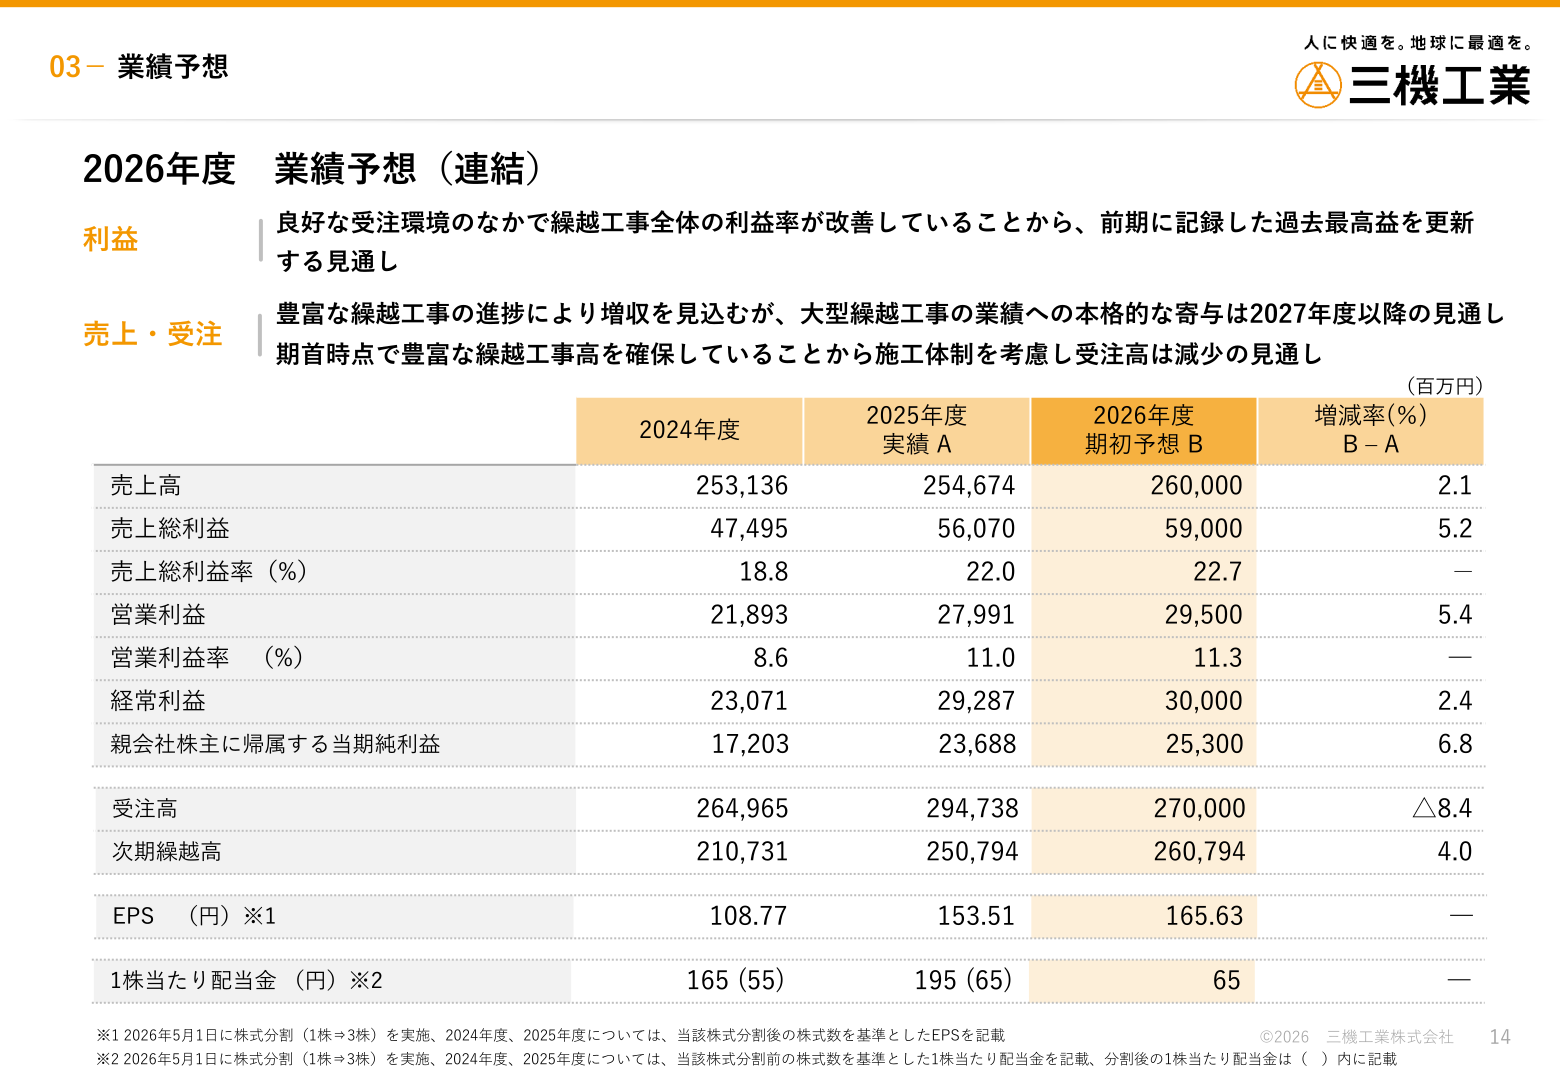
For fiscal 2026 (the fiscal year ending March 31, 2027), the company forecasts net sales of 260,000 million yen (up 2.1% year on year), gross profit of 59,000 million yen (up 5.2%, gross margin 22.7%), operating profit of 29,500 million yen (up 5.4%, operating margin 11.3%), ordinary profit of 30,000 million yen (up 2.4%), and profit attributable to owners of parent of 25,300 million yen (up 6.8%). EPS is expected to be 165.63 yen. The company expects higher sales on progress with its ample carried-over projects, but sees the full contribution of large carried-over projects to earnings coming from fiscal 2027 onward. Because the profit margin of the carried-over order book as a whole is improving amid a favorable order environment, the company expects to surpass the record profit posted in the previous fiscal year. Orders received, on the other hand, are expected to decrease to 270,000 million yen (down 8.4% year on year), reflecting the construction capacity available given the ample carried-over order book secured at the start of the period, and the backlog carried to the next fiscal year is planned at 260,794 million yen (up 4.0%). The dividend per share forecast is 65 yen on the post-split share count following the share split (one share into three) implemented on May 1, 2026, equivalent to 195 yen on a pre-split basis, which is the same level as the previous fiscal year.
| Item | FY ended March 2025 | FY ended March 2026 | FY ending March 2027 (Forecast) | Change (%) |
|---|---|---|---|---|
| Net sales | 253,136 | 254,674 | 260,000 | 2.1 |
| Gross profit | 47,495 | 56,070 | 59,000 | 5.2 |
| Gross margin (%) | 18.8 | 22.0 | 22.7 | ― |
| Operating profit | 21,893 | 27,991 | 29,500 | 5.4 |
| Operating margin (%) | 8.6 | 11.0 | 11.3 | ― |
| Ordinary profit | 23,071 | 29,287 | 30,000 | 2.4 |
| Profit attributable to owners of parent | 17,203 | 23,688 | 25,300 | 6.8 |
| Orders received | 264,965 | 294,738 | 270,000 | △8.4 |
| Backlog carried to next fiscal year | 210,731 | 250,794 | 260,794 | 4.0 |
| EPS (yen) | 108.77 | 153.51 | 165.63 | ― |
Shareholder Returns
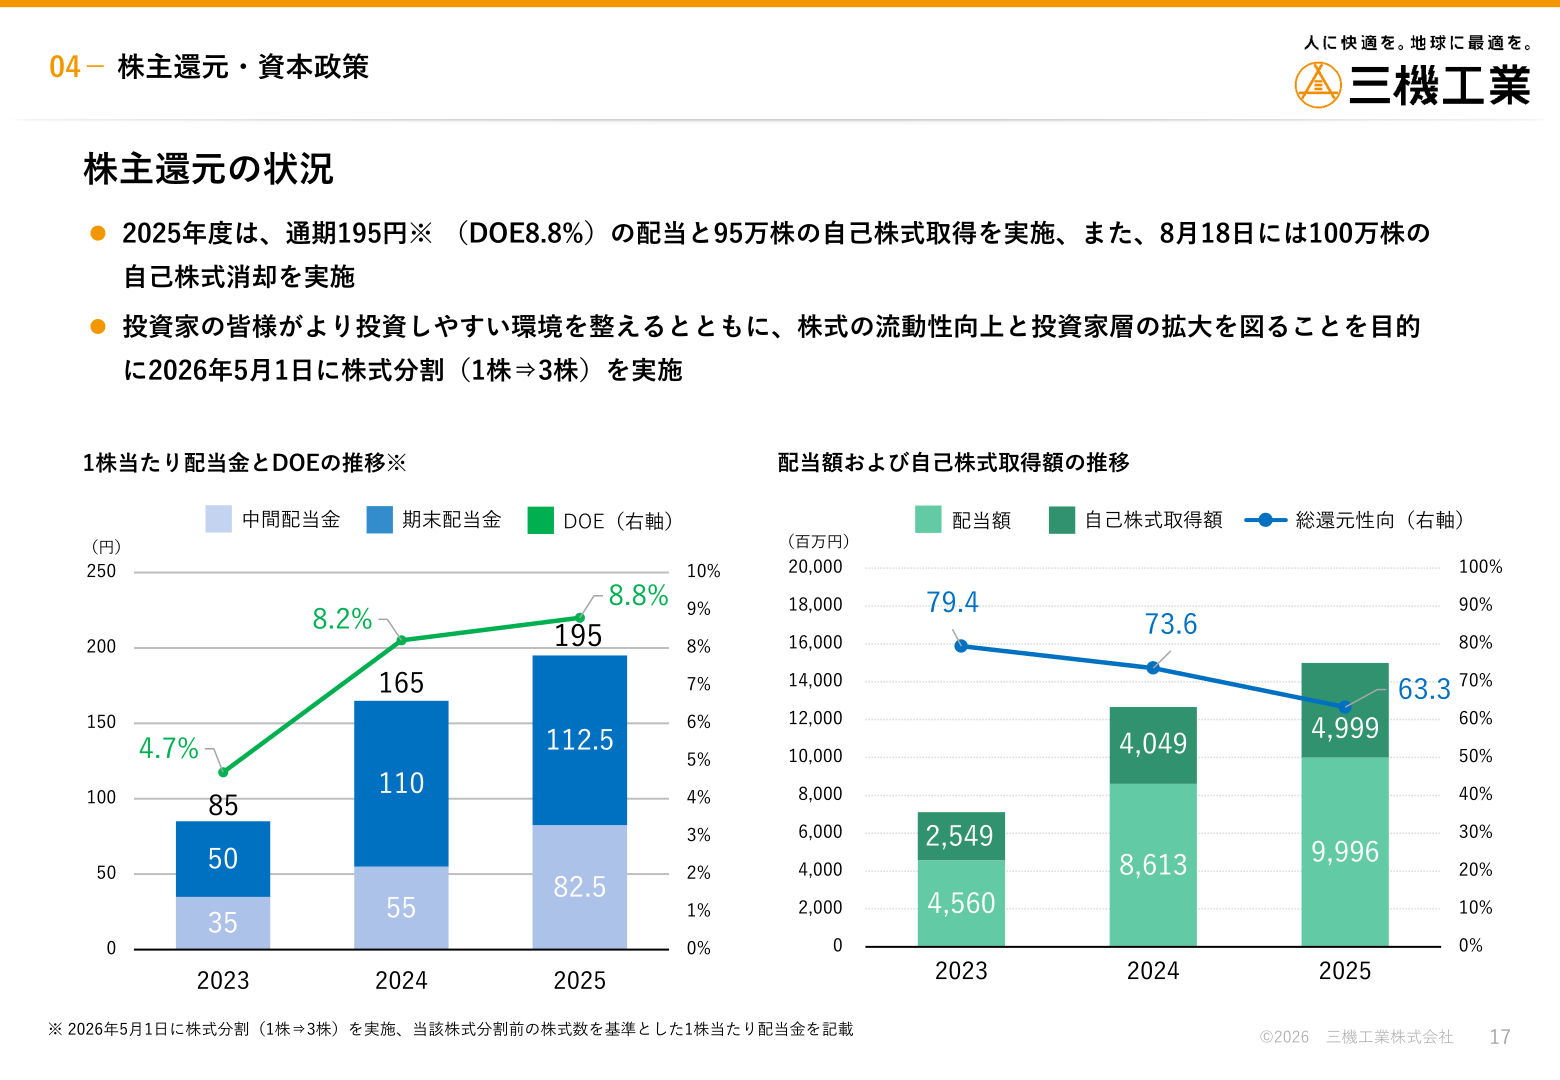
For fiscal 2025 the company paid a full-year dividend of 195 yen per share (an increase of 30 yen year on year, DOE 8.8%) and acquired 950,000 of its own shares. It also cancelled 1,000,000 treasury shares on August 18, 2025. To create an environment in which it is easier for investors to invest, and to improve the liquidity of its shares and broaden its investor base, the company implemented a share split (one share into three) on May 1, 2026. Under the Medium-Term Management Plan 2027, the company has set a policy of DOE of 5.0% or more for dividends and share buybacks of around 4,000,000 shares on a cumulative basis for fiscal 2025 to fiscal 2027; the fiscal 2025 results of DOE 8.8% and share buybacks of 950,000 shares are both tracking above those targets.
| Fiscal year | Interim dividend (yen) | Year-end dividend (yen) | Total dividend (yen) | DOE (%) |
|---|---|---|---|---|
| Fiscal 2023 (FY ended March 2024) | 35 | 50 | 85 | 4.7 |
| Fiscal 2024 (FY ended March 2025) | 55 | 110 | 165 | 8.2 |
| Fiscal 2025 (FY ended March 2026) | 82.5 | 112.5 | 195 | 8.8 |
Medium-Term Management Plan 2027 / Topics
Sanki Engineering launched its new management vision “MIRAI 2030” and its Medium-Term Management Plan 2027 in April 2025, the milestone of its 100th anniversary. The plan targets, for fiscal 2027, net sales of 300 billion yen, operating profit of 30 billion yen, an operating margin of 10.0%, ROE of 16.0% or more (excluding gains on sales of cross-shareholdings), 2,900 employees, and DOE of 5.0% or more. Results for fiscal 2025, the plan’s first year, were net sales of 254.6 billion yen (company assessment: broadly on plan, as the period fell between the completion and start-up of large-project sales), operating profit of 27.9 billion yen with an operating margin of 11.0% (company assessment: above the level assumed when the plan was formulated, thanks to thorough scrutiny of costs and risks at the order-review stage and progress in profit improvement at the construction stage), ROE of 18.6% (excluding gains on sales of cross-shareholdings, above target), DOE of 8.8%, and 2,705 employees. As growth investment in fiscal 2025, the company executed M&A investments: the acquisition of all shares of Hoei Shoko Co., Ltd., which handles construction of waste treatment facilities and other work, and the conclusion of a share transfer agreement to acquire a 40% stake in ES Matrix, a Malaysia-based company engaged in electrical and telecommunications facility work related to semiconductors and data centers. Against a plan for cumulative growth investment of around 50 billion yen over fiscal 2025 to fiscal 2027, fiscal 2025 progress was limited to 6.6 billion yen, but the company said it is advancing steadily, centered on M&A investment and investment in human capital. On the environmental front, it is the only facilities construction company to have been selected for the CDP (an international environmental NGO) Climate Change A List for four consecutive years.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















