
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
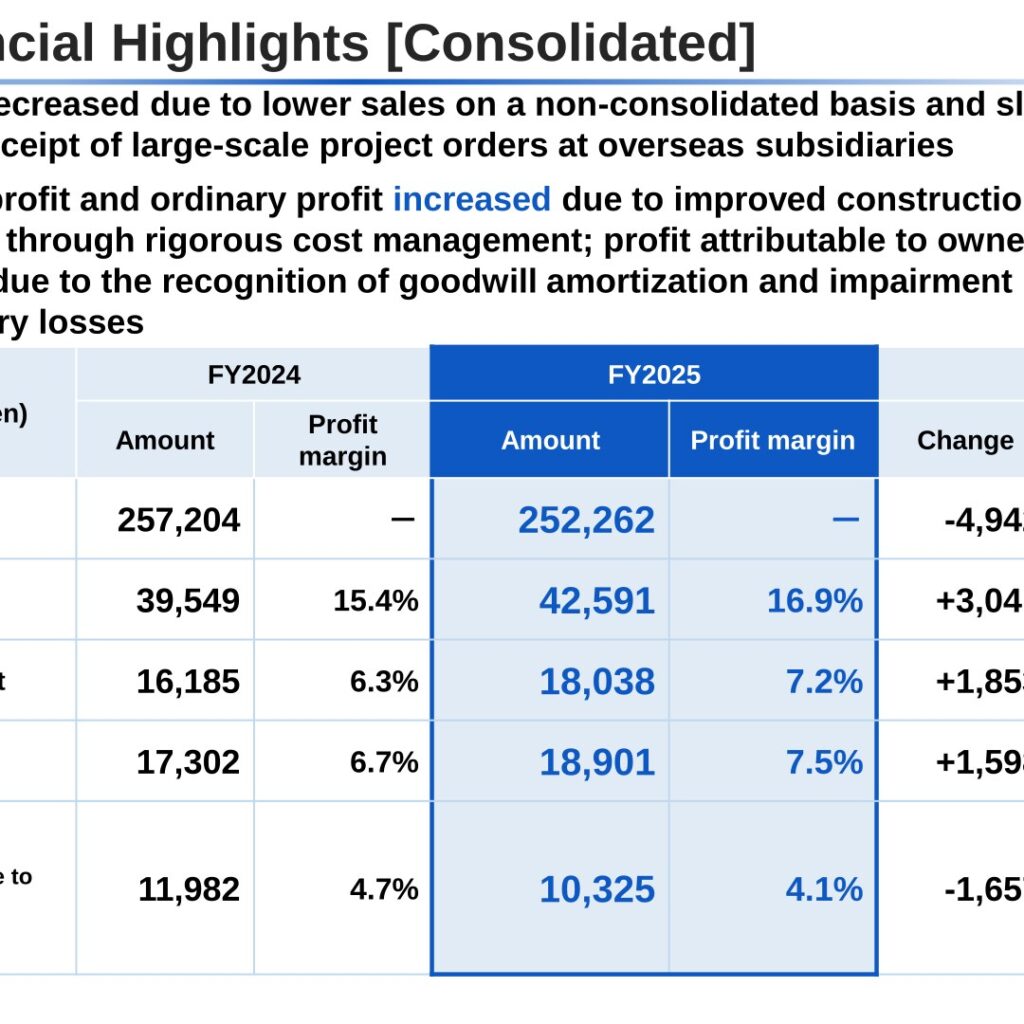
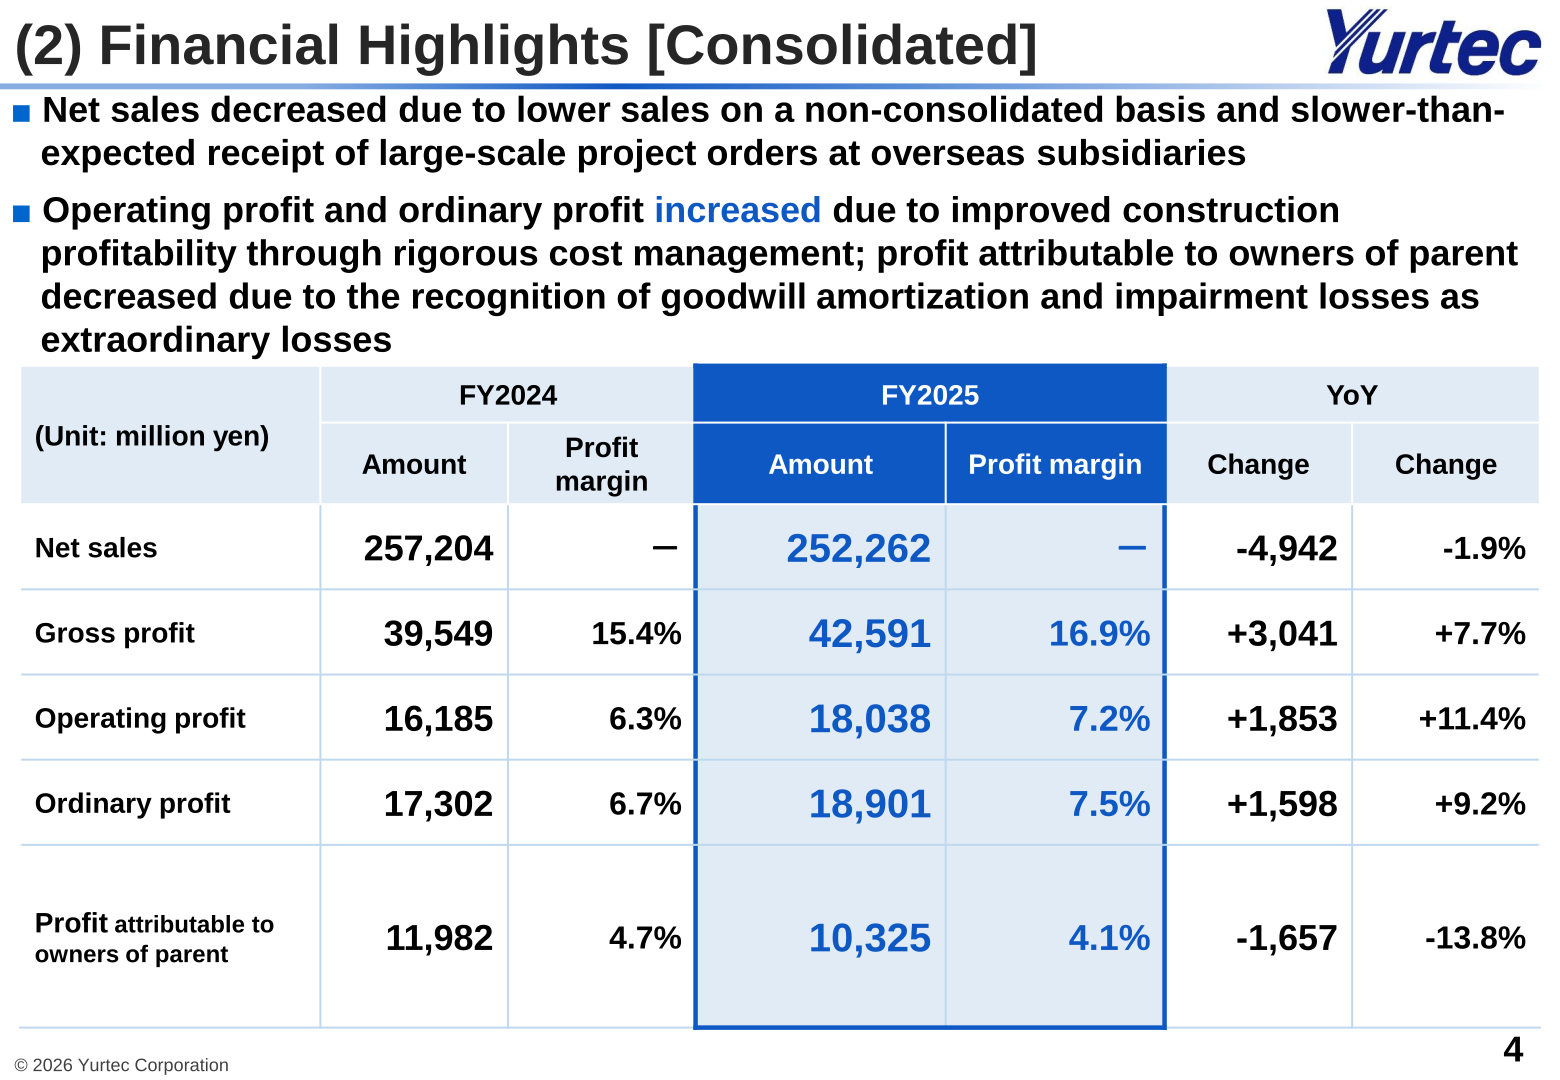
Yurtec Corporation (TSE Prime Market: 1934), a general facility engineering company based in Sendai, released its Financial Results Report for the Fiscal Year Ended March 31, 2026 on May 27, 2026. The presentation labels that year as FY2025. Consolidated net sales decreased 1.9% year on year to 252,262 million yen, while operating profit rose 11.4% to 18,038 million yen and ordinary profit rose 9.2% to 18,901 million yen on improved construction profitability. Profit attributable to owners of parent fell 13.8% to 10,325 million yen, as the company recognized goodwill amortization and impairment losses as extraordinary losses.
Consolidated Results (Full-Year Actual)
The company states that net sales decreased due to lower sales on a non-consolidated basis and slower-than-expected receipt of large-scale project orders at overseas subsidiaries. Operating profit and ordinary profit increased due to improved construction profitability through rigorous cost management. The gross profit margin improved from 15.4% to 16.9%, and the operating profit margin improved from 6.3% to 7.2%. On the business environment, the company notes that public investment remained firm while private-sector capital investment picked up, that construction costs continued to rise due to higher labor and material costs which it reflected in construction prices as appropriate, and that market uncertainty increased due to the impact of U.S. trade policies.
| Item (million yen) | FY2024 | FY2025 | Change | Change (%) |
|---|---|---|---|---|
| Net sales | 257,204 | 252,262 | -4,942 | -1.9% |
| Gross profit | 39,549 | 42,591 | +3,041 | +7.7% |
| Gross profit margin | 15.4% | 16.9% | ||
| Operating profit | 16,185 | 18,038 | +1,853 | +11.4% |
| Operating profit margin | 6.3% | 7.2% | ||
| Ordinary profit | 17,302 | 18,901 | +1,598 | +9.2% |
| Profit attributable to owners of parent | 11,982 | 10,325 | -1,657 | -13.8% |
By region, consolidated net sales in the Tohoku Region and Niigata Prefecture were 213,402 million yen (FY2024: 221,735 million yen), down 8,332 million yen or 3.8%. Sales outside of Tohoku and Niigata were 21,864 million yen (FY2024: 15,409 million yen), up 6,454 million yen or 41.9%. Overseas sales were 16,994 million yen (FY2024: 20,059 million yen), down 3,064 million yen or 15.3%.
On a non-consolidated basis, work orders received increased 7.1% to 253,751 million yen, while net sales decreased 0.4% to 227,891 million yen. Non-consolidated operating profit rose 19.6% to 16,650 million yen and ordinary profit rose 17.9% to 18,051 million yen, while net income decreased 23.5% to 8,361 million yen due to the recognition of a loss on valuation of shares of affiliates as an extraordinary loss. Construction contracts in progress increased 16.3% to 184,741 million yen. In cash flows, the company secured 6,638 million yen in cash flows from operating activities, cash used in investing activities totaled 5,907 million yen, and cash used in financing activities totaled 5,467 million yen, mainly due to dividend payments.
Construction Sales by Category (Non-Consolidated)
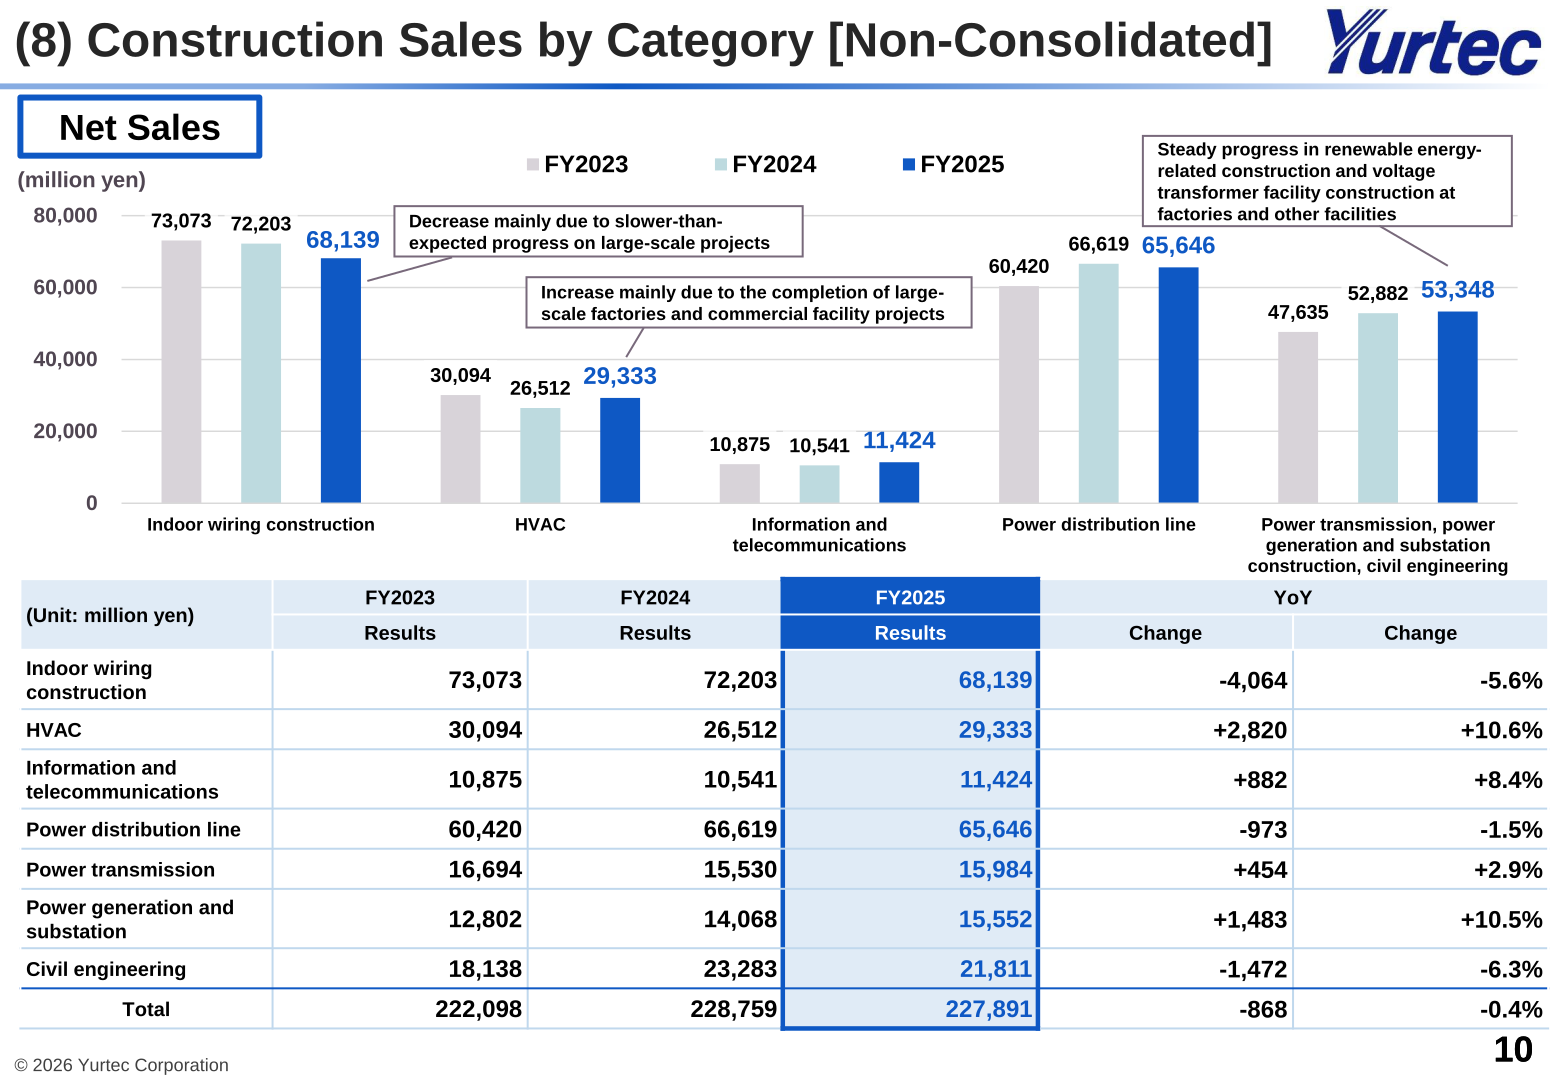
Indoor wiring construction sales decreased mainly due to slower-than-expected progress on large-scale projects. HVAC increased mainly due to the completion of large-scale factory and commercial facility projects, and the company cites steady progress in renewable energy-related construction and voltage transformer facility construction at factories and other facilities.
| Category (million yen) | FY2024 | FY2025 | Change | Change (%) |
|---|---|---|---|---|
| Indoor wiring construction | 72,203 | 68,139 | -4,064 | -5.6% |
| HVAC | 26,512 | 29,333 | +2,820 | +10.6% |
| Information and telecommunications | 10,541 | 11,424 | +882 | +8.4% |
| Power distribution line | 66,619 | 65,646 | -973 | -1.5% |
| Power transmission | 15,530 | 15,984 | +454 | +2.9% |
| Power generation and substation | 14,068 | 15,552 | +1,483 | +10.5% |
| Civil engineering | 23,283 | 21,811 | -1,472 | -6.3% |
| Total | 228,759 | 227,891 | -868 | -0.4% |
By customer, non-consolidated work orders received from general clients were 143,309 million yen (composition ratio 56.5%), up 17.6%, while orders from the Tohoku Electric Power Group were 110,442 million yen (43.5%), down 4.0%. Non-consolidated construction sales to general clients were 119,456 million yen (52.4%), down 0.8%, and sales to the Tohoku Electric Power Group were 108,434 million yen (47.6%), up 0.1%.
FY2026 Forecast
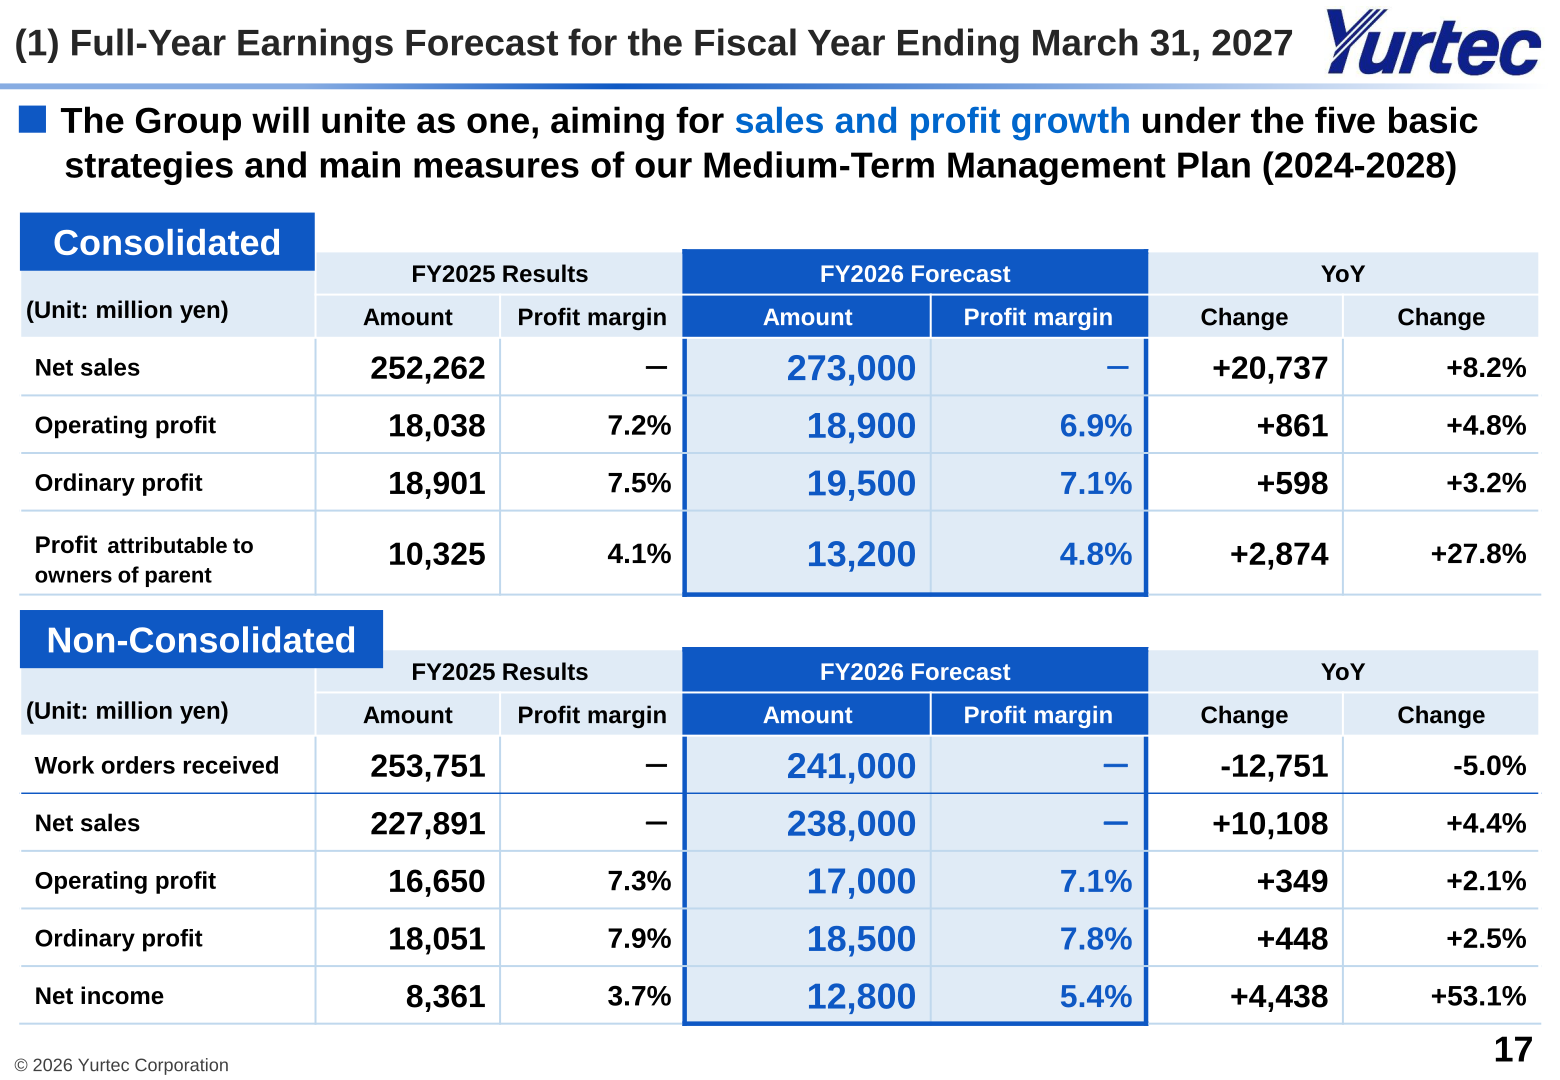
For the fiscal year ending March 31, 2027, which the company labels FY2026, Yurtec forecasts consolidated net sales of 273,000 million yen, up 8.2%, and operating profit of 18,900 million yen, up 4.8%. The company states that the Group will unite as one, aiming for sales and profit growth under the five basic strategies and main measures of its Medium-Term Management Plan (2024-2028). On a non-consolidated basis, the company forecasts work orders received of 241,000 million yen (down 5.0%), net sales of 238,000 million yen (up 4.4%), operating profit of 17,000 million yen (up 2.1%), ordinary profit of 18,500 million yen (up 2.5%), and net income of 12,800 million yen (up 53.1%).
| Item (million yen, consolidated) | FY2025 Results | FY2026 Forecast | Change | Change (%) |
|---|---|---|---|---|
| Net sales | 252,262 | 273,000 | +20,737 | +8.2% |
| Operating profit | 18,038 | 18,900 | +861 | +4.8% |
| Operating profit margin | 7.2% | 6.9% | ||
| Ordinary profit | 18,901 | 19,500 | +598 | +3.2% |
| Profit attributable to owners of parent | 10,325 | 13,200 | +2,874 | +27.8% |
Shareholder Returns
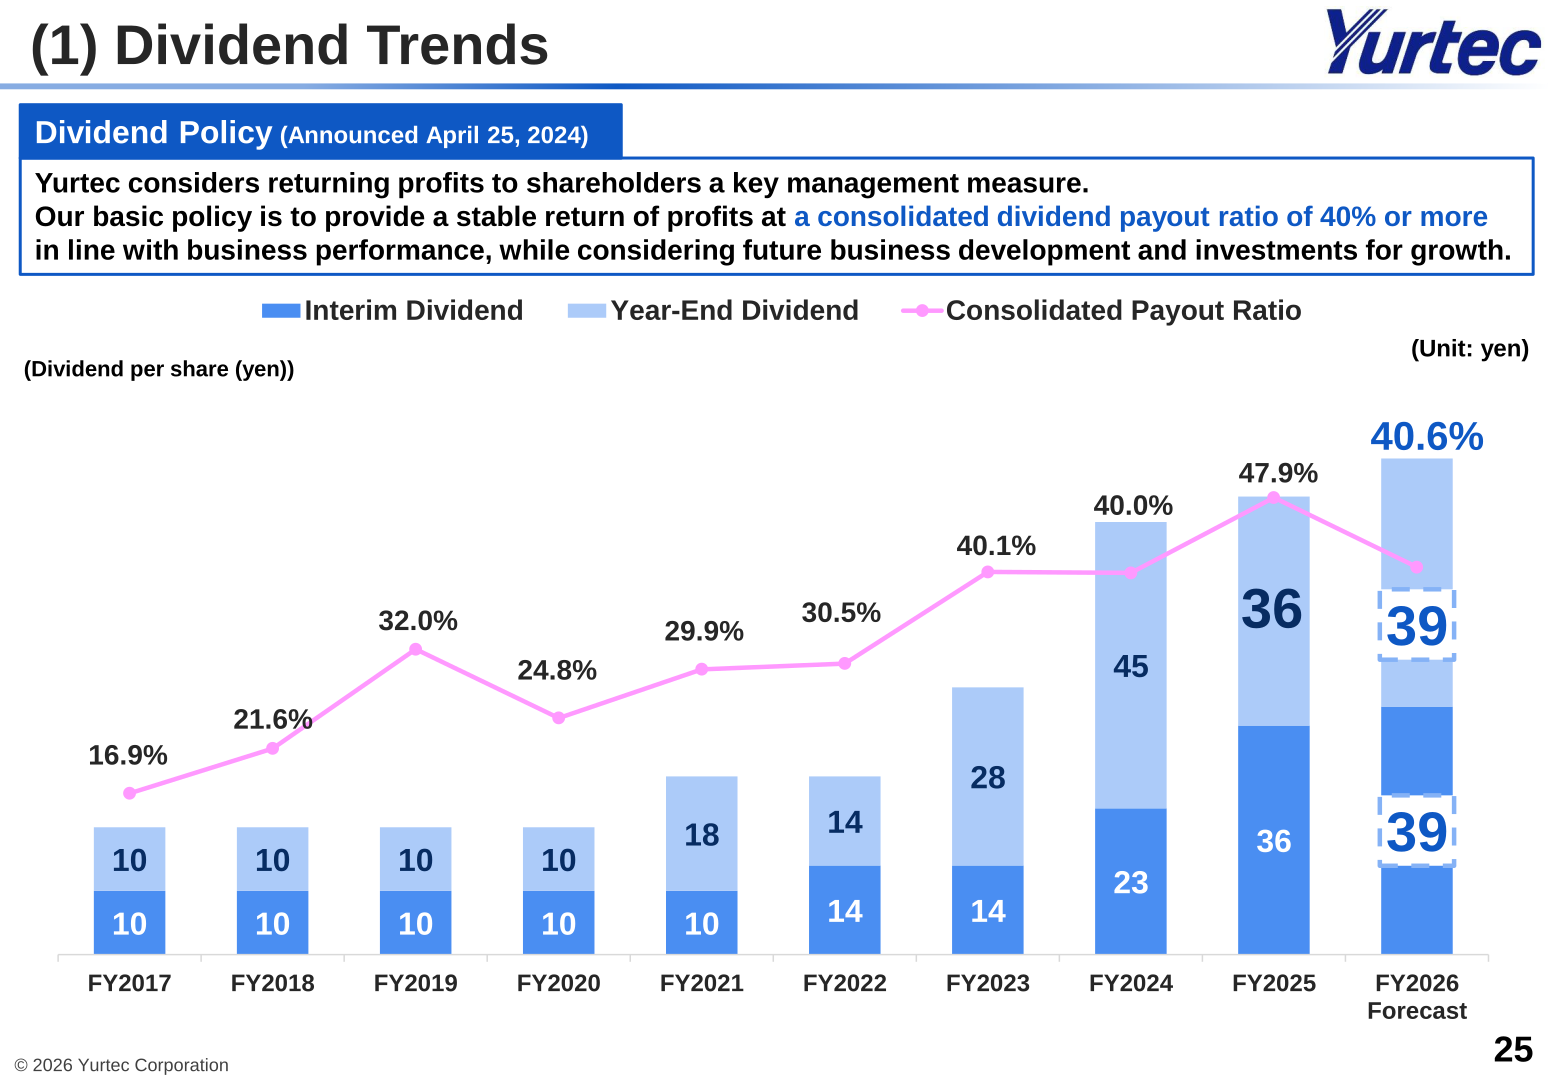
Yurtec’s dividend policy, announced April 25, 2024, is to provide a stable return of profits at a consolidated dividend payout ratio of 40% or more in line with business performance, while considering future business development and investments for growth. For FY2025 the interim dividend was 36 yen and the year-end dividend was 36 yen per share, with a consolidated payout ratio of 47.9%. For FY2026 the company forecasts an interim dividend of 39 yen and a year-end dividend of 39 yen per share, with a consolidated payout ratio of 40.6%. Based on the capital allocation policy announced in October 2024, the company projects a total return ratio of 50% to 60% during the period covered by the Medium-Term Management Plan (2024-2028), and in addition to stable dividends plans to conduct share buybacks as appropriate and in line with valuations and financial conditions, including purchases from the general market as well as from Tohoku Electric Power.
| Dividend per share (yen) | FY2024 | FY2025 | FY2026 Forecast |
|---|---|---|---|
| Interim dividend | 23 | 36 | 39 |
| Year-end dividend | 45 | 36 | 39 |
| Consolidated payout ratio | 40.0% | 47.9% | 40.6% |
Medium-Term Management Plan (2024-2028)
The company raised the numerical targets of its Medium-Term Management Plan (2024-2028) in October 2025, since it had already achieved certain targets, namely operating profit and ROE in FY2024. The FY2028 numerical targets are net sales of 280 billion yen, operating profit of 20 billion yen and ROE of 9.0%. The FY2025 results shown against those targets are net sales of 252.2 billion yen, operating profit of 18.0 billion yen and ROE of 6.8%. Under the 2030 Vision numerical targets disclosed March 27, 2024, the early-2030s targets are net sales of 300 billion yen, operating profit of 20 billion yen and ROE of 8.0%.
The plan sets four priority businesses: business outside of Tohoku and Niigata, overseas business, renewable energy-related construction, and renovation construction. Against FY2028 plans, FY2025 net sales were 202.9 billion yen in Tohoku and Niigata, 23.3 billion yen outside of Tohoku and Niigata, 17.9 billion yen in overseas business, 8.2 billion yen in renewable energy-related construction, and 37.7 billion yen in renovation construction. For capital allocation over the plan period, the company plans total growth investment of approximately 80 billion yen, comprising business investment of approximately 28 billion yen, capital investment of approximately 27 billion yen, human resources investment of approximately 15 billion yen and IT and DX investment of approximately 10 billion yen, alongside total shareholder return of approximately 40 billion yen. During FY2025 the company also secured two large-scale overseas renewable energy-related projects: an ODA loan assistance project for the Hurghada Solar Power Plant Development in Egypt with a contract value of 7,500 million yen, and a wind power plant project in Soc Trang Province, Vietnam with a contract value of 1,256 billion VND.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















