
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: the company labels this fiscal year “2026/3” (the fiscal year ended March 31, 2026), which the presentation also refers to as FY2025; the labels used in the body text and tables below follow the source materials. Wakachiku Construction reported consolidated net sales of 104,748 million yen for 2026/3, up 21.1% year on year, with ordinary profit of 6,426 million yen, up 22.9%. On a non-consolidated basis, orders received reached 127,986 million yen, up 23.1% year on year, and operating profit rose 30.5% to 6,244 million yen. During the year the company became a consolidated subsidiary of Aso Corporation following a tender offer by ACVE Holdings GK. For 2027/3 the company forecasts consolidated net sales of 116,000 million yen and ordinary profit of 6,500 million yen.
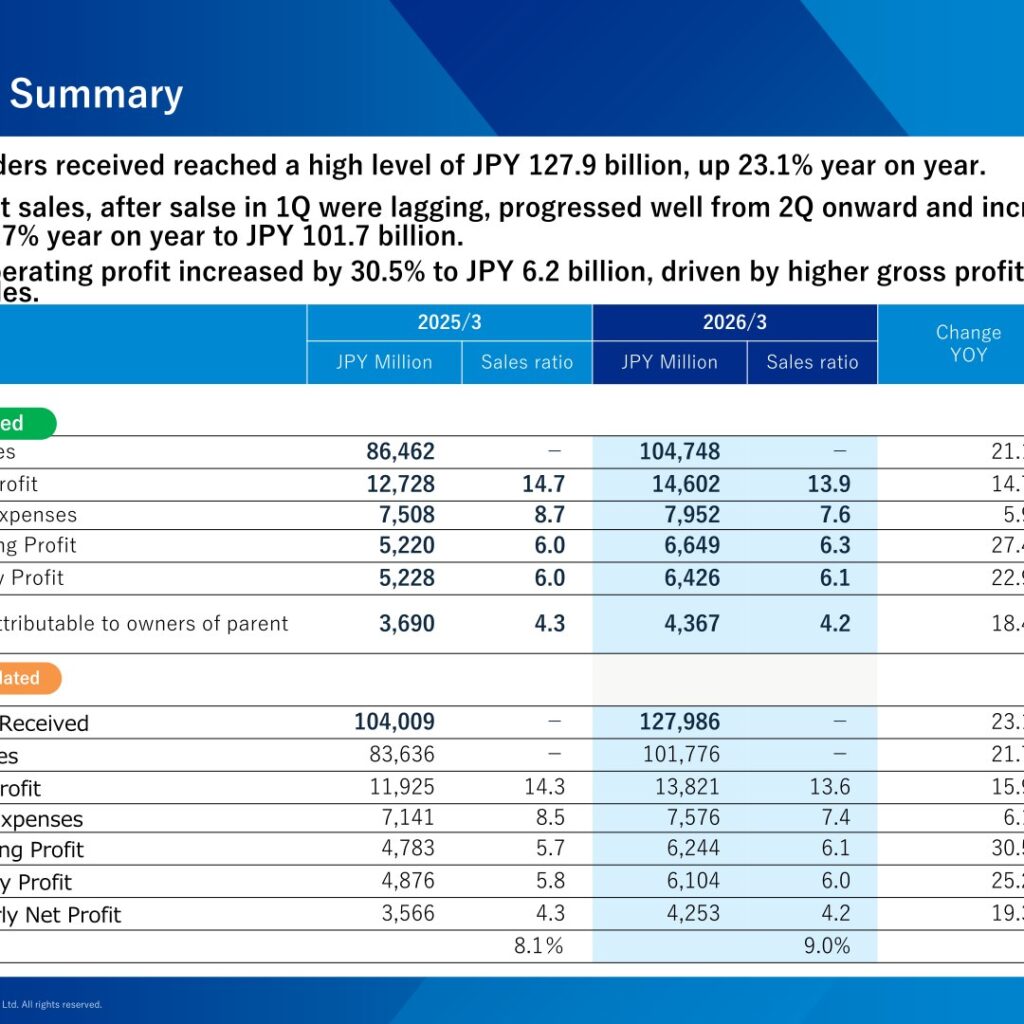
Consolidated Results (Full-Year Actual)
Net sales, after sales in 1Q were lagging, progressed well from 2Q onward and increased by 21.7% year on year to 101,776 million yen on a non-consolidated basis. Operating profit increased by 30.5% to 6,244 million yen (non-consolidated), driven by higher gross profit on increased sales. Orders received reached a high level of 127,986 million yen, up 23.1% year on year. Non-consolidated ROE rose from 8.1% to 9.0%.
| Basis | Item | 2025/3 | Sales ratio | 2026/3 | Sales ratio | Change YoY (%) |
|---|---|---|---|---|---|---|
| Consolidated | Net Sales | 86,462 | - | 104,748 | - | 21.1 |
| Consolidated | Gross Profit | 12,728 | 14.7 | 14,602 | 13.9 | 14.7 |
| Consolidated | SG&A Expenses | 7,508 | 8.7 | 7,952 | 7.6 | 5.9 |
| Consolidated | Operating Profit | 5,220 | 6.0 | 6,649 | 6.3 | 27.4 |
| Consolidated | Ordinary Profit | 5,228 | 6.0 | 6,426 | 6.1 | 22.9 |
| Consolidated | Profit Attributable to Owners of Parent | 3,690 | 4.3 | 4,367 | 4.2 | 18.4 |
| Non-Consolidated | Orders Received | 104,009 | - | 127,986 | - | 23.1 |
| Non-Consolidated | Net Sales | 83,636 | - | 101,776 | - | 21.7 |
| Non-Consolidated | Gross Profit | 11,925 | 14.3 | 13,821 | 13.6 | 15.9 |
| Non-Consolidated | SG&A Expenses | 7,141 | 8.5 | 7,576 | 7.4 | 6.1 |
| Non-Consolidated | Operating Profit | 4,783 | 5.7 | 6,244 | 6.1 | 30.5 |
| Non-Consolidated | Ordinary Profit | 4,876 | 5.8 | 6,104 | 6.0 | 25.2 |
| Non-Consolidated | Quarterly Net Profit | 3,566 | 4.3 | 4,253 | 4.2 | 19.3 |
| Non-Consolidated | ROE | 8.1% | - | 9.0% | - | - |
On the consolidated balance sheet, total assets stood at 122,423 million yen at the end of 2026/3 against 91,890 million yen a year earlier, and total net assets were 54,759 million yen against 49,858 million yen. The equity ratio stands at 44.1%. Net cash flows from operating activities improved to 477 million yen from △10,211 million yen, mainly on higher advances received, and cash and cash equivalents at the end of the period were 19,638 million yen.
Segment Results
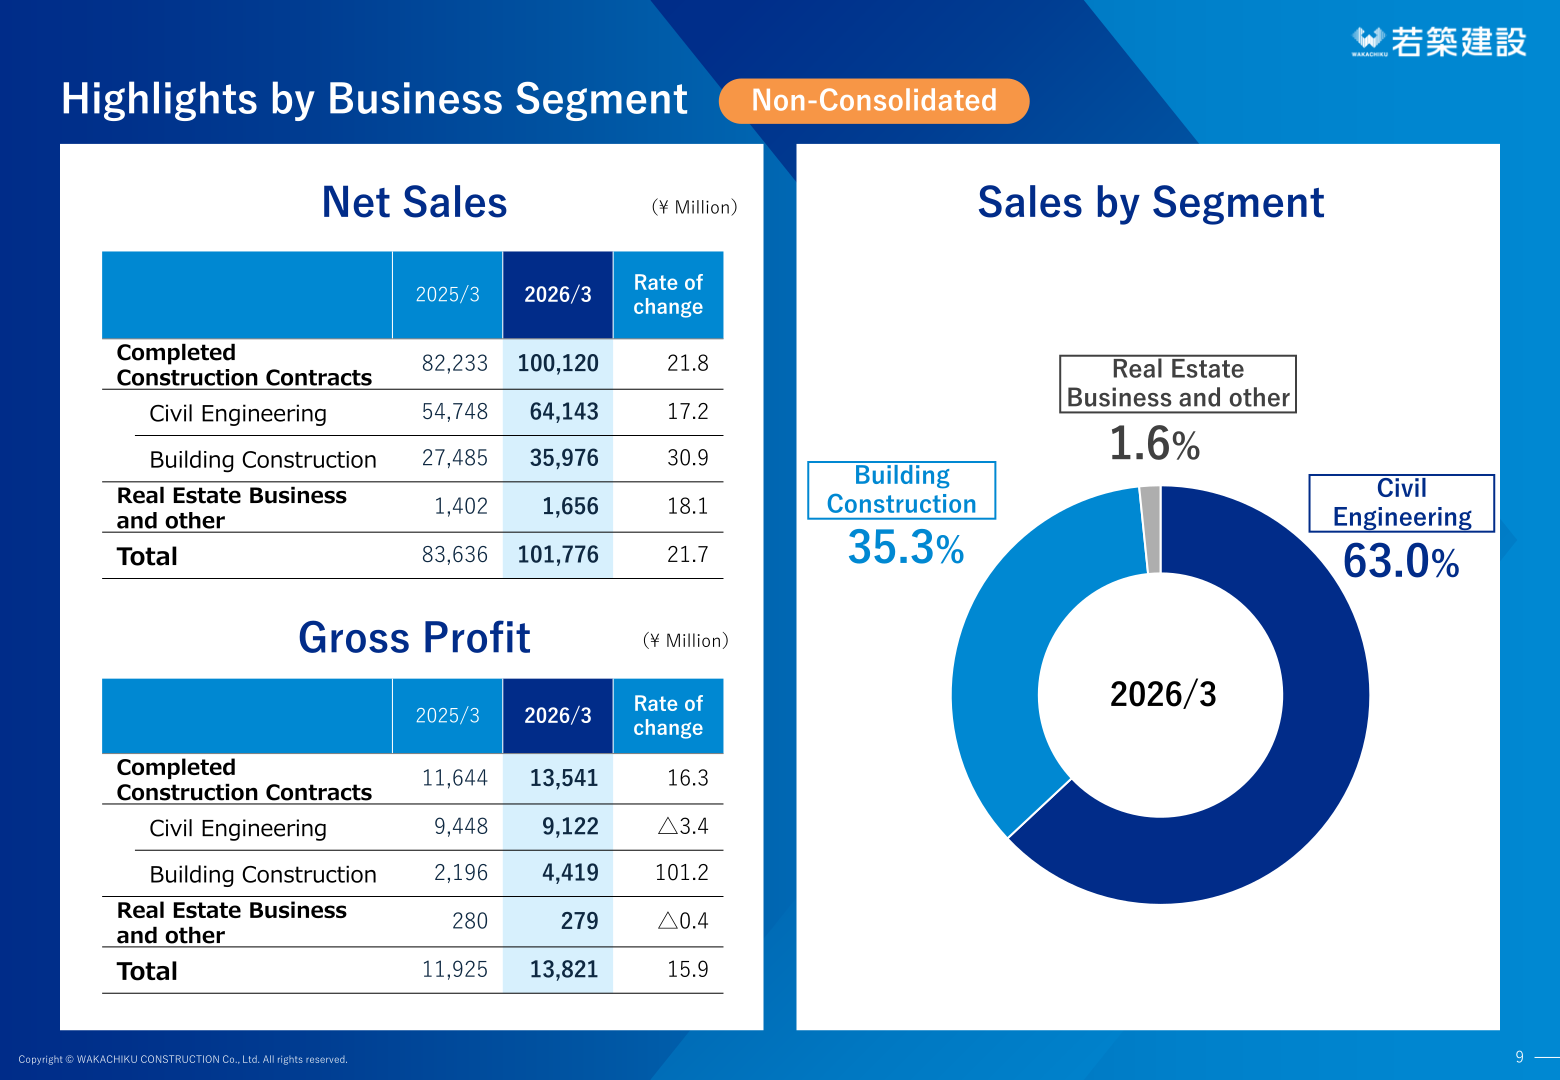
On a non-consolidated basis, completed construction contracts rose 21.8% to 100,120 million yen. Land civil engineering increased by 32.7% year on year, driven by progress on large-scale projects, while the profit margin for land civil engineering decreased by 3.1 points due to extended construction periods on large-scale projects and related factors. In building construction, net sales increased by 30.9% year on year on steady progress on large-scale projects, and gross profit increased by 101.2%, with the gross profit margin reaching 12.3% on productivity improvements from larger-scale projects. Real estate and other businesses grew 18.1% to 1,656 million yen, driven, as in the prior year, by contributions from marine transportation services and the real estate business.
| Segment (Non-Consolidated) | Net Sales 2025/3 | Net Sales 2026/3 | Rate of change (%) | Gross Profit 2025/3 | Gross Profit 2026/3 | Rate of change (%) |
|---|---|---|---|---|---|---|
| Completed Construction Contracts | 82,233 | 100,120 | 21.8 | 11,644 | 13,541 | 16.3 |
| Civil Engineering | 54,748 | 64,143 | 17.2 | 9,448 | 9,122 | △3.4 |
| Building Construction | 27,485 | 35,976 | 30.9 | 2,196 | 4,419 | 101.2 |
| Real Estate Business and other | 1,402 | 1,656 | 18.1 | 280 | 279 | △0.4 |
| Total | 83,636 | 101,776 | 21.7 | 11,925 | 13,821 | 15.9 |
Orders Received and Construction Backlog
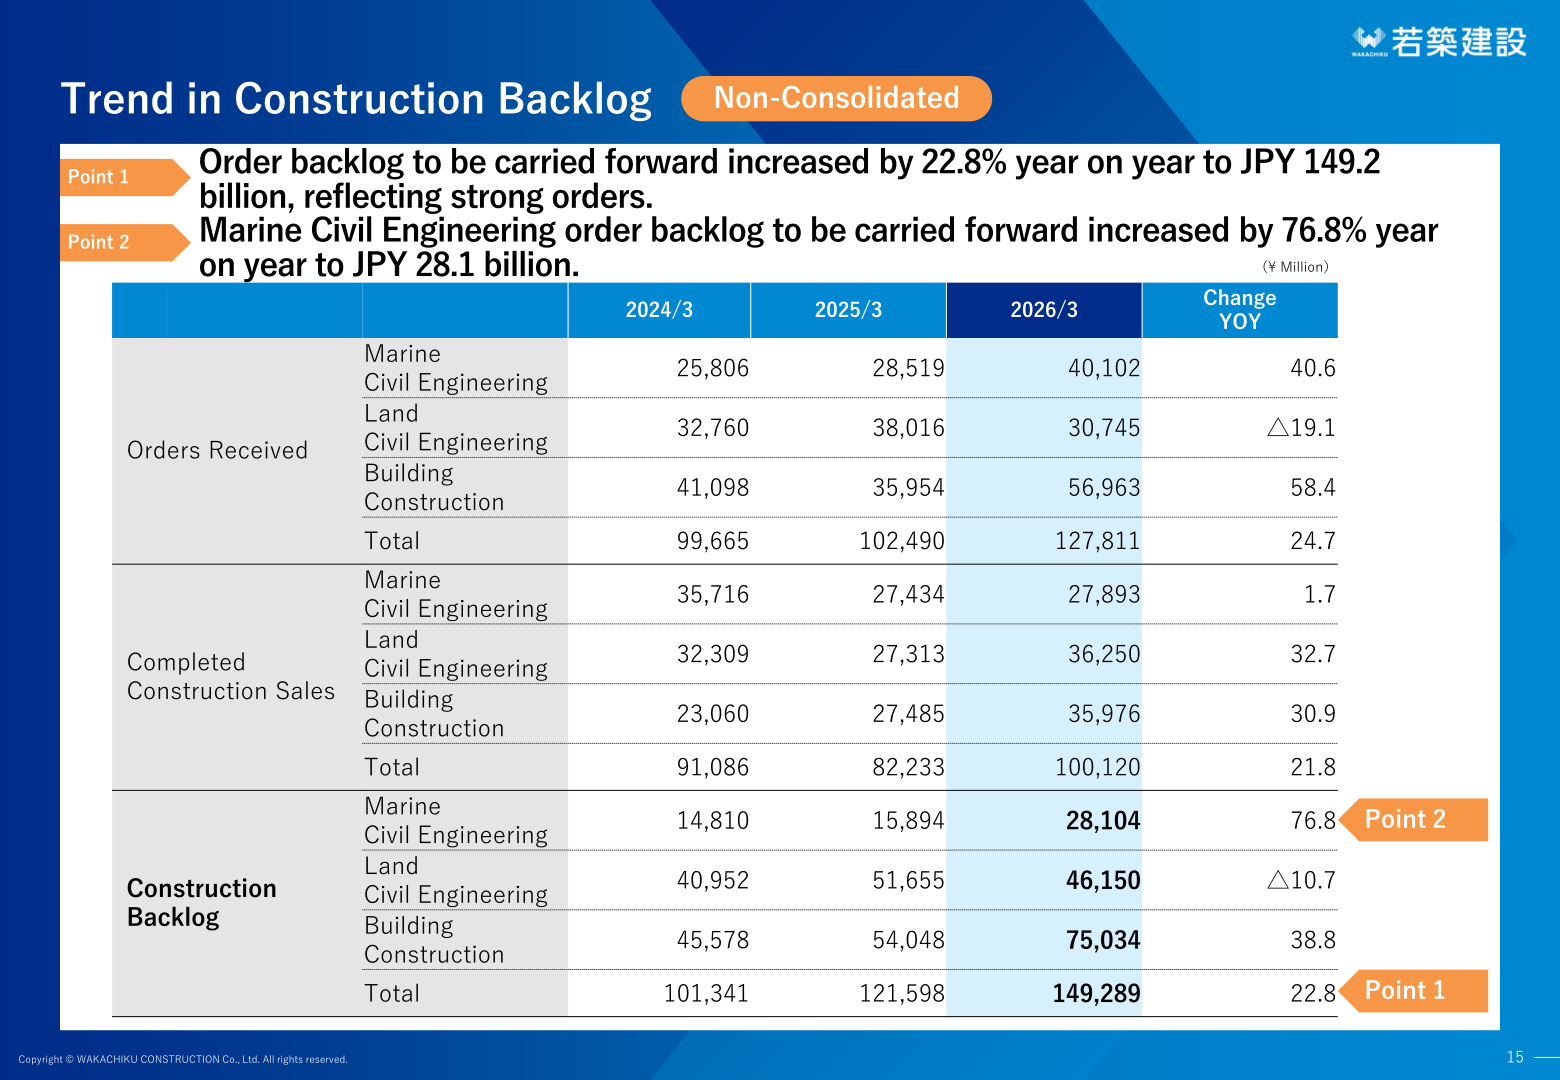
Orders received increased by 23.1% year on year to 127,986 million yen, driven by growth in domestic public-sector civil engineering and domestic building. Domestic orders totaled 122,117 million yen, up 20.2%, split between government at 66,149 million yen (up 20.8%) and private at 55,968 million yen (up 19.4%); reflecting strong private sector demand, the public-to-private ratio stands at 54.2:45.8. Overseas, the company secured port and hospital construction projects totaling 5,693 million yen. Order backlog to be carried forward increased by 22.8% year on year to 149,289 million yen, reflecting strong orders, with marine civil engineering backlog up 76.8% to 28,104 million yen, land civil engineering at 46,150 million yen (△10.7%) and building construction at 75,034 million yen (up 38.8%).
Next-Year Forecast
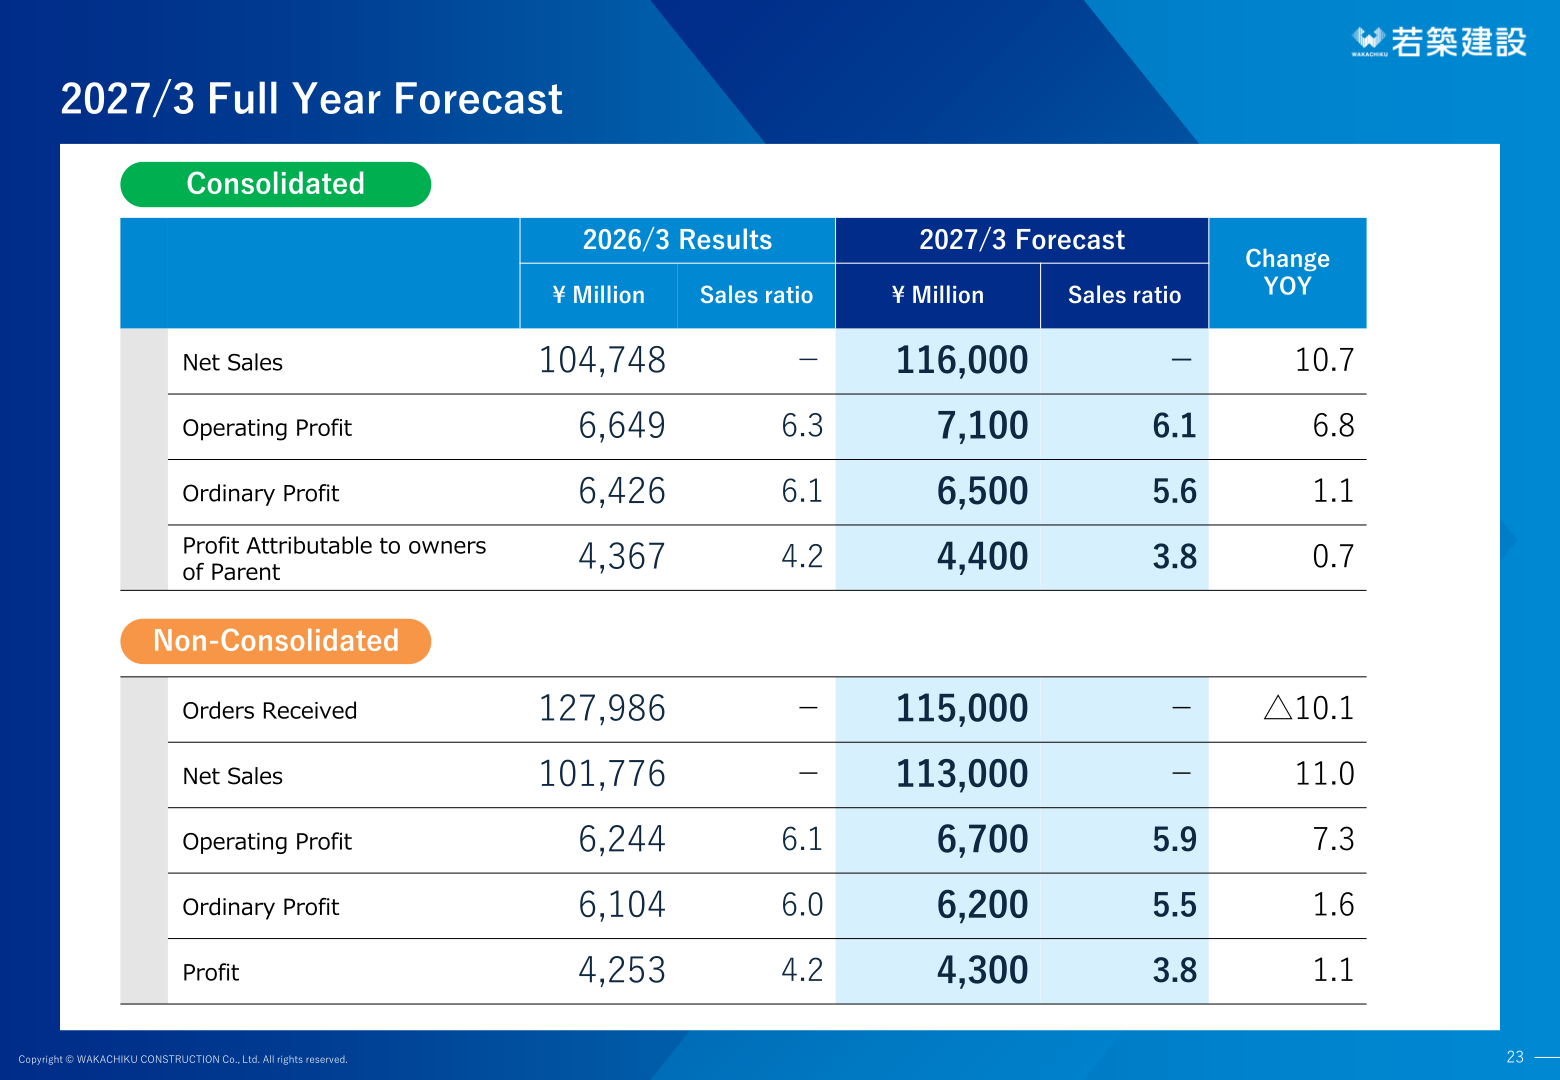
For 2027/3 the company forecasts consolidated net sales of 116,000 million yen (up 10.7%), operating profit of 7,100 million yen (up 6.8%), ordinary profit of 6,500 million yen (up 1.1%) and profit attributable to owners of parent of 4,400 million yen (up 0.7%). Non-consolidated orders received are forecast at 115,000 million yen, down 10.1% from the high level of the year under review.
| Item | 2026/3 Results | 2027/3 Forecast | Change YoY (%) |
|---|---|---|---|
| Net Sales (Consolidated) | 104,748 | 116,000 | 10.7 |
| Operating Profit (Consolidated) | 6,649 | 7,100 | 6.8 |
| Ordinary Profit (Consolidated) | 6,426 | 6,500 | 1.1 |
| Profit Attributable to Owners of Parent (Consolidated) | 4,367 | 4,400 | 0.7 |
| Orders Received (Non-Consolidated) | 127,986 | 115,000 | △10.1 |
| Net Sales (Non-Consolidated) | 101,776 | 113,000 | 11.0 |
| Operating Profit (Non-Consolidated) | 6,244 | 6,700 | 7.3 |
| Ordinary Profit (Non-Consolidated) | 6,104 | 6,200 | 1.6 |
| Profit (Non-Consolidated) | 4,253 | 4,300 | 1.1 |
By segment on a non-consolidated basis, the 2027/3 forecast calls for completed construction contracts of 112,000 million yen (up 11.9%), comprising civil engineering of 72,300 million yen (up 12.7%) and building construction of 39,700 million yen (up 10.3%), with real estate business and other at 1,000 million yen (△39.6%). Total non-consolidated gross profit is forecast at 14,600 million yen, up 5.6%, with the gross profit margin at 12.9% against 13.6% in 2026/3.
Shareholder Returns
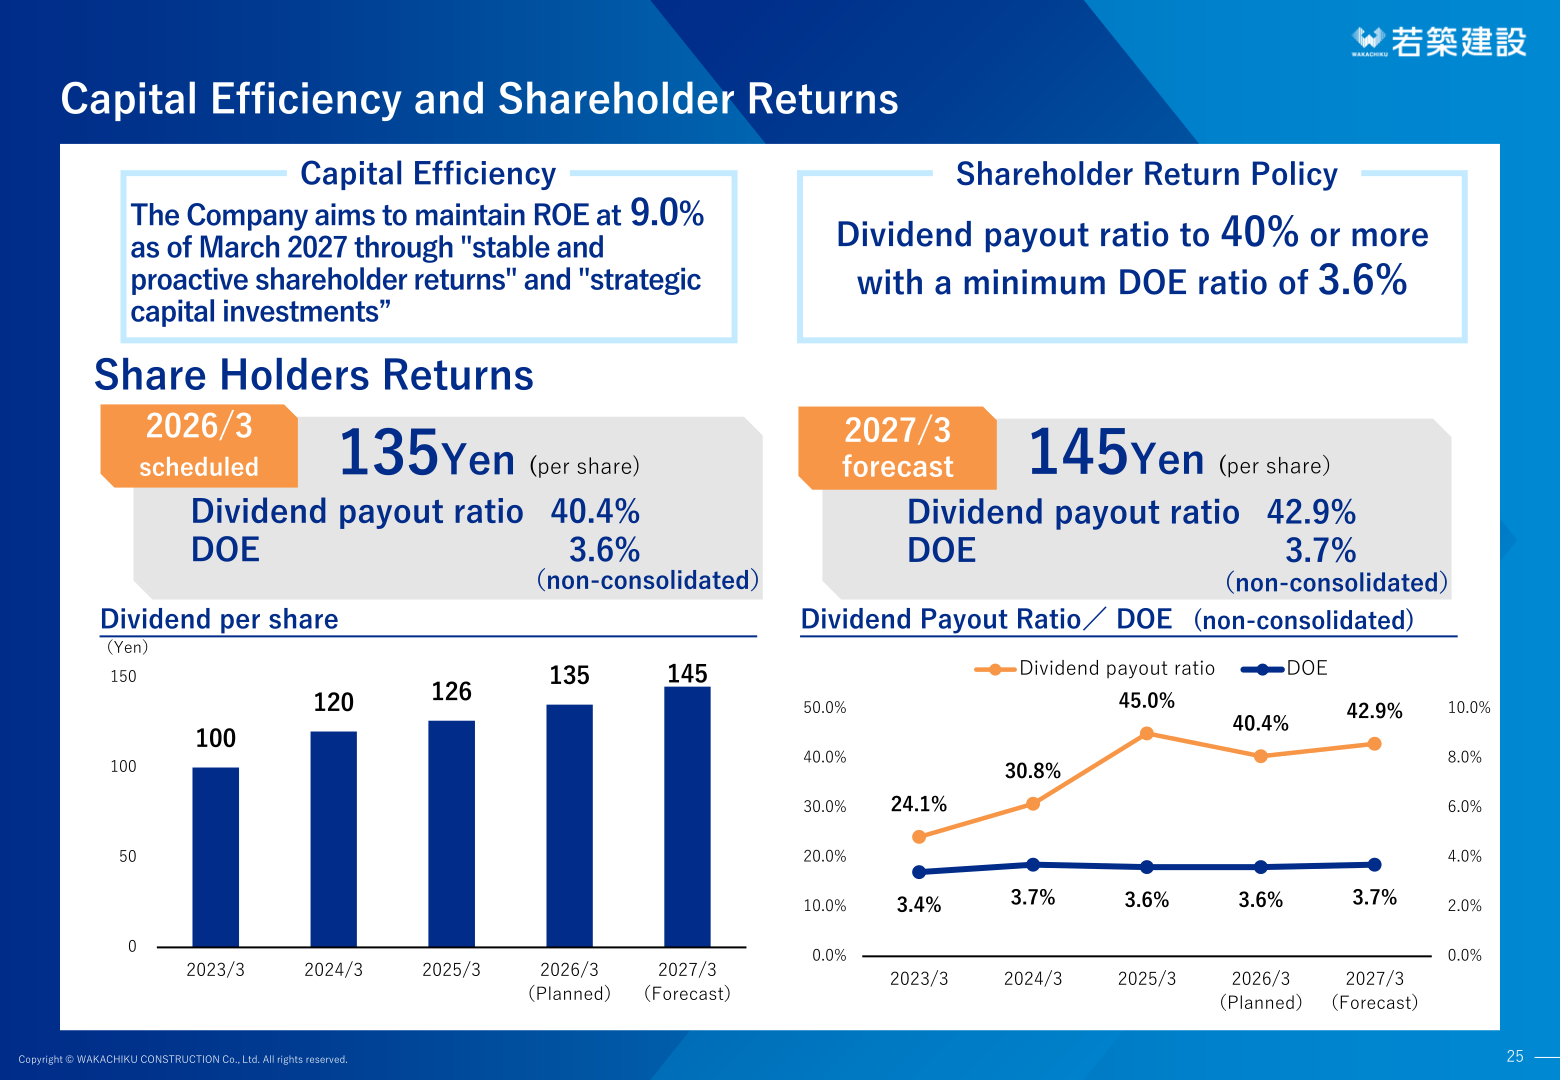
The shareholder return policy sets a dividend payout ratio of 40% or more with a minimum DOE ratio of 3.6%. The dividend per share for 2026/3 is 135 yen (scheduled), giving a dividend payout ratio of 40.4% and DOE of 3.6% on a non-consolidated basis, and the company forecasts 145 yen per share for 2027/3, for a payout ratio of 42.9% and DOE of 3.7%. The company aims to maintain ROE at 9.0% as of March 2027 through “stable and proactive shareholder returns” and “strategic capital investments”.
| Item | 2026/3 (Scheduled) | 2027/3 (Forecast) |
|---|---|---|
| Dividend per share | 135 Yen | 145 Yen |
| Dividend payout ratio (non-consolidated) | 40.4% | 42.9% |
| DOE (non-consolidated) | 3.6% | 3.7% |
Medium-Term Plan and Topics
Wakachiku Construction entered into a capital and business alliance agreement with Aso Corporation and its wholly owned subsidiary, ACVE Holdings GK, and, following a tender offer, became a consolidated subsidiary of Aso Corporation. In response, the company started a review to secure a more independent governance structure following consolidation as a subsidiary, set up a special committee of outside directors to ensure transparency and fairness in transactions with the parent company, and continues to monitor the free-float ratio and execute necessary capital measures to maintain continued listing compliance.
Under the Medium-Term Business Plan (FY2024-FY2026), the three-year non-consolidated targets for 2027/3 are orders of 115 billion yen (against a target of 110 billion yen or more), net sales of 113 billion yen (110 billion yen or more), operating profit of 6.7 billion yen (6.5 billion yen or more), profit of 4.3 billion yen (4.5 billion yen or more) and ROE of 8.5% (9% or more). Against these, 2026/3 actual figures were orders of 127.9 billion yen, net sales of 101.7 billion yen, operating profit of 6.2 billion yen, profit of 4.2 billion yen and ROE of 9.0%. Cumulative investment under the plan reached 4,610 million yen through 2026/3, comprising 1,080 million yen of investment in marine machinery and real estate for profit, 1,430 million yen of R&D, 910 million yen of DX and 1,180 million yen of HR and branding.
On sustainability, the company obtained SBTi approval for revised GHG emissions reduction targets: reduce Scope 1 and 2 by 42% by FY2030 versus FY2024, and reduce Scope 3 absolute emissions by 25% over the same period. It also obtained METI DX Certification in March 2026. In renewable energy, the company is constructing an offshore wind-ready quay wall with ground improvement at Sakata Port, Yamagata, with completion scheduled for March 2027, and participates in the Chokai Hydropower Project in Nikaho, Akita, through project company Nikaho Green Energy G.K. (Wakachiku 10%) with a capacity of 999.9 kW.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















