
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note on year labels: this article covers the fiscal year ended March 31, 2026, which Tokyu Construction’s presentation labels “FY03/2026” and which japan-equity.com classifies as FY2025. Figures, table headers and segment labels below follow the company’s own labels as reported.
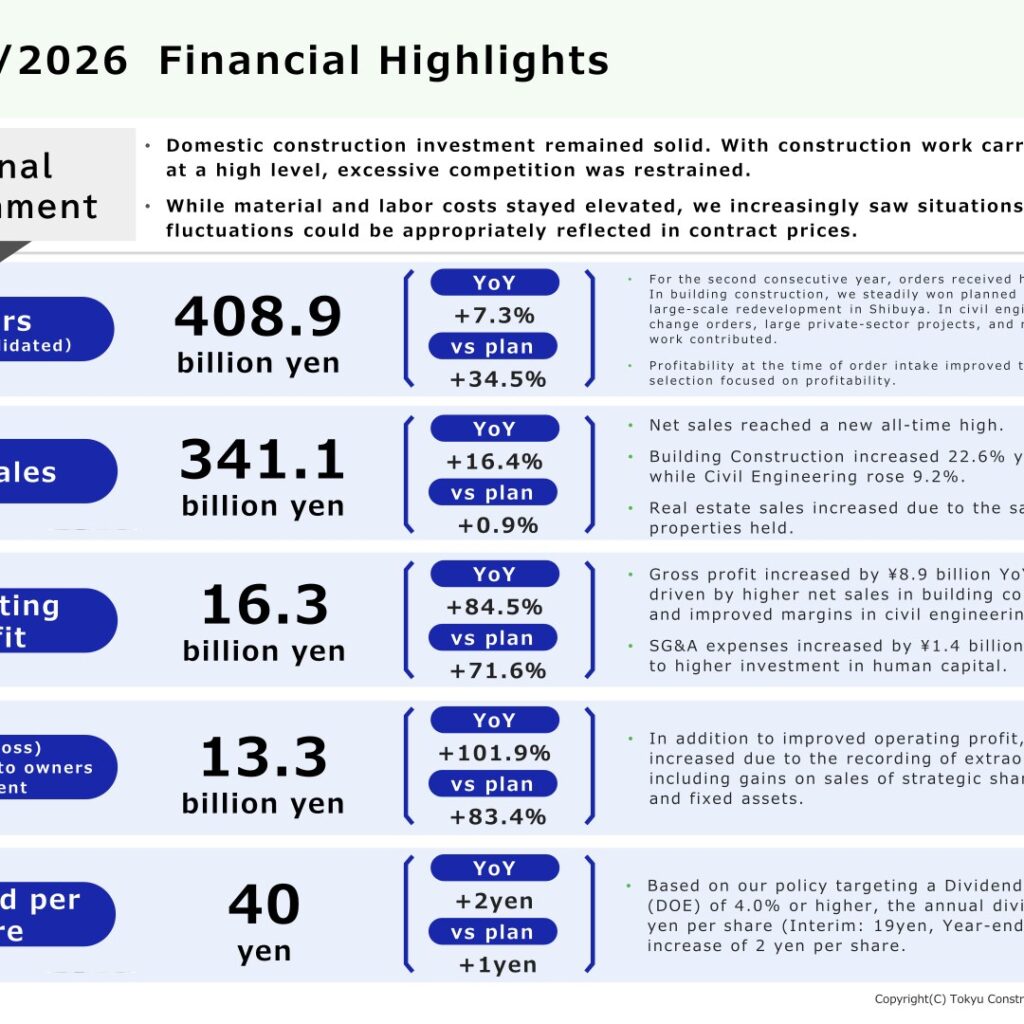
Tokyu Construction reported record-high net sales for the fiscal year ended March 31, 2026, with consolidated net sales of 341,181 million yen, up 48,042 million yen or 16.4% year on year. Operating profit rose 84.5% to 16,306 million yen and profit attributable to owners of parent rose 101.9% to 13,390 million yen. Non-consolidated orders received reached a record high for the second consecutive year at 408,944 million yen, up 7.3%. The company describes the year as the culmination of its “Rebuilding of Earning Capacity” initiatives, which it says have returned the company to a growth trajectory.
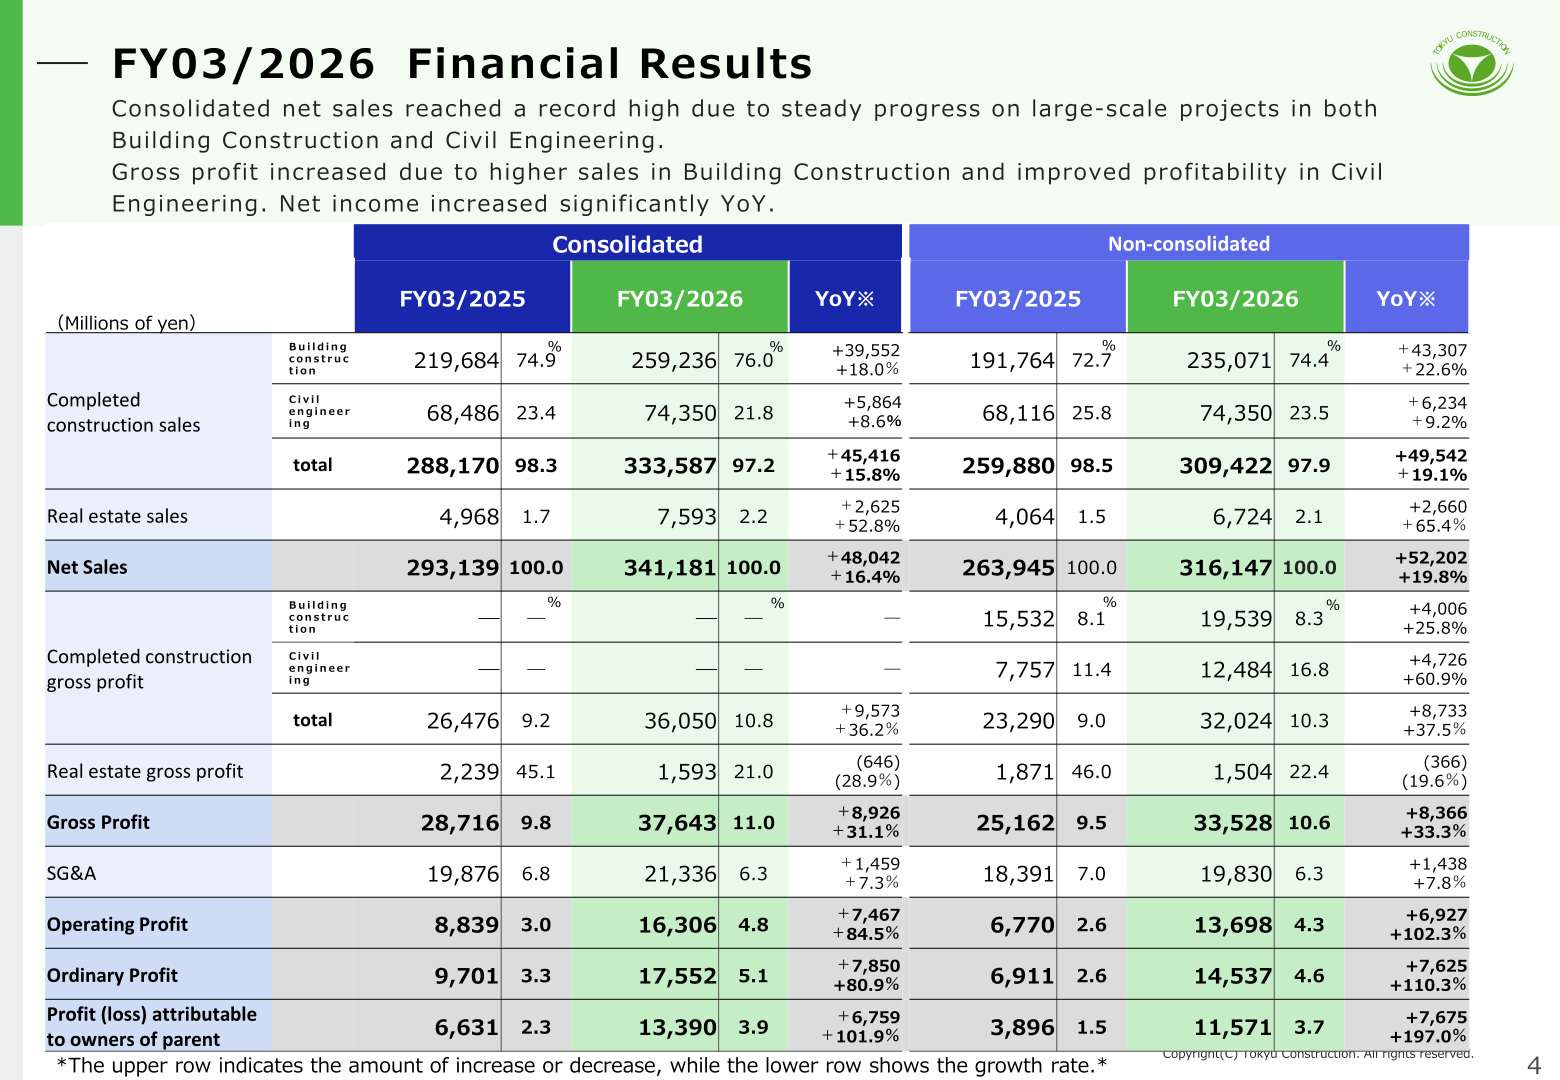
Consolidated Results (FY03/2026 Actual)
Consolidated net sales reached a record high on steady progress of large-scale projects in both Building Construction and Civil Engineering. Gross profit increased by 8,926 million yen (+31.1%), driven by higher sales in Building Construction and improved profitability in Civil Engineering, while SG&A expenses increased by 1,459 million yen (+7.3%), mainly due to higher investment in human capital. In addition to the improvement in operating profit, net income benefited from extraordinary gains including gains on sales of strategic shareholdings and fixed assets. Against the initial plan, the company reported operating profit 71.6% above plan and profit attributable to owners of parent 83.4% above plan.
| Item (Consolidated, Millions of yen) | FY03/2025 | FY03/2026 | YoY |
|---|---|---|---|
| Completed construction sales (total) | 288,170 | 333,587 | +45,416 / +15.8% |
| Real estate sales | 4,968 | 7,593 | +2,625 / +52.8% |
| Net Sales | 293,139 | 341,181 | +48,042 / +16.4% |
| Gross Profit | 28,716 | 37,643 | +8,926 / +31.1% |
| SG&A | 19,876 | 21,336 | +1,459 / +7.3% |
| Operating Profit | 8,839 | 16,306 | +7,467 / +84.5% |
| Ordinary Profit | 9,701 | 17,552 | +7,850 / +80.9% |
| Profit attributable to owners of parent | 6,631 | 13,390 | +6,759 / +101.9% |
Business Results (Non-Consolidated Building Construction and Civil Engineering)
In non-consolidated Building Construction, completed construction sales rose 22.6% to 235,071 million yen as multiple large-scale projects progressed smoothly, and gross profit increased to 19,539 million yen with the profit margin ratio improving 0.2 points to 8.3%. Orders reached a record high above 300 billion yen at 303,808 million yen (+7.0%), including the Shibuya Station District West & Central Buildings project (Shibuya Scramble Square Phase II) and public sector works. In Civil Engineering, completed construction sales rose 9.2% to 74,350 million yen, and both the amount and the margin of gross profit reached all-time highs at 12,484 million yen and 16.8% (+5.4pt), helped by additional work orders and design changes on long-duration projects. Civil engineering orders also hit a record high at 105,136 million yen (+8.2%).
| Item (Non-consolidated, Millions of yen) | FY03/2025 | FY03/2026 | YoY |
|---|---|---|---|
| Building construction — completed construction sales | 191,764 | 235,071 | +43,307 / +22.6% |
| Building construction — completed construction gross profit | 15,532 | 19,539 | +4,006 / +25.8% |
| Building construction — profit margin ratio | 8.1% | 8.3% | +0.2pt |
| Civil engineering — completed construction sales | 68,116 | 74,350 | +6,234 / +9.2% |
| Civil engineering — completed construction gross profit | 7,757 | 12,484 | +4,726 / +60.9% |
| Civil engineering — profit margin ratio | 11.4% | 16.8% | +5.4pt |
| Building construction — orders | 283,892 | 303,808 | 19,915 / 7.0% |
| Civil engineering — orders | 97,206 | 105,136 | 7,930 / 8.2% |
| Total orders | 381,098 | 408,944 | 27,846 / 7.3% |
Among the other businesses shown in the briefing, Construction Renewal recorded net sales of 24,685 million yen with a gross profit margin of 15.8% in FY03/2026. The International business saw revenue decline as progress on backlog projects fell short of assumptions, although the profit margin improved to 13.2% because the prior-year provision for losses at overseas subsidiaries did not recur. Real estate net sales increased by 3.4 billion yen year on year on property sales in addition to steady rental income, while the profit margin declined to 12.3% as prior-year reversals of provisions did not recur.
Balance Sheet and Cash Flows
Total assets increased 36,533 million yen to 310,849 million yen. The equity ratio declined 1.2 percentage points from the end of the previous fiscal year to 35.9%, and the D/E ratio stood at 0.32 times, remaining within the target ceiling of 0.5 times. Interest-bearing debt rose 9,356 million yen to 36,067 million yen and net cash was 13,519 million yen. Cash flows from operating activities were 6,910 million yen and cash flows from investing activities were minus 2,451 million yen, giving free cash flow of 4,459 million yen; cash and cash equivalents at end of period were 49,587 million yen.
FY03/2027 Forecast
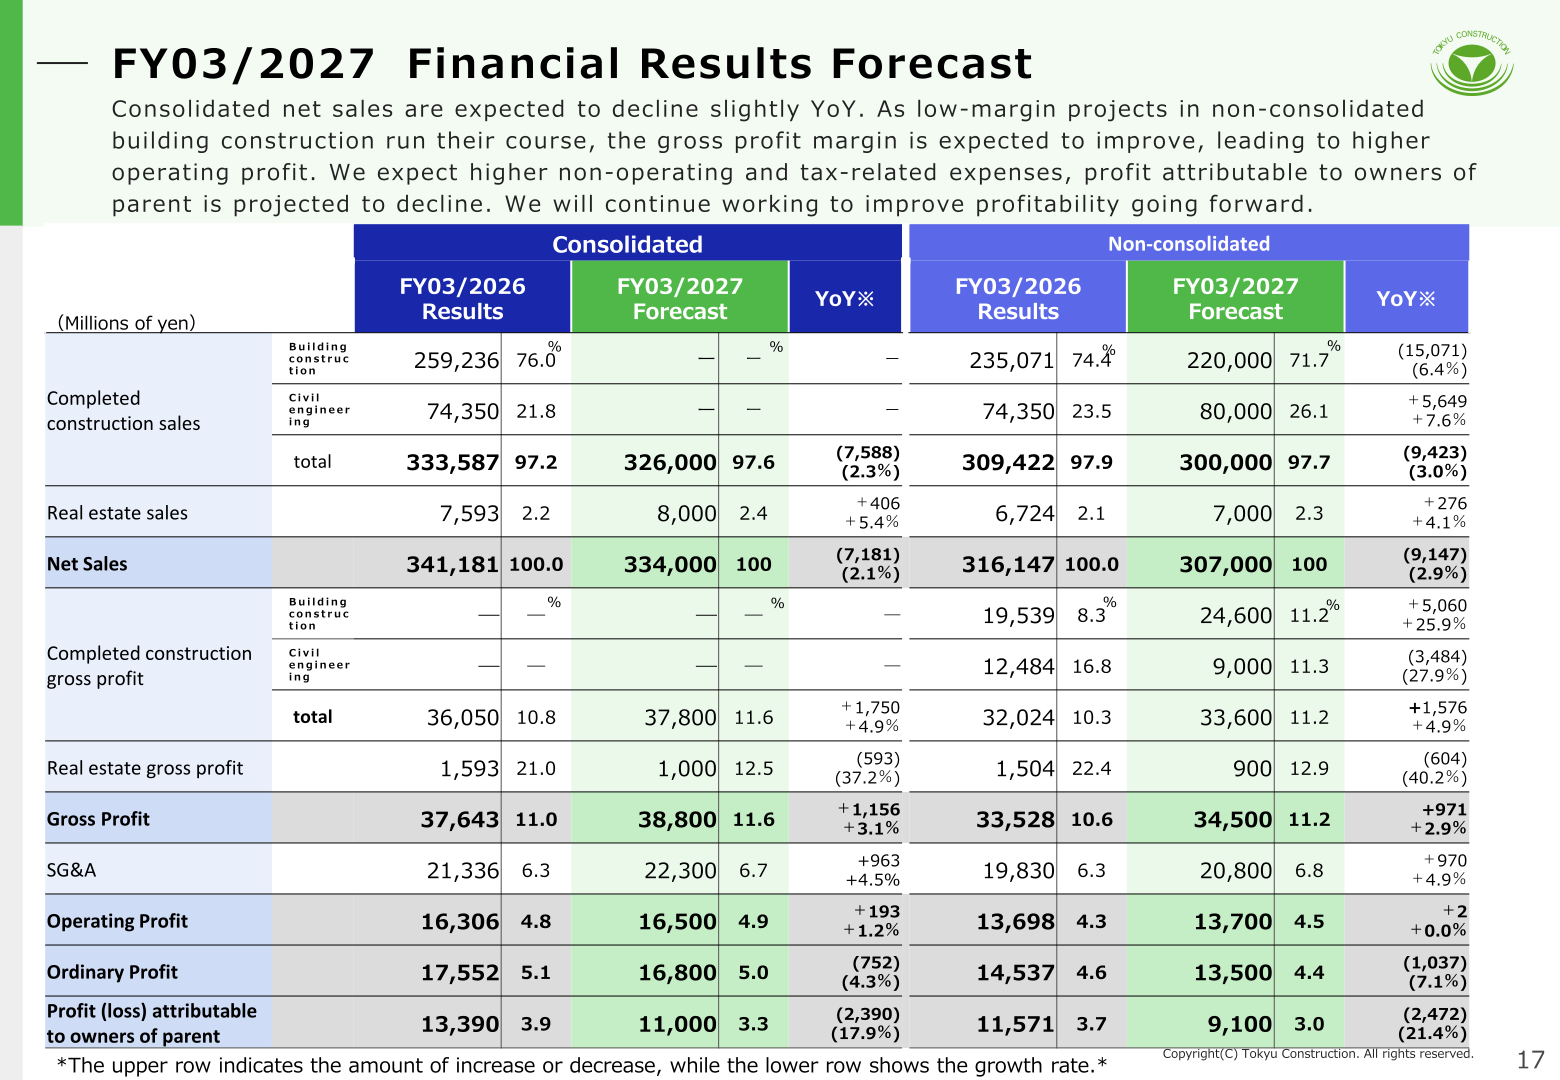
For the fiscal year ending March 31, 2027, the company plans orders received of 486.5 billion yen (+19.0%), which it expects to be a record high for the third consecutive year, while net sales are expected to be slightly below the prior year at 334.0 billion yen (-2.1%) because many projects have only recently broken ground. Operating profit is forecast to rise 1.2% to 16.5 billion yen, described in the briefing as a commitment level set as the current minimum target. Profit attributable to owners of parent is expected to decline 17.9% to 11.0 billion yen, reflecting anticipated decreases in non-operating income and extraordinary gains as well as an increase in income tax expense. The company states that the impact of the situation in the Middle East is not factored into the forecast.
| Item (Consolidated, Millions of yen) | FY03/2026 Results | FY03/2027 Forecast | YoY |
|---|---|---|---|
| Completed construction sales (total) | 333,587 | 326,000 | (7,588) / (2.3%) |
| Real estate sales | 7,593 | 8,000 | +406 / +5.4% |
| Net Sales | 341,181 | 334,000 | (7,181) / (2.1%) |
| Gross Profit | 37,643 | 38,800 | +1,156 / +3.1% |
| SG&A | 21,336 | 22,300 | +963 / +4.5% |
| Operating Profit | 16,306 | 16,500 | +193 / +1.2% |
| Ordinary Profit | 17,552 | 16,800 | (752) / (4.3%) |
| Profit attributable to owners of parent | 13,390 | 11,000 | (2,390) / (17.9%) |
| Orders received (non-consolidated) | 408,944 | 486,500 | +77,555 / +19.0% |
By business on a non-consolidated basis, Building Construction orders are targeted at 344,000 million yen (+13.2%) with completed construction sales of 220,000 million yen (a 6.4% decrease) and a gross profit margin improving to 11.2% as low-margin projects run their course. Civil Engineering orders are planned at 142,500 million yen (+35.5%), including 76,000 million yen of overseas orders tied to a large-scale ODA project for which the company currently holds preferred bidder status, with completed construction sales of 80,000 million yen (+7.6%) and a margin of 11.3%.
Shareholder Returns
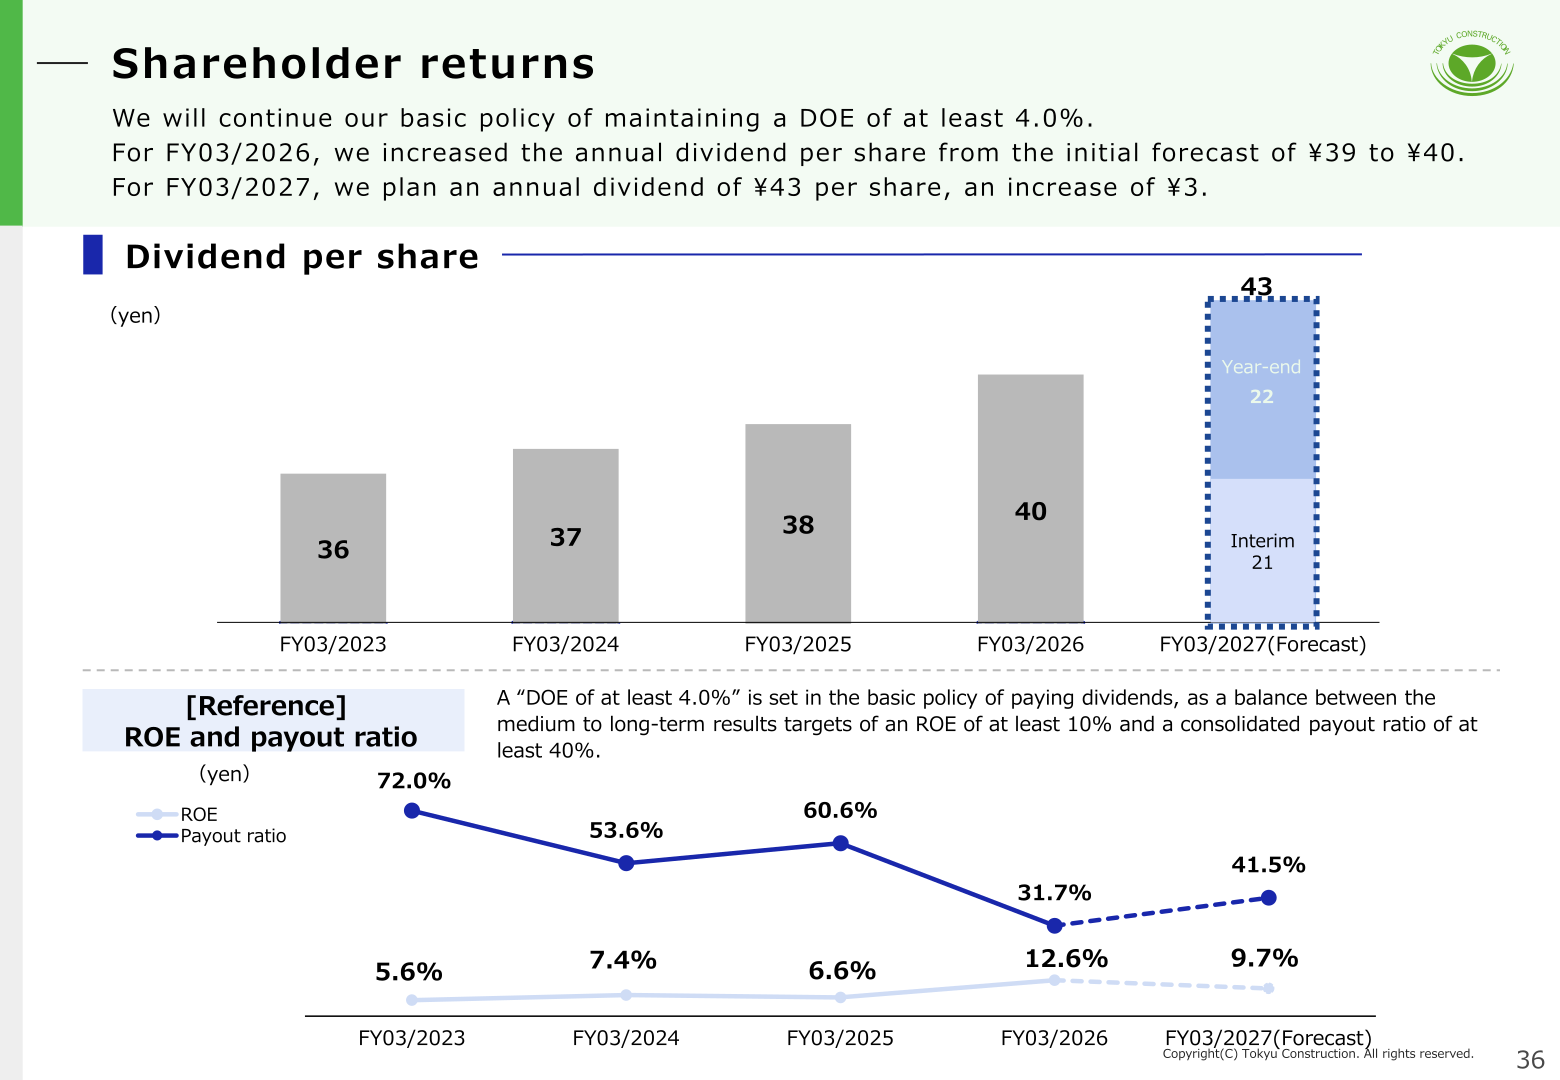
The company’s basic dividend policy is to maintain a dividend on equity (DOE) ratio of at least 4.0%, set as a balance between medium- to long-term targets of an ROE of at least 10% and a consolidated payout ratio of at least 40%. For FY03/2026, the annual dividend per share was raised from the initial forecast of 39 yen to 40 yen (interim 19 yen, year-end 21 yen), an increase of 2 yen per share year on year. For FY03/2027, the company plans an annual dividend of 43 yen per share, an increase of 3 yen. Under its cash allocation plan for FY2021 to FY2030, shareholder returns are set at 41.0 billion yen, and the policy also cites dynamic share buybacks.
Long-Term Management Plan and Capital Policy
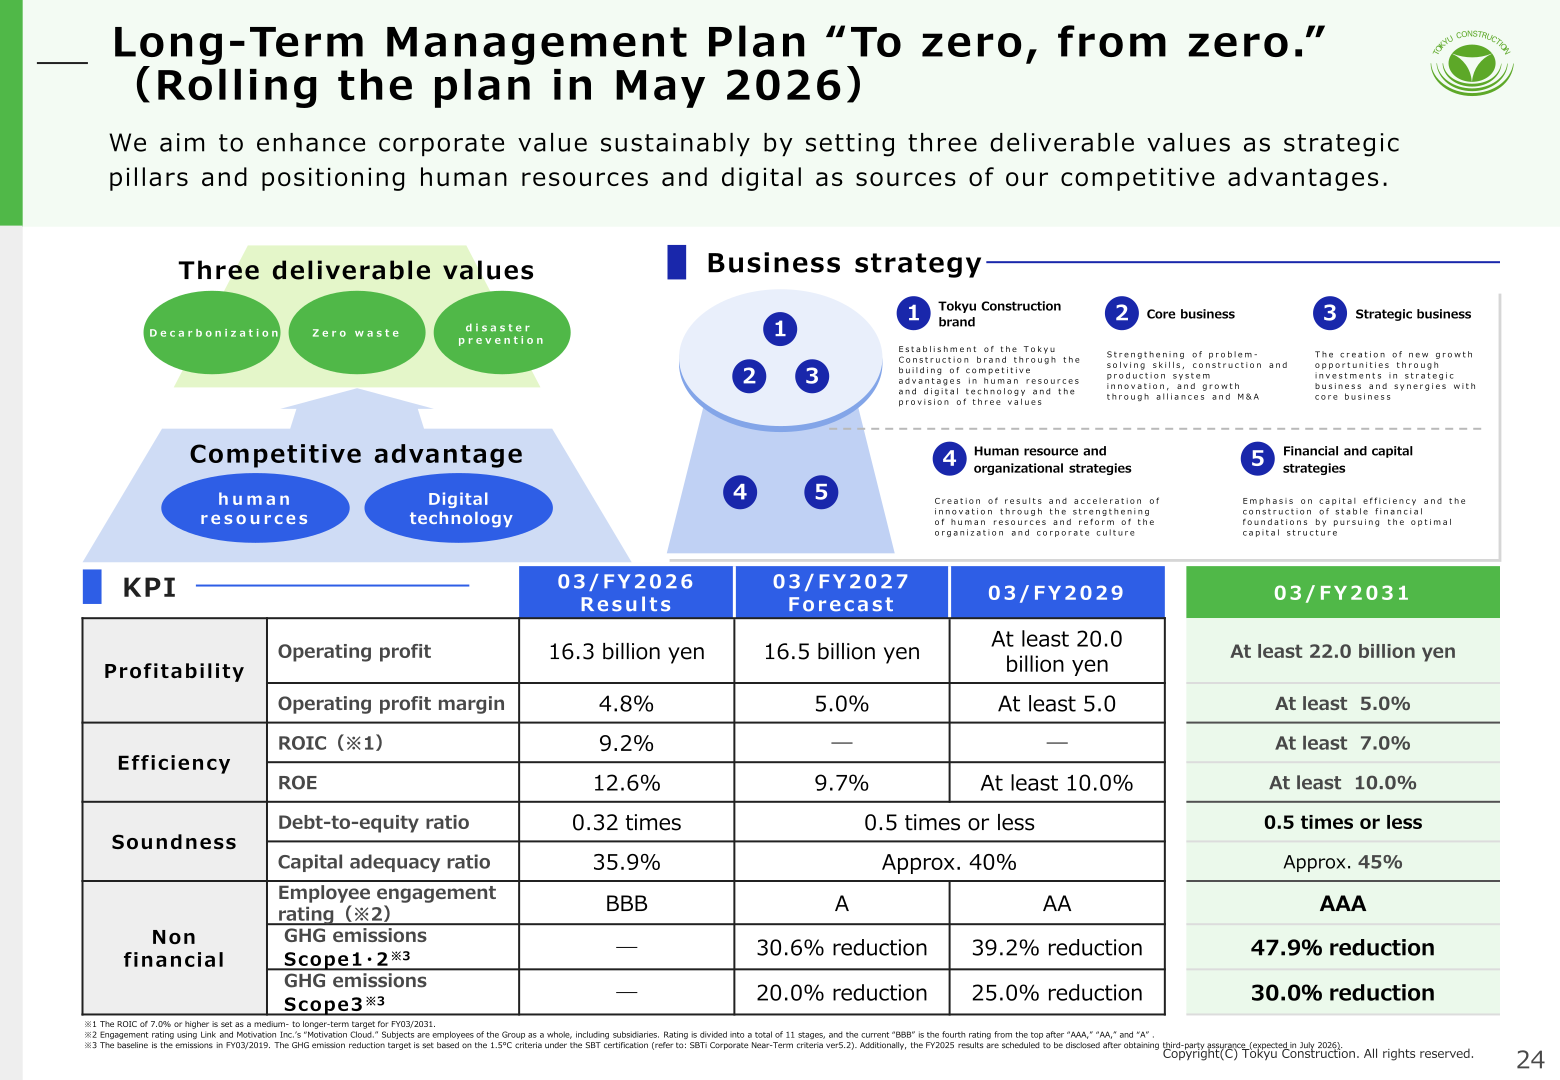
Tokyu Construction rolled its long-term management plan “To zero, from zero.” in May 2026. The plan targets operating profit of at least 20.0 billion yen for 03/FY2029 and at least 22.0 billion yen for 03/FY2031, with an operating profit margin of at least 5.0% and an ROE of at least 10.0%. Reported results for 03/FY2026 were operating profit of 16.3 billion yen, an operating profit margin of 4.8%, ROIC of 9.2% and ROE of 12.6%; the 03/FY2027 forecast is operating profit of 16.5 billion yen, a 5.0% margin and ROE of 9.7%. The capital adequacy ratio was 35.9% and is targeted at approximately 40% for 03/FY2029 and approximately 45% for 03/FY2031.
On capital efficiency, the company recognizes its cost of shareholders’ equity based on CAPM as 5.5% to 6.5%, and reported PBR of 1.47 as of March 31, 2026 versus 0.86 a year earlier. Strategic shareholdings were reduced to a recorded balance sheet amount of 10,607 million yen, equal to 9.4% of consolidated net assets as of March 31, 2026, achieving the “10% or less” target ahead of the FY2030 schedule. Total growth investment of 187.0 billion yen is planned by FY03/2031, comprising 78.0 billion yen for core businesses, 35.0 billion yen for strategic businesses and 74.0 billion yen for human resources and DX investments.
Topics
The briefing announced a leadership transition scheduled for late June 2026: Koji Hisada, currently Managing Executive Officer and Head of Business Administration, is to become Representative Director, President and Representative Executive Officer, while Mitsuhiro Terada is to assume the role of Representative Director and Chairman. The company also plans to transition to a Company with an Audit and Supervisory Committee, with four candidates for directors serving as committee members, of whom three are independent outside directors. Both proposals are scheduled to be submitted to the company’s 23rd Annual General Meeting of Shareholders planned for late June. Separately, the company set out a full-scale expansion of an urban data center business leveraging Tokyu Group assets such as land beneath elevated railway structures, the iTSCOM fiber-optic network and power supply from Tokyu Power Supply, with proof-of-concept testing beneath the Oimachi Line elevated structures scheduled for Q1 FY2026.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















