
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
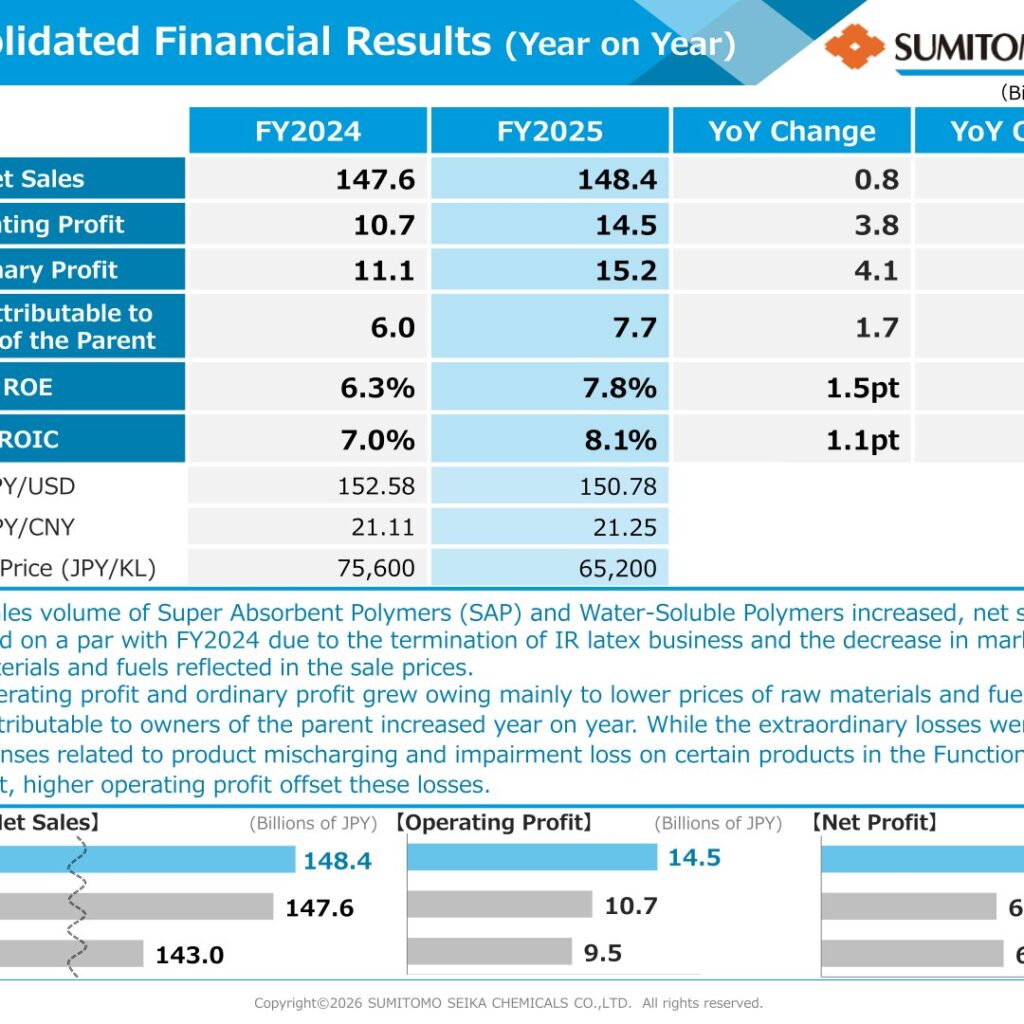
Sumitomo Seika Chemicals Co., Ltd. (Securities Code: 4008) reported FY2025 (fiscal year ended March 31, 2026) net sales of 148.4 billion JPY, up 0.5% year on year, while operating profit rose 35.0% to 14.5 billion JPY and ordinary profit rose 37.3% to 15.2 billion JPY. Profit attributable to owners of the parent increased 28.8% to 7.7 billion JPY, as higher operating profit offset extraordinary losses totaling 4.7 billion JPY. ROE improved to 7.8% and ROIC to 8.1%. Citing risks such as supply constraints on major raw materials amid the Middle East situation, the company has not yet finalized its consolidated financial forecast for FY2026.
Consolidated Results (Full-Year Actual)
While sales volume of Super Absorbent Polymers (SAP) and Water-Soluble Polymers increased, net sales remained on a par with FY2024 due to the termination of the IR latex business and the decrease in market prices of raw materials and fuels reflected in sales prices. Both operating profit and ordinary profit grew owing mainly to lower prices of raw materials and fuels. Profit attributable to owners of the parent increased year on year; while extraordinary losses were recorded for expenses related to product mischarging and impairment loss on certain products in the Functional Materials Segment, higher operating profit offset these losses.
| Item (Billions of JPY) | FY2025 | FY2024 | YoY Change | YoY Change (%) |
|---|---|---|---|---|
| Net Sales | 148.4 | 147.6 | 0.8 | 0.5% |
| Operating Profit | 14.5 | 10.7 | 3.8 | 35.0% |
| Ordinary Profit | 15.2 | 11.1 | 4.1 | 37.3% |
| Profit Attributable to Owners of the Parent | 7.7 | 6.0 | 1.7 | 28.8% |
| ROE | 7.8% | 6.3% | 1.5pt | – |
| ROIC | 8.1% | 7.0% | 1.1pt | – |
| JPY/USD | 150.78 | 152.58 | ||
| JPY/CNY | 21.25 | 21.11 | ||
| Naphtha Price (JPY/KL) | 65,200 | 75,600 |
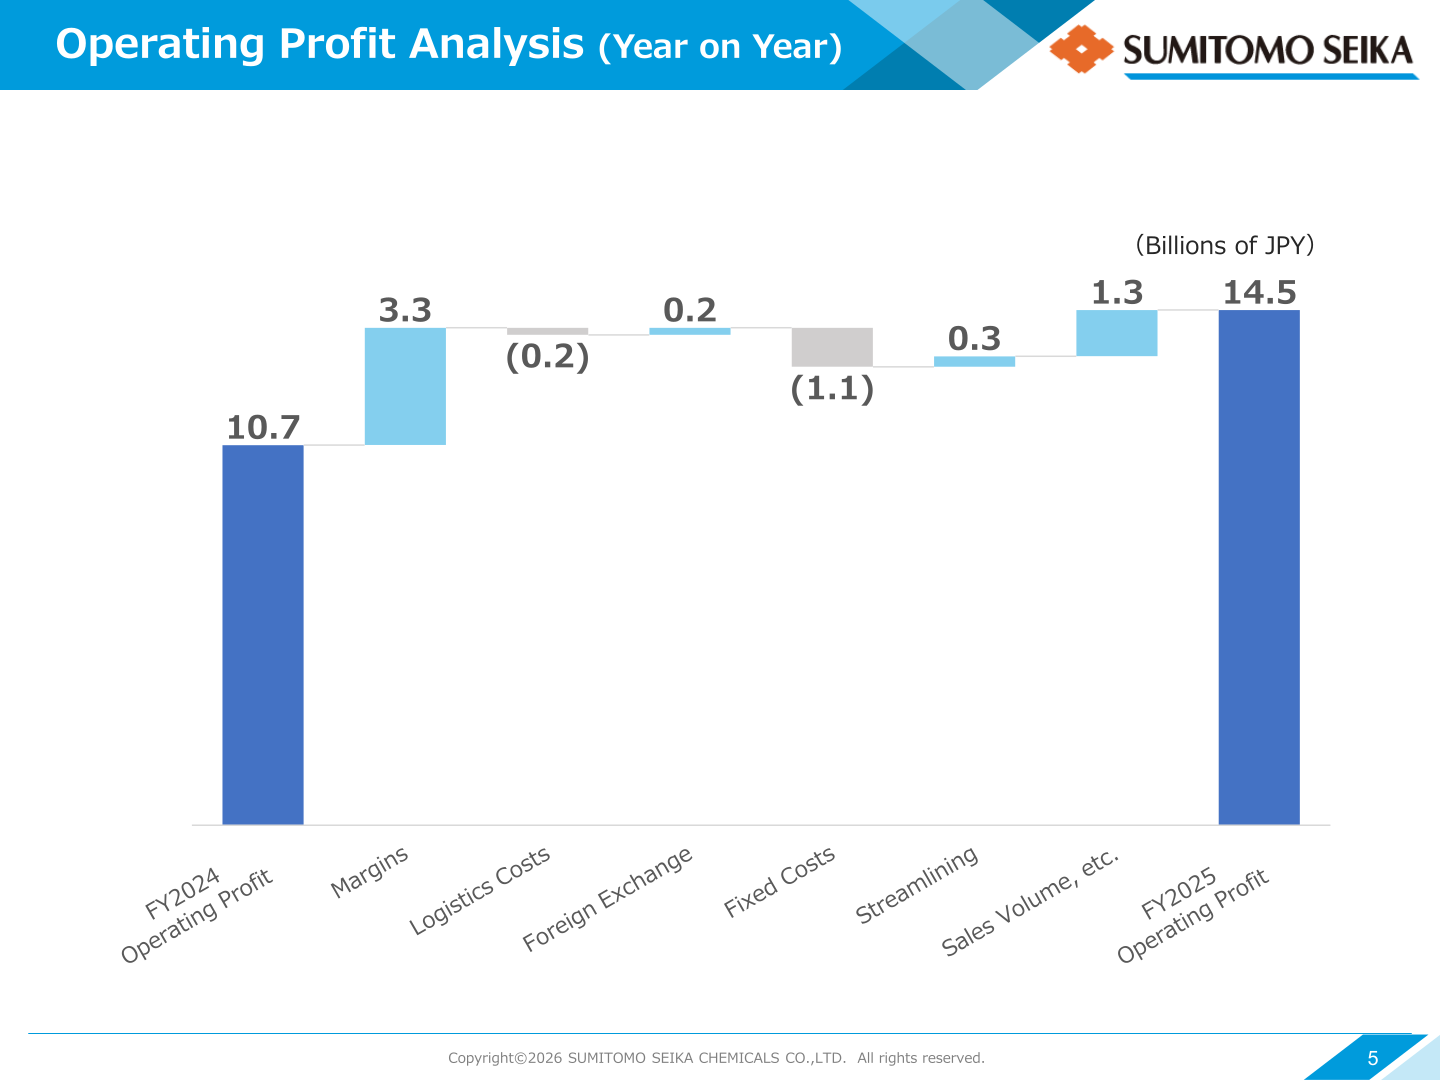
In the year-on-year operating profit analysis, operating profit rose from 10.7 billion JPY to 14.5 billion JPY. Positive factors were margins (+3.3 billion JPY), foreign exchange (+0.2 billion JPY), streamlining (+0.3 billion JPY) and sales volume, etc. (+1.3 billion JPY), while logistics costs ((0.2) billion JPY) and fixed costs ((1.1) billion JPY) were negative factors.
Extraordinary losses totaled 4.7 billion JPY. Expense related to mischarging was 3.2 billion JPY: the company reached an agreement with its customer to pay 3.2 billion JPY in compensation for lost profits incurred by the customer, in addition to the 1.4 billion JPY refund for product mischarging that was recorded as a provision in FY2024. Restructuring costs were 1.2 billion JPY, reflecting impairment losses recognized on certain products in the Functional Materials Segment manufactured at a domestic plant after assessing recoverability based on the business environment.
Segment Results
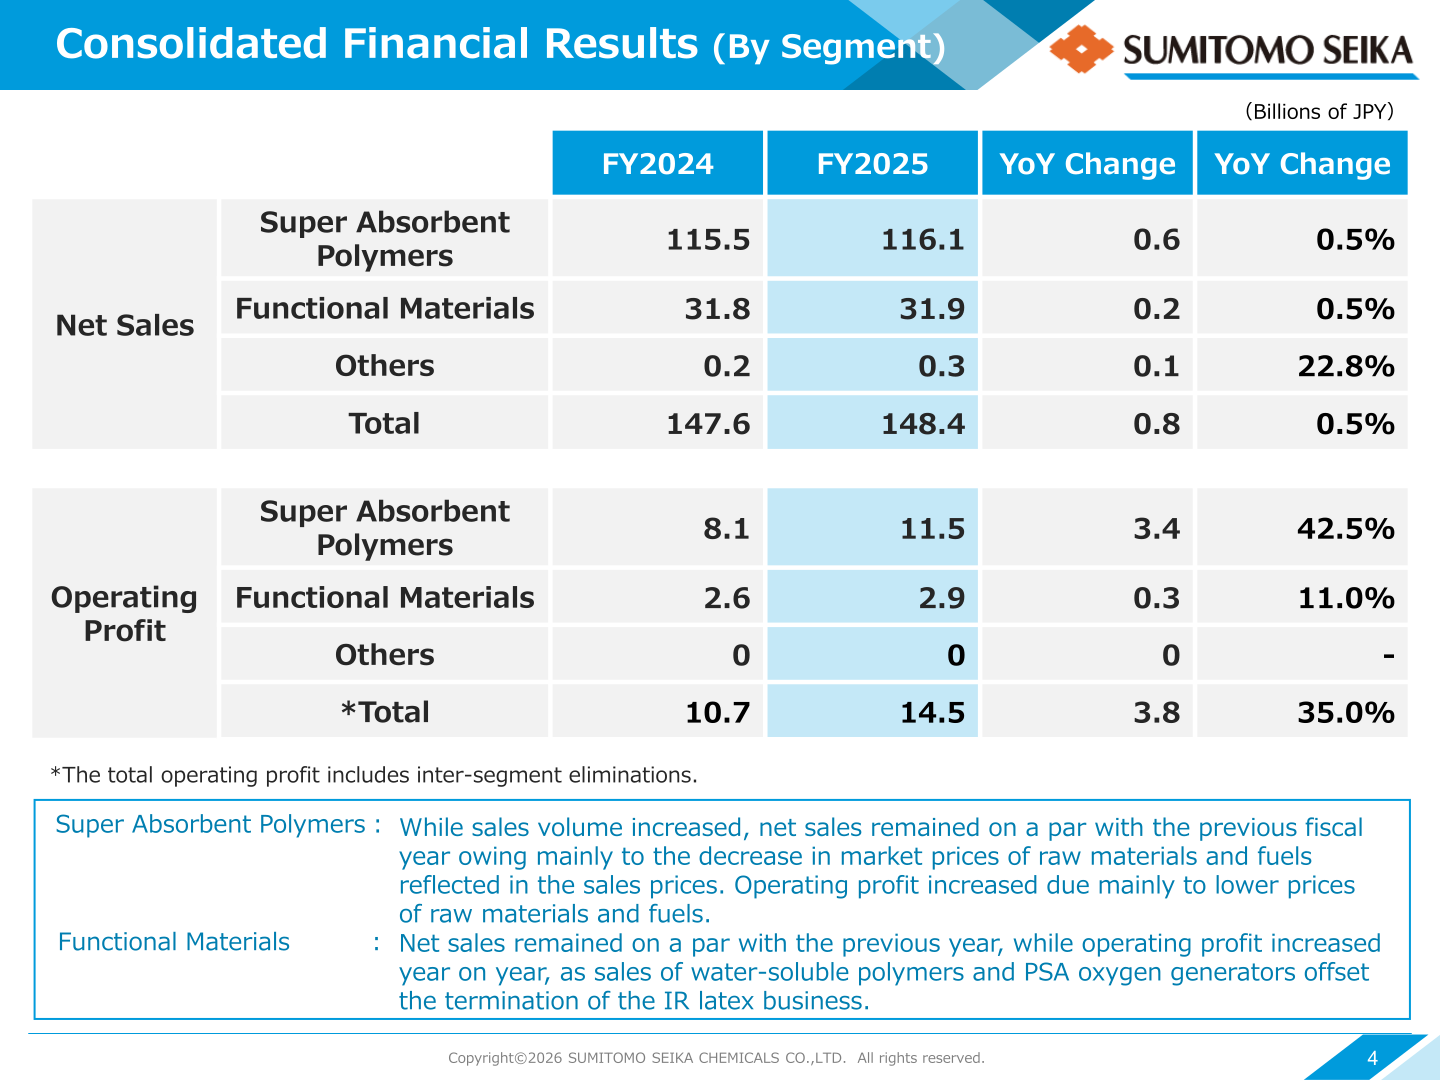
Super Absorbent Polymers: While sales volume increased, net sales remained on a par with the previous fiscal year at 116.1 billion JPY (+0.5%), owing mainly to the decrease in market prices of raw materials and fuels reflected in sales prices. Operating profit increased 42.5% to 11.5 billion JPY, due mainly to lower prices of raw materials and fuels. Global SAP sales volume was 459,000t in FY2025, compared with 455,000t in FY2024.
Functional Materials: Net sales remained on a par with the previous year at 31.9 billion JPY (+0.5%), while operating profit increased 11.0% to 2.9 billion JPY, as sales of water-soluble polymers and PSA oxygen generators offset the termination of the IR latex business. Net sales of electronics gases for FY2025 increased by approximately 3% year on year. Sales of sulfolane, a sulfone-based polar solvent, increased due to higher demand for semiconductor manufacturing cleaning agents; sales of AQUACHARGE, an aqueous binder for lithium-ion secondary batteries, increased; and sales of AQUPEC MG, an aqueous thickener for cosmetics, expanded, driven by increased sales to major global cosmetics manufacturers.
| Segment | Metric (Billions of JPY) | FY2025 | FY2024 | YoY Change | YoY Change (%) |
|---|---|---|---|---|---|
| Super Absorbent Polymers | Net Sales | 116.1 | 115.5 | 0.6 | 0.5% |
| Functional Materials | Net Sales | 31.9 | 31.8 | 0.2 | 0.5% |
| Others | Net Sales | 0.3 | 0.2 | 0.1 | 22.8% |
| Total | Net Sales | 148.4 | 147.6 | 0.8 | 0.5% |
| Super Absorbent Polymers | Operating Profit | 11.5 | 8.1 | 3.4 | 42.5% |
| Functional Materials | Operating Profit | 2.9 | 2.6 | 0.3 | 11.0% |
| Others | Operating Profit | 0 | 0 | 0 | – |
| Total* | Operating Profit | 14.5 | 10.7 | 3.8 | 35.0% |
*The total operating profit includes inter-segment eliminations.
FY2026 Forecast
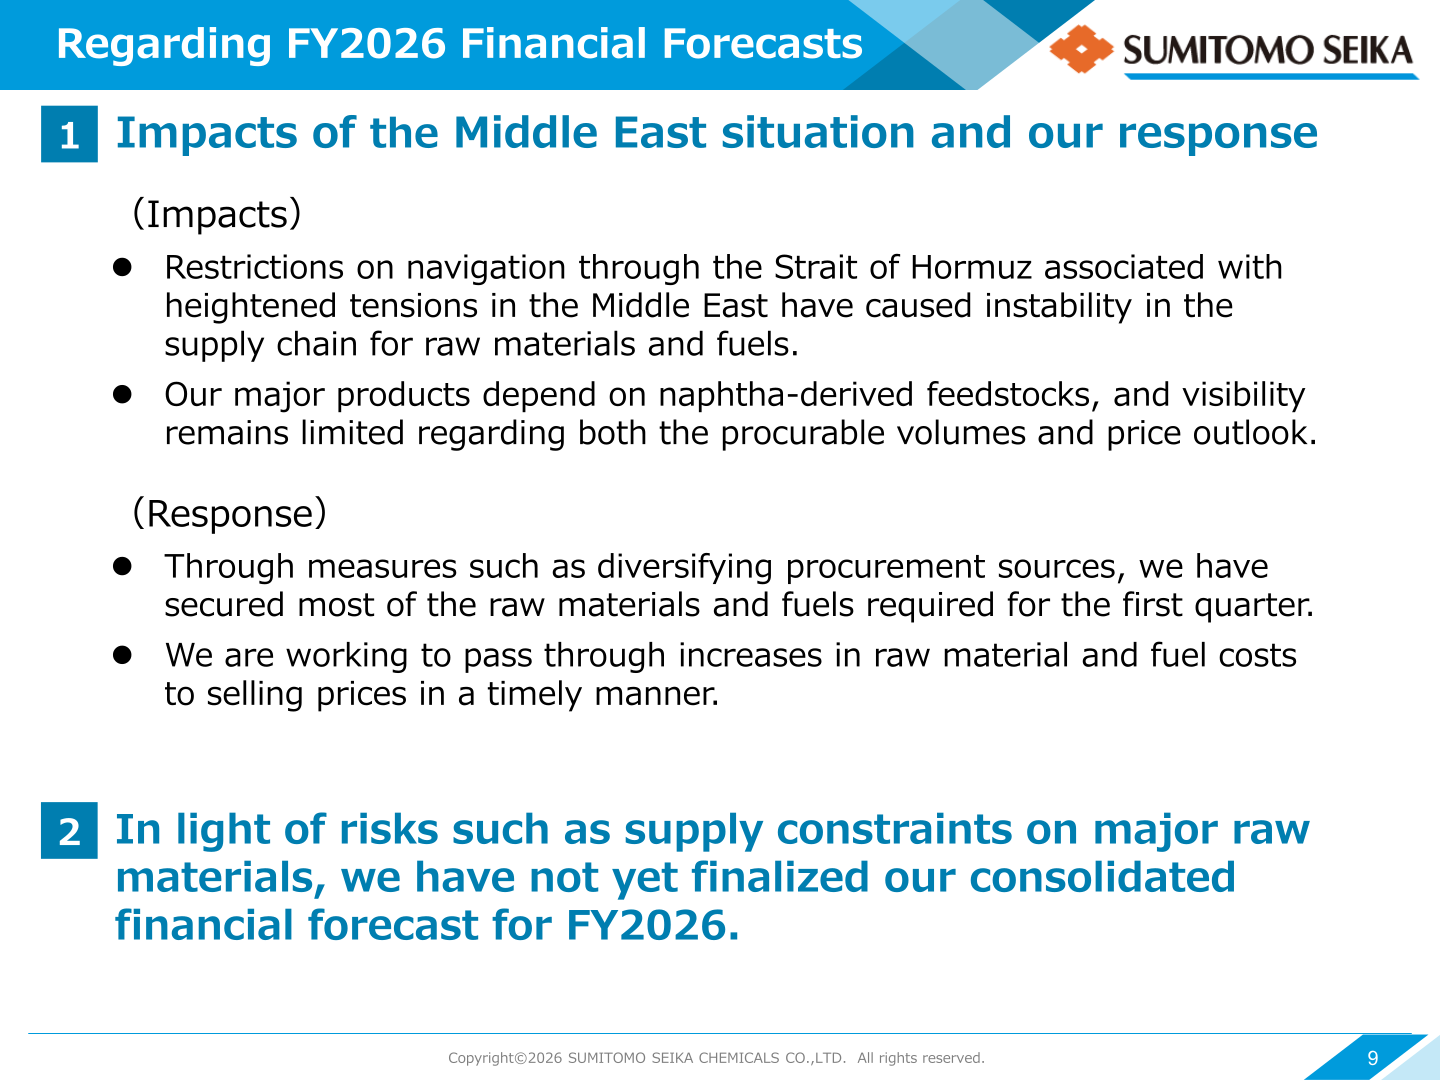
Restrictions on navigation through the Strait of Hormuz associated with heightened tensions in the Middle East have caused instability in the supply chain for raw materials and fuels. The company’s major products depend on naphtha-derived feedstocks, and visibility remains limited regarding both procurable volumes and the price outlook. In light of risks such as supply constraints on major raw materials, the company has not yet finalized its consolidated financial forecast for FY2026. In response, through measures such as diversifying procurement sources, it has secured most of the raw materials and fuels required for the first quarter, and it is working to pass through increases in raw material and fuel costs to selling prices in a timely manner.
By segment, the company describes the following outlook for FY2026. In SAP, global sales volume is expected to increase by approximately 4% compared with the previous year owing to the facility enhancement in Singapore, and sales volume in China by approximately 5%, with steady sales expected assuming no raw material supply constraints. The new Singapore facilities (production capacity of 70,000t/year; invested amount of approx. 160 million USD) were completed in January 2026 and have operated at full capacity since March, bringing capacity in Singapore to 140,000t/year and the Group total to 520,000t/year. For customers to whom the price formula is not applied (mostly local customers in China and other Asian countries), increases in raw material and fuel costs are passed through to selling prices in a timely manner, while for customers to whom the formula is applied (approx. 50% of the total), they are gradually reflected in line with the timing of contract price revisions. In Functional Materials, sales of electronics gases are expected to increase by approximately 6% year on year in FY2026.
Shareholder Returns
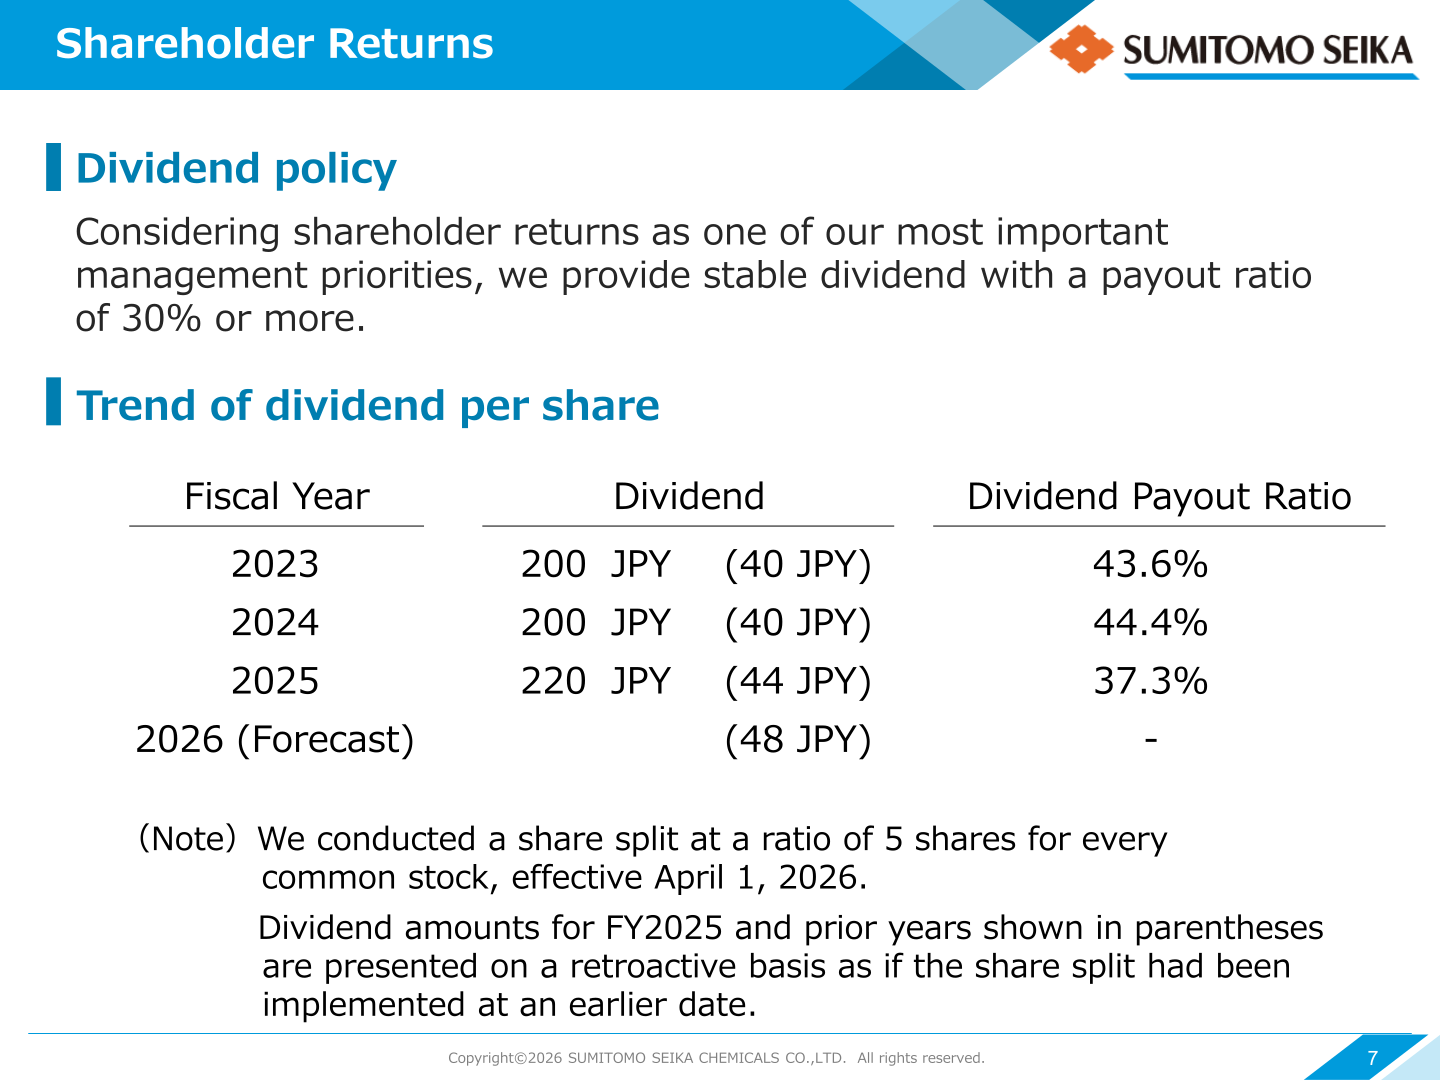
Considering shareholder returns as one of its most important management priorities, the company provides a stable dividend with a payout ratio of 30% or more. The FY2025 dividend was 220 JPY per share (44 JPY on a post-split basis), with a dividend payout ratio of 37.3%, and the FY2026 dividend forecast is 48 JPY. The company conducted a 5-for-1 share split of its common stock effective April 1, 2026; the amounts in parentheses below are presented on a retroactive basis as if the split had been implemented at an earlier date.
| Fiscal Year | Dividend per Share | (Post-Split Basis) | Dividend Payout Ratio |
|---|---|---|---|
| 2023 | 200 JPY | (40 JPY) | 43.6% |
| 2024 | 200 JPY | (40 JPY) | 44.4% |
| 2025 | 220 JPY | (44 JPY) | 37.3% |
| 2026 (Forecast) | (48 JPY) | – |
In FY2025, the company acquired 1 billion JPY of treasury shares, bringing the total payout ratio to 50.3%; the three-year average (FY2023–2025) total payout ratio was 56%. It cancelled 5,275,195 treasury shares on May 26, 2026 (7.54% of issued shares prior to the cancellation). In addition, the company has set out an acquisition of treasury shares of up to 840,000 shares or 1 billion JPY (upper limit) from May 13 to September 30, 2026, with all acquired shares to be cancelled (scheduled cancellation date: October 30, 2026).
Topics: Streamlining, Sustainability and R&D
The company achieved cost savings of approximately 2.1 billion JPY on a three-year cumulative basis (FY2023–2025) and, as supply capacity increased with the start-up of new facilities, implemented streamlining work for existing facilities; it is considering further streamlining measures targeting benefits of approximately 2 billion JPY. In the South Asian (Indian) market, where demand for disposable diapers for infants is expanding, it expects SAP sales volumes to increase by developing and supplying SAP aligned with the specific needs of each region or customer. Sales volumes of SAP to China account for more than 30% of the Group’s total SAP sales volumes.
On sustainability, the company’s GHG reduction plan obtained SBTi validation, it was recognized on the CDP 2025 “A List” in both Climate Change and Water Security and selected as a Supplier Engagement Leader, and it secured a Sustainability Linked Loan with proceeds allocated to capacity expansion investments in Singapore. In R&D, it is developing horizontal chemical recycling technology for SAP separated from used disposable diapers and constructing a pilot facility at Himeji Works; developing a new SAP product that can reduce SAP usage by approximately 20%, with a targeted launch in FY2026; and developing low-concentration CO₂ separation and recovery technology using PSA methods. The new research building “SEIKA R&D Center” (total floor area of 4000㎡) was completed at Befu Works.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















