
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: GMO GlobalSign Holdings K.K. does not publish an English results presentation (its English-language materials are machine translations, with the Japanese version being authoritative); this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials (the results briefing materials for the most recent full fiscal year), with figures transcribed as reported. The company’s fiscal year ends in December; following this site’s convention, the fiscal year ended December 2025 is classified as FY2025, while the body text and tables below keep the company’s own labels (FY12/2025 = fiscal year ended December 2025; FY12/2026 = fiscal year ending December 2026).
For FY12/2025 (full year), GMO GlobalSign Holdings reported net sales of 20,670 million yen (+7.9% year on year), operating profit of 1,475 million yen (+18.3% year on year), ordinary profit of 1,435 million yen (+10.6% year on year) and net income attributable to owners of the parent of 1,005 million yen (+17.6% year on year). According to the materials, both net sales and operating profit reached record highs. Sales increased mainly in the Digital Certificate and eSignature business, and operating profit rose substantially, helped in part by more efficient management of SG&A expenses. Both sales and profits achieved the full-year earnings forecast, and the company decided to increase its dividend.
Consolidated Results (FY12/2025 Actual)
According to the FY2025 full-year results summary, net sales were 20,670 million yen (+7.9% year on year), operating profit was 1,475 million yen (+18.3% year on year), ordinary profit was 1,435 million yen (+10.6% year on year), net income attributable to owners of the parent was 1,005 million yen (+17.6% year on year) and EBITDA (the sum of operating profit and depreciation) was 2,236 million yen (+9.8% year on year). Achievement rates against the full-year earnings forecast were 101.3% for net sales, 102.8% for operating profit, 100.9% for ordinary profit and 114.2% for net income.
| Item (million yen) | FY12/2025 (Actual) | FY12/2024 (Actual) | YoY |
|---|---|---|---|
| Net sales | 20,670 | 19,166 | +7.9% |
| Operating profit | 1,475 | 1,246 | +18.3% |
| Ordinary profit | 1,435 | 1,297 | +10.6% |
| Net income attributable to owners of the parent | 1,005 | 854 | +17.6% |
| EBITDA | 2,236 | 2,037 | +9.8% |
Segment Results
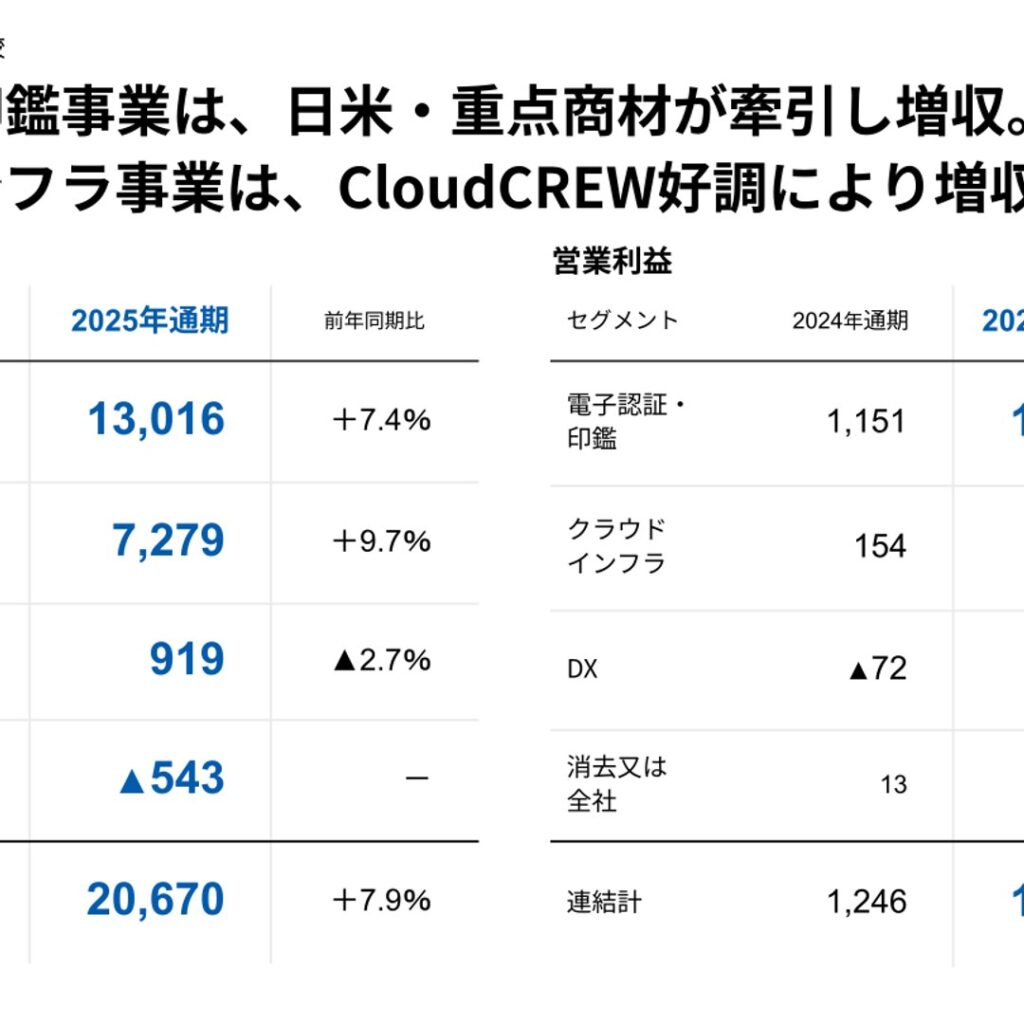
In the Digital Certificate and eSignature business, sales were strong, mainly in Japan and the United States, and Europe also recovered from the impact of the previous year’s revenue decline. The Cloud Infrastructure business posted higher sales and profits on the strength of its managed cloud service “CloudCREW byGMO.” In the DX business, the first-half timing slippage in the O2O app was resolved, but full-year sales declined. By segment, net sales were 13,016 million yen for Digital Certificate and eSignature (+7.4% year on year), 7,279 million yen for Cloud Infrastructure (+9.7% year on year) and 919 million yen for DX (▲2.7% year on year). Segment operating profit was 1,343 million yen for Digital Certificate and eSignature (+16.7% year on year), 194 million yen for Cloud Infrastructure (+25.7% year on year) and ▲89 million yen for DX.
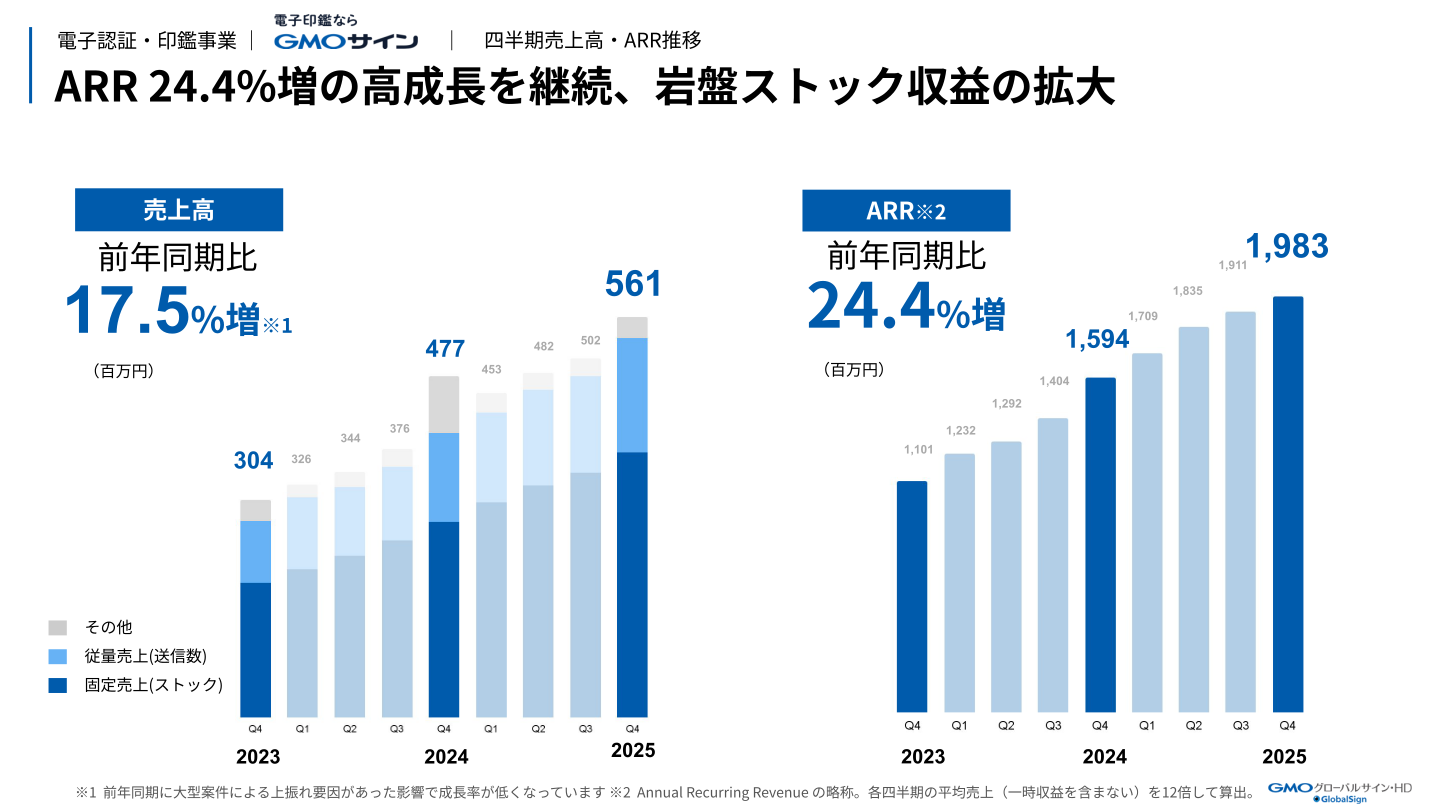
Among the key products, full-year sales of the GMO Sign electronic signature service rose 31.3% year on year, and full-year sales of the login authentication enhancement service (GMO Trust Login) rose 33.3% year on year (full-year sales year-on-year comparisons as stated in the materials). ARR for GMO Sign (short for Annual Recurring Revenue; calculated by multiplying average quarterly sales, excluding one-time revenue, by 12) reached 1,983 million yen as of Q4 2025, up 24.4% year on year. The number of contracts sent (the cumulative number of contracts sent with electronic signatures and time stamps under the Act on Electronic Signatures, aggregated quarterly for the main witness-type electronic signature services, excluding time-stamp-only contracts) was +20.8% year on year.
| Segment (million yen) | Net sales (Current) | Net sales (Prior) | Operating profit (Current) | Operating profit (Prior) |
|---|---|---|---|---|
| Digital Certificate and eSignature | 13,016 | 12,120 | 1,343 | 1,151 |
| Cloud Infrastructure | 7,279 | 6,634 | 194 | 154 |
| DX | 919 | 944 | ▲89 | ▲72 |
| Eliminations or corporate | ▲543 | ▲533 | 26 | 13 |
| Consolidated total | 20,670 | 19,166 | 1,475 | 1,246 |
Full-Year Forecast (FY12/2026)
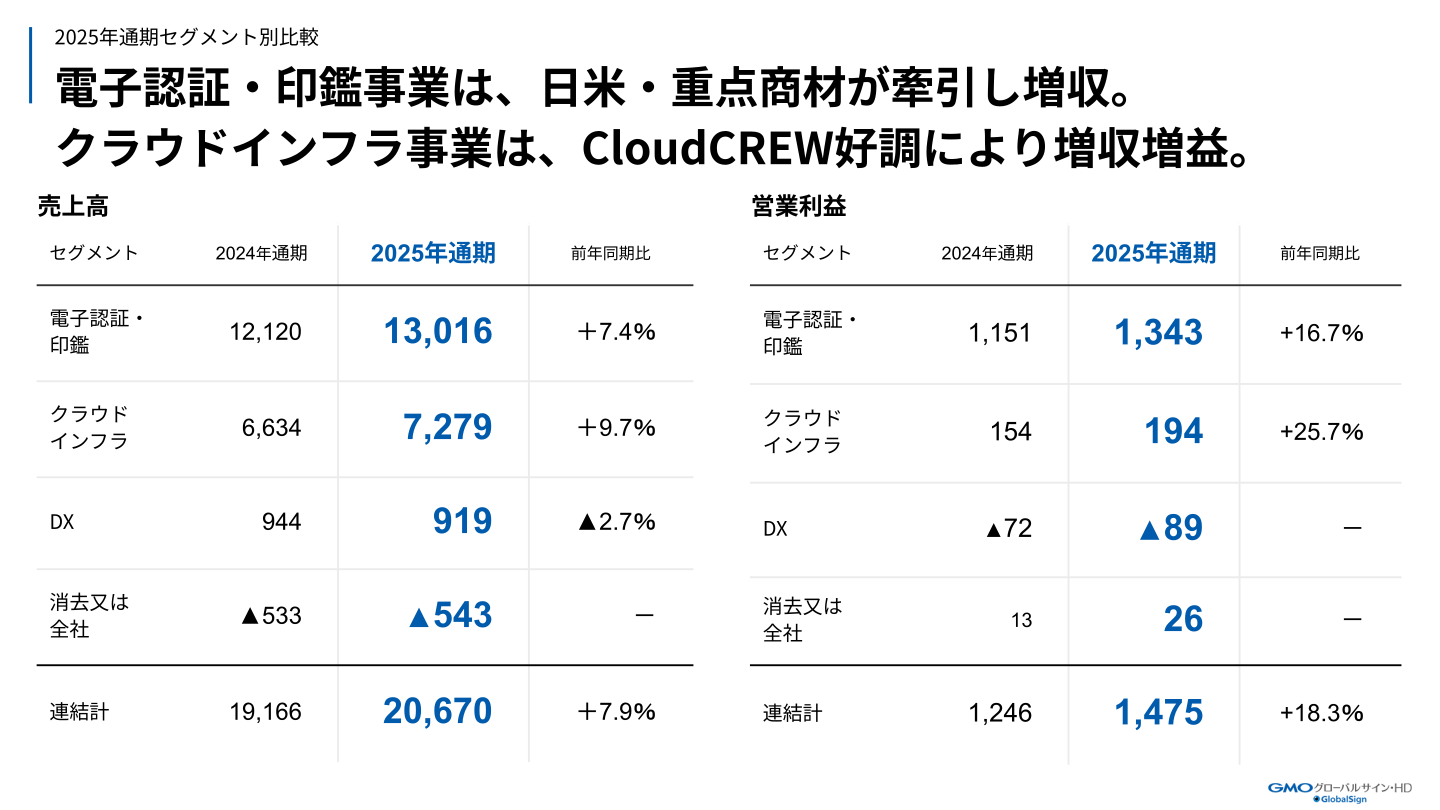
The full-year earnings forecast for FY12/2026 calls for net sales of 22,286 million yen (+7.8% versus 2025), operating profit of 1,622 million yen (+10.0%), ordinary profit of 1,589 million yen (+10.7%), net income attributable to owners of the parent of 1,052 million yen (+4.7%) and earnings per share of 91.79 yen (FY12/2025 actual: 87.55 yen). In the segment forecasts, Digital Certificate and eSignature is expected to post net sales of 14,353 million yen (+10.3% year on year) and operating profit of 1,612 million yen (+20.0%), Cloud Infrastructure net sales of 7,482 million yen (+2.8%), and DX net sales of 1,046 million yen (+13.8%) and operating profit of ▲48 million yen; the materials state that “the Cloud Infrastructure segment will see a temporary decline in profit due to the renewal of its services.”
| Item (million yen) | FY12/2026 (Forecast) | FY12/2025 (Actual) | YoY |
|---|---|---|---|
| Net sales | 22,286 | 20,670 | +7.8% |
| Operating profit | 1,622 | 1,475 | +10.0% |
| Ordinary profit | 1,589 | 1,435 | +10.7% |
| Net income attributable to owners of the parent | 1,052 | 1,005 | +4.7% |
| Earnings per share (yen) | 91.79 | 87.55 | – |
Shareholder Returns
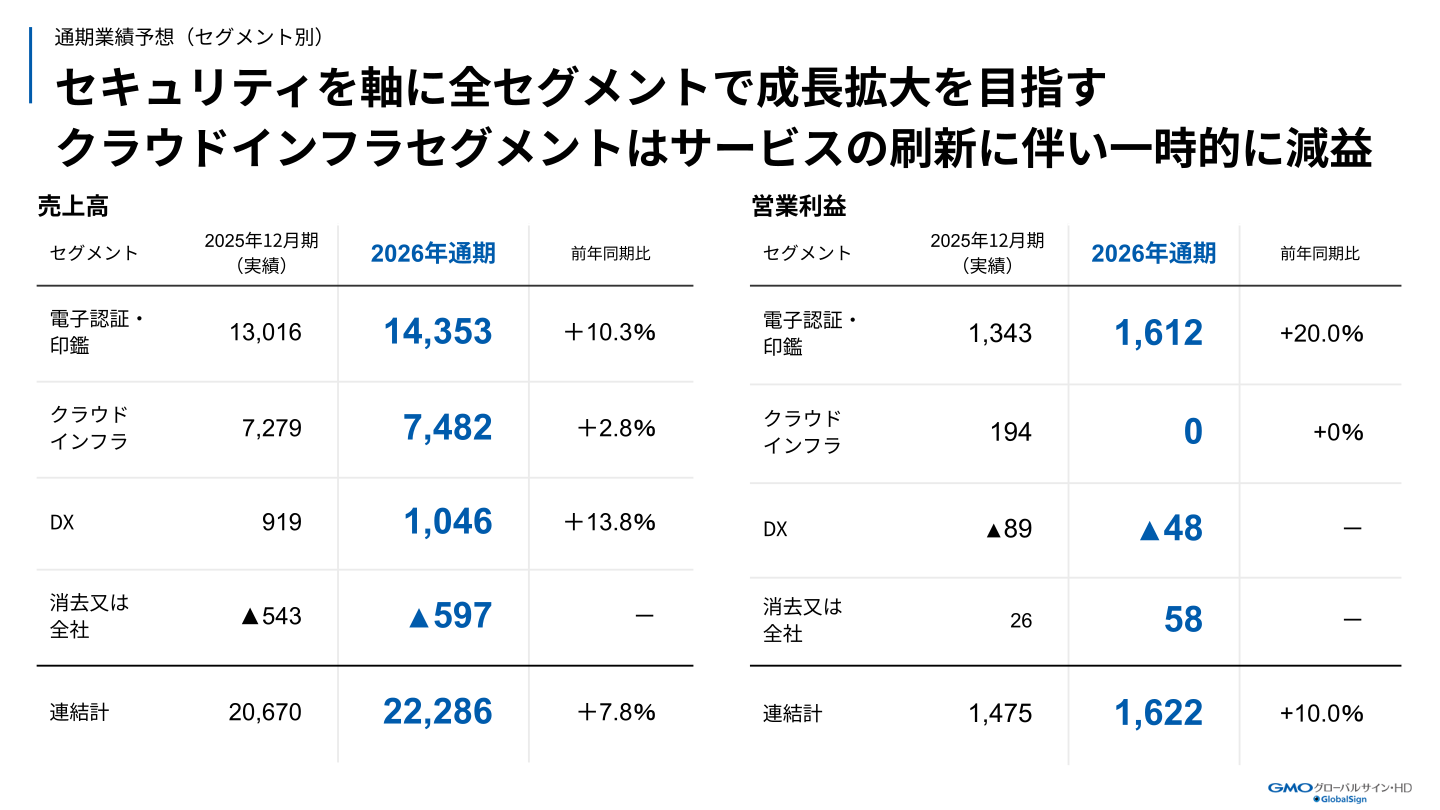
On shareholder returns, the company has additionally introduced a dividend on equity (DOE) standard to stabilize shareholder returns. Its policy is a dividend payout ratio of 65% or more, and the total return ratio was 65.0% for 2025 and is also 65.0% in the 2026 forecast. The company carried out a share buyback, with an acquisition period from November 17, 2025 to January 30, 2026. The materials state that the dividend forecast was revised upward.
| Year | Total dividends (million yen) | Share buybacks (million yen) | Total return ratio |
|---|---|---|---|
| 2022 | 450 | – | 53.1% |
| 2023 | 443 | – | 59.9% |
| 2024 | 427 | 100 | 61.7% |
| 2025 | 653 | – | 65.0% |
| 2026 (Forecast) | 787 | – | 65.0% |
Recurring Revenue from Key Products
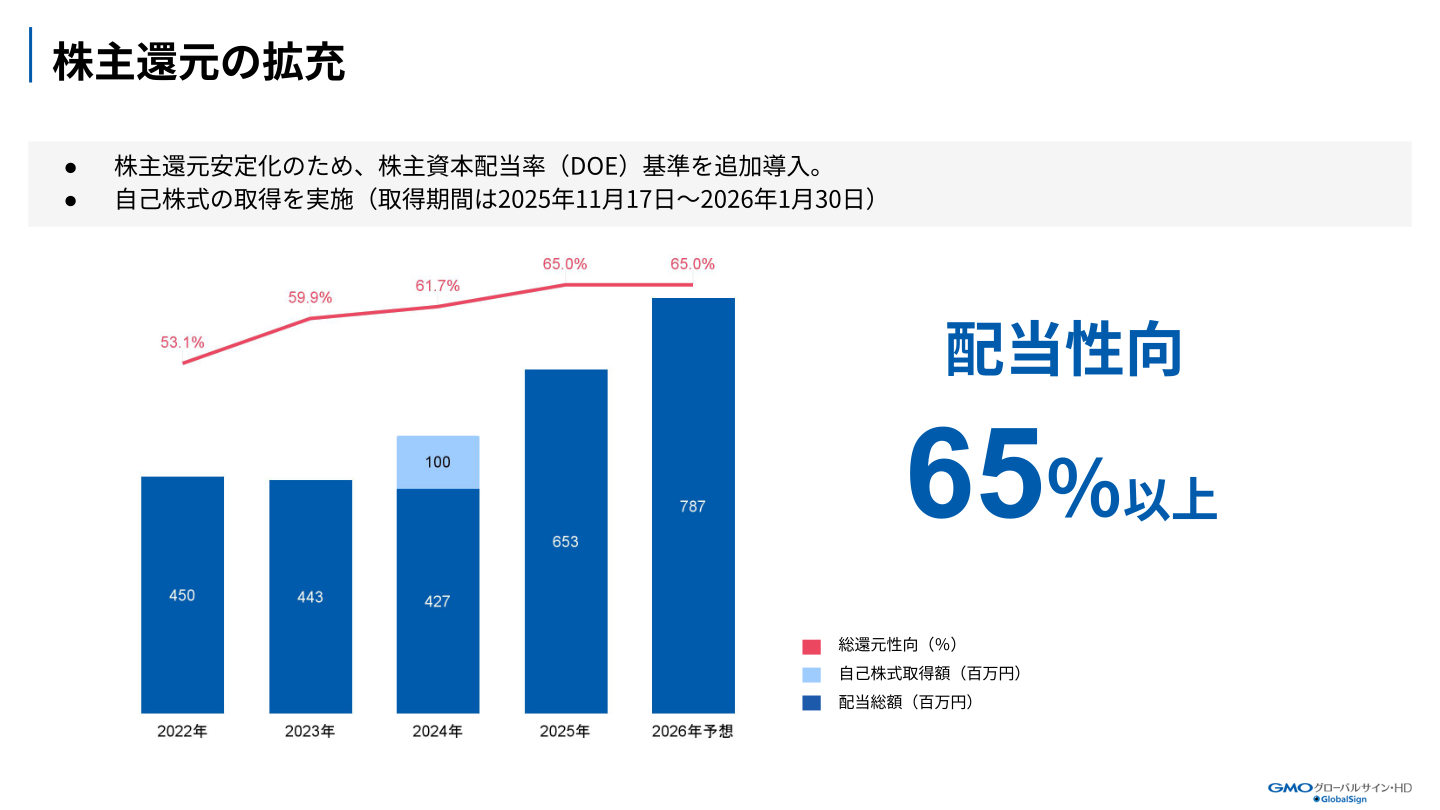
The materials describe “22 rock-solid recurring revenue streams supporting sustainable growth” and “25 consecutive years of revenue growth.” In the quarterly sales and ARR trend for the GMO Sign electronic signature service, ARR expanded from 1,101 million yen in Q4 2023 to 1,983 million yen in Q4 2025, up 24.4% year on year.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















