
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Ateam Holdings Co., Ltd. has a July fiscal year-end and labels the fiscal year covered here as “FY2026” (August 2025 – July 2026); on this site the most recently completed fiscal year is classified as FY2025, and the labels used in the text, tables and segment data below follow the company’s own materials (FY2026 = fiscal year ended July 2026, FY2027 = the current fiscal year).
Ateam Holdings, which operates Digital Marketing (comparison and information media, D2C and businesses acquired through M&A) and Entertainment (game apps) businesses, reported FY2026 revenue of 22,997 million JPY (Y/Y 96.2%) and Adjusted EBITDA of 1,100 million JPY (Y/Y 64.0%). The company attributes the decline in revenue and profit mainly to fiercer competition for customer acquisition in certain businesses, despite strong D2C performance. Ordinary income fell to 584 million JPY (Y/Y 36.8%), which the company describes as a substantial decrease due to the significant impact of fluctuations in the market price of crypto assets. For FY2027 the company forecasts revenue of 24,000 million JPY and Adjusted EBITDA of 1,200 million JPY, with an annual dividend of 28.0 JPY per share.
Consolidated Results (Full-Year Actual)
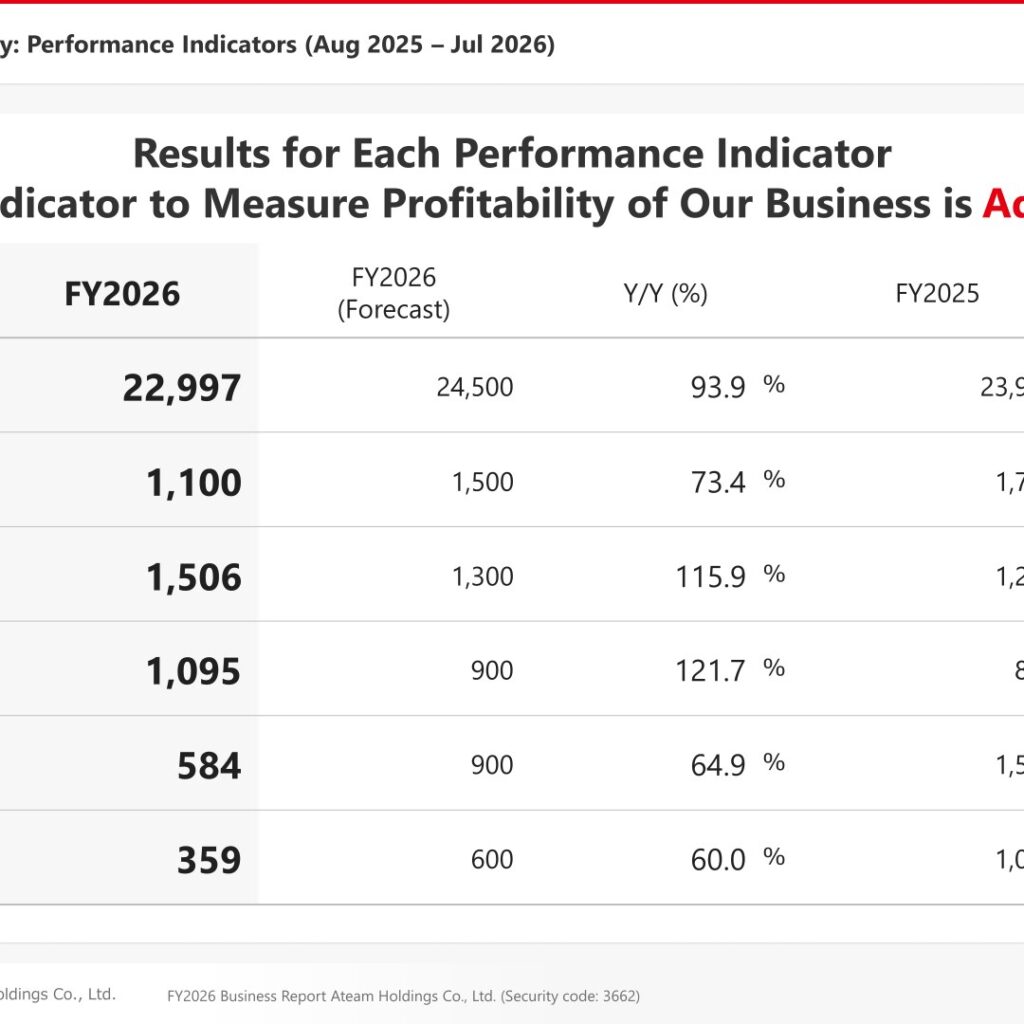
Ateam treats Adjusted EBITDA as the appropriate indicator to measure the profitability of its business. Against the FY2026 forecast, revenue achieved 93.9%, Adjusted EBITDA 73.4%, ordinary income 64.9% and net income 60.0%. Operating income rose to 1,095 million JPY from 845 million JPY in FY2025, and EBITDA rose to 1,506 million JPY from 1,273 million JPY.
| Item (million JPY) | FY2026 | FY2026 (Forecast) | FY2025 | Y/Y (%) |
|---|---|---|---|---|
| Revenue | 22,997 | 24,500 | 23,917 | 96.2% |
| Adjusted EBITDA | 1,100 | 1,500 | 1,719 | 64.0% |
| EBITDA | 1,506 | 1,300 | 1,273 | 118.3% |
| Operating Income | 1,095 | 900 | 845 | 129.6% |
| Ordinary Income | 584 | 900 | 1,585 | 36.8% |
| Net Income | 359 | 600 | 1,036 | 34.7% |
The company explains that ordinary income decreased due to valuation losses resulting from declining market prices of crypto assets held by Paddle, its crypto asset point app subsidiary. According to the materials, the Bitcoin market price declined substantially from approx. 17 million JPY at the end of July 2025 to approx. 9 million JPY at the end of July 2026. Gains on sale of shares in affiliates of approx. 153 million JPY, resulting from the sale of shares in Ateam Finergy Inc., were recorded as extraordinary income in FY2026 Q1.
In FY2026 Q4 (May – July 2026), revenue was 5,754 million JPY (Y/Y 96.7%, Q/Q 97.1%) and Adjusted EBITDA was 322 million JPY (Y/Y 105.2%, Q/Q 122.8%), with the company noting that the D2C business supported profit despite the impact of decreased revenue in certain existing businesses.
Segment Results
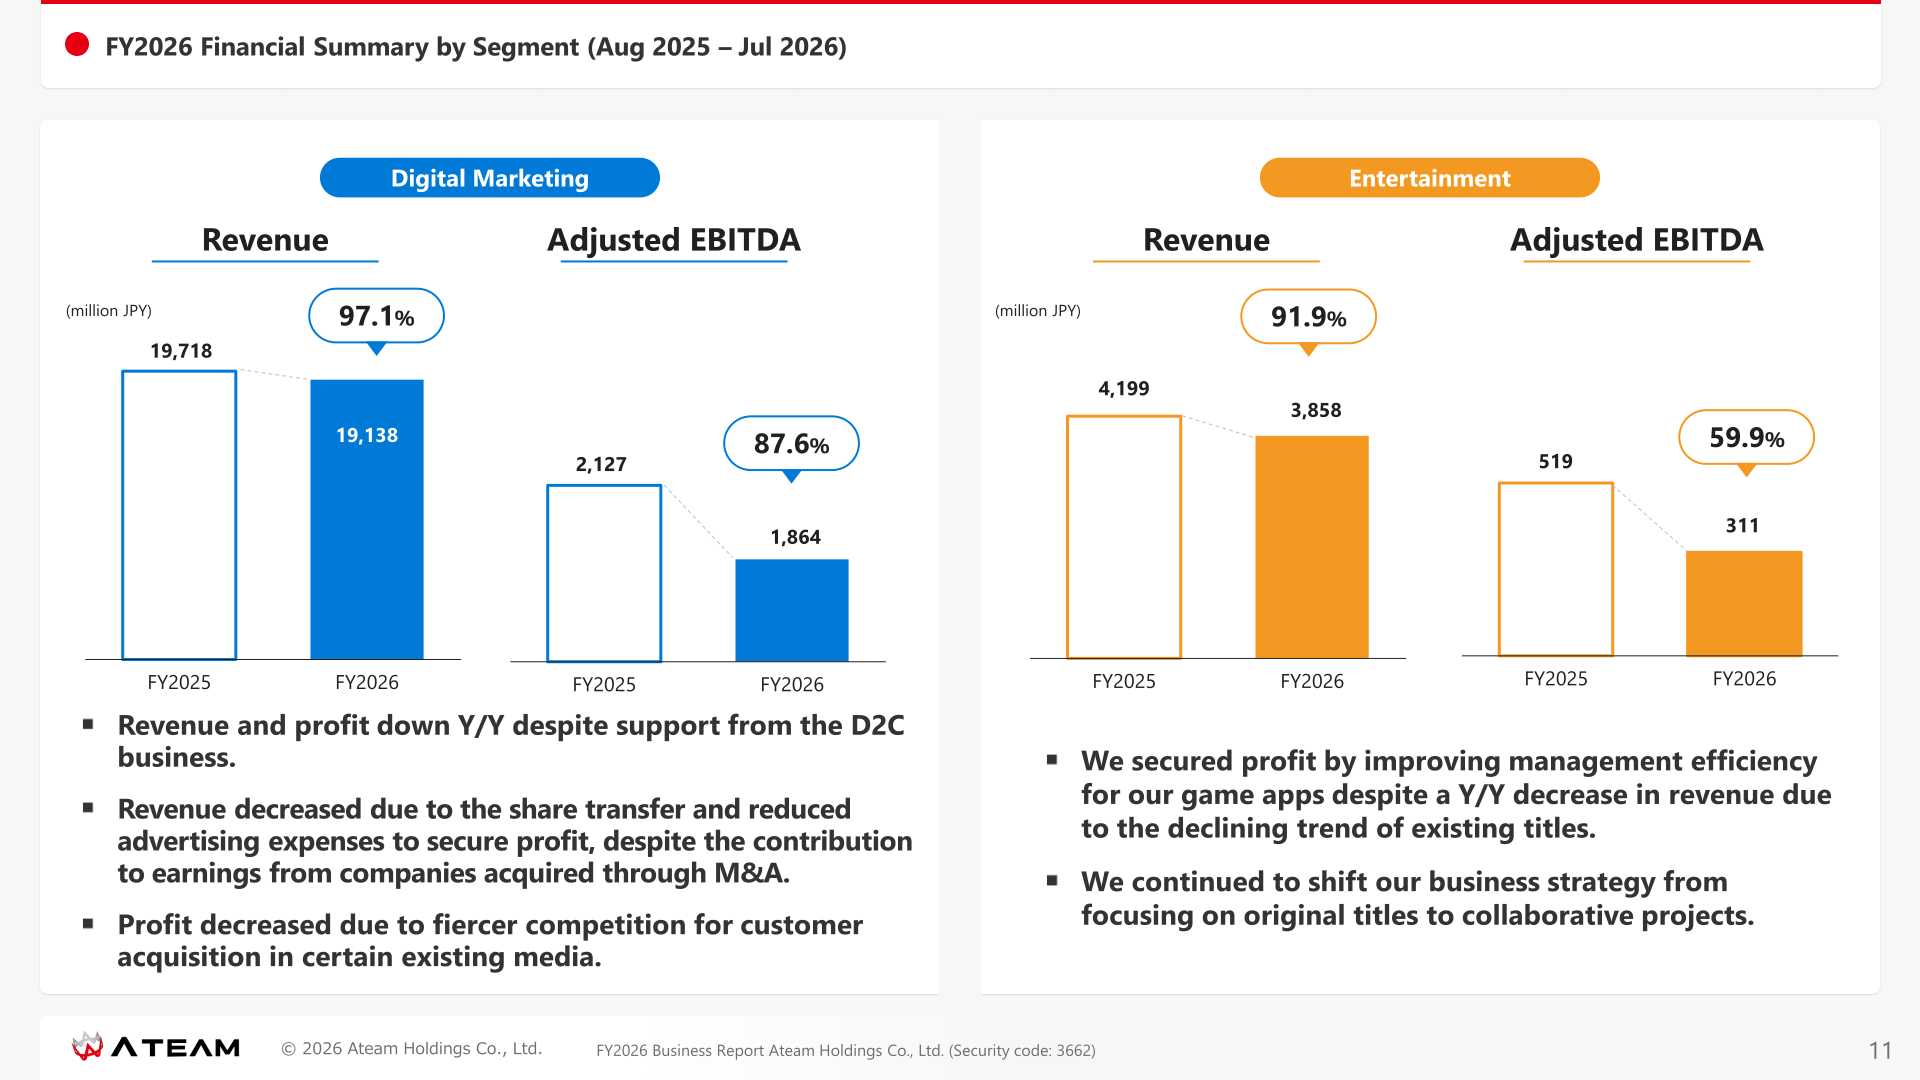
Digital Marketing: revenue was 19,138 million JPY (97.1% of FY2025) and Adjusted EBITDA was 1,864 million JPY (87.6%). Revenue decreased due to the share transfer and reduced advertising expenses to secure profit, despite the contribution to earnings from companies acquired through M&A, while profit decreased due to fiercer competition for customer acquisition in certain existing media. Revenue from the five companies acquired through M&A accounted for 10% of the segment’s revenue in FY2026 Q4.
Entertainment: revenue was 3,858 million JPY (91.9%) and Adjusted EBITDA was 311 million JPY (59.9%). The company secured profit by improving management efficiency for its game apps despite a Y/Y decrease in revenue due to the declining trend of existing titles, and continued to shift its business strategy from original titles to collaborative projects.
| Segment | Metric (million JPY) | FY2026 | FY2025 |
|---|---|---|---|
| Digital Marketing | Revenue | 19,138 | 19,718 |
| Digital Marketing | Adjusted EBITDA | 1,864 | 2,127 |
| Digital Marketing | Operating income | 1,931 | 1,334 |
| Entertainment | Revenue | 3,858 | 4,199 |
| Entertainment | Adjusted EBITDA | 311 | 519 |
| Entertainment | Operating income | 309 | 518 |
FY2027 Forecast
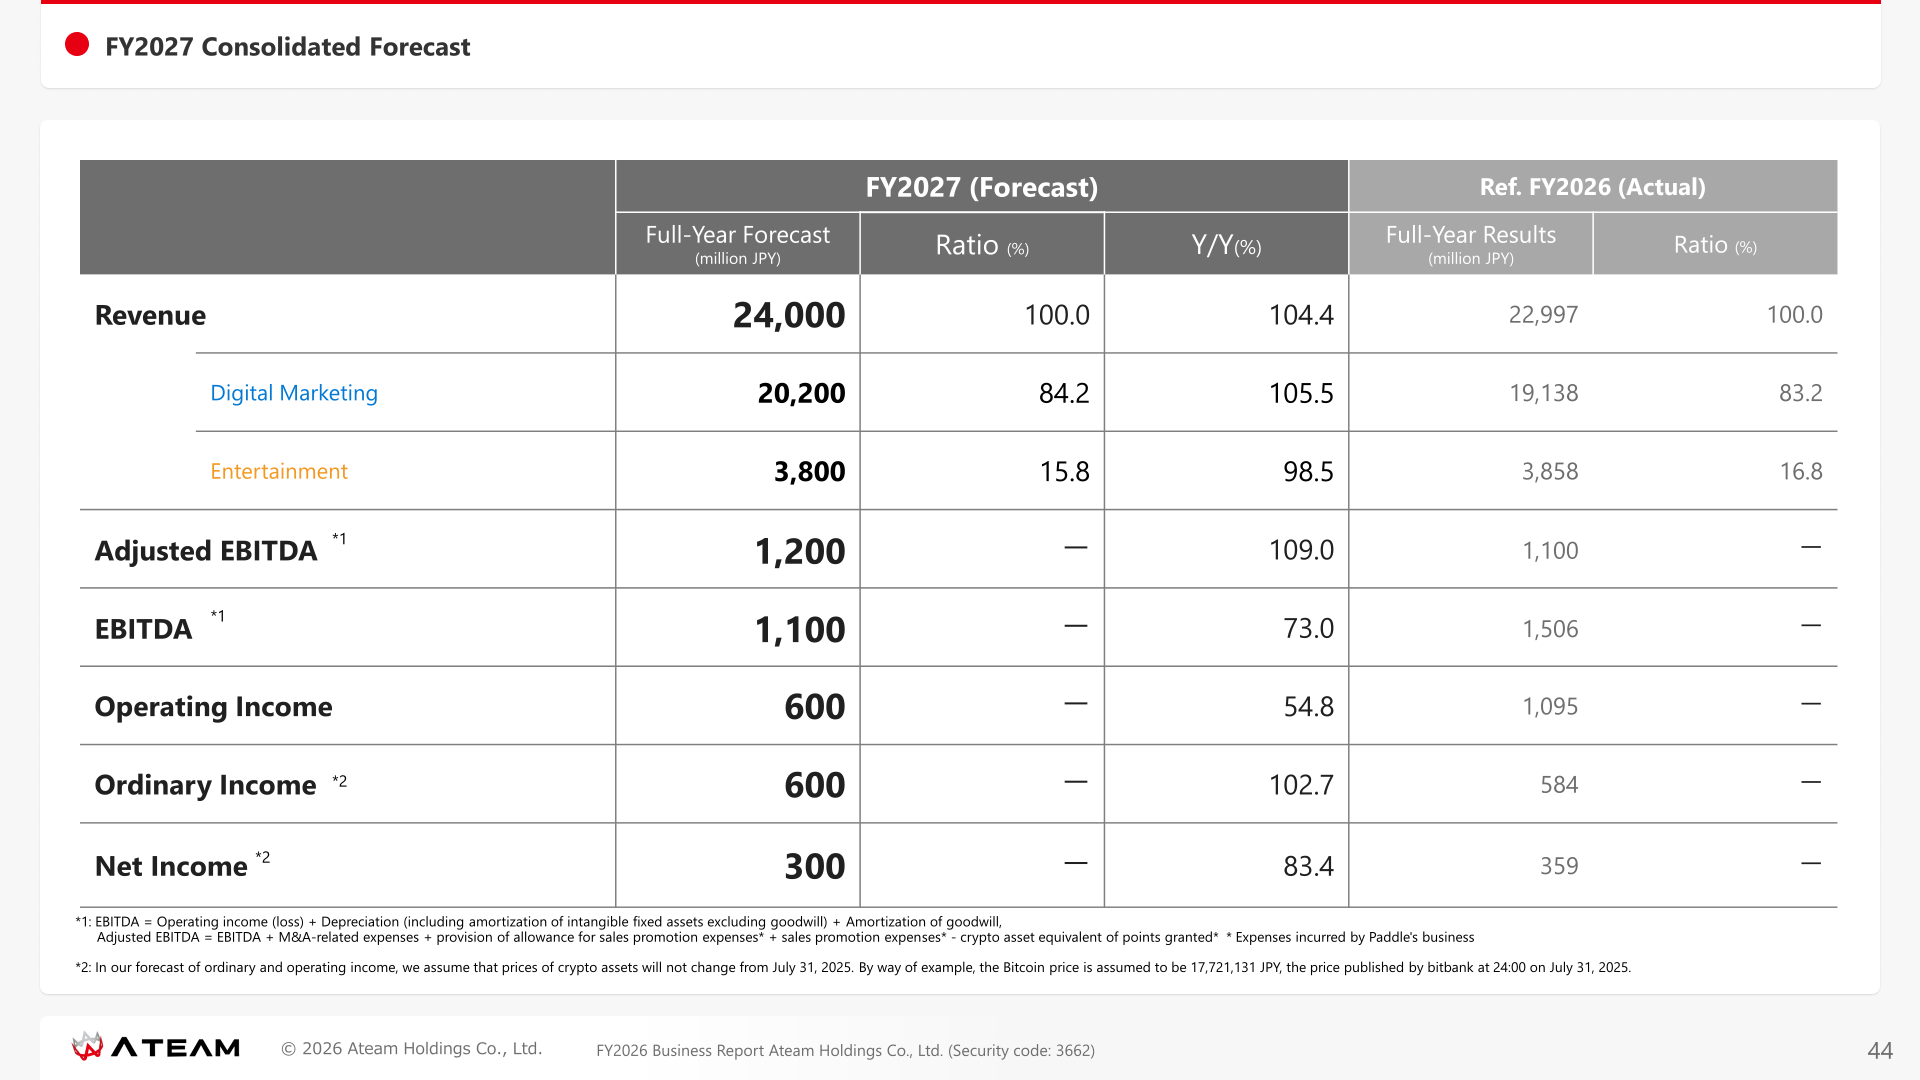
For FY2027 the company forecasts revenue of 24,000 million JPY (Y/Y 104.4%) and Adjusted EBITDA of 1,200 million JPY (Y/Y 109.0%). The forecast is weighted toward the second half because Q3 is the busiest period for the major existing media. The company plans to invest approximately 6.7 billion JPY in M&A over the remaining two years of the Medium-Term Business Plan, but the forecast does not reflect the impact of M&A because it is difficult to predict. It also assumes crypto asset prices will not fluctuate from their levels at the end of July 2026 and does not reflect provision of allowance for sales promotion expenses or gains/losses on the valuation of crypto assets.
| Item (million JPY) | FY2027 (Forecast) | Y/Y (%) | FY2026 (Actual) |
|---|---|---|---|
| Revenue | 24,000 | 104.4 | 22,997 |
| Digital Marketing | 20,200 | 105.5 | 19,138 |
| Entertainment | 3,800 | 98.5 | 3,858 |
| Adjusted EBITDA | 1,200 | 109.0 | 1,100 |
| EBITDA | 1,100 | 73.0 | 1,506 |
| Operating Income | 600 | 54.8 | 1,095 |
| Ordinary Income | 600 | 102.7 | 584 |
| Net Income | 300 | 83.4 | 359 |
Shareholder Returns
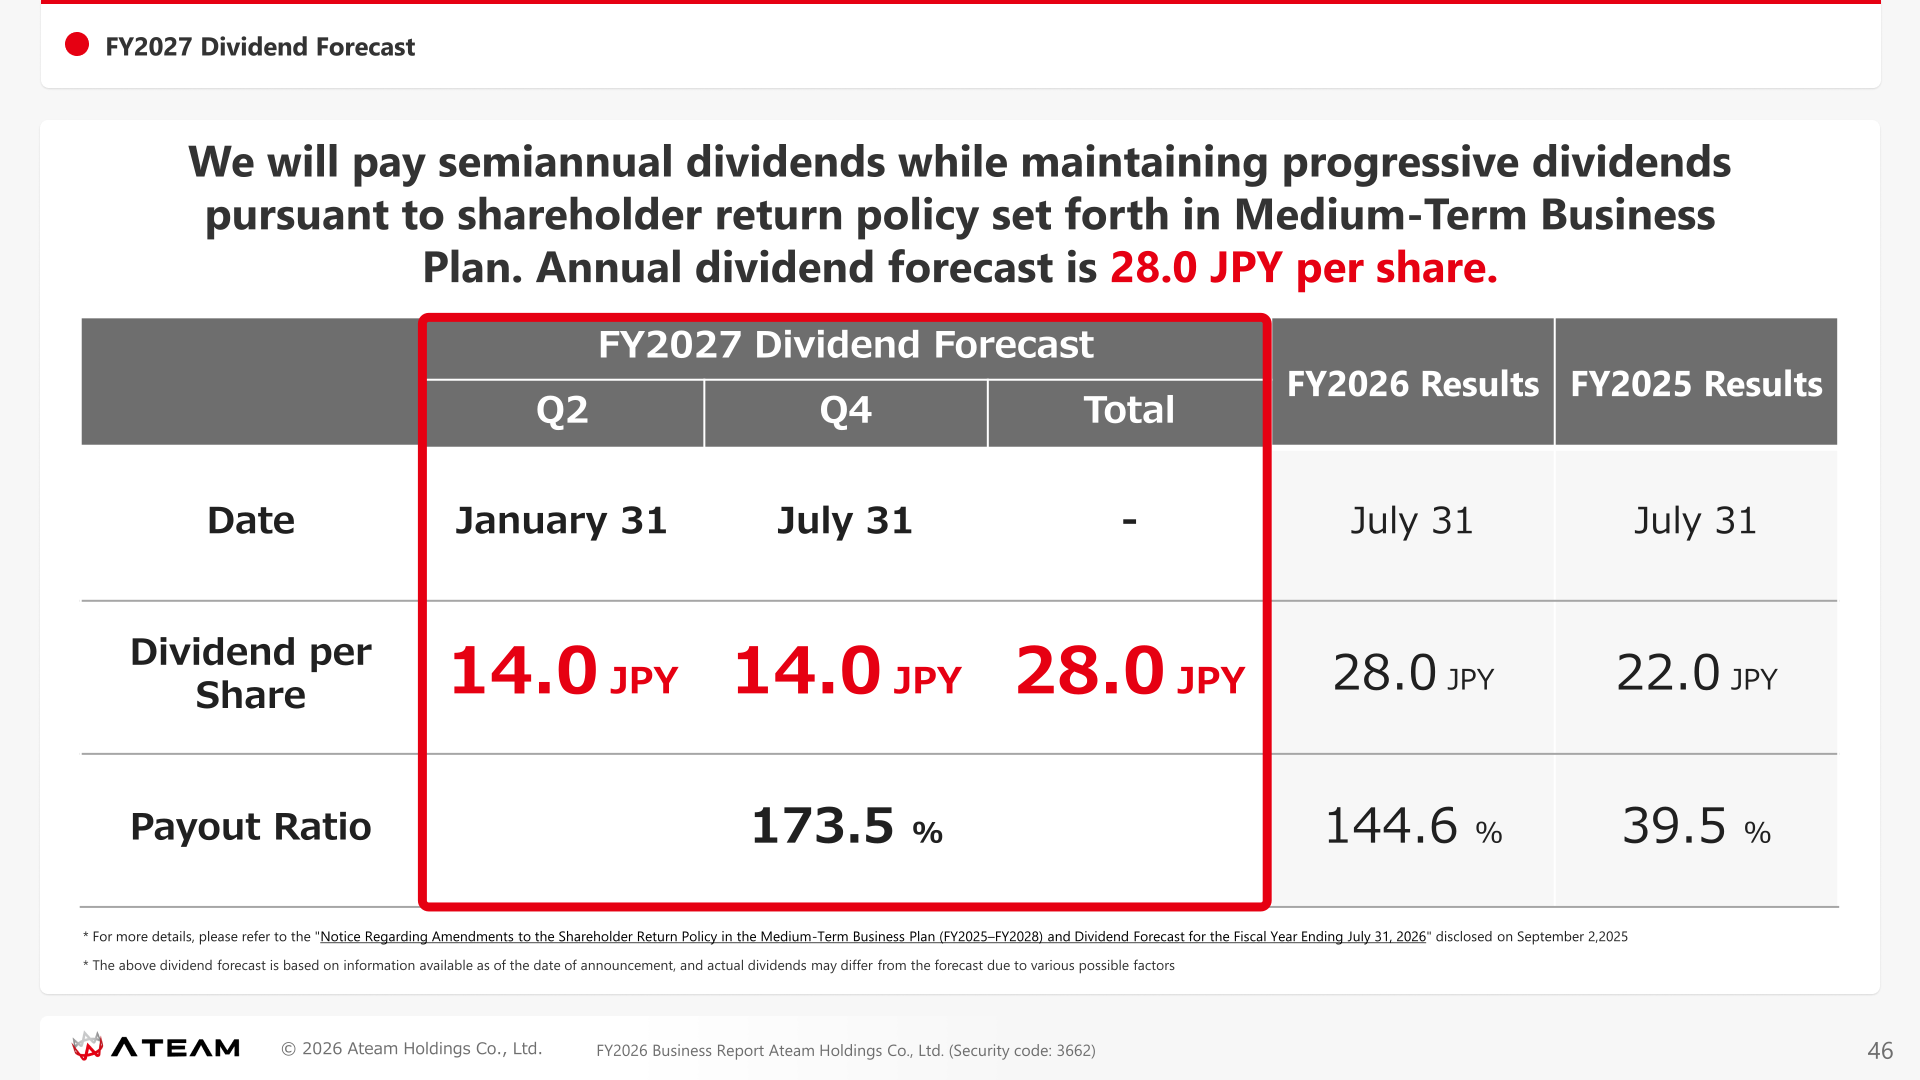
The FY2026 annual dividend was 28.0 JPY per share (including an interim dividend of 14.0 JPY), up from 22.0 JPY in FY2025, for a payout ratio of 144.6%. For FY2027 the company plans semiannual dividends of 14.0 JPY at Q2 and 14.0 JPY at Q4, for an annual dividend forecast of 28.0 JPY per share and a payout ratio of 173.5%, while maintaining progressive dividends pursuant to the shareholder return policy in the Medium-Term Business Plan.
| Dividend per Share | FY2027 (Forecast) | FY2026 (Results) | FY2025 (Results) |
|---|---|---|---|
| Annual | 28.0 JPY | 28.0 JPY | 22.0 JPY |
| Of which interim (Q2) | 14.0 JPY | 14.00 JPY | 0.00 JPY |
| Payout Ratio | 173.5% | 144.6% | 39.5% |
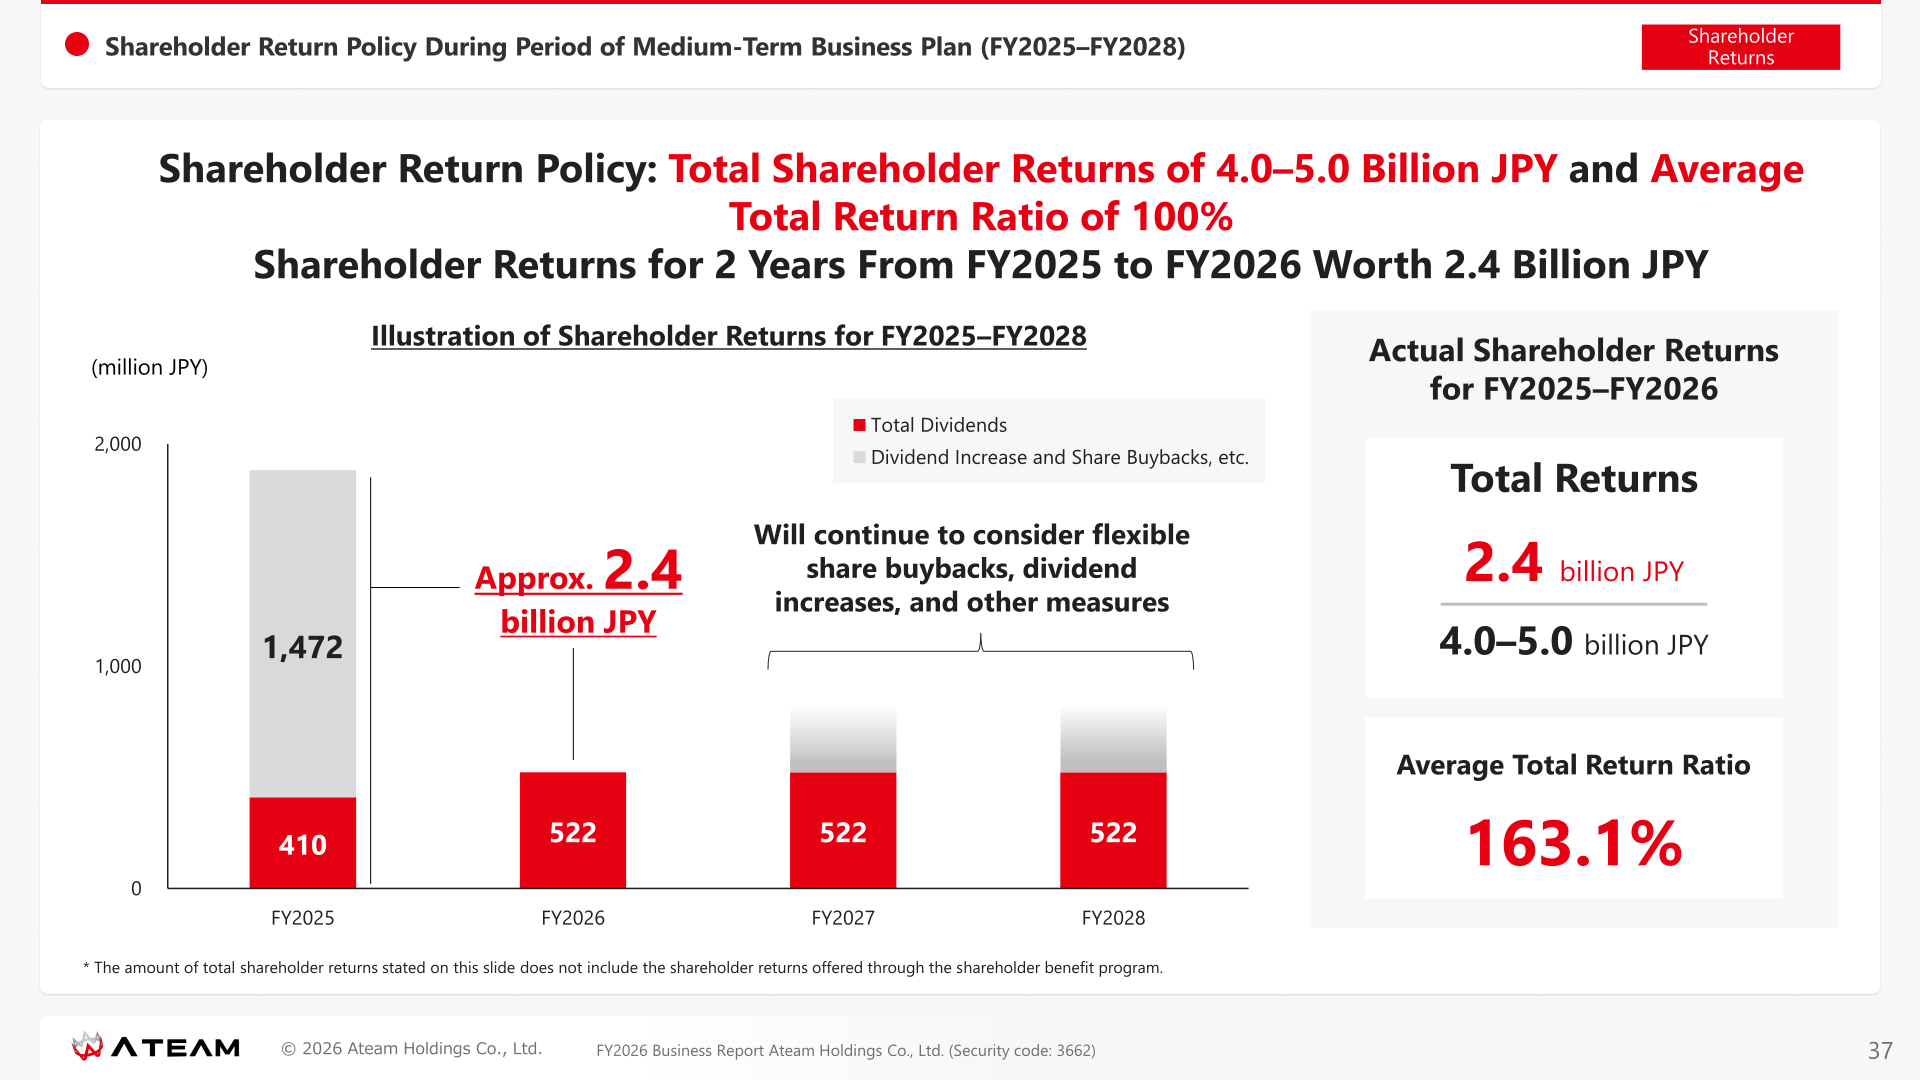
Under the Medium-Term Business Plan (FY2025–FY2028), the shareholder return policy targets total shareholder returns of 4.0–5.0 billion JPY and an average total return ratio of 100%. Shareholder returns for the two years from FY2025 to FY2026 were worth approx. 2.4 billion JPY, with an average total return ratio of 163.1%, and the company will continue to consider flexible share buybacks, dividend increases and other measures. It also operates a shareholder benefit program offering a QUO Card of 10,000 JPY at the end of January and the end of July each year (20,000 JPY annually) to holders of five units (500 shares) or more.
Medium-Term Business Plan and Future Initiatives
The Medium-Term Business Plan (FY2025–FY2028) targets revenue of 34 billion JPY, Adjusted EBITDA of 4.0 billion JPY and operating income of 2.0 billion JPY, with M&A investment of 10 billion JPY. By FY2026 the company had sourced 293 M&A opportunities, acquired five companies (microCMS, Paddle, WCA, Strainer and SiGNITY) with M&A investments totaling 3.3 billion JPY, and raised 1 billion JPY through borrowing to secure investment funds for M&A. It plans to invest 6.7 billion JPY over the remaining two years and has established an Investment Committee and an M&A Promotion Division to pursue disciplined investment.
Against the 4.0 billion JPY Adjusted EBITDA target for FY2028 (FY2026 results: 1.1 billion JPY), the company targets 2.0–2.5 billion JPY of earnings growth in existing businesses and 0.5–1.0 billion JPY of M&A-driven earnings growth. Among the acquired companies, microCMS’s MRR grew by 85% in the two years since acquisition, and Paddle’s revenue increased 54% in one year (FY2025 Q2 to FY2026 Q2). In existing businesses, the company sold “life.” and “NaviNavi Insurance,” launched Navikuru Assist and Hikkoshi Samurai Smart Comparison, and reports that its D2C brand lujo has sold over 2 million units in total.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















