
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
Note: Senshukai does not publish an English results presentation; this article is an English translation of the Japanese-language article on our sister site Investalk, which is based on the company’s Japanese-language IR materials, with figures transcribed as reported.
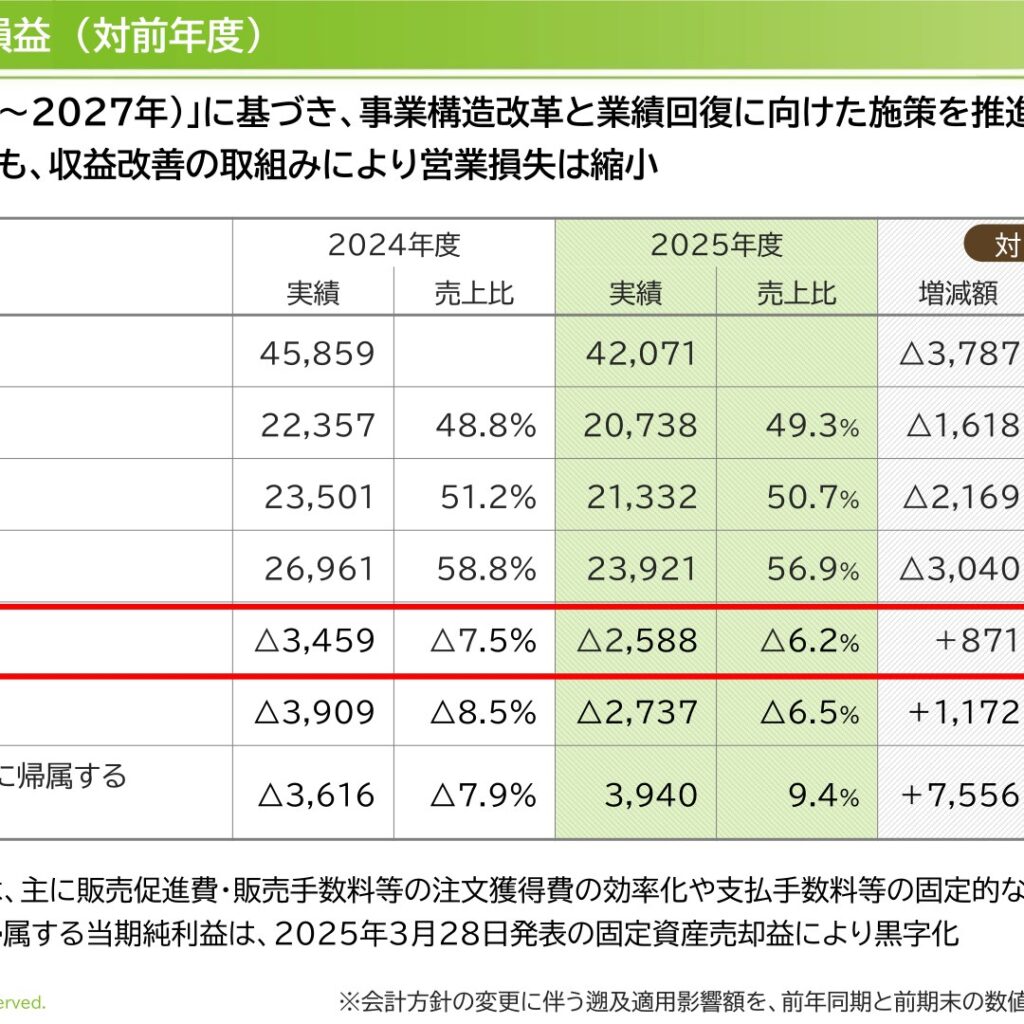
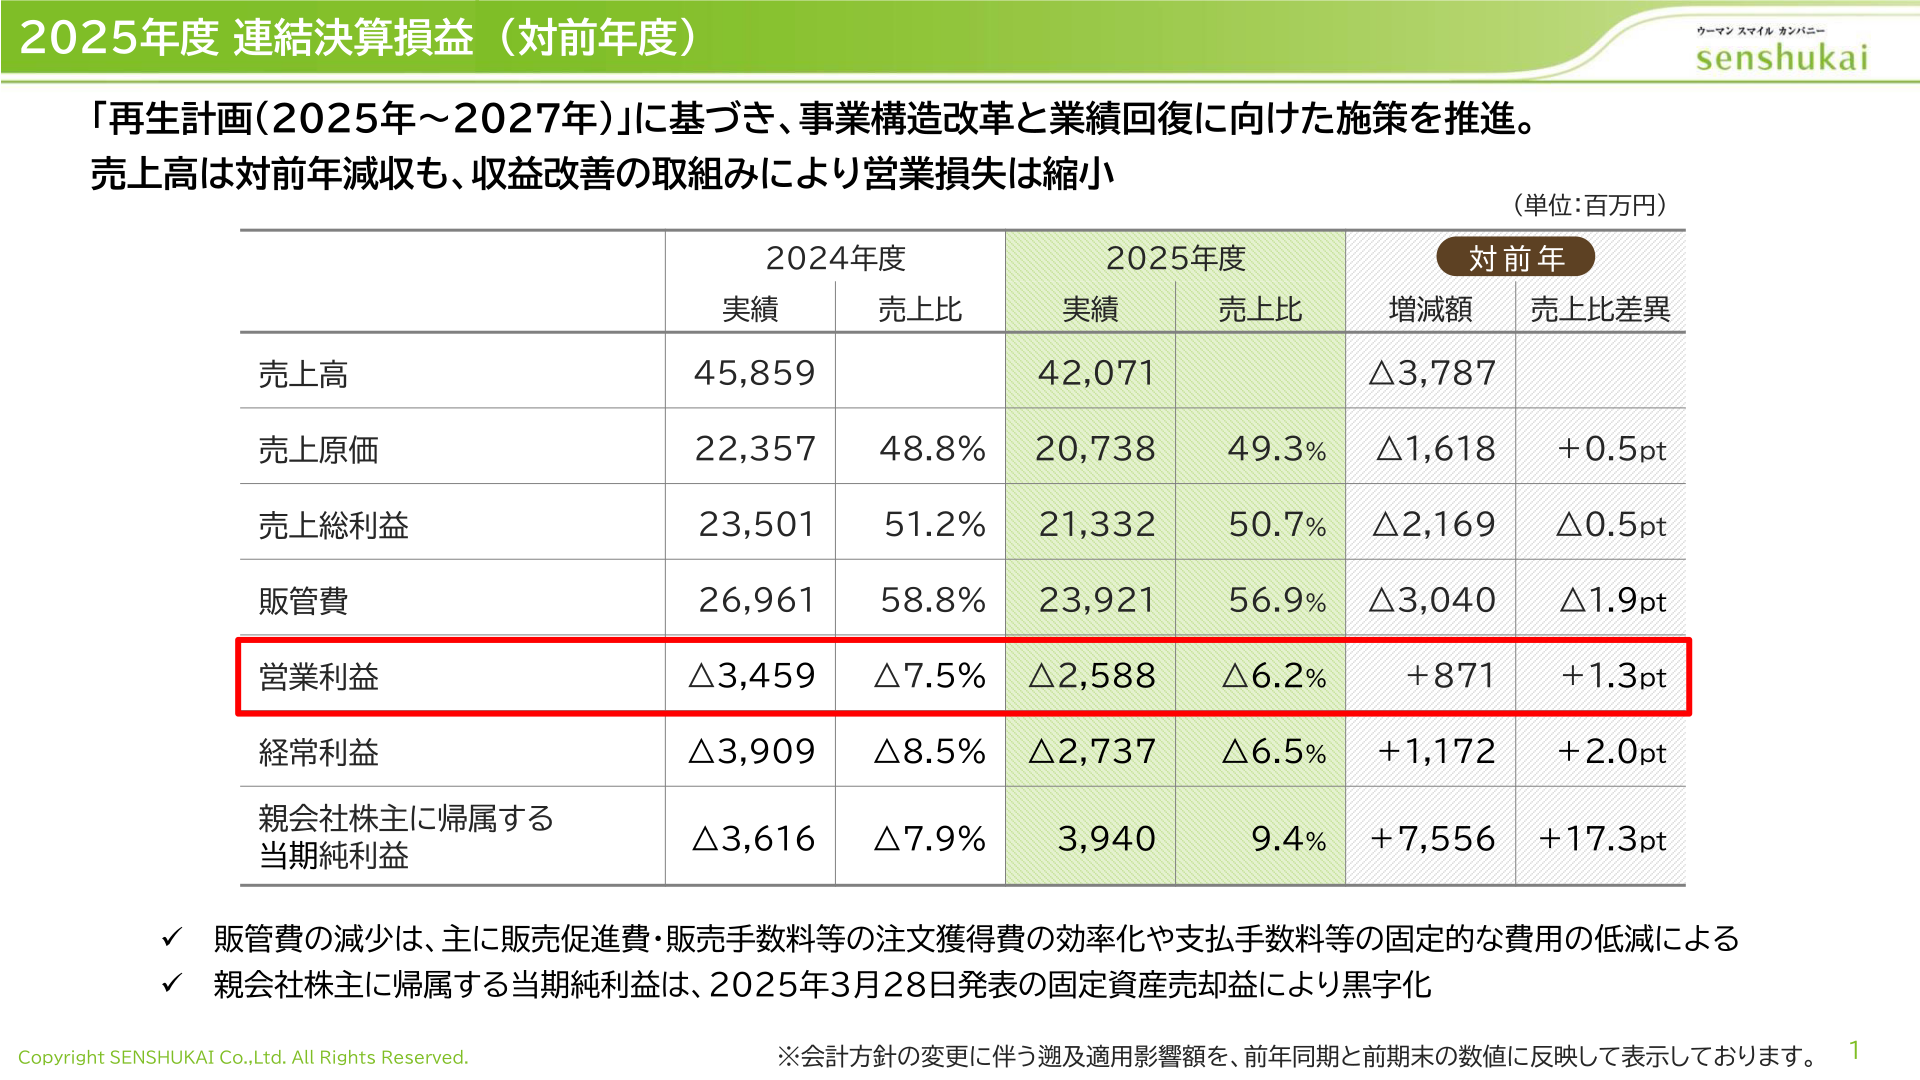
Senshukai Co., Ltd. (securities code: 8165, Tokyo Stock Exchange Standard Market) published its consolidated results presentation for the fiscal year ended December 31, 2025 (FY2025) on February 13, 2026. Under its “Revival Plan (2025-2027),” the company pursued business restructuring and profit-recovery measures. Consolidated net sales declined to ¥42,071 million (down ¥3,787 million year on year), but the operating loss narrowed to ¥2,588 million (versus a loss of ¥3,459 million in the previous year) on the back of profitability-improvement efforts. Profit attributable to owners of parent turned positive at ¥3,940 million, up from a loss of ¥3,616 million in the previous year, on the recognition of a gain on sale of fixed assets announced on March 28, 2025. Figures reflect the retrospective application of a change in accounting policy to the prior-year and prior fiscal year-end figures.
Consolidated Results (FY2025 Actual)
Net sales were ¥42,071 million, down ¥3,787 million year on year. Cost of sales was ¥20,738 million (49.3% of net sales, a 0.5-point deterioration year on year), and gross profit was ¥21,332 million (gross margin of 50.7%, down 0.5 point year on year). Selling, general and administrative (SG&A) expenses were ¥23,921 million (56.9% of net sales, a 1.9-point improvement year on year), which the company attributes mainly to greater efficiency in customer-acquisition costs such as sales promotion expenses and sales commissions, and to lower fixed costs such as commission expenses paid. As a result, the operating loss narrowed to ¥2,588 million (versus a loss of ¥3,459 million in the previous year), and the ordinary loss also narrowed to ¥2,737 million (versus a loss of ¥3,909 million in the previous year). Profit attributable to owners of parent was ¥3,940 million, turning positive from a loss of ¥3,616 million in the previous year, owing to the gain on sale of fixed assets announced on March 28, 2025. Versus its own forecast, net sales exceeded the ¥42,000 million forecast by ¥71 million, the operating loss narrowed by ¥112 million against the ¥2,700 million forecast loss, and the ordinary loss narrowed by ¥63 million against the ¥2,800 million forecast loss; the company stated that net sales and the operating loss both landed in line with plan. Profit attributable to owners of parent came in ¥210 million below the ¥4,150 million forecast.
| Item | FY2025 (Actual) | FY2024 (Actual) | Change |
|---|---|---|---|
| Net sales | ¥42,071 million | ¥45,859 million | -¥3,787 million |
| Gross profit (gross margin) | ¥21,332 million (50.7%) | ¥23,501 million (51.2%) | -¥2,169 million |
| SG&A expenses (% of net sales) | ¥23,921 million (56.9%) | ¥26,961 million (58.8%) | -¥3,040 million |
| Operating profit (loss) (margin) | -¥2,588 million (-6.2%) | -¥3,459 million (-7.5%) | +¥871 million |
| Ordinary profit (loss) (margin) | -¥2,737 million (-6.5%) | -¥3,909 million (-8.5%) | +¥1,172 million |
| Profit attributable to owners of parent | ¥3,940 million (9.4%) | -¥3,616 million (-7.9%) | +¥7,556 million |
Segment Results
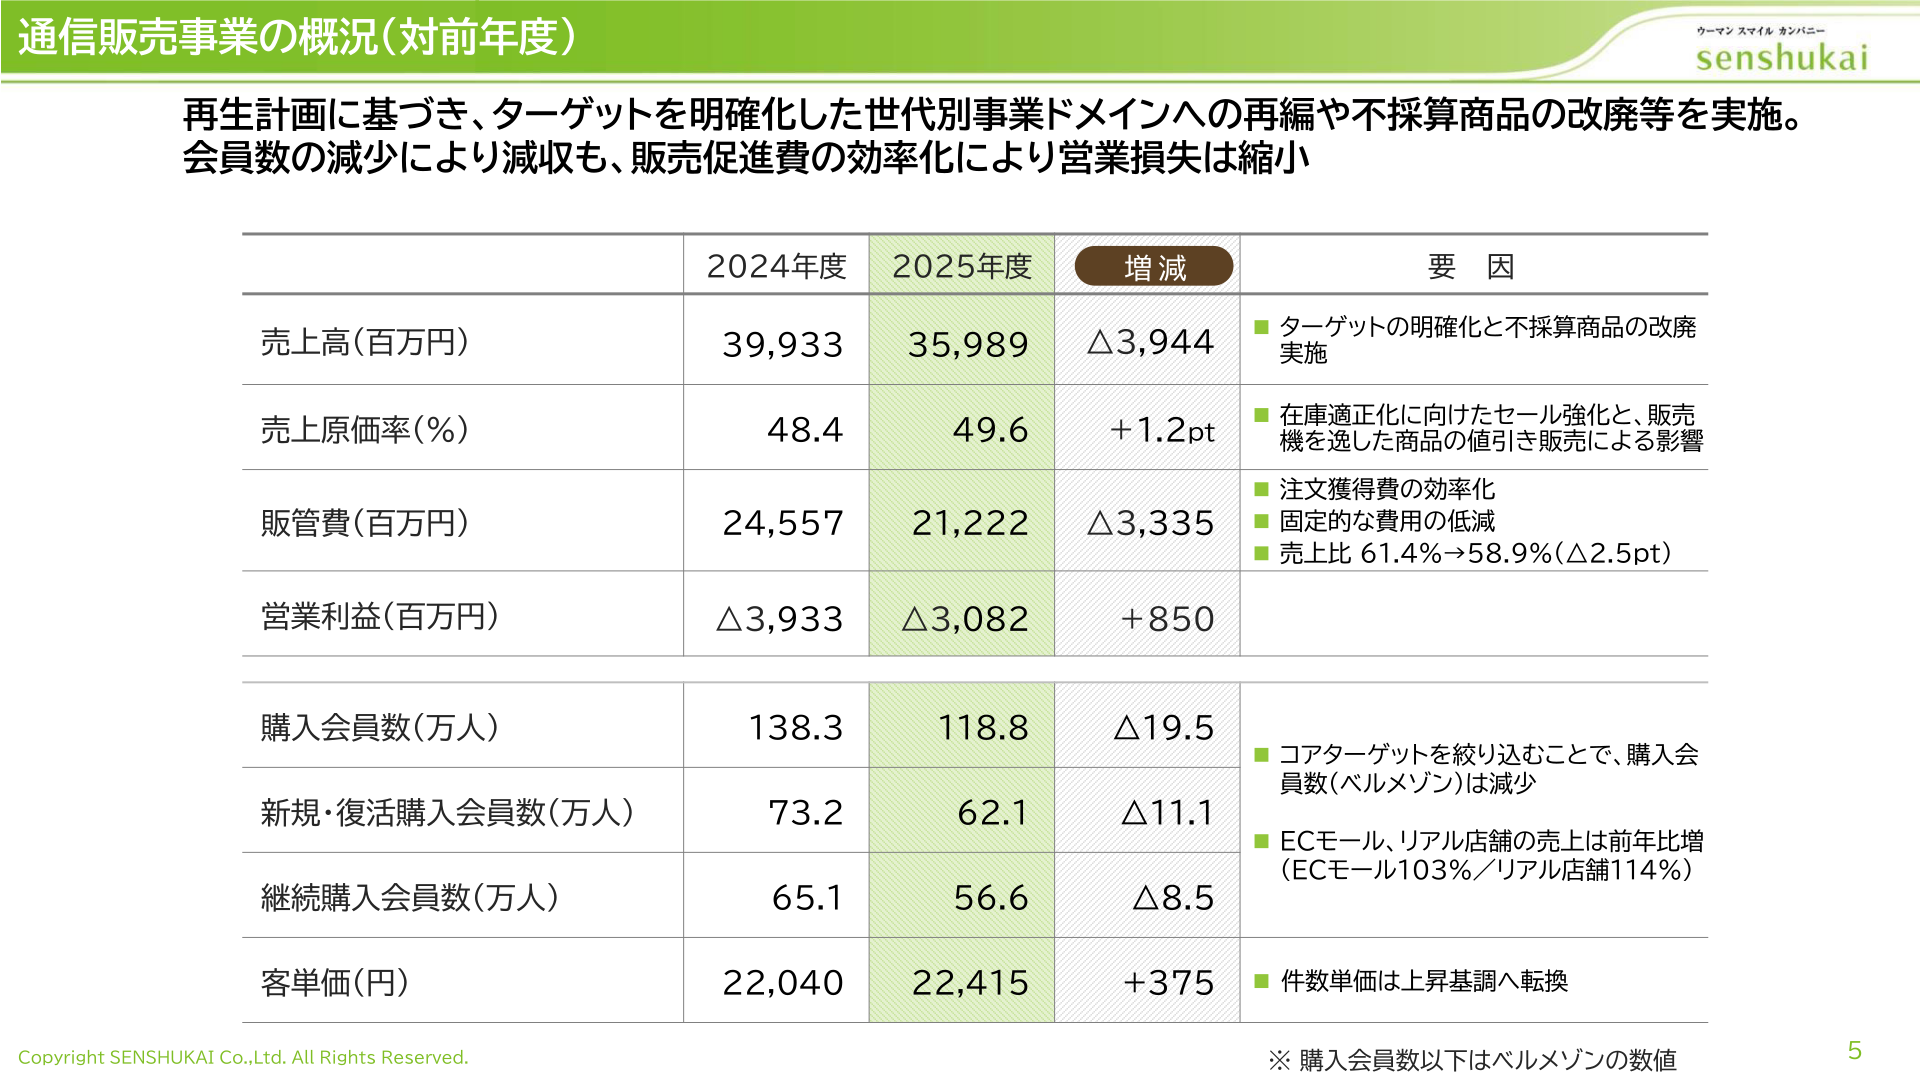
In the Mail Order business, Senshukai restructured its business domains by generation with clearly defined targets and discontinued unprofitable products under the Revival Plan. As a result, net sales declined to ¥35,989 million (down ¥3,944 million year on year) due to a decrease in membership, while the operating loss narrowed to ¥3,082 million (versus a loss of ¥3,933 million in the previous year) thanks to greater efficiency in sales promotion expenses. The cost-of-sales ratio was 49.6% (up 1.2 points year on year), affected by stronger sales campaigns to optimize inventory and discounted sales of products that missed their selling window. SG&A expenses were ¥21,222 million (58.9% of net sales, a 2.5-point improvement year on year). The number of Belle Maison purchasing members was 1.188 million (down 0.195 million year on year); both new/reactivated purchasing members at 0.621 million (down 0.111 million) and continuing purchasing members at 0.566 million (down 0.085 million) decreased, while average spend per customer rose to ¥22,415 (up ¥375 year on year), turning to an upward trend. Sales through EC malls rose to 103% of the previous year, and sales at physical stores rose to 114% of the previous year, both increasing. In the Corporate business, the outsourced-operations business performed steadily, with net sales of ¥4,007 million (up ¥95 million year on year) and operating profit of ¥253 million (up ¥92 million year on year, operating margin of 6.3%), an increase in both sales and profit. In the Insurance business, the number of new contracts from conventional channels decreased, with net sales of ¥390 million (down ¥122 million year on year) and operating profit of ¥142 million (down ¥120 million year on year, operating margin of 36.5%), a decrease in both sales and profit. In the Other business (childcare support business), nursery operations progressed smoothly, with net sales of ¥1,684 million (up ¥183 million year on year) and operating profit of ¥96 million (up ¥48 million year on year, operating margin of 5.7%), an increase in both sales and profit.
| Segment | Metric | FY2025 | FY2024 |
|---|---|---|---|
| Mail Order | Net sales | ¥35,989 million | ¥39,933 million |
| Mail Order | Operating profit (loss) | -¥3,082 million | -¥3,933 million |
| Corporate | Net sales | ¥4,007 million | ¥3,912 million |
| Corporate | Operating profit | ¥253 million | ¥161 million |
| Insurance | Net sales | ¥390 million | ¥512 million |
| Insurance | Operating profit | ¥142 million | ¥263 million |
| Other (Childcare Support) | Net sales | ¥1,684 million | ¥1,500 million |
| Other (Childcare Support) | Operating profit | ¥96 million | ¥48 million |
Financial Position
Total assets were ¥26,149 million (up ¥664 million from the previous fiscal year-end), and total net assets were ¥17,037 million (up ¥3,889 million from the previous fiscal year-end), with the equity ratio rising from 51.6% to 65.2%. On the assets side, cash and cash equivalents increased to ¥6,937 million (up ¥4,283 million from the previous fiscal year-end), while buildings and structures (net) decreased by ¥772 million and land decreased by ¥1,284 million. On the liabilities side, electronically recorded monetary claims payable decreased by ¥969 million and long-term borrowings decreased by ¥1,963 million. In cash flows, operating cash flow was -¥3,075 million (versus -¥3,459 million in the previous year); investing cash flow was ¥9,854 million (versus ¥297 million in the previous year), reflecting proceeds of ¥9,503 million from the sale of property, plant and equipment, among other items; and financing cash flow was -¥2,511 million (versus -¥710 million in the previous year), reflecting expenditure of ¥2,365 million for the repayment of long-term borrowings, among other items.
| Item | FY2025 End | FY2024 End | Change |
|---|---|---|---|
| Total assets | ¥26,149 million | ¥25,484 million | +¥664 million |
| Total net assets | ¥17,037 million | ¥13,147 million | +¥3,889 million |
| Equity ratio | 65.2% | 51.6% | – |
| Cash and cash equivalents (period-end) | ¥6,937 million | ¥2,654 million | +¥4,283 million |
FY2026 Forecast
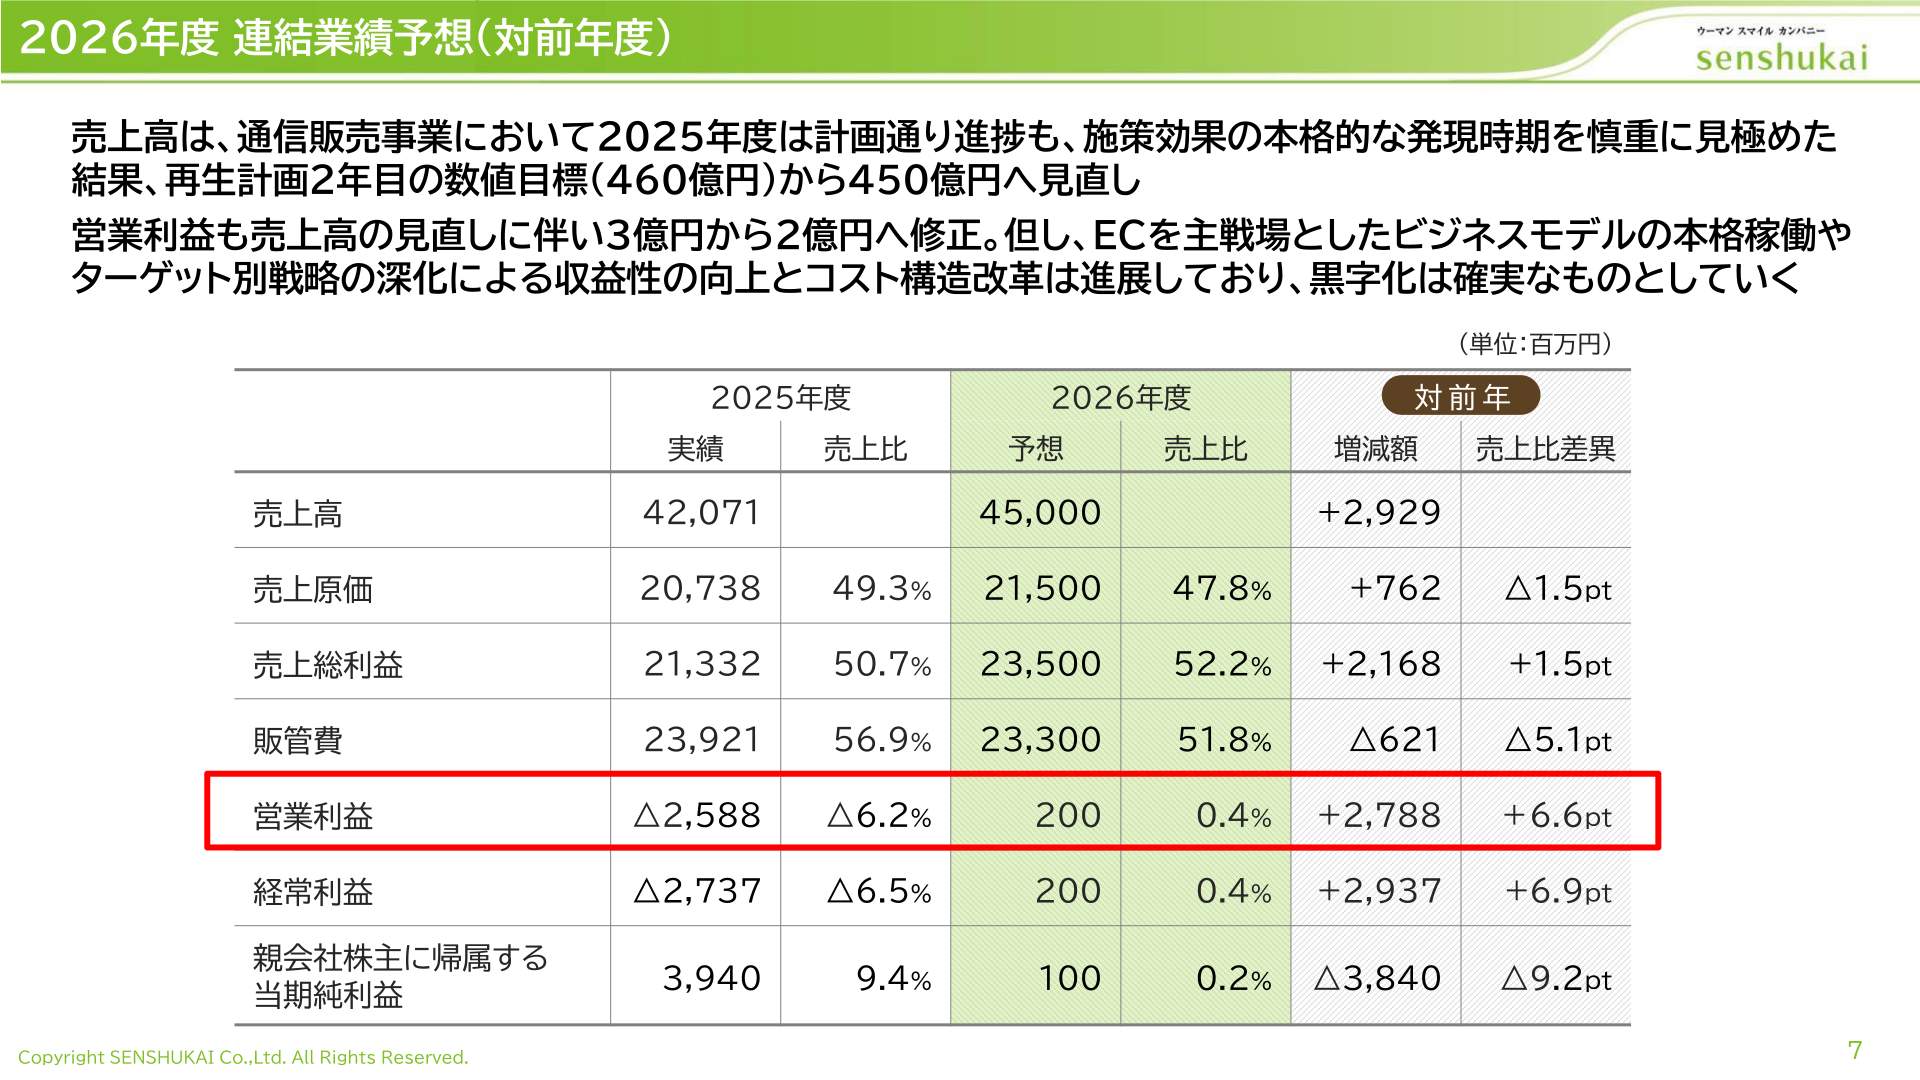
After carefully assessing the timing for the Mail Order business’s measures to take full effect, the company revised its Year 2 numerical target under the Revival Plan for net sales from ¥46,000 million down to ¥45,000 million. It forecasts net sales of ¥45,000 million (up ¥2,929 million year on year), operating profit of ¥200 million (versus an operating loss of ¥2,588 million in the previous year; revised down from the initial target of ¥300 million in line with the net sales revision), ordinary profit of ¥200 million (versus an ordinary loss of ¥2,737 million in the previous year), and profit attributable to owners of parent of ¥100 million (versus profit of ¥3,940 million in the previous year). The company states that the full-scale rollout of its EC-centered business model and the deepening of its target-based strategy are improving profitability, and that cost-structure reforms are progressing, and that it will work to make the return to profitability certain.
| Item | FY2026 (Forecast) | FY2025 (Actual) | Change |
|---|---|---|---|
| Net sales | ¥45,000 million | ¥42,071 million | +¥2,929 million |
| Gross profit (gross margin) | ¥23,500 million (52.2%) | ¥21,332 million (50.7%) | +¥2,168 million |
| SG&A expenses (% of net sales) | ¥23,300 million (51.8%) | ¥23,921 million (56.9%) | -¥621 million |
| Operating profit (loss) (margin) | ¥200 million (0.4%) | -¥2,588 million (-6.2%) | +¥2,788 million |
| Ordinary profit (loss) (margin) | ¥200 million (0.4%) | -¥2,737 million (-6.5%) | +¥2,937 million |
| Profit attributable to owners of parent | ¥100 million (0.2%) | ¥3,940 million (9.4%) | -¥3,840 million |
Shareholder Returns
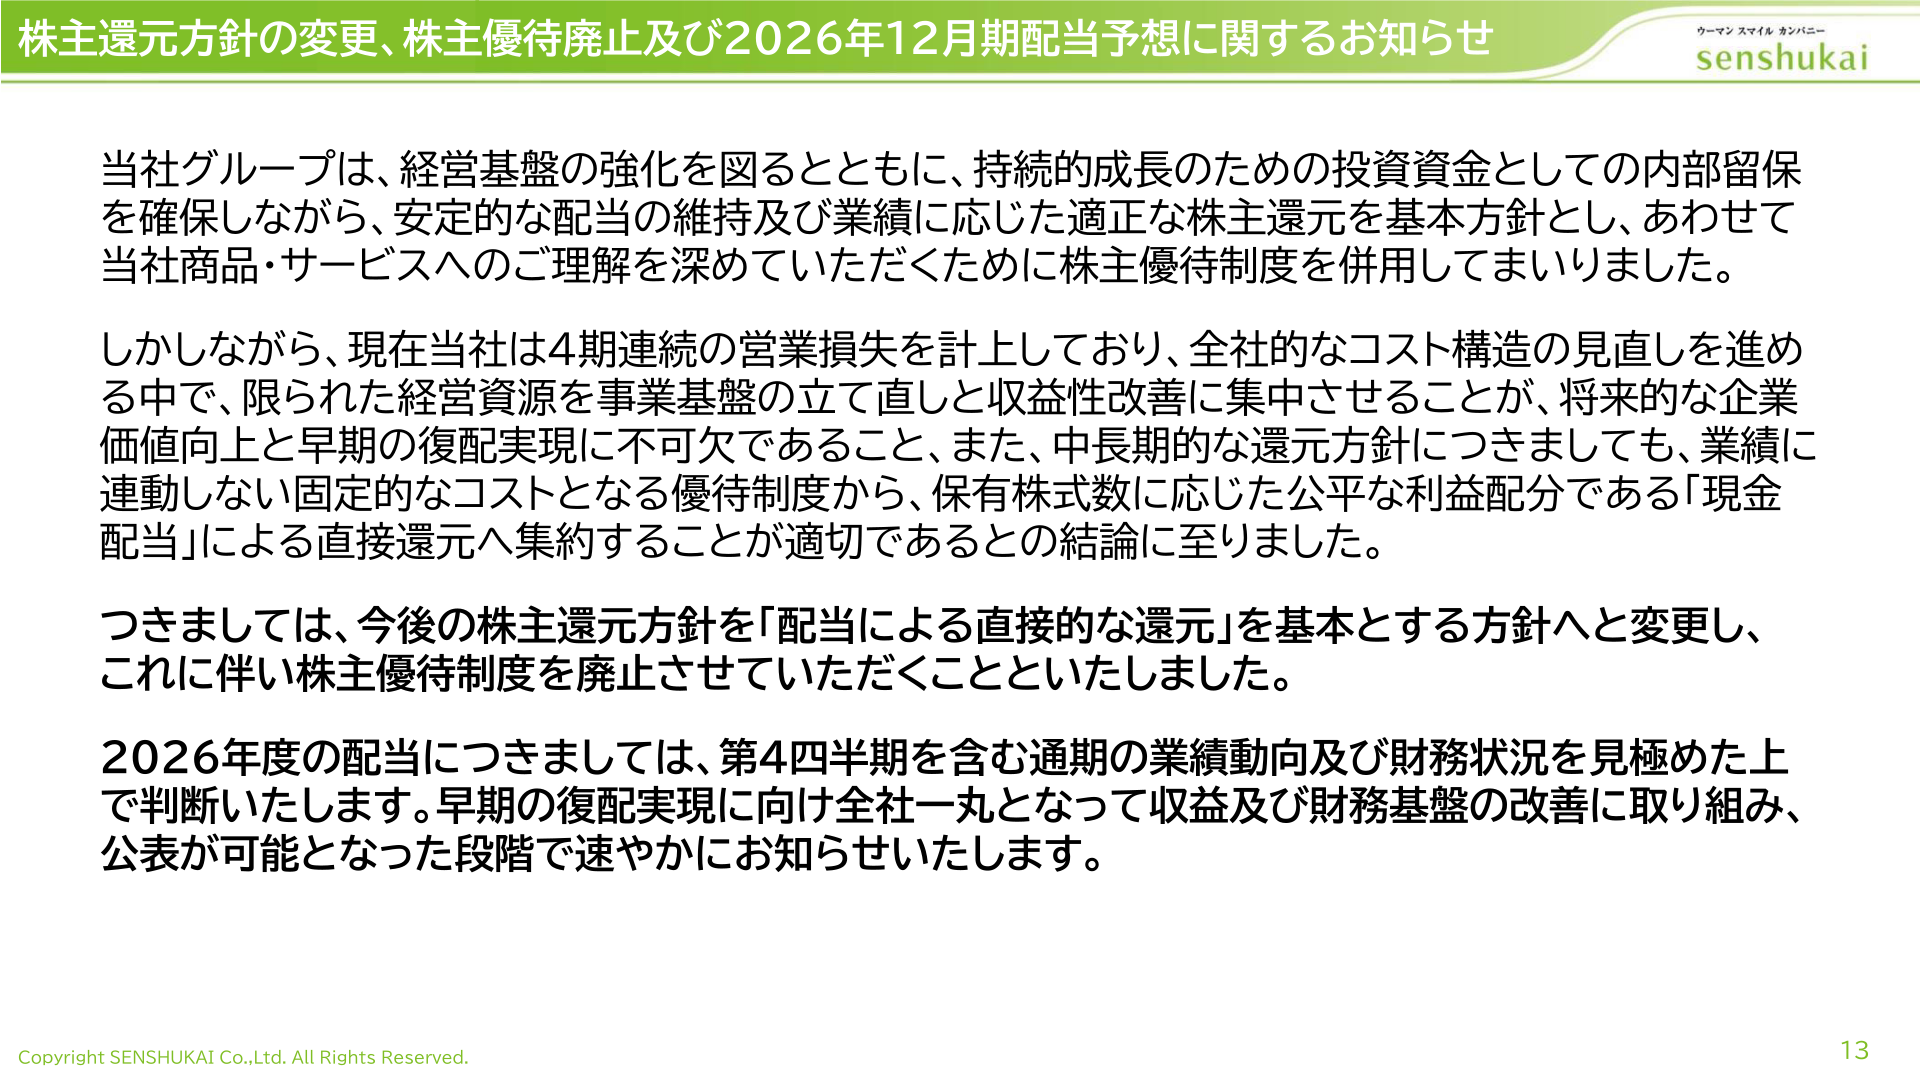
The Senshukai Group’s basic policy has been to maintain stable dividends and provide appropriate shareholder returns in line with business performance, while also operating a shareholder benefit program. However, in light of currently recording four consecutive fiscal years of operating losses, the company has concluded that concentrating its limited management resources on rebuilding its business foundation and improving profitability is essential for enhancing corporate value over the long term and for achieving an early resumption of dividend payments. It also concluded that it is appropriate to shift its shareholder returns away from the benefit program — a fixed cost unrelated to business performance — toward direct returns via cash dividends, which distribute profits fairly according to the number of shares held. Accordingly, the company has changed its shareholder return policy to one based on “direct returns through dividends” and has decided to abolish its shareholder benefit program. Regarding the FY2026 dividend, the company will decide after assessing full-year business trends, including the fourth quarter, and its financial condition, and will announce its decision promptly once it becomes possible to do so.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















