
This article is based on publicly available IR materials and is not a recommendation to buy or sell any specific securities.
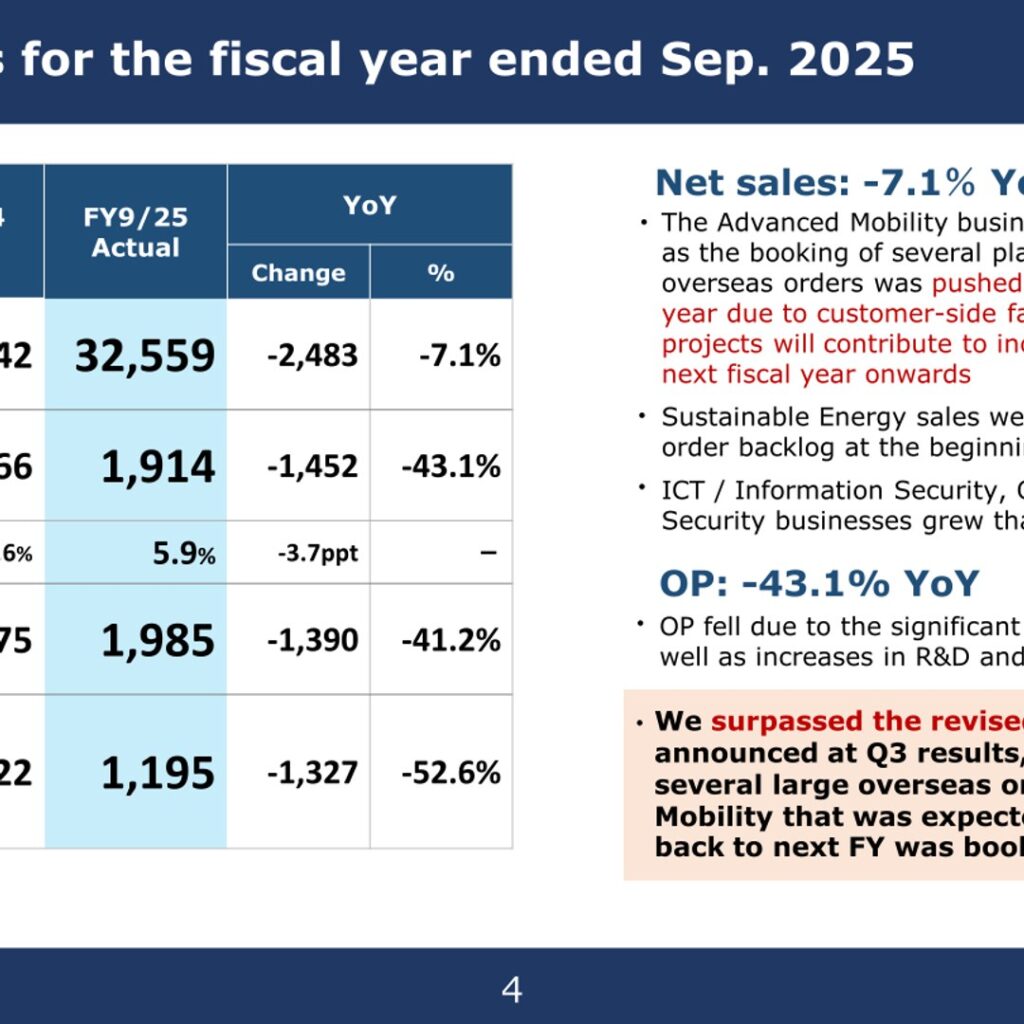
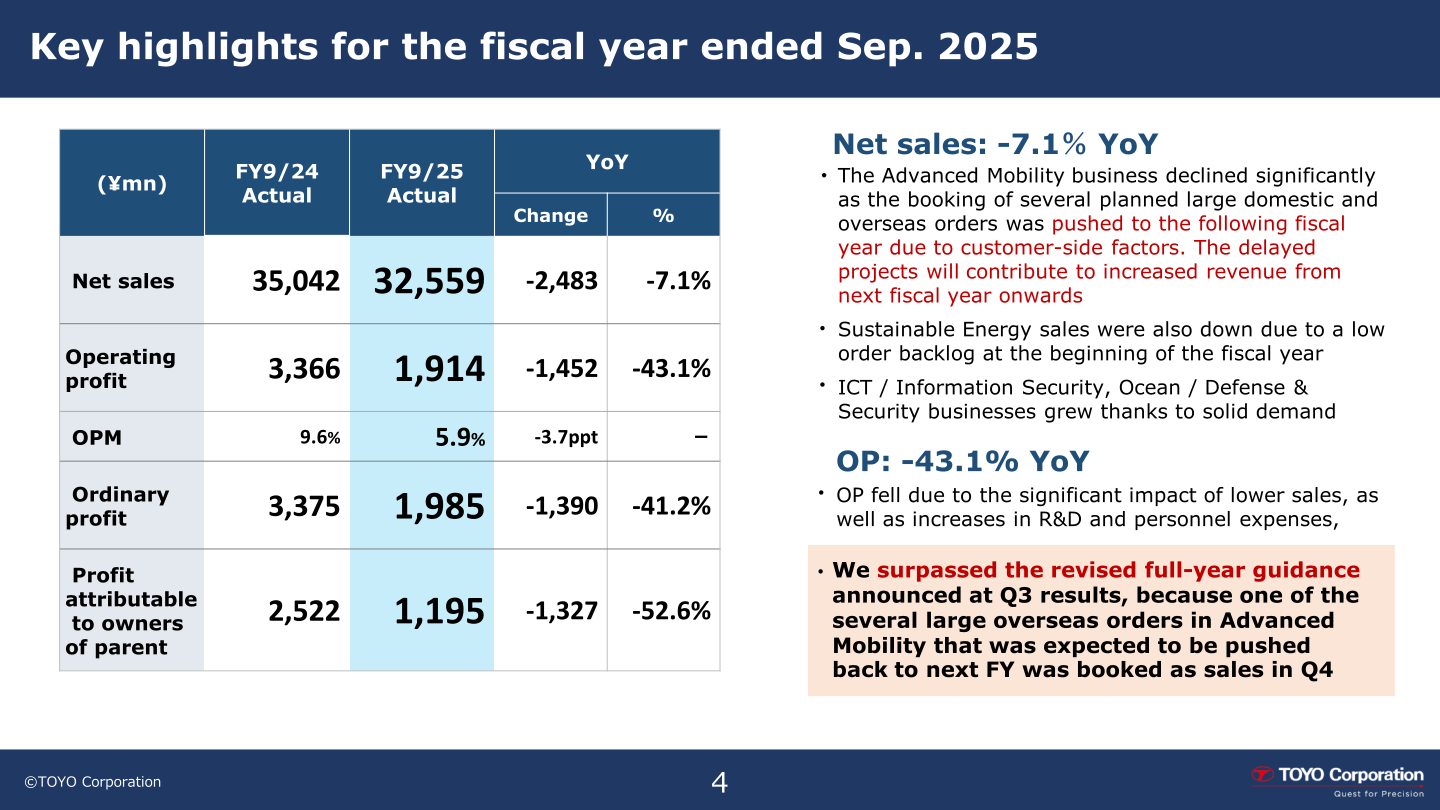
TOYO Corporation (TSE Prime: 8151) reported consolidated net sales of ¥32,559 million for FY9/25, down 7.1% year on year, with operating profit falling 43.1% to ¥1,914 million and profit attributable to owners of parent down 52.6% to ¥1,195 million. The decline was driven mainly by the Advanced Mobility segment, where several large domestic and overseas orders were pushed to the following fiscal year due to customer-side factors, and by lower Sustainable Energy sales stemming from a low order backlog at the start of the year, while ICT / Information Security and the Ocean / Defense & Security business grew on solid demand. New orders reached a record high of ¥40,151 million (+19.4% YoY) and the order backlog rose 44.6% YoY to ¥24,625 million, and the company noted that it surpassed the revised full-year guidance announced at the Q3 stage after one of the large overseas Advanced Mobility orders expected to slip to the next fiscal year was booked as sales in Q4.
Note: TOYO Corporation’s fiscal year ends September 30. This article covers the fiscal year ended September 30, 2025, which the company’s materials label “FY9/25”; the materials’ own labels (FY9/24, FY9/25, FY9/26) are retained in the tables and text below.
Consolidated Results (Full-Year Actual)
Net sales declined 7.1% YoY to ¥32,559 million and operating profit fell 43.1% to ¥1,914 million (operating profit margin 5.9%, down 3.7 points YoY). Ordinary profit decreased 41.2% to ¥1,985 million and profit attributable to owners of parent fell 52.6% to ¥1,195 million. The company said operating profit declined due to the significant impact of lower sales as well as increases in R&D and personnel expenses.
| Item (¥mn) | FY9/24 Actual | FY9/25 Actual | Change | % Change |
|---|---|---|---|---|
| Net sales | 35,042 | 32,559 | -2,483 | -7.1% |
| Operating profit | 3,366 | 1,914 | -1,452 | -43.1% |
| OPM | 9.6% | 5.9% | -3.7ppt | – |
| Ordinary profit | 3,375 | 1,985 | -1,390 | -41.2% |
| Profit attributable to owners of parent | 2,522 | 1,195 | -1,327 | -52.6% |
Segment Results
Advanced Mobility net sales fell 22.7% to ¥7,595 million and segment profit fell 65.9% to ¥707 million, as sales for large overseas AD/ADAS evaluation system projects and large domestic e-mobility projects slipped to the next fiscal year and beyond due to delays in building construction and facility installation at customer sites, although domestic sales of noise and vibration measurement-related products were robust. Sustainable Energy net sales fell 11.3% to ¥5,841 million and segment profit fell 40.8% to ¥943 million on a smaller order backlog at the start of the year and higher SG&A expenses, including for expanded production capacity at subsidiary L.Tail Co., Ltd. ICT / Information Security net sales rose 8.5% to ¥8,120 million and segment profit rose 76.8% to ¥686 million, led by core network performance testing products, vulnerability scanners and cybersecurity service-provider projects, including a large government-agency project. EMC & Antenna Systems net sales fell 5.4% to ¥4,427 million and segment profit fell 28.9% to ¥168 million due to a lower opening order backlog and a customer-side delay in completing an anechoic chamber. Other businesses (Ocean / Defense & Security, Software Quality & Productivity, and Others) net sales rose 1.6% to ¥6,573 million, but segment profit fell 35.7% to ¥631 million on one-off costs associated with large Ocean / Defense & Security orders and higher SG&A expenses in Software Quality & Productivity.
| Segment | Metric | FY9/24 Actual | FY9/25 Actual | % Change |
|---|---|---|---|---|
| Advanced Mobility | Net sales | 9,826 | 7,595 | -22.7% |
| Advanced Mobility | Segment profit | 2,077 | 707 | -65.9% |
| Sustainable Energy | Net sales | 6,585 | 5,841 | -11.3% |
| Sustainable Energy | Segment profit | 1,591 | 943 | -40.8% |
| ICT / Information Security | Net sales | 7,481 | 8,120 | +8.5% |
| ICT / Information Security | Segment profit | 388 | 686 | +76.8% |
| EMC & Antenna Systems | Net sales | 4,681 | 4,427 | -5.4% |
| EMC & Antenna Systems | Segment profit | 237 | 168 | -28.9% |
| Other businesses (Ocean / Defense & Security, Software Quality & Productivity, and Others) | Net sales | 6,468 | 6,573 | +1.6% |
| Other businesses (Ocean / Defense & Security, Software Quality & Productivity, and Others) | Segment profit | 982 | 631 | -35.7% |
Orders & Order Backlog
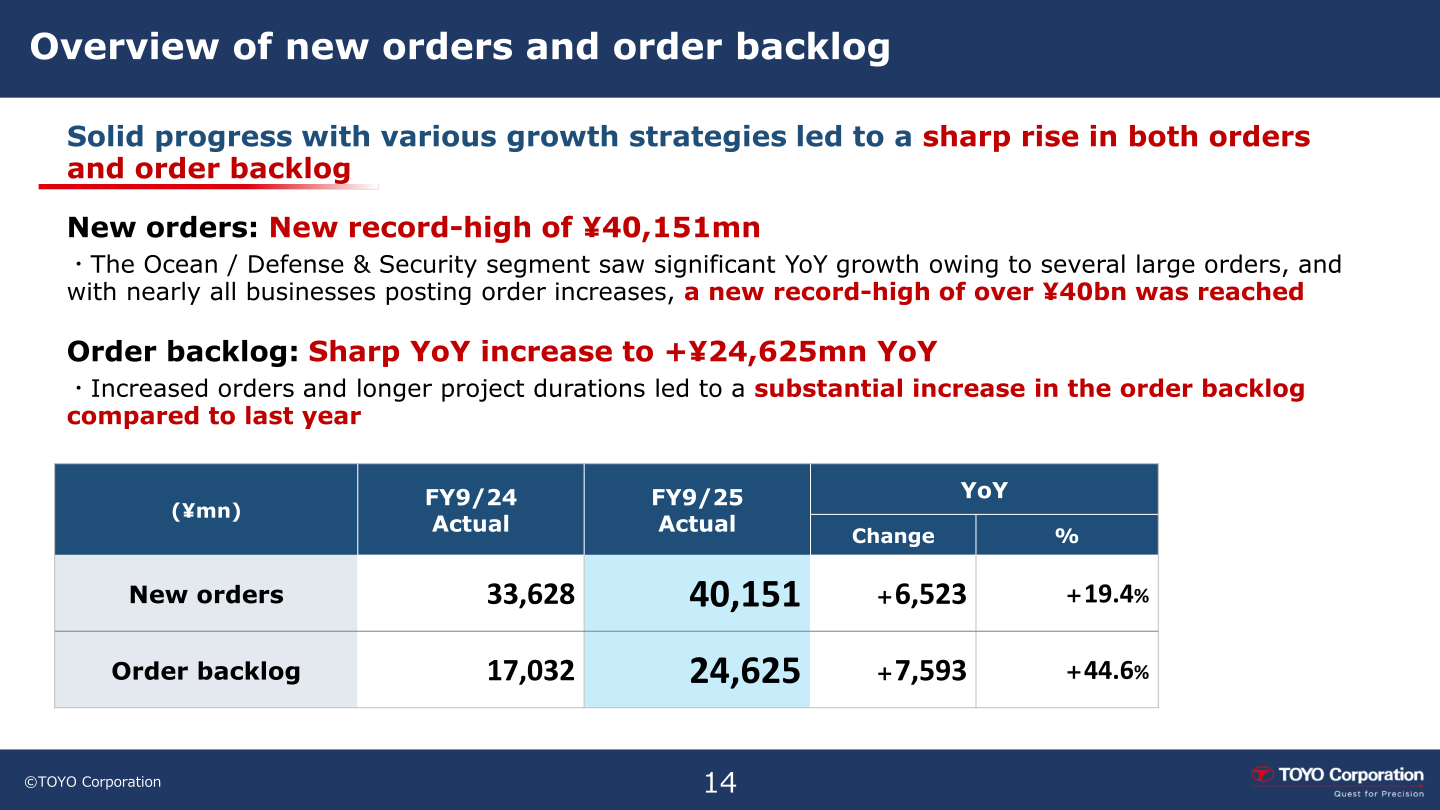
New orders reached a new record high of ¥40,151 million, up 19.4% YoY, as the Ocean / Defense & Security segment saw significant YoY growth from several large orders and nearly all businesses posted order increases. The order backlog rose 44.6% YoY to ¥24,625 million, reflecting increased orders and longer project durations. By segment, orders and backlog increased in Advanced Mobility, Sustainable Energy, EMC & Antenna Systems and Other businesses (notably Ocean / Defense & Security), while ICT / Information Security orders and backlog declined as renewal/replacement of core products offset growth in cybersecurity large-scale contracts.
| Segment | Metric | FY9/24 Actual | FY9/25 Actual | % Change |
|---|---|---|---|---|
| Total | New orders | 33,628 | 40,151 | +19.4% |
| Total | Order backlog | 17,032 | 24,625 | +44.6% |
| Advanced Mobility | Orders | 9,101 | 9,762 | +7.3% |
| Advanced Mobility | Backlog | 4,819 | 6,985 | +45.0% |
| Sustainable Energy | Orders | 5,810 | 6,359 | +9.5% |
| Sustainable Energy | Backlog | 2,113 | 2,630 | +24.5% |
| ICT / Information Security | Orders | 8,144 | 7,817 | -4.0% |
| ICT / Information Security | Backlog | 3,736 | 3,432 | -8.1% |
| EMC & Antenna Systems | Orders | 4,111 | 5,130 | +24.8% |
| EMC & Antenna Systems | Backlog | 2,593 | 3,296 | +27.1% |
| Other businesses | Orders | 6,461 | 11,081 | +71.5% |
| Other businesses | Backlog | 3,770 | 8,279 | +119.6% |
| (of which: Ocean / Defense & Security) | Orders | 2,812 | 6,120 | +117.7% |
| (of which: Ocean / Defense & Security) | Backlog | 2,168 | 5,582 | +157.5% |
FY9/26 Forecast
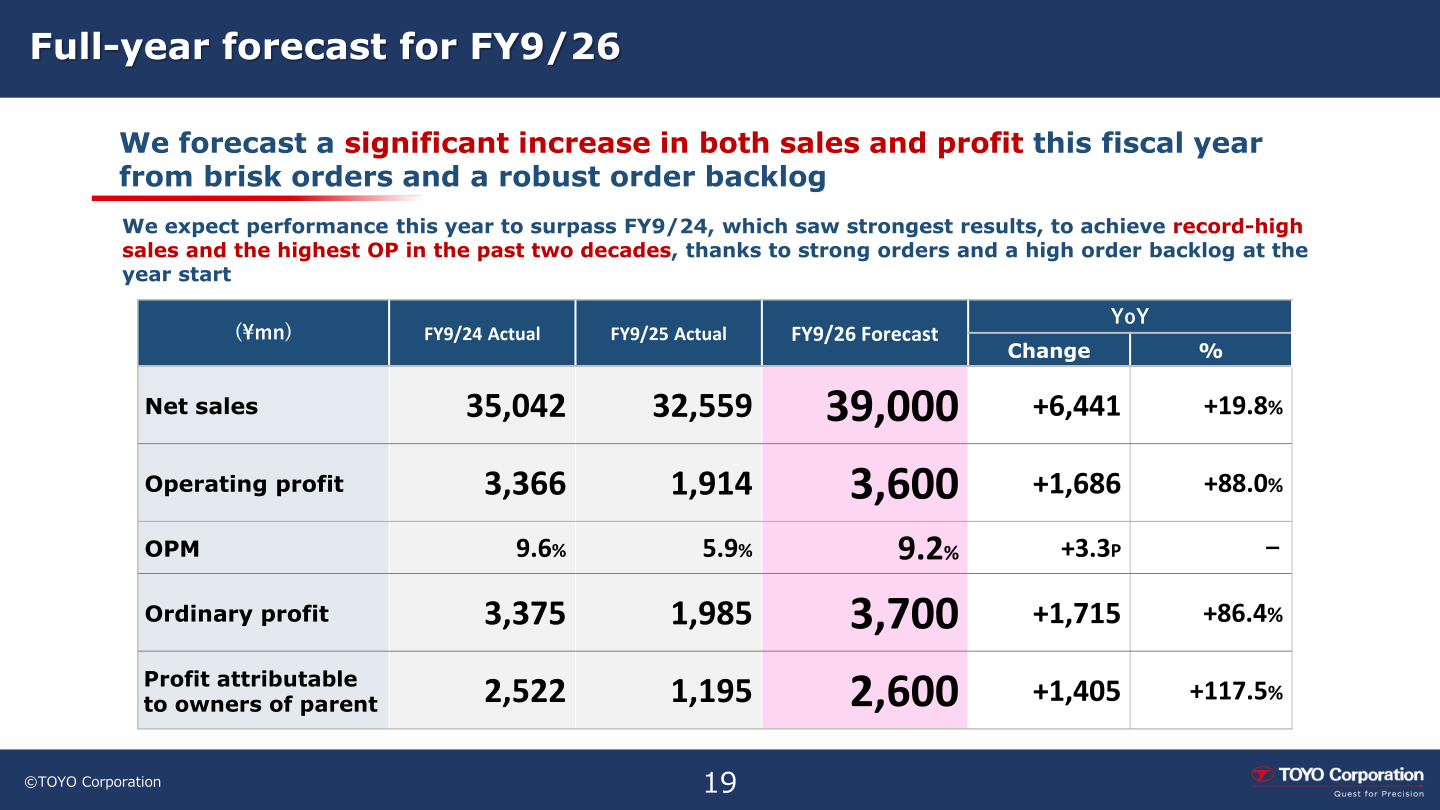
TOYO Corporation forecasts a significant increase in both sales and profit for FY9/26, from brisk orders and a robust order backlog. The company expects performance to surpass FY9/24, its previous strongest year, achieving record-high sales and the highest operating profit in the past two decades, thanks to strong orders and a high order backlog at the start of the year.
| Item (¥mn) | FY9/24 Actual | FY9/25 Actual | FY9/26 Forecast | Change (FY9/26 vs FY9/25) | % Change |
|---|---|---|---|---|---|
| Net sales | 35,042 | 32,559 | 39,000 | +6,441 | +19.8% |
| Operating profit | 3,366 | 1,914 | 3,600 | +1,686 | +88.0% |
| OPM | 9.6% | 5.9% | 9.2% | +3.3ppt | – |
| Ordinary profit | 3,375 | 1,985 | 3,700 | +1,715 | +86.4% |
| Profit attributable to owners of parent | 2,522 | 1,195 | 2,600 | +1,405 | +117.5% |
Shareholder Returns
The FY9/25 dividend is a record high of ¥69 per share (interim ¥30, year-end ¥39; DOE 5.3%), and the company expects to raise the dividend further to ¥70 per share (interim ¥30, year-end ¥40) in FY9/26, which would mark the 9th consecutive year of dividend increases. As part of the medium-term management plan “TY2027,” the dividend policy for the three years from FY9/25 targets a DOE of at least 5%. On share buybacks, the company said it will continue to consider the balance with growth investments as appropriate.
| Item | FY9/25 Actual | FY9/26 Forecast |
|---|---|---|
| Interim dividend (yen) | 30 | 30 |
| Year-end dividend (yen) | 39 | 40 |
| Annual dividend per share (yen) | 69 | 70 |
| DOE | 5.3% | – |
Medium-Term Management Plan “TY2027”
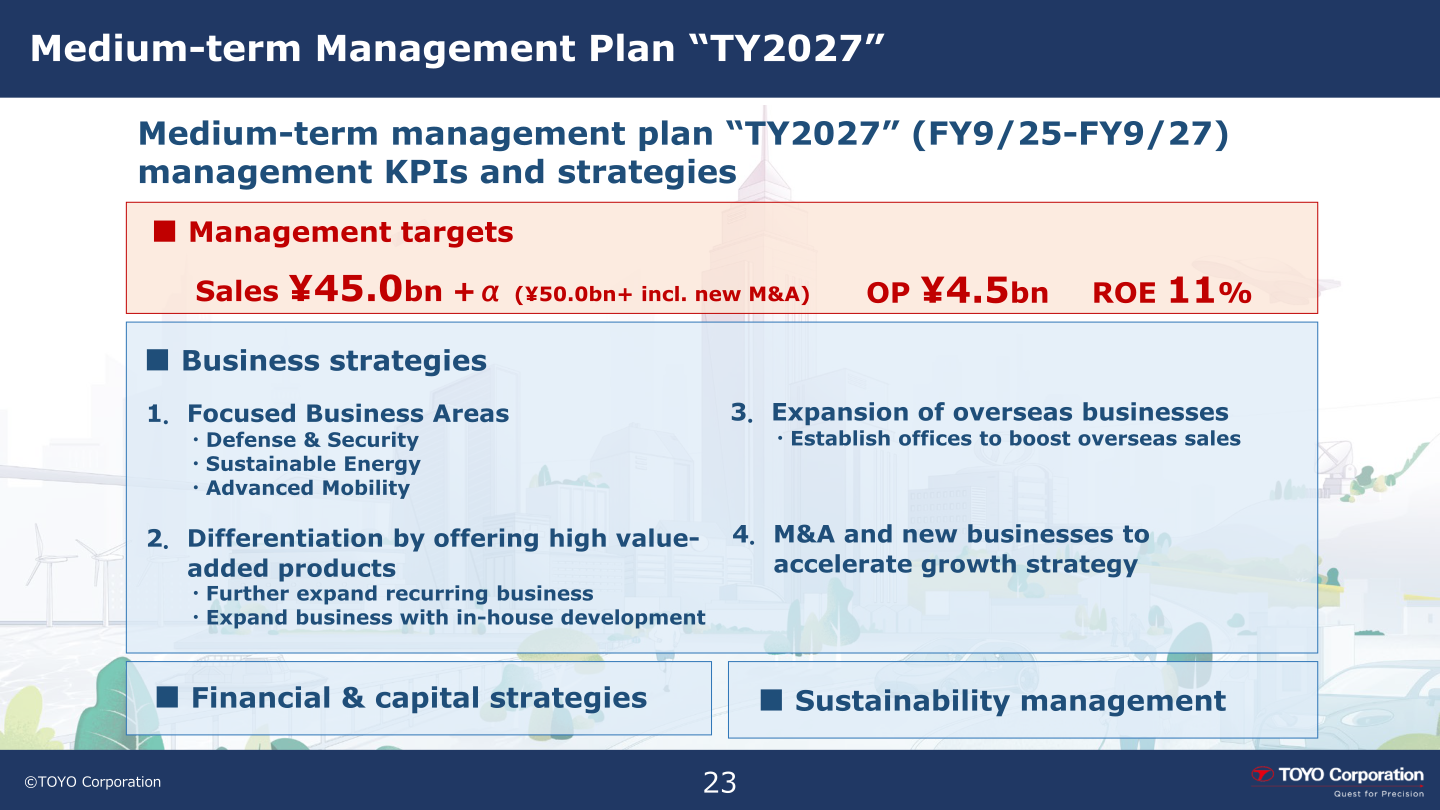
Under the medium-term management plan “TY2027” (FY9/25-FY9/27), TOYO Corporation’s management targets are sales of ¥45.0 billion +α (¥50.0 billion+ including new M&A), operating profit of ¥4.5 billion, and ROE of 11%. The plan’s four business strategies are: (1) focusing on Defense & Security, Sustainable Energy and Advanced Mobility as focused business areas; (2) differentiation by offering high value-added products, including expanding recurring business and in-house development; (3) expansion of overseas businesses, including establishing offices to boost overseas sales; and (4) M&A and new businesses to accelerate the growth strategy. Within Defense & Security, the company secured multiple large-scale defense-related orders in FY9/25, including a surveillance ROV order of ¥2.7 billion, and forecasts defense business sales of over ¥5.0 billion in FY9/27 and over ¥10.0 billion in FY9/29.
This article is an analysis based on publicly available information and is not a recommendation to buy or sell any specific securities. Investment decisions are your own responsibility.
















